

First BanCorp: Banking Services and Lending Risks – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
First Bank Strategy Analysis Bundle
First Bank is considered here in the context of FB Financial Corporation, the Tennessee-based bank holding company for FirstBank. This is a parent-group banking context rather than a similarly named business elsewhere. The analysis focuses on how a relationship-led bank can serve consumer, business and lending customers while competing on trust, convenience, credit judgment and a coherent choice of digital and human service.
FB Financial Corporation reported GAAP net income of USD 58.649 million for April 1 to June 30, 2026, filed on August 3, 2026, as consolidated parent-group results. That snapshot raises practical questions about where customer relationships create durable value, how lending and deposit offerings should be differentiated, and which external pressures deserve close attention. The bundle provides structured ways to investigate those questions; it does not represent that the downloadable files were updated in 2026.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which First Bank customer propositions merit greater resource commitment when growth potential and relative competitive position differ?
A First Bank BCG Matrix helps separate portfolio-priority questions from a simple list of banking products. It examines market growth alongside relative market share, using the Stars, Cash Cows, Question Marks and Dogs logic to compare areas such as deposits, mortgage lending, business banking, card relationships or advisory-related services where relevant evidence is available. In banking, an apparently mature service may still support valuable customer retention, while a faster-growing digital proposition may require investment before its economics are clear. The framework is useful for comparing alternatives without assuming that any named offering already belongs in a particular quadrant.
- Growth versus position. Compare demand potential with relative competitive standing instead of treating every product line as equally strategic.
- Relationship spillovers. Consider whether a lending, deposit or payment relationship helps attract broader household or business banking activity.
- Portfolio working view. Use the Excel framework to map evidence and assumptions, then use the Word analysis to interpret trade-offs behind possible funding priorities.
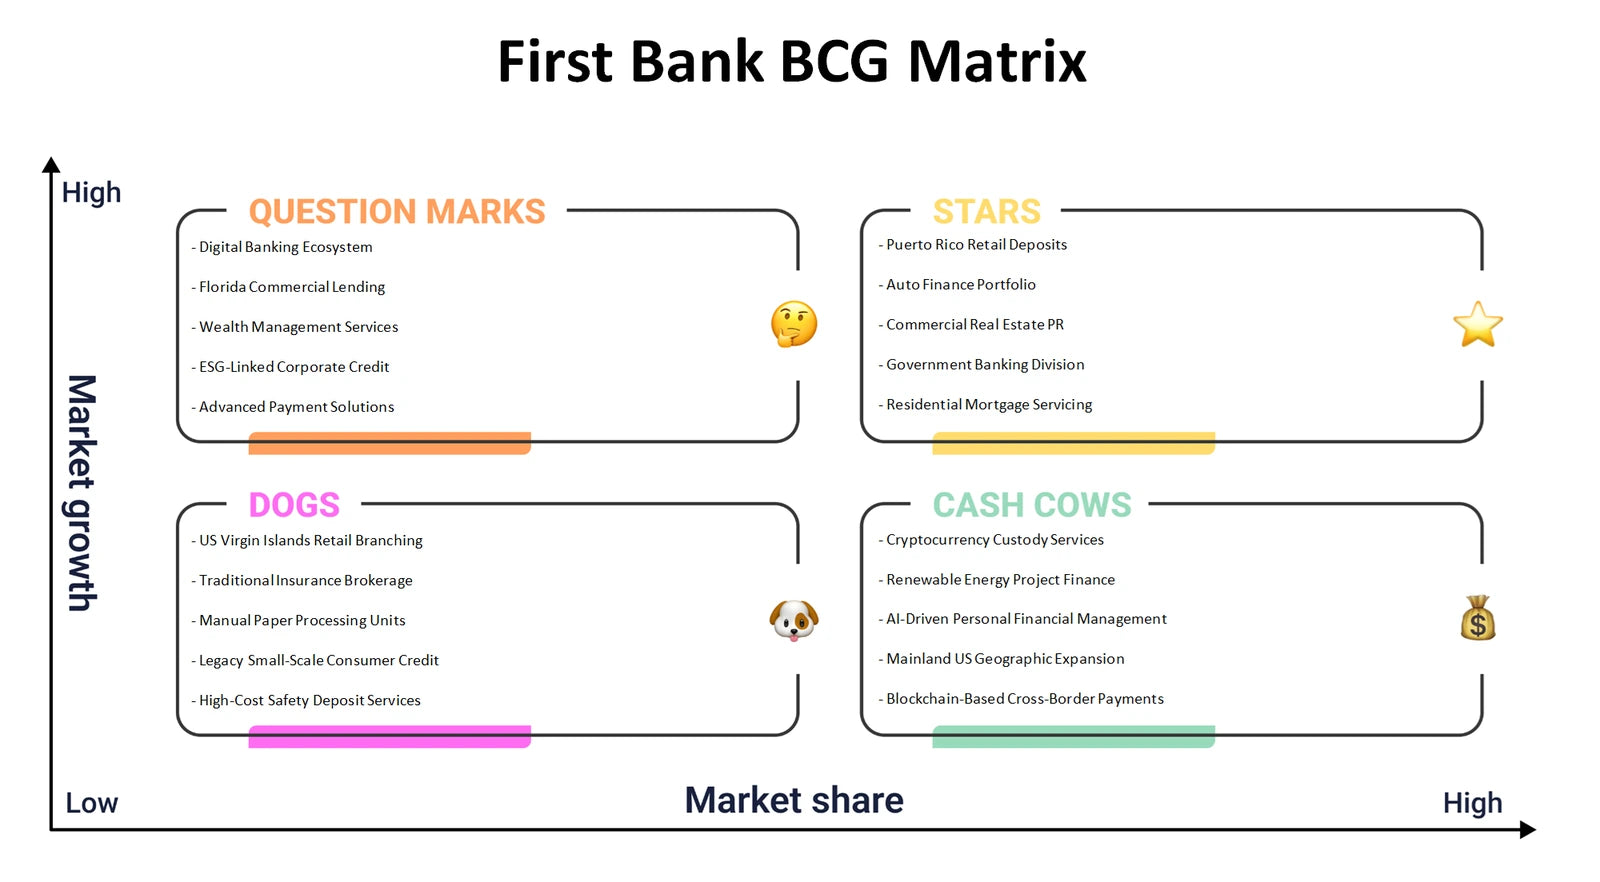
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do First Bank’s customer relationships, delivery channels and partner ecosystem fit together to create banking value?
The First Bank Business Model Canvas connects all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For this banking context, it can help assess how personal service, digital access, lending expertise, deposit relationships and risk controls may reinforce one another. Mortgage intermediaries, title firms, appraisers, insurers, card networks and wealth-platform providers are useful partnership questions because they can affect customer experience, compliance workload and speed of service. The Canvas does not presume the company uses every possible channel or partnership; it organizes the questions needed to see how value delivery and economics connect.
- Customer choice. Contrast the needs of households, borrowers and business customers when deciding what service experience matters most.
- Economic connections. Trace how revenue streams and operating costs relate to key resources, regulated activities and relationship-management effort.
- Model alignment. Populate the Excel Canvas as a structured working map and use the Word analysis to examine the links and tensions between its nine blocks.
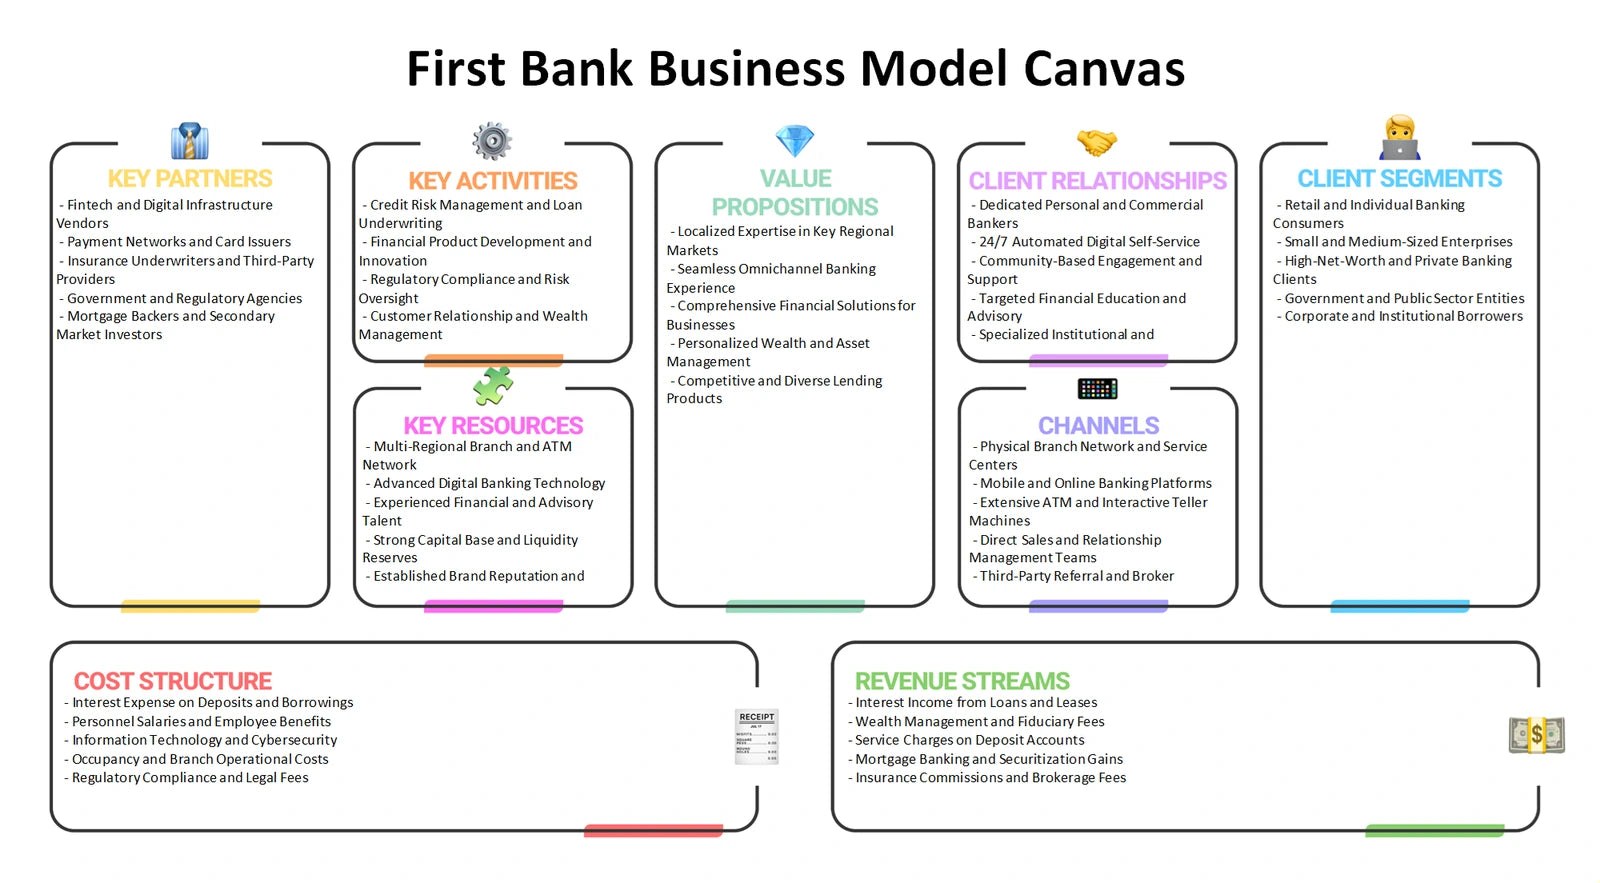
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures shape First Bank’s ability to differentiate service, earn returns and retain customer relationships?
First Bank Porter's Five Forces examines rivalry among banks and other financial providers, supplier power, buyer power, the threat of new entrants and the threat of substitutes. Rivalry matters where customers can compare rates, mobile tools, branch convenience and perceived service quality with little effort. Depositors, borrowers and business clients can exercise buyer power when switching options are accessible. Funding sources, technology vendors, payment networks and specialist partners may influence supplier power. New entrants can emerge through digital-first providers, while substitutes include non-bank payments, investment products or alternative credit options that meet a similar financial need. The lens supports disciplined comparison without assigning unsupported force scores.
- Competitive friction. Assess where convenience, trust, underwriting capability and relationship depth may matter more than a headline product feature.
- Switching alternatives. Distinguish direct banking competitors from payment, savings and financing substitutes that can change customer behavior.
- Pressure testing. Use the Excel framework to record evidence for each force and use the Word analysis to connect those pressures to strategic choices.
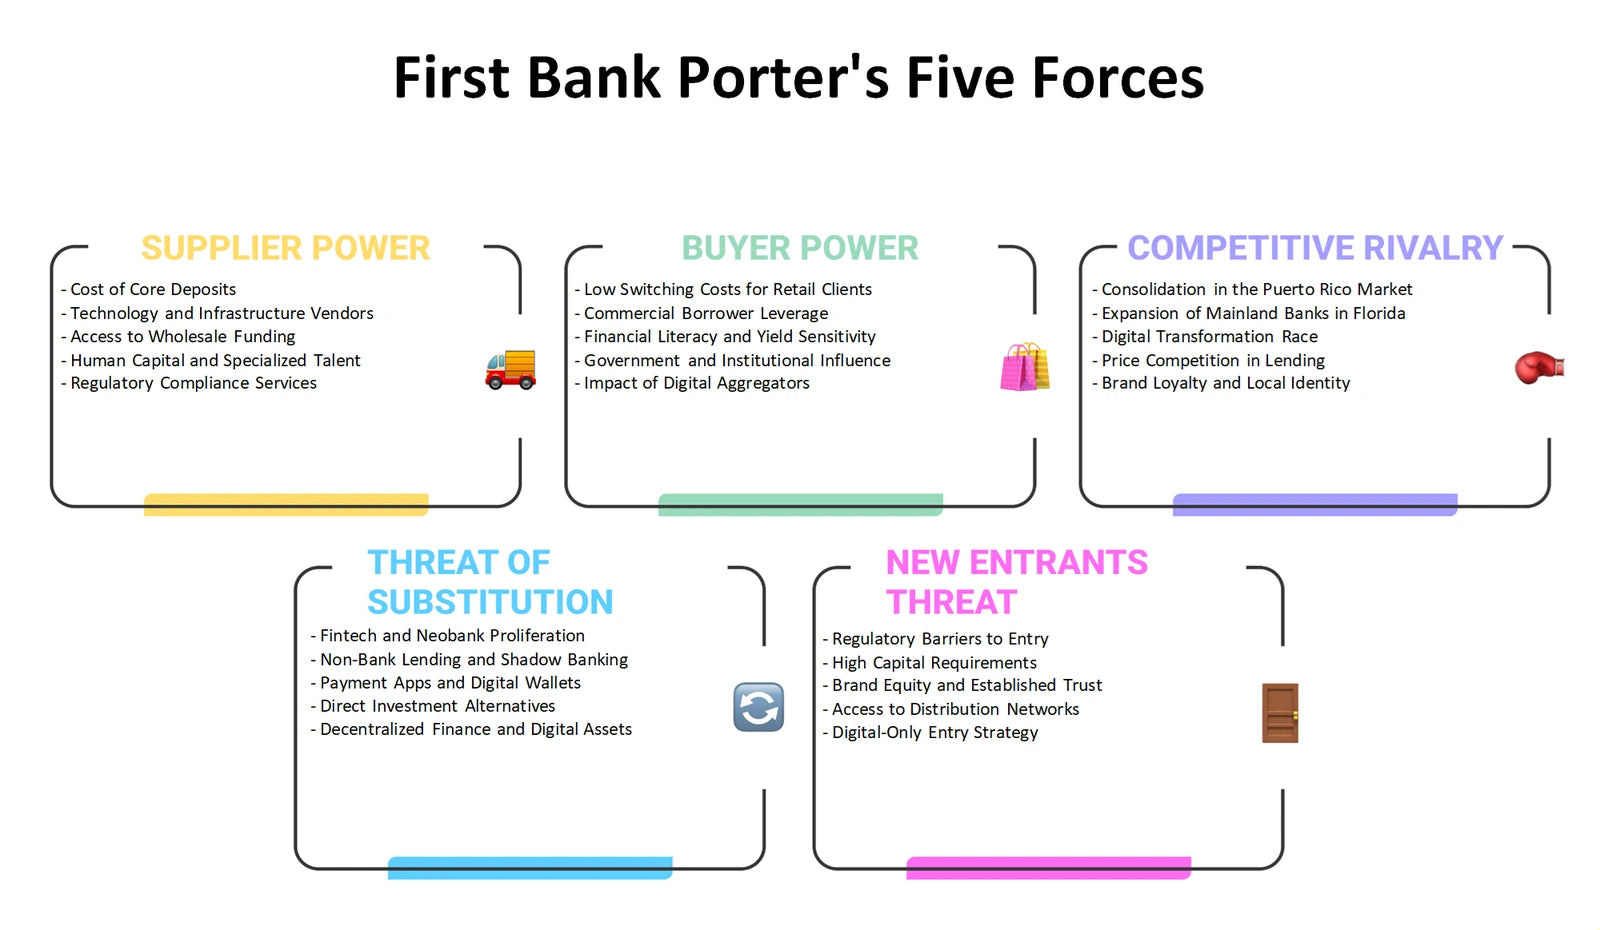
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can First Bank make its regulated financial-service offer understandable and preferable across different customer journeys?
A First Bank Marketing Mix reviews Product, Price, Place and Promotion in a banking setting where trust and clarity influence customer choice. Product can cover the relevance and usability of deposit, lending, payment or relationship-banking services. Price concerns rates, fees and value communication rather than an invented price list. Place evaluates the blend of digital access, assisted service and relationship channels that customers use at different moments, particularly during complex borrowing decisions. Promotion considers how the bank can communicate suitability, convenience and responsible financial service without reducing regulated products to generic advertising claims. The 4Ps lens helps align what is offered with how customers discover, evaluate and continue using it.
- Offer design. Examine whether product features and service support address the practical needs of borrowers, depositors and business customers.
- Channel coherence. Compare how digital journeys and person-to-person support can complement rather than confuse each other.
- Go-to-market review. Use the Excel structure to compare the four Ps and use the Word analysis to frame evidence-led customer and channel questions.
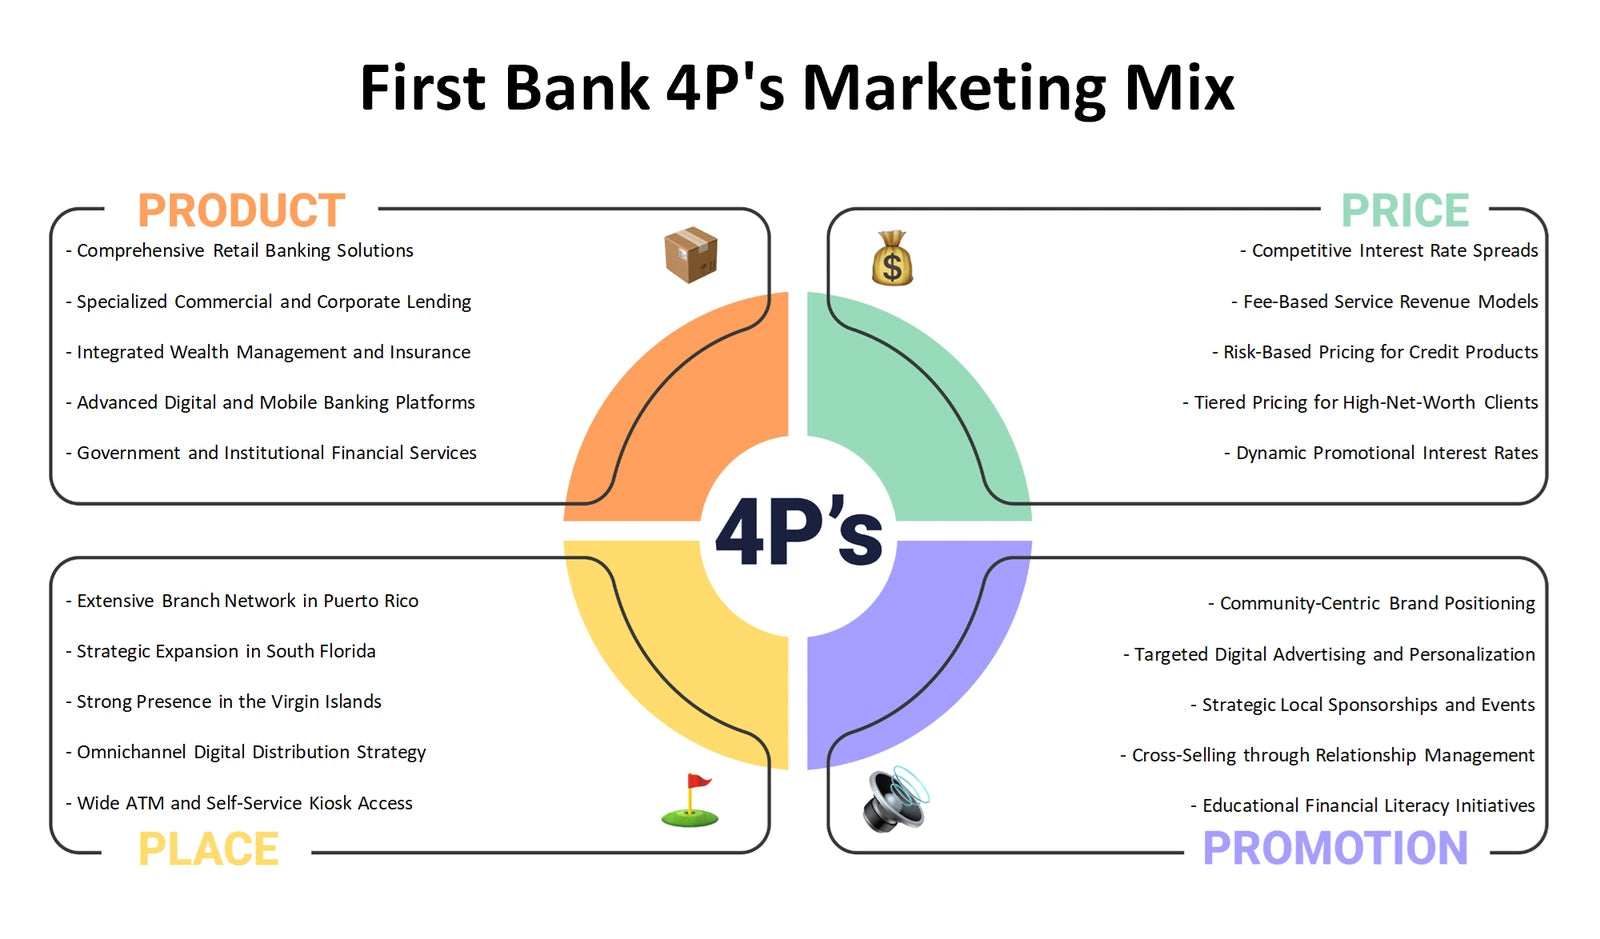
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter First Bank’s customer demand, operating choices and competitive boundaries?
First Bank PESTLE analysis, also commonly called PESTEL, structures the external environment through Political, Economic, Social, Technological, Legal and Environmental factors. Political and legal questions include the direction of banking oversight, consumer protection and data responsibilities; they should not be confused with a claim about a particular new rule. Economic conditions can influence deposit behavior, credit demand and borrower resilience. Social expectations may affect preferences for convenient, transparent and responsive financial service. Technology raises questions around cybersecurity, digital onboarding, payments and automation. Environmental factors can affect physical operations, borrower exposure and risk-management expectations. Together, these factors identify conditions outside management’s direct control that still influence strategic options.
- External signals. Separate documented environmental conditions from assumptions that require monitoring or validation.
- Banking relevance. Relate policy, economic and technology questions to customer confidence, credit decisions and operational resilience.
- Monitoring plan. Use the Excel framework to classify external developments and use the Word analysis to explore why selected factors could matter most.
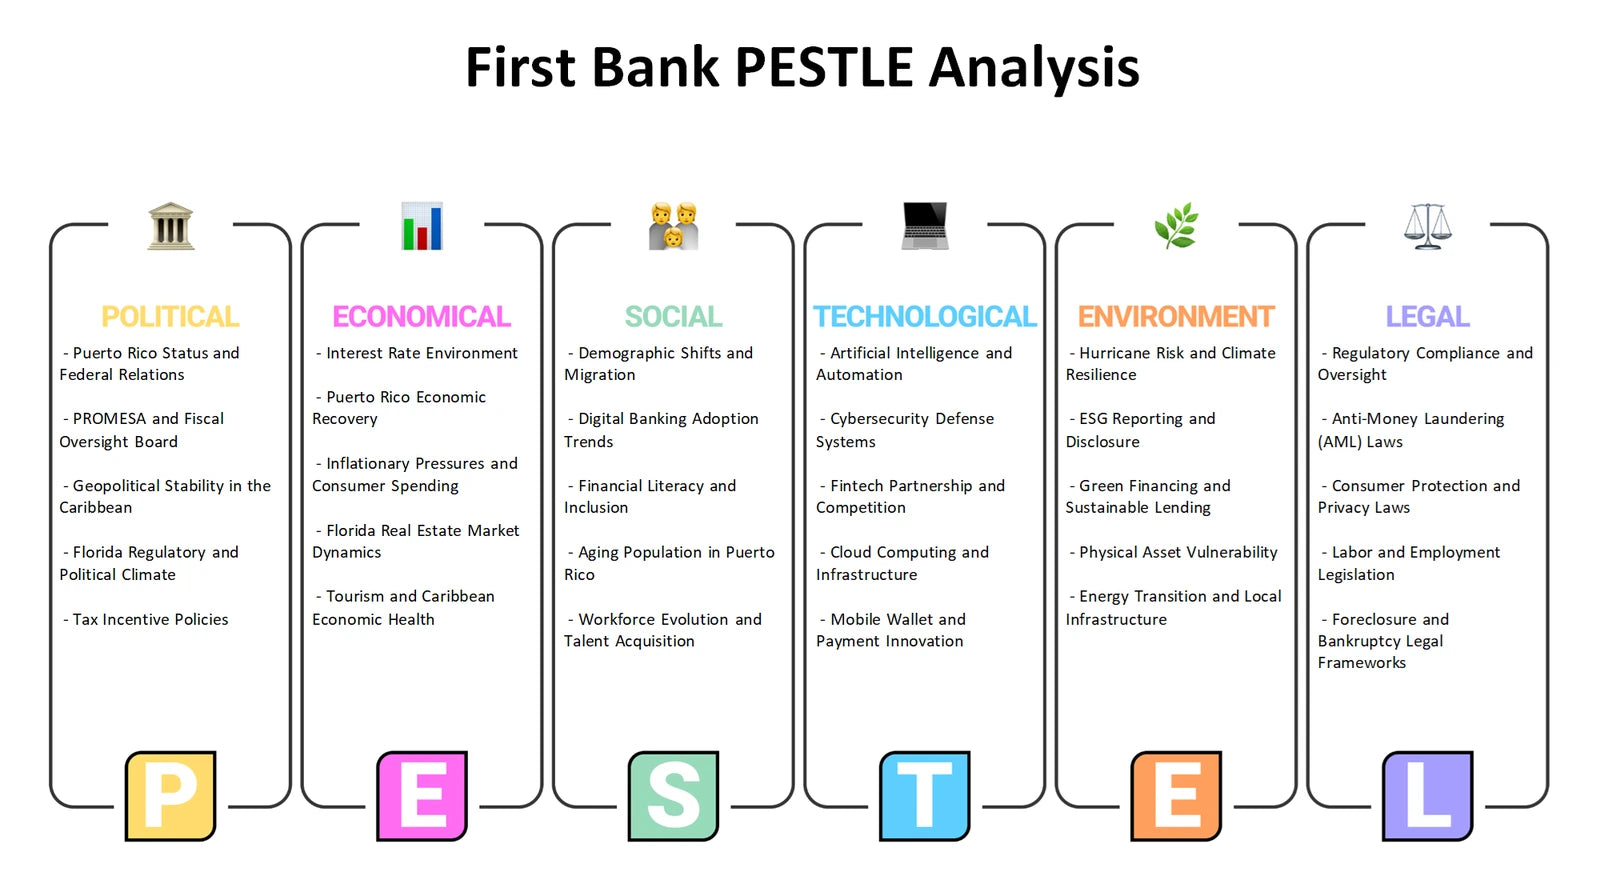
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can First Bank distinguish internal capabilities and constraints from external opportunities and threats when setting priorities?
A First Bank SWOT analysis brings the earlier lenses into one practical decision frame. Strengths and weaknesses are internal: possible areas to assess include relationship-management capability, local market knowledge, technology execution, credit discipline, operating complexity and the capacity to integrate partner-supported services. Opportunities and threats are external: these may include changing customer preferences, non-bank alternatives, competitive intensity, economic uncertainty and evolving regulatory expectations. The framework is deliberately diagnostic. It does not state that any potential strength, weakness, opportunity or threat has already been proven. Instead, it helps users classify evidence correctly and avoid mistaking an external market change for an internal capability, or vice versa.
- Capability reality check. Test whether a perceived differentiator is supported by resources, processes and consistent customer delivery.
- Strategic fit. Compare external openings and risks with the bank’s capacity to respond without diluting its customer proposition.
- Priority synthesis. Use the Excel matrix to organize internal and external observations, then use the Word analysis to develop balanced strategic discussion points.
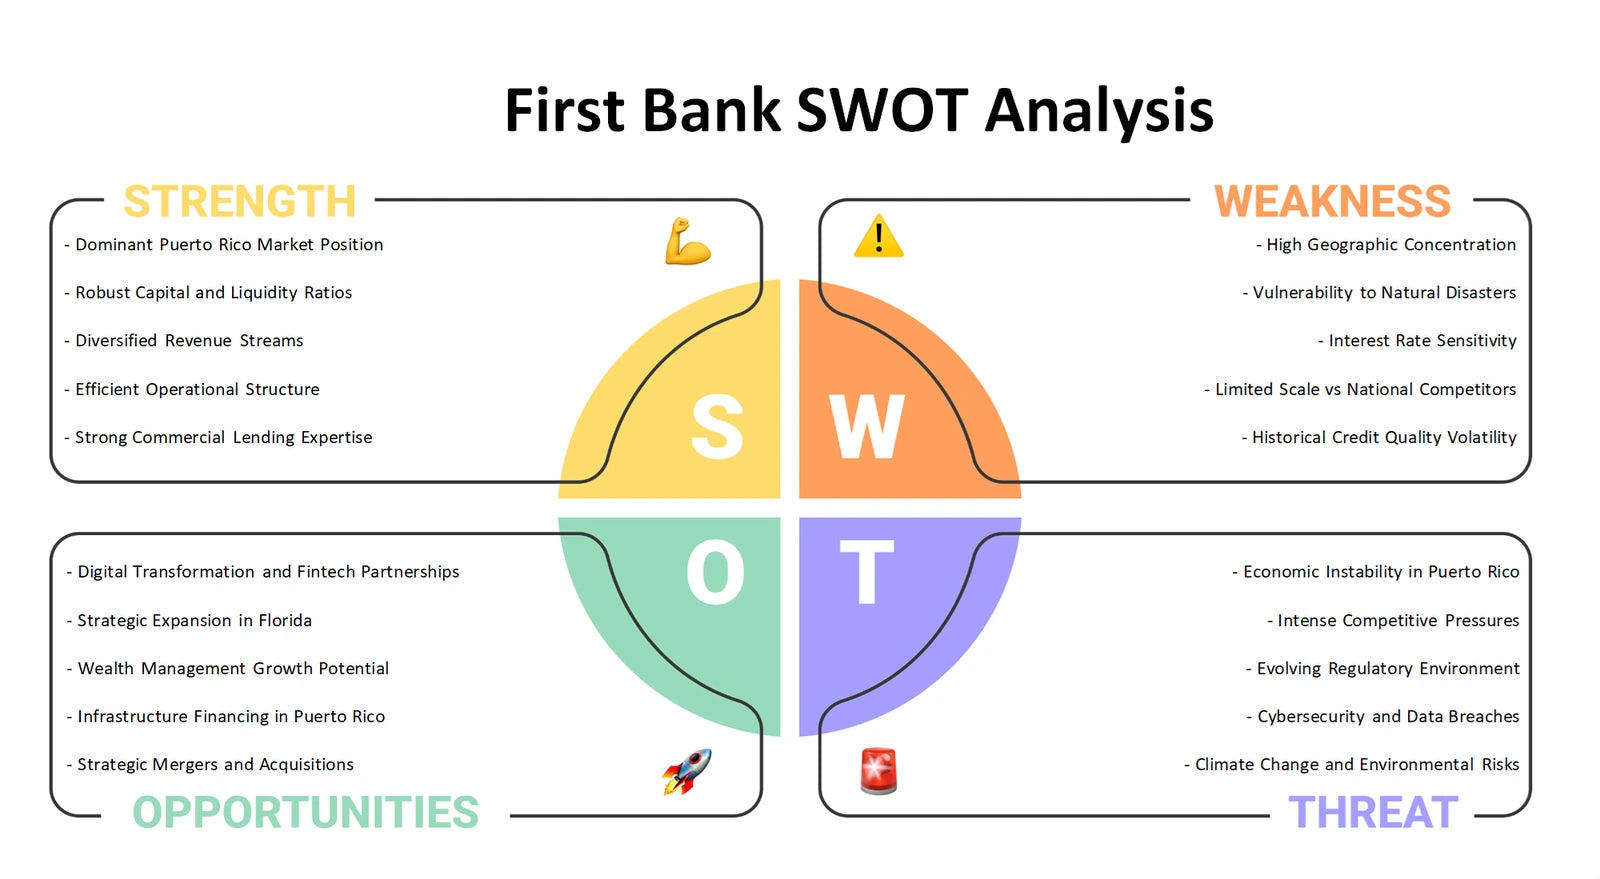
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect customer choice with strategic discipline
For First Bank, the six perspectives work best as connected tools: the BCG Matrix frames portfolio attention; the Business Model Canvas links customer value to operating economics; Five Forces and PESTLE examine competitive and external conditions; the Marketing Mix focuses on customer choice; and SWOT brings internal and external considerations together. The Excel frameworks provide an organized basis for comparison, while the detailed Word analyses support fuller interpretation of the company-specific strategic questions.
Company background: First Bank — FB Financial Corporation SEC submissions profile.