

W. R. Berkley: Underwriting, Competition and Customer Choice – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
W. R. Berkley Strategy Analysis Bundle
This bundle is framed around W. R. Berkley Corporation, the commercial property and casualty insurance business represented by the product context. Its specialist insurance offerings are distributed through independent brokers and agents, connecting commercial policyholders with underwriting businesses that serve particular risk needs. Reinsurance relationships are also relevant to the company context because they can help insurers manage exposure on larger or more concentrated risks.
For W. R. Berkley, value creation depends on more than premium volume: underwriting discipline, distribution access, retained risk, claims handling and technology-supported operations all affect the economics of growth. The six analyses help examine which insurance activities merit resources, how broker and reinsurer relationships fit together, and how external loss, regulatory and competitive pressures could shape strategic choices.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which specialist underwriting activities could justify more capital, attention or distribution support?
The W. R. Berkley BCG Matrix helps separate a portfolio question from a simple premium-growth question. It compares relative market share with market growth, then tests whether a line of business, specialty focus or distribution opportunity may resemble a Star, Cash Cow, Question Mark or Dog. No quadrant should be assumed without evidence; the useful exercise is to compare growth potential against capital needs, loss volatility and the capacity required to support policyholders.
- Portfolio lens. Compare specialist insurance activities by their market momentum and relative competitive position rather than treating all written business alike.
- Capital discipline. Consider where underwriting capacity and reinsurance protection may support expansion, harvesting or closer review.
- Working comparison. Use the Excel matrix to organize candidate activities, then use the Word analysis to interpret why their economics may differ.
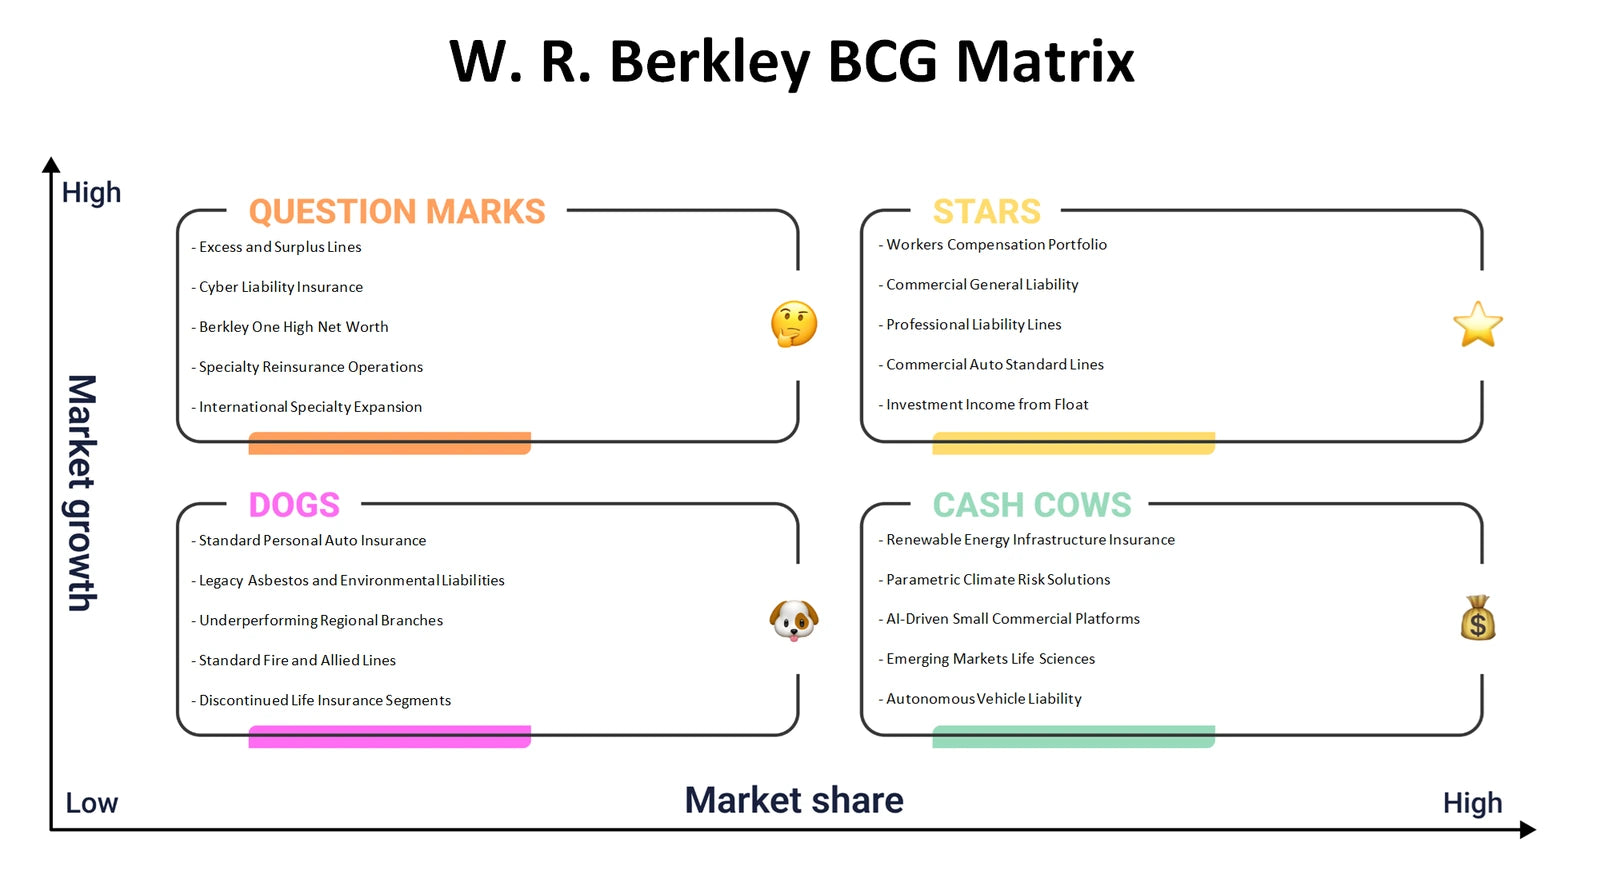
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do specialist underwriting, broker access and risk transfer combine to create economic value?
The W. R. Berkley Business Model Canvas connects all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. Commercial policyholders may value relevant coverage and responsive expertise, while brokers and agents are central channels and relationship partners. The analysis can map how premiums and risk-bearing economics relate to underwriting, claims, technology, reinsurance and the costs of operating a specialist insurer.
- Value delivery. Examine how broker-led access and specialist products can link policyholder needs to underwriting decisions and service expectations.
- Economic engine. Trace the trade-offs among premium income, claims costs, operating expense, retained exposure and reinsurance arrangements.
- Model mapping. Complete the Excel canvas block by block and use the Word analysis to connect each choice to the wider operating model.
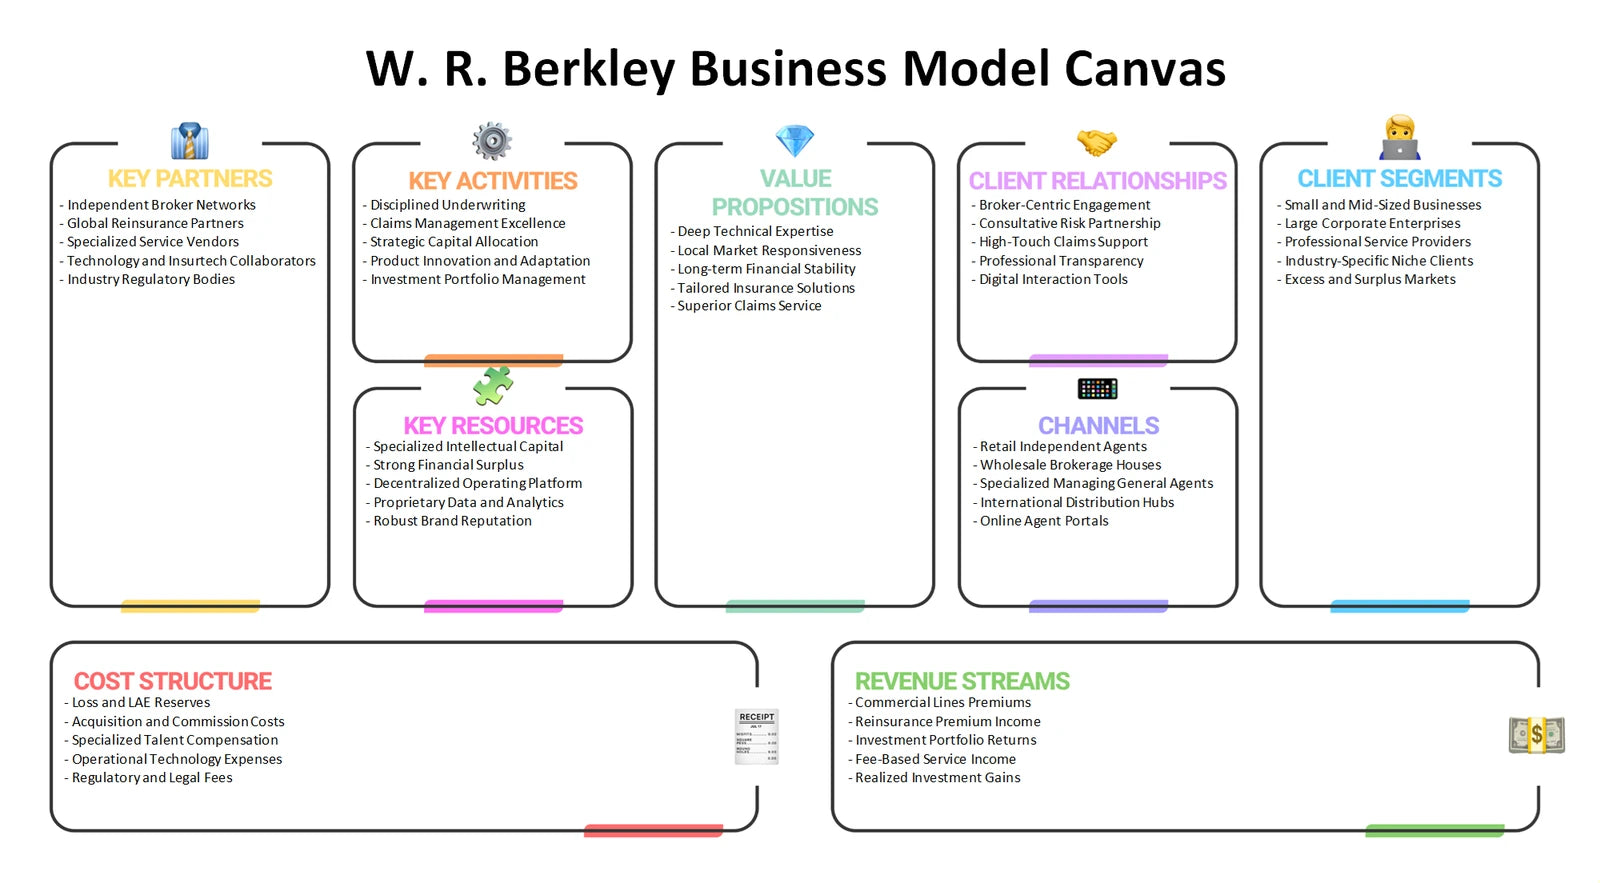
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
Where could industry pressure weaken underwriting returns or bargaining power in commercial insurance?
W. R. Berkley Porter's Five Forces examines the structure around specialist property and casualty insurance. Rivalry can affect terms and underwriting discipline; buyer power can emerge through sophisticated commercial customers and their intermediaries. Supplier power is relevant where reinsurers, data providers or core technology suppliers matter. The framework also considers new entrants facing capital, expertise and regulatory barriers, alongside substitutes such as self-insurance, captives or other methods of retaining risk.
- Competitive pressure. Assess whether competition is likely to centre on coverage design, service, broker relationships, capacity or pricing discipline.
- Risk-transfer dependence. Explore how reinsurance availability and terms could affect the ability to write larger or more volatile exposures.
- Force testing. Use the Excel framework to record evidence for each force, with the Word analysis providing context for the insurance-specific implications.
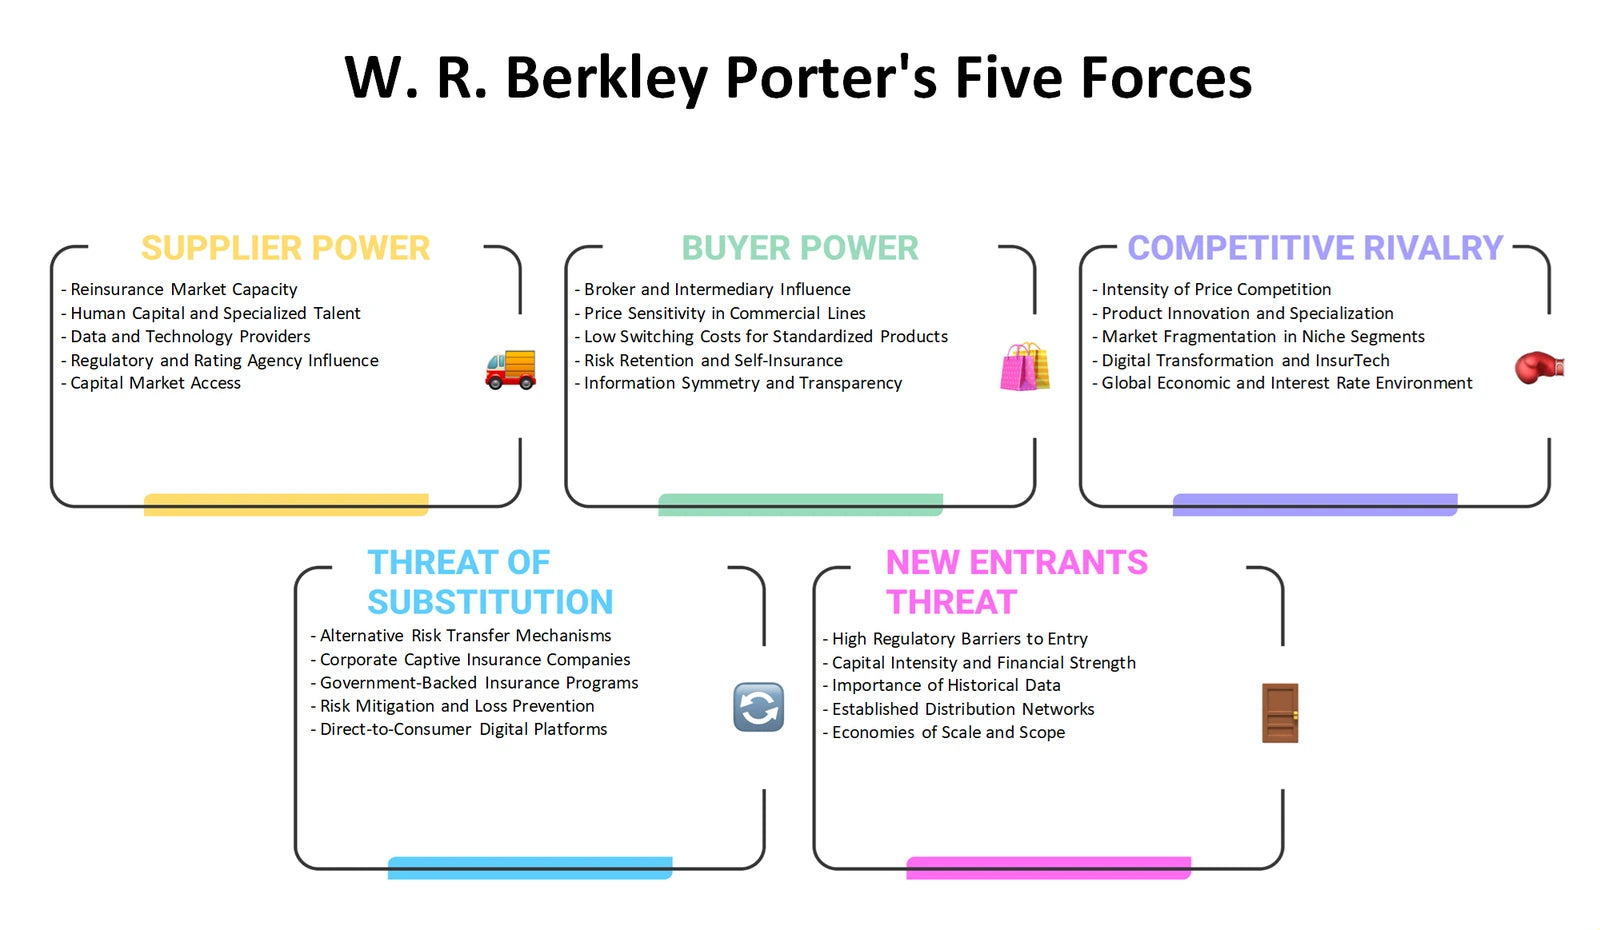
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a broker-distributed insurer align coverage, pricing logic, access and communication around commercial buyers?
The W. R. Berkley Marketing Mix considers Product, Price, Place and Promotion in a regulated business-to-business insurance setting. Product analysis can examine how specialised coverage, limits, policy terms and service address particular commercial risks. Price is better assessed through underwriting assumptions, deductibles, limits and risk-adjusted terms than through a simple list price. Place centres on independent brokers and agents, while promotion can examine the expertise, education and underwriting clarity that help intermediaries present insurance solutions to clients.
- Product fit. Relate coverage design and claims-service expectations to the risk needs of targeted commercial customer groups.
- Channel economics. Consider how broker relationships affect reach, information flow, acquisition cost and policyholder experience.
- 4Ps planning. Use the Excel structure to compare the four decisions and consult the Word analysis when linking them to insurance-market realities.
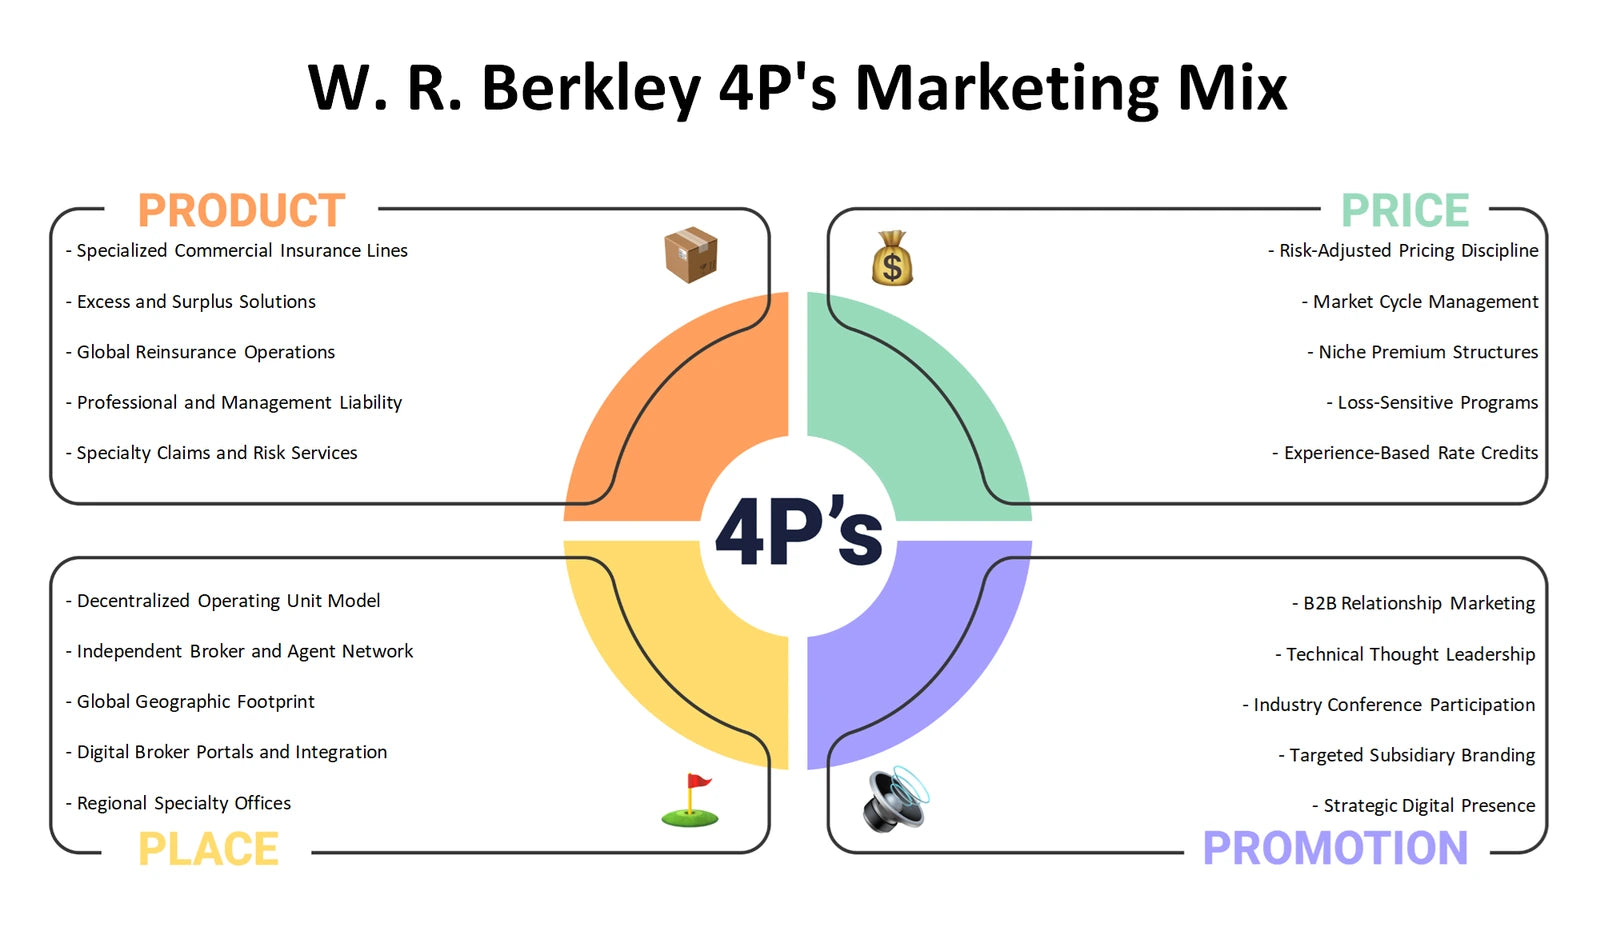
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter commercial risk demand, insurance costs or the ability to write business?
The W. R. Berkley PESTLE analysis, also called PESTEL, distinguishes external conditions from internal execution. Political and legal factors may include insurance supervision, licensing, policy wording and reporting requirements. Economic conditions can affect insured values, claims severity and business demand; social shifts can change customer expectations and emerging risk concerns. Technology influences data, claims and broker connectivity, while environmental conditions can affect catastrophe exposure and resilience expectations. These are questions to assess, not claims that a particular change has already occurred.
- Regulatory horizon. Track policy and legal questions that may change compliance effort, product design or permissible underwriting practices.
- Loss environment. Examine how inflation, severe events and changing exposure patterns could influence claims costs and risk selection.
- External scan. Use the Excel categories to prioritize signals, then use the Word analysis to interpret relevance for a specialist P&C insurer.
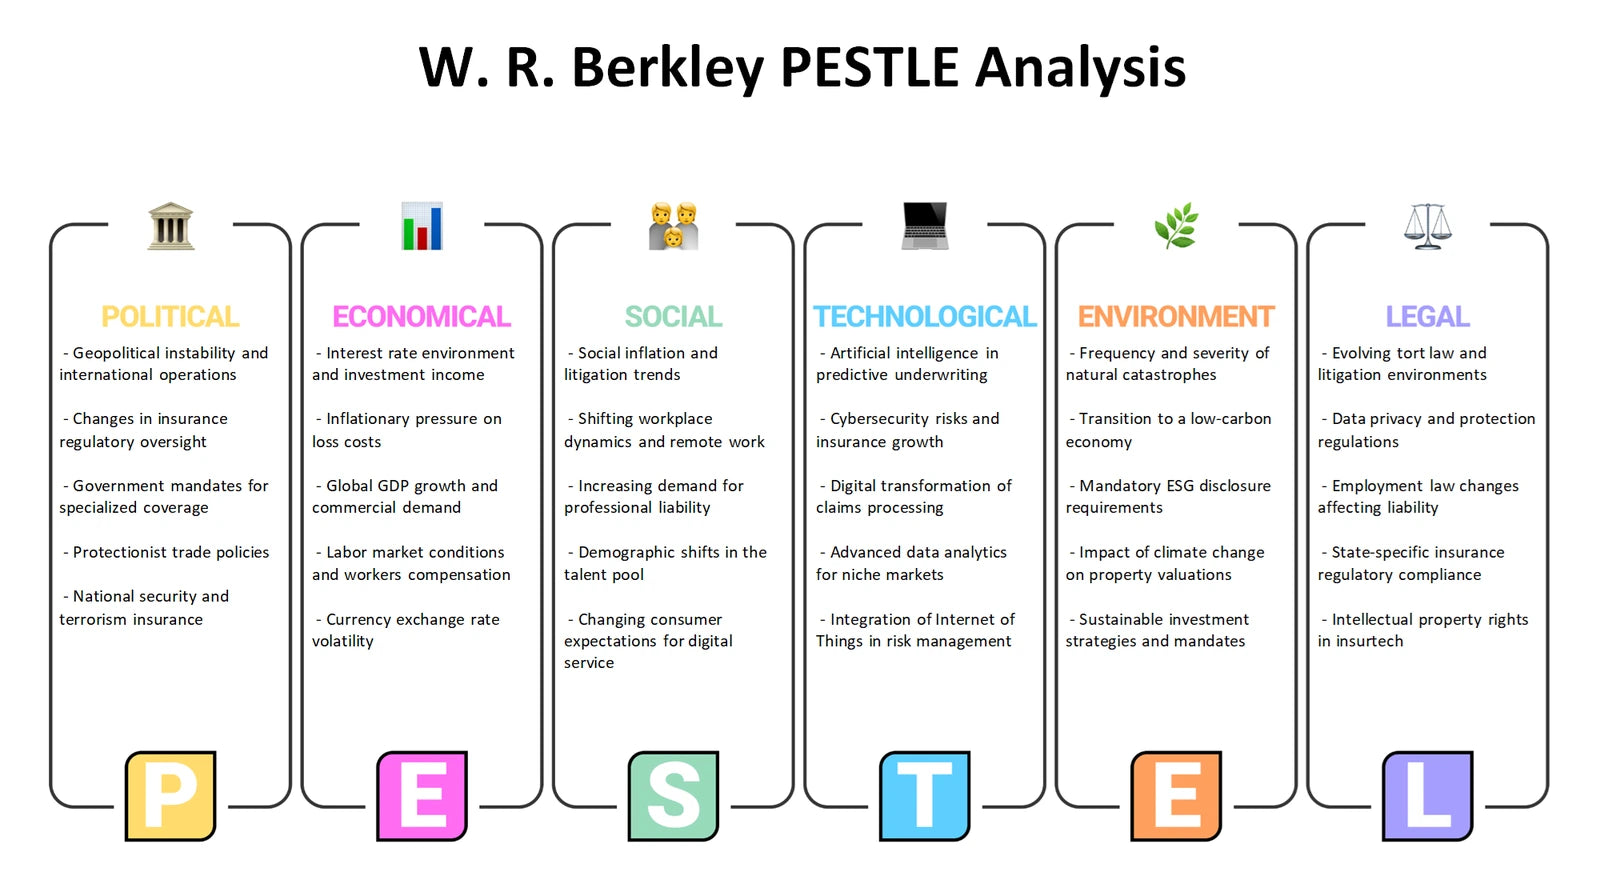
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can W. R. Berkley match its operating capabilities to an uncertain commercial insurance environment?
The W. R. Berkley SWOT analysis keeps internal and external factors distinct. Broker and agent distribution, specialist underwriting knowledge, reinsurance relationships and technology capability can be examined as potential strengths to validate. Dependence on intermediaries, risk-transfer capacity or complex operating processes may represent possible internal constraints. Opportunities and threats sit outside the firm: changing commercial risk needs may create demand, while competitive pricing, loss volatility, regulation and catastrophic events can pressure results. The framework is most useful when each item is supported, classified correctly and connected to a strategic response.
- Capability check. Test which resources and relationships may improve underwriting reach, risk selection or service quality.
- Exposure balance. Separate controllable weaknesses from external threats such as changing claims conditions or market-cycle pressure.
- Decision synthesis. Use the Excel SWOT grid to prioritize issues and the Word analysis to explore how strengths may address opportunities or threats.
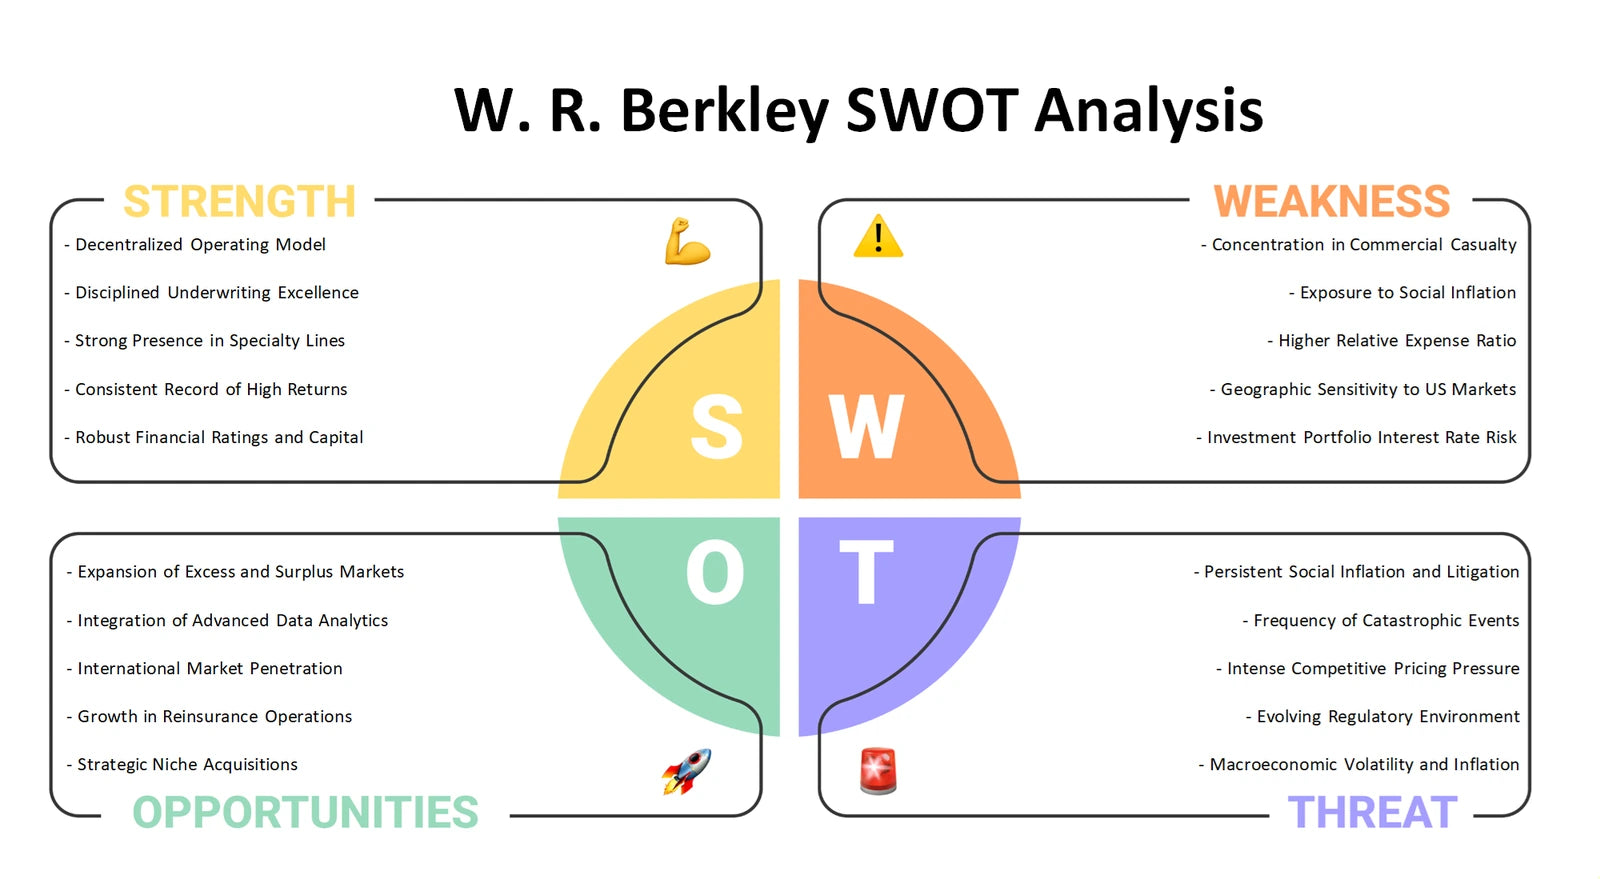
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect underwriting economics with strategic choices
Together, the six perspectives move from portfolio allocation and business-model economics to market structure, broker-led marketing, external change and strategic fit. The Excel frameworks provide organized places to compare evidence and questions, while the detailed Word files help develop company-specific interpretation for W. R. Berkley without treating any preview as a complete analysis or a predetermined recommendation.
Company background: W. R. Berkley — product-context page.