

Essent: Market Access and Partnerships – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Essent Strategy Analysis Bundle
The intended Essent business is the mortgage-insurance company reflected in this bundle’s product context. It serves mortgage-lending customers in the U.S. housing-finance ecosystem by helping manage residential mortgage credit risk. Its business model depends on sound underwriting, risk monitoring, insurer capital and continued eligibility to participate in the government-sponsored enterprise mortgage market.
That operating context makes risk transfer, lender relationships and technology-enabled decisioning especially useful subjects for strategic analysis. The six connected frameworks help examine questions such as where portfolio resources belong, how value reaches lender customers, and how policy, housing-market and capital-market conditions could shape the business without presenting analytical possibilities as established findings.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which Essent offerings, customer opportunities or operating priorities merit investment when market growth and relative market share are considered together?
An Essent BCG Matrix provides a disciplined way to compare a portfolio through two distinct criteria: the growth of the relevant market and relative market share. For a mortgage insurer, the relevant choices may include lender-facing coverage propositions, borrower or loan segments, distribution-support capabilities and related risk-management priorities. The familiar Stars, Cash Cows, Question Marks and Dogs categories are analytical tools, not claimed placements for Essent. They help prevent a high-growth mortgage opportunity from being confused with a strong competitive position, or a mature activity from being dismissed despite its potential contribution to capital generation and customer retention.
- Portfolio boundaries. Compare activities at a useful level of detail, separating insurance-market opportunity from individual loan-credit performance.
- Capital discipline. Consider how growth ambitions interact with underwriting capacity, GSE participation requirements and the need to manage mortgage credit exposure.
- Framework application. Use the Excel matrix to test comparable portfolio assumptions, then use the Word analysis to interpret what each possible position could mean for resource priorities.
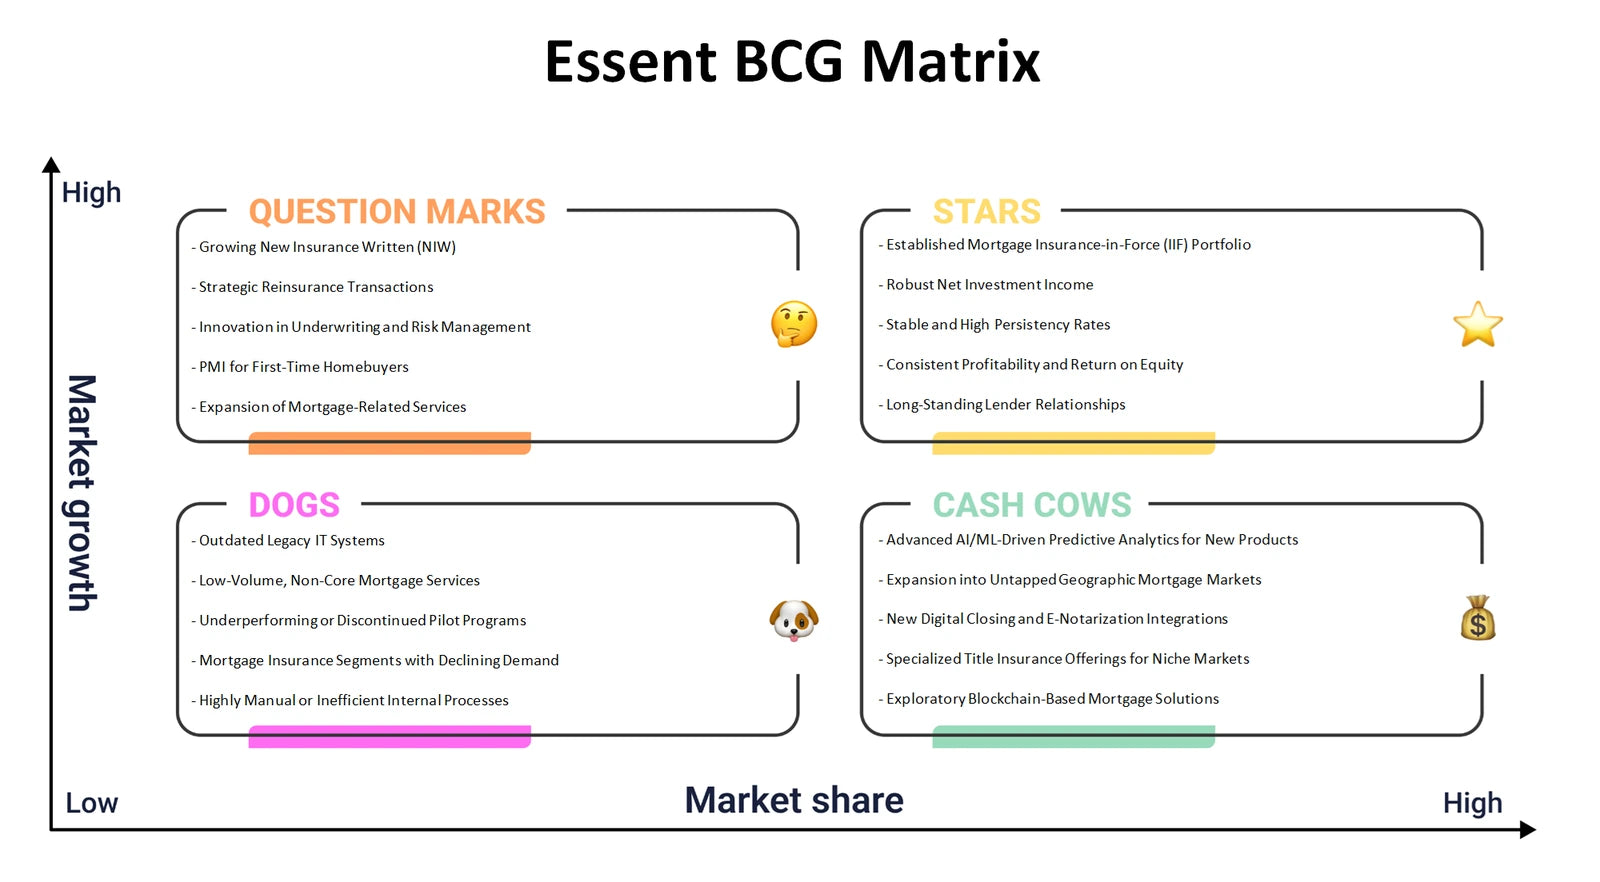
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do Essent’s lender relationships, mortgage-credit capabilities and risk-transfer arrangements connect to a sustainable insurance model?
The Essent Business Model Canvas examines the logic joining nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. Lenders are central customer segments, while mortgage insurance and credit-risk support form the value proposition being examined. Channels and relationships can be assessed through how insurance is ordered, supported and maintained in lender workflows. The model also directs attention to premium-based economics, underwriting and claims-related activities, data and risk expertise, reinsurance and capital-markets relationships, and the costs of operating within a regulated housing-finance market. This matters because an apparently attractive customer proposition must also be deliverable with appropriate capital efficiency and risk controls.
- Value-to-revenue link. Map how lender service, coverage decisions and insurance economics may reinforce one another across the customer journey.
- Partner dependency. Examine why reinsurers, capital-markets investors and technology or data providers can affect both resilience and cost structure.
- Model mapping. Populate the Excel canvas systematically and use the Word analysis to connect individual blocks into a coherent discussion of Essent’s business logic.
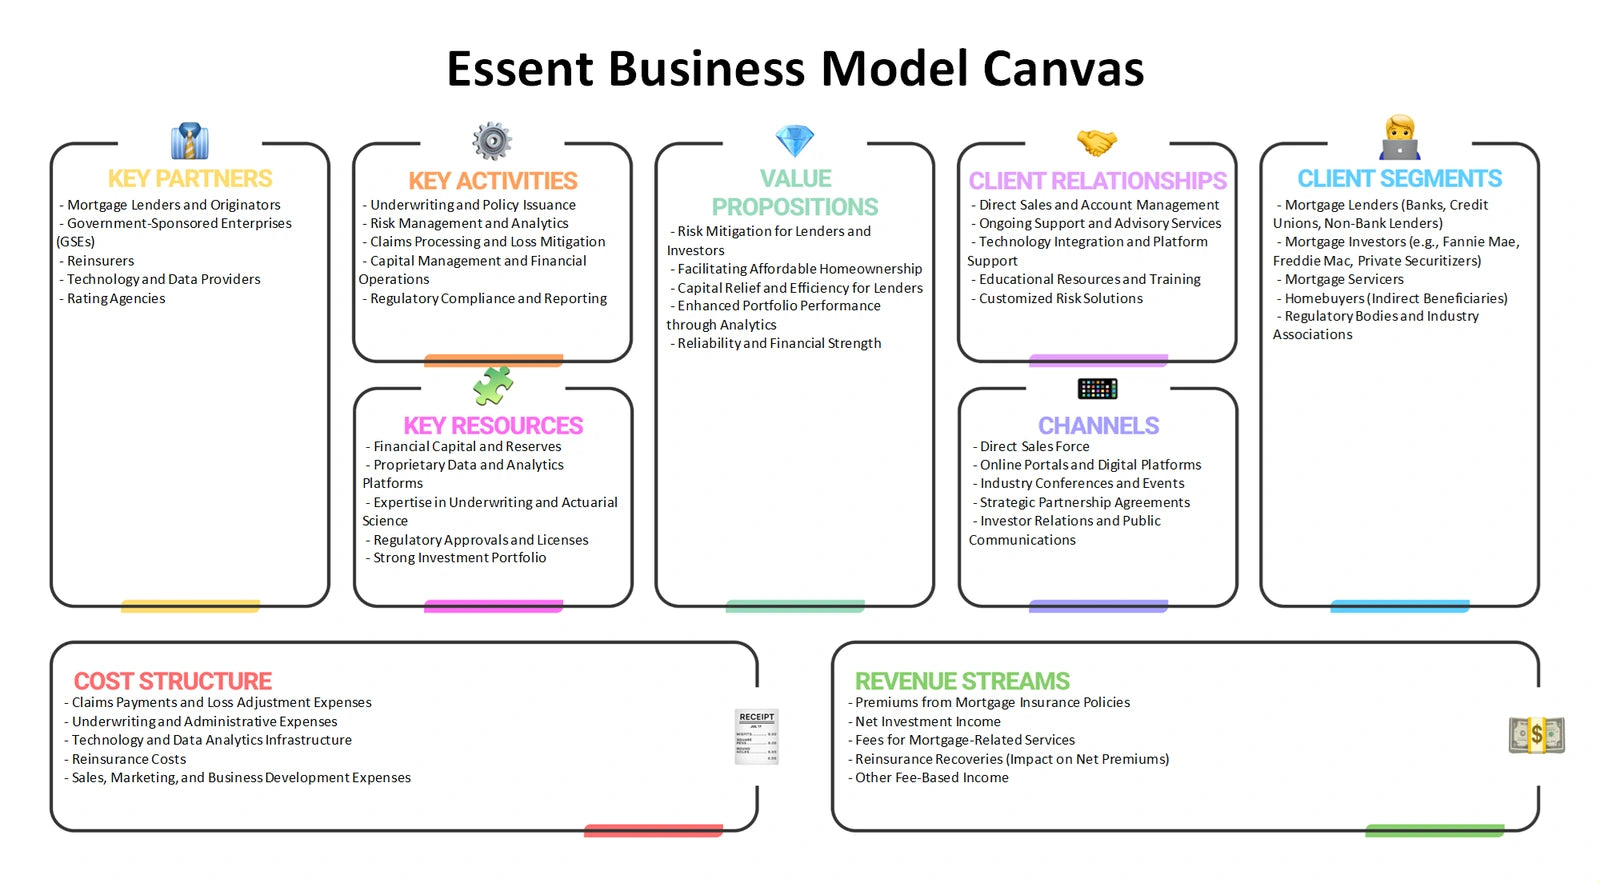
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could influence Essent’s ability to serve lenders profitably while maintaining disciplined mortgage-credit risk management?
Essent Porter’s Five Forces analysis frames competition beyond a simple list of other insurers. Rivalry concerns how mortgage insurers compete for lender relationships and eligible business. Buyer power considers lender concentration, procurement choices and the importance of service quality in underwriting workflows. Supplier power can include the influence of reinsurance capacity, capital providers, data inputs and specialist technology on operating flexibility. The threat of new entrants is shaped by capital intensity, regulation, credibility and access to lender distribution. Substitutes are alternative ways for borrowers, lenders or the housing-finance system to meet mortgage credit-enhancement needs, rather than merely direct insurance competitors. The framework helps distinguish structural pressure from a temporary business-cycle change.
- Lender choice. Assess which service, underwriting and relationship factors may affect switching or purchasing leverage for mortgage-lending customers.
- Risk-capacity inputs. Explore how the availability and terms of reinsurance or investor capital can influence the economics of accepting insured risk.
- Pressure comparison. Use the Excel structure to organize evidence by force, then consult the Word analysis to relate the forces to practical strategic questions.
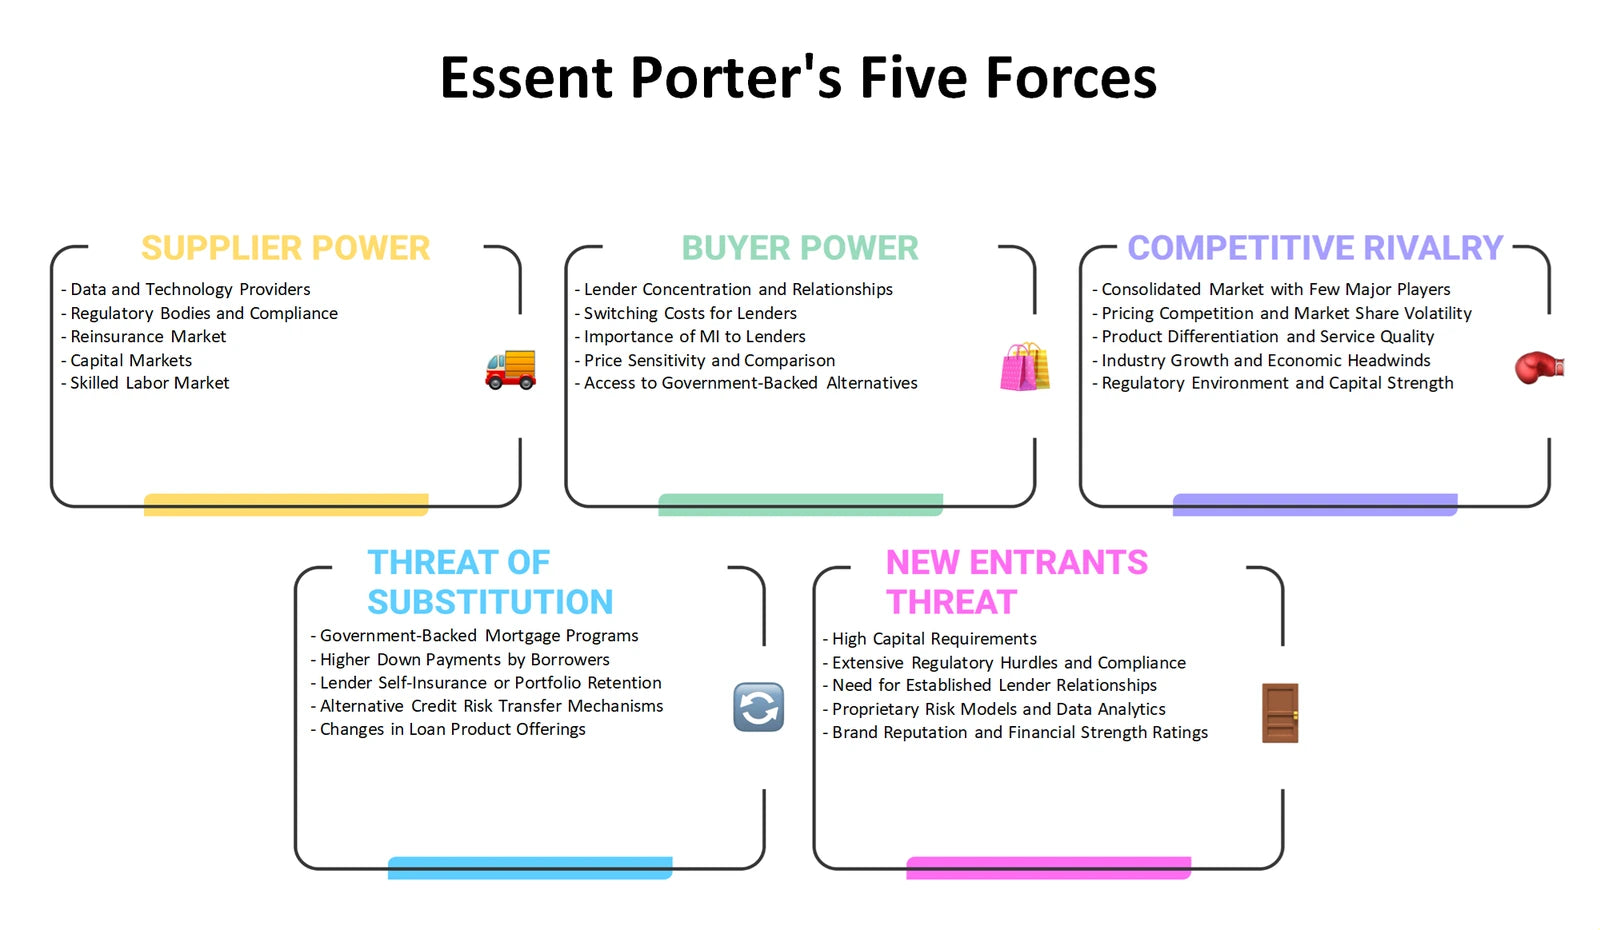
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can Essent align its mortgage-insurance proposition, pricing approach, lender access and communications with a regulated B2B buying process?
An Essent Marketing Mix examines Product, Price, Place and Promotion in the context of mortgage insurance rather than consumer retail marketing. Product can include the insurance coverage, underwriting support, lender-facing tools and ease of ordering that contribute to the lender experience. Price is a question of risk-sensitive insurance economics and value communication, not an assumed public price list. Place concerns the routes through which lender customers access coverage, including integration into mortgage-origination processes and relationship-based distribution. Promotion focuses on credible communication with professional customers about eligibility, service and risk-management value. The four elements must remain aligned: a streamlined technology experience has limited value if the insurance proposition, pricing logic or lender support does not meet customer needs.
- Offering design. Compare how coverage, underwriting support and digital ordering can be framed around lender workflow needs.
- Commercial coherence. Test whether pricing considerations, distribution access and professional communications reinforce the same value proposition.
- Go-to-market review. Use the Excel 4Ps layout to identify gaps or trade-offs, with the Word analysis providing context for interpreting B2B mortgage-insurance choices.
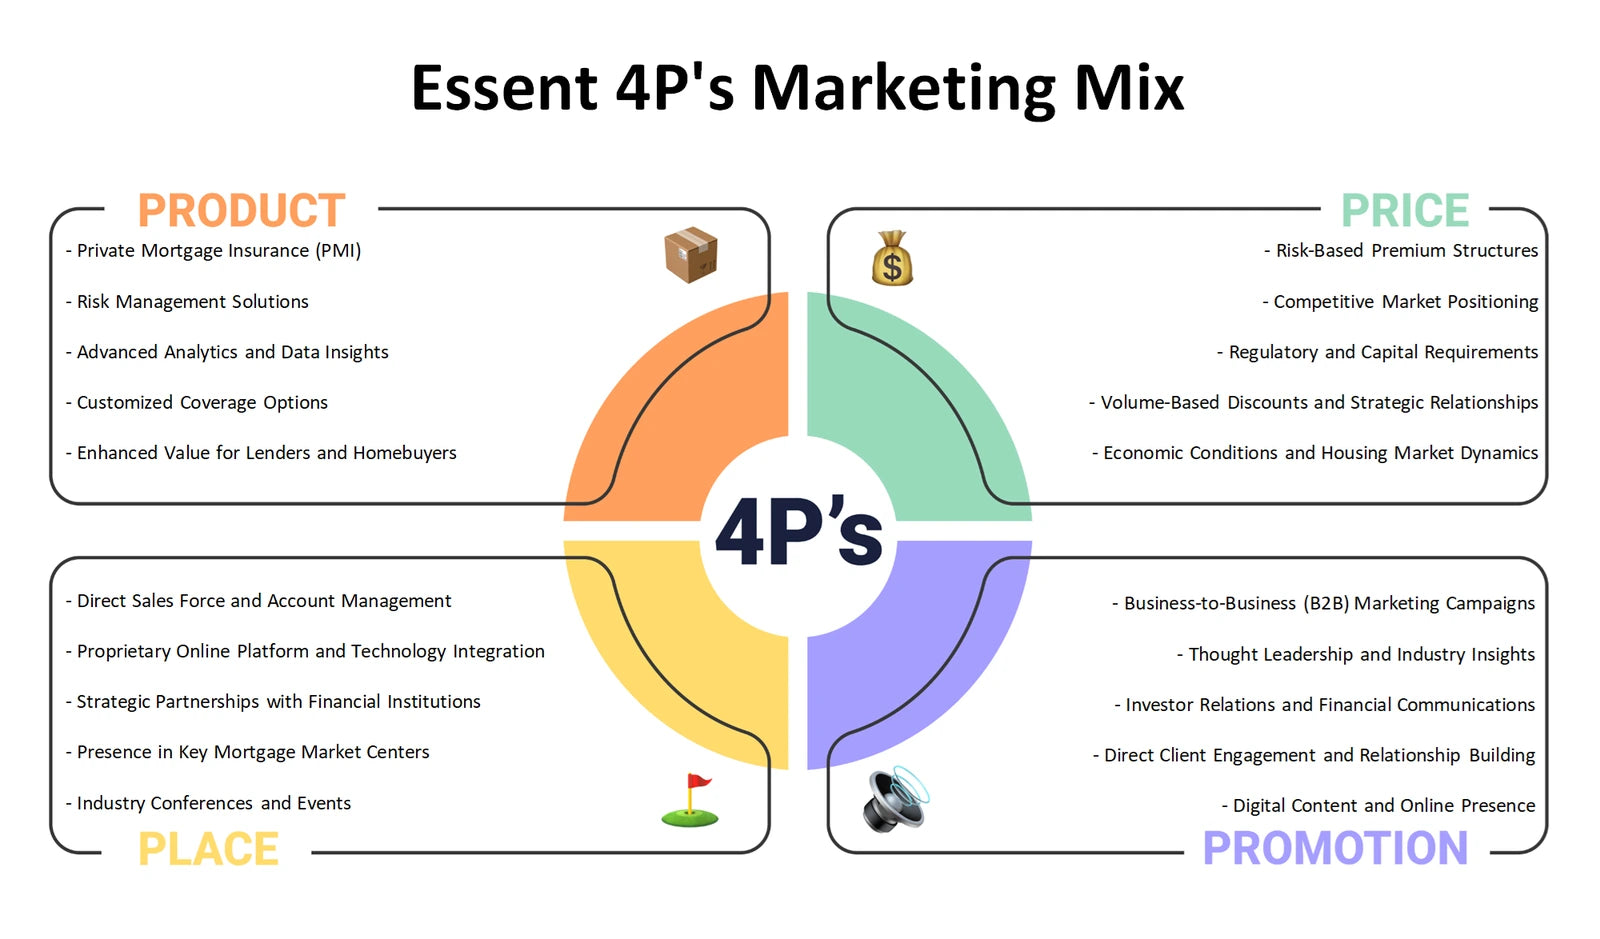
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should Essent monitor because they could alter mortgage demand, insured-credit risk, capital access or operating obligations?
An Essent PESTLE analysis, also known as PESTEL, separates external influences into Political, Economic, Social, Technological, Legal and Environmental dimensions. Political and legal questions include the policy and eligibility environment surrounding U.S. housing finance and GSE participation. Economic factors can include housing activity, employment conditions, borrower affordability and capital-market conditions, without assuming a particular rate outlook. Social themes may cover household formation, homeownership needs and customer expectations for simpler mortgage processes. Technological change matters where data quality, automated workflows and risk assessment affect service and underwriting. Environmental considerations can be assessed through property-related exposure, resilience expectations and the wider consequences of climate events for housing markets. These are categories for monitoring and analysis, not claims that a new policy or event has occurred.
- External scanning. Separate macro housing-cycle questions from regulatory requirements and longer-term shifts in borrower or lender expectations.
- Interconnected exposure. Consider how policy, economic conditions and technology may jointly affect eligibility, risk selection and operational investment.
- Monitoring tool. Organize signals and implications in the Excel PESTLE framework, then use the Word analysis to develop a more reasoned external-environment discussion.
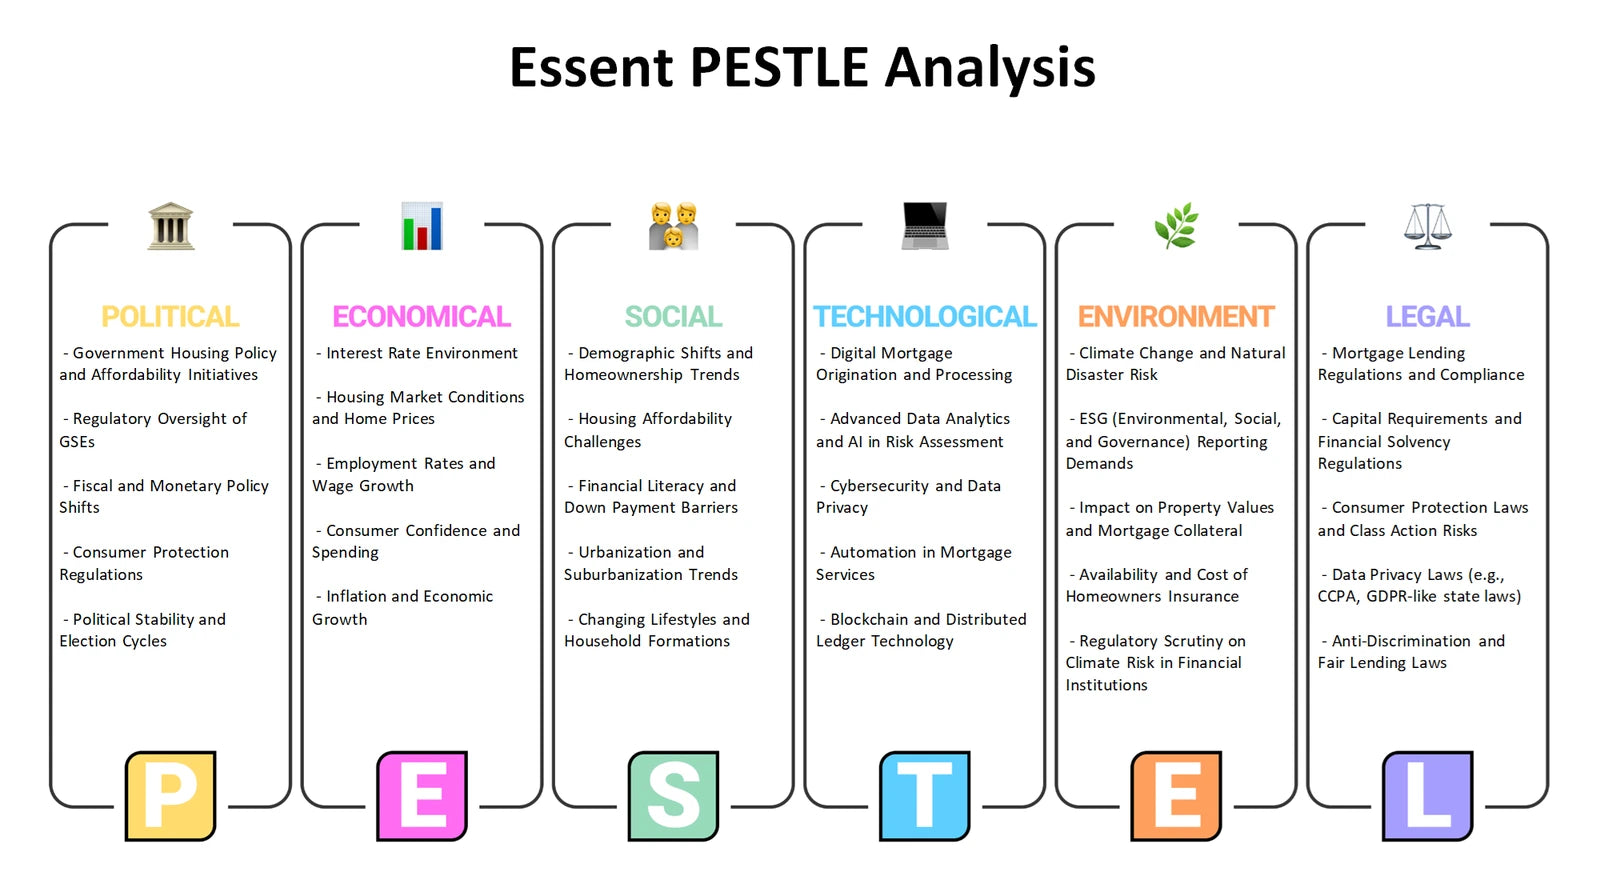
PESTLE analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Essent distinguish internal capabilities and constraints from external opportunities and threats in mortgage insurance?
An Essent SWOT analysis keeps internal and external issues properly separated. Strengths and weaknesses concern resources and capabilities within the business: for example, the quality of underwriting processes, lender-service capabilities, technology integration, risk expertise or dependence on particular operating resources are topics to examine, not pre-set conclusions. Opportunities and threats arise outside the organization, such as changes in mortgage-market demand, housing-finance policy, risk-transfer availability, technology expectations or credit conditions. This classification matters because a favorable market opportunity does not itself create an internal capability, and an external threat cannot be solved simply by relabelling it as a weakness. The framework supports a candid comparison between what Essent can influence directly and the conditions to which it must adapt.
- Internal reality. Evaluate operational, underwriting, relationship and capital-management capabilities separately from broad market conditions.
- External choice. Identify opportunities and threats that may require a response while avoiding the assumption that every market change is positive or controllable.
- Priority synthesis. Use the Excel SWOT grid to classify evidence clearly, then use the Word analysis to explore links between internal factors and external scenarios.
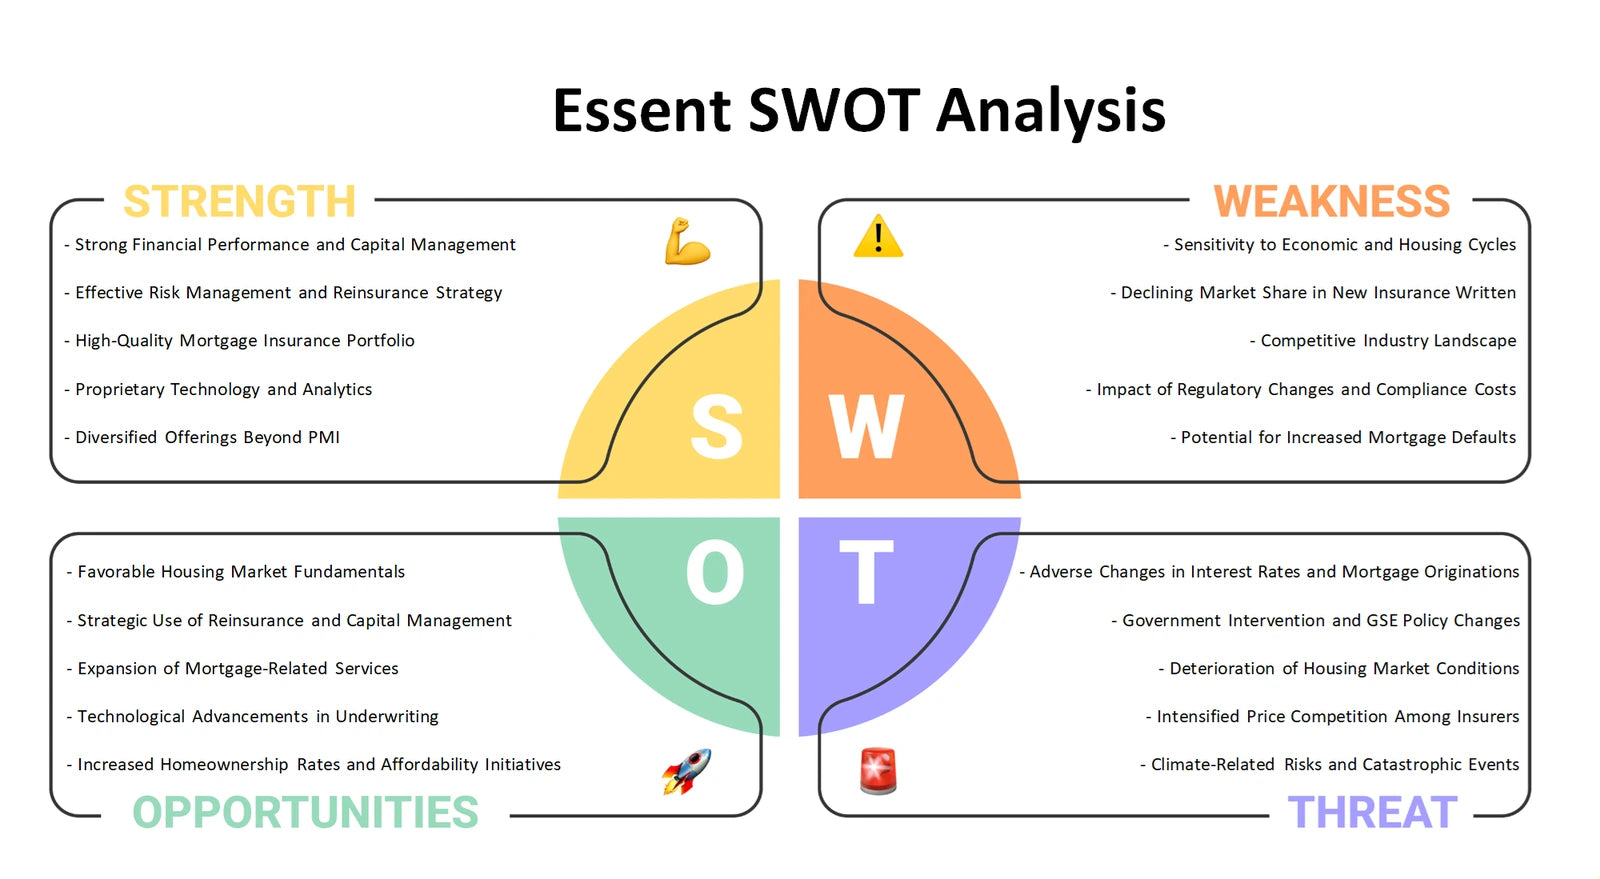
SWOT analysis summary preview. The full company analysis is provided in Excel and Word.
Bring mortgage-insurance strategy into one connected view
Together, the six perspectives help turn separate questions about Essent’s portfolio, operating model, industry structure, lender-facing marketing, external environment and strategic position into a more coherent analysis. The Excel frameworks provide structured places to compare issues and record assumptions, while the detailed Word files support fuller interpretation of the company-specific context. Used together, they can help customers develop more organized strategic discussion without treating framework categories as automatic conclusions or investment advice.
Company background: Essent — product-context page.