

Colony Bank: Banking Business and Partnerships – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Colony Bank Strategy Analysis Bundle
This bundle addresses the Colony Bank banking business described in the supplied company context. That context identifies small-business financing through government-guaranteed SBA lending and a digital-banking infrastructure relationship with fintech provider PortX. These details make lending access, customer service and technology delivery useful subjects for structured strategy analysis.
The available background is business context rather than current financial evidence. Instead of assuming performance outcomes, the six frameworks help examine practical questions: which banking activities merit resources, how SBA lending and digital services create value, and how regulation, competition and technology dependencies may shape priorities.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which Colony Bank activities deserve greater resources when market growth is considered alongside relative market share?
A Colony Bank BCG Matrix helps separate portfolio logic from assumptions about results. It can compare lending programmes, small-business services and digitally enabled offerings using the two BCG criteria: market growth and relative market share. The resulting Stars, Cash Cows, Question Marks and Dogs are analytical categories, not pre-assigned labels for any Colony Bank activity. For a bank balancing SBA lending capability with technology investment, the useful question is whether an activity should be funded for growth, maintained for contribution, tested carefully or reviewed for a different role.
- Portfolio comparison. Contrast established banking activities with newer digital propositions without inventing market-share outcomes.
- Resource discipline. Link growth potential to the staffing, technology and risk-management attention an activity may require.
- Structured review. Use the Excel framework to document comparison inputs, then use the Word analysis to explain the strategic reasoning behind possible priorities.
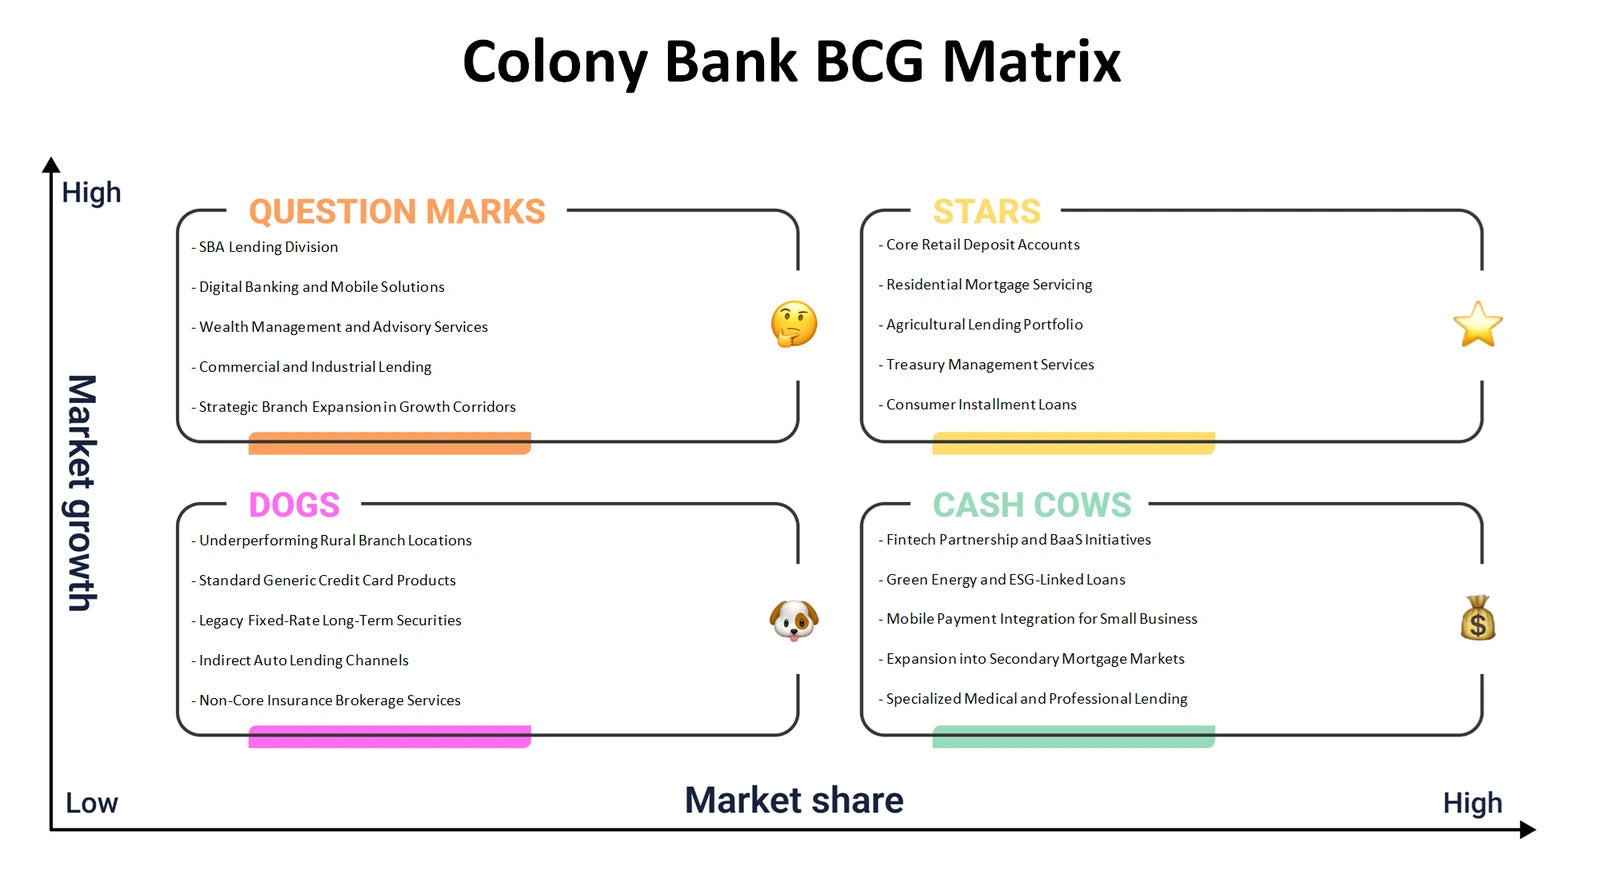
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer needs, lending delivery and digital infrastructure fit together in Colony Bank's value-creation model?
The Colony Bank Business Model Canvas connects all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. Small businesses seeking finance are a relevant segment to examine, while SBA programme access and convenient digital service may shape the value proposition. The framework also helps trace the connection between lending relationships, technology partners such as PortX, operational capabilities and the economic cost of serving customers. It is a way to test how the model hangs together rather than to assume that every component is already optimised.
- Value chain. Map how a customer moves from financing need through relationship, channel, underwriting and ongoing service.
- Partnership logic. Consider how specialised technology support may affect key resources, activities, costs and service speed.
- Connected evidence. Populate the Excel canvas by block and use the Word analysis to interpret dependencies between customer value and bank economics.
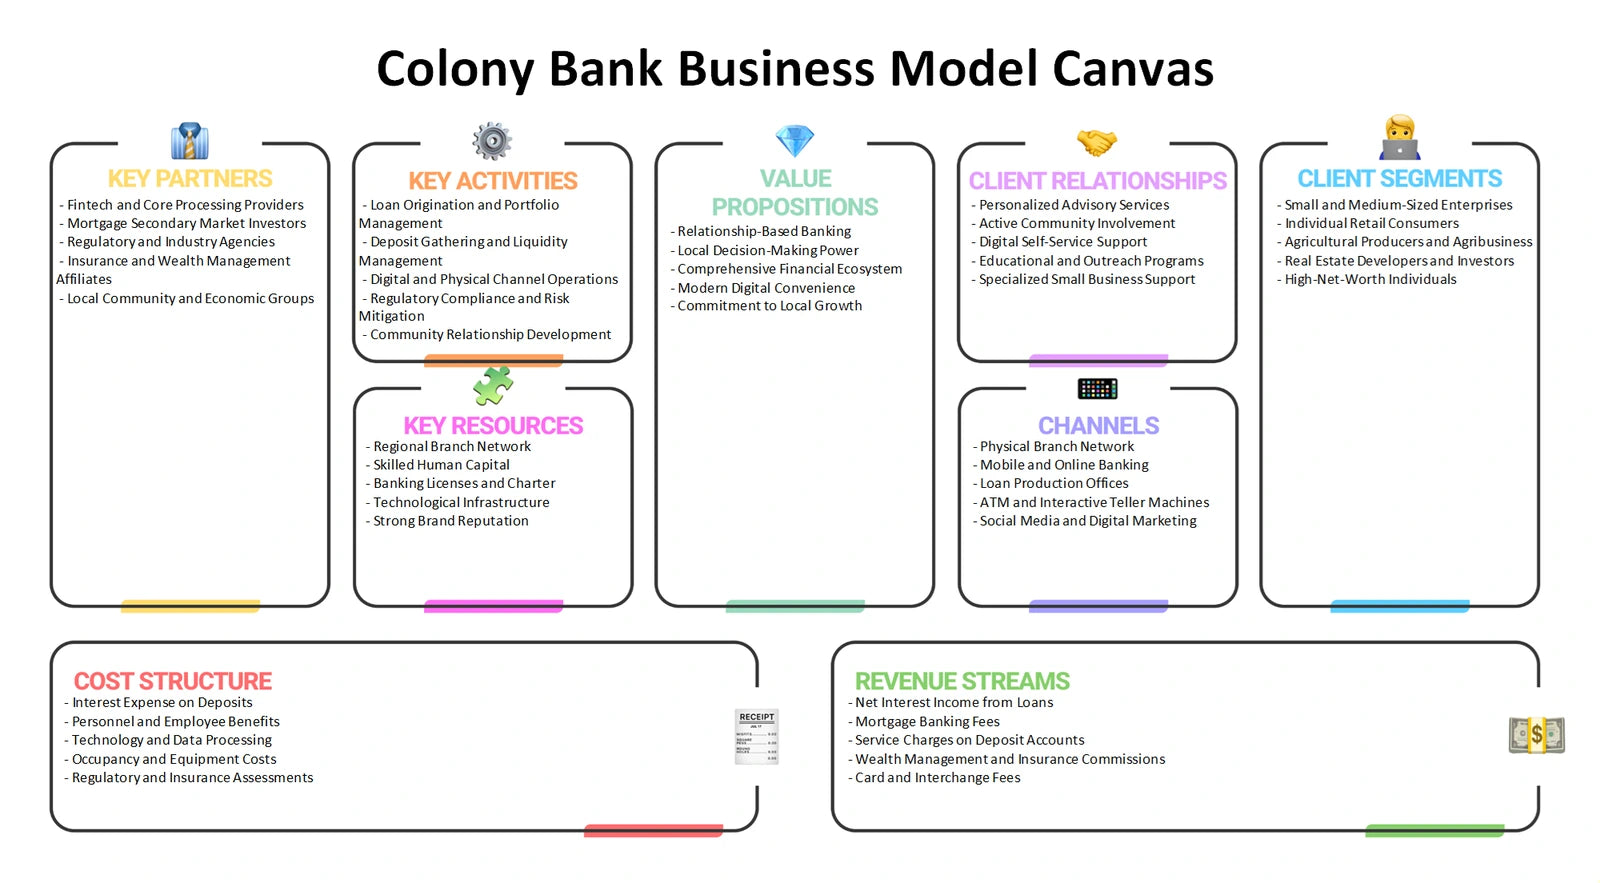
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could affect the attractiveness of small-business banking and digitally delivered financial services?
A Colony Bank Porter's Five Forces analysis examines rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes around the relevant banking activities. Rivalry can include competition for qualified borrowers and deposits; buyer power concerns customers' ability to compare terms, service and convenience. Technology providers, payment infrastructure and funding conditions can matter to supplier power. New digital entrants may lower barriers in selected services, while substitutes include non-bank finance or other ways a small business can obtain working capital. The framework does not assign force scores; it helps organise the pressures that could influence margins, differentiation and service design.
- Competitive pressure. Distinguish direct banking competition from substitutes that address the same small-business funding need.
- Dependency exposure. Examine where vendors, platforms or external infrastructure may affect negotiating leverage and operational resilience.
- Scenario record. Use Excel to compare each force and the Word analysis to preserve the assumptions and implications behind that comparison.
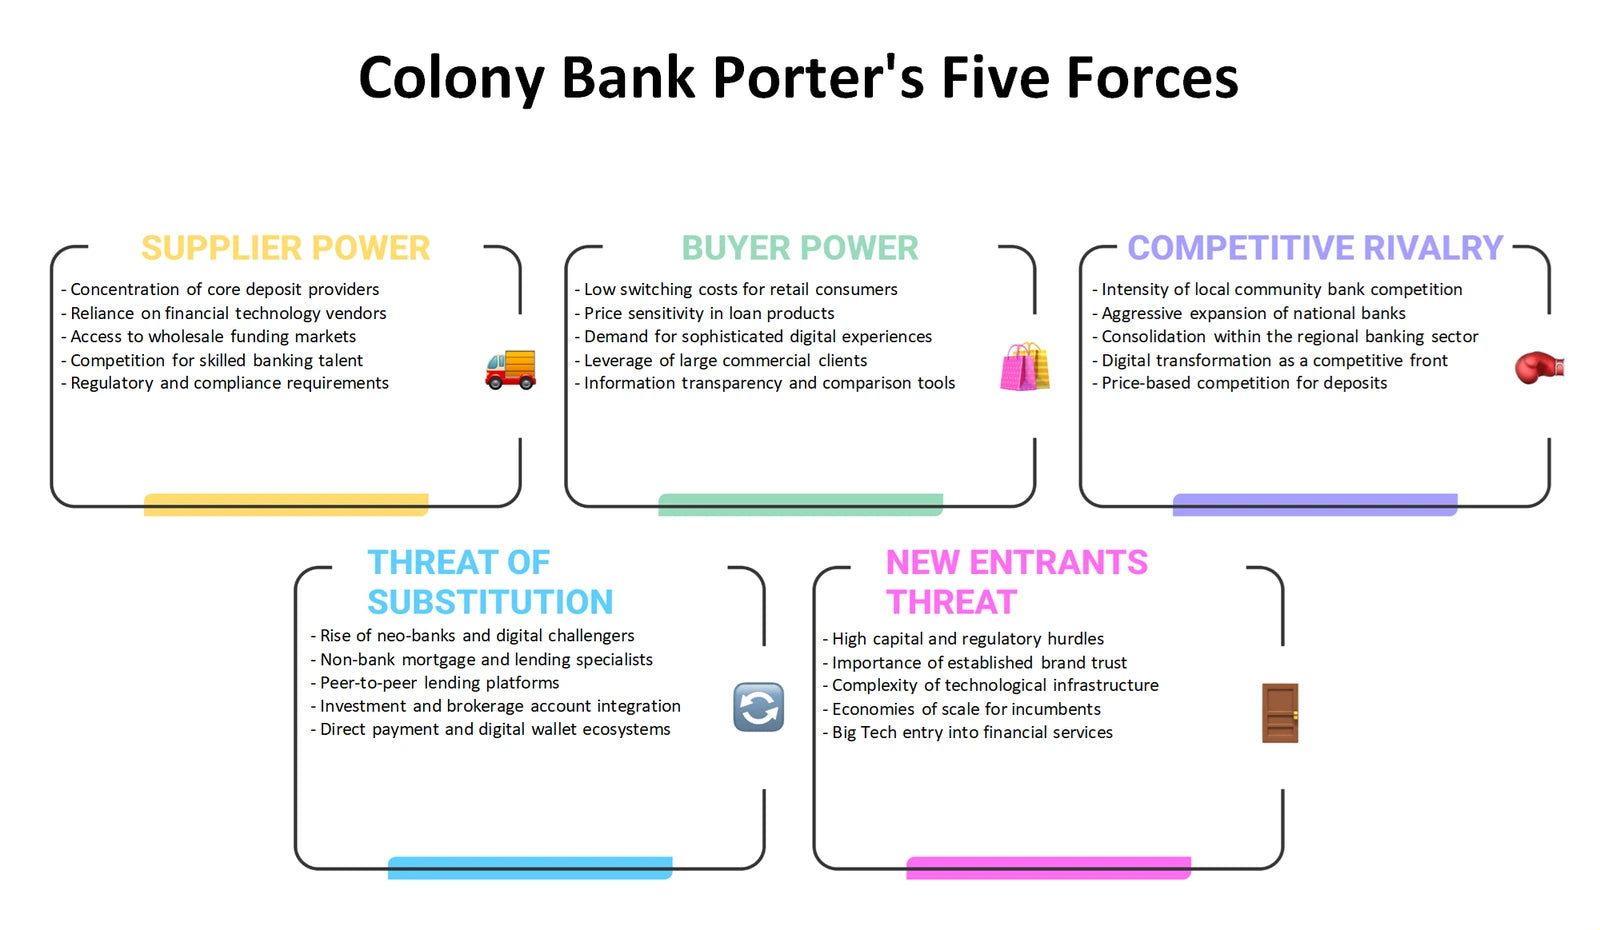
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can Colony Bank align its banking offer, pricing logic, customer access and communication for small-business needs?
A Colony Bank Marketing Mix review applies Product, Price, Place and Promotion to a regulated service business. Product can cover the practical fit of SBA-backed finance and associated banking services. Price should be assessed as a combination of lending terms, fees, transparency and risk-based economics rather than as an assumed advertised rate. Place considers the routes through which customers can engage, including relationship-led and digitally supported journeys where relevant. Promotion examines how a bank communicates credibility, eligibility and service value without treating marketing as separate from compliance and customer understanding.
- Offer clarity. Test whether financing propositions address the needs and decision process of small-business customers.
- Channel fit. Compare the service implications of human guidance, digital access and hand-offs between them.
- Planning aid. Use the Excel framework to arrange the four Ps, then consult the Word analysis when linking customer-facing choices to banking operations.
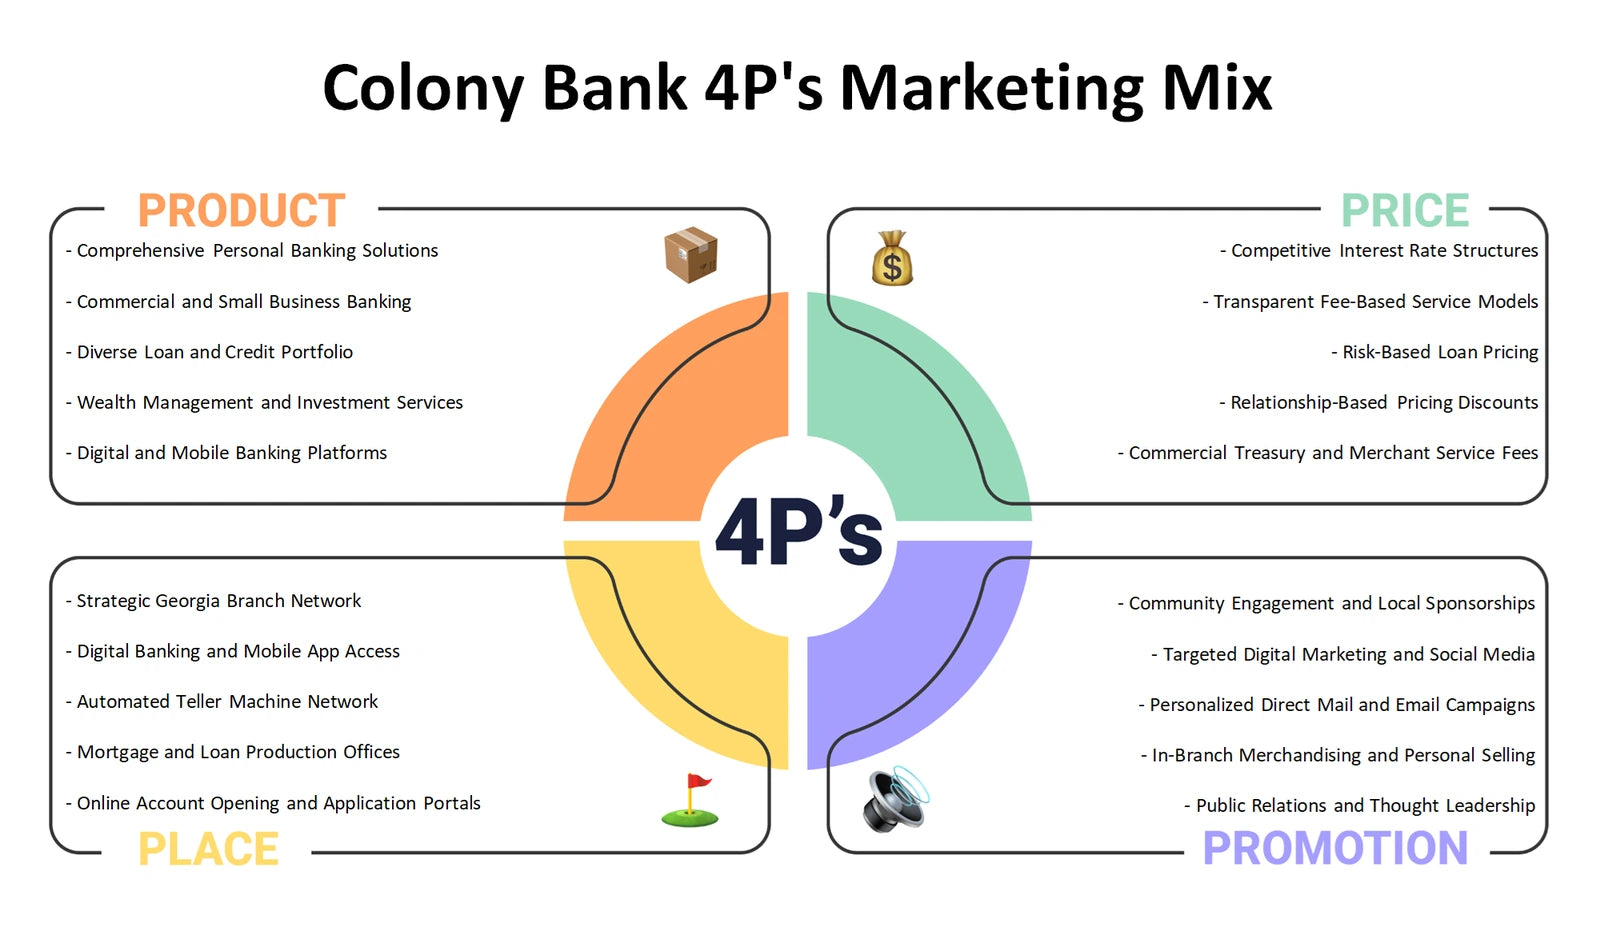
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should be monitored when Colony Bank combines small-business lending with digital banking delivery?
A Colony Bank PESTLE analysis, also known as PESTEL, separates Political, Economic, Social, Technological, Legal and Environmental influences. Political and legal questions can include the policy setting and compliance requirements surrounding SBA-related lending. Economic conditions may affect borrower demand, credit quality and funding economics, while social expectations can shape demand for accessible, responsive service. Technology raises issues of integration, data quality, cybersecurity and third-party oversight. Environmental factors can be considered through operational continuity and the exposure of borrowers or collateral to physical disruption. These are lenses for investigation, not claims that a particular law, rate or external event has occurred.
- External scan. Keep policy, economy, customer behaviour, technology, legal duties and environmental exposure distinct but connected.
- Change signals. Identify which outside developments could require a response in lending processes or digital-service governance.
- Monitoring map. Use Excel to sort signals by PESTLE category and the Word analysis to add context, relevance and follow-up questions.
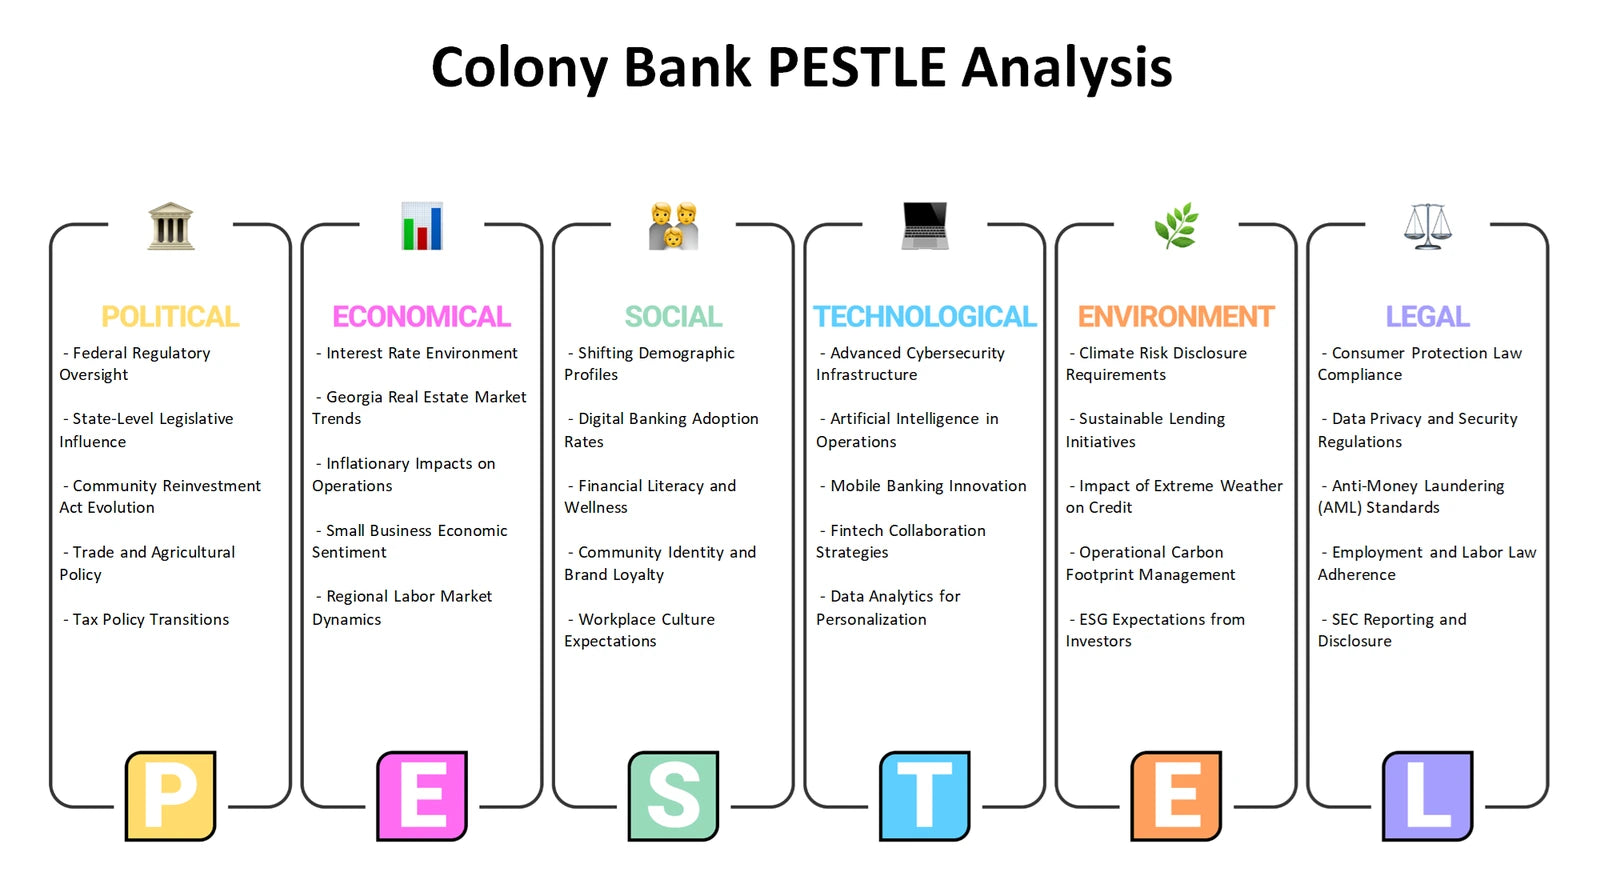
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal capabilities and constraints should Colony Bank weigh against external opportunities and threats?
A Colony Bank SWOT analysis keeps internal strengths and weaknesses separate from external opportunities and threats. The supplied business context identifies SBA Preferred Lender activity and a fintech infrastructure relationship as relevant capability themes to examine; their strategic value should still be tested rather than assumed. Internal questions may cover lending expertise, customer relationships, data integration and operating capacity. Potential weaknesses, such as implementation complexity or dependence on external providers, remain hypotheses until supported by evidence. Opportunities can arise from unmet small-business finance needs or improved digital delivery, while threats may include competitive pressure, credit conditions, compliance demands and cyber risk.
- Correct classification. Separate what the organisation can influence directly from market conditions that it must monitor and respond to.
- Evidence discipline. Treat plausible capability gaps and opportunity themes as items to validate, not as established company findings.
- Decision narrative. Use the Excel SWOT layout to prioritise issues and the Word analysis to connect internal choices with external scenarios.
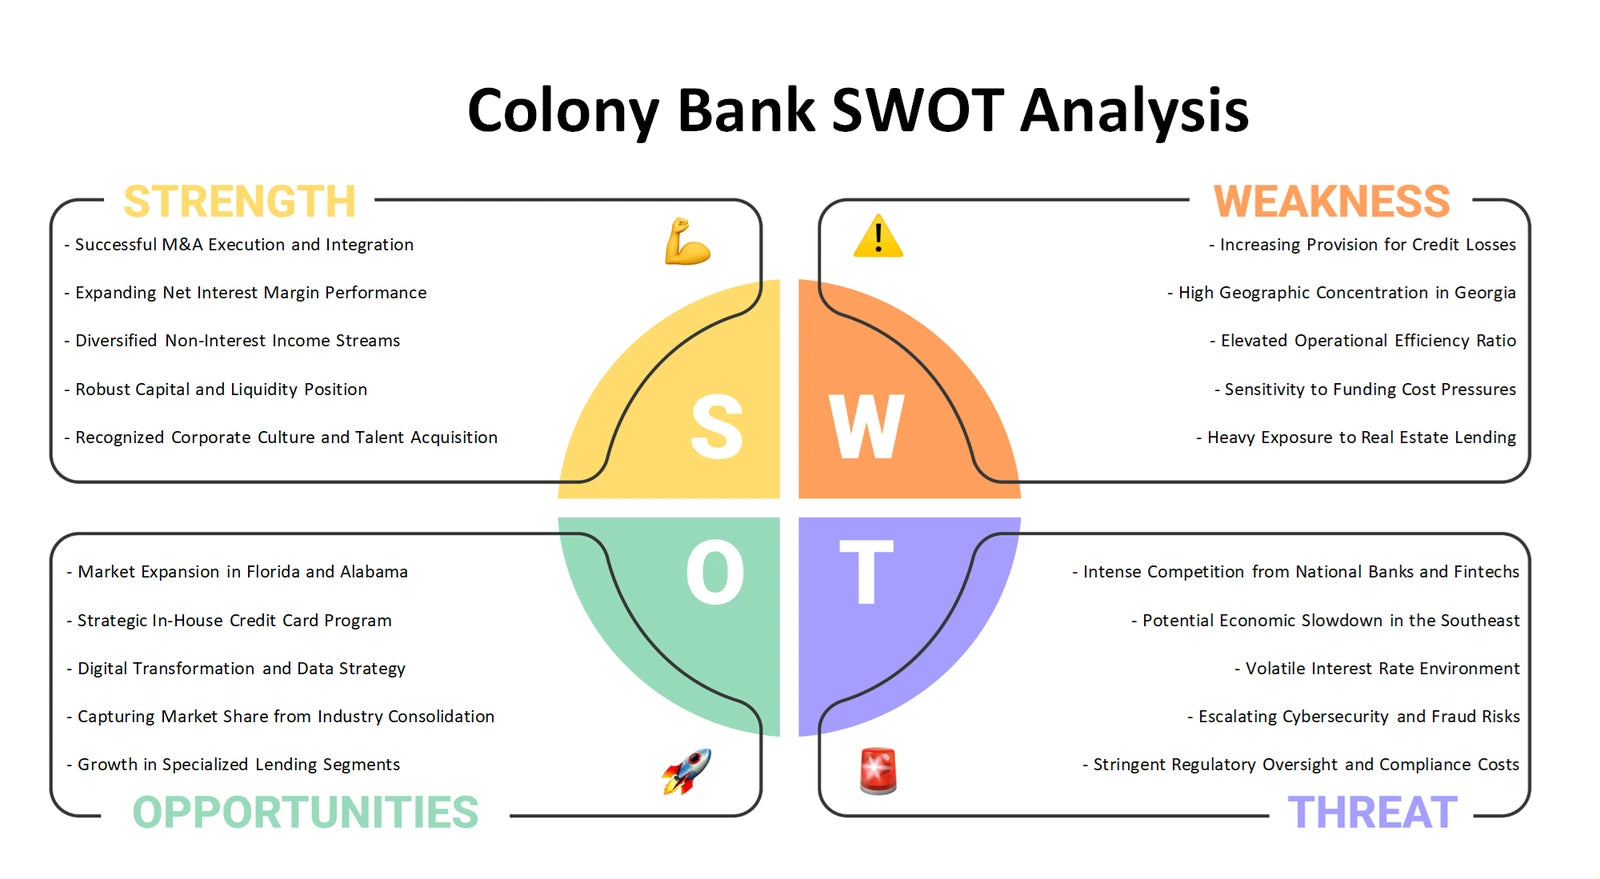
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of Colony Bank's strategic choices
Used together, the six perspectives move from portfolio priorities and business-model connections to market forces, customer delivery, external change and internal-versus-external positioning. The Excel frameworks provide a structured way to organise comparisons and questions, while the detailed Word analyses support a fuller interpretation of Colony Bank's small-business lending and digital-banking context.
Company background: Colony Bank — PESTEL Analysis business-model context.