

Xiamen Bank: Banking Business and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Xiamen Bank Strategy Analysis Bundle
Xiamen Bank is identified as a banking company associated with Xiamen, also known historically as Amoy, in the People's Republic of China. Available business context describes a bank whose core commercial questions include attracting stable deposits, extending consumer, SME and corporate credit, managing loan risk and deepening customer relationships through relevant financial services.
For a bank, growth cannot be separated from funding quality, credit discipline, regulation and customer trust. This bundle helps examine how Xiamen Bank could prioritise lending and deposit propositions, connect its operating model to customer value, and test external pressures affecting a regional banking business. The analyses frame decisions and comparisons; they do not claim unverified market positions, financial results or investment recommendations.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking propositions merit further resources when both relative market share and market growth must be weighed against funding and credit risk?
The Xiamen Bank BCG Matrix provides a disciplined way to compare potential activity areas such as deposit propositions, consumer lending, SME credit and corporate banking services. The framework uses relative market share and market growth as analytical criteria, then considers whether an activity may resemble a Star, Cash Cow, Question Mark or Dog. For a bank, that discussion should not be reduced to volume alone: a growing loan category can consume capital and increase risk, while a stable deposit relationship can support funding resilience. The matrix therefore helps organise portfolio-priority conversations without assigning unverified quadrant positions.
- Growth versus position. Compare the attractiveness of customer or product markets with Xiamen Bank's relative competitive standing in each defined segment.
- Resource discipline. Consider how lending capacity, deposit acquisition effort, risk oversight and relationship coverage might be allocated across different propositions.
- Portfolio working view. Use the Excel framework to map comparable activities, then use the Word analysis to document assumptions, evidence needs and implications for priorities.
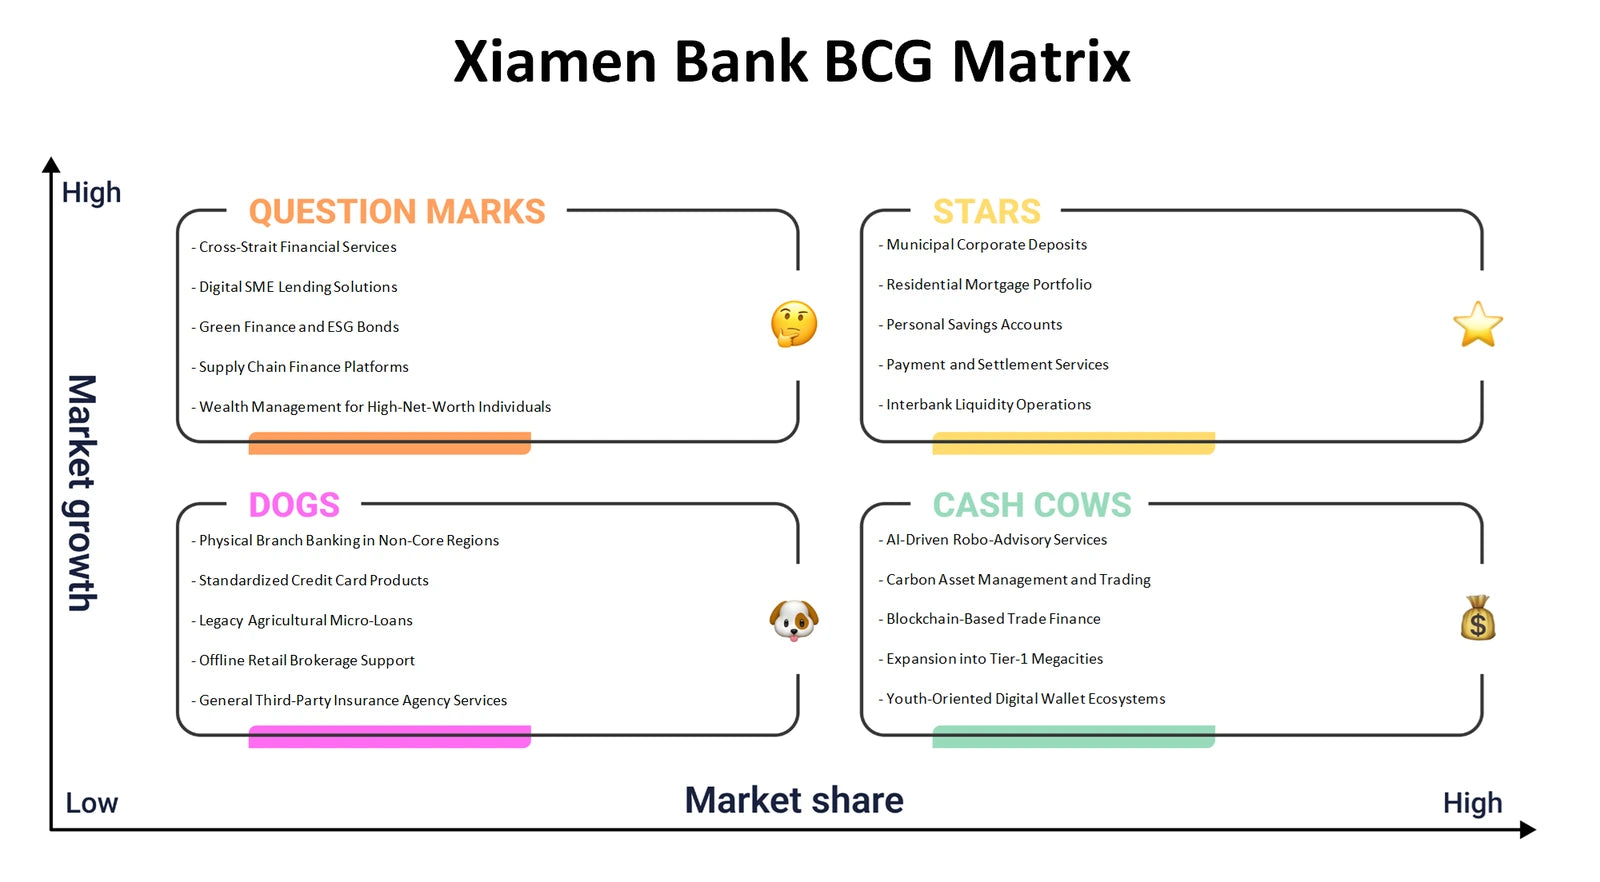
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do deposits, responsible lending and customer relationships fit together to create value and sustainable banking economics?
The Xiamen Bank Business Model Canvas connects all nine building blocks in one operating-model view: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. It can help examine the different needs of consumers, small and medium-sized enterprises and corporate borrowers alongside the value of accessible financing, secure savings and ongoing service. Deposit funding, underwriting, portfolio monitoring and compliance are particularly important links because they influence both revenue logic and the cost or risk of serving customers. Regulatory and regional-development relationships can also be considered as possible partnership topics rather than assumed commercial advantages.
- Value-to-economics link. Trace how customer needs and service propositions relate to lending income, funding costs, operating effort and risk controls.
- Operating dependencies. Examine the resources, activities and partnerships needed to acquire deposits, assess credit and maintain trusted relationships.
- Connected model map. Populate the Excel canvas as a shared structure and use the Word analysis to explain the trade-offs between value delivery, costs and revenue streams.
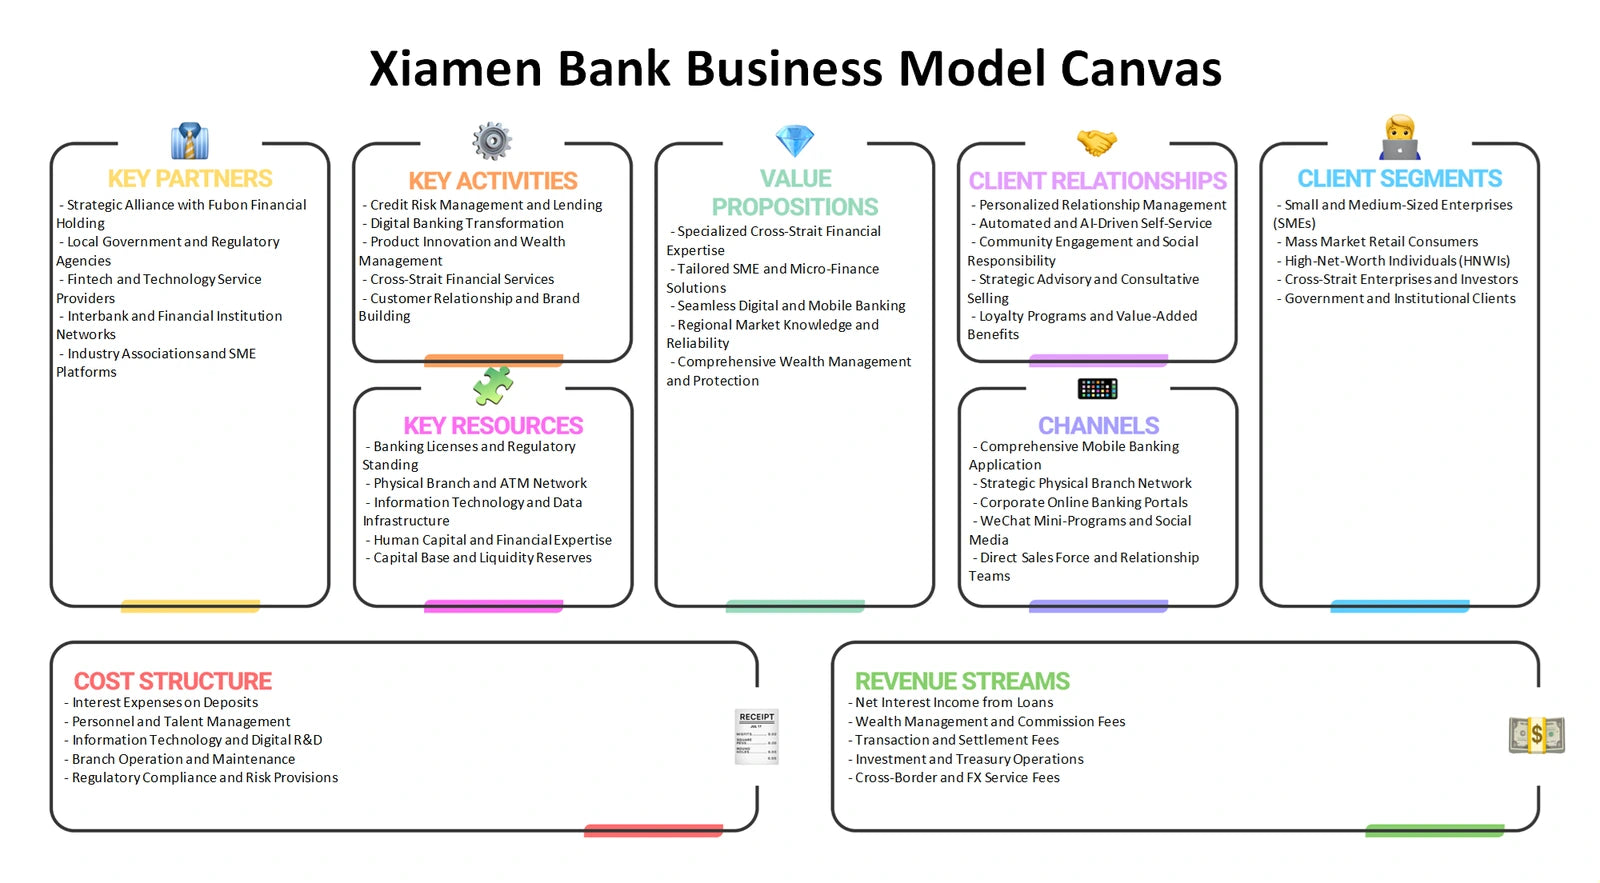
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could affect the attractiveness of serving depositors, borrowers and business customers in Xiamen Bank's banking markets?
Xiamen Bank Porter's Five Forces analysis examines the structure around a regulated banking business rather than producing a simple competitor list. Rivalry can influence pricing, service quality and customer acquisition costs. Buyer power considers the ability of depositors and borrowers to compare alternatives or switch providers. Supplier power is relevant to funding sources, capital providers, technology suppliers and specialist service partners. The threat of new entrants is shaped by licensing, trust and scale requirements, while substitutes include payment platforms, non-bank financing, capital-market funding and other ways customers can save, pay or obtain credit. These forces help test the durability of a banking proposition.
- Competitive pressure. Assess how competition for deposits and creditworthy borrowers may affect margins, relationship depth and service expectations.
- Alternative solutions. Distinguish direct banking competition from substitutes that meet payment, savings or financing needs through different models.
- Evidence-led comparison. Use the Excel force-by-force structure to record observations and use the Word analysis to add context, limitations and strategic questions.
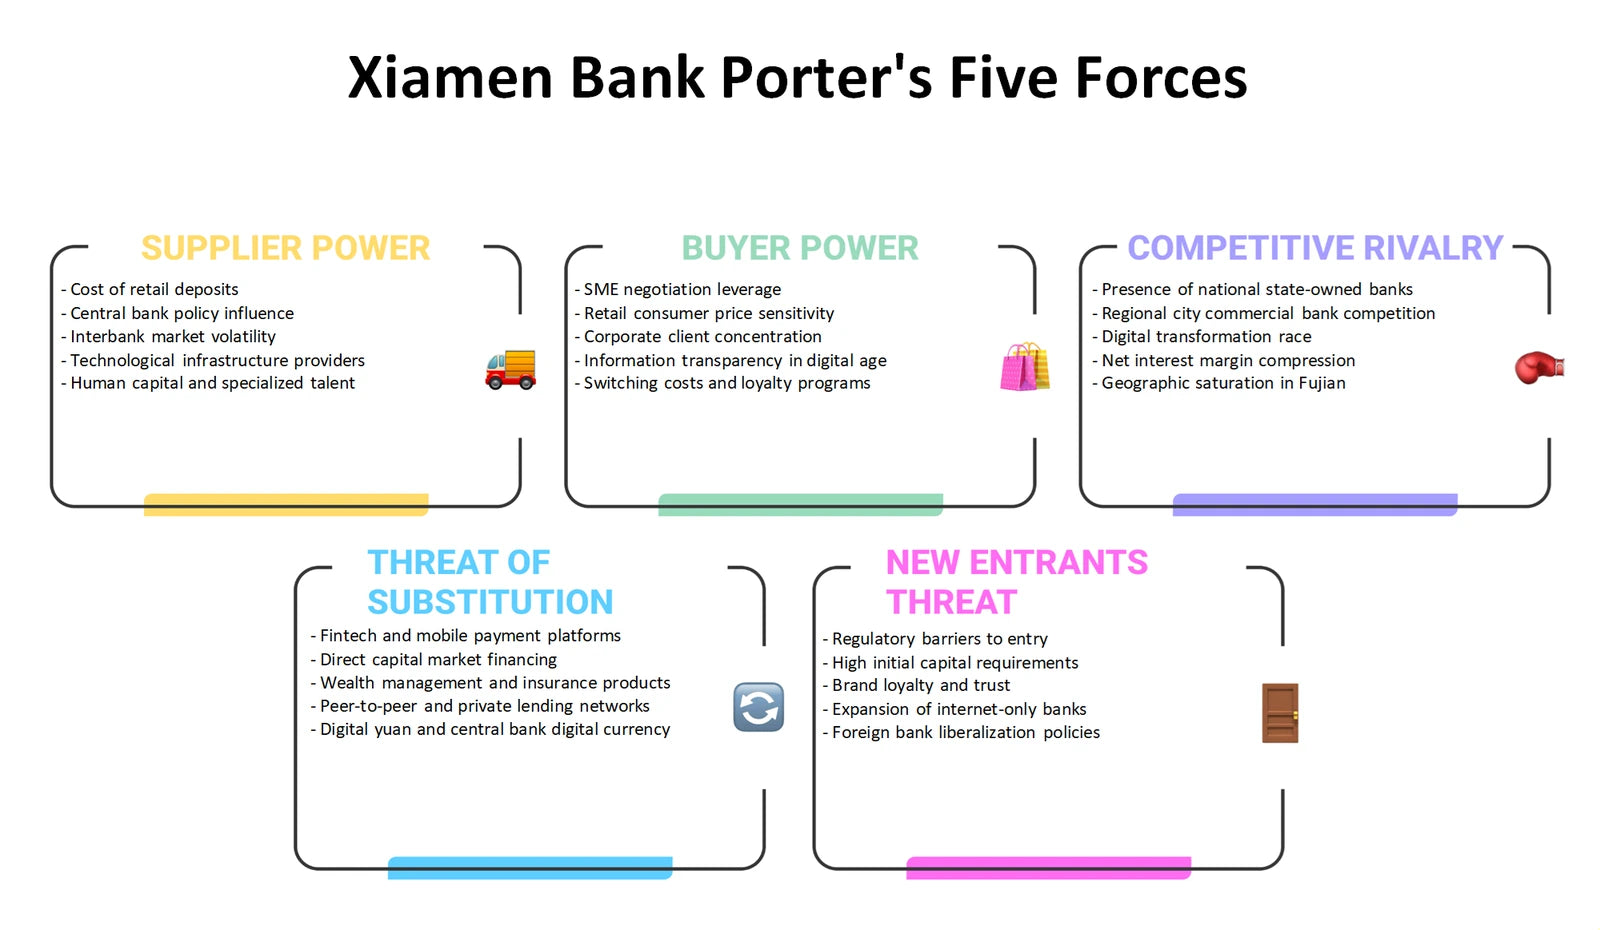
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a regulated bank align its product design, risk-adjusted pricing, customer access and communications with distinct banking needs?
The Xiamen Bank Marketing Mix applies Product, Price, Place and Promotion to financial services, where trust and suitability matter as much as acquisition. Product analysis can compare deposit accounts, lending arrangements and relationship-led services against the needs of households, SMEs and larger organisations. Price considers interest rates, fees and risk-adjusted lending terms without assuming any actual price level. Place examines the appropriate blend of relationship, assisted and digital customer access, while Promotion considers clear communication of service value, eligibility and responsible use. Together, the 4Ps help prevent a product decision from being made without considering customer reach, risk and communication requirements.
- Offer architecture. Review how savings, credit and supporting services could be grouped around the needs of defined customer segments.
- Trustworthy commercial choices. Test the fit between risk-sensitive pricing, access routes and communications that customers can understand.
- Go-to-market worksheet. Organise 4P options in Excel, then use the Word analysis to capture rationale, customer considerations and questions for review.
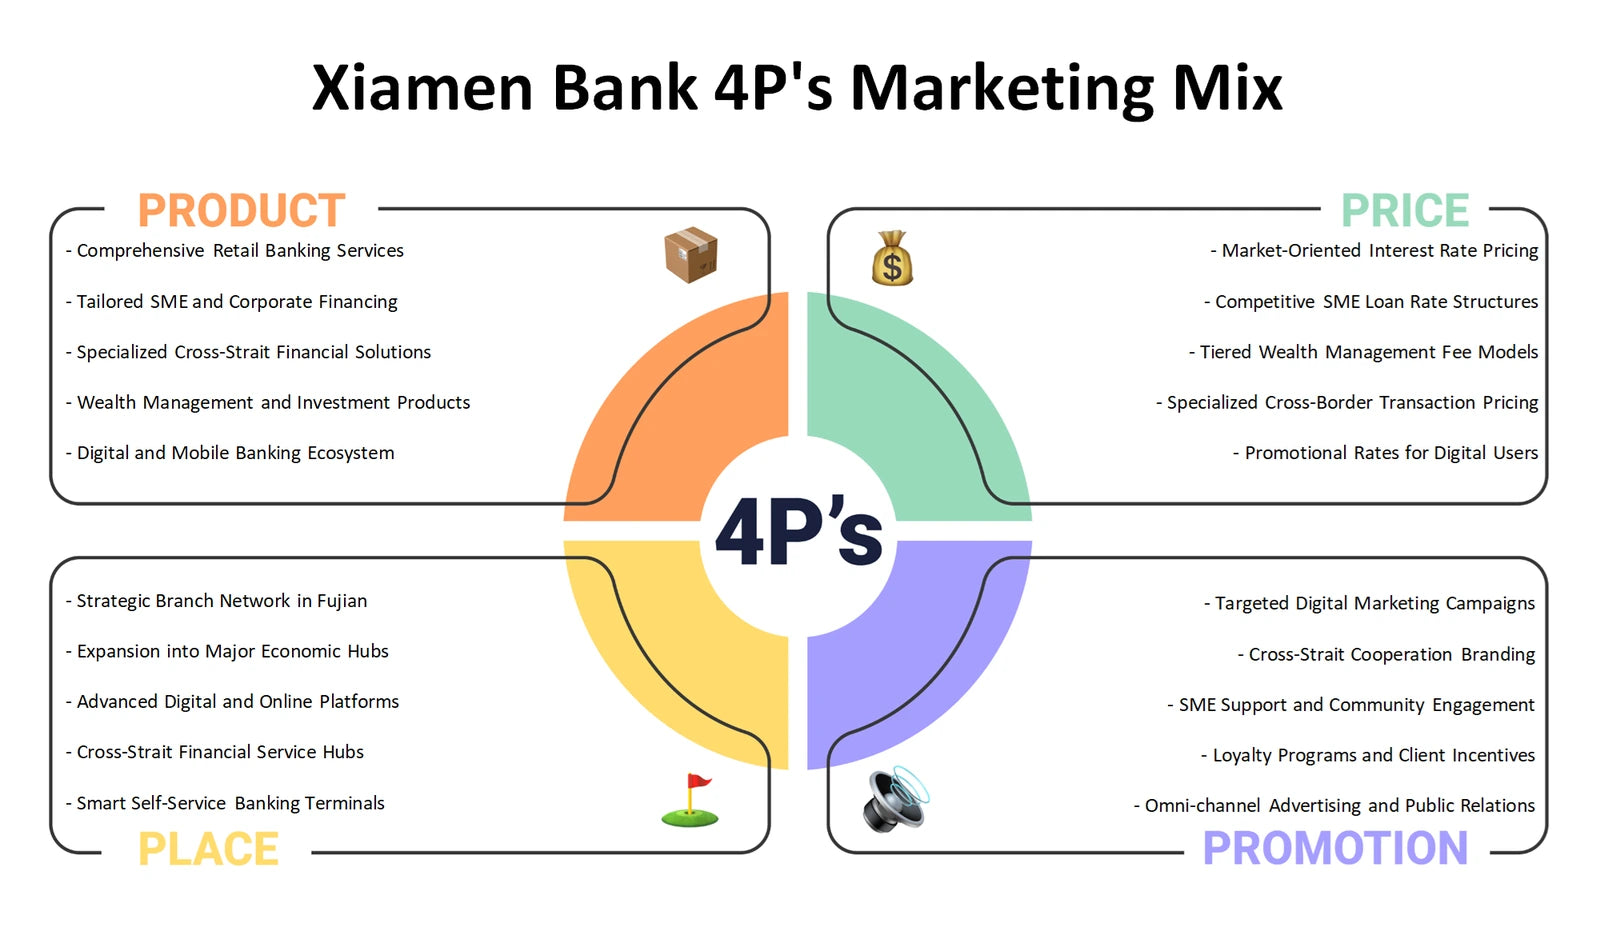
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should be monitored when planning a banking strategy connected to Xiamen and the wider Chinese financial sector?
The Xiamen Bank PESTLE analysis, also commonly called PESTEL, separates external influences from internal capability. Political factors can include public-policy priorities and the role of financial-sector oversight. Economic questions include credit demand, funding conditions, business activity and borrower resilience. Social analysis considers trust, financial needs and changing customer expectations. Technological forces cover secure digital service, data protection and payment innovation. Legal factors address licensing, consumer protection, prudential expectations and compliance obligations, while environmental factors can examine climate-related credit exposure and sustainability expectations. The framework does not assert that a particular policy, rate or law has changed; it creates a disciplined monitoring agenda.
- External signal map. Separate macroeconomic and policy questions from customer, technology and environmental developments that may affect banking decisions.
- Risk transmission. Consider how an outside change could influence deposits, loan demand, borrower quality, operating controls or reputation.
- Monitoring structure. Use Excel to classify signals by PESTLE category and use the Word analysis to record why each issue may matter to the bank.
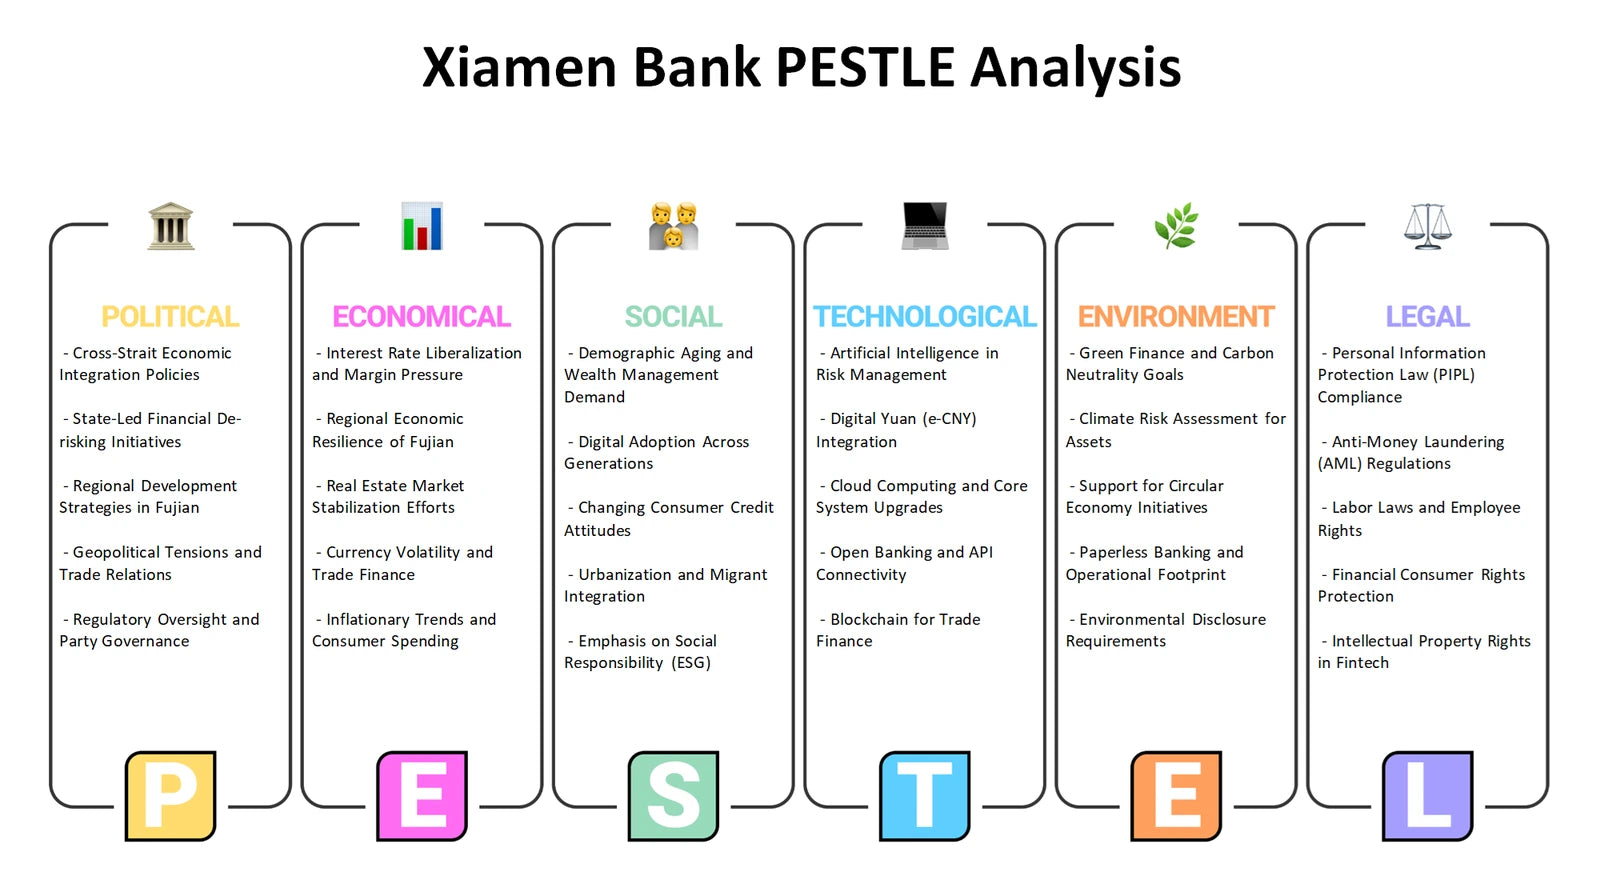
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Xiamen Bank distinguish what it can influence internally from external opportunities and threats in its operating environment?
The Xiamen Bank SWOT analysis provides a final synthesis by separating internal Strengths and Weaknesses from external Opportunities and Threats. Potential internal topics to investigate include deposit-gathering capability, credit underwriting processes, risk monitoring, customer knowledge, technology capacity and the cost of serving different segments. These are not presented as established findings. Opportunities may arise from changing customer needs or regional economic activity, while threats can include credit stress, competitive pressure, substitute financial services, operational risk and changing regulation. Keeping the categories distinct is valuable: an internal process gap is a weakness, for example, whereas an outside market shift is a threat or opportunity.
- Capability reality check. Identify the evidence needed to assess whether operational, relationship and risk-management capabilities are genuine strengths or constraints.
- External fit. Match plausible opportunities and threats to the internal capabilities required to respond without confusing conditions with company attributes.
- Priority synthesis. Use the Excel grid to organise themes and the Word analysis to develop balanced implications, dependencies and follow-up questions.
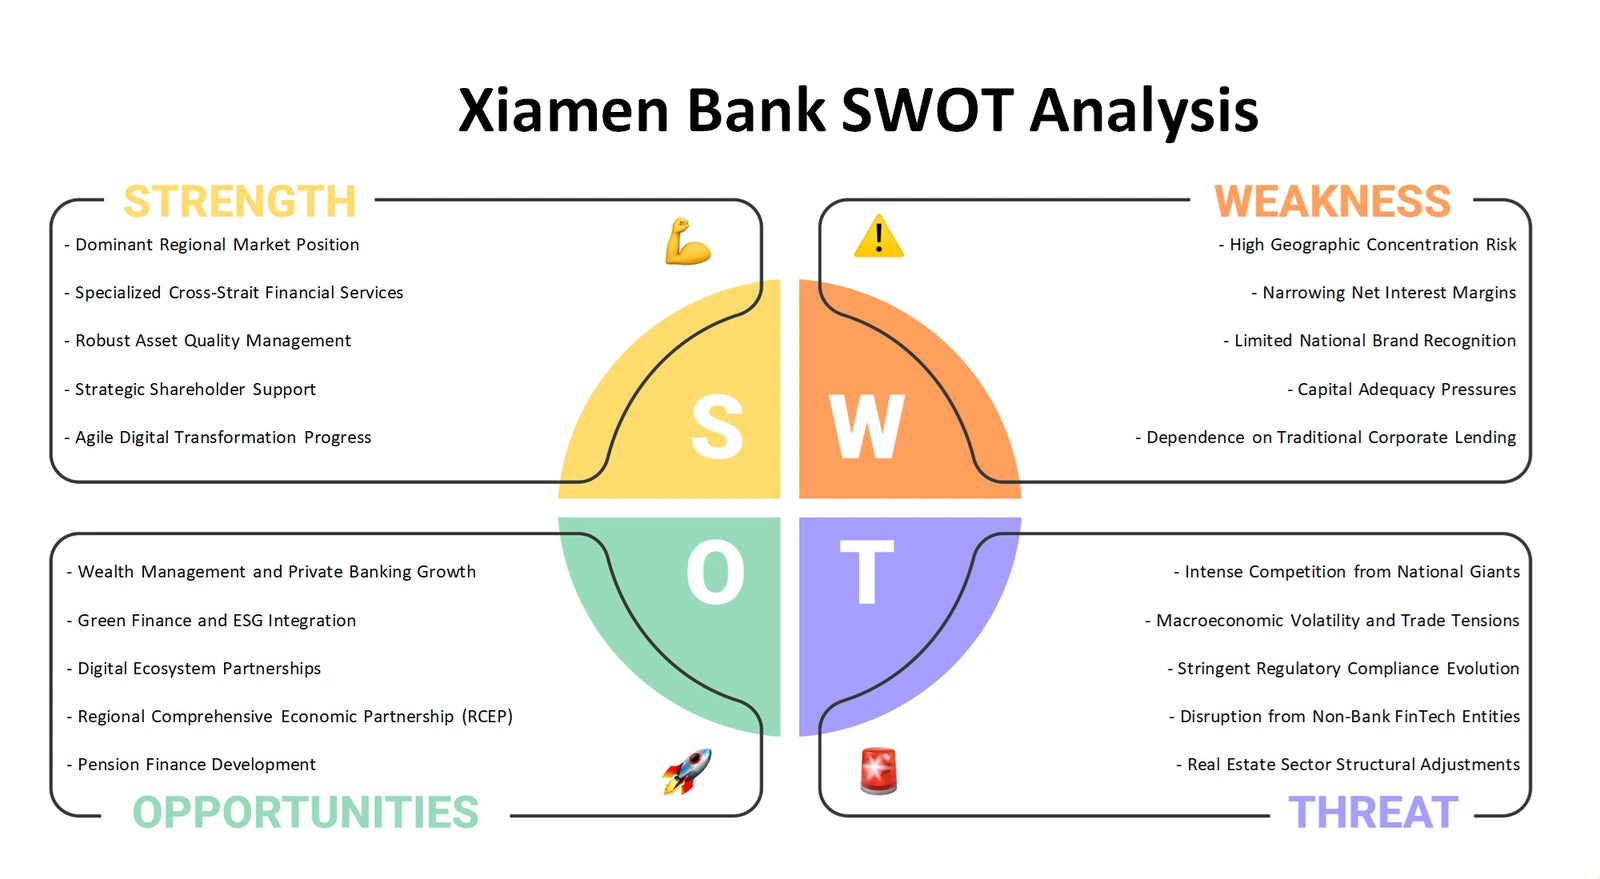
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a more connected view of Xiamen Bank
Used together, the six perspectives link portfolio priorities, banking economics, industry structure, customer-facing choices, external conditions and organisational capability. The Excel frameworks provide a structured way to compare issues and capture inputs, while the detailed Word analyses help explain the reasoning behind each lens. Customers can use the materials to develop a more organised discussion of deposits, lending, customer value, risk and strategic trade-offs relevant to Xiamen Bank.
Company background: Xiamen Bank — Wikidata company profile.