

Weihai City Commercial Bank: Banking Business and Lending Economics – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Weihai City Commercial Bank Strategy Analysis Bundle
The available product context for Weihai City Commercial Bank describes a deposit-taking banking business serving individual customers, small and medium-sized enterprises and larger corporate clients in its operating region around Weihai. Deposits provide funding for lending and investment activity, while relationships with local businesses and financing partners can broaden the bank's ability to serve corporate needs.
This bundle does not treat that background as current financial evidence or assign unverified results to the bank. Instead, it turns the documented operating model into practical strategic questions: where resources may matter most, how customer value and funding economics connect, and how banking competition, regulation and external change should be assessed.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which customer propositions and banking activities deserve resources when local demand growth and relative market share may differ?
The Weihai City Commercial Bank BCG Matrix provides a disciplined way to compare a portfolio rather than assuming every deposit, lending or corporate-financing activity has the same strategic role. It uses market growth and relative market share to test possible Stars, Cash Cows, Question Marks and Dogs. For a relationship-led bank, the useful discussion is not a pre-set quadrant placement: it is whether particular customer groups, credit propositions or service capabilities justify investment, cash generation, selective testing or tighter resource control. This perspective helps connect portfolio choices with funding capacity, risk attention and the practical limits of serving retail, SME and larger corporate customers simultaneously.
- Portfolio boundaries. Compare meaningful banking activities or customer propositions rather than treating the whole institution as one undifferentiated unit.
- Share versus growth. Separate a locally strong offering with modest growth from an expanding opportunity where the bank's relative position may still be limited.
- Working view. Use the Excel matrix to organize evidence and assumptions, then use the detailed Word analysis to record why each possible priority warrants review.
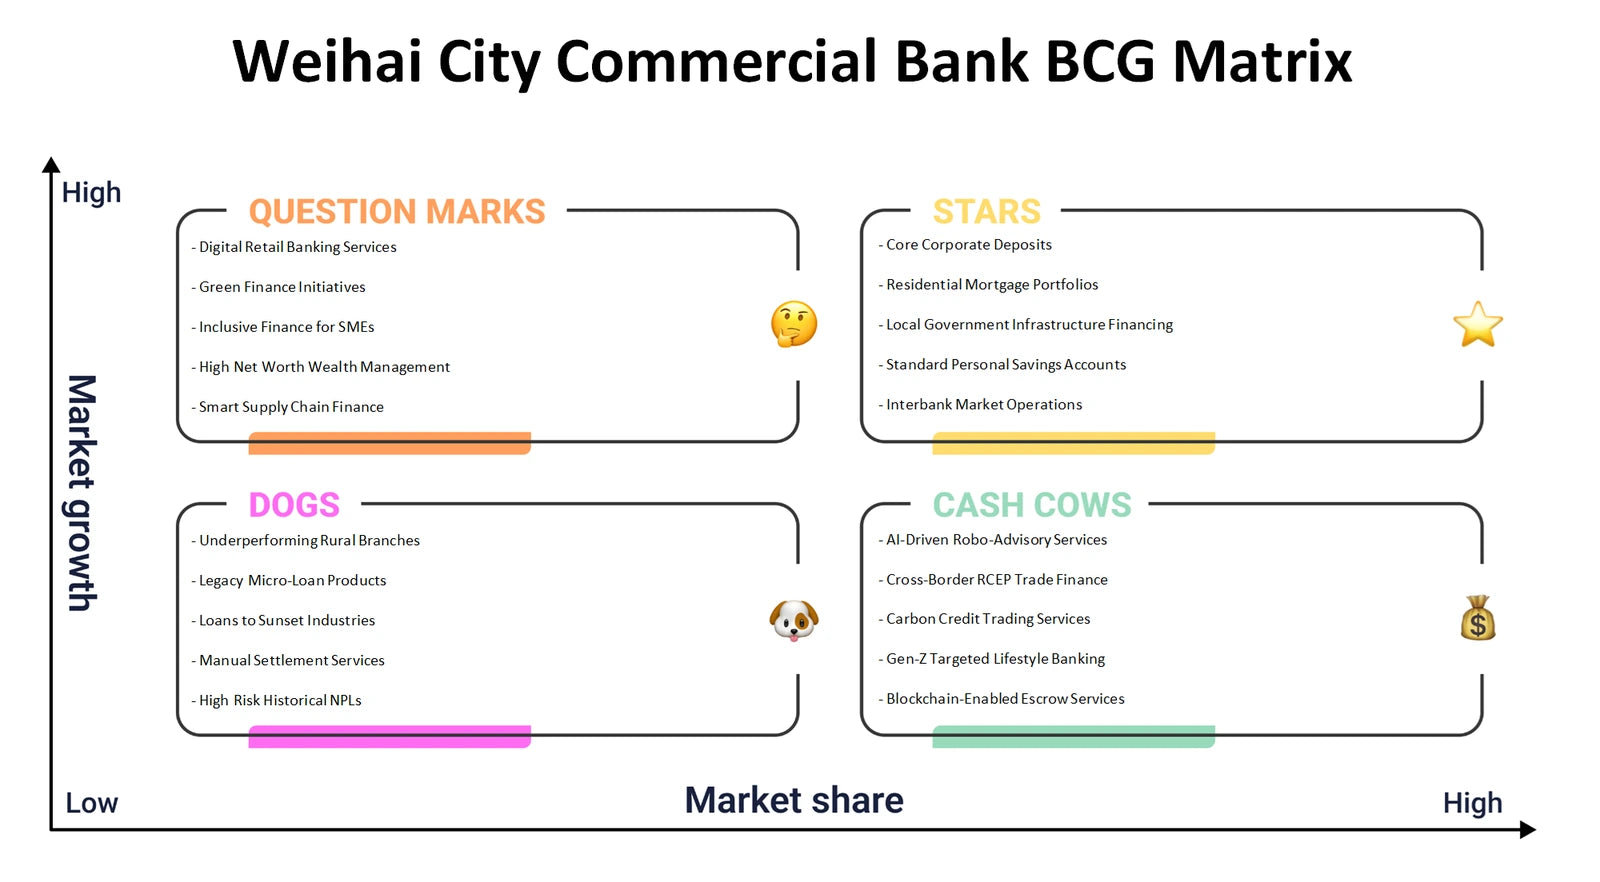
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do deposits, customer relationships and financing capabilities combine to create value and sustain bank economics?
The Weihai City Commercial Bank Business Model Canvas maps the connected logic behind a regional banking model. It considers customer segments, value propositions, channels and customer relationships alongside revenue streams, key resources, key activities, key partnerships and cost structure. The supplied context makes deposit gathering, lending and investment deployment especially relevant starting points, while local SME and corporate relationships may help explain customer access and product fit. Partnerships can also be assessed in relation to larger financing transactions, including the capacity that collaborative arrangements may provide. The value of the Canvas is seeing dependencies: a proposition for a business borrower requires funding, risk processes, relationship coverage, delivery routes and a cost base that can support it.
- Value chain. Trace how customer trust and deposits can support financing activity, while recognizing that each link carries operational and risk-management requirements.
- Partnership role. Examine how industry relationships or financing collaborations may extend reach without assuming that every partnership produces the same economics.
- Model mapping. Populate the Excel Canvas block by block, then use the Word analysis to connect the completed model to questions about trade-offs and dependencies.
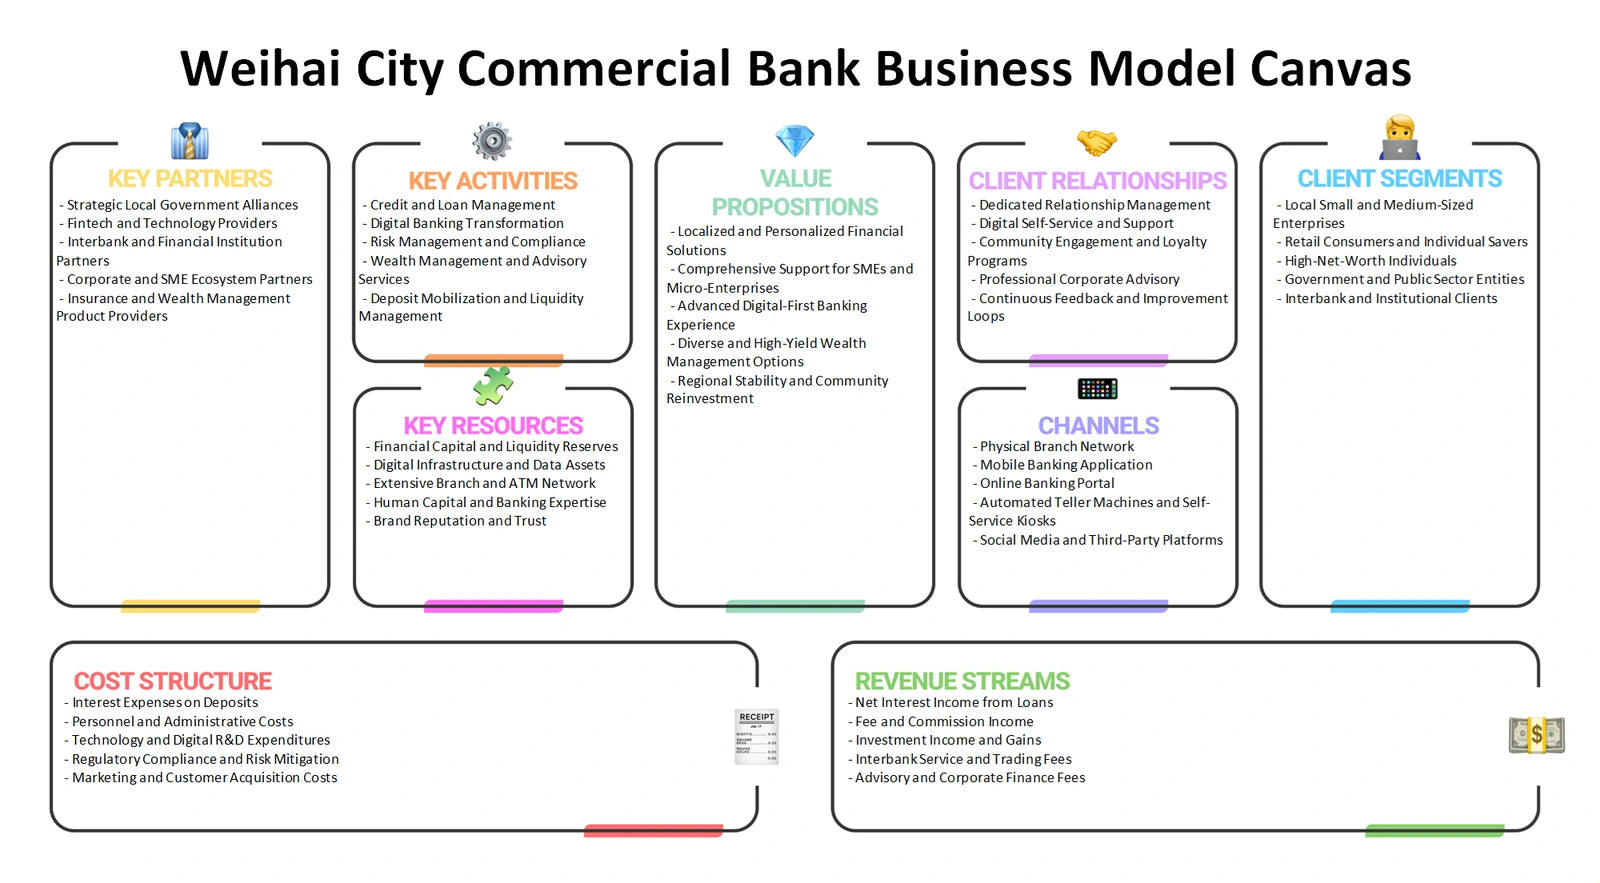
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can affect a relationship-based bank's ability to attract deposits and serve borrowers profitably?
Weihai City Commercial Bank Porter's Five Forces analysis focuses on the competitive setting around deposit-taking and financing services. Rivalry can shape customer acquisition and pricing discipline; buyer power comes from depositors and borrowers able to compare alternatives. Supplier power can be considered through the availability and cost of funding, as well as dependence on important service providers. New entrants face banking, trust and regulatory barriers, yet digital or specialist providers may alter parts of the customer journey. Substitutes are wider than direct banks: households may choose other saving vehicles, while businesses may seek alternative ways to finance working capital or larger projects. The framework helps distinguish these pressures instead of reducing competition to a list of named rivals.
- Funding competition. Assess how competition for stable deposits can affect the economic room available for lending and relationship service.
- Customer alternatives. Compare the switching options available to individuals, SMEs and corporate clients, including non-bank ways to save or obtain finance.
- Pressure test. Use the Excel framework to rate evidence and open questions by force, while the Word analysis supports a fuller explanation of the implications.
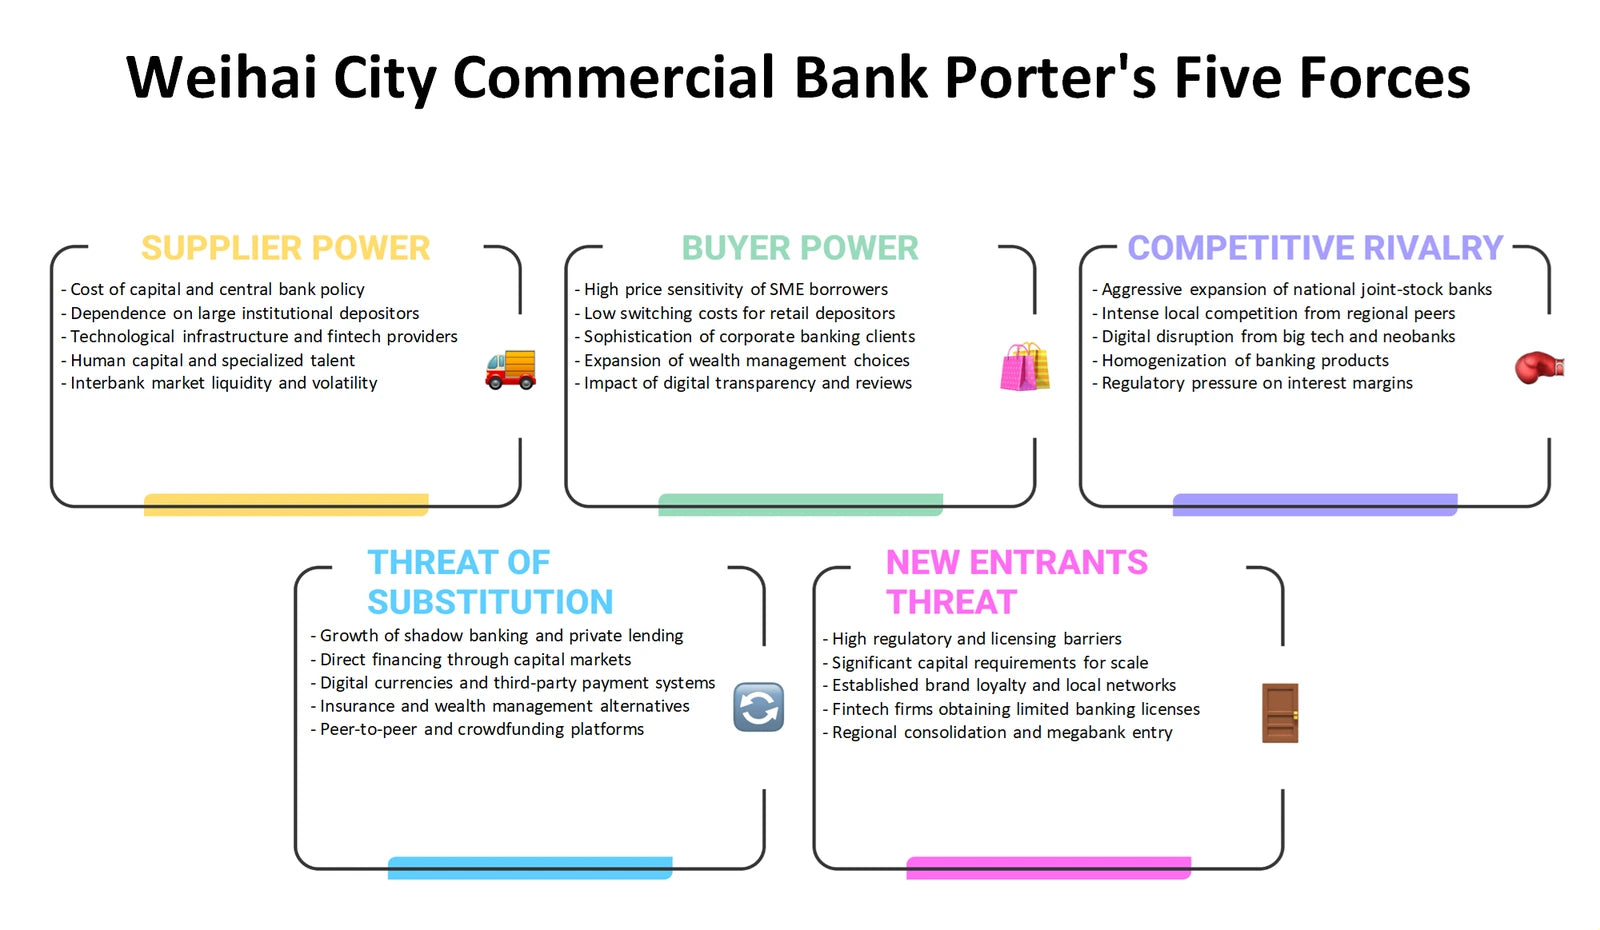
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a bank align its service offer, pricing logic, access routes and communications with the needs of individuals and businesses?
The Weihai City Commercial Bank Marketing Mix examines Product, Price, Place and Promotion in a regulated financial-services context. Product can cover the fit between deposit services, financing needs and the differing requirements of personal, SME and larger corporate customers. Price is not simply an advertised figure: deposit remuneration, lending terms, fees, risk assessment and regulatory expectations can all shape the value exchange. Place asks how customers access and receive service through appropriate relationship, branch or other delivery routes. Promotion considers clear, compliant communication that builds trust and explains an offer without overstating it. This 4Ps lens is useful because a locally relevant product can still underperform if access, pricing rationale or communication does not match the intended segment.
- Offer fit. Compare whether service propositions address the distinct cash-management and financing priorities of consumer and business customers.
- Trust signals. Review how clear terms, responsive relationship service and compliant communication may support confidence in financial decisions.
- Mix review. Use the Excel 4Ps structure to capture segment-by-segment considerations, then consult the Word analysis for the strategic links between the four decisions.
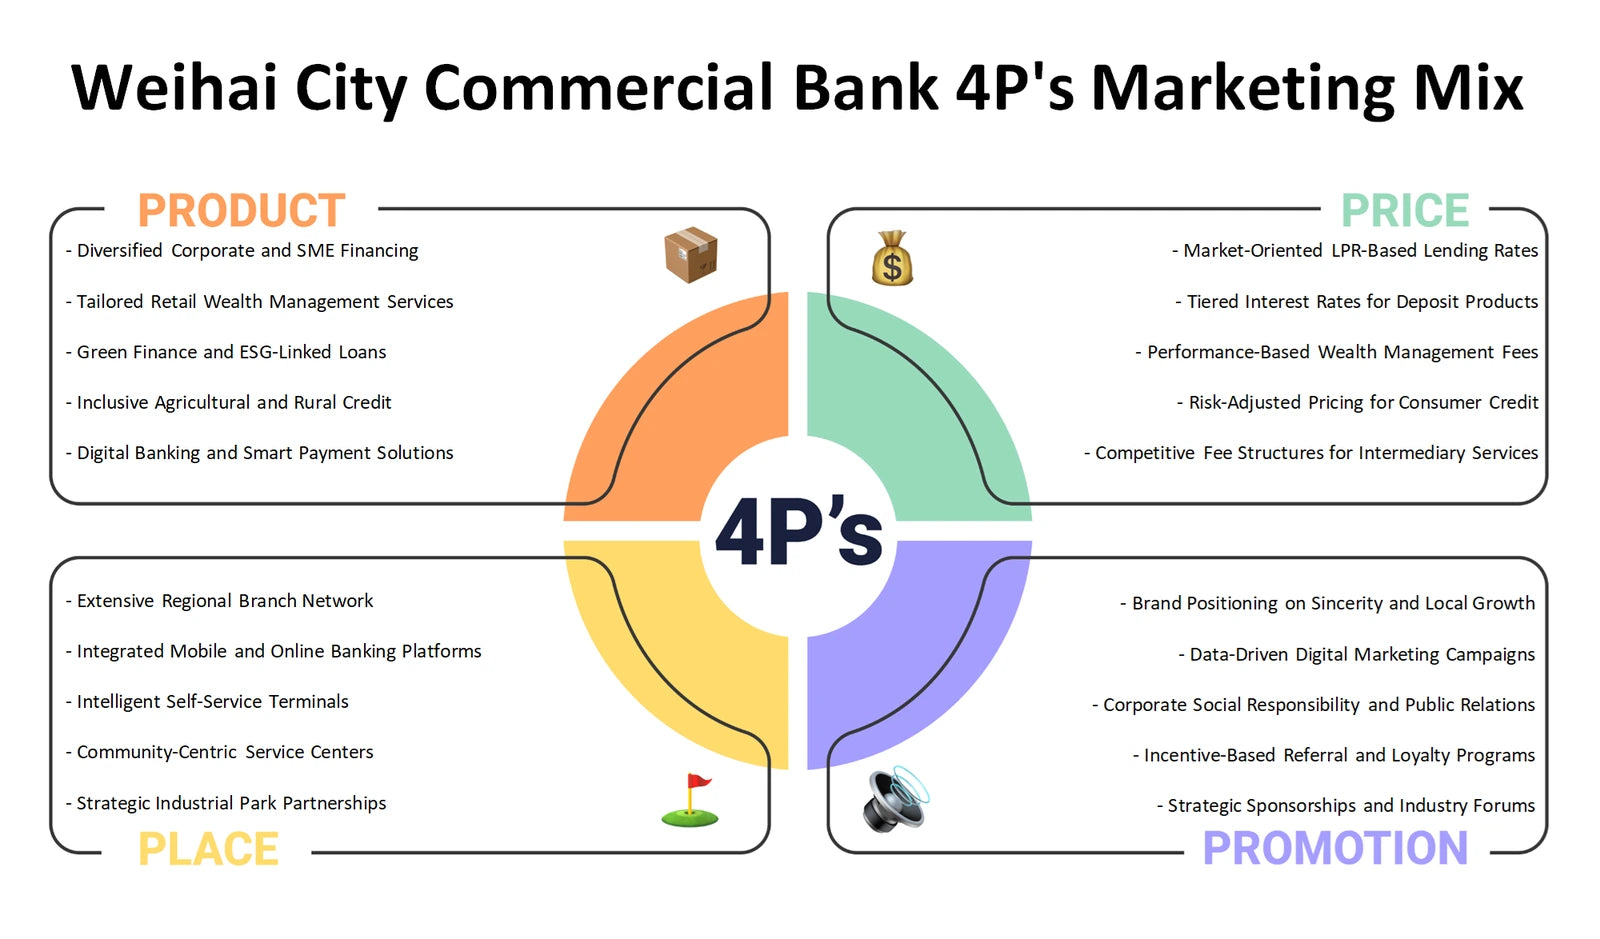
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could reshape the conditions under which a regional deposit-taking and lending business operates?
The Weihai City Commercial Bank PESTLE analysis, also commonly called PESTEL, organizes external conditions that management cannot control but must monitor. Political conditions can influence the policy environment for banking and local economic priorities. Economic factors include credit demand, funding conditions and changes in borrower affordability. Social trends may affect customer trust, savings behaviour and expectations for convenient service. Technological change raises questions about secure delivery, data protection and the competitive pace of financial innovation. Legal factors cover supervisory rules, consumer protection and lending requirements. Environmental considerations can affect operational continuity and the risks facing customers or financed activities. The framework treats these as analytical categories, not claims that a particular policy, rate or law has recently changed.
- External signals. Separate broad macroeconomic conditions from local customer impacts that may affect deposits, loan demand and credit quality.
- Compliance horizon. Identify regulatory, technology and resilience topics that warrant monitoring before they become operational constraints.
- Monitoring plan. Use the Excel PESTLE grid to log developments and relevance, then use the Word analysis to explore why selected factors may matter to the bank's model.
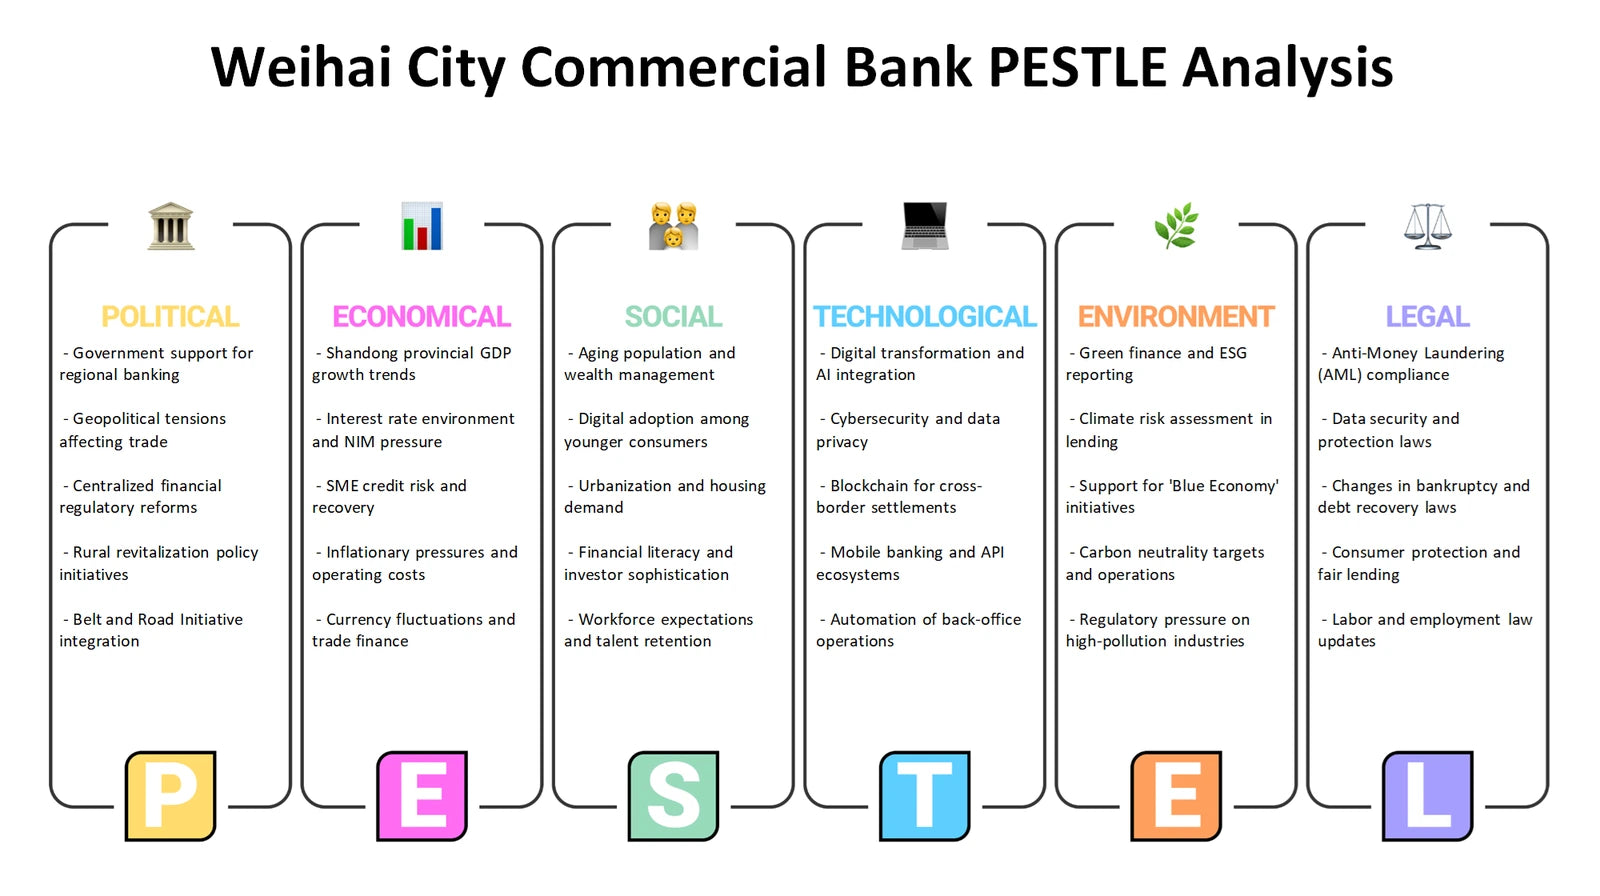
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal capabilities and limitations should be considered alongside the opportunities and threats facing this banking model?
The Weihai City Commercial Bank SWOT analysis keeps internal factors separate from external conditions. Strengths and weaknesses concern capabilities the bank may possess or need to improve, such as customer knowledge, funding relationships, processes, partnership management or service coverage. The supplied context's emphasis on local SMEs, corporate clients and industry relationships provides useful themes to test, but not pre-confirmed strengths. Opportunities and threats arise outside the organization, including changing customer needs, competitive alternatives, economic conditions, regulation and technology. This distinction matters because a local relationship capability is not itself an external opportunity, and a regulatory shift is not an internal weakness. SWOT brings the earlier frameworks together into a balanced discussion of strategic fit and priorities for further evidence.
- Internal evidence. Test capability themes against documented operations rather than automatically treating customer proximity or partnerships as proven advantages.
- External exposure. Relate opportunities and threats to the market, competitive and PESTLE questions already identified for deposit and financing services.
- Decision summary. Use the Excel SWOT layout to classify observations correctly, then use the detailed Word analysis to develop a reasoned narrative around the most relevant combinations.
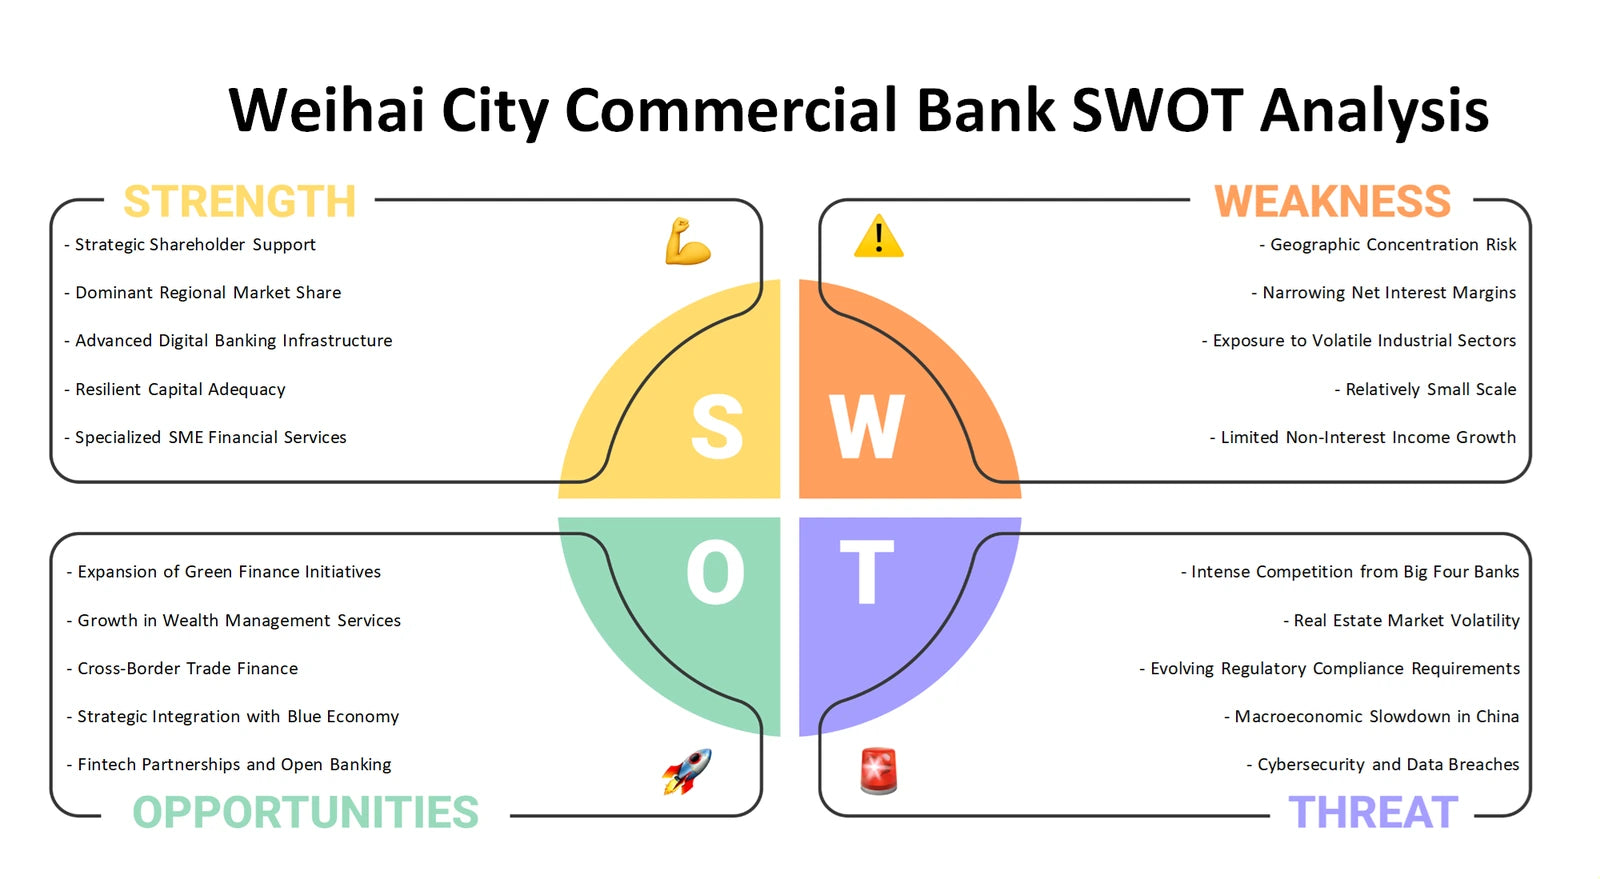
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Six lenses for a more connected banking strategy discussion
Together, the six perspectives move from portfolio priorities and business-model logic to competitive forces, customer-facing choices, external conditions and strategic fit. The Excel frameworks give users a structured way to organize comparisons and questions, while the Word files provide detailed company analysis to support a more informed discussion of Weihai City Commercial Bank's deposit, lending and relationship-based banking context.
Company background: Pestel-Analysis.com — Weihai City Commercial Bank Business Model Canvas product page.