

Western Alliance Bank: Banking Business and Merchant Services – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Western Alliance Bank Strategy Analysis Bundle
Western Alliance Bank is a U.S. commercial bank operating within Western Alliance Bancorporation, its publicly reporting parent. Its business-focused banking model combines lending, deposits and treasury-related services for commercial customers, including specialized businesses whose financing, cash-management and payment needs can require both sector knowledge and careful credit judgment.
The supplied business context highlights technology relationships supporting treasury management and data analytics, correspondent-bank connections for payments and loan syndication, and professional advisers supporting risk and regulatory work. Those facts raise practical questions about portfolio priorities, relationship economics, competitive pressure and external change. This bundle provides connected Excel frameworks and detailed Word analysis to help examine those questions without presenting assumptions as established outcomes.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking activities deserve greater resource commitment when growth potential and relative market share may differ by customer need or service line?
A Western Alliance Bank BCG Matrix helps separate the question of market attractiveness from the question of competitive position. Rather than treating the entire bank as one portfolio, it can examine potential areas such as specialized commercial lending, deposit gathering, treasury services, payment capabilities and relationship-led banking. The framework uses market growth and relative market share to test whether an activity might warrant Star, Cash Cow, Question Mark or Dog treatment. It does not assign a quadrant without defined markets and evidence; its value is in making those definitions, comparisons and resource assumptions explicit.
- Portfolio boundaries. Compare activities only after defining the relevant customer segment, geography and alternative providers, since a strong position in a niche is not the same as broad banking-market leadership.
- Funding versus growth. Consider how deposits, lending capacity, treasury relationships and operating attention may reinforce or constrain different growth opportunities.
- Decision map. Use the Excel matrix to organize growth and relative-share inputs, then use the Word analysis to document assumptions, evidence gaps and the reasoning behind priority discussions.
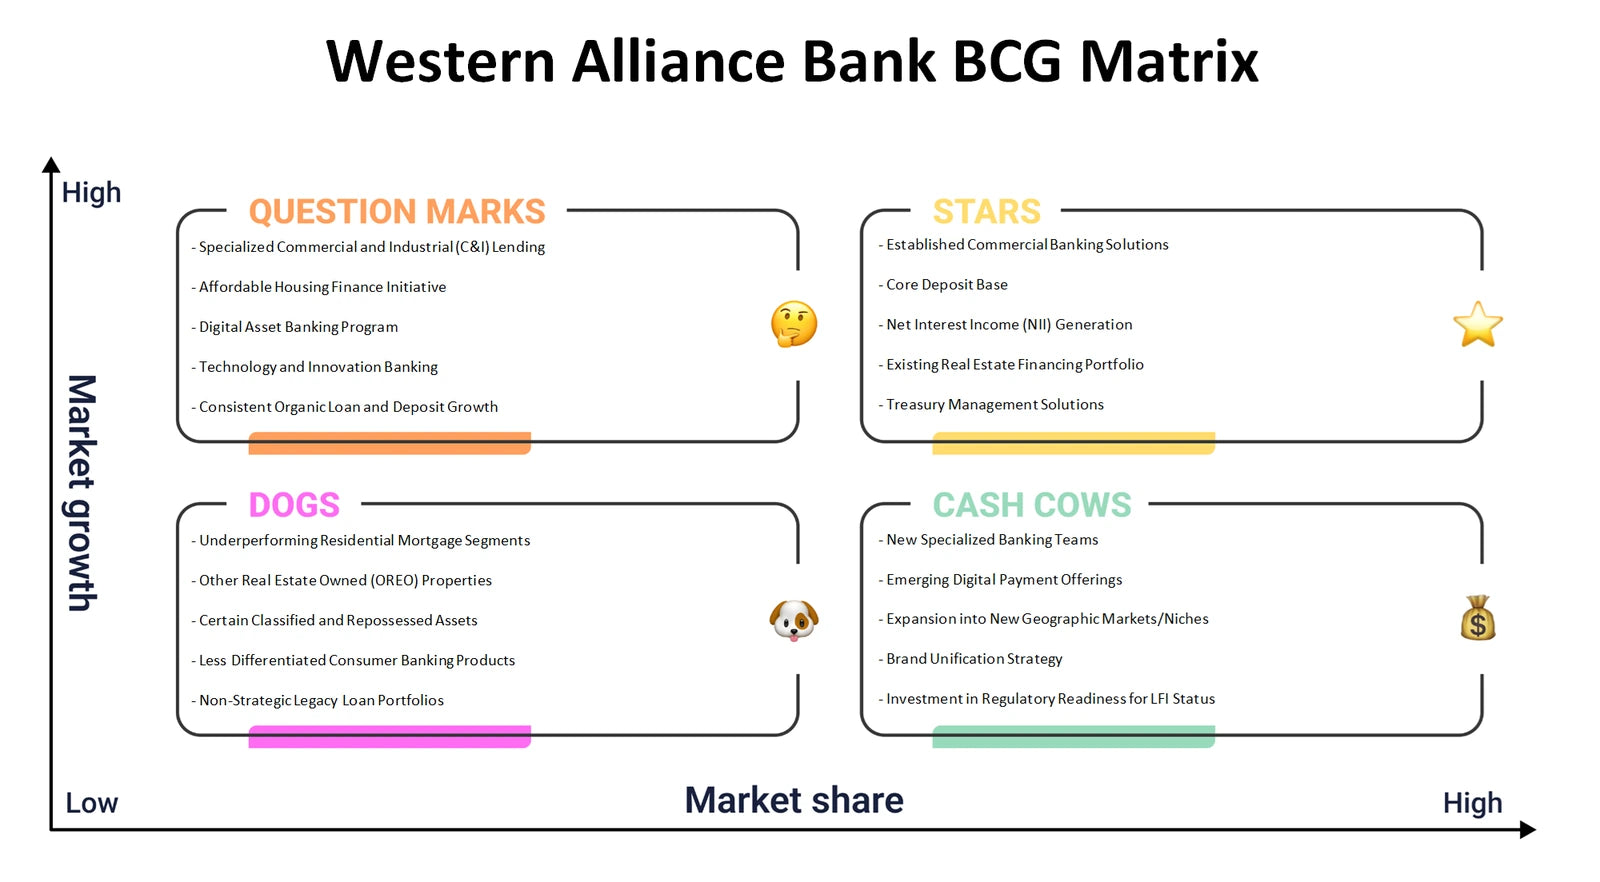
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do commercial customer relationships, banking capabilities and funding economics fit together to create value?
The Western Alliance Bank Business Model Canvas connects all nine building blocks in one operating logic: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For a commercial bank, the customer proposition may combine access to credit, deposits, treasury support and responsive sector understanding. Revenue can be examined through interest-related economics and service fees, while costs and risk requirements depend on funding, technology, compliance, people and credit operations. Technology providers, correspondent institutions and specialist advisers are particularly relevant partnership topics because they may support service delivery without replacing the bank's responsibility for controls and customer outcomes.
- Relationship architecture. Trace how commercial clients are served through bankers, treasury contacts, digital tools and payment networks, rather than viewing a loan or deposit account as an isolated product.
- Economic linkages. Test how customer value, balance-sheet usage, fee opportunities, risk controls and operating costs interact when a relationship expands.
- Connected evidence. Populate the Excel canvas with concise model components and use the Word analysis to explore the dependencies, trade-offs and questions behind each block.
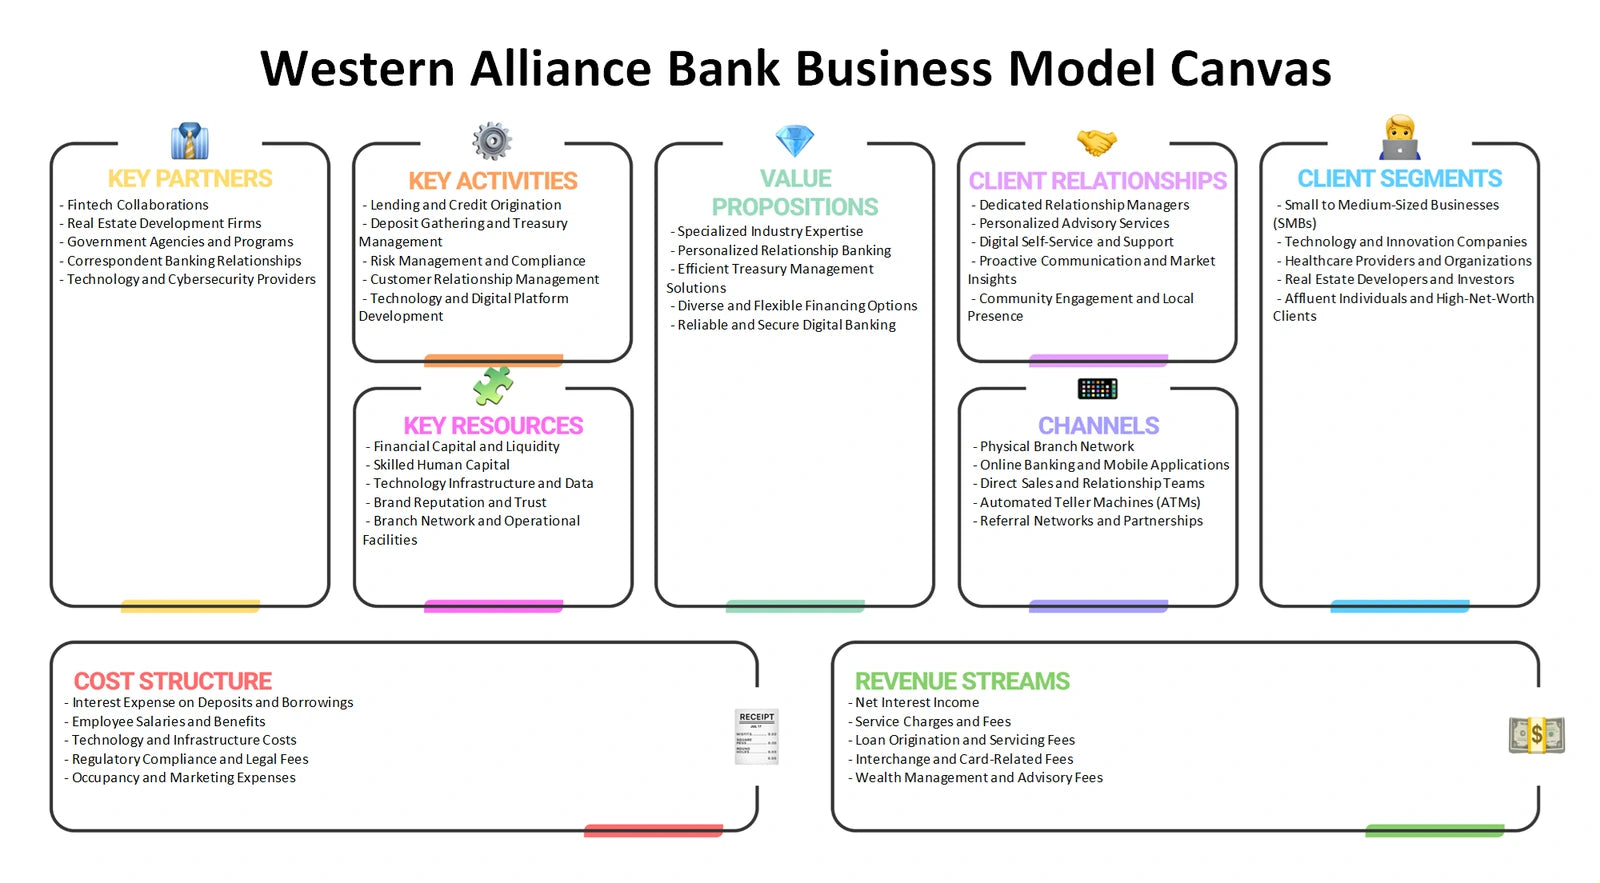
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can affect the bank's ability to win commercial relationships while protecting lending, deposit and service economics?
Western Alliance Bank Porter's Five Forces analysis examines the competitive environment around business banking rather than claiming a single force score. Rivalry can arise where banks compete for commercial loans, operating deposits and treasury mandates. Buyer power may increase when sophisticated clients can compare lenders, payment providers and cash-management options. Supplier power includes access to funding, technology, payment infrastructure and specialist external services. New entrants may emerge from digitally enabled financial providers, while substitutes include nonbank credit, capital-market financing, private funds and alternative payment arrangements. Each force matters differently depending on the client segment, product and relationship depth under review.
- Competitive choice. Evaluate whether the customer is choosing a relationship bank, a specialist lender, a transaction provider or a combination of providers for different needs.
- Margin pressure. Examine how funding conditions, service-provider dependence, procurement expectations and switching possibilities can influence pricing discipline and investment needs.
- Scenario comparison. Use the Excel framework to record force-specific evidence and use the Word analysis to interpret which pressures deserve monitoring in selected banking markets.
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a regulated commercial bank communicate and deliver a differentiated offer without reducing banking decisions to simple product promotion?
A Western Alliance Bank Marketing Mix analysis applies Product, Price, Place and Promotion to relationship-led financial services. Product can cover lending, deposits, treasury management, payment support and specialized expertise. Price is broader than a posted rate: it may involve interest margins, account charges, service scope, credit terms and the value of a broader relationship. Place includes relationship managers, digital banking tools, payment networks and other service routes used by commercial clients. Promotion must support informed decision-making and trust, particularly where service claims, risk disclosures and client suitability matter. The framework helps connect market communication to the operating experience customers actually receive.
- Offer design. Compare which combinations of lending, deposits and treasury services appear most relevant to distinct commercial customer situations.
- Route to client. Assess the balance between relationship coverage, digital access and partner-enabled payment or transaction capabilities.
- Message alignment. Use the Excel 4Ps structure to organize customer-facing choices, then use the Word analysis to assess whether positioning, delivery and pricing logic are mutually consistent.
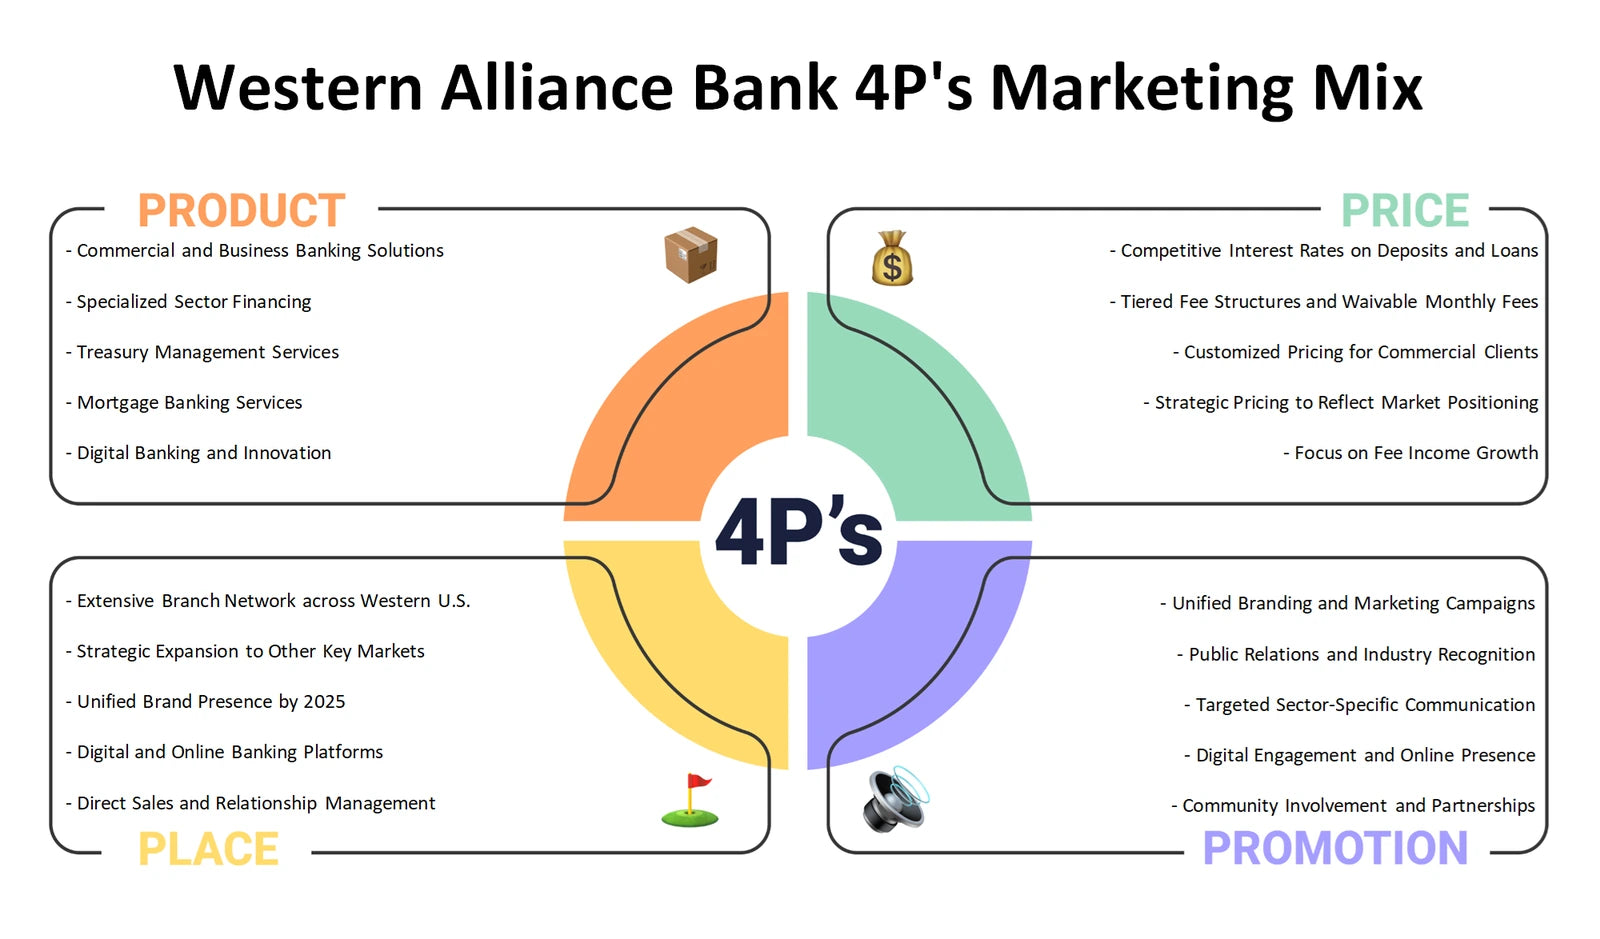
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external conditions could alter demand, risk, compliance obligations or operating costs for a U.S. commercial bank?
Western Alliance Bank PESTLE analysis considers Political, Economic, Social, Technological, Legal and Environmental influences that sit outside day-to-day management control. Political and legal questions can include banking supervision, policy direction and changing compliance expectations. Economic conditions may affect borrowing demand, deposit competition, credit performance and funding decisions. Social factors include how commercial clients expect to access advice and digital services. Technology creates both service opportunities and cyber, resilience and third-party-risk questions. Environmental considerations can affect client sectors, property exposure, operational continuity and risk assessment. PESTEL is a common alternative spelling of PESTLE; both describe the same external-environment lens.
- Rate and credit sensitivity. Explore how different economic conditions could affect clients' financing needs, deposit behavior and the bank's risk-management priorities without assuming a particular rate path.
- Control environment. Identify external developments that could increase the importance of cybersecurity, vendor oversight, payment resilience and regulatory documentation.
- External watchlist. Use the Excel framework to categorize environmental signals and the Word analysis to explain why selected developments may matter to banking decisions.
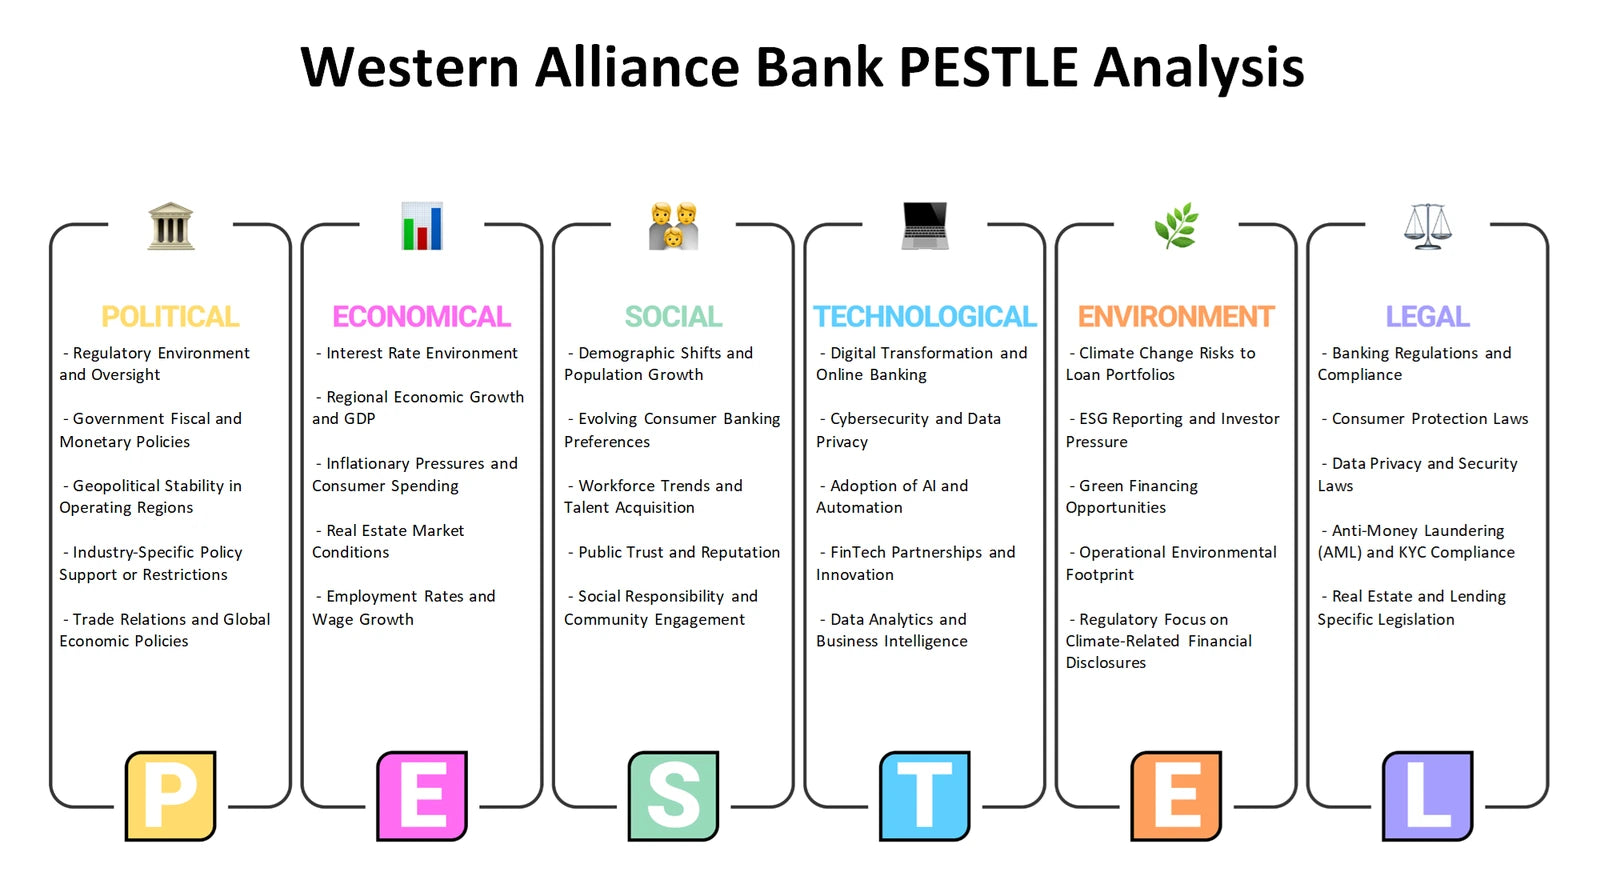
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal banking capabilities and constraints be considered alongside external openings and risks affecting commercial clients?
A Western Alliance Bank SWOT analysis keeps internal and external issues distinct. Strengths and weaknesses concern capabilities within the organization, such as relationship-banking expertise, specialized service capacity, technology integration, funding discipline, operational complexity or control requirements; they should be supported by evidence rather than assumed. Opportunities and threats arise outside the bank, including unmet client needs, changing financing alternatives, economic uncertainty, regulatory developments and technology-enabled competition. The supplied context makes partnerships a useful theme to examine: they may extend service capabilities, but they can also create dependency, oversight and resilience questions. SWOT helps convert this broad evidence into priorities without presenting plausible themes as proven findings.
- Internal diagnosis. Separate controllable resources, processes and capabilities from weaknesses that may require investment, governance attention or clearer operating choices.
- External fit. Compare potential opportunities in commercial banking with threats from market shifts, substitutes, compliance demands and changing customer expectations.
- Priority translation. Use the Excel SWOT grid to classify evidence and use the Word analysis to develop balanced implications, open questions and possible management discussion points.
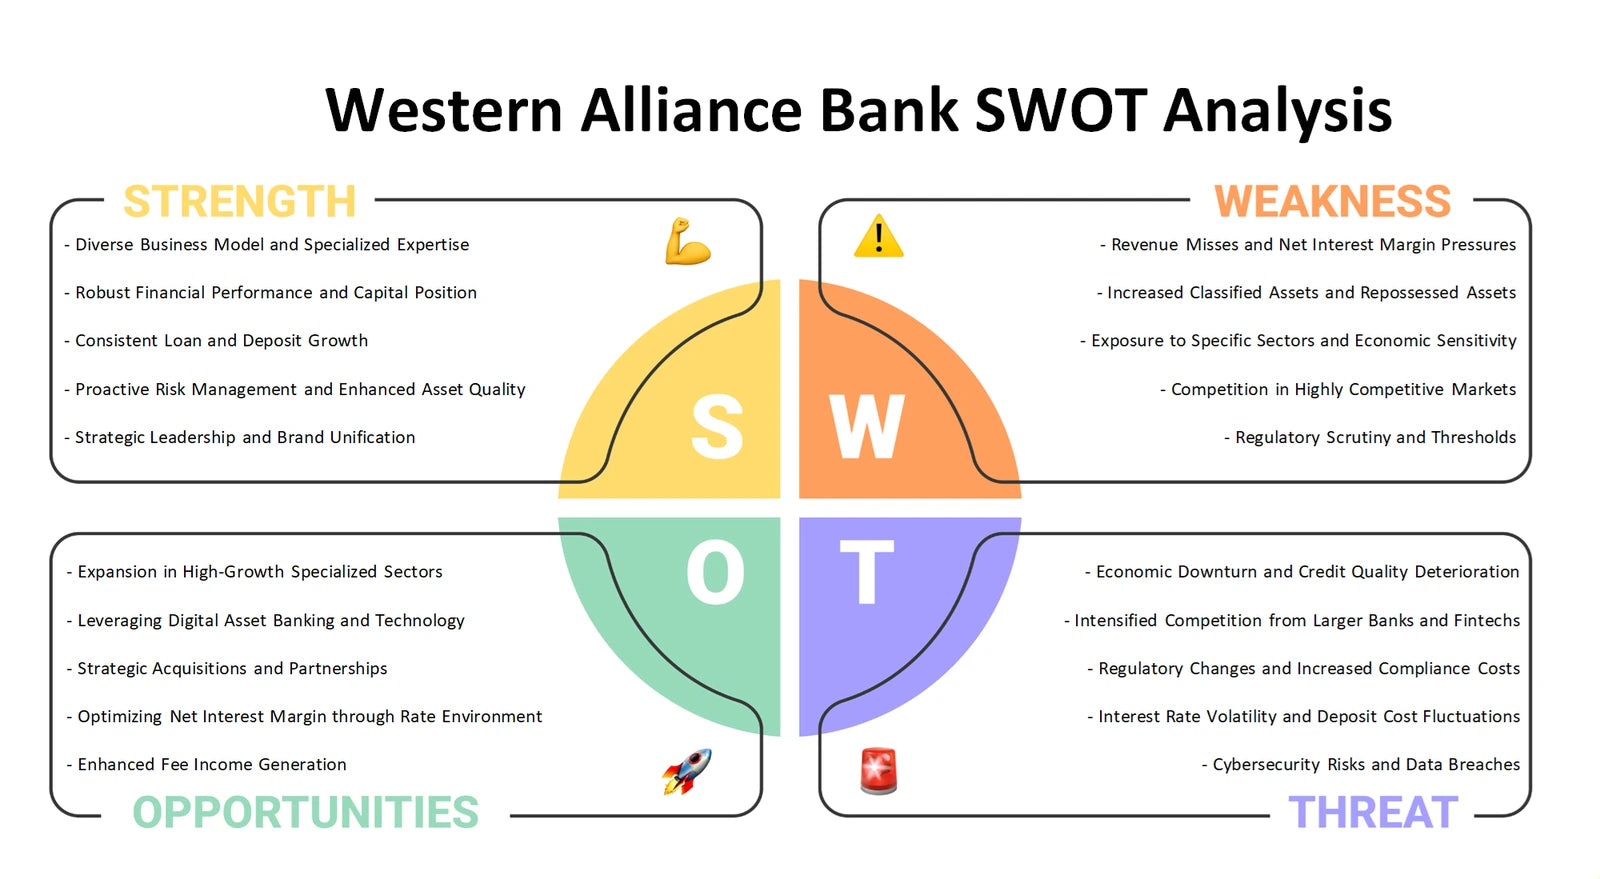
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of commercial banking strategy
Together, the six perspectives move from portfolio choices and value creation to industry pressure, customer-facing decisions, external conditions and internal-versus-external priorities. The Excel frameworks help organize comparisons and questions, while the detailed Word materials provide a fuller company-specific basis for developing strategy discussions around Western Alliance Bank's commercial banking model, partnerships and operating trade-offs.
Company background: Western Alliance Bank — SEC issuer filing profile for Western Alliance Bancorporation.