

VCREDIT: Underwriting and Lending Economics – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
VCREDIT Strategy Analysis Bundle
VCREDIT is treated here as the lending-model business described in the supplied product context: a business whose value creation depends on underwriting, pricing and risk controls for borrowers. No verified legal entity, parent company or operating geography is used where the available context does not establish it, helping keep this analysis focused on the intended lending business rather than an unrelated same-name organisation.
For a lender, strategic choices connect closely: customer demand affects credit-product priorities, funding and operating costs affect pricing, and risk management influences both growth capacity and borrower trust. The six frameworks help examine those links from different angles, including which lending activities deserve resources, how the model earns income, and which external forces could alter the economics of credit.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which potential lending products or borrower segments should receive scarce capital, operating attention and risk capacity?
A VCREDIT BCG Matrix helps separate portfolio-priority questions from simple loan-volume growth. The framework compares market growth with relative market share, then uses the familiar Stars, Cash Cows, Question Marks and Dogs categories to organise possible choices. For a lending-model business, the exercise can test whether a product line, acquisition route or customer segment may justify further investment after accounting for underwriting effort, servicing needs and credit-risk exposure. It does not assign VCREDIT offerings to a quadrant or claim a market-share position. Instead, it gives decision-makers a disciplined way to compare growth prospects with the resources required to support them.
- Growth versus position. Compare demand potential for lending categories against VCREDIT's relative standing in the relevant market rather than treating every originations increase as equally valuable.
- Capital allocation. Consider how portfolio priorities may affect risk capacity, technology work, borrower acquisition effort and ongoing loan administration.
- Portfolio working view. Use the Excel matrix to organise candidate offerings and use the Word analysis to document assumptions, evidence needs and management questions behind each placement.
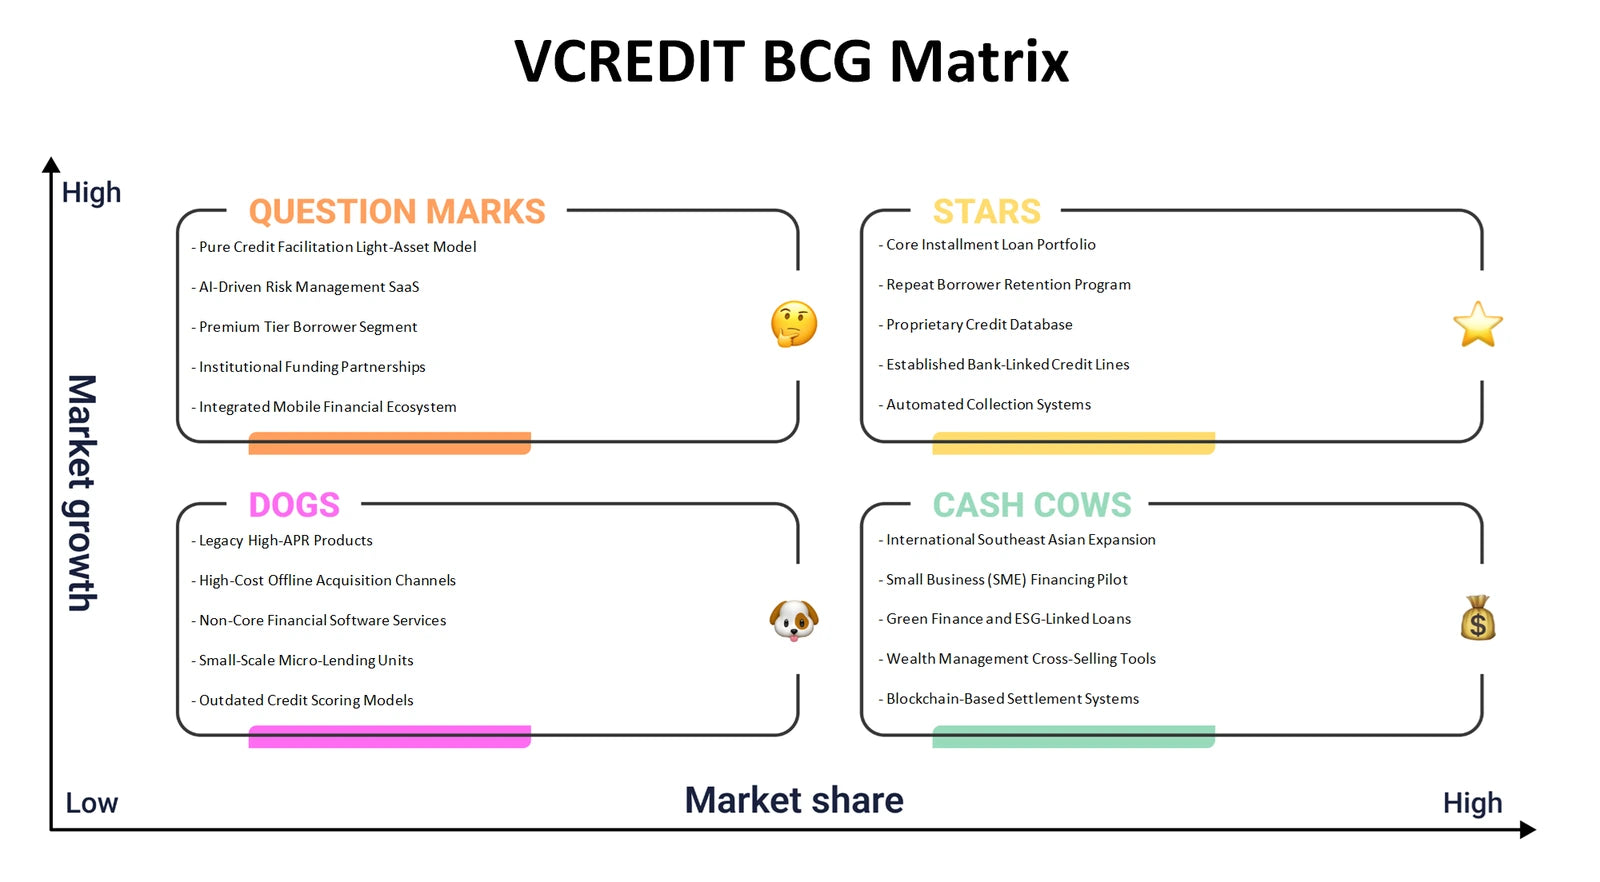
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do VCREDIT's lending, underwriting and risk-control activities connect to borrower value and sustainable economics?
The VCREDIT Business Model Canvas examines the full logic of a lending business rather than viewing pricing or risk in isolation. It brings together customer segments, value propositions, channels and customer relationships with revenue streams, key resources, key activities, key partnerships and cost structure. For example, an attractive borrower proposition may depend on a smooth application journey, credible credit decisions and clear repayment communication; each can create technology, compliance, servicing or funding implications. The framework helps map those connections without assuming unverified channels, partners or revenue figures. It is particularly useful when a change to approval criteria, pricing approach or customer access could improve one block while placing pressure on another.
- Borrower proposition. Examine what prospective borrowers may value in a credit relationship and what evidence is needed to support a differentiated service proposition.
- Economic links. Trace how revenue streams and cost structure may be influenced by risk assessment, servicing, capital access, customer acquisition and operating controls.
- Model alignment. Populate the structured Excel canvas as a one-page working map, then use the Word analysis to explore the trade-offs and interdependencies in greater detail.
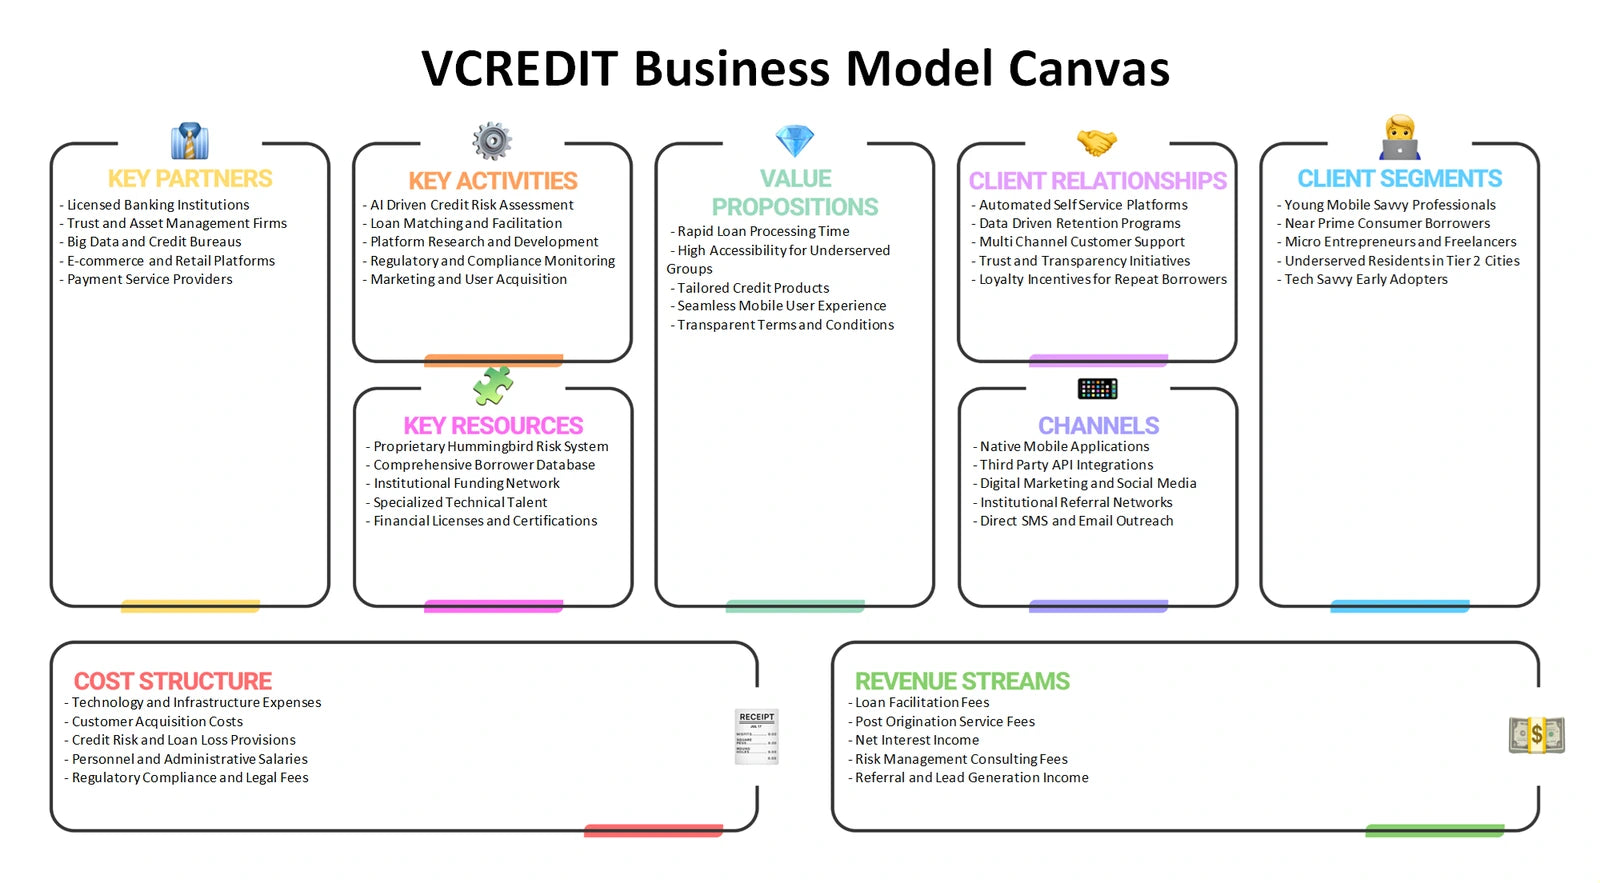
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could influence VCREDIT's ability to attract borrowers, price credit and protect lending margins?
VCREDIT Porter's Five Forces frames lending as an industry shaped by more than direct competition. Rivalry can affect borrower acquisition and pricing discipline; buyer power concerns how easily borrowers can compare providers or defer borrowing. Supplier power may matter where access to funding, data, technology or specialist service providers influences the cost and continuity of lending operations. The threat of new entrants tests barriers created by regulation, capital, trust and underwriting capability. Substitutes go further than another lender, covering alternative ways a customer can meet a financing need, such as saving longer, using supplier terms or seeking other forms of payment flexibility. The analysis offers questions to investigate, not unsupported force scores.
- Margin pressure. Explore how rivalry and borrower choice may constrain pricing, approval standards, service quality or acquisition spending.
- Operating dependencies. Assess where funding sources, credit information, technology infrastructure or outsourced capabilities could create negotiating exposure.
- Evidence-led comparison. Use the Excel framework to record each force and its indicators, while the Word analysis supports fuller reasoning about implications for VCREDIT's lending model.
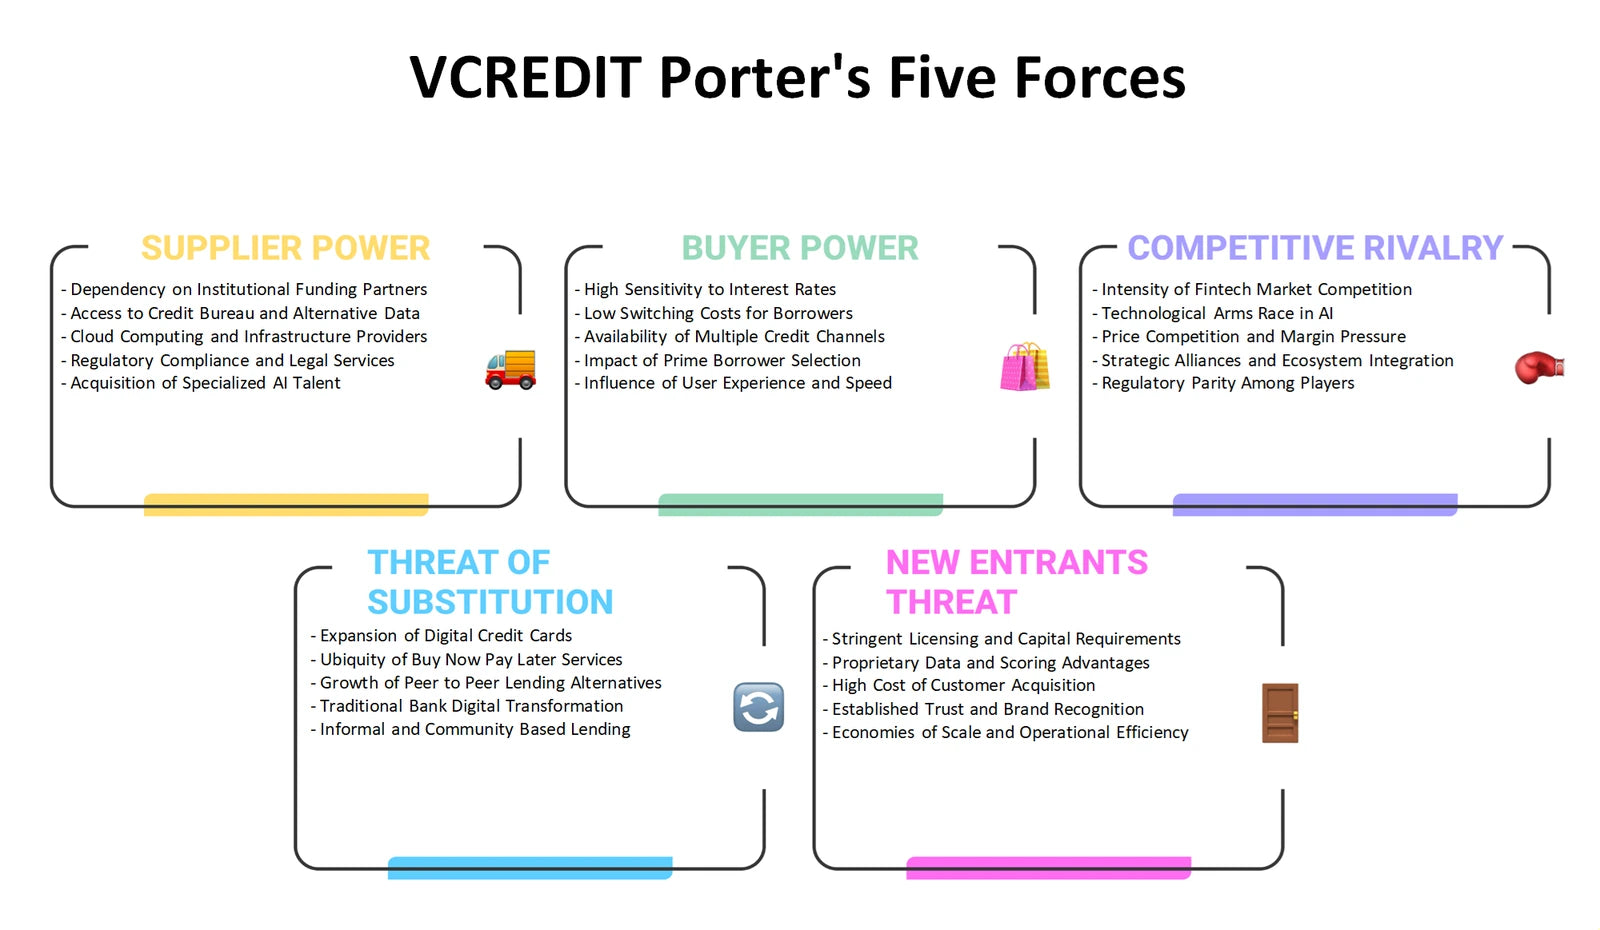
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can VCREDIT communicate and deliver lending products without separating customer acquisition from responsible credit decisions?
The VCREDIT Marketing Mix considers Product, Price, Place and Promotion in a service where trust and clarity matter alongside demand generation. Product analysis can examine loan features, application experience, repayment support and the fit between an offering and borrower needs. Price covers the logic, transparency and affordability questions surrounding borrowing costs rather than inventing a rate. Place investigates the routes through which prospective borrowers discover, apply for and access lending services. Promotion considers how messages can communicate eligibility, terms and benefits in a way that is understandable and appropriate for a credit decision. Together, the 4Ps help connect market positioning with operational delivery and risk-aware customer treatment.
- Offer design. Review how lending features, application steps and repayment expectations may shape perceived usefulness and borrower confidence.
- Responsible communication. Compare pricing presentation, promotional claims and channel choices against the need for clear, balanced customer information.
- Go-to-market workshop. Structure the four Ps in Excel for focused review, then use the Word analysis to develop discussion points around customer fit, controls and channel consistency.
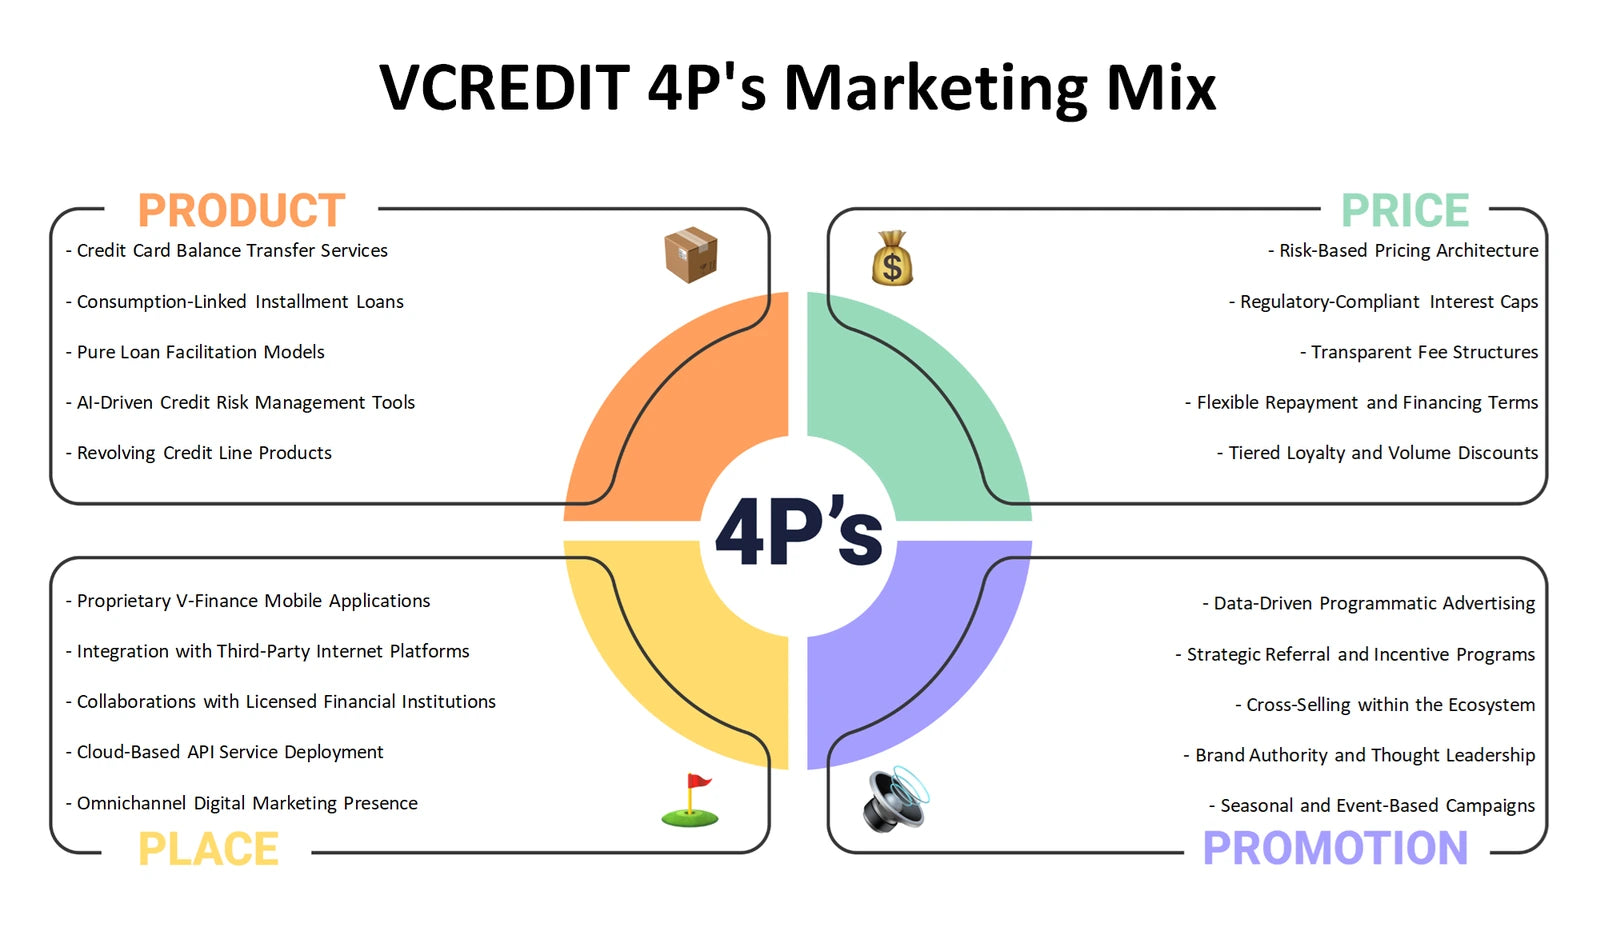
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could change demand for credit, lending economics and the control environment around VCREDIT?
A VCREDIT PESTLE analysis, also commonly called PESTEL, separates external influences that can affect a lender even when they are outside management's direct control. Political conditions can alter policy priorities around consumer or business finance. Economic conditions may influence borrowing demand, repayment capacity, funding costs and default risk. Social expectations can shape trust, financial confidence and attitudes toward credit. Technological change may affect identity checks, data use, automation and digital access. Legal questions can cover lending, consumer protection, privacy and financial-crime obligations, while environmental conditions may influence borrower resilience and risk exposure in affected sectors or locations. These are analytical areas to monitor, not claims that a particular change has occurred.
- External signals. Identify which macroeconomic, policy and customer-behaviour developments warrant regular attention in a lending-model business.
- Control implications. Consider how technology, legal duties and environmental disruptions could affect underwriting, data handling, servicing and operational continuity.
- Monitoring agenda. Use the Excel framework to classify external drivers by category and use the Word analysis to capture why selected developments may matter to VCREDIT.
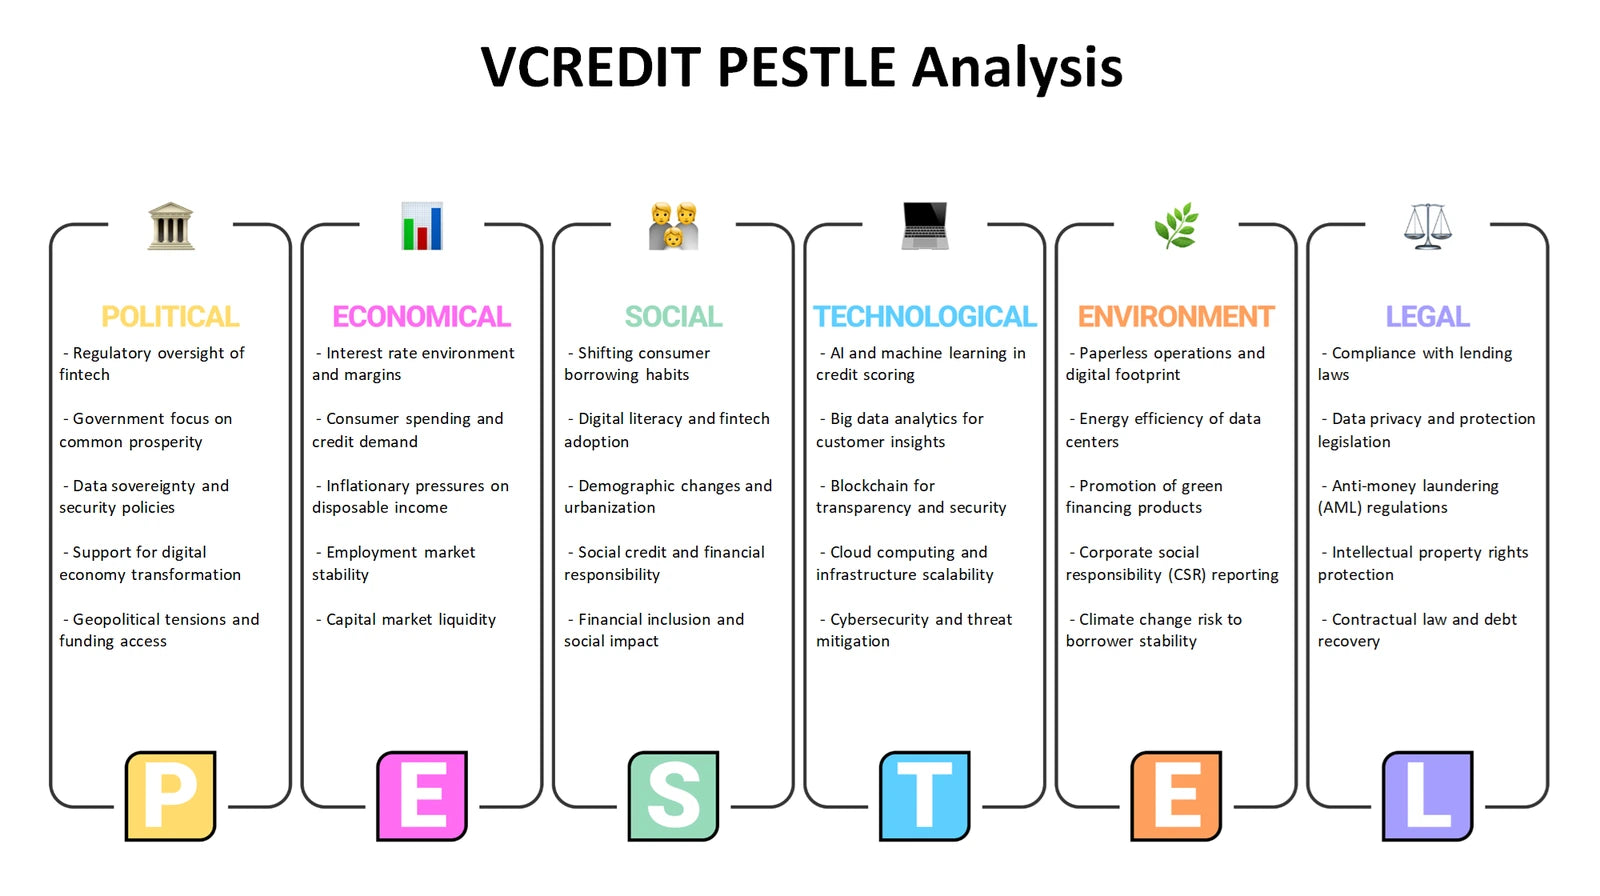
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal lending capabilities and constraints should VCREDIT weigh against external opportunities and threats?
A VCREDIT SWOT analysis provides a disciplined distinction between internal and external considerations. Strengths and weaknesses concern capabilities or limitations within the business, such as underwriting processes, risk governance, customer-service capacity, technology, funding access or brand trust where evidence supports examination. Opportunities and threats arise outside the business, including changing borrower needs, market openings, competitive intensity, economic stress or regulatory developments. The value lies in testing how these categories interact: a possible market opportunity may only be attractive if internal controls and resources can support it, while an external threat may be reduced through an existing capability. The analysis does not present plausible themes as confirmed findings; it creates a structured basis for validation and prioritisation.
- Internal reality check. Separate controllable capabilities and operating constraints from conditions that belong to the wider lending environment.
- Strategic fit. Explore whether potential opportunities match VCREDIT's risk appetite, servicing capacity and ability to maintain sound lending practices.
- Priority register. Use the Excel SWOT grid to capture and compare themes, then use the Word analysis to explain evidence, dependencies and possible strategic responses.
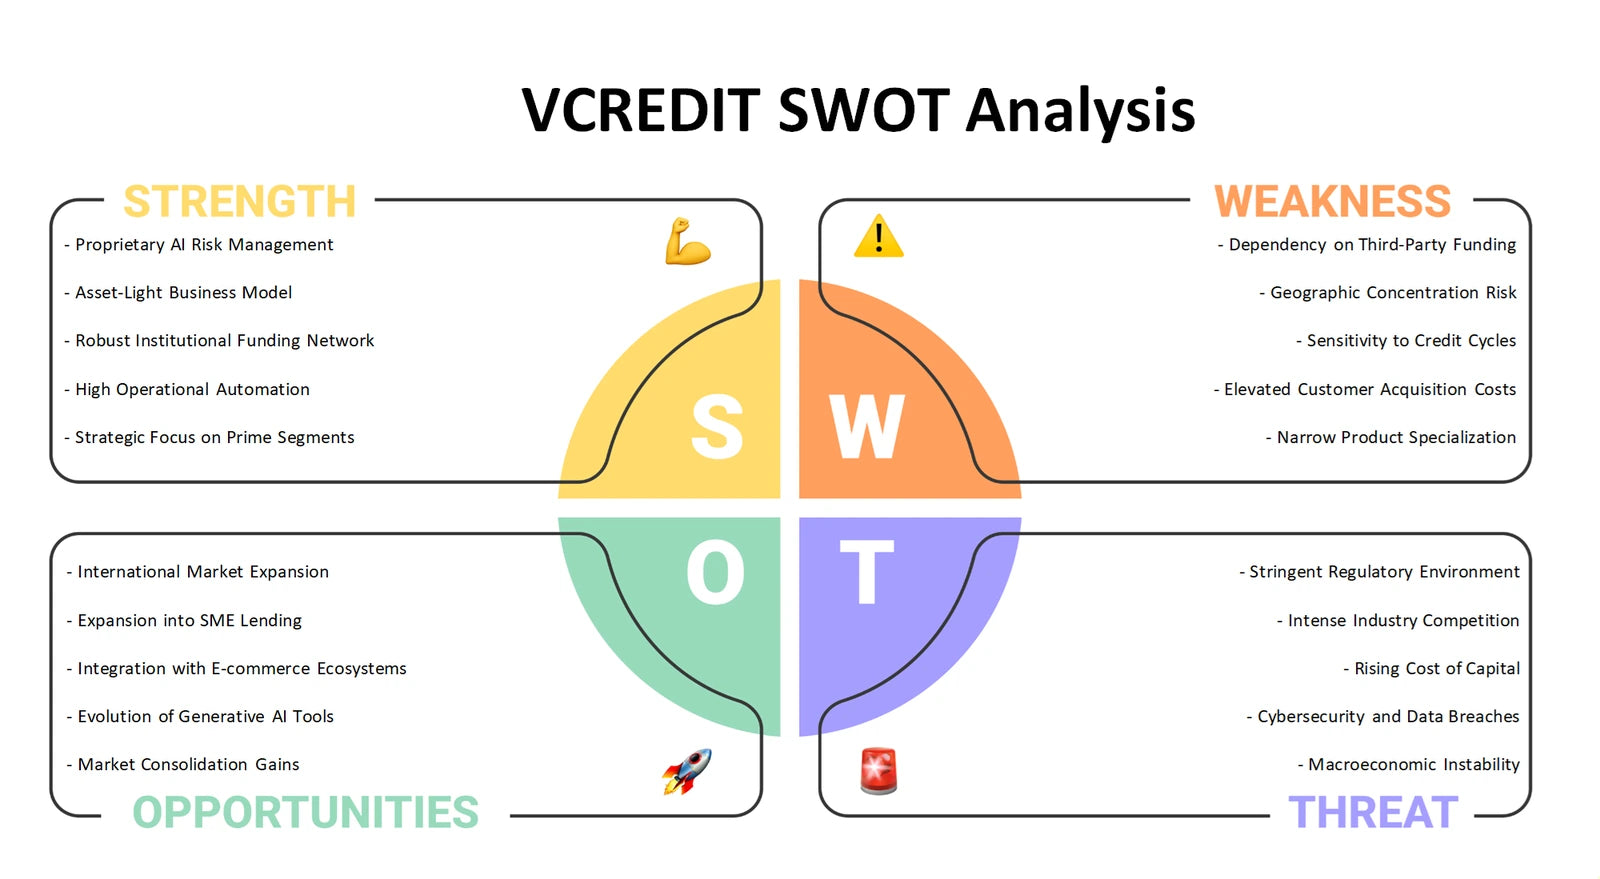
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Bring lending strategy into one connected view
Used together, the six perspectives let customers examine VCREDIT from portfolio, business-model, industry, market, external-environment and capability viewpoints. The Excel frameworks provide structured places to compare issues and record priorities, while the detailed Word analyses support fuller interpretation of lending economics, customer value, underwriting and risk-control questions. This combination can help turn separate strategic observations into a more coherent agenda for discussion and further validation.
Company background: VCREDIT — product-context page on PESTLE Analysis.