

Universal Insurance Holdings: Insurance Business – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
Universal Insurance Holdings Strategy Analysis Bundle
Universal Insurance Holdings refers here to UNIVERSAL INSURANCE HOLDINGS, INC., a U.S. fire, marine and casualty insurance issuer classified under SIC 6331. The business context for this bundle centres on serving insurance policyholders while managing underwriting exposure, claims obligations, capital and reinsurance relationships, with particular attention to its concentrated Florida-market exposure.
In its July 30, 2026 Form 10-Q filing, the company reported revenue of $427.033 million and GAAP net income of $59.188 million for April 1 through June 30, 2026. Those quarterly figures make portfolio allocation, catastrophe-risk transfer and customer-value choices useful questions for the six analysis lenses below; they do not indicate when the downloadable files were prepared.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance products, policyholder segments or geographic exposures deserve capital and management attention?
The Universal Insurance Holdings BCG Matrix provides a disciplined way to compare possible business units through market growth and relative market share, rather than treating premium volume alone as a priority signal. For an insurer with Florida catastrophe exposure and material reinsurance needs, the exercise can help frame where growth may consume capital, where established books may generate dependable cash, and where retrenchment or further investigation may be warranted. It does not assign any Universal business to a quadrant or claim market-share results.
- Portfolio comparison. Examine potential Stars, Cash Cows, Question Marks and Dogs using consistently defined product, territory or customer-group boundaries.
- Capital discipline. Compare growth potential with underwriting capacity, catastrophe aggregation and the cost of transferring risk to reinsurers.
- Working view. Use the Excel matrix to organise candidate units and the Word analysis to document assumptions, evidence gaps and priority questions.
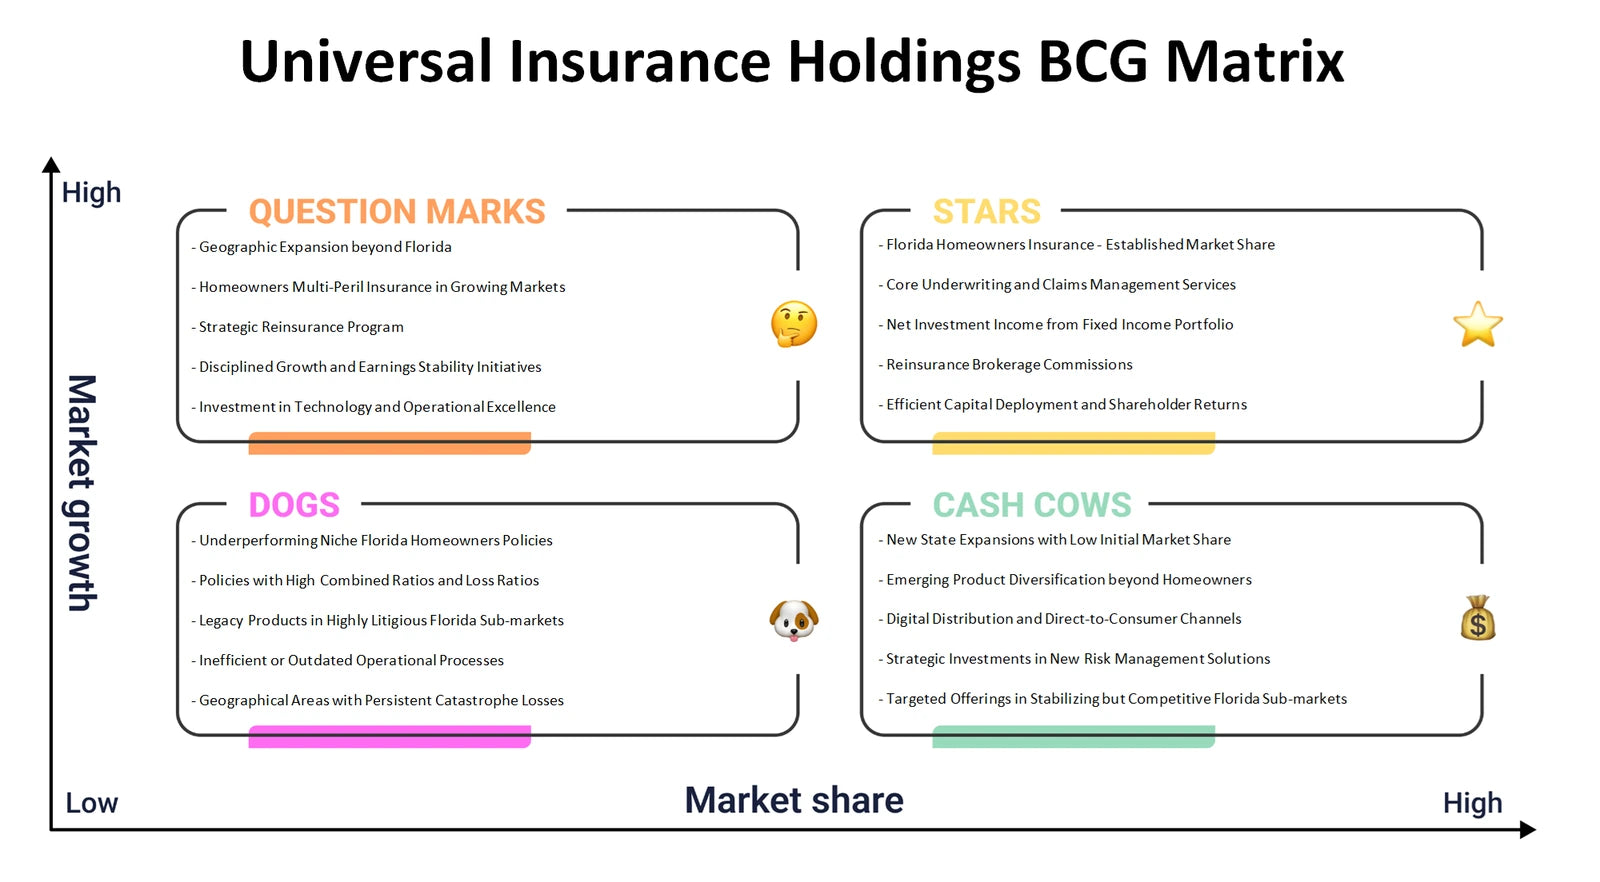
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do underwriting, claims service, capital management and risk transfer connect to sustainable policyholder value?
The Universal Insurance Holdings Business Model Canvas connects all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. It is especially useful for testing the links between policyholders’ need for dependable coverage, the distribution and service routes used to reach them, premium-based revenue, underwriting and claims activity, and the capital required to support obligations. Reinsurance providers and investment-management relationships are important subjects because they can affect liquidity, resilience and the economics of a concentrated insurance market.
- Value delivery. Map how coverage, claims responsiveness and financial reliability may shape the proposition offered to policyholders.
- Economic links. Trace how premiums, investment income, operating costs, claims costs and reinsurance arrangements may interact.
- Model testing. Populate the Excel canvas with connected assumptions, then use the Word analysis to explain dependencies and trade-offs.
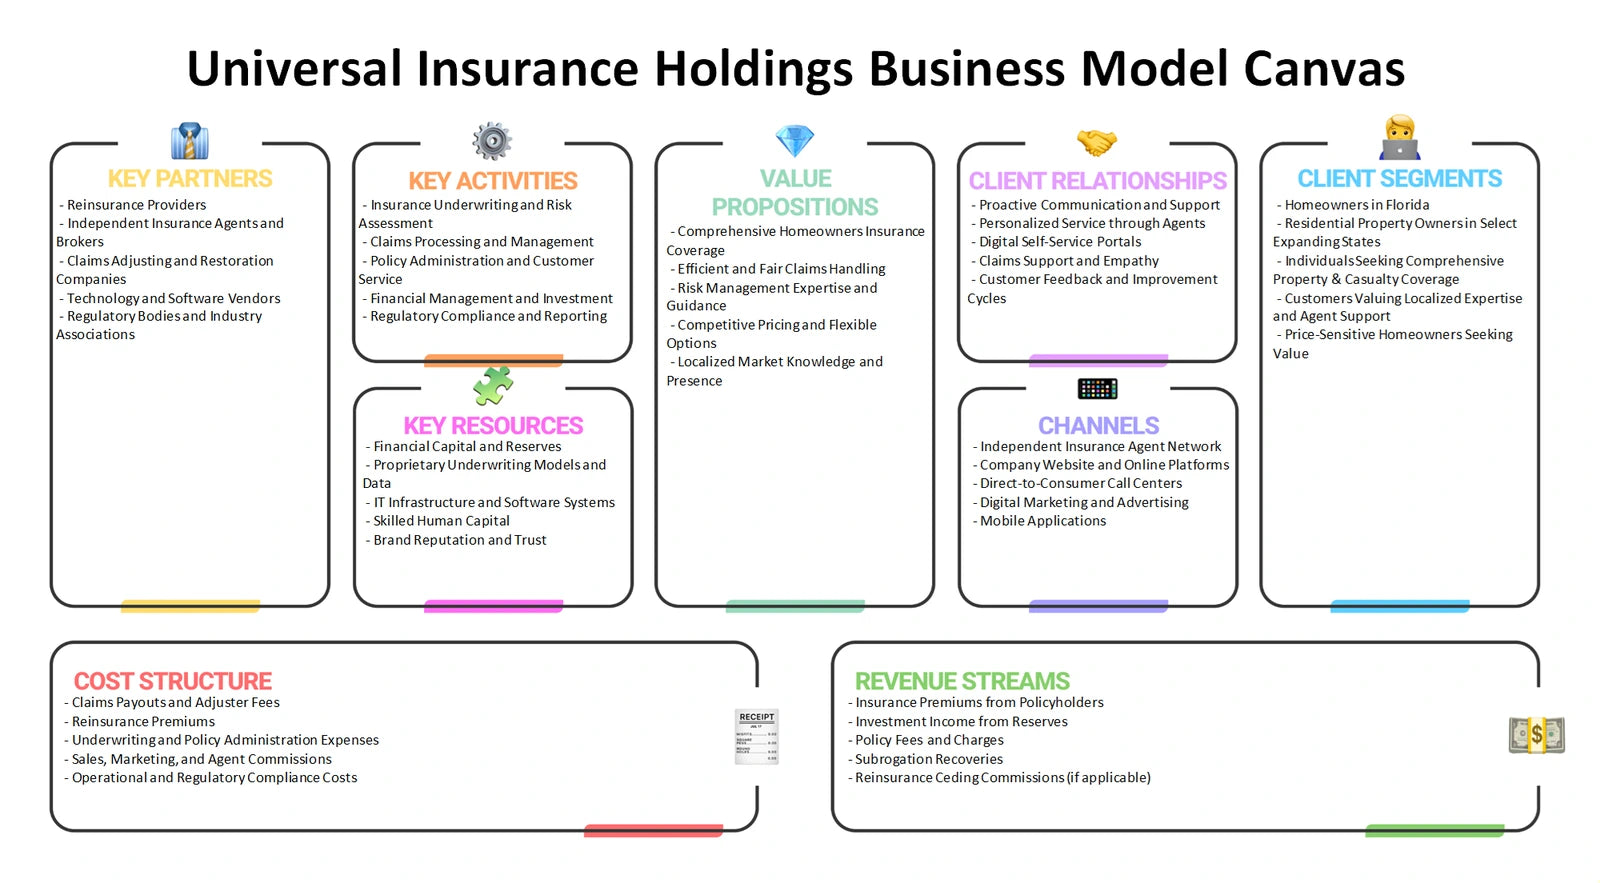
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could influence underwriting margins, distribution economics and the availability of risk capacity?
Universal Insurance Holdings Porter's Five Forces analysis examines the competitive setting around property and casualty insurance without assuming a force score or naming unverified rivals. Rivalry can affect pricing and retention; supplier power can include the influence of reinsurance markets, technology vendors and distribution partners; and buyer power can reflect policyholders’ ability to compare coverage and switch. The framework also considers new entrants with capital or specialist underwriting capability, plus substitutes such as self-insurance, higher deductibles or alternative risk-financing arrangements that meet a similar protection need.
- Competitive pressure. Separate price competition from differences in coverage terms, service, underwriting appetite and financial strength perceptions.
- Capacity dependence. Assess how reinsurance availability and cost may shape the room to write or retain catastrophe-exposed risk.
- Evidence trail. Use the Excel framework to compare each force and the Word analysis to record the reasoning behind strategic responses.
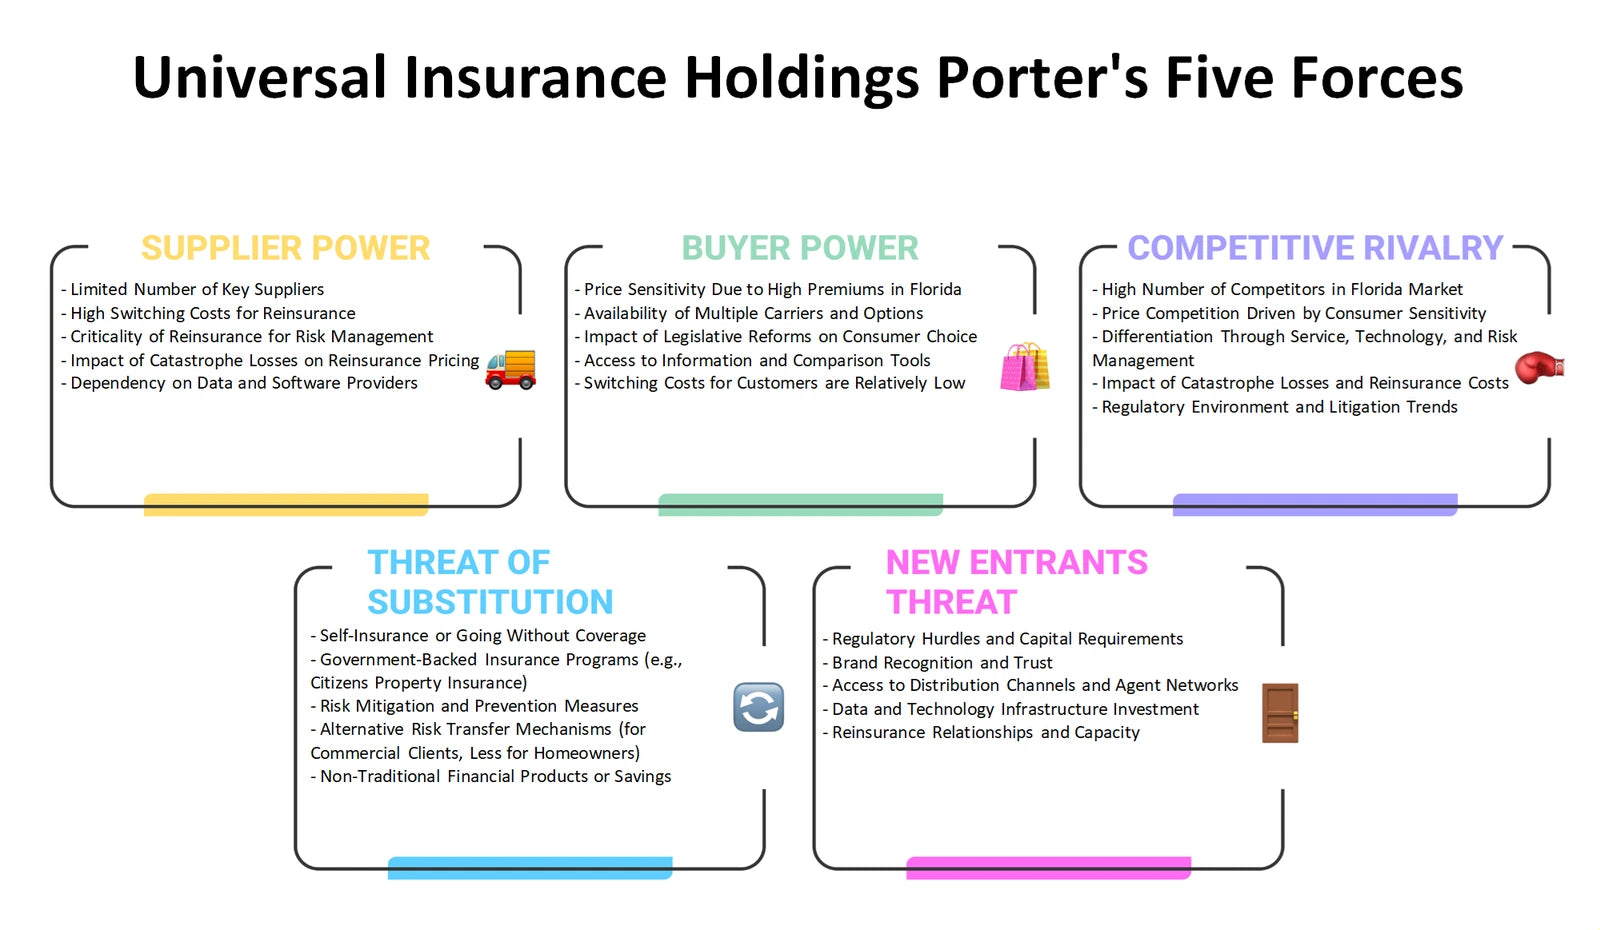
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can insurance offerings be positioned and communicated while respecting pricing, underwriting and regulatory constraints?
The Universal Insurance Holdings Marketing Mix considers Product, Price, Place and Promotion in a regulated insurance context. Product analysis can distinguish coverage design, policy terms and service expectations. Price is not merely a marketing lever: premiums must be considered alongside underwriting risk, claims exposure, reinsurance costs and regulatory requirements. Place examines how customers encounter and obtain policies, including the roles of direct and intermediary routes where applicable. Promotion explores clear communication of coverage value and limitations without presuming campaigns, prices or channel shares that are not evidenced.
- Offer design. Compare how policy features and claims-service expectations may address different customer needs and risk profiles.
- Route-to-customer. Examine the customer journey from awareness and quote through policy servicing, renewal and claims contact.
- Decision map. Use the Excel 4Ps structure to align questions by lever, then consult the Word analysis for company-specific context.
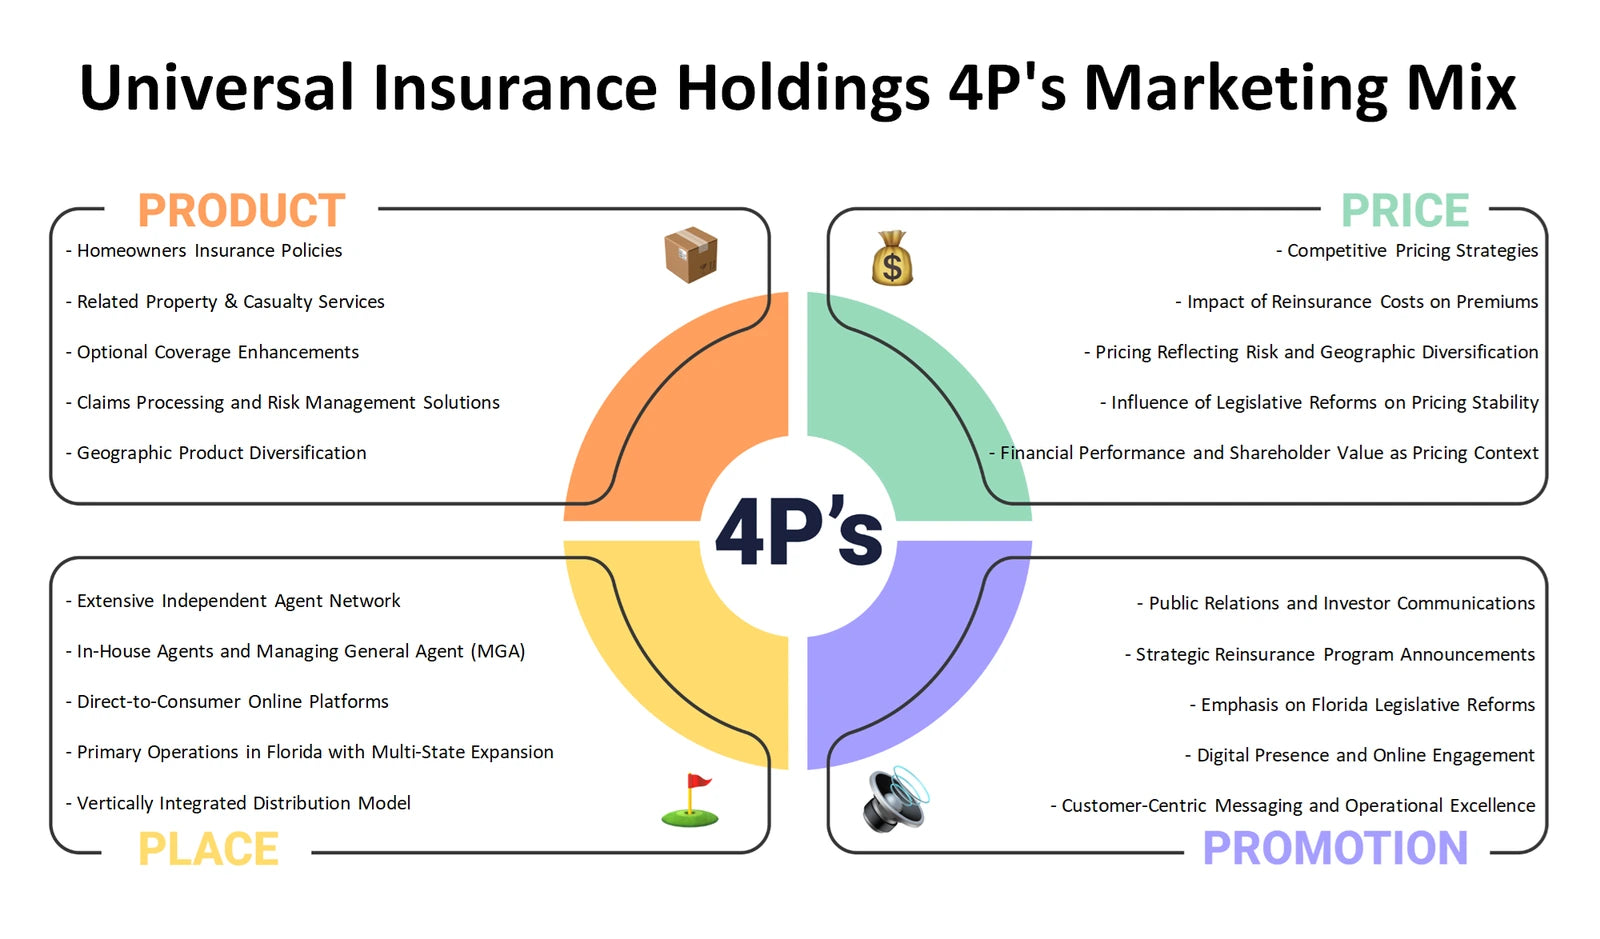
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter risk selection, affordability, capital needs or policyholder expectations?
The Universal Insurance Holdings PESTLE analysis, also commonly called PESTEL, separates six external dimensions that can otherwise become blurred in insurance planning. Political and Legal factors include regulatory oversight and insurance-policy questions. Economic conditions can influence investment returns, repair costs and household affordability. Social factors include changing expectations around coverage and claims service. Technological developments may affect quoting, fraud detection, modelling and customer contact. Environmental conditions are particularly relevant when catastrophe exposure is concentrated in Florida, while the framework avoids presenting possible hazards or policy changes as documented current events.
- External scan. Distinguish macroeconomic, regulatory, customer-behaviour and catastrophe-related influences rather than combining them into one risk list.
- Scenario questions. Explore how changes in rebuilding costs, climate exposure or data capabilities could affect underwriting and operations.
- Monitoring plan. Use the Excel categories to prioritise signals and the Word analysis to add context, implications and follow-up questions.
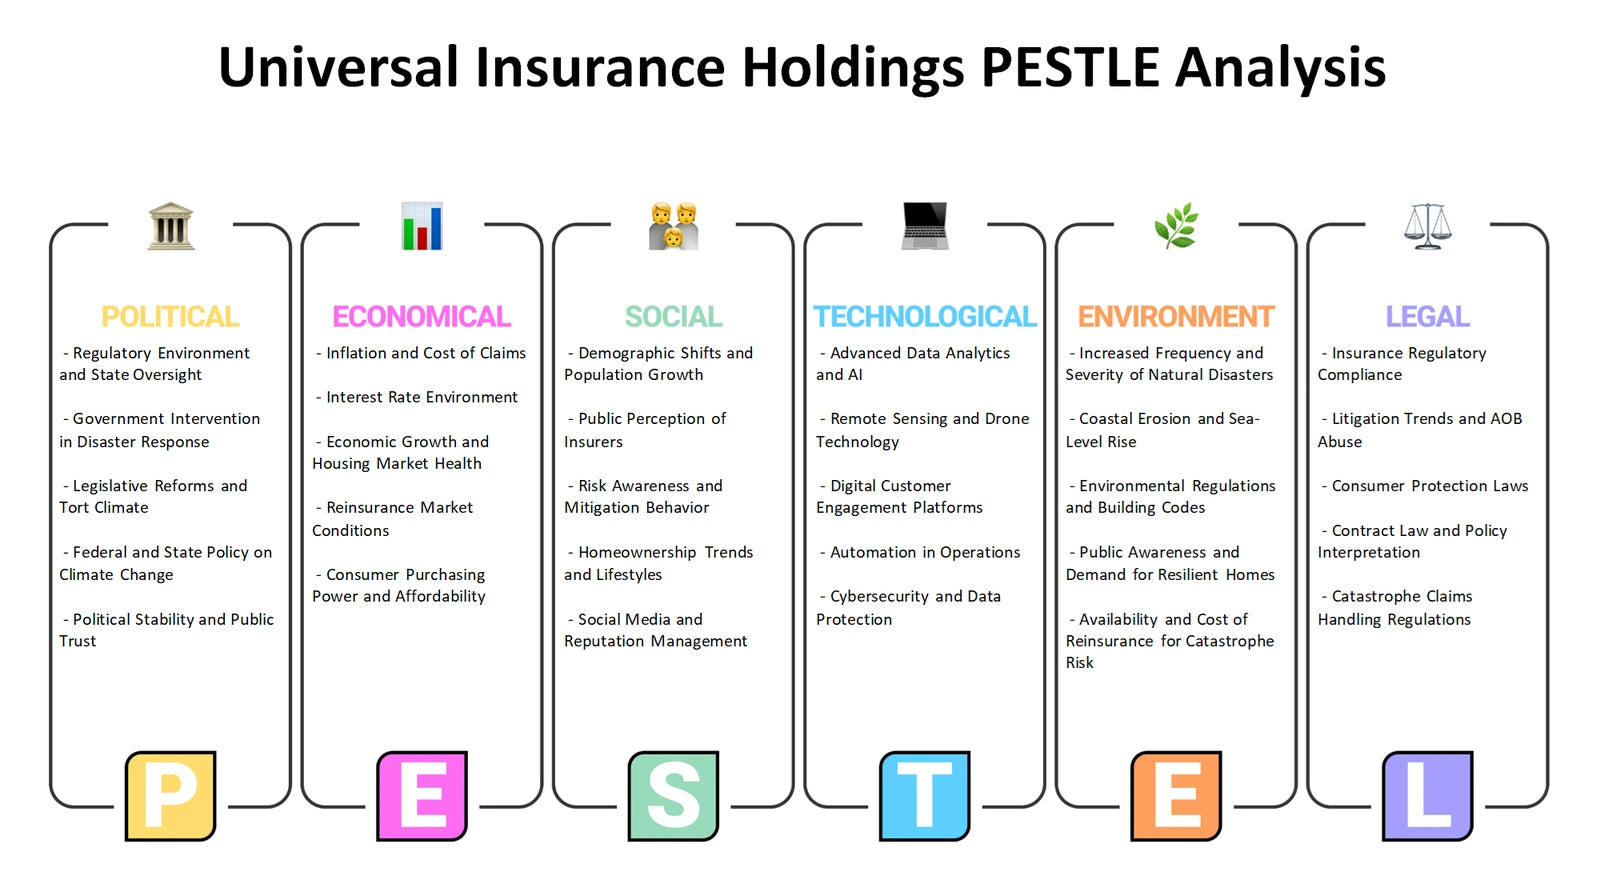
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal insurance capabilities and constraints be weighed against external market opportunities and threats?
The Universal Insurance Holdings SWOT analysis keeps internal and external factors distinct. Potential strengths and weaknesses concern resources, operating capabilities, underwriting discipline, claims processes, capital management and partnership arrangements that should be supported by evidence before being treated as findings. Opportunities and threats arise outside the business, such as shifts in customer demand, market capacity, catastrophe conditions, regulation or technology. This distinction matters because a favorable market opening is not automatically an internal capability, and a concentrated exposure may require careful analysis rather than an automatic conclusion.
- Internal evidence. Test candidate strengths and weaknesses against operational resources, processes and financial-risk-management questions.
- Strategic fit. Relate external opportunities and threats to the company’s ability to act while maintaining policyholder commitments.
- Action framing. Use the Excel grid to sort observations, then use the Word analysis to develop balanced implications and discussion prompts.
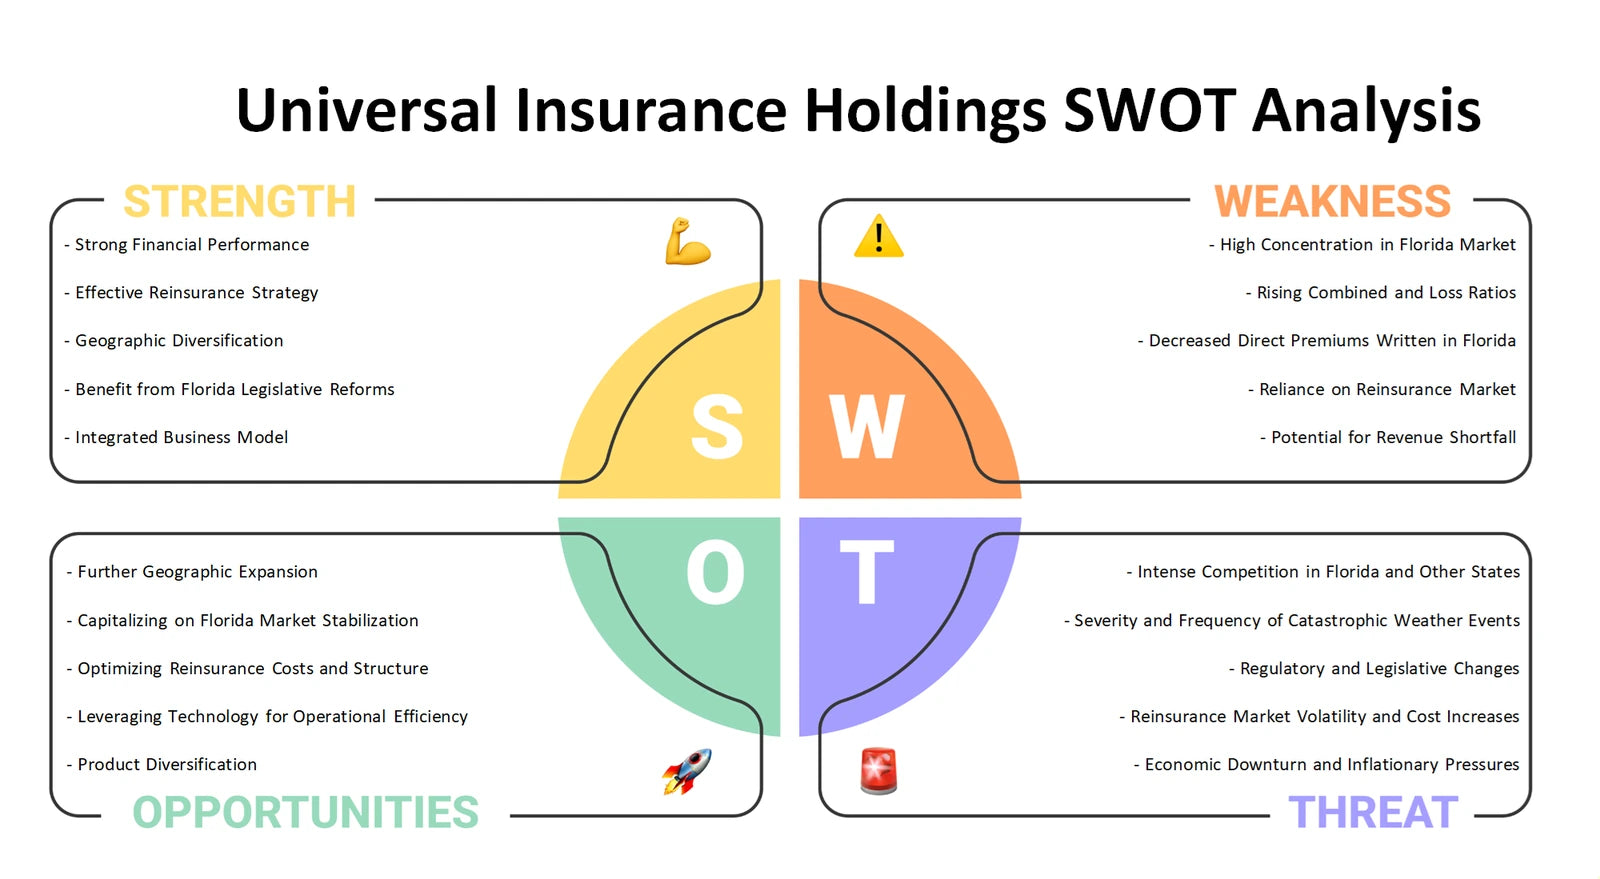
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Six connected lenses for insurance strategy
Together, the BCG Matrix, Business Model Canvas, Five Forces, Marketing Mix, PESTLE and SWOT perspectives move from portfolio choices and business-model economics to industry pressure, customer-facing decisions, external change and strategic fit. The Excel frameworks help organise comparison and discussion, while the detailed Word materials support a fuller company-specific review of risk, value creation and strategic priorities.
Company background: Universal Insurance Holdings — SEC regulatory issuer profile.