

UNIQA Insurance Group: Six Analyses of Insurance Business and Digital Investment

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
UNIQA Insurance Group Strategy Analysis Bundle
UNIQA Insurance Group is an Austrian insurance company serving policyholders through insurance protection and related risk-management services. Its business depends on assessing risk, collecting premiums, managing claims and maintaining trust over long customer relationships. In insurance, the quality of customer access, underwriting discipline and service delivery can matter as much as the range of policies offered.
The supplied business context highlights the relevance of reinsurance, a varied distribution network and technology partnerships to UNIQA Insurance Group. These factors create practical strategic questions: which parts of an insurance portfolio deserve resources, how value reaches customers through different channels, and how external regulation or changing risks affect operations. This bundle helps organise those questions using six connected strategy frameworks.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance product areas should receive investment, careful maintenance, selective testing or possible rationalisation?
A UNIQA Insurance Group BCG Matrix helps examine an insurance portfolio through two analytical criteria: market growth and relative market share. Rather than assuming that any policy line belongs in a particular quadrant, the framework provides a disciplined way to compare product categories, customer propositions or distribution-led businesses. It distinguishes the logic of Stars, Cash Cows, Question Marks and Dogs, then links that logic to resource priorities. For an insurer, this can mean comparing the demands of growth-oriented protection needs with established books that may generate dependable premium and renewal activity, while allowing for capital, claims and service implications.
- Portfolio logic. Compare relative market position with the pace of demand development before considering whether an area resembles a Star, Cash Cow, Question Mark or Dog.
- Capital discipline. Relate growth choices to underwriting capacity, reinsurance support, claims capability and the cost of acquiring and retaining policyholders.
- Structured comparison. Use the Excel framework to map candidate portfolio areas, then use the Word analysis to record assumptions and discuss why each priority may differ.
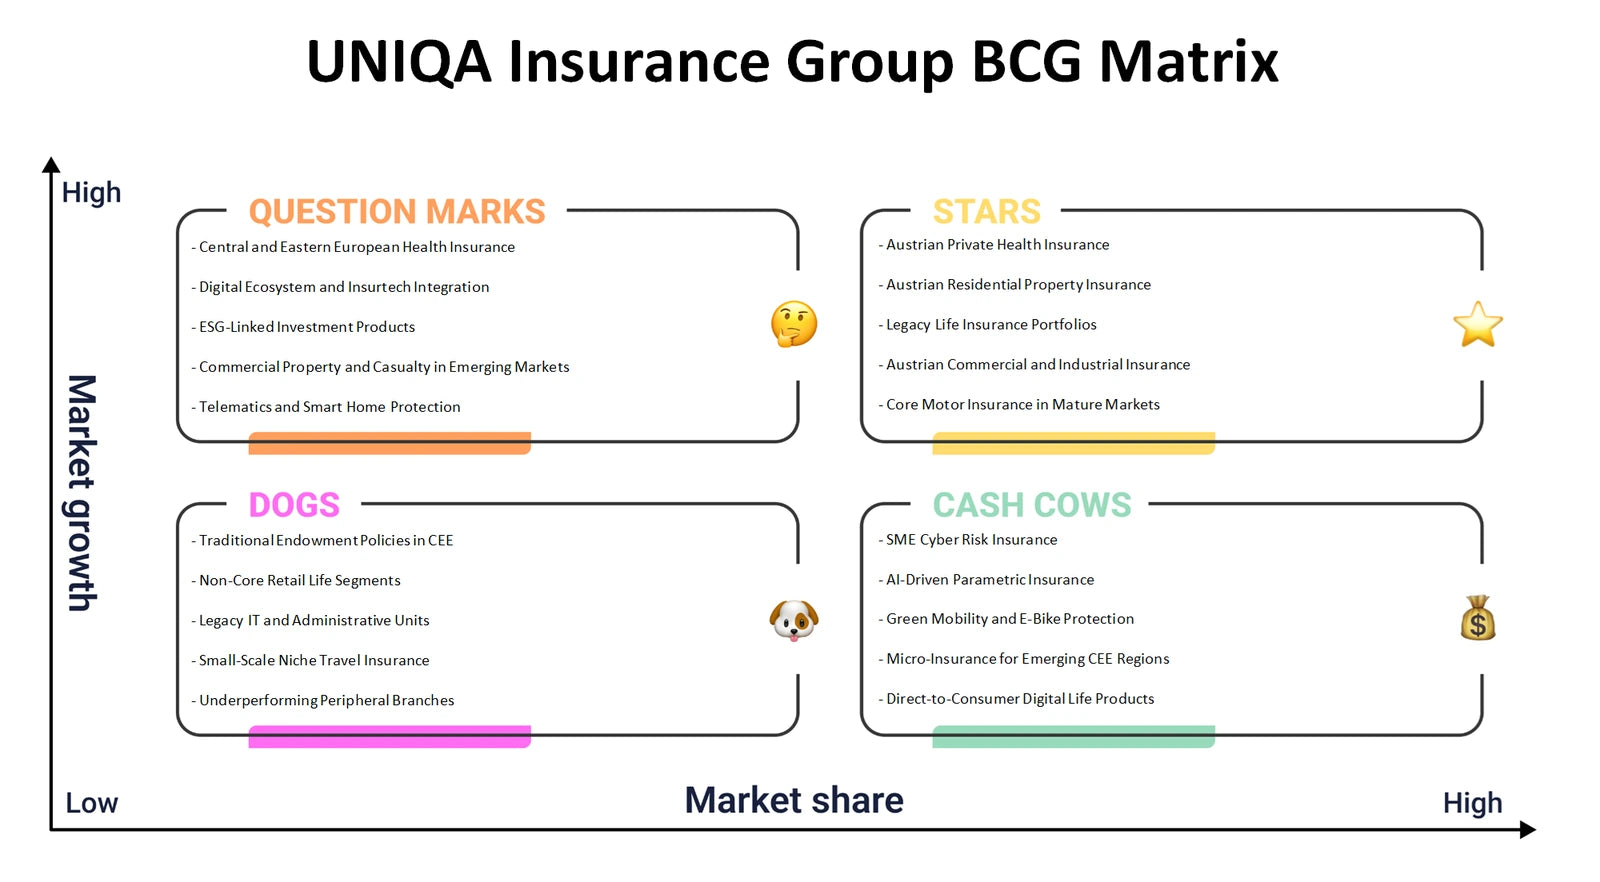
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do risk protection, trusted service and partner distribution connect to the economics of an insurer?
The UNIQA Insurance Group Business Model Canvas brings together all nine building blocks of value creation. It helps consider customer segments and value propositions alongside channels and customer relationships: policyholders need relevant cover, understandable service and confidence when a claim occurs. Revenue streams can be examined in relation to premium-based insurance economics, while key resources, key activities and cost structure direct attention to capabilities such as underwriting, claims handling, technology and risk control. Key partnerships are particularly relevant where reinsurance, brokers, tied agents, bancassurance relationships and technology providers can extend capacity or reach. The point is to test the connections between these elements, not to present an unverified model as a settled fact.
- Value chain connection. Trace how a customer promise travels from product design and distribution through policy servicing, claims support and renewal.
- Partner economics. Examine how reinsurance and distribution relationships may affect risk sharing, access to customers, operating costs and revenue quality.
- Model workshop. Populate the Excel canvas with evidence and open questions, using the Word analysis to explain the trade-offs behind each building block.
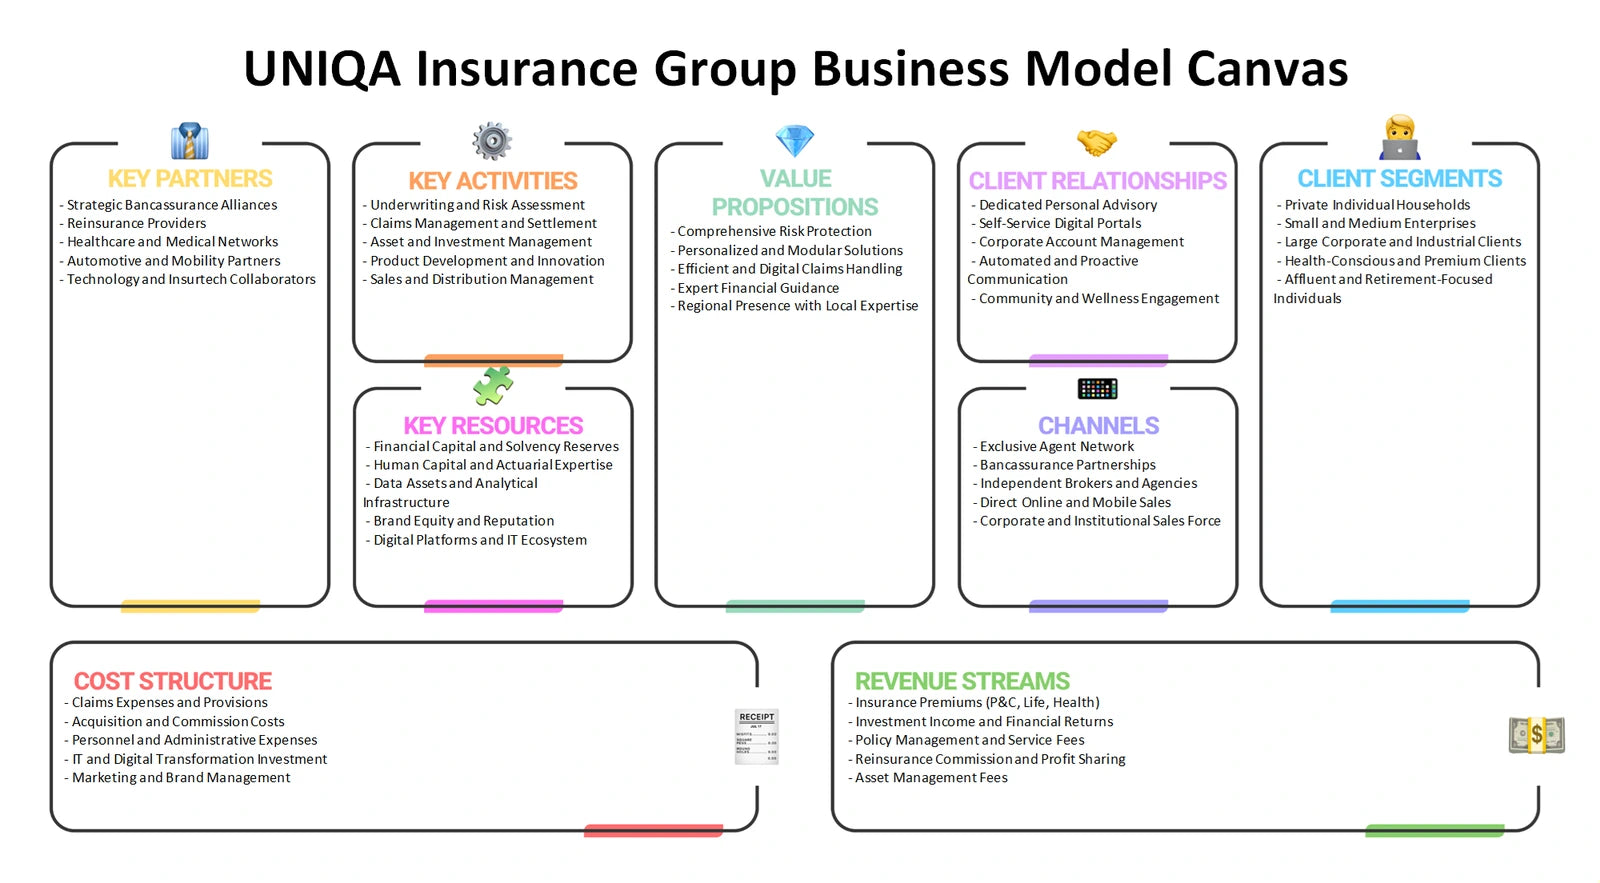
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can affect underwriting margins, customer retention and the cost of serving insurance demand?
UNIQA Insurance Group Porter's Five Forces analysis looks beyond direct insurance competitors to the structure of the market around an Austrian insurer. Rivalry can influence product differentiation, distribution spending and service expectations. Buyer power matters where customers can compare cover, switch providers or use advisers to seek alternatives. Supplier power can include dependence on specialist technology, distribution capability, repair and health-service ecosystems, or reinsurance capacity. Threats from new entrants may arise through digital propositions or niche providers, while substitutes include ways customers reduce, fund or transfer risk without purchasing comparable insurance. The framework does not assign force scores; it helps identify where evidence should be gathered and where strategic responses need testing.
- Competitive pressure. Assess how rivalry and customer choice may shape retention, acquisition costs and the need to explain policy value clearly.
- Risk-transfer access. Consider supplier influence across reinsurance, service providers and technology partners where external capability supports insurance delivery.
- Evidence trail. Use the Excel force map to list pressure points and questions, then use the Word analysis to connect them to possible operational implications.
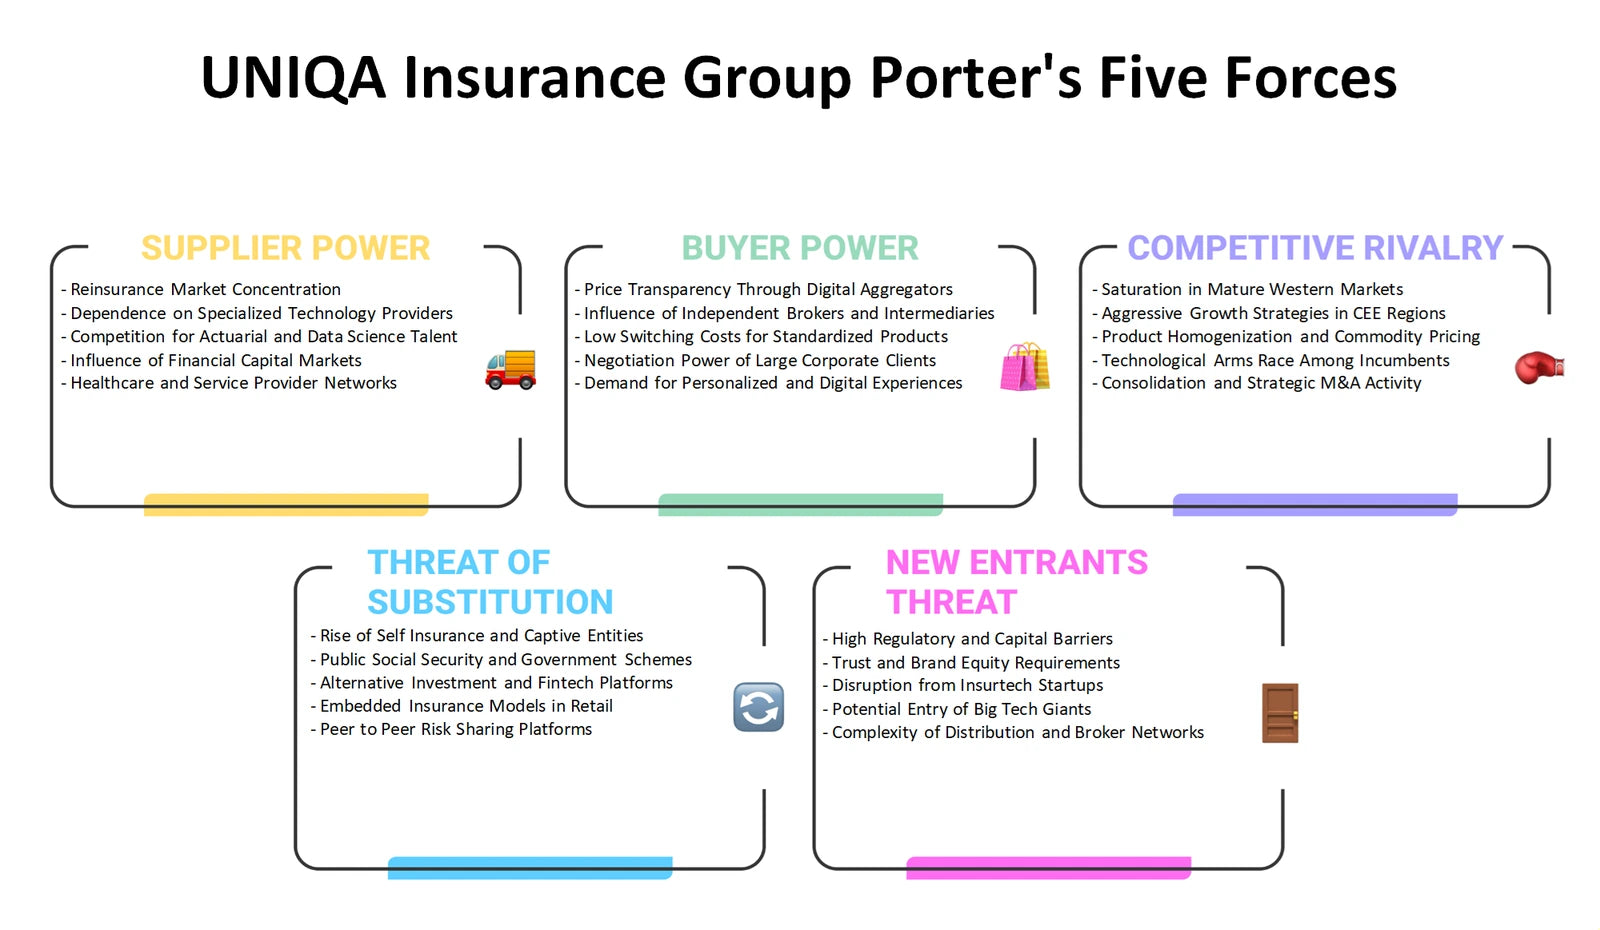
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can an insurer align policy design, pricing communication, distribution routes and promotion with customer trust?
A UNIQA Insurance Group Marketing Mix analysis adapts the 4Ps to a regulated service where customers often evaluate value over time and most intensely when they need support. Product covers the design, clarity and service experience surrounding insurance protection. Price examines premium logic, affordability, risk differentiation and how customers understand exclusions or terms, without inventing actual price points. Place considers direct digital journeys alongside brokers, tied agents and bancassurance routes described in the supplied business context. Promotion concerns useful, compliant communication that can explain protection and build confidence rather than merely generate attention. Together, the four Ps help test whether an offer can be understood, accessed and trusted by its intended audience.
- Offer clarity. Compare the customer problem addressed by a policy with the service features, explanations and claims experience needed to make it credible.
- Channel fit. Examine where adviser-led, bank-linked and digital access may suit different customer decisions and servicing needs.
- Planning application. Organise Product, Price, Place and Promotion observations in Excel, then use the Word analysis to develop a coherent customer-facing narrative.
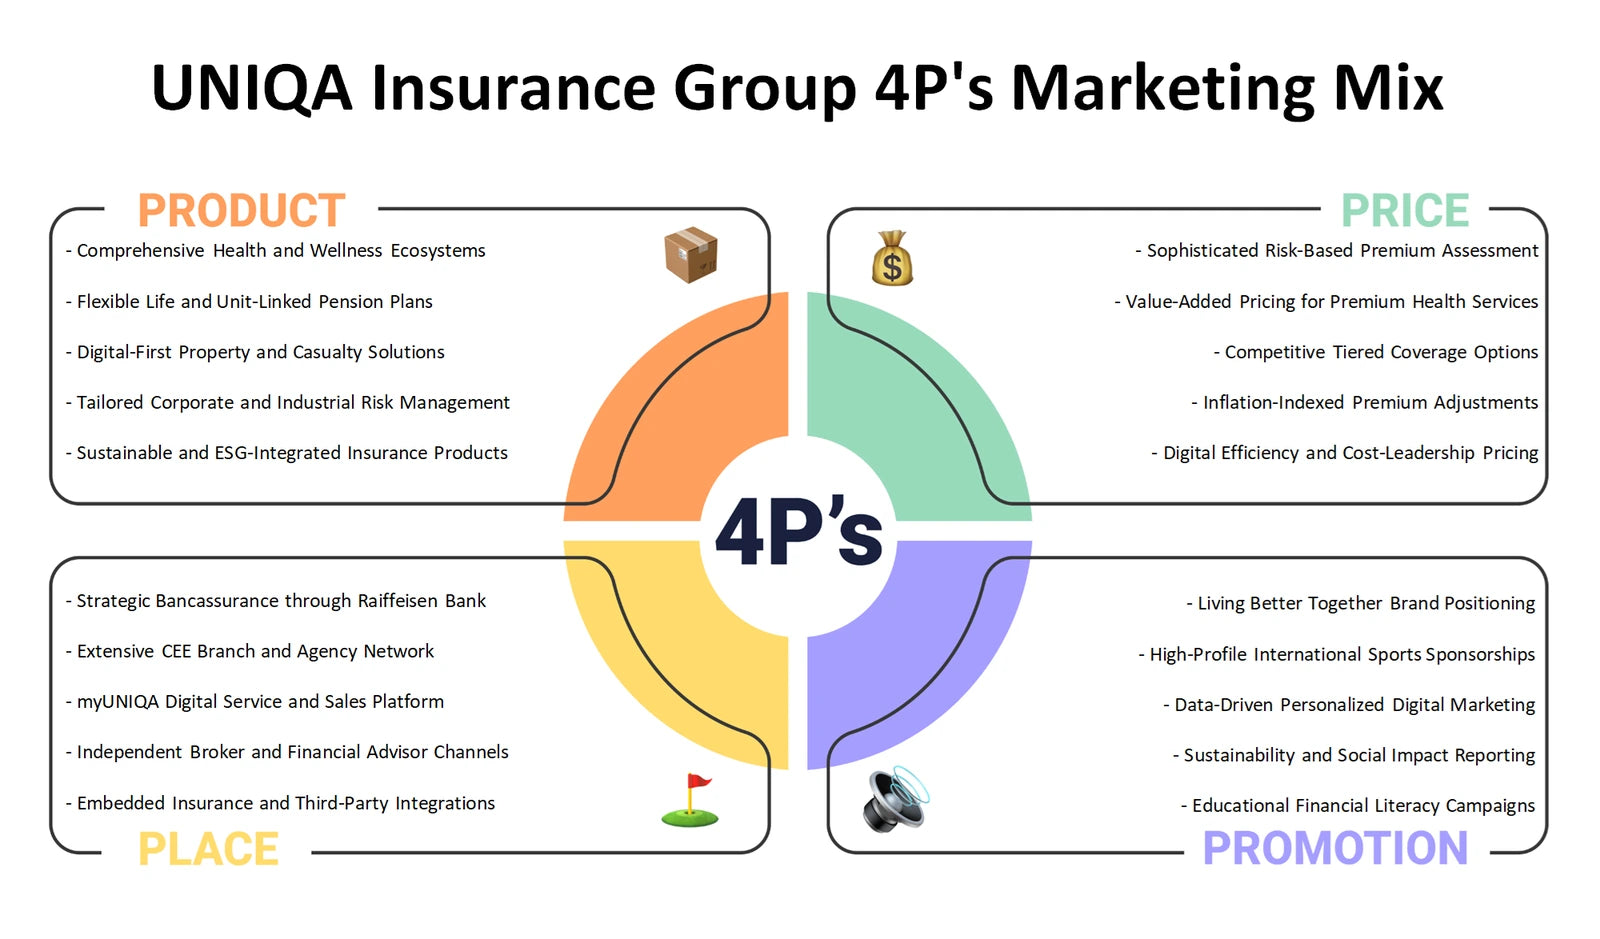
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could reshape insurance demand, risk exposure, compliance requirements and operating costs?
A UNIQA Insurance Group PESTLE analysis, also commonly called PESTEL, examines the external conditions around an Austrian insurance business. Political factors can include public-policy priorities and supervisory direction. Economic conditions may affect household budgets, business activity, investment conditions and claims inflation. Social change can alter protection needs, demographic patterns and expectations for accessible service. Technological developments raise questions about digital customer journeys, data use, cyber resilience and insurtech collaboration. Legal factors cover the rules governing insurance products, conduct, privacy and solvency. Environmental conditions matter because physical risks, transition risks and sustainability expectations can influence underwriting, claims and investment decisions. These are categories for analysis, not claims that a particular change has occurred.
- External radar. Separate broad macro forces from firm-specific actions so management questions are not confused with documented developments.
- Insurance relevance. Link each factor to possible effects on demand, risk selection, claims frequency, compliance workload or operational resilience.
- Scenario record. Use the Excel framework to rank external topics for review and use the Word analysis to capture assumptions, uncertainties and response questions.
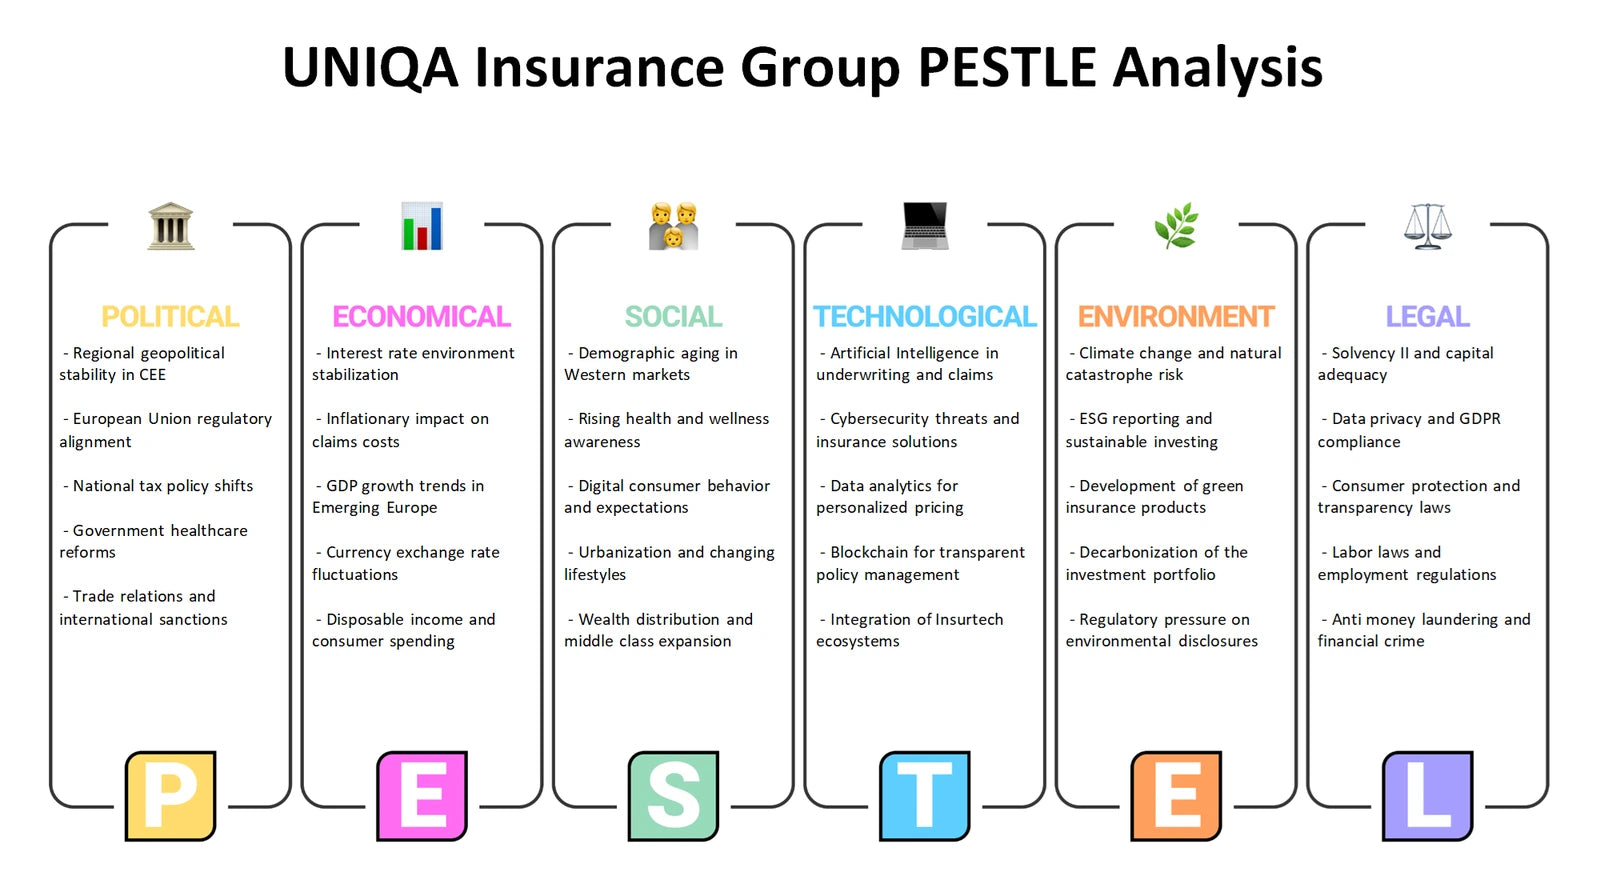
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can UNIQA Insurance Group distinguish its internal capabilities and constraints from the external opportunities and threats it faces?
A UNIQA Insurance Group SWOT analysis provides a concise bridge between the internal business model and the external environment. Strengths and weaknesses are internal: they may include capabilities, resources, operational processes, distribution relationships or areas requiring improvement, subject to evidence. Opportunities and threats are external: they may arise from changing customer needs, technology, regulation, economic conditions or evolving risk patterns. The distinction matters because a market opportunity is not automatically a company strength, and an internal gap is not the same as an external threat. Used after the other five frameworks, SWOT can help organise insights into issues that deserve management attention without presenting plausible themes as established company findings.
- Clear classification. Test whether each observation belongs inside the organisation as a strength or weakness, or outside it as an opportunity or threat.
- Strategic matching. Explore how supported capabilities may be applied to external openings and where internal constraints could increase exposure to outside pressure.
- Decision synthesis. Use the Excel matrix to prioritise evidence-backed items and use the Word analysis to explain the strategic links behind the resulting discussion.
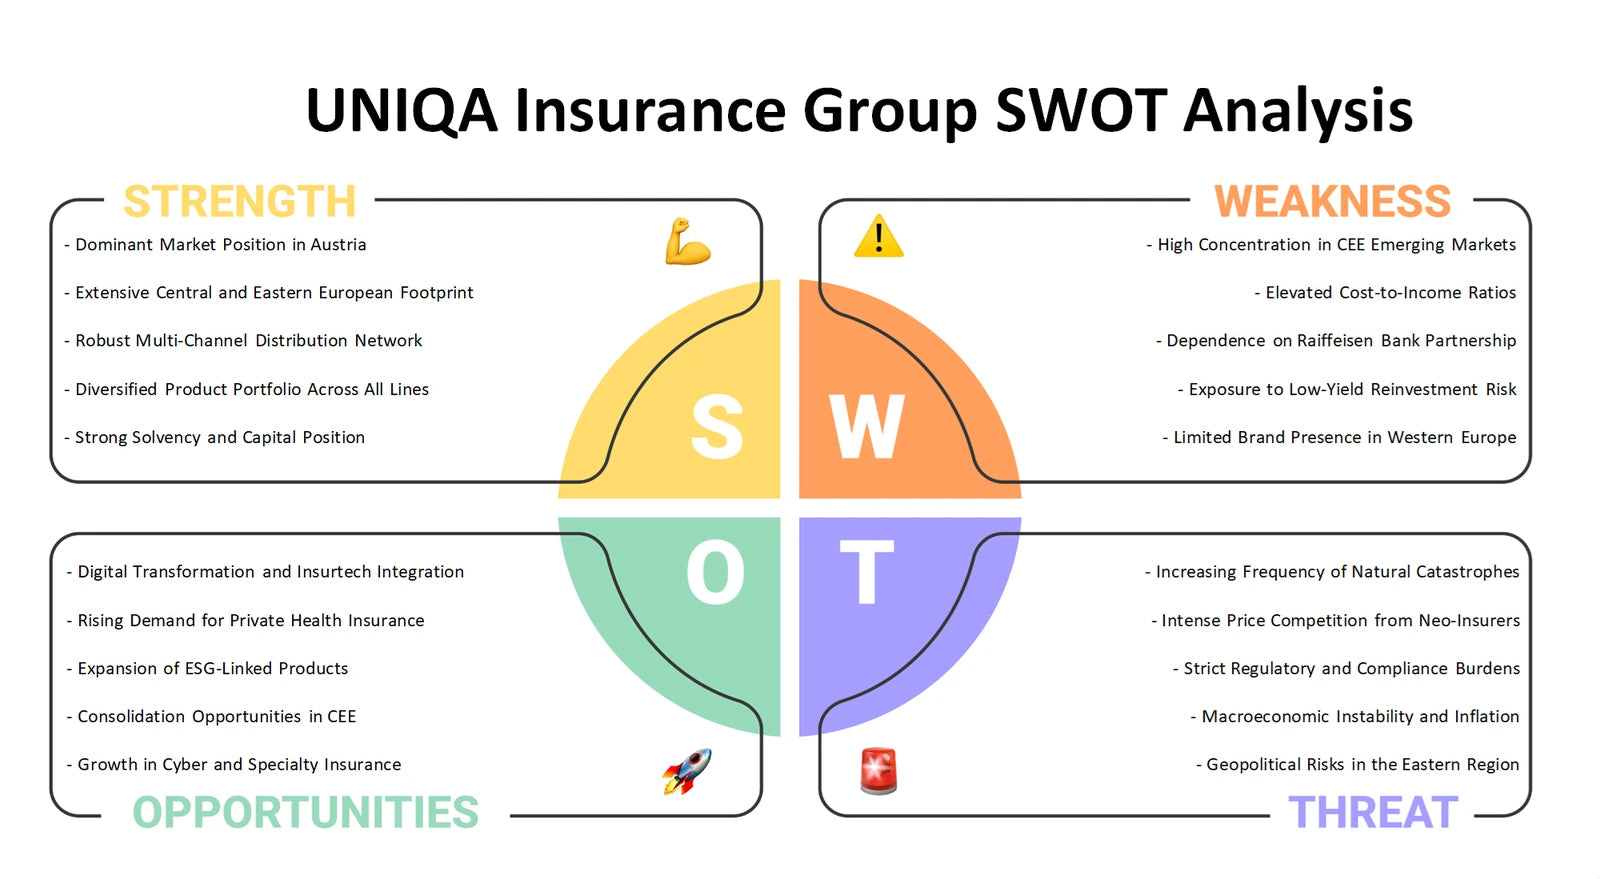
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of UNIQA Insurance Group
The six perspectives work best together: the Canvas examines how insurance value is created, Five Forces and PESTLE frame outside pressures, the 4Ps considers customer access, BCG supports portfolio discussion, and SWOT brings the resulting questions together. Using the Excel frameworks alongside the detailed Word analysis, customers can develop a more organised basis for examining UNIQA Insurance Group's strategic choices.
Company background: UNIQA Insurance Group — corporate home page.