

UniCredit: Customer Relationships and Value Creation – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
UniCredit Strategy Analysis Bundle
This bundle is framed around the UniCredit banking business described in the supplied product context, where financial services are extended through bancassurance relationships and other financial partnerships. It is relevant to a bank serving customers who need everyday banking, financing, savings, protection and related financial solutions, while balancing customer trust, distribution reach, risk management and return on capital.
The supplied context also points to insurance alliances, strategic holdings in financial businesses and collaboration with Italy's Fondo Ambiente Italiano (FAI). These are useful starting points for asking how UniCredit should prioritise a varied portfolio, connect partnerships to customer value, and respond to changing competitive and regulatory pressures. The Excel frameworks and detailed Word analysis help organise those questions without treating a preview as the full analysis.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which UniCredit activities deserve investment, selective management, cash generation or reconsideration as markets and relative market share change?
A UniCredit BCG Matrix provides a disciplined way to compare banking, lending, savings, payment, insurance-distribution and investment-related activities through two analytical criteria: market growth and relative market share. The point is not to assume that a service belongs in a quadrant, but to test whether it behaves like a Star, Cash Cow, Question Mark or Dog under defined market boundaries. For a bank, that distinction matters because capital, technology spending, specialist expertise and compliance capacity cannot be allocated everywhere with equal intensity.
- Portfolio boundaries. Separate customer needs and product categories before comparing growth conditions with UniCredit's relative position in each relevant market.
- Resource trade-offs. Examine whether mature relationship-led services can support investment in faster-changing digital, protection or financing opportunities.
- Structured prioritisation. Use the Excel framework to map assumptions consistently, then use the Word analysis to interpret why a category may require investment, harvesting, testing or review.
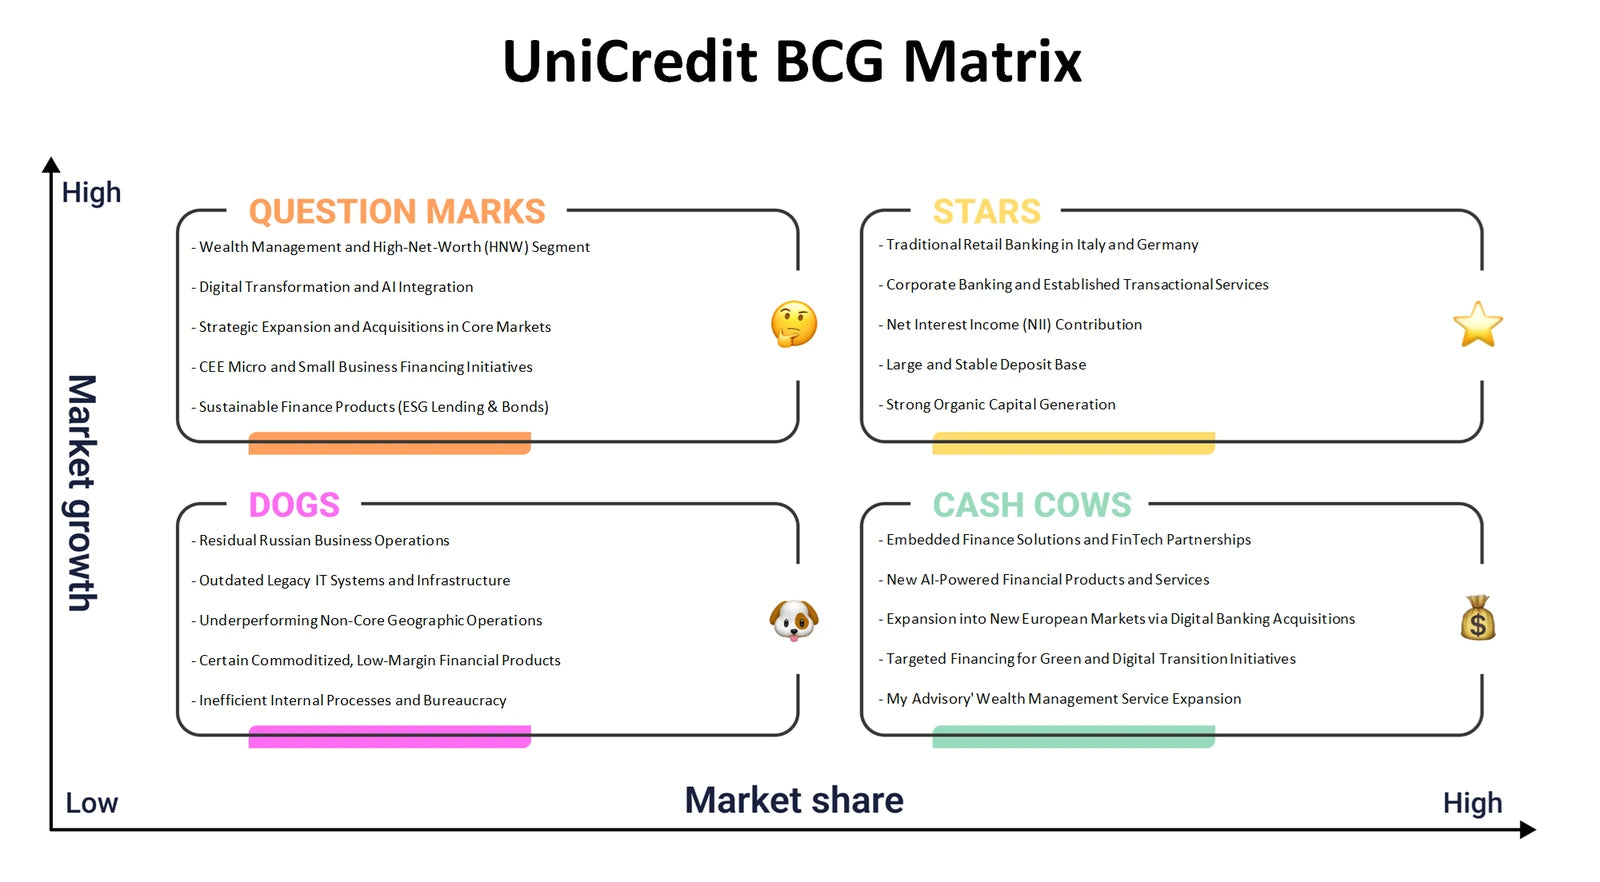
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do UniCredit's customer relationships, financial offerings and partnerships fit together to create value and generate income?
The UniCredit Business Model Canvas connects all nine building blocks rather than treating products in isolation: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. In this context, bancassurance can be examined as more than an additional offer: it may connect customer needs for protection with partner capabilities, advisory or distribution channels, fee-related revenue logic and operating responsibilities. Strategic financial holdings and community relationships can likewise be considered for their role, limits and economic rationale rather than assumed to create value automatically.
- Value-chain links. Trace how banking and insurance needs may move from customer segment to proposition, channel, relationship model and revenue stream.
- Partnership economics. Consider what external insurers, financial investees and other partners contribute alongside UniCredit's resources, activities and cost commitments.
- Connected model view. Complete the Excel Canvas block by block, then use the Word analysis to test whether the links between value creation, delivery and economics are coherent.
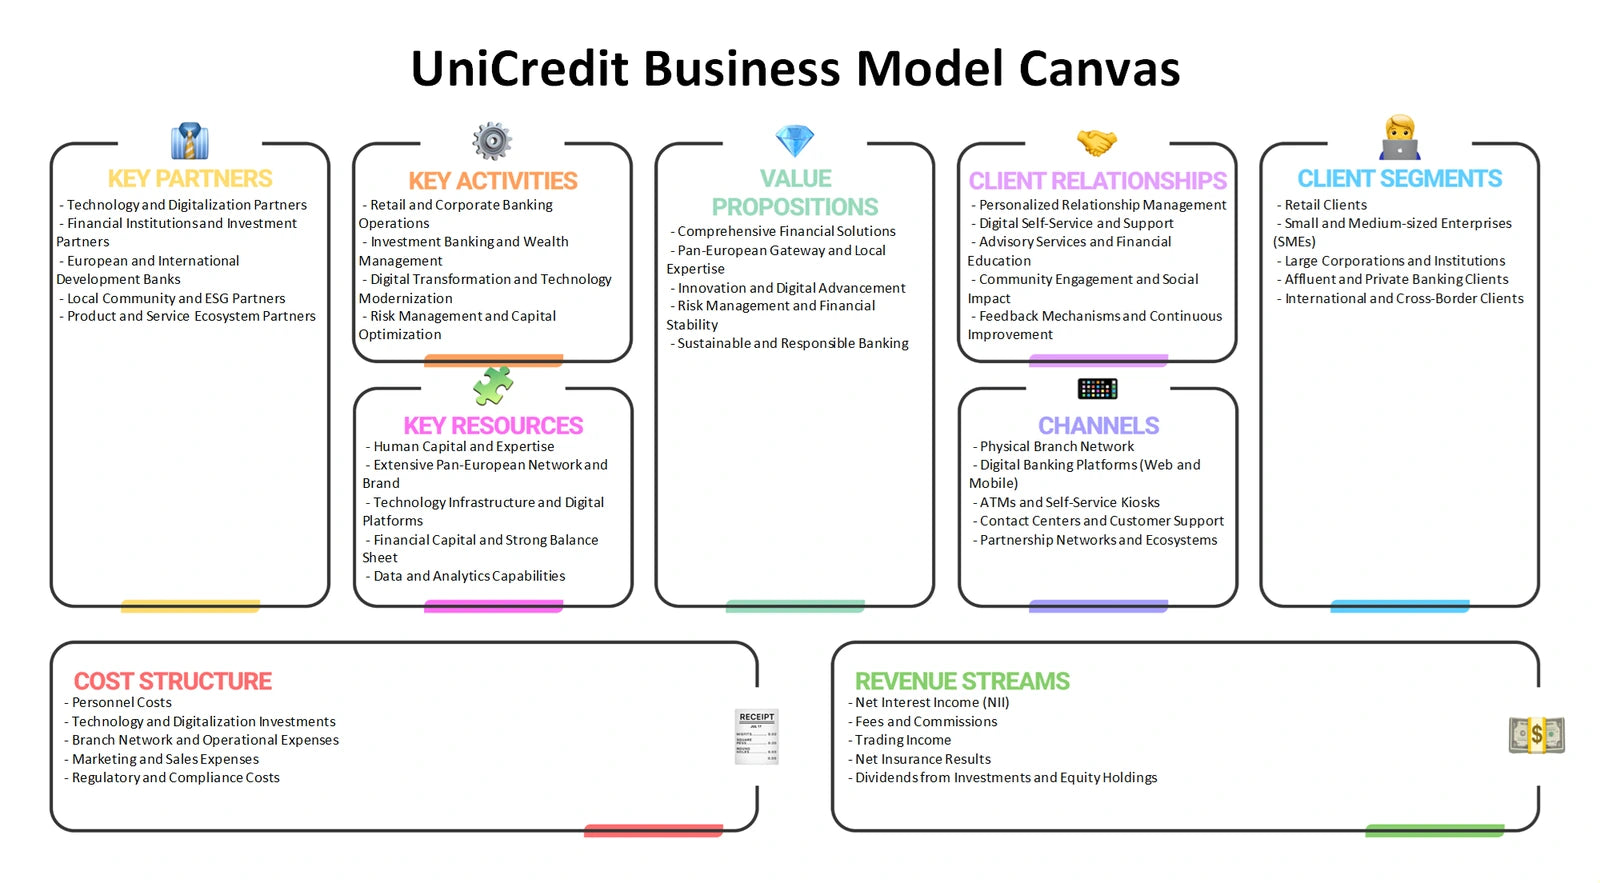
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could shape UniCredit's ability to sustain customer relationships, margins and strategic flexibility?
UniCredit Porter's Five Forces examines the competitive environment around banking and related financial services through rivalry, supplier power, buyer power, threat of new entrants and threat of substitutes. Rivalry can involve competition for deposits, lending relationships, investment flows and trusted advice. Supplier power may arise from technology providers, skilled specialists, funding sources or essential external partners. Buyer power reflects customers' ability to compare providers or switch. New entrants can emerge through regulated financial firms or technology-enabled models, while substitutes include non-bank ways of making payments, investing, obtaining credit or protecting against risk.
- Competitive pressure. Distinguish direct banking rivalry from the broader alternatives that can meet a customer's financial need differently.
- Dependency review. Assess where access to data, technology, talent, funding or partner capabilities could influence bargaining power and operating resilience.
- Evidence-led comparison. Use the Excel structure to record each force and its drivers, then consult the Word analysis for sector-specific interpretation and discussion prompts.
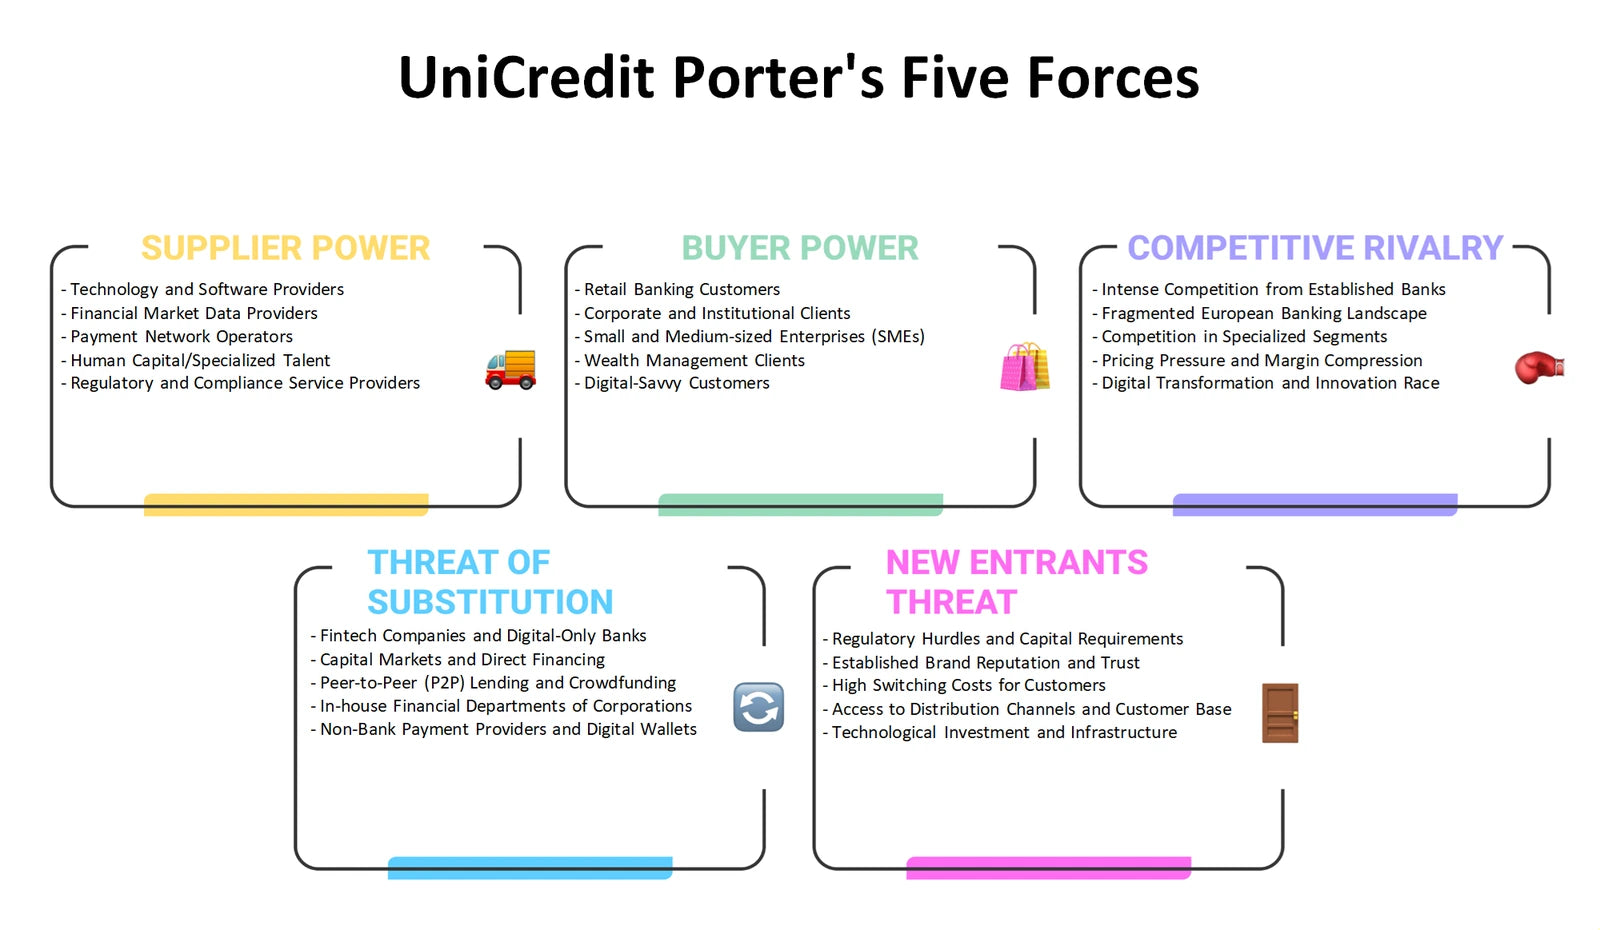
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can UniCredit align financial products, pricing logic, customer access and communications in a trust-sensitive regulated service market?
The UniCredit Marketing Mix applies Product, Price, Place and Promotion to a financial-services setting. Product analysis can compare core banking solutions with lending, savings, investment, payment and insurance-related needs. Price is broader than a posted fee: it can include rates, commissions, bundled value, transparency and the customer perception of fairness. Place considers branches, relationship managers, digital journeys and partner-enabled distribution where relevant. Promotion must communicate useful value clearly while respecting the sensitivity of financial decisions, the need for informed customer choice and the importance of confidence in the institution.
- Offer design. Explore whether propositions address distinct needs such as liquidity, financing, wealth planning or protection without obscuring complexity.
- Channel consistency. Compare how human advice, digital access and partnership distribution could create a consistent customer experience across touchpoints.
- Mix planning. Use the Excel framework to organise Product, Price, Place and Promotion questions, with the Word analysis adding context for interpreting service-market trade-offs.
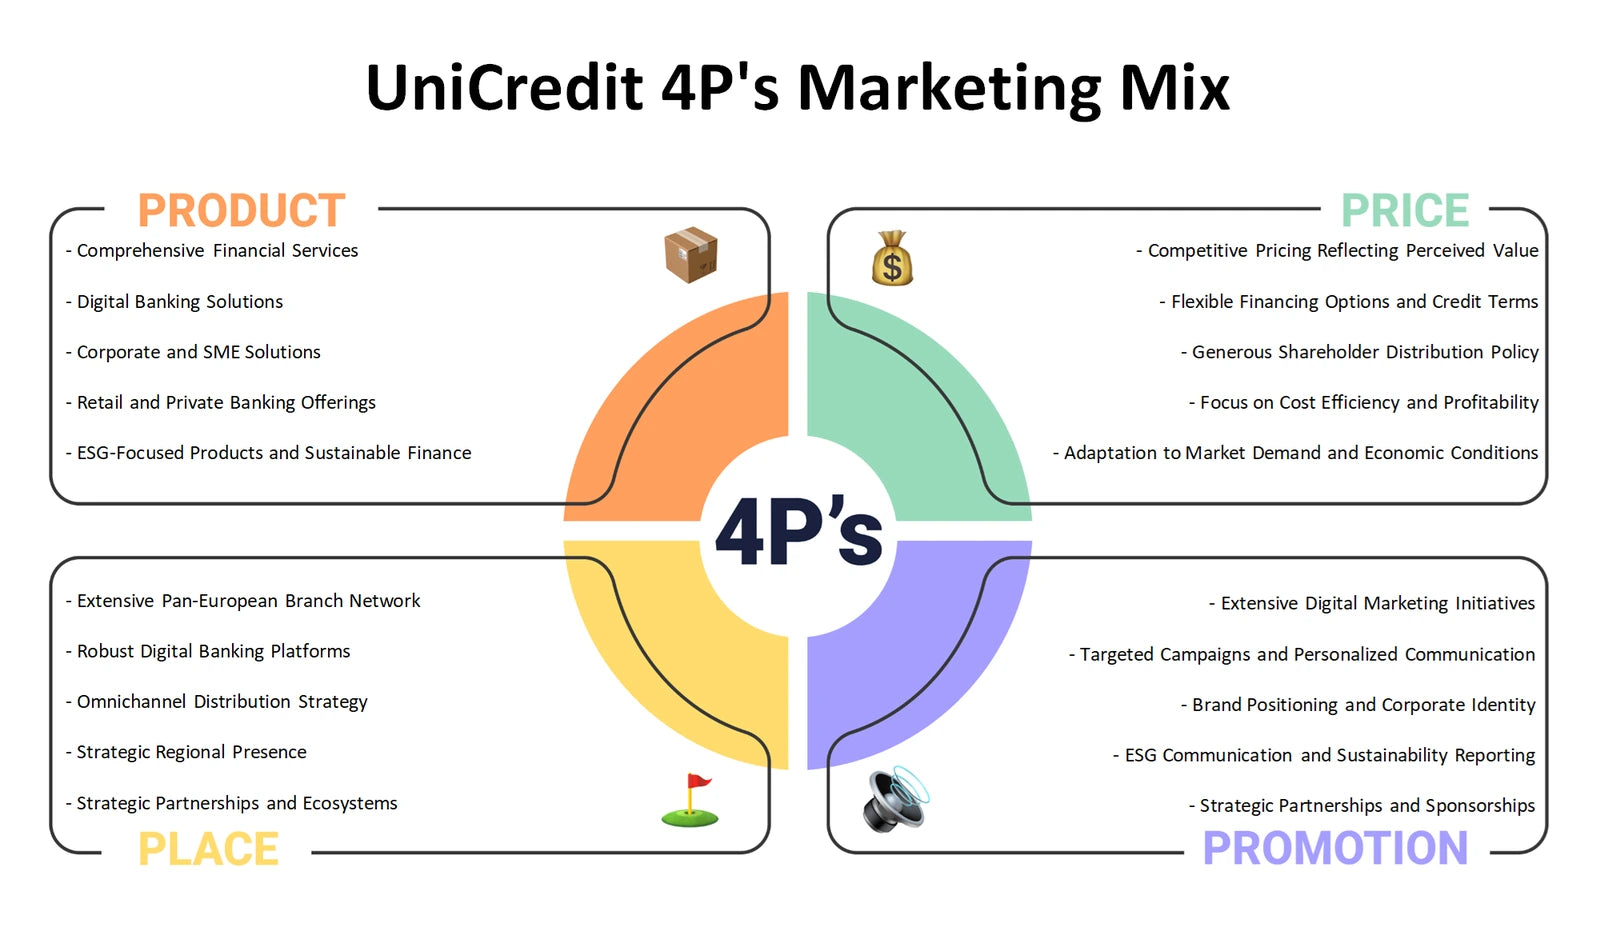
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should UniCredit monitor when planning services, partnerships, technology investment and risk management?
A UniCredit PESTLE analysis, also commonly called PESTEL, separates external influences into Political, Economic, Social, Technological, Legal and Environmental dimensions. Political and legal questions can include the direction of banking policy, supervision, consumer protection and data requirements. Economic conditions may affect borrowing demand, savings behaviour, credit quality and funding choices. Social change can alter expectations for convenient and understandable financial support. Technology raises questions around digital security, data use and delivery models, while environmental factors can influence financing needs, risk assessment and stakeholder expectations. These are analytical categories, not claims that a particular rule or market change has occurred.
- External scanning. Separate macroeconomic uncertainty from policy, social, technological and environmental developments so that different signals are not blended together.
- Banking relevance. Link each external factor to a possible effect on customers, product demand, operations, risk controls or partner relationships.
- Scenario discipline. Populate the Excel PESTLE grid with sourced observations and questions, then use the detailed Word analysis to develop implications worth monitoring.
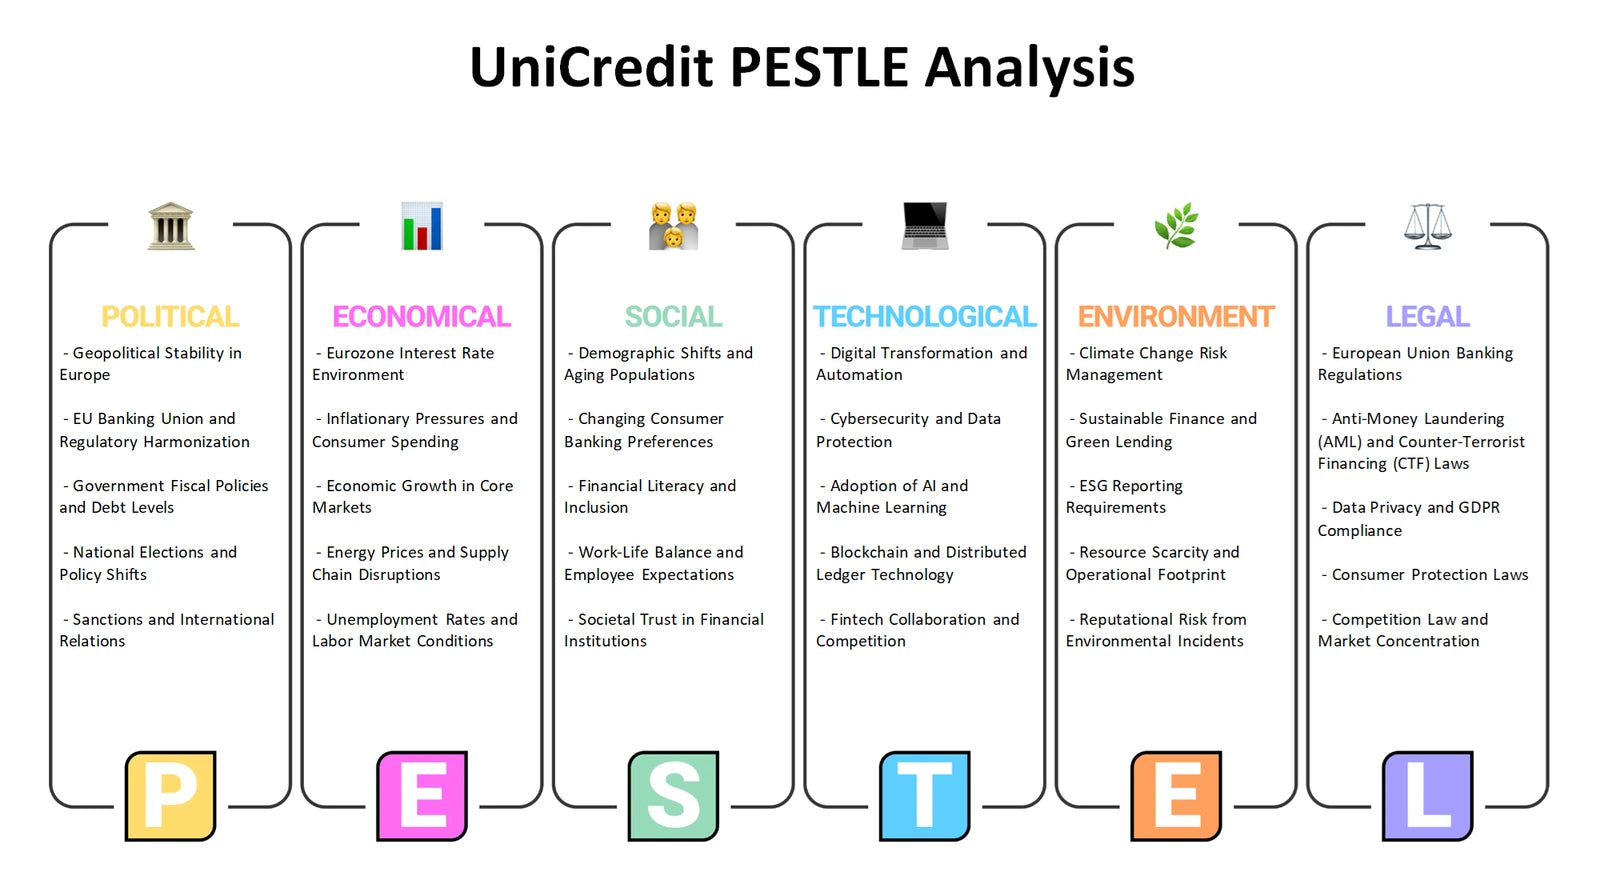
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can UniCredit distinguish its internal capabilities and constraints from the outside opportunities and threats it must navigate?
The UniCredit SWOT analysis keeps internal and external questions properly separate. Strengths and Weaknesses concern capabilities, resources, processes, relationships and limitations that belong within the business. Opportunities and Threats arise outside it, such as changing customer demand, technology shifts, economic conditions, regulation or competitive alternatives. The supplied context around bancassurance, financial partnerships and broader stakeholder relationships offers relevant themes to examine, but it should not be converted into automatic conclusions. SWOT is most useful when each item is supported, classified accurately and linked to a realistic strategic question rather than listed as a generic positive or risk.
- Internal diagnosis. Consider how distribution, customer trust, partnership-management capability and operating complexity could be assessed as strengths or weaknesses.
- External choices. Explore where evolving customer needs, financial-market conditions, regulation and substitutes may create opportunities or threats.
- Actionable synthesis. Use the Excel matrix to separate and prioritise observations, then use the Word analysis to connect potential strengths and opportunities with possible weaknesses and threats.
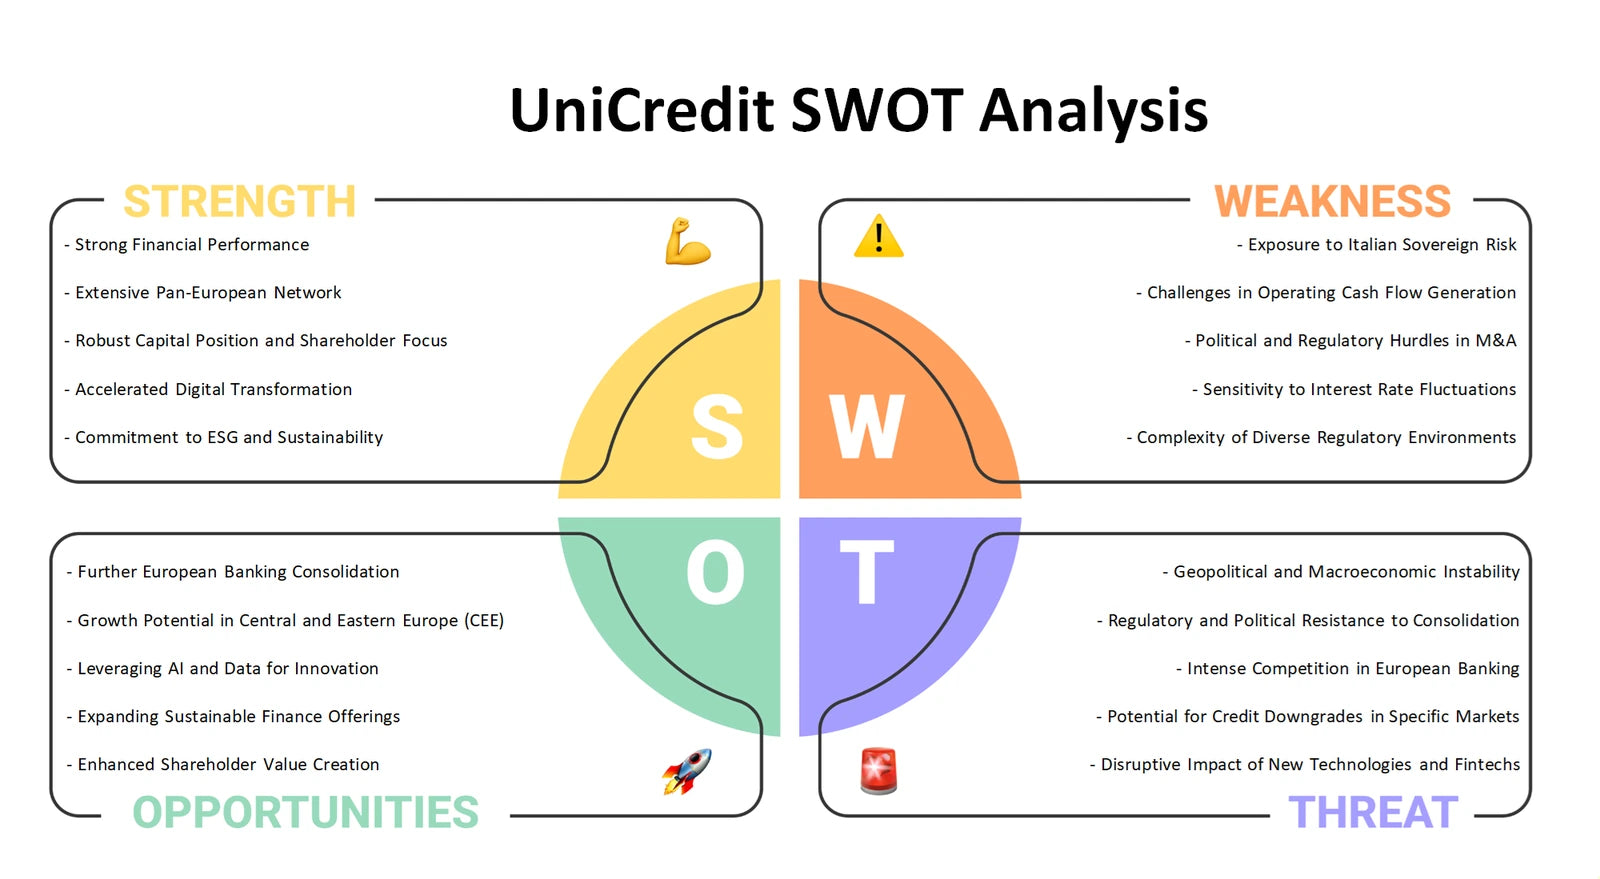
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of UniCredit's strategic choices
Together, the six perspectives move from portfolio priorities and value creation to industry pressure, customer-market choices, external change and strategic position. The Excel files provide structured places to compare questions and organise evidence, while the Word files provide detailed company analysis to support more informed discussion of UniCredit's banking, partnership and customer-value themes.
Company background: UniCredit — supplied product-context page.