

United Fire Group: Six Analyses of Underwriting and Production Capacity

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
United Fire Group Strategy Analysis Bundle
This bundle examines United Fire Group, the insurance business associated with the SEC reporting issuer UNITED FIRE GROUP INC. The supplied product context centres on specialty commercial and personal insurance, including tailored coverage considerations for manufacturing, hospitality, healthcare and agribusiness customers whose operating exposures may not fit standard policy forms.
For the period from April 1 to June 30, 2026, the company reported revenue of US$383.726 million and GAAP net income of US$33.365 million in its August 4, 2026 Form 10-Q filing. This is a dated company-context snapshot, not evidence that the downloadable files were updated in 2026. It frames useful questions about portfolio focus, underwriting economics and exposure to competitive and external pressures.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance lines, customer niches or coverage propositions deserve the greatest share of underwriting capacity and management attention?
The United Fire Group BCG Matrix helps organize a portfolio discussion using market growth and relative market share rather than assuming every product line warrants the same investment. It can compare specialty commercial opportunities with personal insurance activity, tailored forms and sector-oriented propositions. Stars, Cash Cows, Question Marks and Dogs are analytical categories for prioritisation; they are not pre-assigned outcomes or claims about United Fire Group market share.
- Portfolio logic. Compare growth potential against relative competitive position before directing capital, distribution effort or product-development resources.
- Insurance trade-offs. Test whether a niche's premium opportunity is matched by sustainable underwriting quality, reinsurance needs and claims volatility.
- Working view. Use the Excel matrix to map candidate business areas, then use the Word analysis to document the assumptions and strategic questions behind each position.
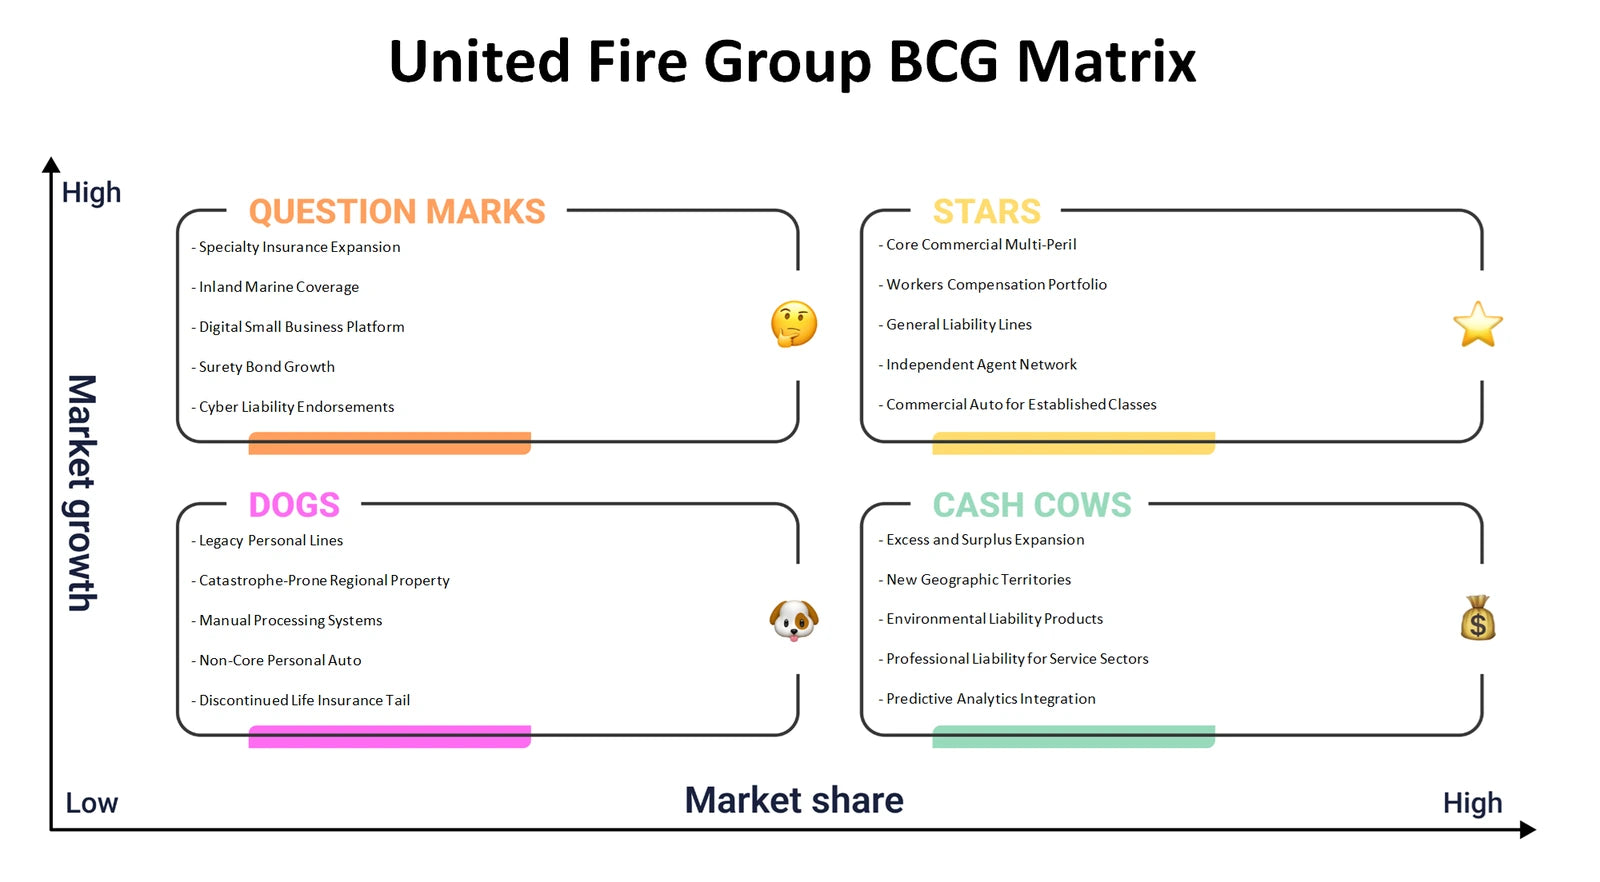
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do tailored insurance offerings connect customer needs, underwriting operations, distribution and financial returns?
The United Fire Group Business Model Canvas links all nine building blocks in one operating picture: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For an insurer serving varied commercial exposures, the useful question is how customized policy terms, risk selection, service and claims obligations fit together while premium revenue must cover losses, expenses, reinsurance and capital requirements.
- Customer fit. Examine how manufacturing, hospitality, healthcare and agribusiness needs may shape propositions, service expectations and distribution choices.
- Economic chain. Connect premiums and other revenue streams to underwriting, reserving, claims handling, risk control, technology and partnership demands.
- Model connection. Populate the Excel canvas as a concise map, then consult the detailed Word analysis when explaining relationships and tensions between the blocks.
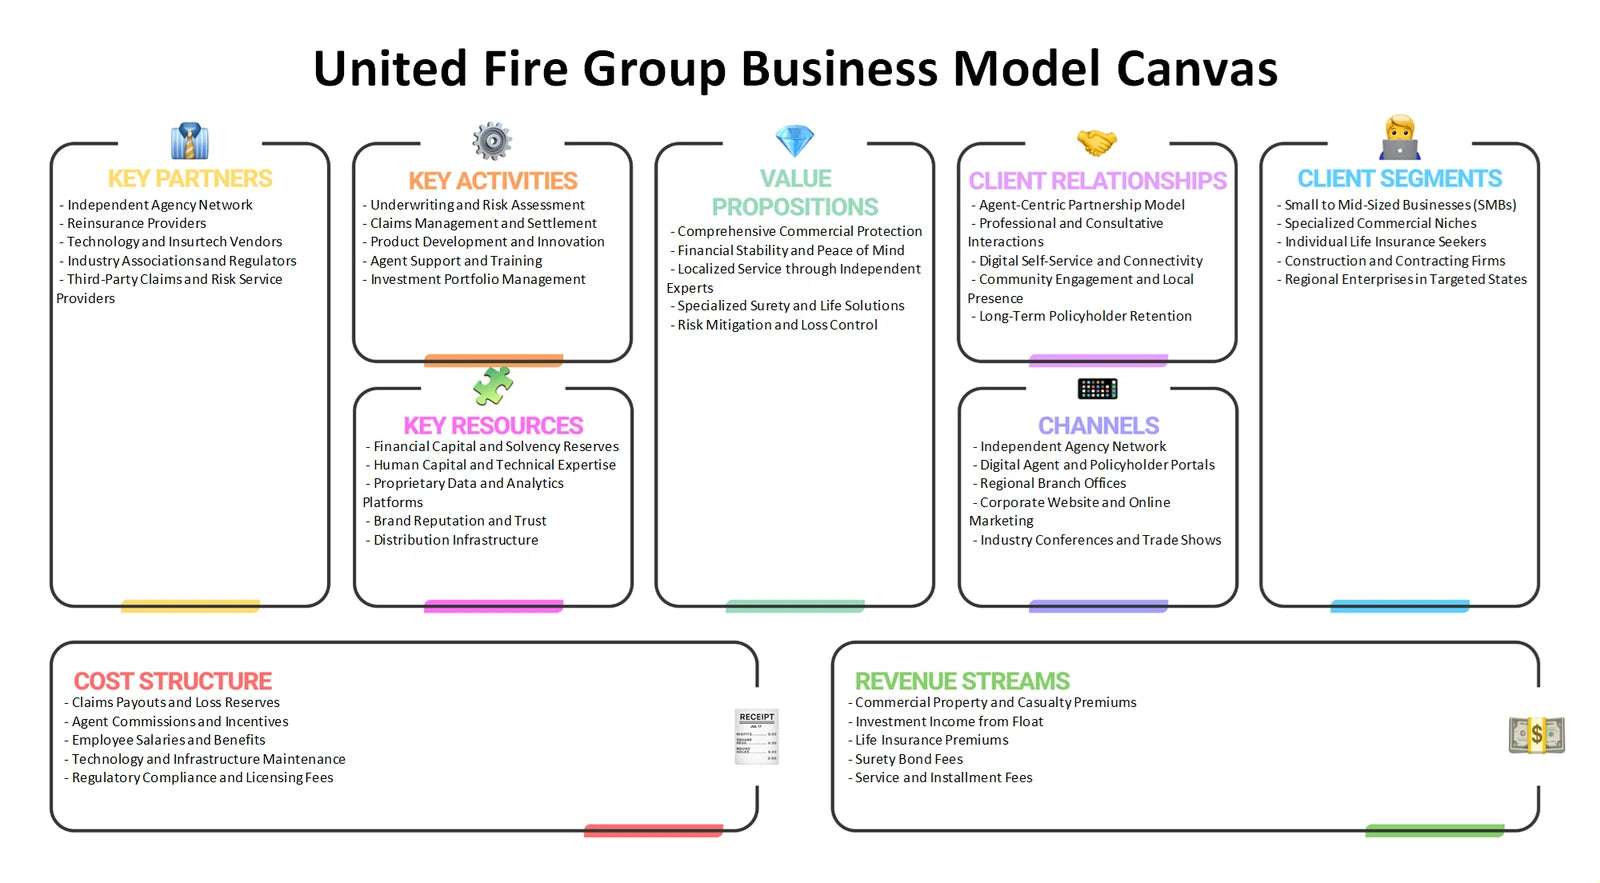
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can influence pricing discipline, customer retention and the attractiveness of specialty insurance segments?
United Fire Group Porter's Five Forces examines rivalry among insurers, the bargaining power of buyers, supplier power, the threat of new entrants and the threat of substitutes. In property and casualty insurance, suppliers can include reinsurance capacity and specialist service inputs, while substitutes may include risk retention, captives, self-insurance or operational loss prevention rather than only another carrier. The framework helps separate pressure on a market from a conclusion about any individual competitor.
- Rivalry and buyers. Assess how comparable coverage, renewal choices, procurement processes and service expectations can affect policy terms and retention.
- Capacity dependence. Explore how reinsurance availability, claims expertise and regulatory barriers shape entry conditions and industry bargaining dynamics.
- Pressure map. Use the Excel framework to compare each force by segment, with the Word analysis supplying the rationale and insurance-specific interpretation.
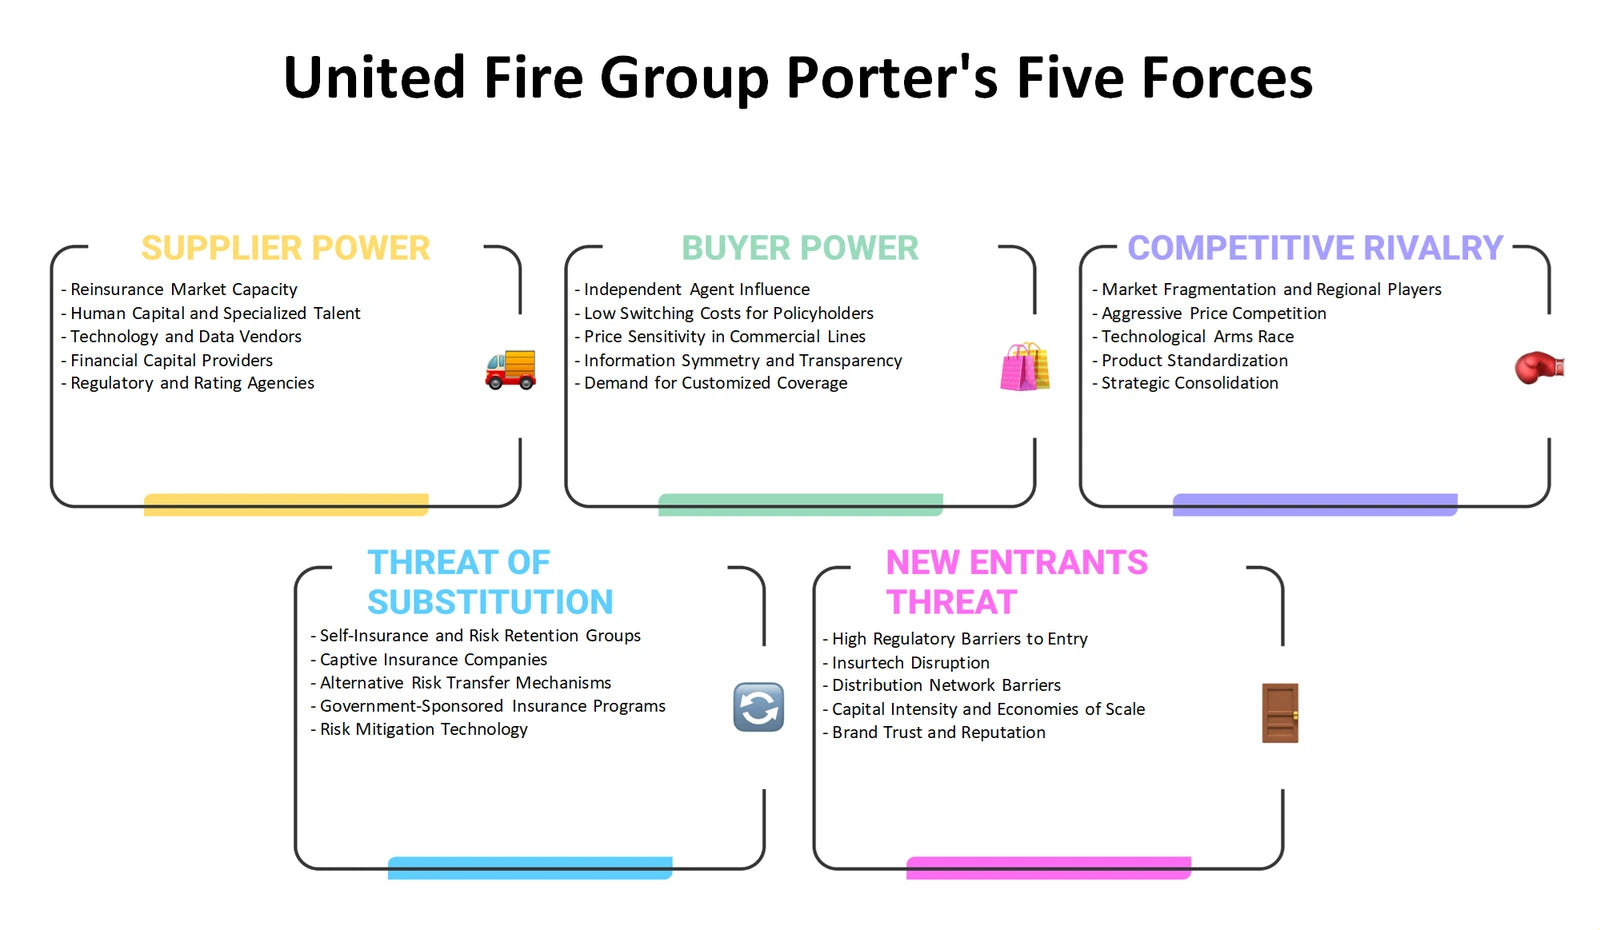
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can coverage design, premium logic, distribution access and communication reinforce a credible insurance proposition?
The United Fire Group Marketing Mix examines Product, Price, Place and Promotion in a regulated insurance setting. Product can include coverage forms, endorsements, limits and loss-control support; Price concerns premiums, deductibles, terms and the risk characteristics behind them. Place considers routes through appropriate distribution relationships, while Promotion addresses how a specialist proposition is communicated without overstating protection. Together, the 4Ps help test whether a tailored offer is understandable and reachable for its intended customers.
- Product clarity. Compare how specialized forms and endorsements may address operational exposures that standard policies can leave insufficiently addressed.
- Pricing discipline. Consider how risk selection, expected loss costs, catastrophe exposure and policy structure inform pricing questions without inventing rates.
- Go-to-market review. Use the Excel 4Ps layout to organise options, then use the Word analysis to assess the customer and channel implications behind them.
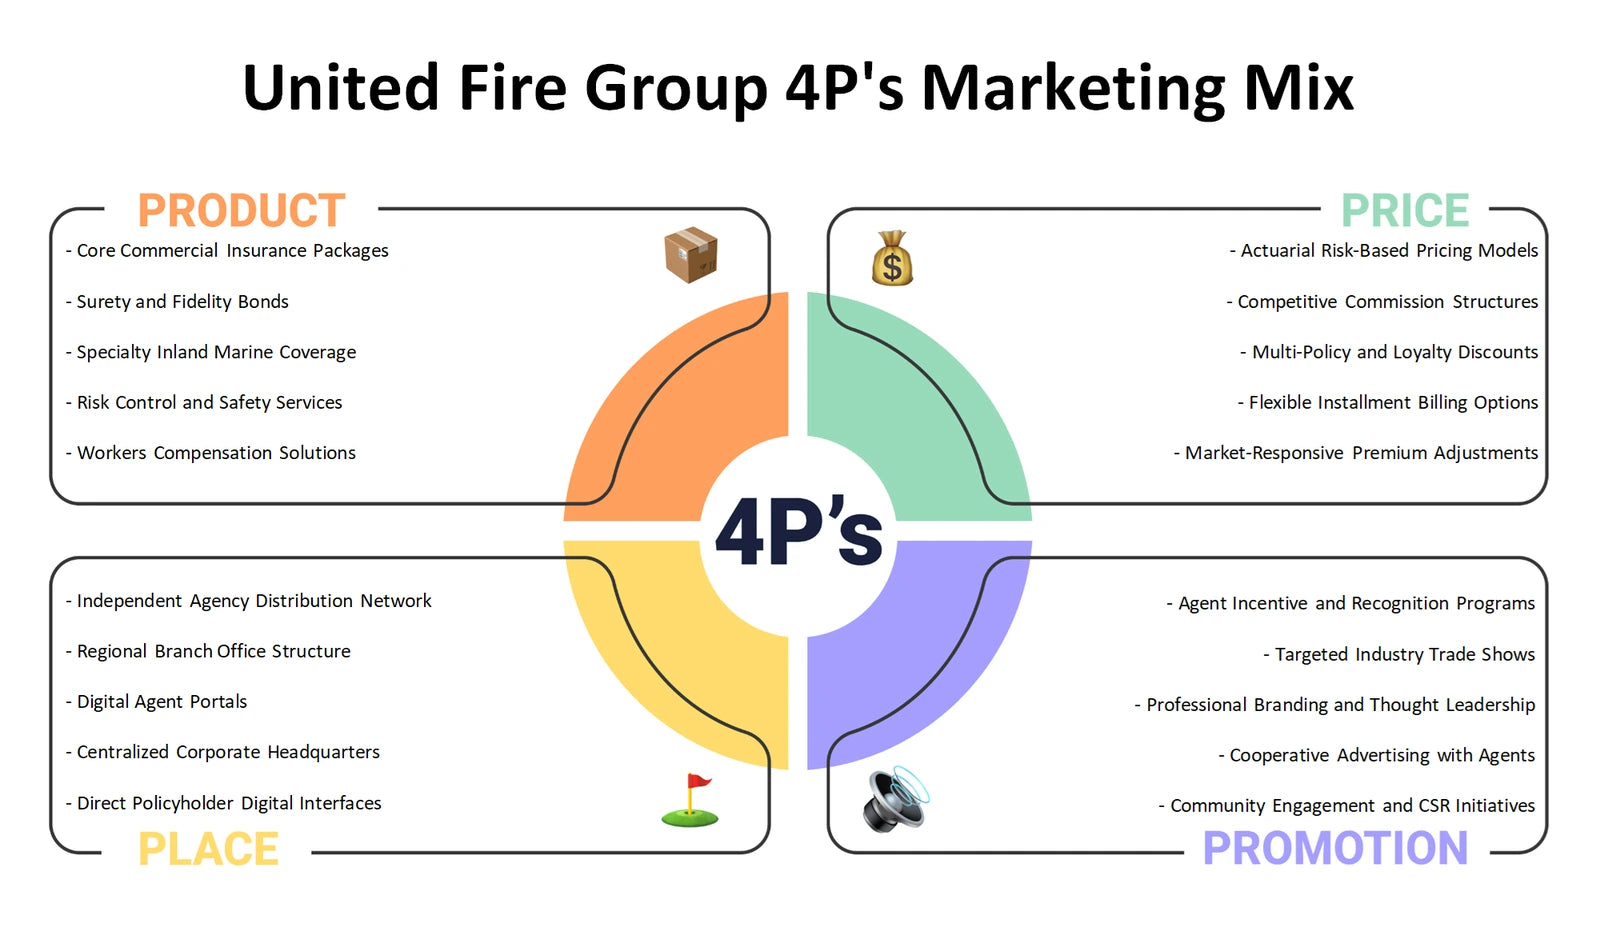
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter claims costs, regulation, customer risk needs or the economics of insurance coverage?
The United Fire Group PESTLE analysis, also commonly called PESTEL, separates Political, Economic, Social, Technological, Legal and Environmental influences. It can help examine insurance-policy and regulatory questions, inflation in repair or medical costs, changing expectations around risk protection, claims and underwriting technology, legal disputes over coverage, and weather-related loss exposure. These are areas for structured external scanning, not assertions that a particular law, rate or event has already changed the company.
- External cost drivers. Track questions around loss severity, catastrophe volatility, reserving uncertainty and the capital consequences of changing conditions.
- Customer change. Explore how sector-specific operations and emerging risks may reshape coverage needs across commercial and personal insurance.
- Scanning discipline. Use the Excel grid to sort developments by factor, while the Word analysis helps connect each external issue to possible strategic relevance.
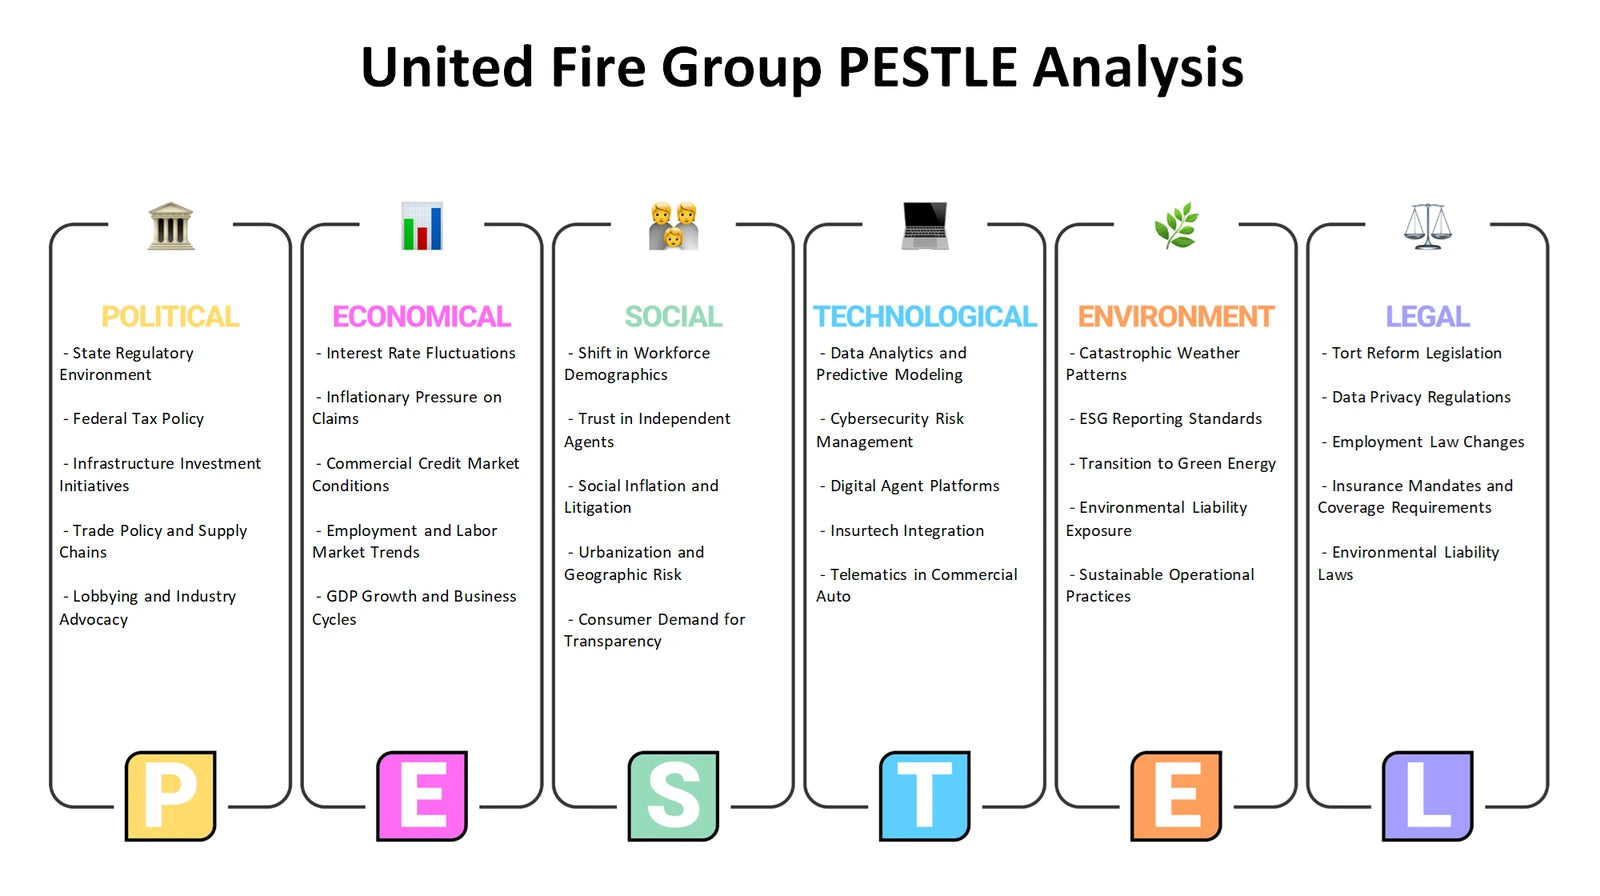
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal underwriting capabilities and constraints be considered alongside changing insurance opportunities and threats?
The United Fire Group SWOT analysis separates internal Strengths and Weaknesses from external Opportunities and Threats. Possible strengths to examine include specialized coverage knowledge and the ability to address unusual operational exposures; possible internal constraints include claims, reserving, expense or concentration challenges that require careful validation. Opportunities and threats belong outside the company, such as changing customer demand, competitive capacity, catastrophe conditions and regulatory developments. Keeping those classifications distinct makes the discussion more decision-useful.
- Internal reality check. Identify capabilities and limitations that may affect underwriting consistency, customer service and the ability to support specialized risks.
- External exposure. Compare market openings with threats from loss volatility, substitute risk-financing choices and changes in the insurance environment.
- Actionable synthesis. Use the Excel SWOT structure to capture evidence and questions, then use the Word analysis to develop balanced implications without treating themes as proven findings.
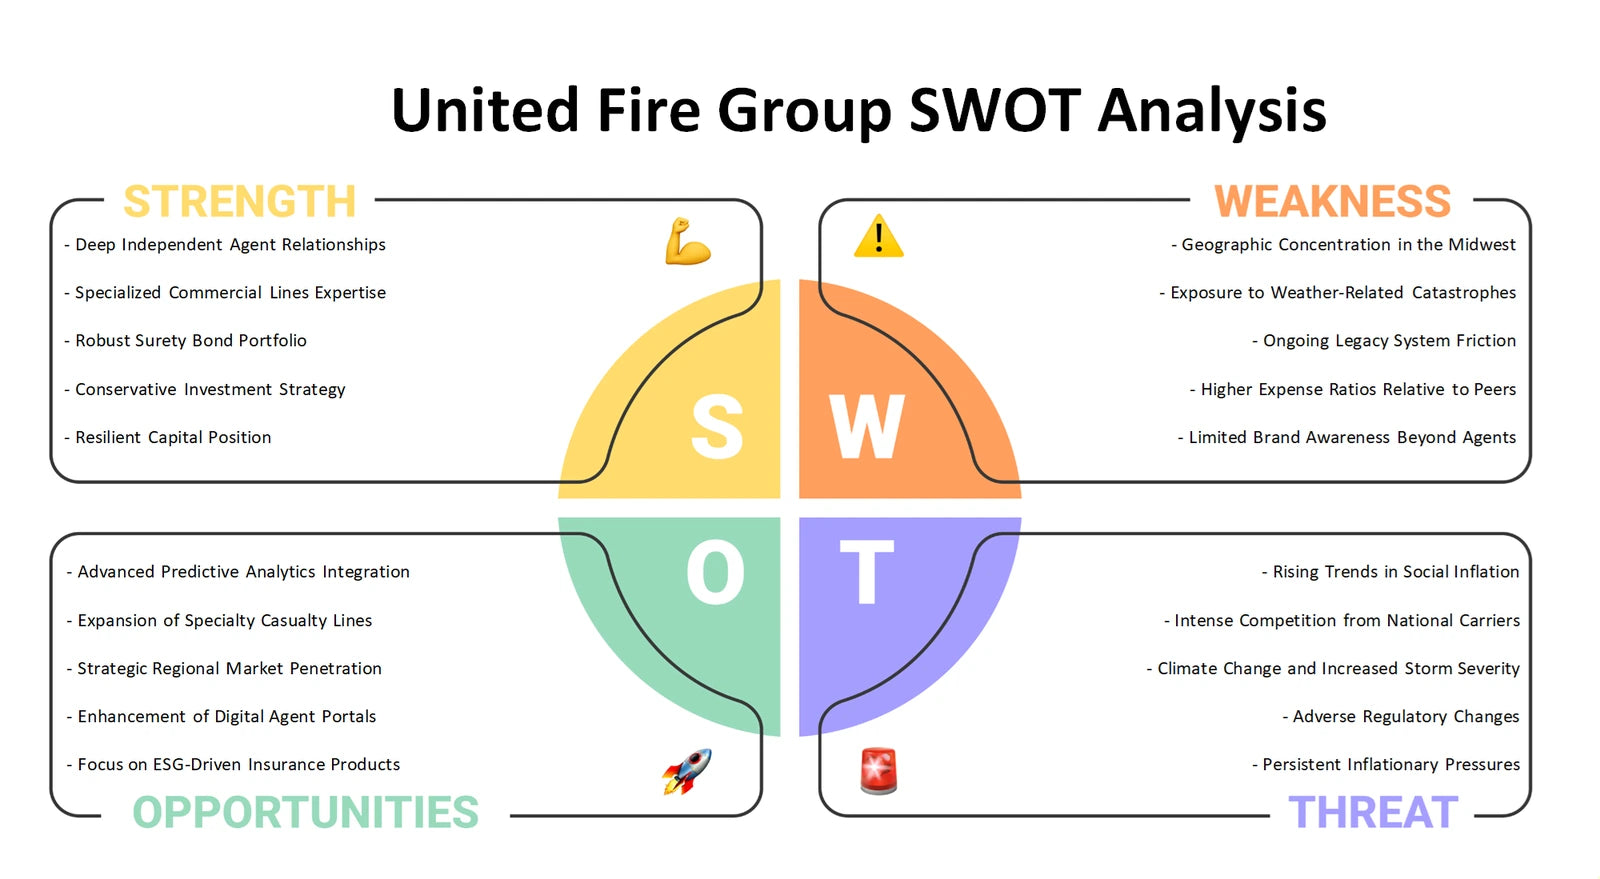
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
One connected view of insurance strategy
Used together, the six perspectives connect portfolio choices with business-model economics, industry bargaining pressures, customer-facing decisions, external change and internal strategic position. The Excel frameworks provide structured places to compare issues, while the detailed Word files help develop a company-specific narrative around underwriting, claims exposure, tailored coverage and longer-term priorities.
Company background: United Fire Group — SEC EDGAR filing: Form 10-Q filed August 4, 2026.