

United Bank for Africa: Banking Business and Lending Economics – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
United Bank for Africa Strategy Analysis Bundle
United Bank for Africa is used here only for the intended banking business described by the supplied product context: a deposit-taking operation serving individuals, businesses and public-sector customers, with funds used in lending. That context also identifies card-payment alliances with Visa and Mastercard as relevant to retail and corporate banking. The exact legal entity and market are not established by that source, so no subsidiary-specific geography, financial figures or regulatory claims are attributed here.
The useful strategic issue is therefore not a claimed verdict about a particular same-name bank, but a structured examination of this banking model: which services merit resources, how deposits and lending connect to customer value, and how payments, regulation and digital alternatives shape choices. The six linked perspectives help turn those questions into a traceable working analysis.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking services should receive resources when growth potential and relative market share differ?
A United Bank for Africa BCG Matrix helps separate the portfolio question from a general discussion of banking growth. Deposit products, lending propositions, card services and corporate banking offerings may face different market-growth conditions and different relative market-share positions. The framework tests those two criteria before considering the familiar Stars, Cash Cows, Question Marks and Dogs categories. It does not assume that any service belongs in a quadrant. Instead, it gives a disciplined way to compare whether a service may justify investment, protection, selective testing or tighter resource control, while recognising that capital, risk appetite and service obligations matter in banking.
- Portfolio logic. Compare retail, business, public-sector and payments-related offers as distinct uses of management attention and operating capacity.
- Relative position. Distinguish market growth from relative market share so a fast-moving service is not automatically treated as strategically strong.
- Working view. Use the Excel framework to record assumptions and comparisons, then use the Word analysis to explain the business rationale behind each possible priority.
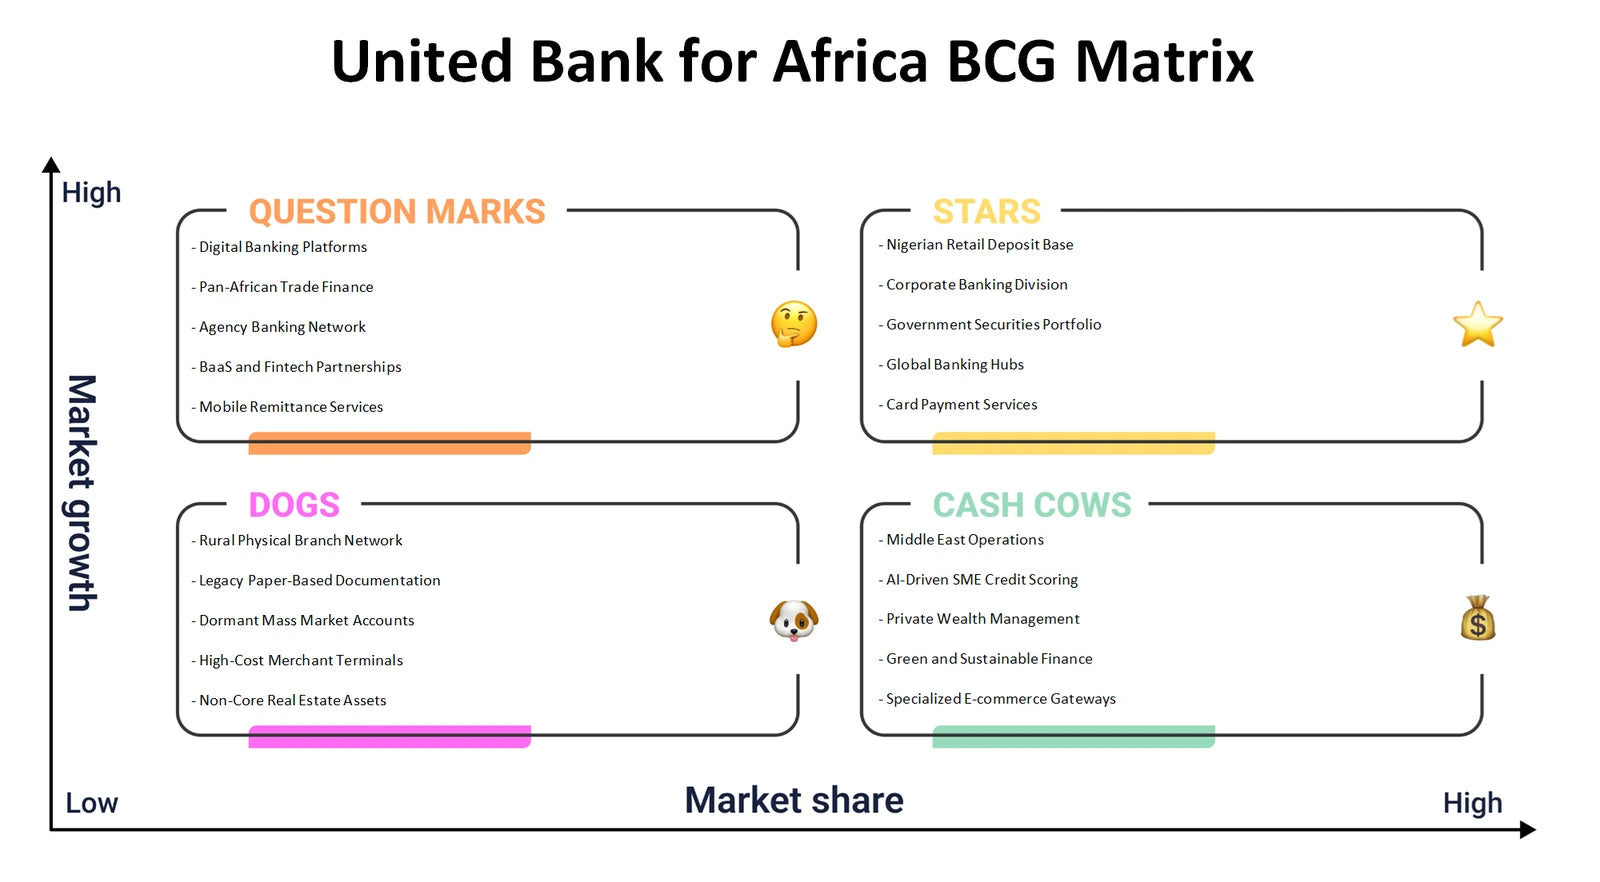
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do deposits, lending and payment services connect into a coherent banking value-creation system?
The United Bank for Africa Business Model Canvas examines the links between customer segments, value propositions, channels and customer relationships rather than treating each product in isolation. For the intended banking context, individuals, businesses and public-sector customers can have different needs for safeguarding funds, credit, transaction access and support. Revenue streams may be assessed alongside key resources such as funding, technology, trust and risk capability; key activities such as deposit-taking, lending and payment processing; and key partnerships, including payment networks. The canvas also makes cost structure visible, helping the user consider the operational and compliance effort required to serve each proposition.
- Nine connected blocks. Map all nine building blocks to show how customers, delivery, economics, resources, activities, partnerships and costs reinforce or strain one another.
- Payment relevance. Assess how card-network relationships can support transaction access while also creating partnership, technology and service-dependence questions.
- Model mapping. Populate the Excel canvas systematically, then use the Word analysis to interpret important links, gaps and trade-offs across the model.
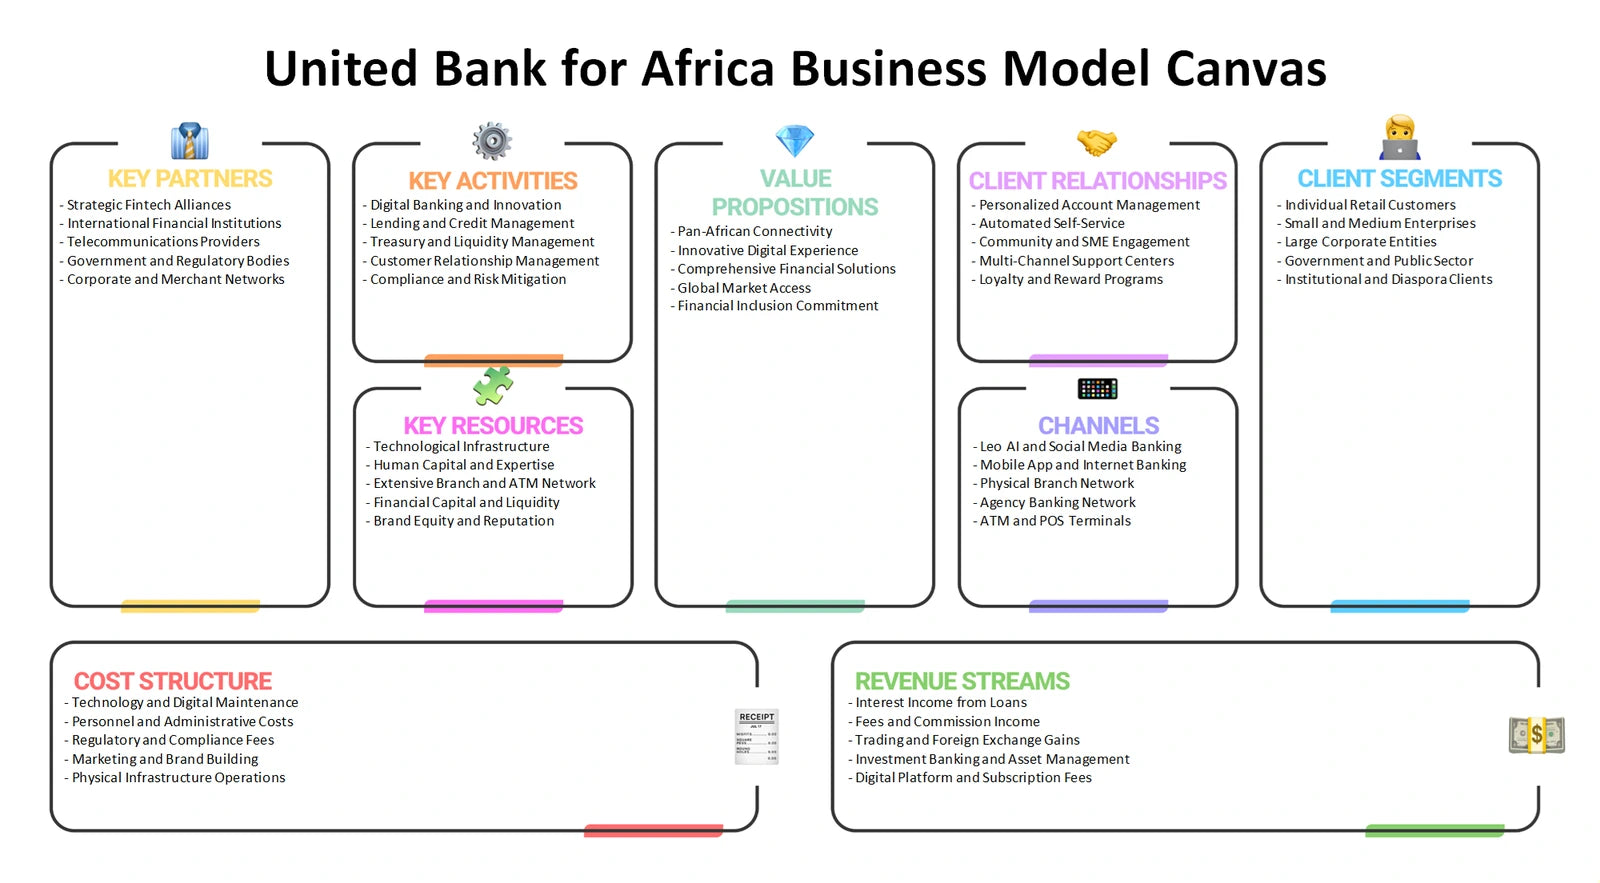
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What competitive pressures can affect the attractiveness and economics of the banking activities under review?
A United Bank for Africa Porter's Five Forces assessment looks beyond direct bank-to-bank competition. Rivalry may influence product features, service quality and the cost of winning deposits or loan customers. Buyer power matters because retail, business and public-sector customers can compare providers, negotiate terms or spread funds across institutions. Supplier power can include the influence of funding sources, technology providers and payment infrastructure partners. New entrants may emerge through licensed financial institutions or digitally focused providers, while substitutes include non-bank ways to save, transfer money, pay merchants or access credit. The analysis does not assign unsupported force scores; it frames the evidence needed for a defensible industry view.
- Competitive pressure. Separate rivalry in deposits, lending and transaction services because customer switching conditions may differ across each activity.
- Alternatives to banks. Consider substitutes as alternative ways to meet payment, financing or savings needs, not simply as another named competitor.
- Evidence trail. Use the Excel framework to compare each force and use the Word analysis to explain why a pressure could influence margins, retention or investment needs.
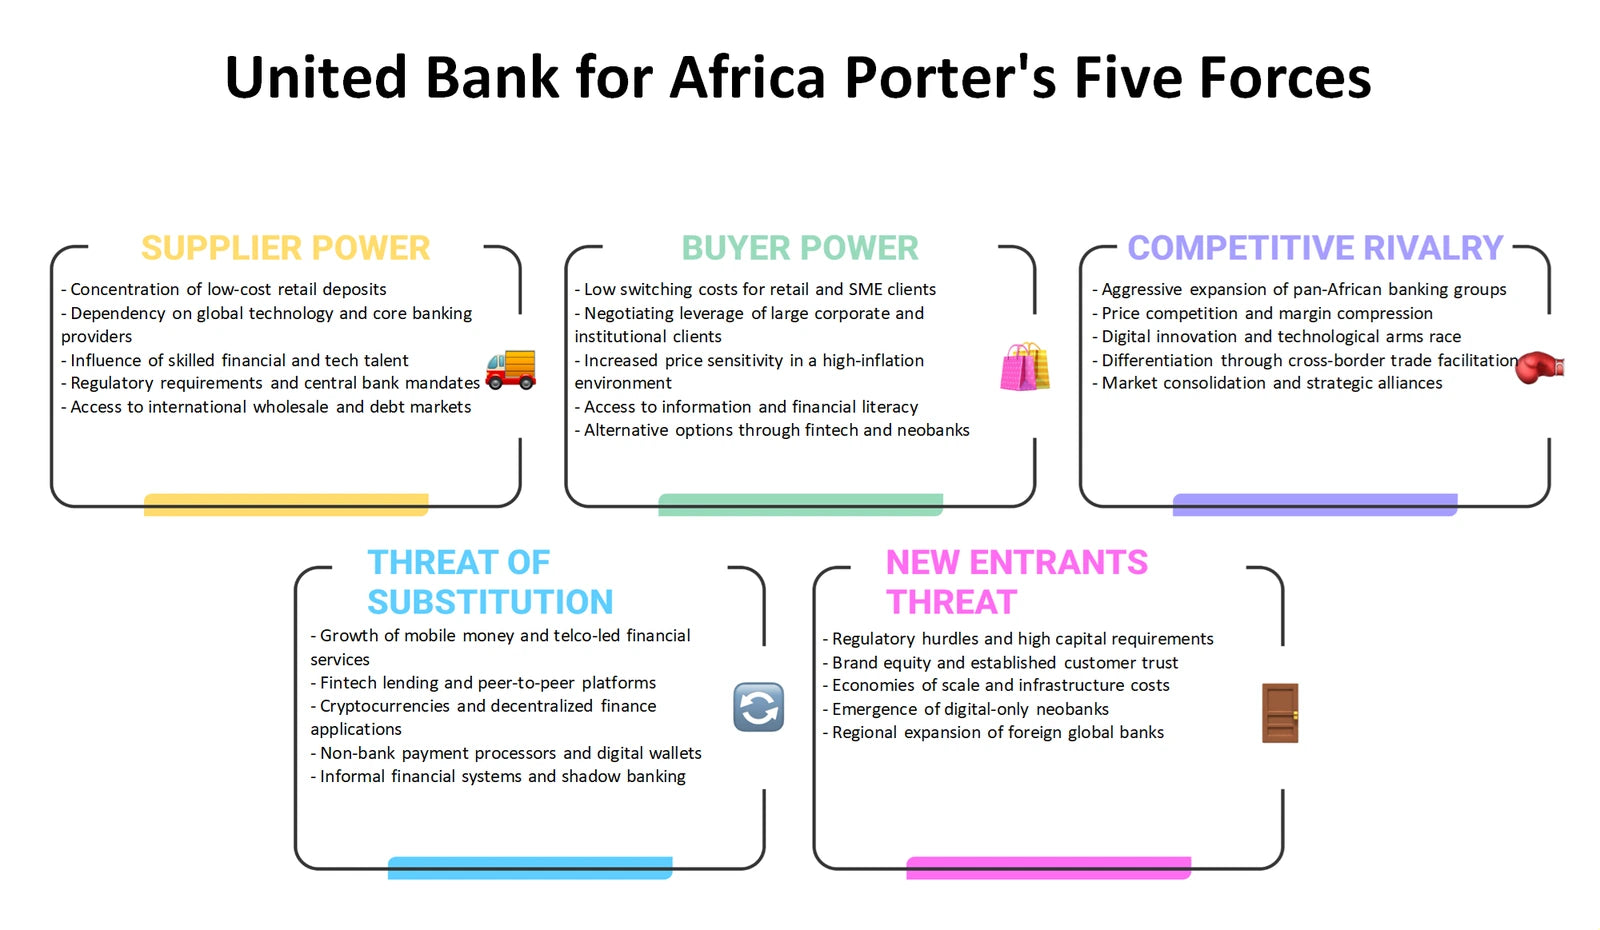
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should banking propositions be considered across product design, pricing logic, access and communication?
The United Bank for Africa Marketing Mix applies Product, Price, Place and Promotion to a regulated service business. Product can cover the practical combination of deposit accounts, lending, cards, payment access and relationship support required by different customer groups. Price is broader than a headline fee: it can include interest, charges, terms and the value exchange associated with service level or credit access. Place considers where customers interact with the bank, including physical service points and digital routes where relevant. Promotion examines how trust, clarity and suitability are communicated without assuming a particular campaign, price point or channel share.
- Offer design. Compare how retail and organisational customers may value convenience, credit, transaction capability and ongoing support differently.
- Service distribution. Examine the trade-off between accessible customer contact and the cost, consistency and control of delivery channels.
- Go-to-market review. Use the Excel structure to align the four Ps for each proposition, supported by the Word analysis for narrative context and decision questions.
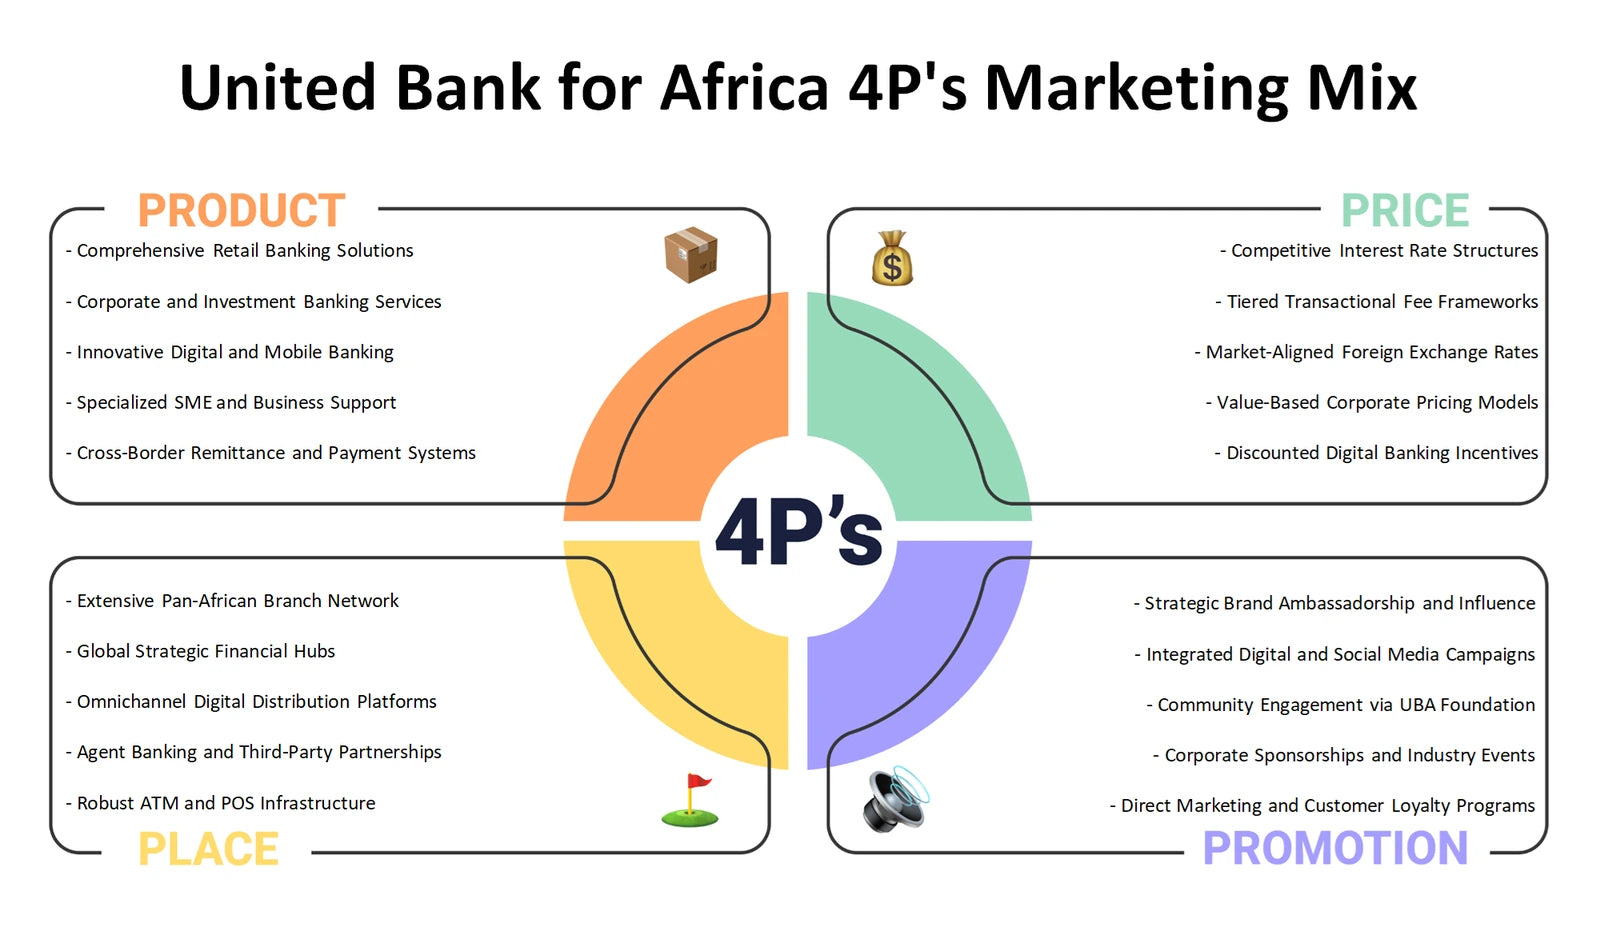
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes should be monitored when assessing a deposit, lending and payments business?
A United Bank for Africa PESTLE analysis, also commonly written as PESTEL, puts external conditions around the intended banking model. Political conditions can affect public-sector relationships and policy direction. Economic conditions may shape borrowing demand, deposit behaviour, credit quality and funding costs. Social change can influence expectations for convenience, trust and financial access. Technological developments matter for secure transactions, digital service delivery and payment integration. Legal conditions include banking, consumer, data and financial-crime obligations, while environmental factors can affect customer sectors, operational resilience and risk assessment. These are analytical categories, not claims that a particular policy, law or rate has changed.
- External scan. Separate macroeconomic questions from legal or political questions so different risks are not compressed into a single broad assumption.
- Payments and resilience. Consider how technology dependence and secure card transactions can create both customer-value opportunities and operational exposure.
- Monitoring agenda. Use the Excel framework to organise external signals by category, then use the Word analysis to connect them to banking decisions and possible responses.
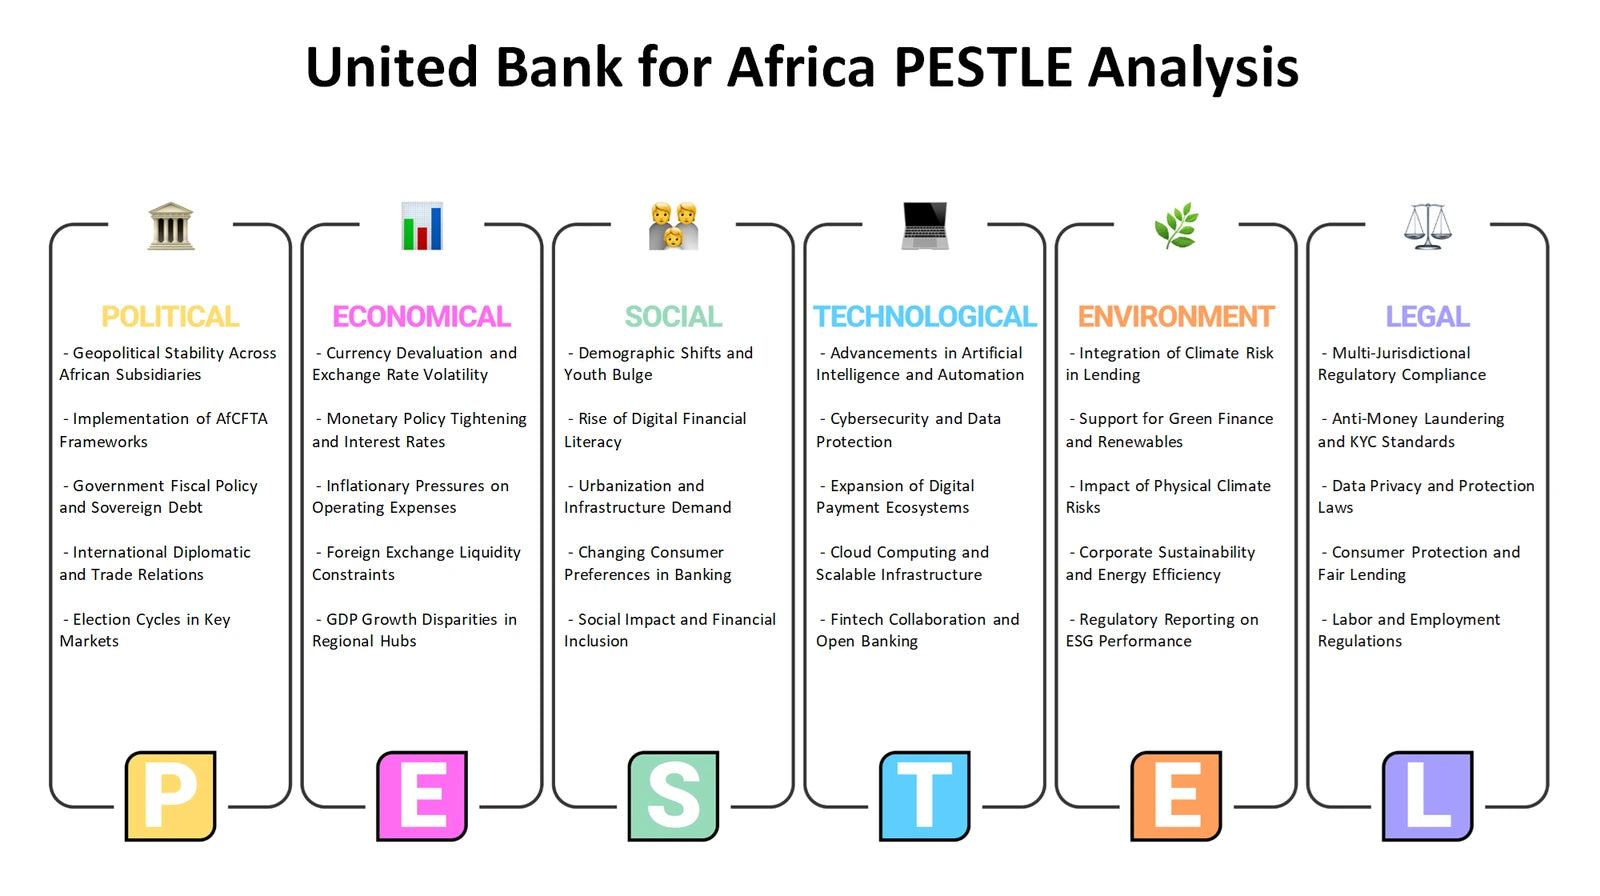
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal banking capabilities be weighed against external opportunities and threats without confusing the two?
A United Bank for Africa SWOT analysis helps keep internal and external factors distinct. Strengths and weaknesses concern capabilities and constraints inside the operating model, such as customer relationships, funding access, operational processes, payment partnerships, technology or risk-management capacity where evidence supports examination. Opportunities and threats arise outside the organisation, such as changing customer needs, competitive alternatives, economic conditions or regulatory expectations. The value of SWOT is not a generic list of positives and negatives. It is a way to test whether an internal capability could support a response to an external opening, or whether an internal limitation could increase exposure to an external threat.
- Correct classification. Keep a capability or limitation inside Strengths or Weaknesses, and place market, policy and competitive conditions under Opportunities or Threats.
- Strategic fit. Explore how deposit, lending and payment-service capabilities may relate to changing customer expectations or industry pressure.
- Actionable synthesis. Use the Excel matrix to capture evidence and priorities, then use the Word analysis to develop balanced implications rather than unsupported conclusions.
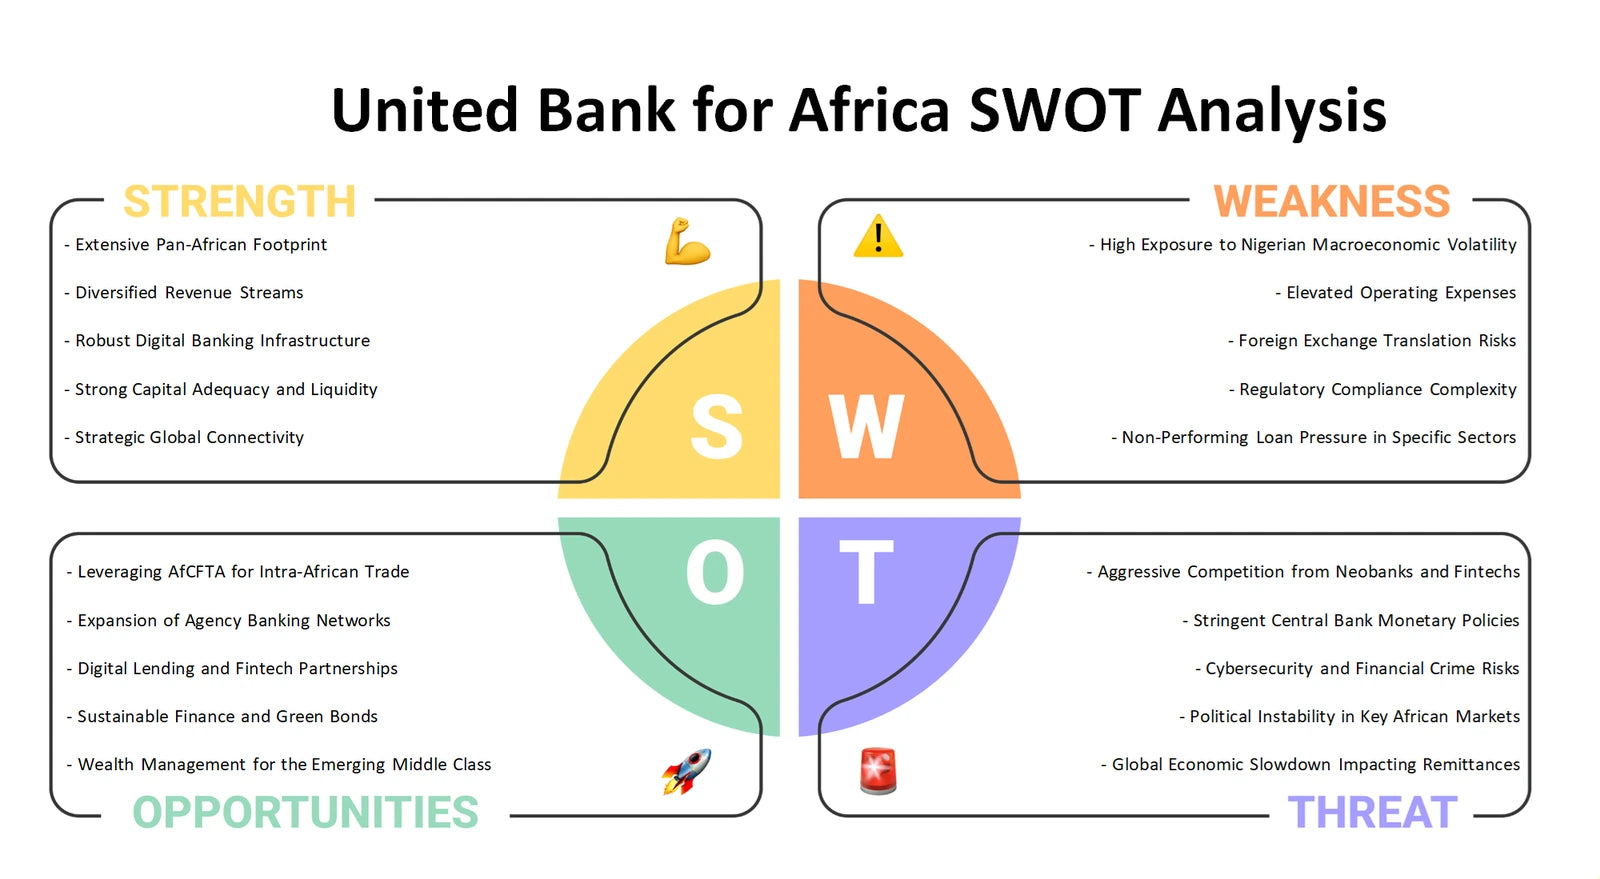
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect the banking questions before drawing conclusions
Used together, the six perspectives move from portfolio choices and value creation to industry pressure, customer-facing decisions, external conditions and strategic fit. The Excel files provide structured places to compare and organise the questions, while the Word files provide detailed company-analysis context for interpreting the relationships. For United Bank for Africa, this supports a more connected review of the intended deposit, lending and payments business without presenting assumptions as verified findings.
Company background: United Bank for Africa — supplied product-context page.