

Towne Bank: Banking Business and Lending Economics – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Towne Bank Strategy Analysis Bundle
This bundle is scoped to the Towne Bank banking business described in the supplied product context, rather than to another similarly named organisation. That context focuses on commercial real-estate developers and owners seeking construction-to-permanent financing, tailored credit terms, joint-venture equity structuring and treasury or cash-management services. The relevant customer relationship is therefore not a simple transaction: lending, draw administration, valuation and operating cash flows can remain connected through a project lifecycle.
Towne Bank’s documented analytical context also highlights compliance, risk governance, internal audit, BSA/AML, fair lending, privacy and safety-and-soundness controls. The six perspectives help examine how a relationship-led financial-services model allocates resources, earns risk-adjusted returns and responds to changing credit, regulatory and technology conditions. They are decision frameworks, not claims that the downloadable analyses assign scores, market shares or investment recommendations.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which customer, lending and service activities deserve scarce capital, specialist attention and risk-management capacity?
A Towne Bank BCG Matrix helps organise a portfolio discussion around market growth and relative market share, rather than treating every banking activity as equally strategic. For a business serving developers and owners, the useful comparison may include lending relationships, treasury-service needs and adjacent client-support activities. The model uses Stars, Cash Cows, Question Marks and Dogs as analytical categories; it does not establish that any Towne Bank offering belongs in a particular quadrant. Its value is in testing where growth may justify investment, where established activity may fund capability, and where concentration or complexity deserves a harder review.
- Capital priorities. Compare potential growth opportunities with the balance-sheet capacity, underwriting effort and control requirements needed to support them.
- Relationship economics. Consider whether lending activity can be assessed alongside treasury relationships, deposits, servicing demands and the long timeline of a property project.
- Portfolio working view. Use the Excel framework to map candidate activities by growth and relative-share evidence, then use the Word analysis to record assumptions, risks and decision questions.
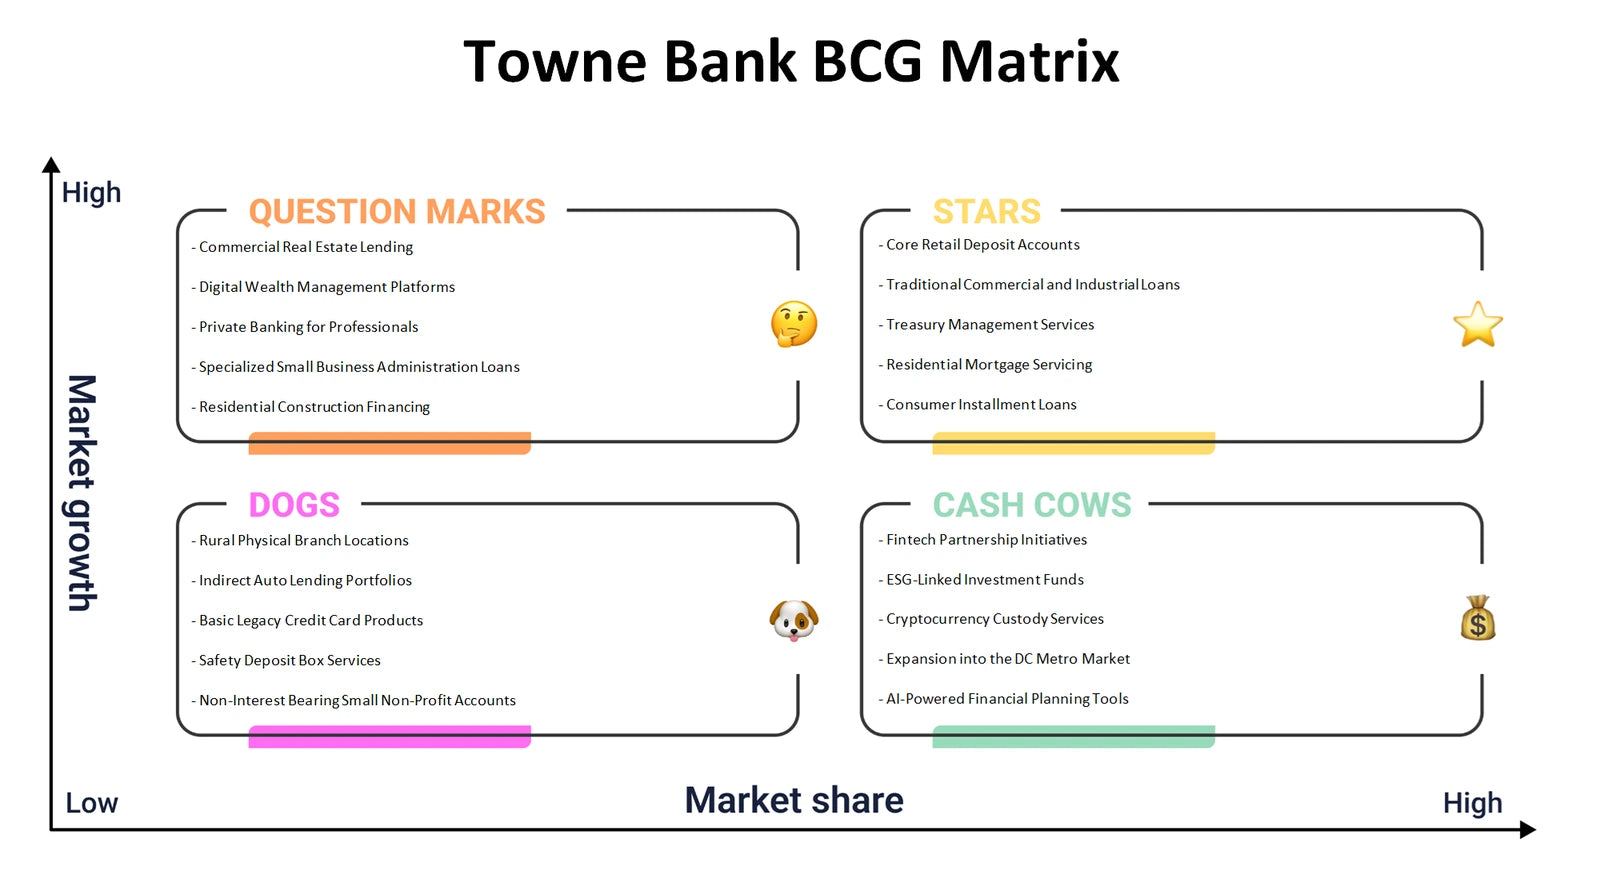
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do specialised real-estate finance relationships create value while covering credit, compliance and operating costs?
The Towne Bank Business Model Canvas connects the full operating logic behind tailored banking services. It considers customer segments such as developers and owners; value propositions such as financing and cash-management support; channels and customer relationships; and revenue streams associated with financial services. It also brings together key resources, key activities, key partnerships and cost structure. That connection matters because a construction-to-permanent facility can require local market judgement, draw controls, valuation work, compliance oversight and ongoing client service before it produces a sustainable return. The Canvas helps trace those dependencies instead of viewing a loan product in isolation.
- Value delivery. Examine how tailored credit terms, project-timeline understanding and treasury services may address complex capital stacks and operating cash needs.
- Economic connections. Relate revenue logic to underwriting, monitoring, technology, specialist staff, audit activity and recurring regulatory expenses.
- Model alignment. Populate the structured Excel blocks with evidence and open questions, while the Word analysis provides narrative context for links between customers, activities and costs.
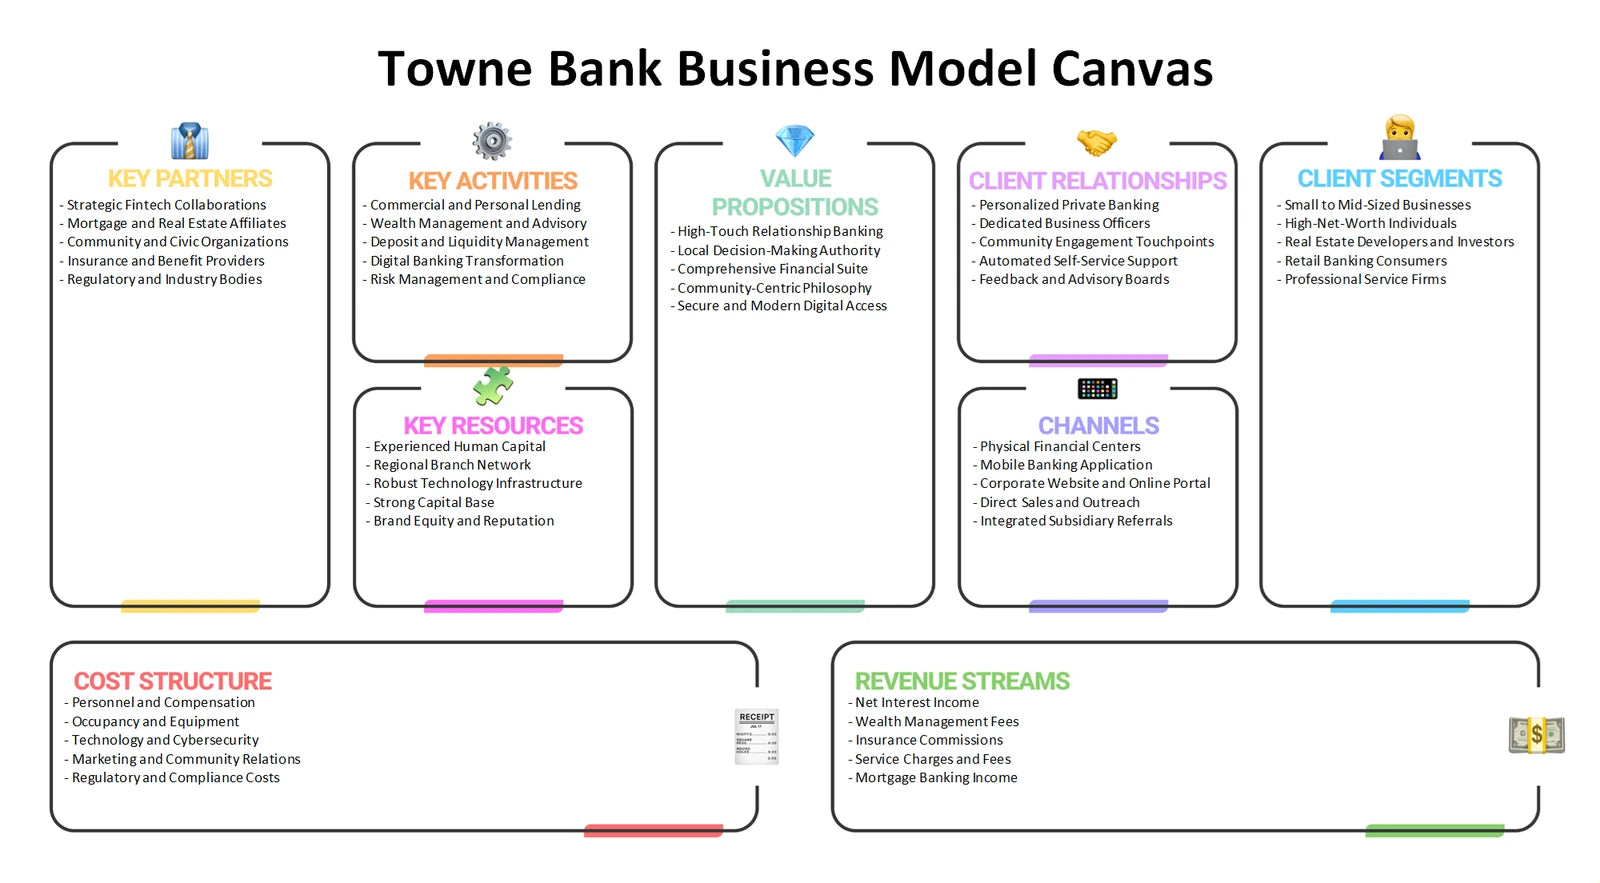
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could shape the attractiveness of specialised commercial banking relationships?
Towne Bank Porter's Five Forces examines competitive pressure around the financial needs of property developers and owners. Rivalry can arise when banks compete for creditworthy borrowers, operating balances and treasury relationships. Buyer power may increase when sophisticated clients compare terms, service levels and financing structures. Supplier power is relevant to funding, specialised talent, technology providers and professional advisers. The threat of new entrants includes institutions able to target profitable niches, while substitutes include non-bank lenders, private capital, alternative payment tools and other ways to obtain project funding or manage cash. The framework does not assign a force score; it structures evidence about where margins, service expectations and risk standards may be tested.
- Competitive tension. Assess how tailored financing and local project knowledge may differentiate a relationship while borrowers retain alternative sources of capital.
- Input dependence. Compare the effect of funding conditions, compliance expertise, technology vendors and external valuation or legal support on operating flexibility.
- Pressure test. Use the Excel framework to organise each force and supporting observations, then consult the Word analysis when translating the five forces into focused management questions.
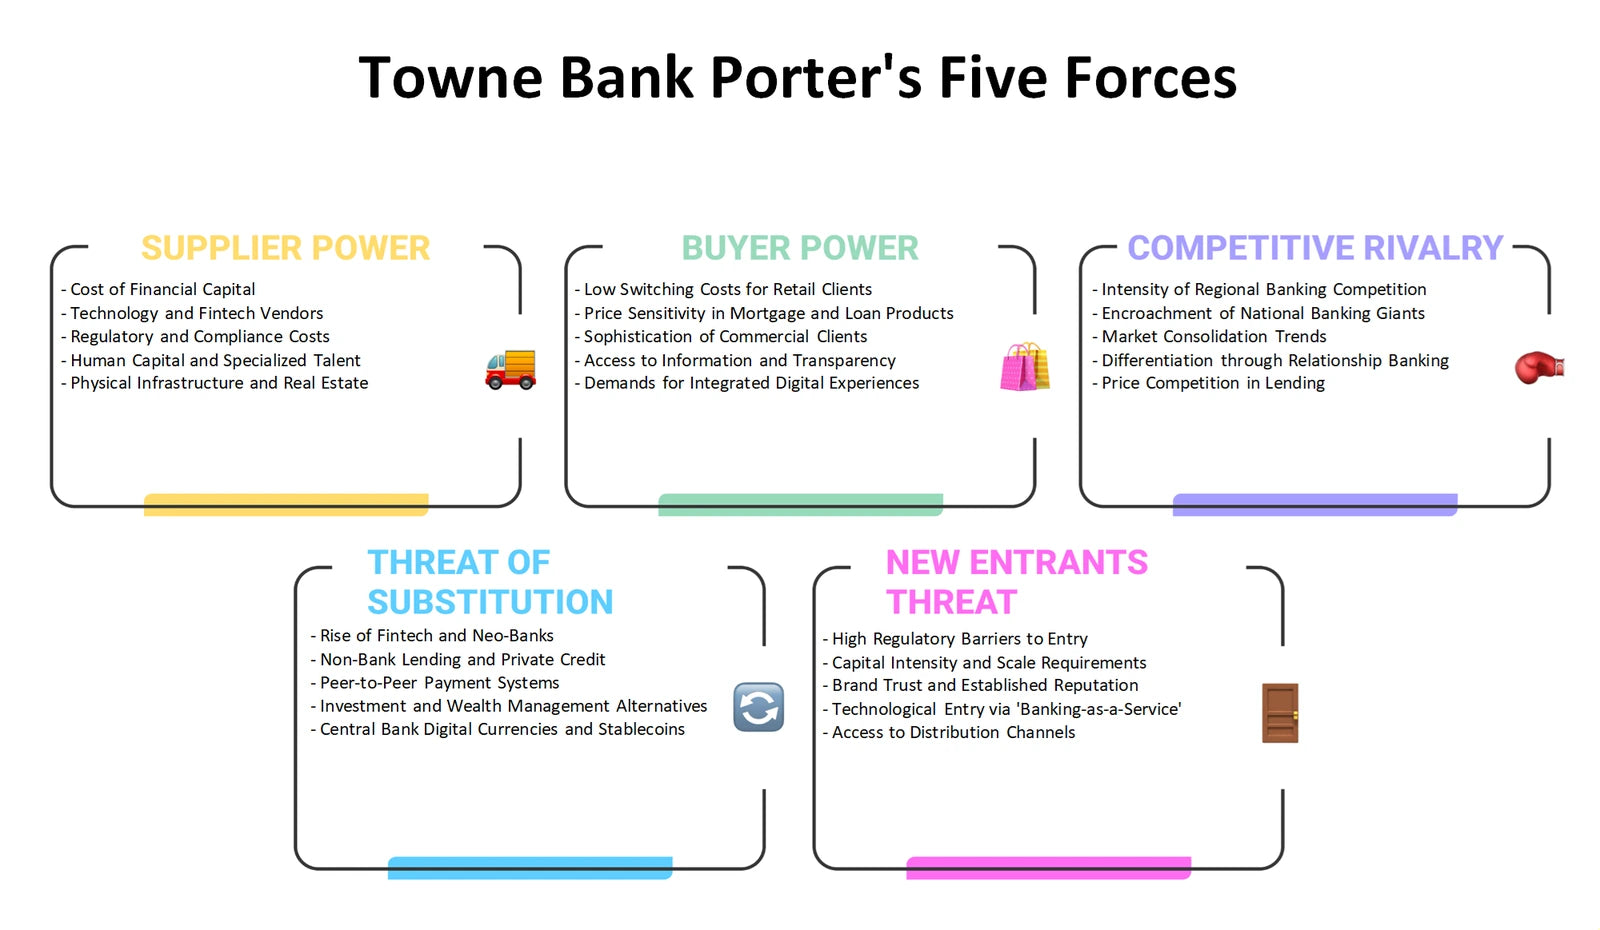
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a regulated, relationship-based bank present specialised financing and treasury support to the customers it is equipped to serve?
The Towne Bank Marketing Mix considers Product, Price, Place and Promotion in a financial-services setting where suitability, trust and risk discipline matter. Product analysis can cover construction-to-permanent lending, tailored credit structures and treasury services. Price is not merely an advertised rate: it may be examined through risk-adjusted terms, fees, covenants, collateral and the cost of servicing a complex project. Place concerns the routes through which relationships are developed and maintained, including relationship managers and service touchpoints. Promotion should be assessed as clear, compliant communication of relevant capabilities rather than as unsupported campaign claims.
- Offer design. Test how lending, draw controls and cash-management support may fit the milestones and liquidity needs of multi-phase development projects.
- Commercial discipline. Compare pricing logic with credit risk, valuation uncertainty, project timing and the service resources required for tailored terms.
- Go-to-market review. Use the Excel 4Ps structure to separate offer, pricing, access and communication choices, with the Word analysis adding sector-specific rationale and caveats.
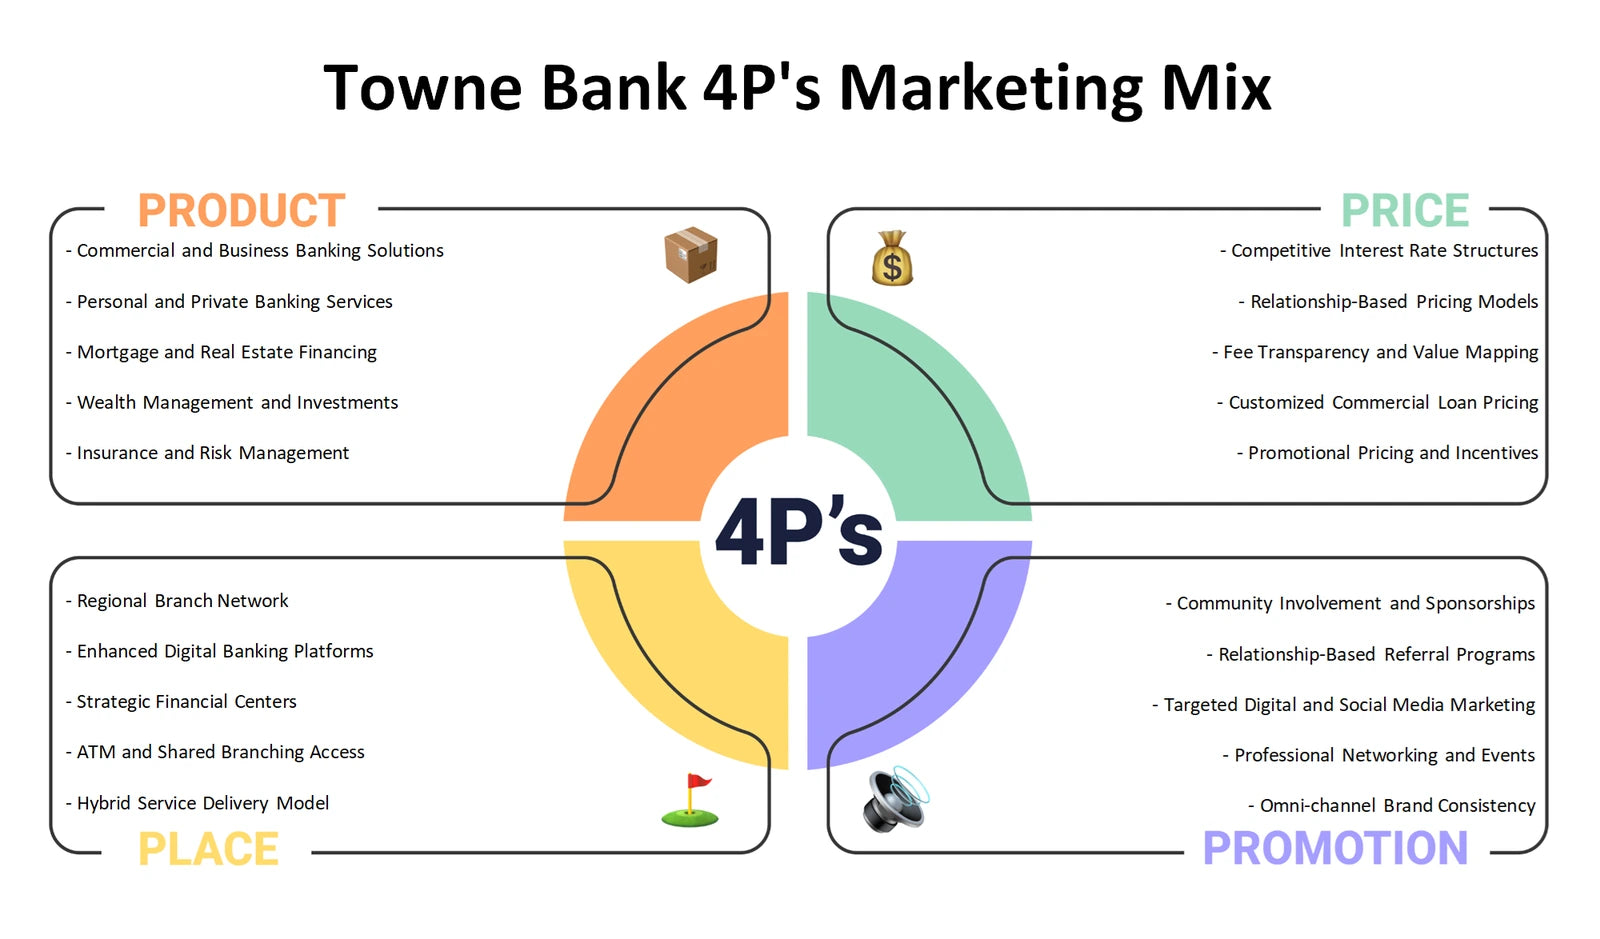
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter credit demand, compliance workload and the economics of commercial banking?
A Towne Bank PESTLE analysis, also commonly called PESTEL, separates external influences from internal performance. Political factors may include public-policy priorities affecting financial services or development activity. Economic questions can cover credit conditions, property cycles, construction costs and borrower cash flows. Social factors may influence expectations for trust, accessibility and responsible lending. Technological developments can affect treasury tools, data protection and fraud controls. Legal considerations are particularly important where BSA/AML, fair lending, privacy, examinations and safety-and-soundness obligations shape processes. Environmental issues may affect property risk, insurance availability and long-term collateral assessment. These are categories for investigation, not assertions that a particular policy or market change has occurred.
- Regulatory horizon. Examine how evolving supervisory expectations could affect training, independent testing, internal audit, reporting and specialist staffing.
- Property exposure. Consider how external construction, leasing, sales and environmental conditions may affect valuation assumptions and draw-control decisions.
- Scenario structure. Organise external drivers in the Excel PESTLE framework and use the Word analysis to connect each driver to relevant banking decisions and monitoring needs.
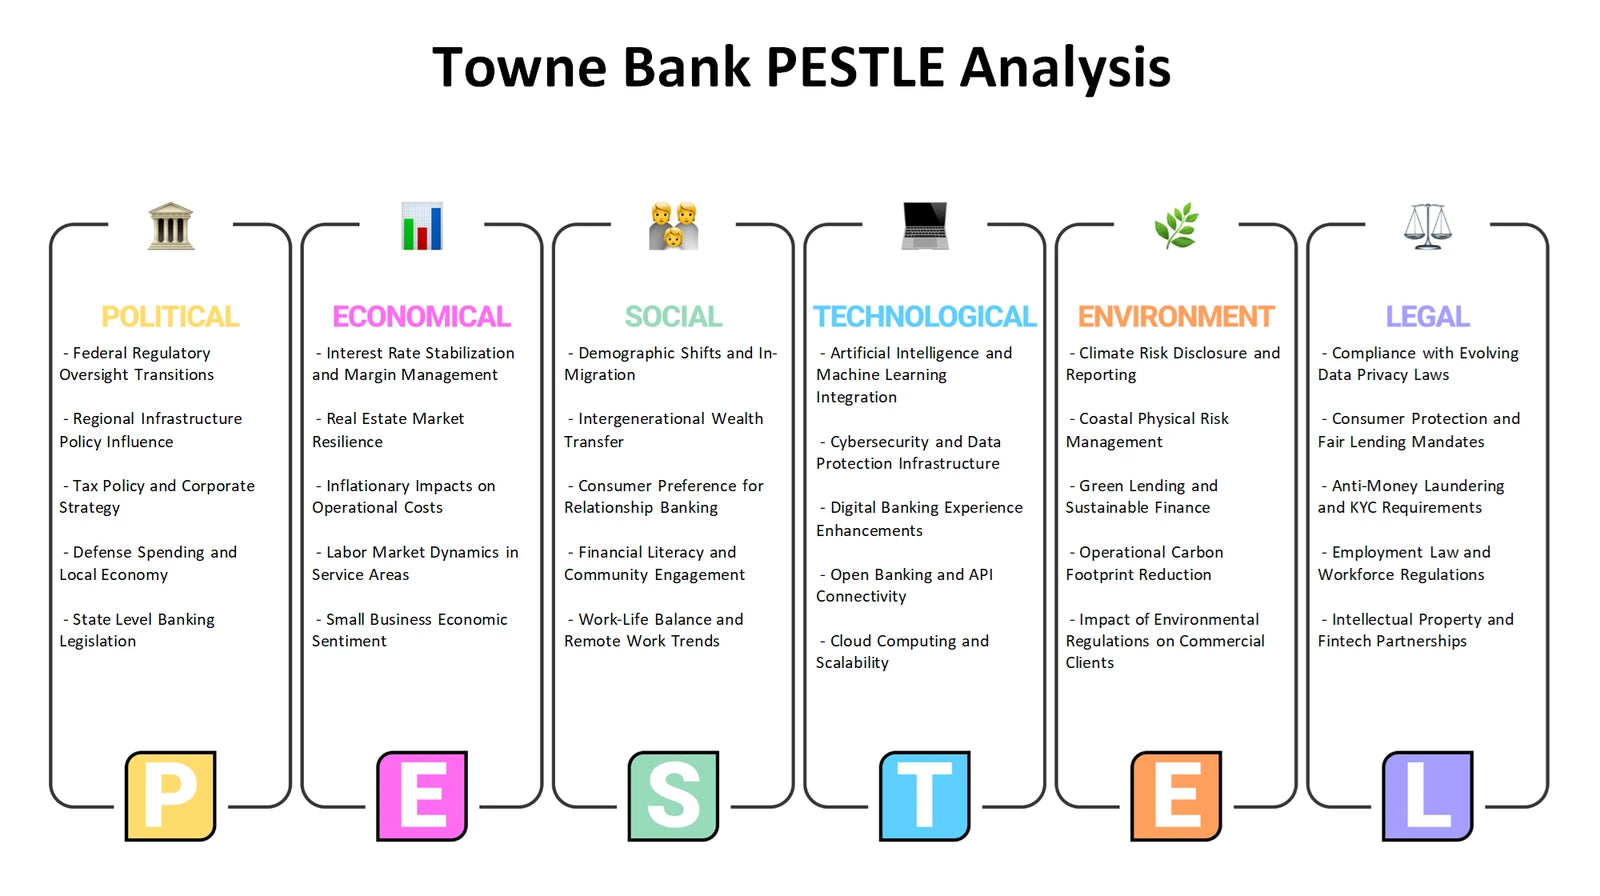
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Towne Bank distinguish its capabilities and constraints from the opportunities and threats around it?
A Towne Bank SWOT analysis provides a disciplined distinction between internal and external factors. Potential strengths to assess may include the ability to provide tailored credit and treasury support, local-market insight and established risk-control practices. Potential weaknesses may involve the resource intensity of specialised underwriting, portfolio monitoring and recurring compliance obligations. Opportunities are external possibilities, such as unmet client needs for coordinated financing and cash management, while threats are external pressures such as property-market stress, funding competition, cyber risk or regulatory change. None of these themes should be treated as a confirmed finding without evidence; the purpose is to make assumptions visible and connect them to actions, controls and priorities.
- Internal reality check. Separate documented operating capabilities and cost burdens from aspirational claims about differentiation or growth.
- External fit. Match potential opportunities in developer and owner relationships against threats from credit conditions, substitutes and compliance demands.
- Actionable synthesis. Use the Excel grid to classify evidence and uncertainties, then use the detailed Word analysis to develop balanced discussion points across all four categories.
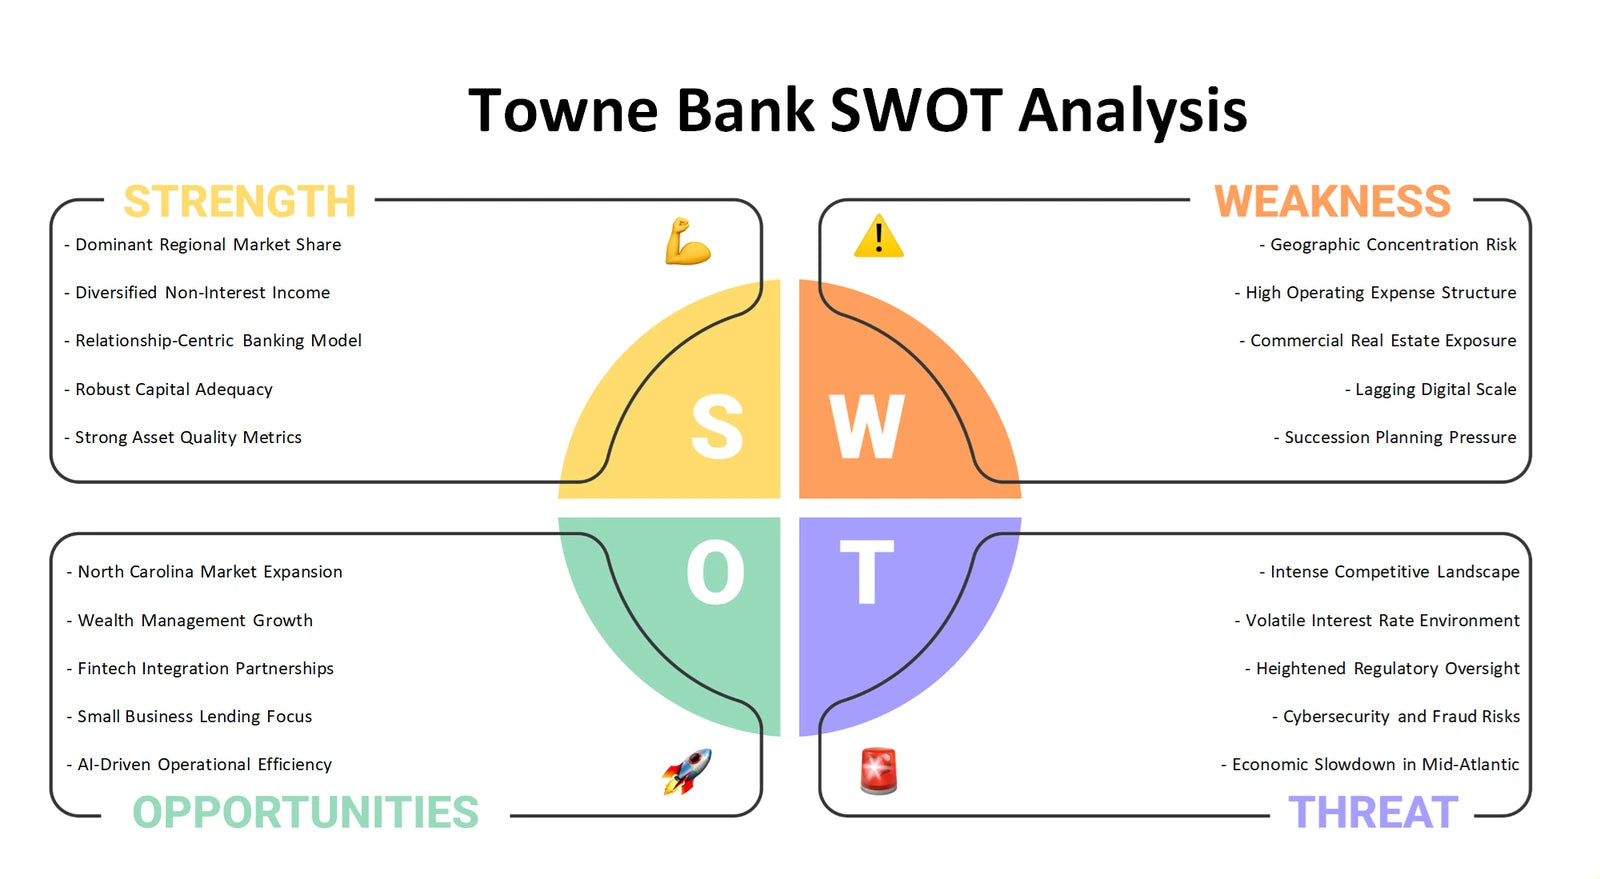
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices with risk-aware relationship banking
Used together, the six perspectives move from portfolio priorities and business-model mechanics to competitive pressure, customer-facing choices, external conditions and strategic fit. For Towne Bank, that creates a practical route for examining the trade-offs surrounding specialised commercial real-estate finance, treasury relationships, compliance investment and disciplined risk management. The Excel frameworks provide structured places to compare evidence and questions, while the Word files provide detailed company-analysis context for developing a more coherent strategic view.
Company background: Towne Bank — supplied business-model context.