

Third Federal: Banking Business and Lending Economics – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Third Federal Strategy Analysis Bundle
Third Federal, identified in public company-reference sources as Third Federal S&L, is an American regional bank headquartered in Cleveland, Ohio. Its supported business context centres on mortgage lending: serving borrowers through mortgage origination, underwriting and servicing activities, with customer experience and risk assessment central to the operating model.
The available context also describes relationships with mortgage-technology and credit-data providers that can support lending workflows and credit decisions. The useful strategic questions are therefore not assumed conclusions: how should mortgage activities be prioritised, where does value arise in the borrower journey, and which external pressures could reshape lending economics? The bundle applies six connected frameworks to examine those questions.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending activities or borrower segments merit attention when growth prospects and relative market share are considered together?
A Third Federal BCG Matrix helps organise portfolio-priority discussions without assuming that any mortgage activity already occupies a particular quadrant. The framework compares market growth with relative market share and uses the familiar Stars, Cash Cows, Question Marks and Dogs categories to test resource choices. For a mortgage-focused regional bank, this can clarify whether different lending propositions, servicing capabilities or customer niches warrant investment, selective maintenance, redesign or possible de-emphasis. The value lies in making the comparison explicit rather than treating all lending activity as equally attractive.
- Portfolio lens. Compare mortgage-related activities by their market setting and relative competitive position, while keeping unverified market-share assumptions out of the analysis.
- Capital discipline. Connect each possible priority to the practical demands of underwriting capacity, servicing operations, technology support and risk management.
- Structured review. Use the Excel framework to map candidate activities consistently, then use the detailed Word analysis to document the reasoning, evidence gaps and questions behind each placement.
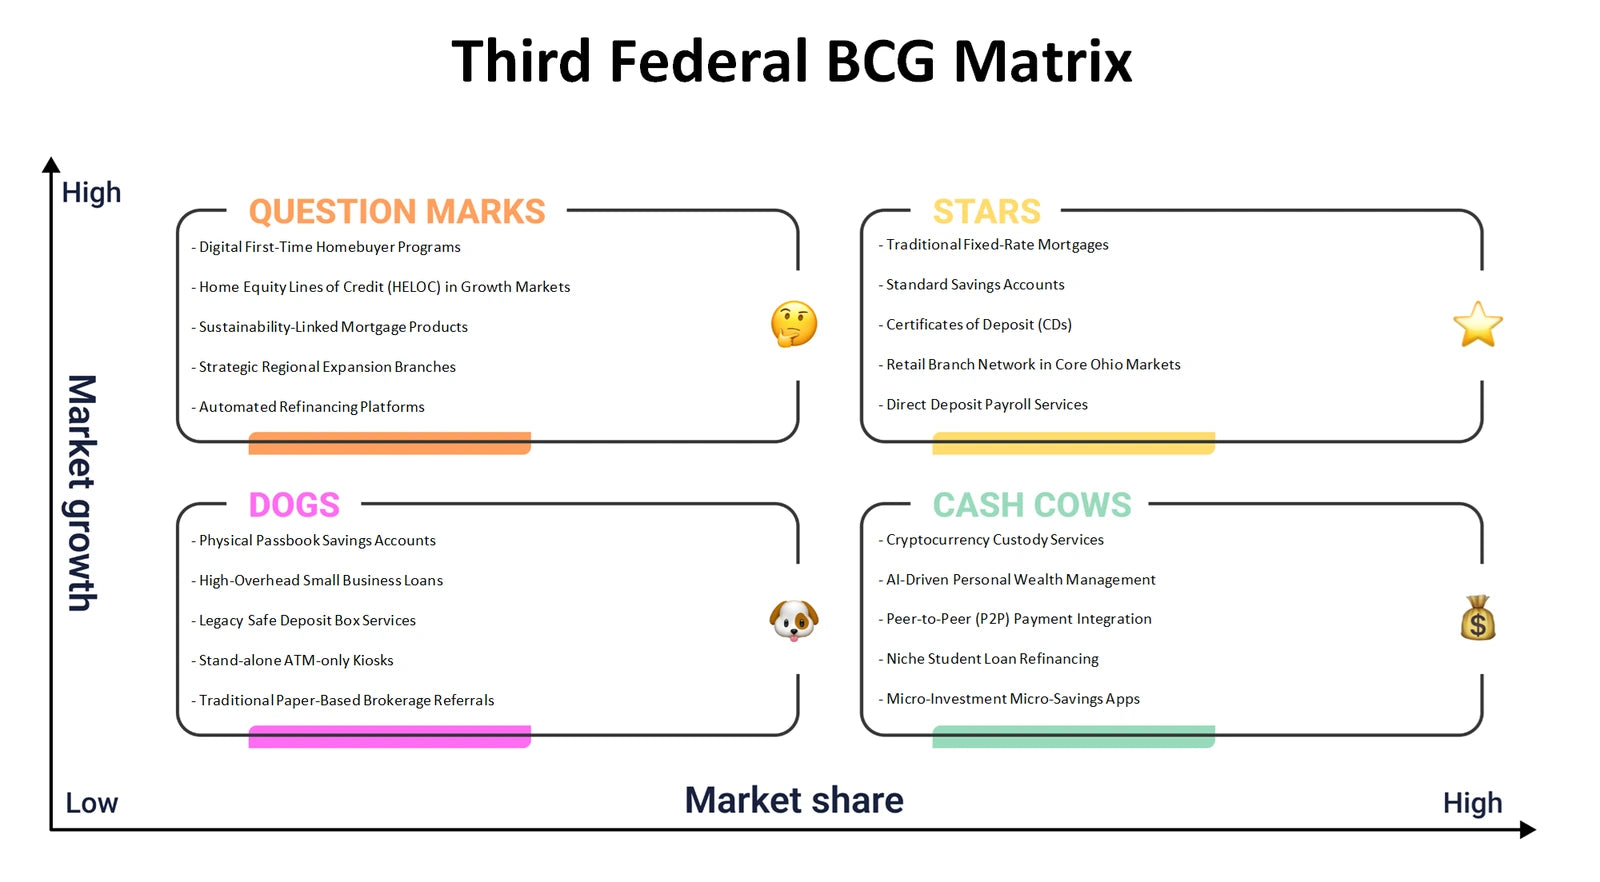
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do borrower needs, lending delivery and operating economics fit together in Third Federal's mortgage-centred model?
The Third Federal Business Model Canvas connects the nine building blocks behind a lending business rather than viewing technology, customer service and risk control in isolation. It helps examine customer segments such as prospective borrowers and existing mortgage customers; value propositions such as a dependable, convenient lending journey; and the channels and customer relationships through which that journey is delivered. It also brings together revenue streams, key resources, key activities, key partnerships and cost structure. The supplied context makes technology providers and credit-data relationships especially relevant analytical inputs because they can affect speed, data quality, underwriting workflow and operating cost.
- Borrower journey. Trace how channels, relationships and service expectations connect from application and credit review through mortgage servicing.
- Economic links. Consider how lending income logic relates to operational resources, compliance-intensive activities, external data and technology partners, and the costs they create.
- Model alignment. Populate the Excel canvas as a one-page operating map, then use the Word analysis to explore the dependencies and trade-offs that deserve management attention.
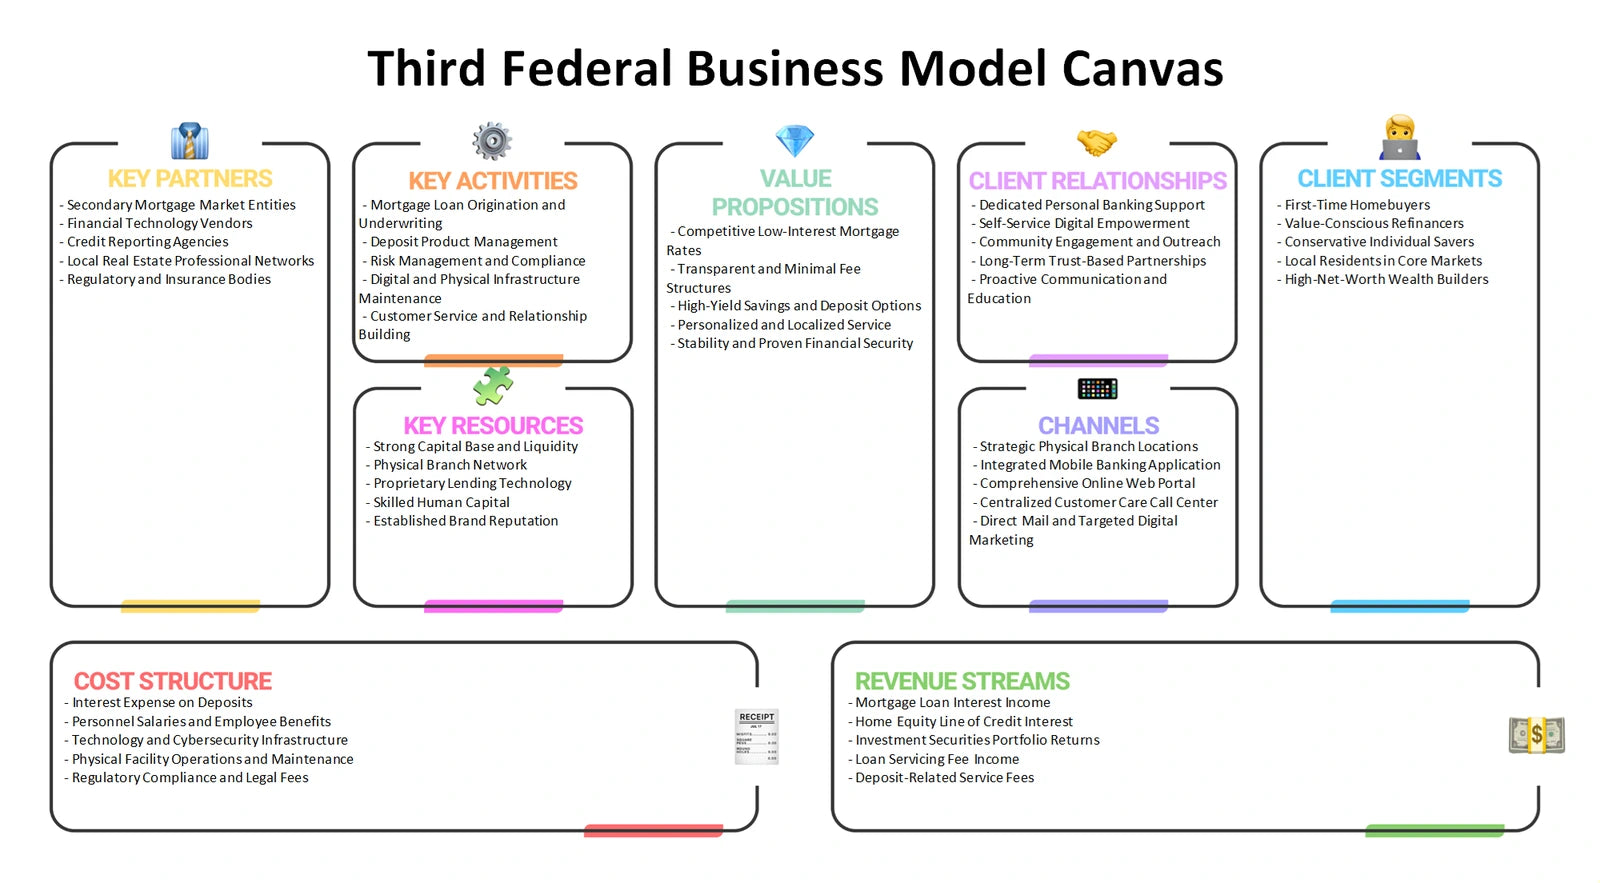
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What structural pressures can influence the attractiveness and defensibility of mortgage lending for a regional bank?
Third Federal Porter's Five Forces examines the mortgage-lending environment through rivalry, supplier power, buyer power, threat of new entrants and threat of substitutes. Rivalry can arise where lenders compete for qualified borrowers on service, process speed, terms and trust. Borrower power matters because customers can compare lenders and may be sensitive to the total cost and convenience of financing. Supplier power can include the influence of technology platforms and credit-data providers used in lending processes. New entrants may include digitally focused providers, while substitutes extend beyond direct lenders to alternatives such as delaying a purchase, renting, using cash or considering other forms of credit.
- Competitive pressure. Separate direct mortgage competition from the wider set of choices that can reduce a household's need for a traditional mortgage.
- Dependency check. Assess where reliance on external data, workflow technology or specialised service inputs could affect cost, resilience or differentiation.
- Evidence trail. Score discussion topics in the Excel framework and use the Word analysis to explain which assumptions require validation before a strategic response is chosen.
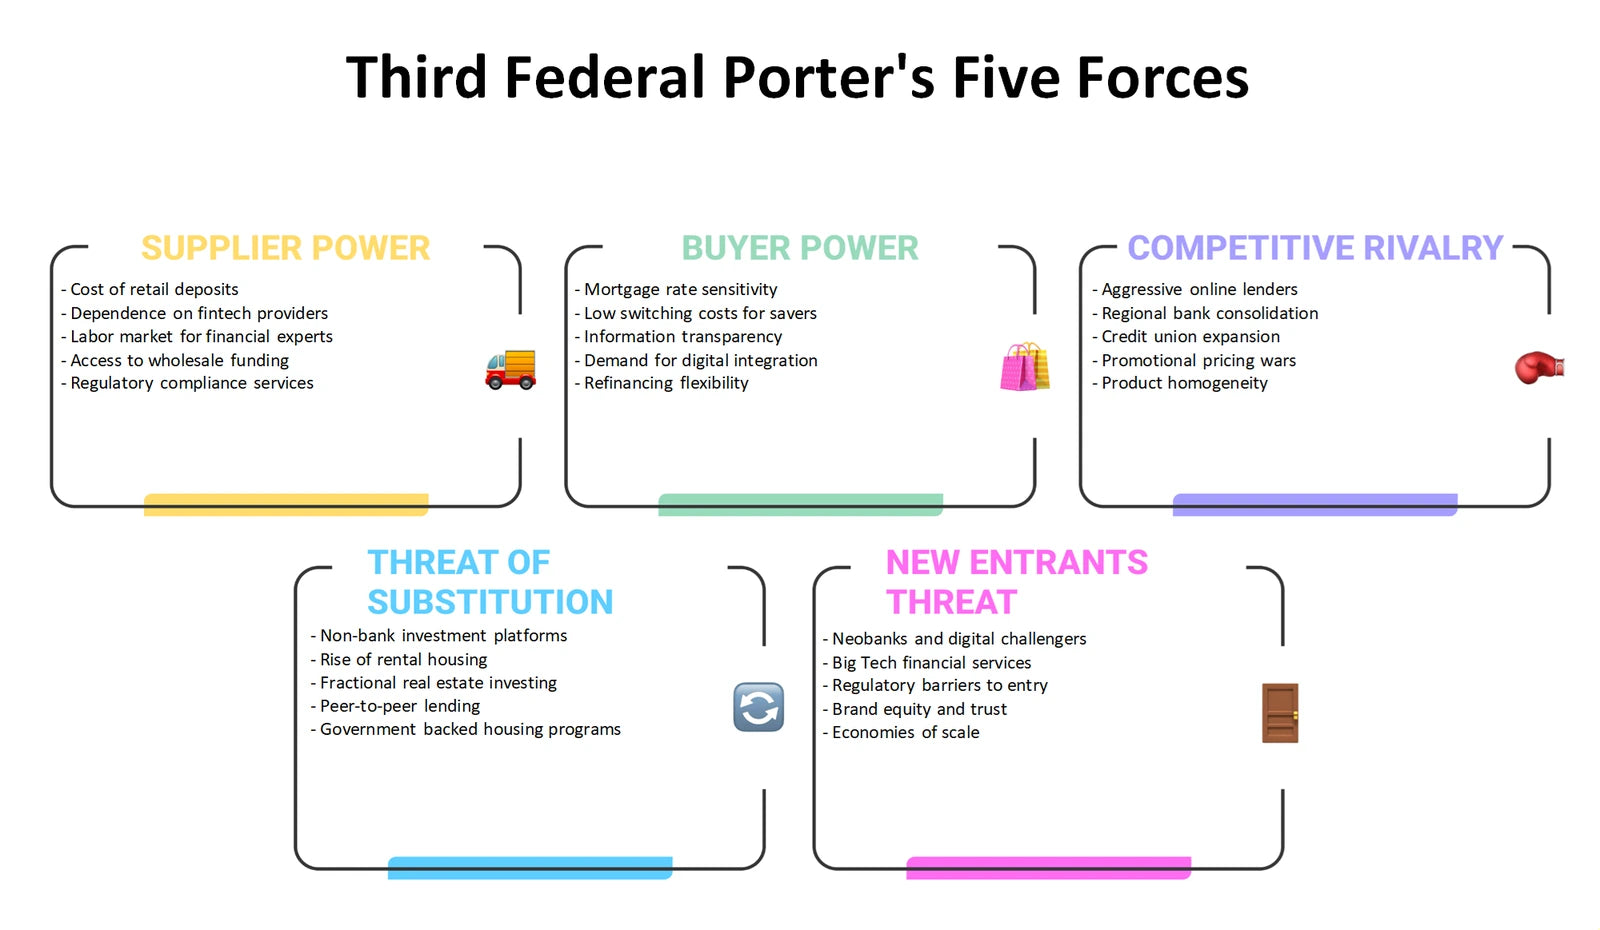
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a mortgage lender align its offer, pricing logic, access routes and communications with borrower confidence?
The Third Federal Marketing Mix applies Product, Price, Place and Promotion to a regulated financial-service decision rather than treating marketing as advertising alone. Product analysis considers the mortgage experience, including the clarity and reliability that borrowers may expect during application, underwriting and servicing. Price examines the logic of rates, fees, terms and total borrowing cost without inventing actual prices. Place evaluates how prospective and existing customers can engage with the lender, including the role of technology-enabled processes alongside relationship-led support. Promotion considers clear, compliant communication that helps borrowers understand a consequential financial commitment.
- Offer design. Test whether the product proposition addresses the moments that matter to borrowers, from information gathering to ongoing account servicing.
- Trust signals. Compare how price transparency, accessible service routes and responsible communications can reinforce a credible lending experience.
- Mix planning. Use the Excel structure to compare the four decisions side by side, then consult the Word analysis to connect proposed messaging or channel choices to customer and compliance considerations.
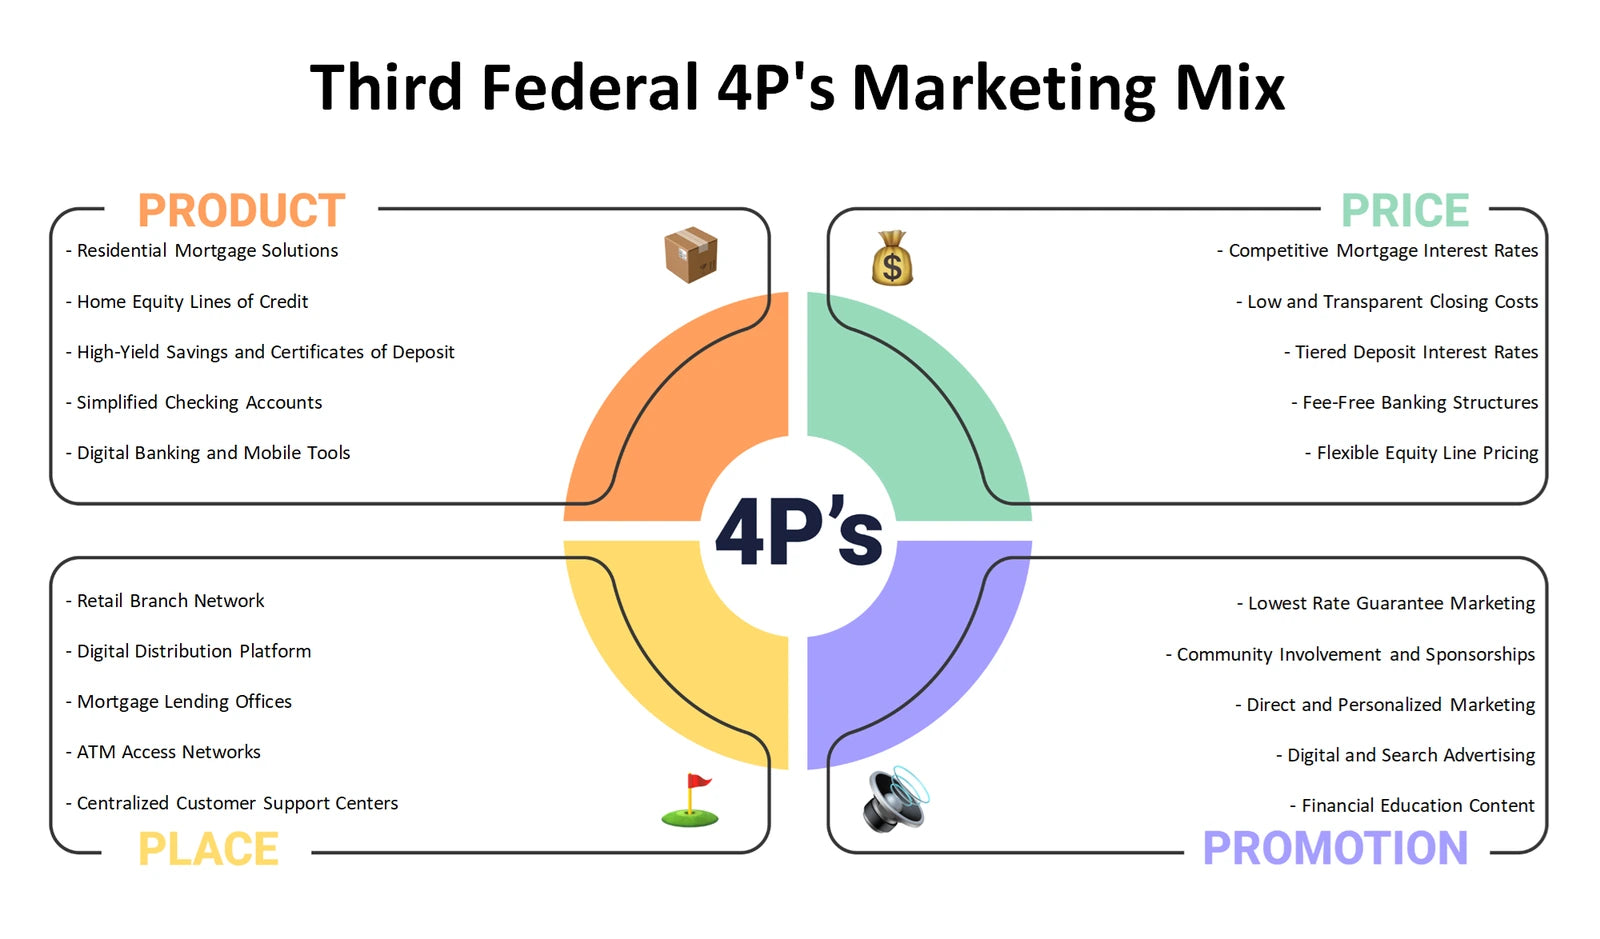
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter demand, risk and operating requirements for a Cleveland-headquartered mortgage lender?
A Third Federal PESTLE analysis, also commonly called PESTEL, separates external influences from internal capabilities. Political questions can include housing-policy priorities and the public environment for financial institutions. Economic factors include interest-rate conditions, housing affordability, employment and borrower repayment capacity. Social factors cover household preferences, demographic patterns and expectations for convenient service. Technological change is relevant to digital origination, servicing and data analysis. Legal considerations include lending, consumer-protection, privacy and fair-treatment obligations, while environmental factors may affect property exposure, insurance availability and the resilience of housing markets. These are analytical categories, not claims that a particular new policy or rate change has occurred.
- External scan. Identify which macro factors could influence borrower demand, credit quality, property values or the cost of mortgage operations.
- Regulatory horizon. Distinguish documented requirements from policy questions that should be monitored rather than presented as established change.
- Priority register. Organise external signals in Excel by relevance and possible business effect, then use the Word analysis to add context, implications and follow-up research questions.
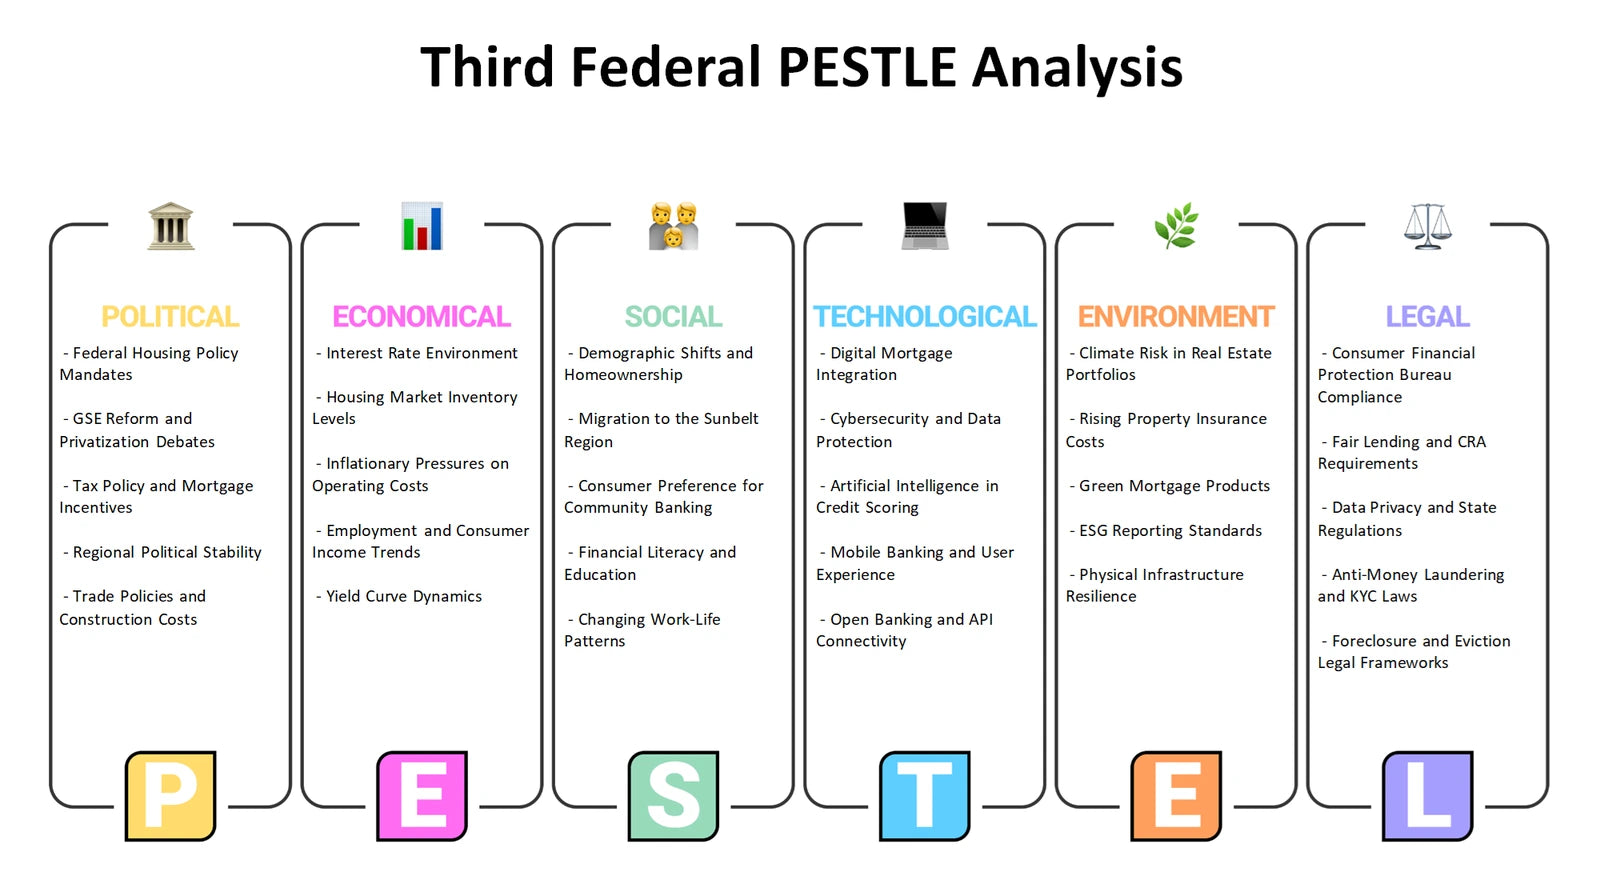
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Third Federal distinguish internal lending capabilities from external mortgage-market opportunities and threats?
The Third Federal SWOT analysis provides a final synthesis by keeping internal and external factors correctly separated. Strengths and weaknesses concern capabilities or constraints within the business: for example, the quality of lending processes, customer relationships, data use, servicing capacity or dependency on particular operating resources. Opportunities and threats arise outside the organisation, such as shifts in borrower needs, mortgage-market conditions, technology change, regulatory expectations or competitive alternatives. The supplied context around mortgage technology and credit information can be examined as a potential operational capability and partnership dependency, but it should not be treated as proof of a completed strategic advantage. This distinction keeps the discussion grounded.
- Internal reality. Test potential strengths and weaknesses against evidence about process capability, borrower experience, risk discipline and operational dependencies.
- External choices. Relate opportunities and threats to the wider forces identified in PESTLE and Five Forces rather than confusing market conditions with internal performance.
- Decision synthesis. Use the Excel matrix to pair internal factors with external conditions, then use the Word analysis to develop balanced strategic questions and supporting rationale.
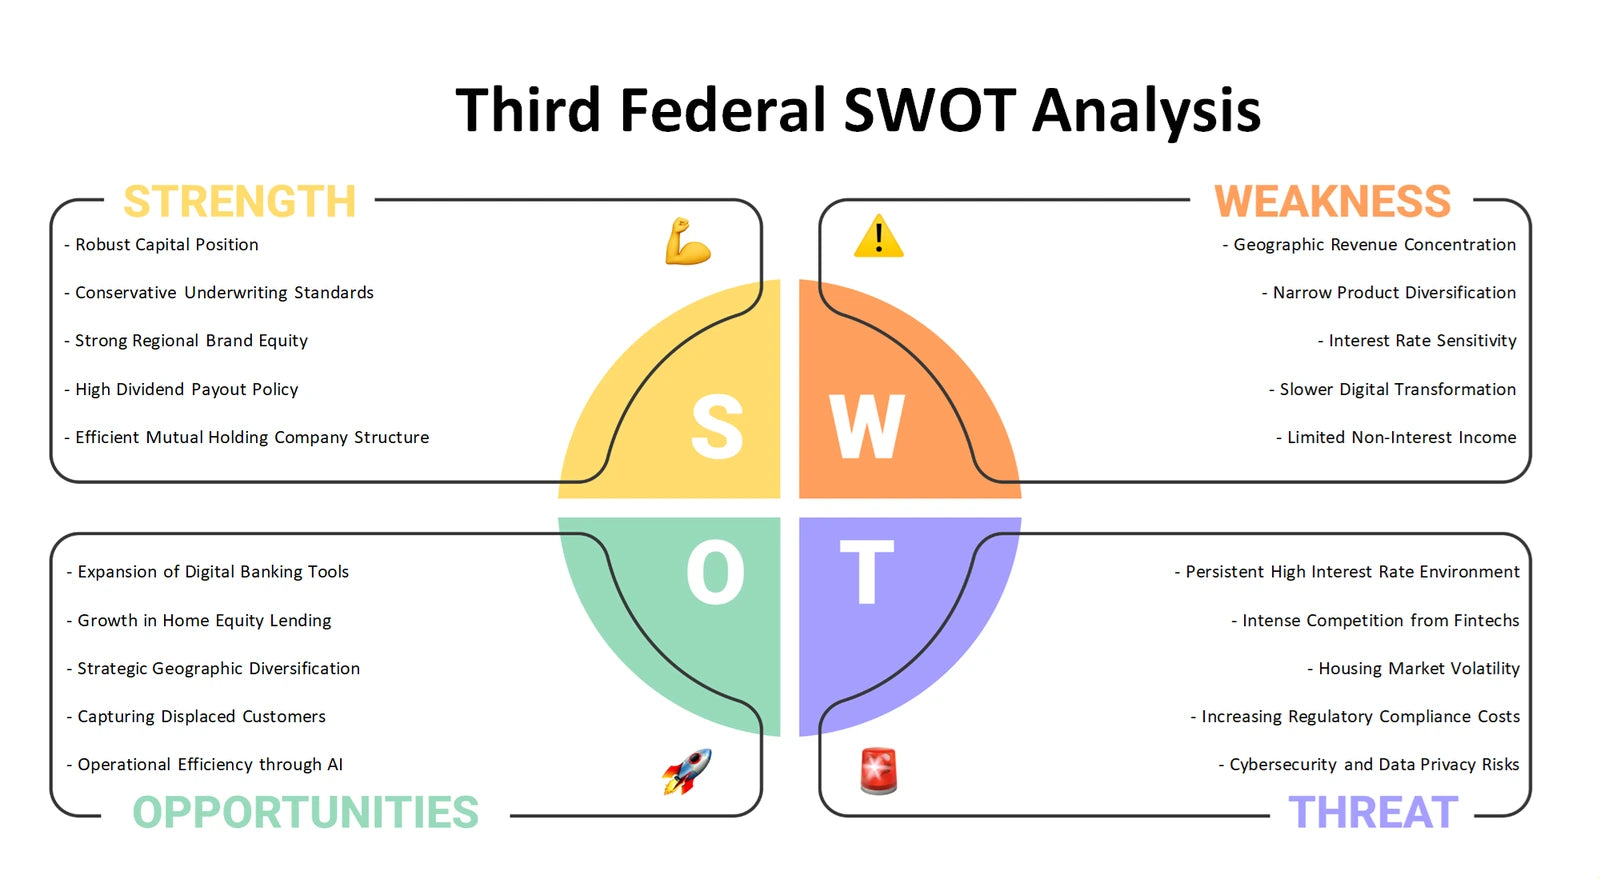
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Bring the six perspectives into one lending strategy discussion
Used together, the six analyses connect portfolio priorities, borrower value creation, industry structure, marketing choices, external change and strategic positioning. The Excel frameworks provide structured places to compare and organise the issues, while the detailed Word analysis helps develop the company-specific context behind them. For Third Federal, this creates a more coherent basis for discussing mortgage lending, borrower experience, operating dependencies and market uncertainty without treating analytical questions as established findings.
Company background: Third Federal — Wikidata profile for Third Federal S&L.