

Taiwan Cooperative Financial: Data Capabilities and Partnerships – Six-Framework Review

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Taiwan Cooperative Financial Strategy Analysis Bundle
This bundle is prepared for the business presented as Taiwan Cooperative Financial in the supplied product-context material. That context describes a financial-services operation focused on digital banking infrastructure, payment-card and digital-payment capability, and insurance activity supported by specialist underwriters and reinsurers. It also highlights relationships with FinTech developers, software providers and payment networks that help serve a diverse financial-services customer base.
These descriptions create useful strategic questions without treating them as independently verified current results: where should digital and insurance resources be concentrated, how do partnership dependencies affect economics, and which external changes could reshape customer demand or compliance costs? The Excel frameworks structure those questions, while the Word files provide detailed company-focused analysis to support comparison and discussion.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which Taiwan Cooperative Financial activities merit investment, harvesting, selective testing or tighter resource discipline when growth and relative market share are considered together?
A Taiwan Cooperative Financial BCG Matrix helps organise a multi-offering financial-services portfolio rather than assuming every banking, payment, digital or insurance-related activity should receive the same attention. The framework compares market growth with relative market share and uses the familiar Stars, Cash Cows, Question Marks and Dogs categories as analytical options. It can help examine whether digital-payment capabilities require investment to build scale, whether mature customer relationships can fund capability development, and where partnership-dependent offerings should be reviewed more cautiously. The matrix does not establish a quadrant placement without reliable market and business-unit evidence; its value is in making portfolio assumptions visible.
- Portfolio boundaries. Separate relevant service lines, customer propositions or delivery capabilities so that unlike activities are not compared as one undifferentiated financial-services business.
- Relative position. Test the evidence needed to compare growth conditions and relative market share, including the effect of network reach, digital adoption and insurance distribution economics.
- Resource workshop. Use the Excel matrix to map possible positions and the Word analysis to document assumptions, evidence gaps and discussion points behind each priority.
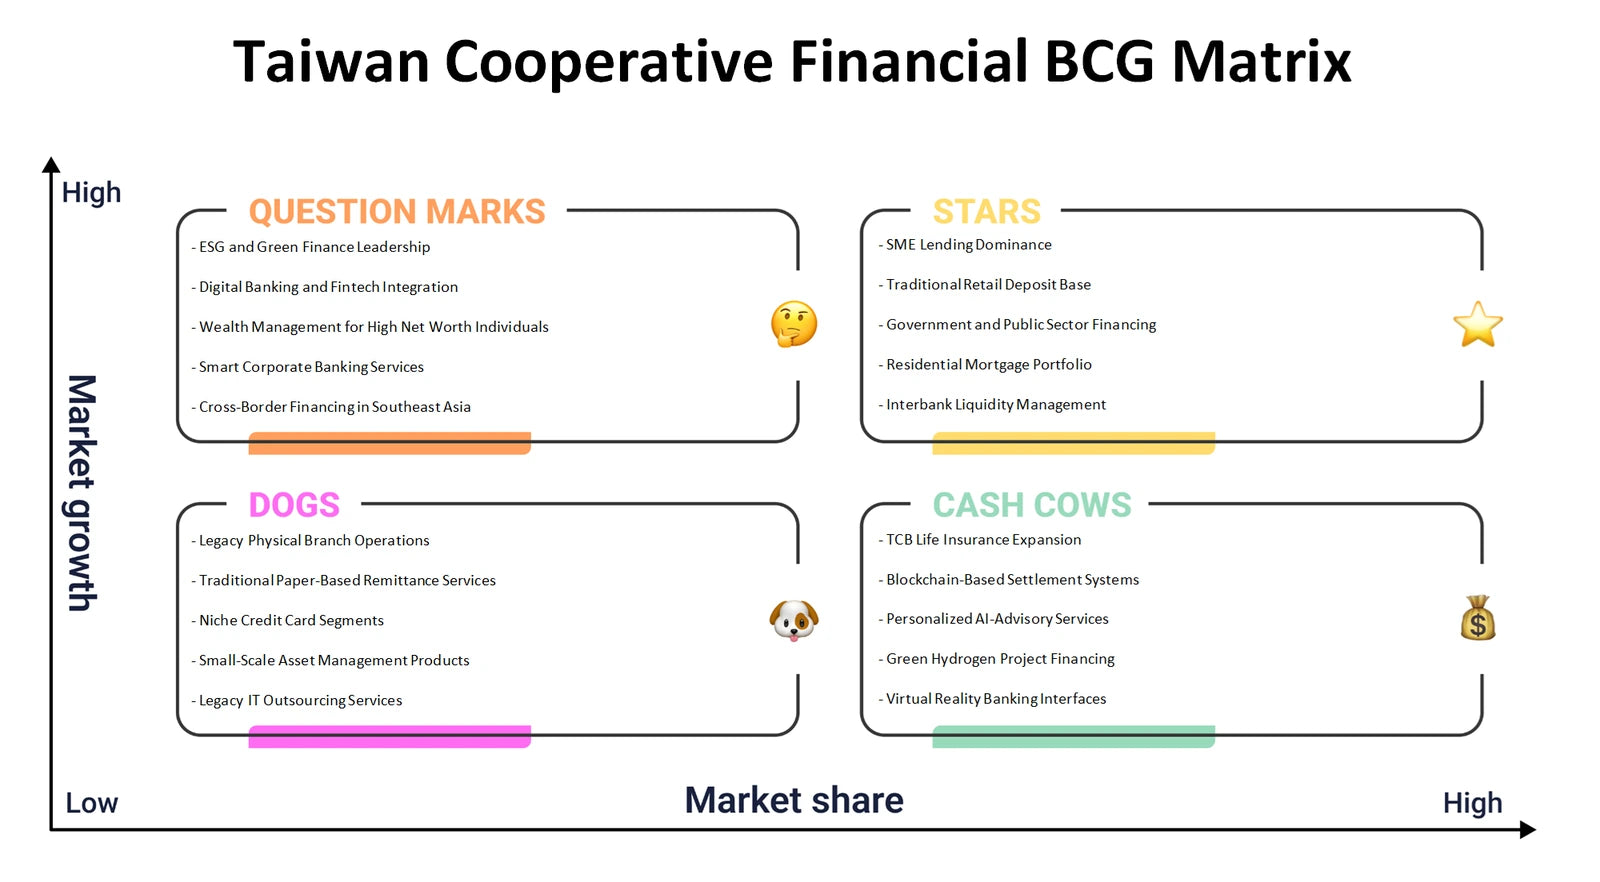
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer needs, digital delivery, financial partnerships and risk-bearing activities fit together to create value and sustainable economics?
The Taiwan Cooperative Financial Business Model Canvas connects all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. In this context, the supplied material makes digital infrastructure, cybersecurity, data analytics, payment networks, underwriters and reinsurers especially relevant themes to examine. The canvas can show how customer access through cards, payment tools or digital banking relates to trusted service delivery, operational capability and partnership costs. It also encourages careful treatment of revenue logic and risk management rather than assuming that greater digital usage automatically improves returns.
- Customer-value fit. Explore how convenience, transaction security, financial access and insurance protection may address different customer segments and relationship needs.
- Economic links. Connect revenue streams and cost structure to the resources, activities and outside partners required to operate secure financial and payment services.
- Model alignment. Complete the Excel canvas block by block, then use the detailed Word analysis to trace dependencies and challenge whether each connection is adequately supported.
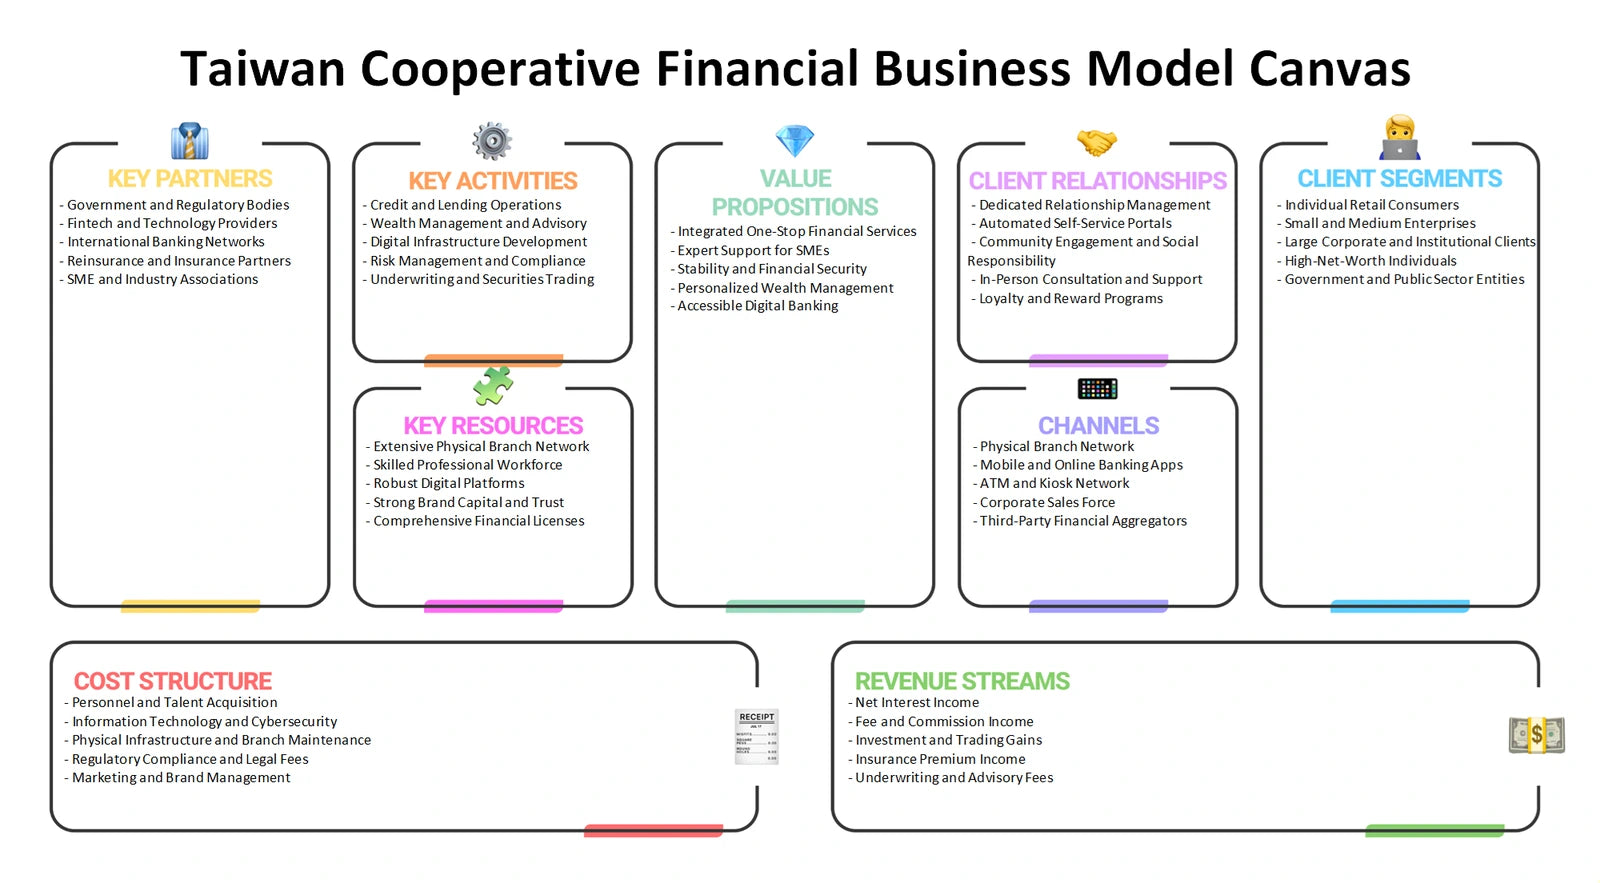
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What pressures could shape the attractiveness of the financial-services, payment and digital-banking spaces relevant to Taiwan Cooperative Financial?
Taiwan Cooperative Financial Porter's Five Forces examines industry structure rather than simply listing competitors. Rivalry can be considered across financial institutions and digitally enabled providers competing for customer relationships and transactions. Supplier power may arise where specialist technology, cybersecurity, payment-network access, underwriting capacity or reinsurance expertise is concentrated. Buyer power concerns how easily customers can compare, switch or use multiple providers. The threat of new entrants includes firms able to build trusted, compliant distribution at scale, while substitutes include alternative ways to pay, save, borrow, insure or manage financial needs. These are questions for assessment, not unsupported force ratings.
- Dependency exposure. Examine where network providers, software developers, underwriters or reinsurers may influence service quality, costs or negotiating leverage.
- Customer alternatives. Compare direct financial-service competition with substitute behaviours, including non-bank payment methods and digital tools that reduce reliance on conventional channels.
- Pressure map. Use the Excel framework to record evidence for each force and use the Word analysis to explain how the forces may interact across banking, payments and insurance-related activity.
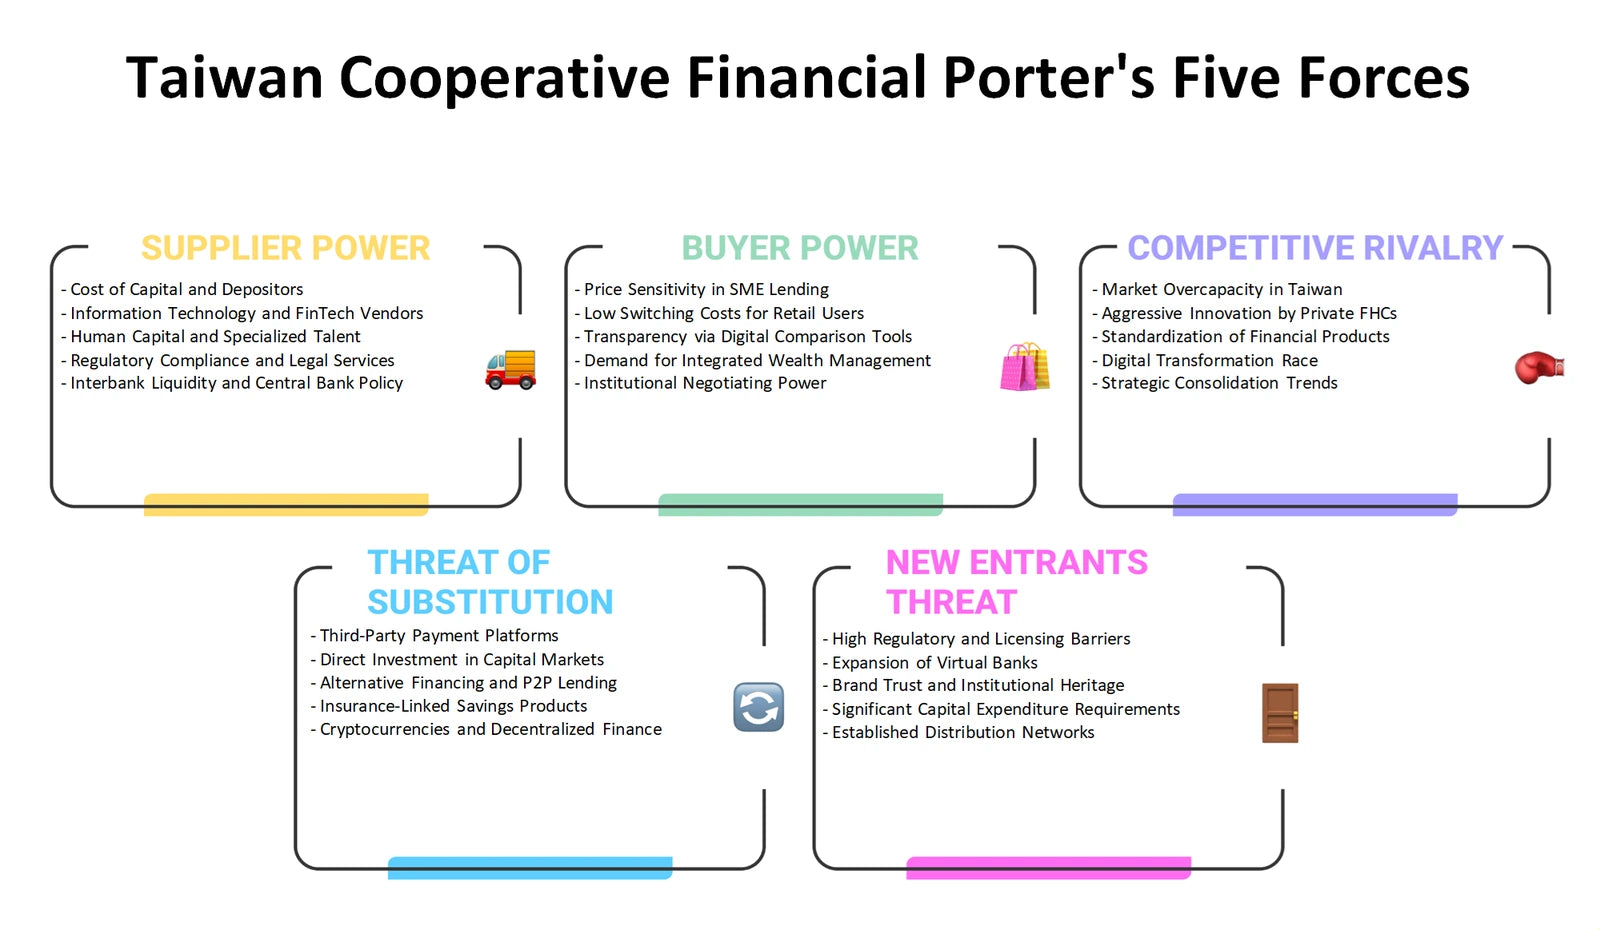
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can product design, pricing logic, customer access and communications be assessed for regulated financial and payment services?
The Taiwan Cooperative Financial Marketing Mix applies Product, Price, Place and Promotion to a service context where trust, clarity and compliance can matter as much as feature breadth. Product analysis can compare the role of digital banking capabilities, card and payment functions, and insurance-related propositions. Price considers the logic of fees, spreads, premiums or partner economics without inventing actual prices. Place examines physical, digital and partner-enabled routes through which customers access services. Promotion asks how a financial-services brand can communicate security, utility and suitability while avoiding messages that customers may misunderstand. Together, the 4Ps help turn a broad offering list into more testable customer choices.
- Service proposition. Assess whether each offer solves a recognisable customer need and whether product complexity, security requirements and service support are appropriately reflected.
- Channel coherence. Compare digital journeys, payment touchpoints and partner distribution with the customer relationships needed for trust and retention.
- Go-to-market review. Use the Excel 4Ps structure to compare propositions by segment, then use the Word analysis to capture the trade-offs between accessibility, pricing logic and responsible communication.
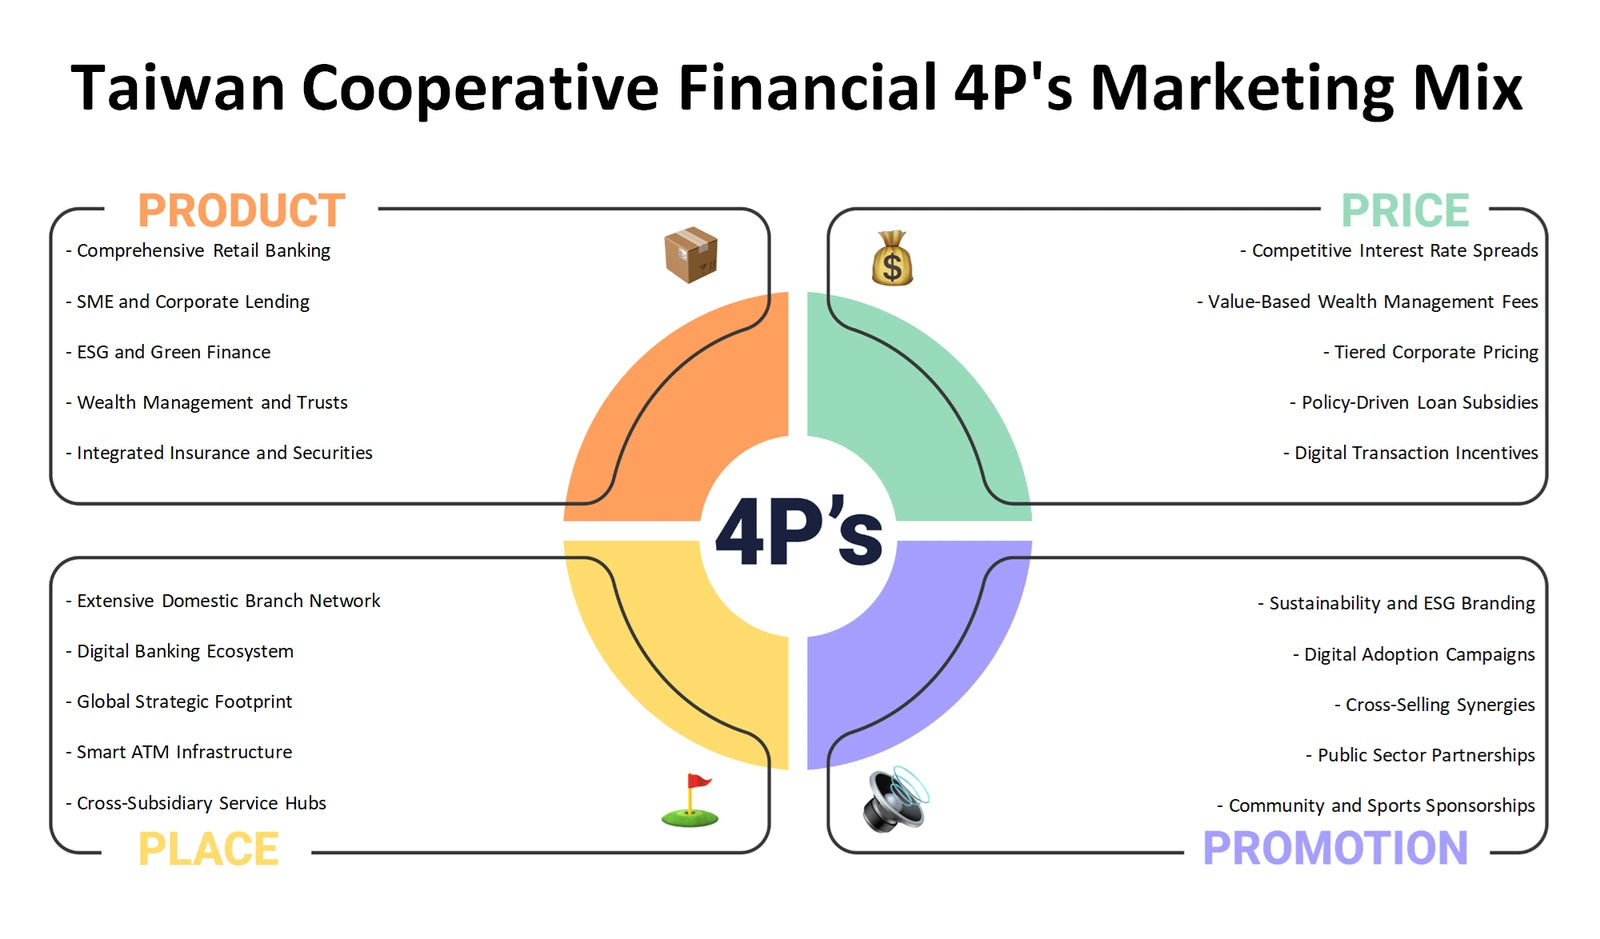
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could alter the operating environment for digital finance, payment relationships and insurance-related activity?
A Taiwan Cooperative Financial PESTLE analysis, also commonly called PESTEL, separates external conditions into Political, Economic, Social, Technological, Legal and Environmental dimensions. Political and legal questions may concern financial-sector oversight, consumer protection, data handling or payment rules; they should not be confused with claims that a particular rule has recently changed. Economic analysis can consider customer affordability, credit conditions, investment sentiment and insurance demand. Social factors include trust in digital finance and changing expectations of convenience. Technology highlights cybersecurity, analytics and platform resilience, while environmental factors can affect risk assessment, operational continuity and stakeholder expectations. The framework helps ensure that external change is considered beyond immediate competition.
- Regulatory horizon. Identify policy, legal and supervisory questions that could affect digital onboarding, transaction security, insurance distribution or third-party relationships.
- Technology resilience. Consider how reliance on advanced analytics, software development and cybersecurity capabilities changes exposure to operational and customer-trust risks.
- Scenario register. Use the Excel categories to log external signals and uncertainty, then use the Word analysis to connect each factor to potential business implications and monitoring questions.
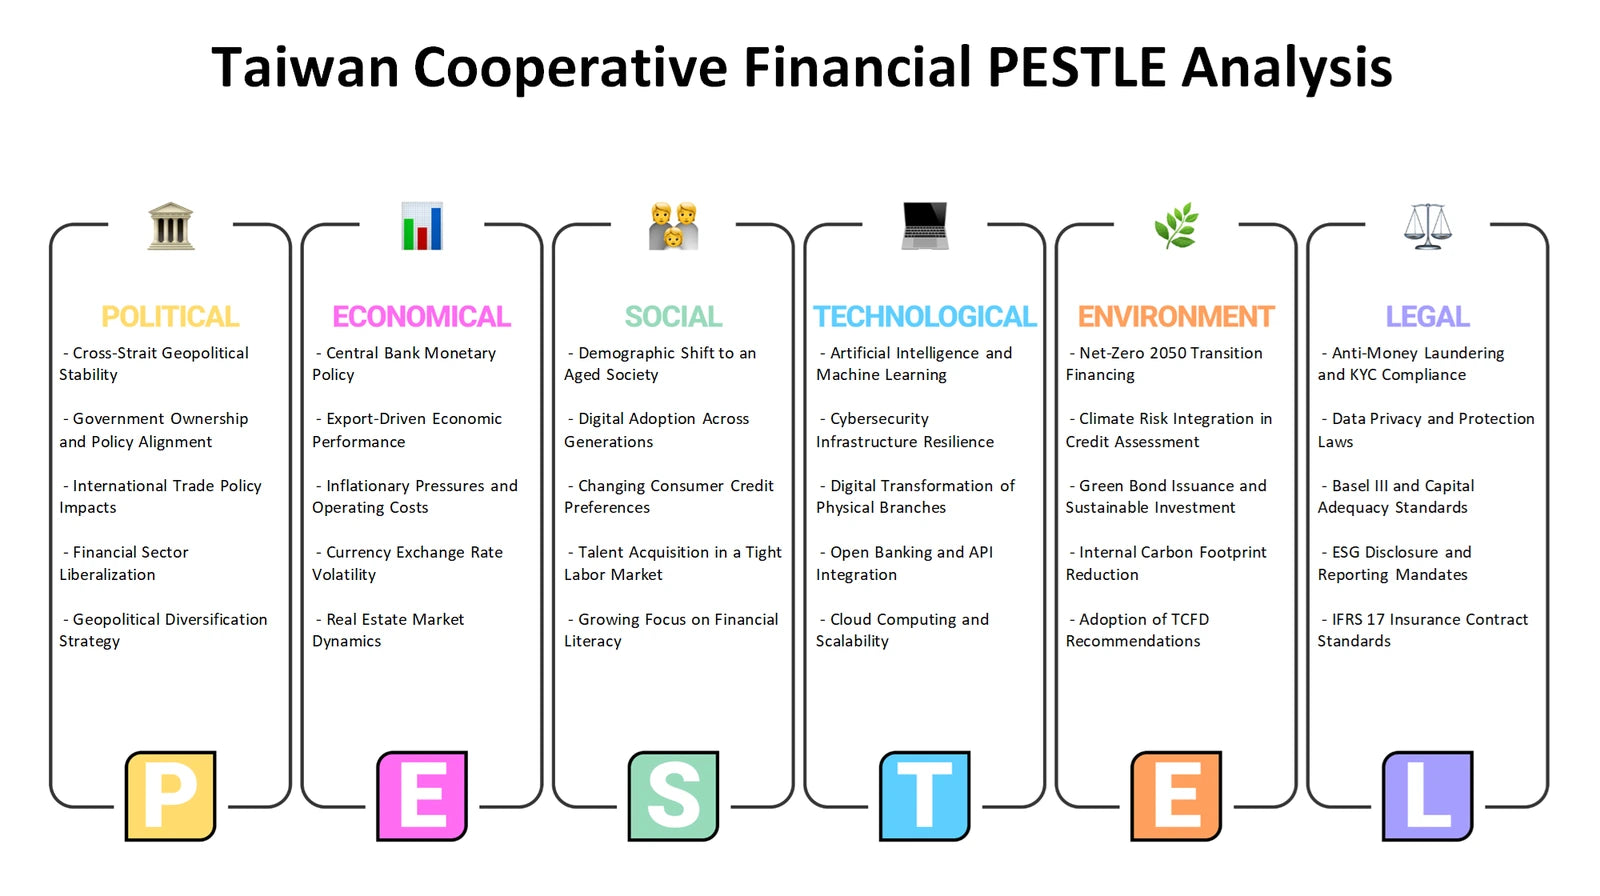
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Taiwan Cooperative Financial distinguish its internal capabilities and constraints from external opportunities and threats before setting priorities?
The Taiwan Cooperative Financial SWOT analysis provides a disciplined boundary between internal Strengths and Weaknesses, and external Opportunities and Threats. The supplied context suggests themes worth testing, such as partnership capability, digital infrastructure, cybersecurity needs, payment connectivity and specialised insurance risk relationships. Those themes are not automatic SWOT findings: the analysis should ask what the business can genuinely control, where it depends on outside parties, and how external market or regulatory conditions may change. A useful SWOT avoids treating every positive idea as a strength or every uncertainty as a threat. It instead links evidence to decisions about capability development, risk reduction, customer value and strategic focus.
- Internal evidence. Evaluate whether technology, partnership management, customer relationships and risk capabilities represent demonstrable strengths or areas requiring improvement.
- External context. Separate opportunities such as changing customer needs from threats such as cyber risk, switching behaviour, market pressure or changing compliance expectations.
- Priority conversion. Use the Excel SWOT grid to classify observations, then use the Word analysis to turn the most relevant combinations into questions for management review rather than unsupported conclusions.
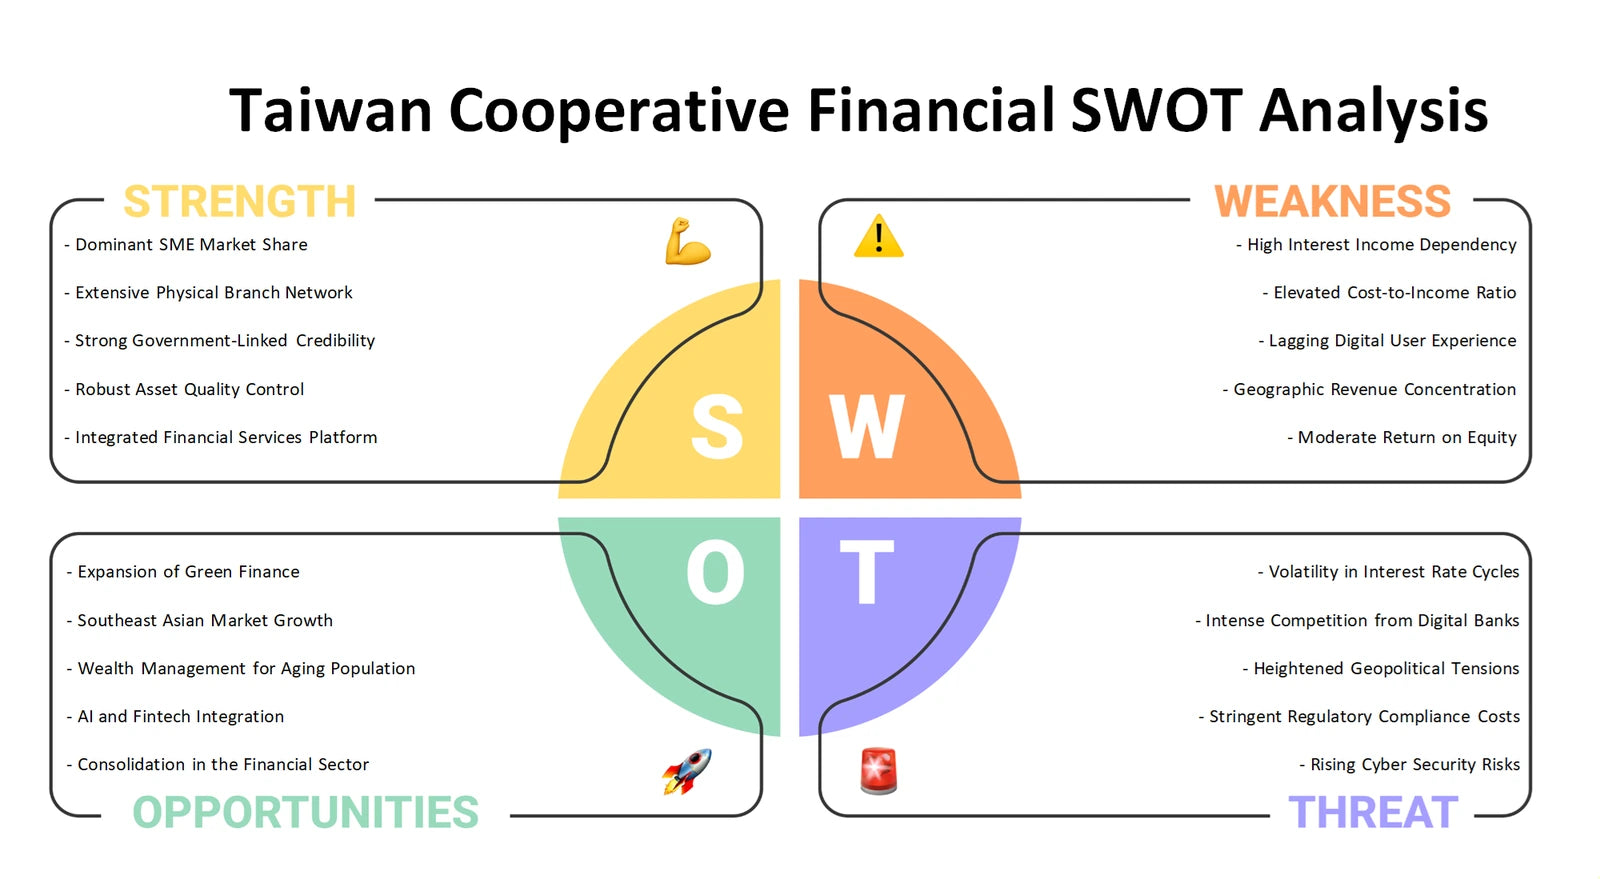
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices with operating realities
Used together, the six perspectives move from portfolio priorities and value creation to industry pressure, customer delivery, external change and capability fit. The Excel frameworks help organise evidence and comparison, while the detailed Word analyses provide company-focused context for discussing Taiwan Cooperative Financial's digital, payment and insurance-related strategic questions without assuming unverified outcomes.
Company background: Taiwan Cooperative Financial — supplied business-model context page.