

Bank of Suzhou: Banking Business and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Bank of Suzhou Strategy Analysis Bundle
Bank of Suzhou is examined here as a banking business serving borrowers and deposit customers, with particular attention to lending capacity, small and medium-sized enterprise finance, credit-risk controls and relationship-based financial services. The available product context also highlights the relevance of guarantee institutions, insurance and other risk-sharing partners in supporting credit decisions, loss management and borrower access to finance.
The key strategic questions are not simply how to grow lending, but where to allocate resources, how to balance risk and return, and how regulatory expectations affect customer access and operating economics. This bundle connects those questions across portfolio priorities, value creation, competitive pressure, marketing choices, external change and organisational capability. It provides structured Excel frameworks alongside detailed Word analysis for disciplined company-specific discussion.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which Bank of Suzhou customer propositions or service lines deserve greater management attention when growth potential must be weighed against relative market share?
The Bank of Suzhou BCG Matrix provides a portfolio lens rather than treating the bank as one undifferentiated operation. It helps compare possible lending propositions, customer niches, deposit services or fee-generating activities through the two BCG criteria: market growth and relative market share. The familiar Stars, Cash Cows, Question Marks and Dogs categories are analytical tools, not claims about Bank of Suzhou’s current positions. For a bank, this distinction matters because fast growth can absorb capital, risk capacity and relationship-management effort, while mature activities may provide steadier funding or earnings support. The framework helps turn a broad growth discussion into explicit resource-priority questions.
- Portfolio comparison. Assess potential service areas by their market-growth setting and relative competitive position without assuming any unit already occupies a quadrant.
- Capital discipline. Explore how expansion priorities may interact with credit risk, funding needs, operating capacity and the economics of serving SMEs or other borrower groups.
- Working view. Use the Excel matrix to map candidate activities, then use the Word analysis to document the evidence, assumptions and management questions behind each placement.
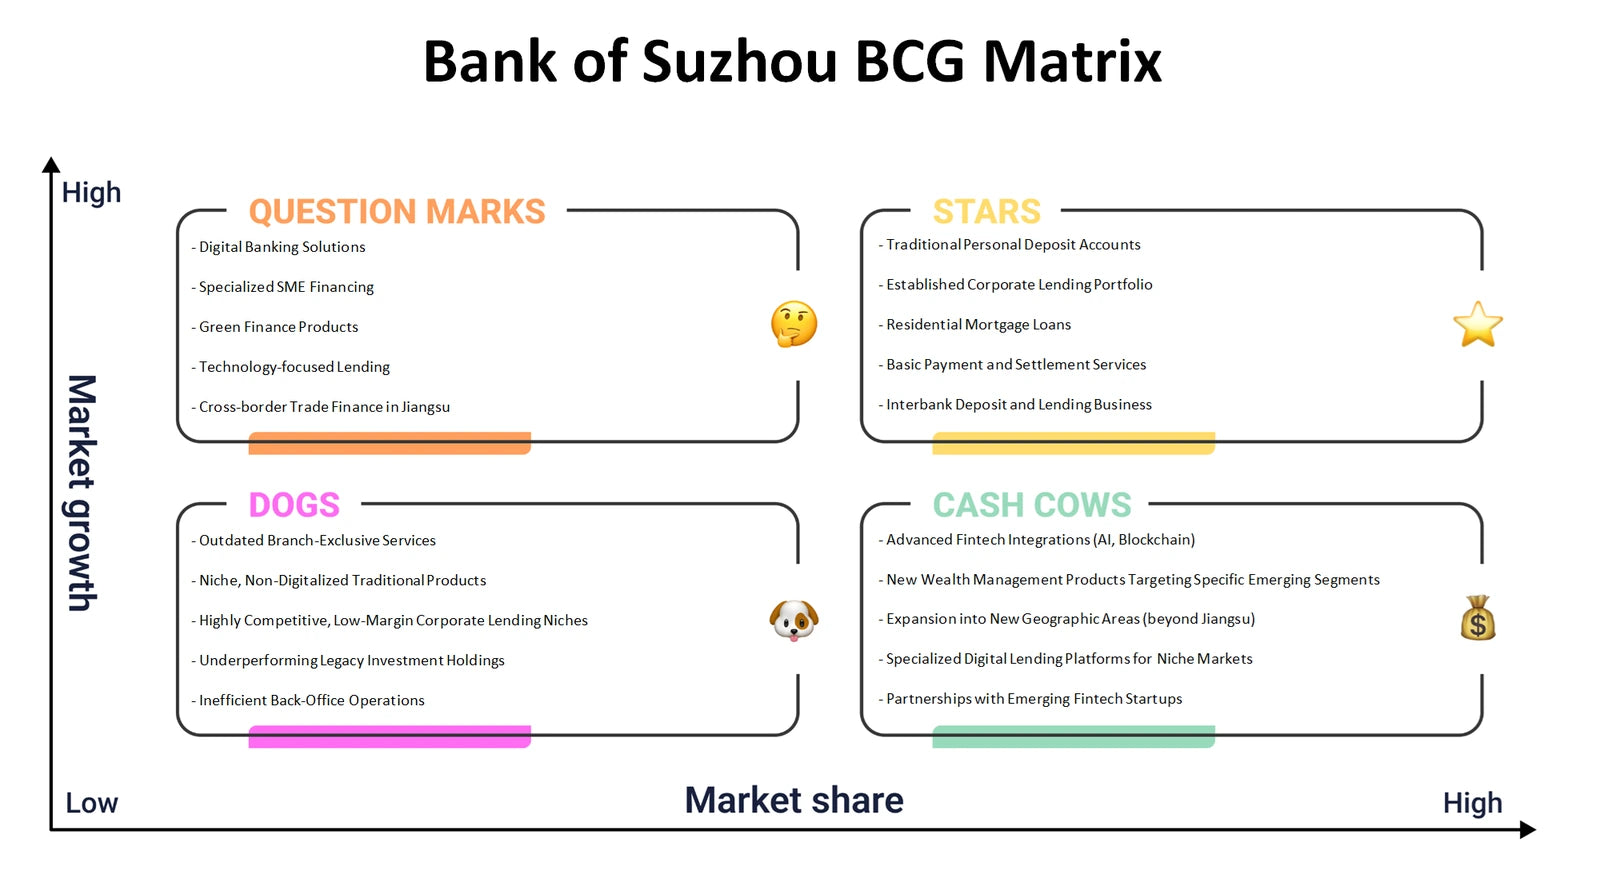
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How can Bank of Suzhou connect customer access to credit with sustainable revenue, controlled risk and the operating resources required to deliver both?
The Bank of Suzhou Business Model Canvas brings the bank’s commercial logic onto one connected page. It examines customer segments and value propositions alongside channels and customer relationships: for example, how different borrowers may access lending and receive ongoing service. Revenue streams must be considered with cost structure, because lending income, fees, risk costs and compliance expenditure cannot be viewed separately. The canvas also links key resources, key activities and key partnerships. Credit assessment, KYC and AML controls, risk management and capital planning are relevant activities to explore, while guarantee and insurance arrangements can be assessed as potential partnership mechanisms that may help distribute or protect credit exposure. The result is a practical view of how value delivery and economics depend on one another.
- Customer logic. Compare the needs of borrower and deposit customer segments with the trust, speed, advice and financing access they may value.
- Connected economics. Trace how channels, relationship management, revenue streams, resources, activities, partners and costs affect the feasibility of a proposition.
- Model alignment. Populate the Excel canvas during a workshop and use the Word analysis to explain the relationships, dependencies and unresolved business-model questions.
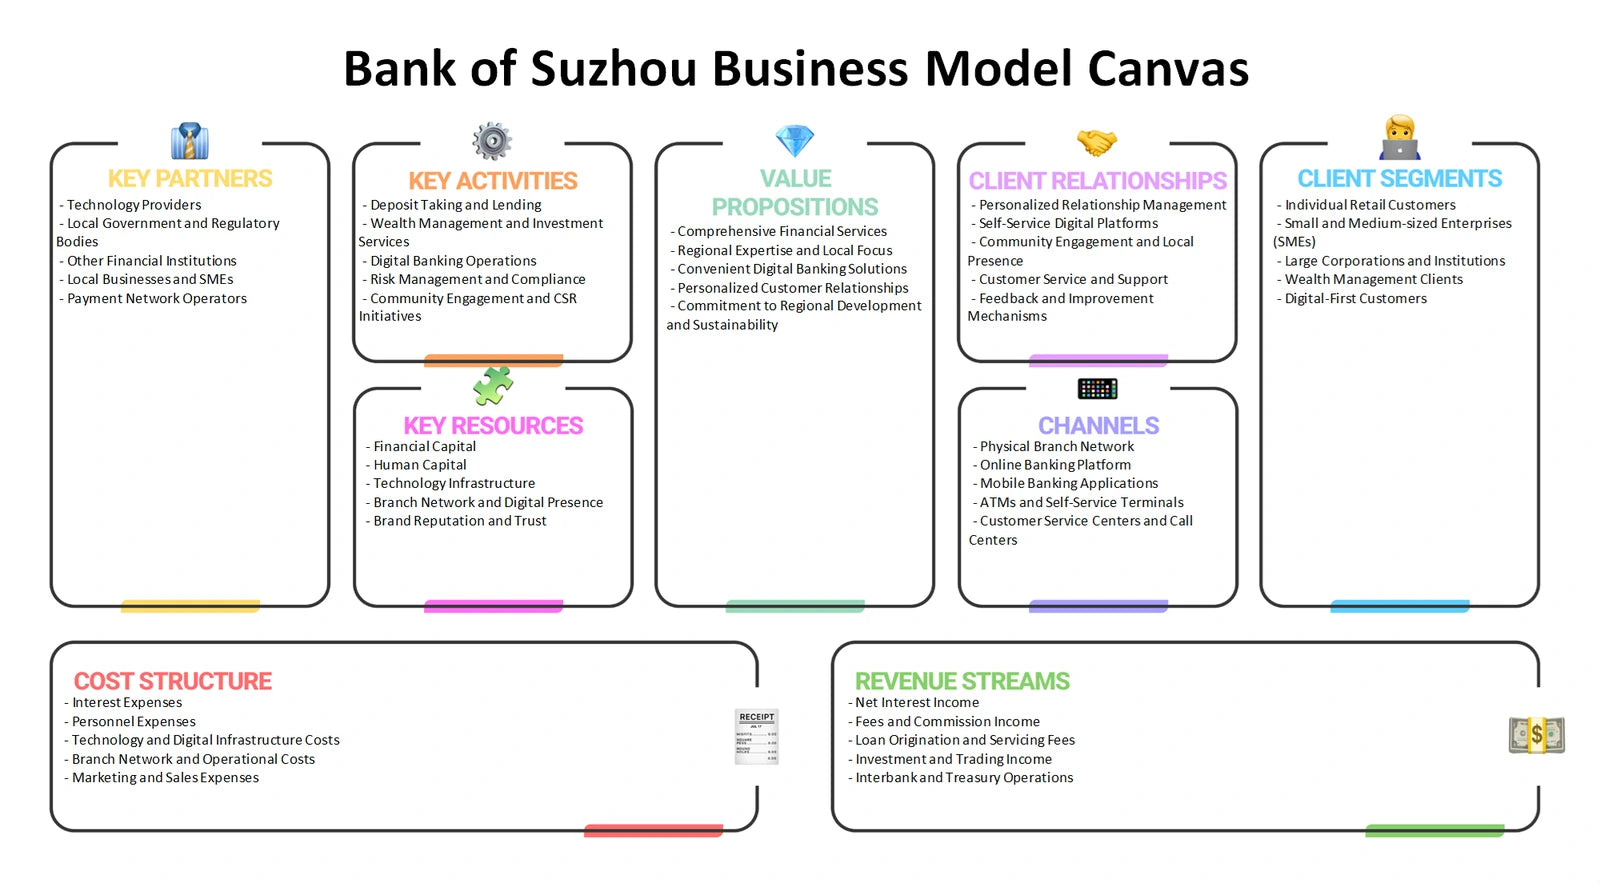
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could shape Bank of Suzhou’s ability to price credit, retain customers and earn an acceptable return after risk and compliance costs?
Bank of Suzhou Porter's Five Forces focuses on the structure surrounding a regulated banking business. Rivalry considers competition for borrowers, deposits, payments activity and relationship banking. Buyer power asks how readily customers can compare providers, negotiate terms or move balances. Supplier power is relevant to funding sources, specialised technology, data, professional services and other inputs that support operations. The threat of new entrants includes institutions or platforms capable of reaching customers with alternative financial services, while substitutes extend beyond direct banks to any credible way of meeting a financing, savings or payment need. The framework does not assign force scores; it gives users a disciplined method for considering how industry pressure can influence margins, service design and risk appetite.
- Rivalry and choice. Examine whether customer switching, comparable credit offers and deposit competition may intensify pressure on service quality or pricing decisions.
- Alternative finance. Consider substitutes such as non-bank funding, digital payment options or other mechanisms that could address customer needs outside conventional lending.
- Evidence trail. Use the Excel framework to record force-by-force observations and use the Word analysis to distinguish documented context from questions requiring further market evidence.
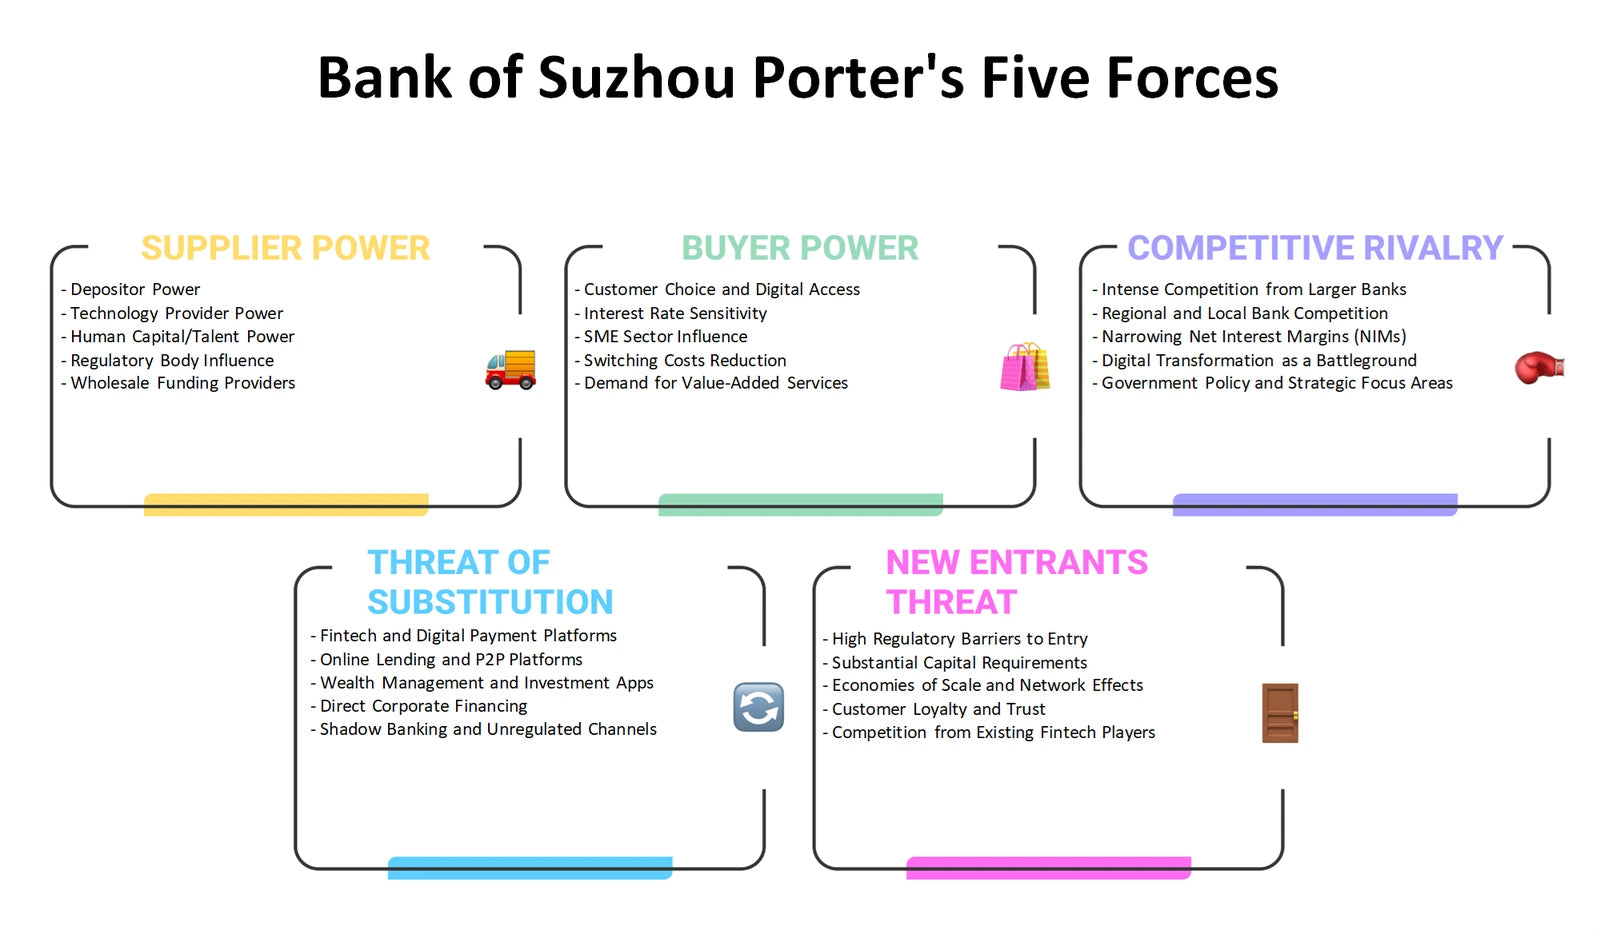
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should Bank of Suzhou assess its Product, Price, Place and Promotion choices while preserving customer trust and meeting banking-control requirements?
The Bank of Suzhou Marketing Mix translates strategy into customer-facing decisions. Product can cover lending, deposit, payment or related financial-service propositions and the service features that make them relevant to a defined customer need. Price should be studied as pricing logic rather than assumed rates: risk, funding costs, service intensity, guarantees and regulatory boundaries may all affect what is viable. Place considers how customers reach the bank and receive support, including the balance between relationship channels and available digital routes. Promotion is especially sensitive in financial services because messages must communicate suitability, transparency and trust rather than rely on unqualified promises. This 4Ps lens helps connect a commercial offer with the practical conditions of regulated banking delivery.
- Offer design. Test whether products and service features are clearly matched to the financing, transaction or savings needs of priority customer groups.
- Trustworthy communication. Review how pricing explanation, channel choice and promotional language can support informed customer decisions and relationship confidence.
- Go-to-market review. Use the Excel 4Ps structure to compare proposition options, then use the Word analysis to capture the rationale, constraints and questions for each choice.
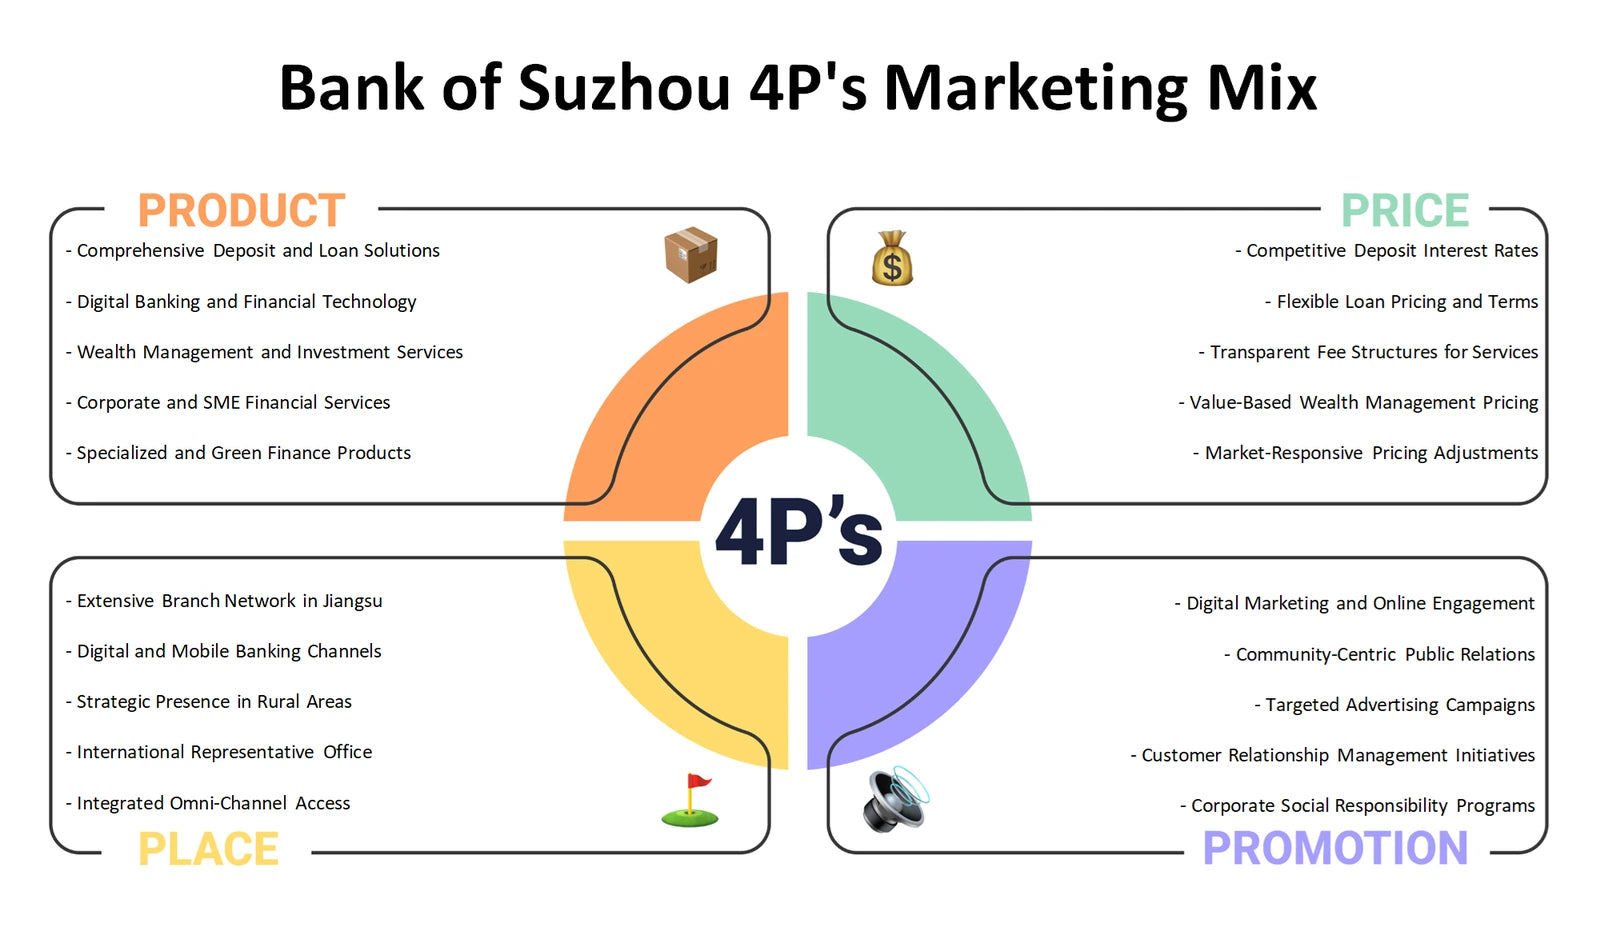
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter the demand, risk profile, cost base or supervisory expectations relevant to Bank of Suzhou?
The Bank of Suzhou PESTLE analysis, also known as PESTEL, separates external influences that management cannot control but must interpret. Political factors can include the direction of public policy and priorities affecting financial access. Economic conditions may influence borrower demand, repayment capacity, funding conditions and credit quality. Social change can affect customer expectations for convenience, trust and small-business support. Technological factors raise questions about secure digital delivery, data use and operational resilience. Legal considerations include ongoing regulatory, KYC, AML, reporting and consumer-protection obligations. Environmental factors can affect the credit implications of climate-related events, resource exposure and stakeholder expectations. These are analytical categories, not claims that a particular policy, rate or law has recently changed.
- External signals. Organise macroeconomic, supervisory, customer-behaviour and technology developments according to their possible relevance to lending and risk management.
- Scenario questions. Consider how a change in borrower conditions, compliance expectations or operational resilience requirements could affect priorities across the bank.
- Monitoring tool. Use the Excel framework to log potential drivers and impacts, with the Word analysis providing fuller context for scenario discussions and review meetings.
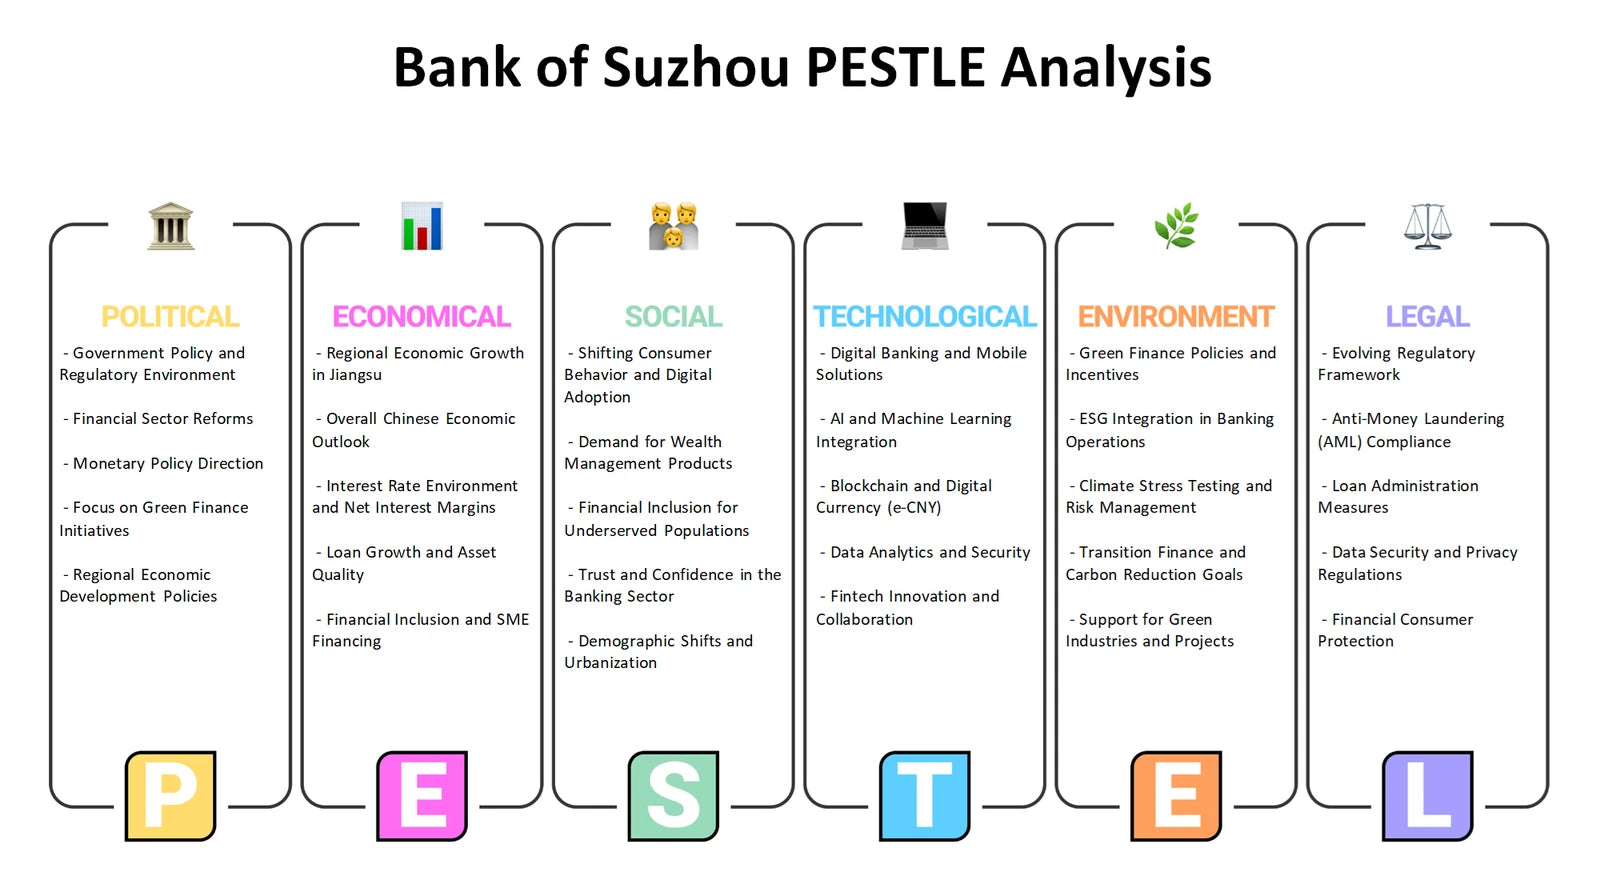
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Bank of Suzhou distinguish internal capabilities and constraints from the external opportunities and threats facing its banking model?
The Bank of Suzhou SWOT analysis closes the bundle by separating what is internal from what is external. Strengths may be investigated through capabilities such as credit assessment, customer relationships, risk governance, service delivery or partner coordination; they should not be assumed without evidence. Weaknesses are internal limitations, such as process complexity, concentration concerns, skills gaps or cost pressures that may warrant scrutiny. Opportunities are external possibilities, including unmet financing needs or new ways to improve customer access. Threats are external conditions such as changing competition, borrower stress, cyber risk or supervisory developments. This classification is valuable because it prevents a market trend from being mistaken for a capability, or an internal operational issue from being presented as an unavoidable external force.
- Clear classification. Separate internal strengths and weaknesses from external opportunities and threats before discussing priorities or responses.
- Risk-to-action links. Relate possible growth opportunities to the controls, partnerships, capital discipline and customer-service capabilities they may require.
- Decision record. Use the Excel SWOT grid to capture concise points and use the Word analysis to expand their evidence, implications and relationships with the other five frameworks.
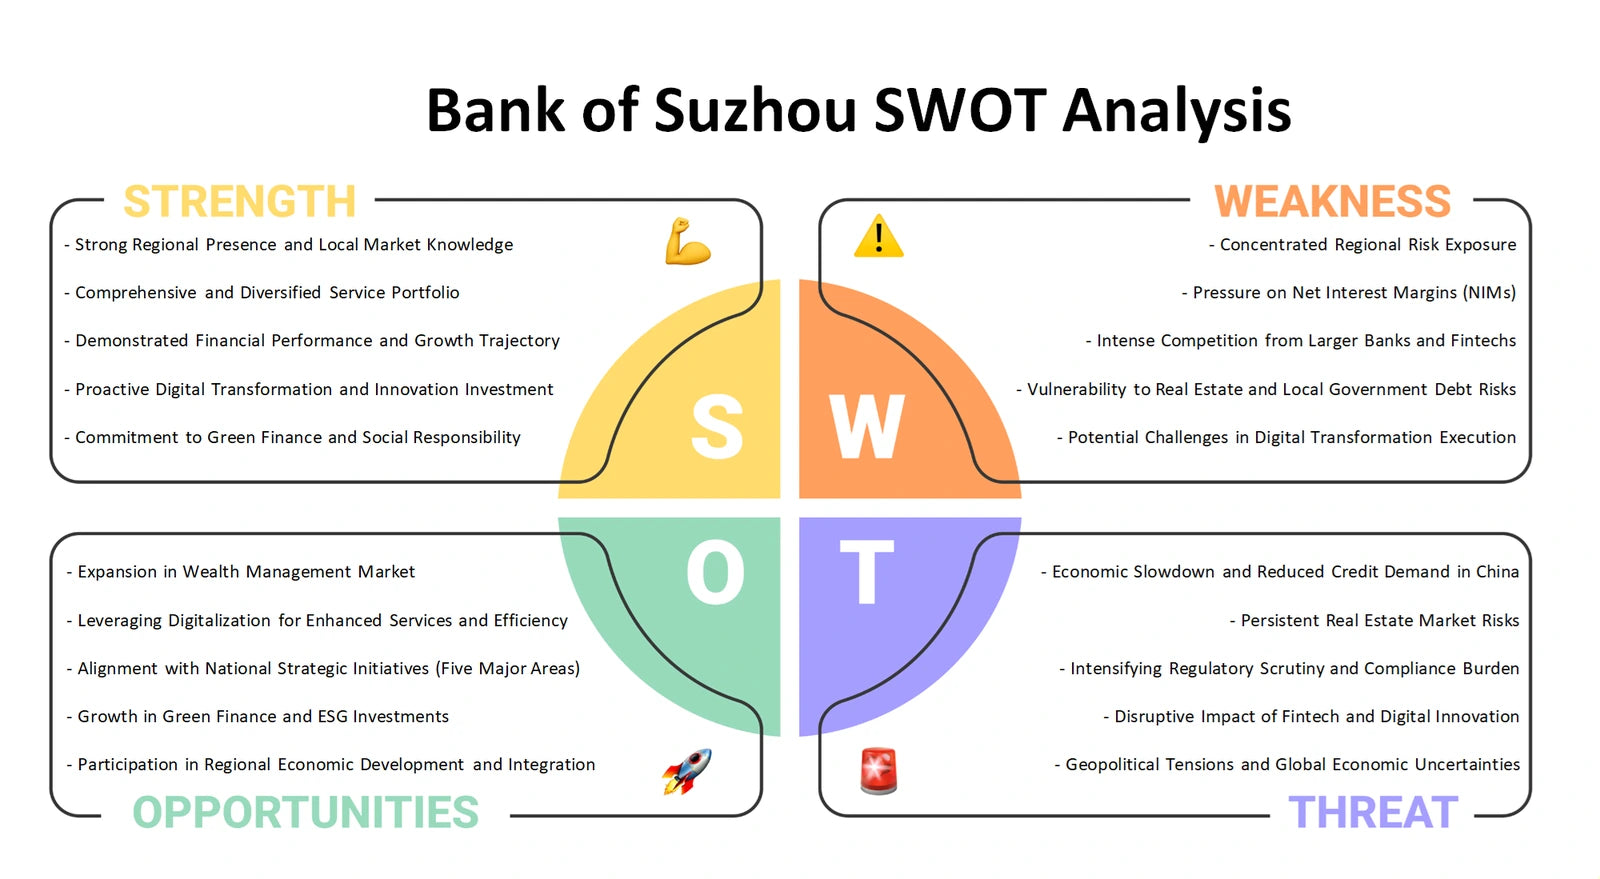
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices to banking realities
Together, the six perspectives move from portfolio priorities and value creation to industry pressure, customer delivery, external conditions and internal capability. The Excel frameworks help structure comparisons and workshop inputs, while the detailed Word analysis helps explain assumptions, evidence needs and strategic trade-offs relevant to Bank of Suzhou’s lending, risk and customer-service context.
Company background: Bank of Suzhou — product-context page for Business Model Canvas.