

S&U: Six Analyses of Lending Economics and Digital Investment

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
S&U Strategy Analysis Bundle
Here S&U means the specialist-lending business associated in the supplied company context with Advantage Finance and Aspen Bridging, rather than another organisation sharing the abbreviated name. Its model brings together vehicle finance and property bridging for borrowers, with credit assessment, loan origination, disbursement and servicing central to managing lending risk.
The available company context highlights relationships with credit-reference agencies and technology and software providers, used to inform borrower assessment, risk profiling and lending workflow. That makes portfolio allocation, risk-sensitive customer value and operating dependencies useful questions—not pre-set findings—for the six connected analyses in this bundle.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
How should S&U compare lending activities when growth prospects and relative market share may point in different directions?
An S&U BCG Matrix helps separate the portfolio question from a simple product popularity judgement. It compares market growth with relative market share across vehicle-finance and property-bridging activity, then frames whether a unit might warrant the logic of a Star, Cash Cow, Question Mark or Dog. It does not assume that either activity belongs in a particular quadrant; it provides a disciplined basis for discussing capital, underwriting capacity and management attention.
- Portfolio contrast. Compare each lending activity against the relevant market rather than treating all specialist credit demand as one market.
- Resource choices. Test where funding capacity, risk expertise and digital investment could be protected, developed, monitored or constrained.
- Working view. Use the Excel framework to map assumptions, then use the Word analysis to record the reasoning behind possible priorities.
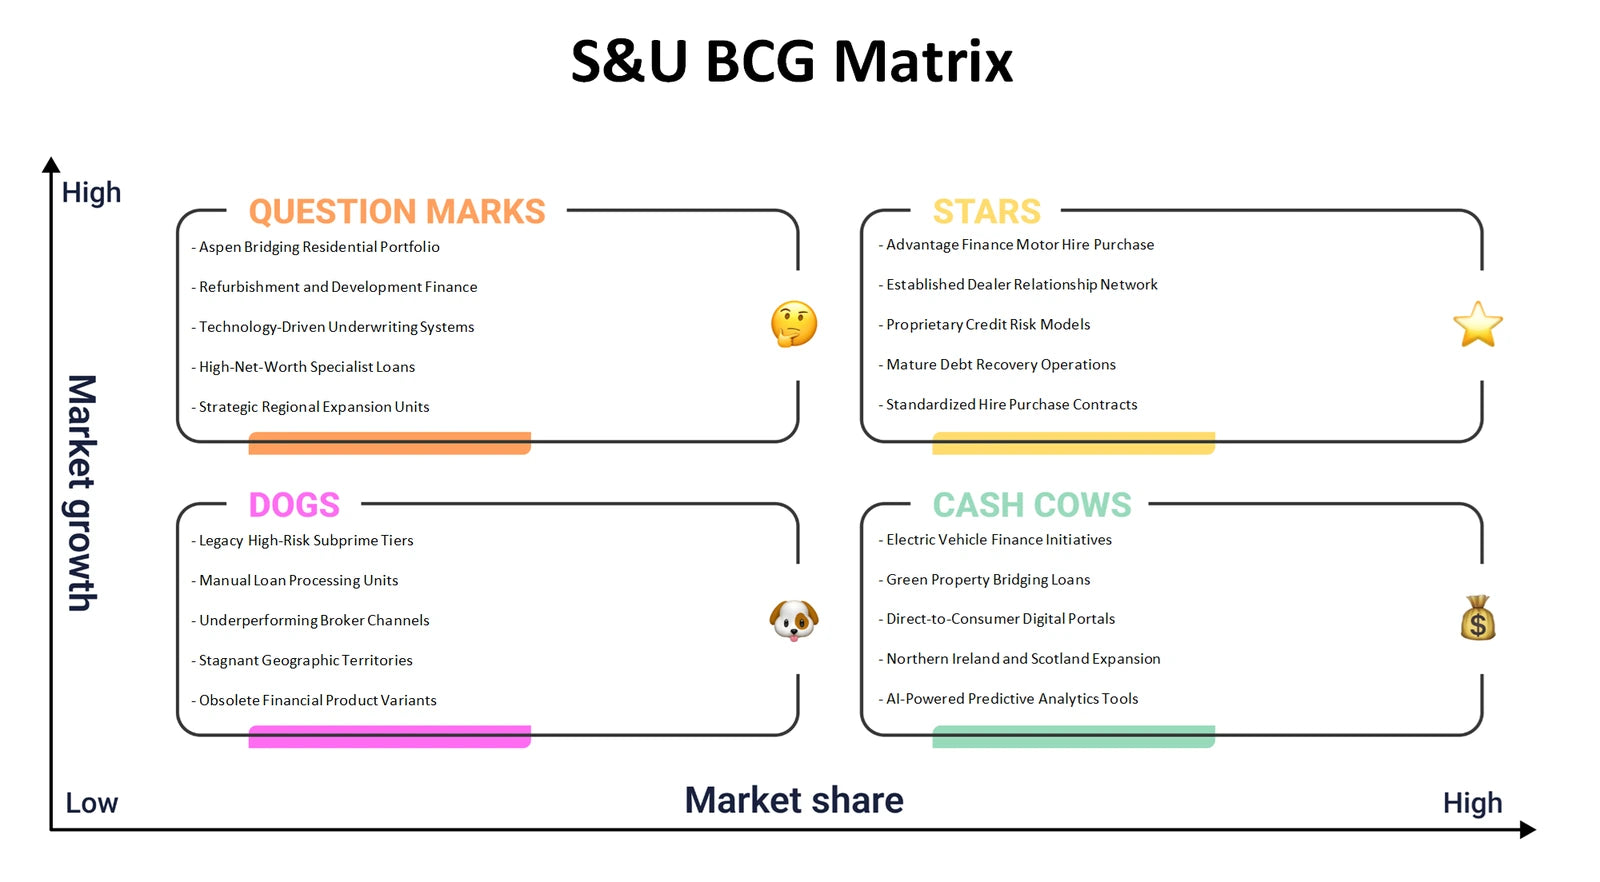
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do S&U's borrower needs, risk controls and lending operations connect to sustainable revenue and cost economics?
The S&U Business Model Canvas examines the full logic of specialist lending across all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. It is particularly useful for linking credit-reference relationships and technology providers to the borrower journey, from application and risk assessment through loan servicing. The lens helps show where a promised fast, informed lending experience depends on data, systems, people and controlled operating costs.
- Value chain. Connect borrower needs and intermediary relationships with assessment, origination, servicing and repayment activity.
- Economic links. Examine how revenue streams and cost structure depend on lending volumes, risk management and operational capability.
- Model mapping. Complete the Excel blocks systematically and use the Word analysis to explain the links and trade-offs between them.
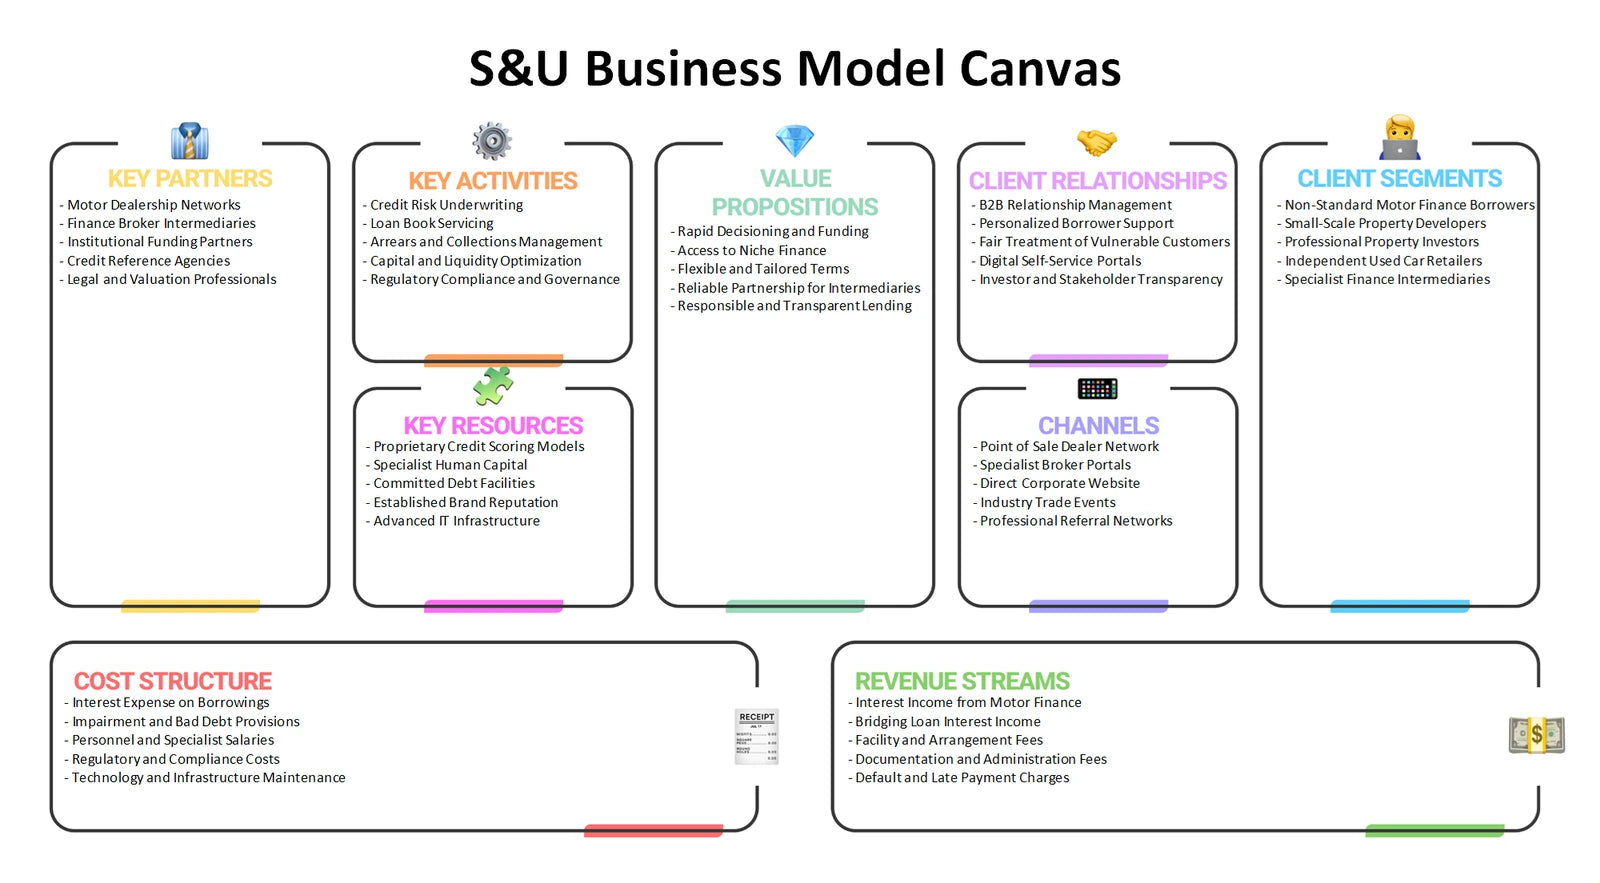
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
Which industry pressures could shape S&U's ability to lend profitably while maintaining responsible credit decisions?
An S&U Porter's Five Forces analysis considers the structure around specialist vehicle finance and property bridging, rather than claiming a force score. It tests rivalry among lenders, supplier power from important data, technology and funding inputs, and buyer power among borrowers and intermediaries. It also considers new entrants using digital lending models and substitutes such as mainstream bank credit, cash resources or other ways of financing a vehicle or property need. These pressures matter because pricing, service expectations and risk controls must work together.
- Industry pressure. Identify where competitive offers or customer switching options may place pressure on lending terms and service quality.
- Dependency review. Assess why credit data, software and other essential operating inputs can affect resilience and bargaining power.
- Evidence trail. Use Excel to compare the five forces and the Word analysis to document company-specific implications and open questions.
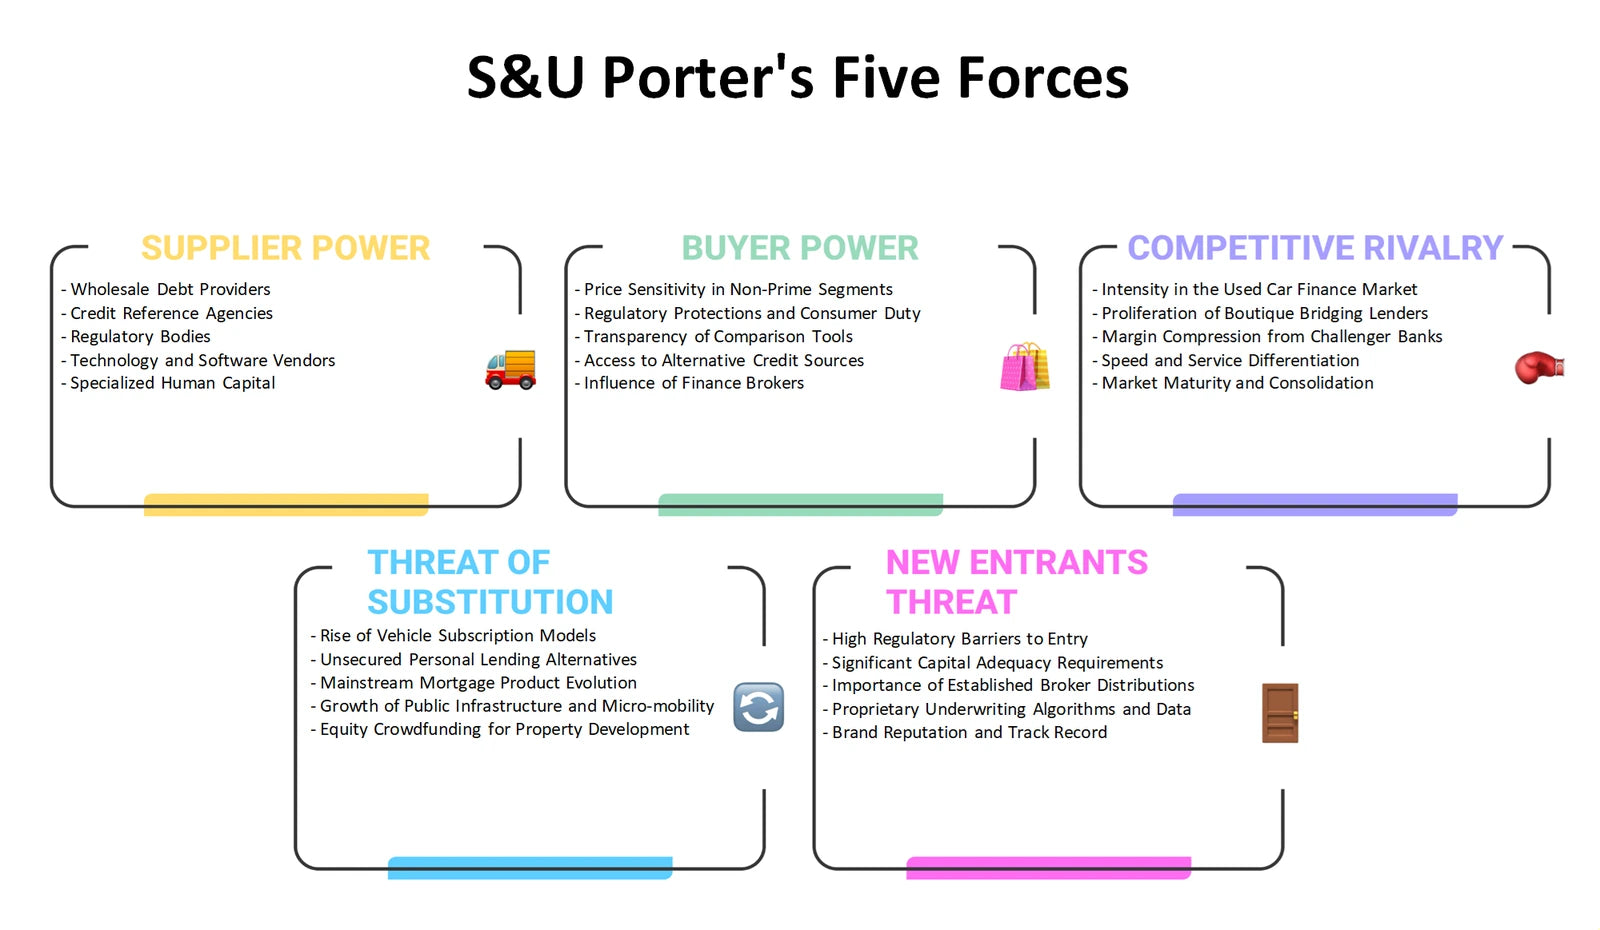
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can S&U present specialist finance clearly while balancing customer access, risk-based pricing and responsible communication?
The S&U Marketing Mix applies Product, Price, Place and Promotion to a regulated lending context. Product asks how vehicle-finance and bridging propositions address defined borrower circumstances. Price focuses on how loan terms, charges and risk are communicated and compared, rather than assuming a particular price level. Place considers the routes through which borrowers and intermediaries encounter an application process, while Promotion examines clear, appropriate messages that set realistic expectations. Together, the 4Ps help test consistency between commercial reach and responsible customer treatment.
- Offer design. Clarify the borrower problem each finance proposition is intended to address and the information needed before commitment.
- Channel fit. Compare direct digital journeys and intermediary-led routes as analytical possibilities, including their support and disclosure needs.
- Message planning. Use the Excel framework to organise the 4Ps and the Word analysis to assess alignment between proposition, communication and delivery.
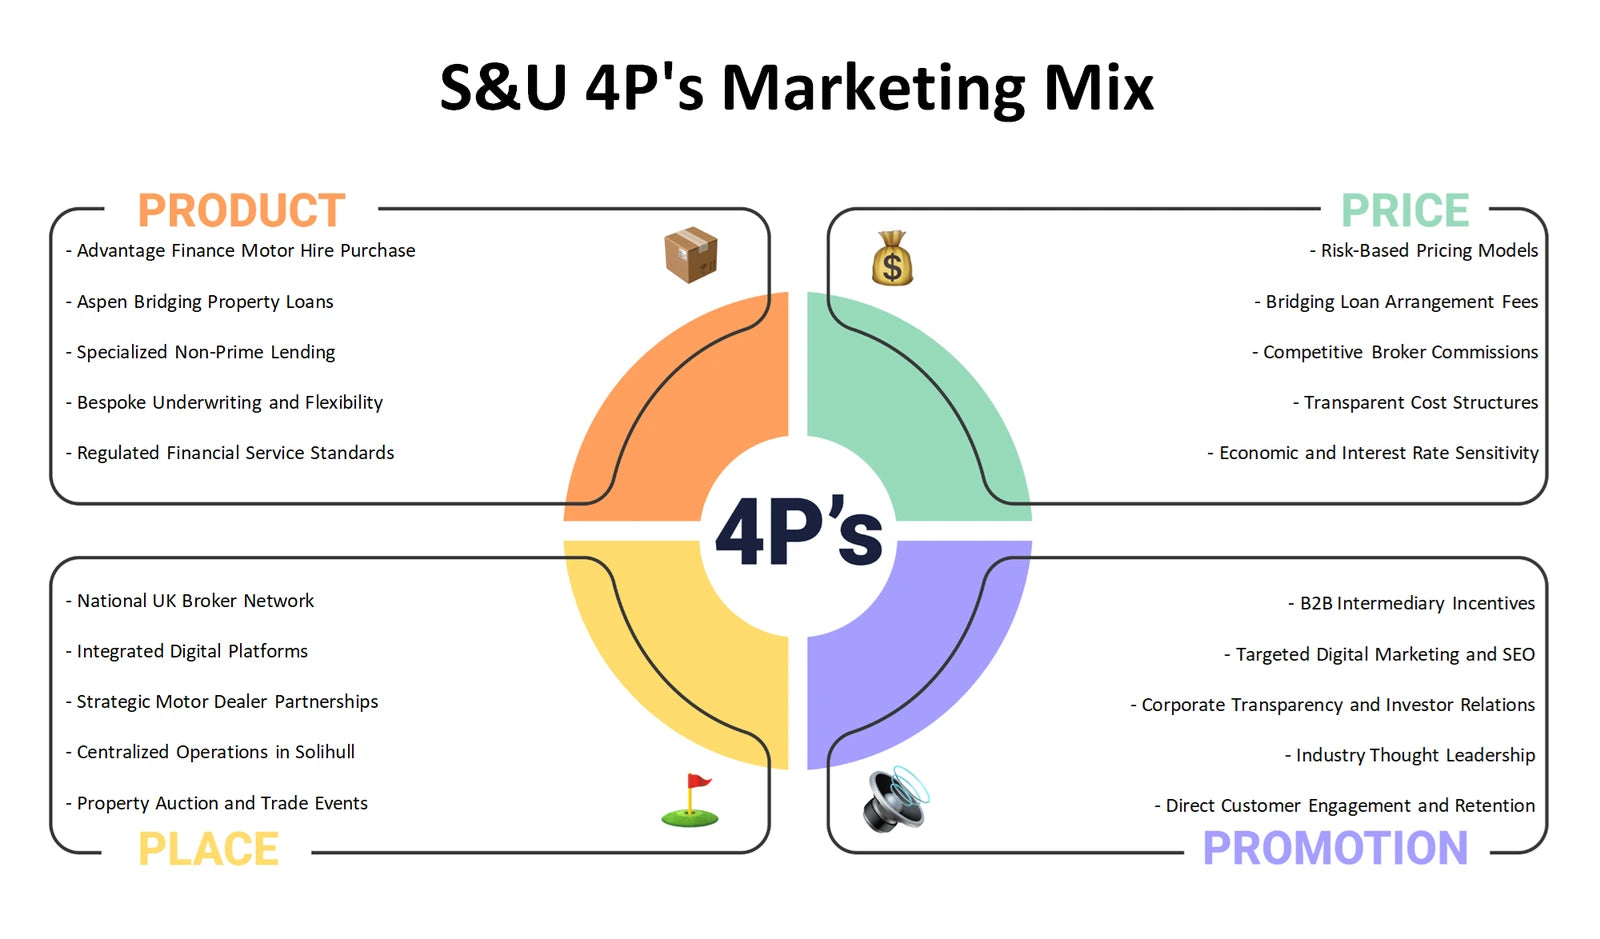
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external conditions could alter demand, affordability, compliance expectations or operating requirements for S&U?
An S&U PESTLE analysis, also commonly called PESTEL, maps external questions affecting specialist lending. Political priorities may influence financial-services policy; economic conditions can affect borrower affordability, vehicle demand and property activity. Social factors include attitudes to credit and fair treatment, while technological change raises questions around data, automation and cyber resilience. Legal considerations include consumer-credit, data and financial-crime obligations; environmental factors can affect vehicle transition and property-related decisions. The framework distinguishes these external influences from internal company capabilities and avoids presenting a possible policy change as an established fact.
- Affordability context. Track how economic scenarios could affect repayment capacity and demand without treating any forecast as an achieved outcome.
- Regulatory horizon. Organise questions around consumer protection, data handling, lending controls and compliance resources.
- Scenario use. Populate the Excel categories with monitored factors and use the Word analysis to connect them to relevant operational responses.
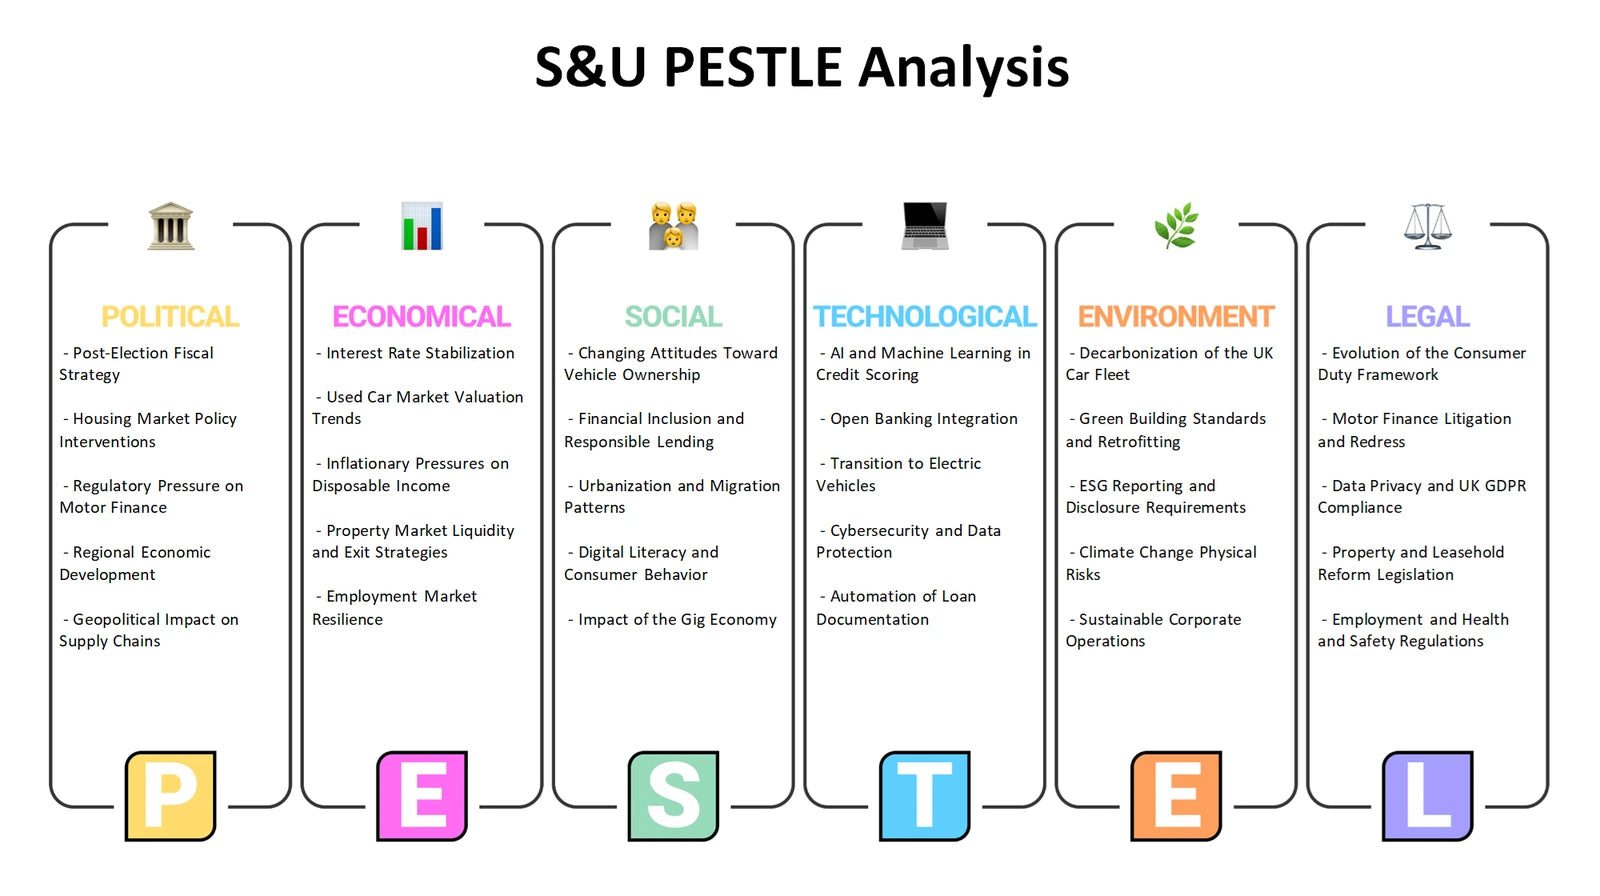
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can S&U separate its internal lending capabilities and constraints from opportunities and threats in its markets?
An S&U SWOT analysis brings the earlier lenses into a clear internal-versus-external comparison. The supplied context identifies credit-reference and technology relationships that can be examined as potential strengths in informed assessment and lending workflow. Possible weaknesses require evidence too, such as operational complexity or dependence on key inputs. Opportunities belong outside the business, including changing specialist-credit needs or better digital journeys; threats include credit deterioration, stronger competition and regulatory pressure. The purpose is not to declare these themes proven findings, but to test them with the right classification and evidence.
- Internal assessment. Separate underwriting knowledge, systems, partnerships and operational constraints from market conditions beyond management control.
- External choices. Compare potential opportunities with threats that could affect borrower demand, defaults, competition or compliance requirements.
- Action prompts. Use Excel to prioritise evidence-backed themes and the Word analysis to explain how they relate to the other five frameworks.
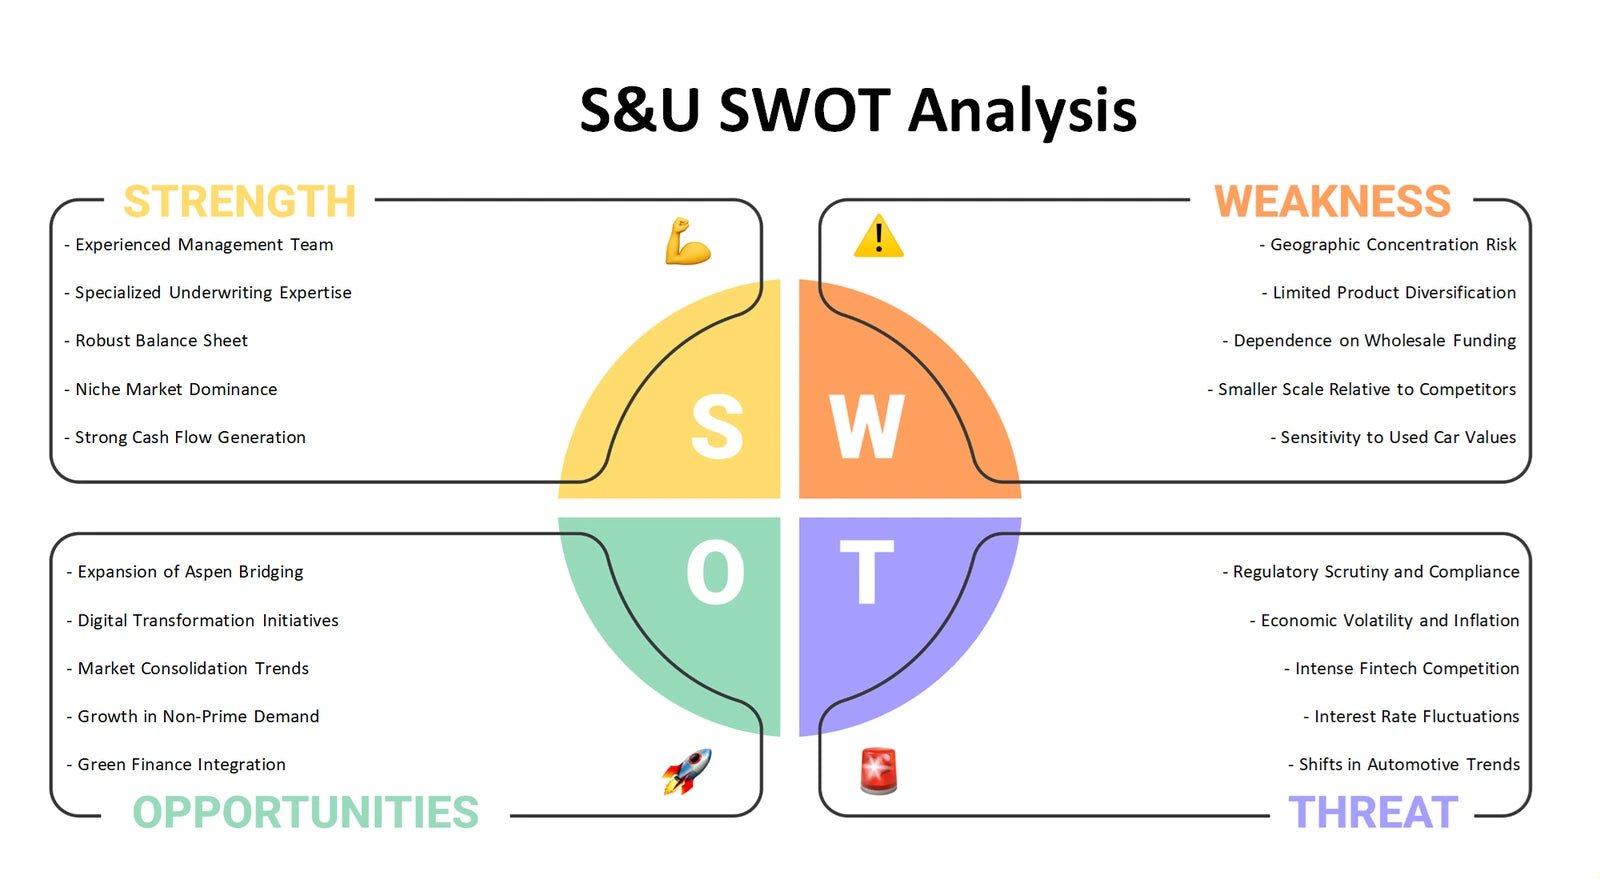
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices with lending economics
Used together, the six perspectives move from S&U's portfolio priorities and business-model mechanics to industry pressure, customer-facing choices, external change and strategic positioning. The Excel frameworks help organise comparisons and questions, while the detailed Word analysis provides fuller company-specific context for developing a more coherent view of specialist lending decisions.
Company background: S&U — matching product-context page (Pestel-Analysis.com).