

Sunlight Financial: Solar Demand and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Sunlight Financial Strategy Analysis Bundle
The available matching business description presents Sunlight Financial as a financing business serving residential solar installers and home improvement contractors. Its model centres on enabling financing offers at the point of sale, helping contractor partners introduce customer loan options through integrated tools while applications are being considered.
The same context describes funding relationships with banks, credit unions, warehouse lenders and asset-backed securities investors, alongside whole-loan sales and securitizations that can recycle capital for new originations. That makes portfolio priorities, partner economics, underwriting constraints, customer acquisition and external lending conditions practical questions for the six connected analyses in this bundle.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which Sunlight Financial financing propositions merit capital, partner attention and operating capacity under different market-growth and relative-share conditions?
A Sunlight Financial BCG Matrix helps separate analytical portfolio choices from assumptions about performance. For a point-of-sale lender, possible units to compare may include solar-oriented financing, broader home-improvement financing, contractor-facing acquisition routes or funding-supported product structures. The framework tests each unit against market growth and relative market share, then considers the implications of Stars, Cash Cows, Question Marks and Dogs. It does not assign a quadrant without evidence; instead, it creates a disciplined way to ask where growth may require investment, where mature activity may support other priorities and where complexity may outweigh strategic value. This is particularly useful when loan demand, contractor capacity and funding availability may not move together.
- Portfolio boundary. Compare business lines or partner propositions only after defining the market and the relative-share measure consistently.
- Capital discipline. Examine how growth opportunities could affect underwriting capacity, funding needs and the pace at which originated loans are recycled.
- Working view. Use the Excel matrix to organise candidate units and the Word analysis to document the market definitions, evidence gaps and priority questions behind each position.
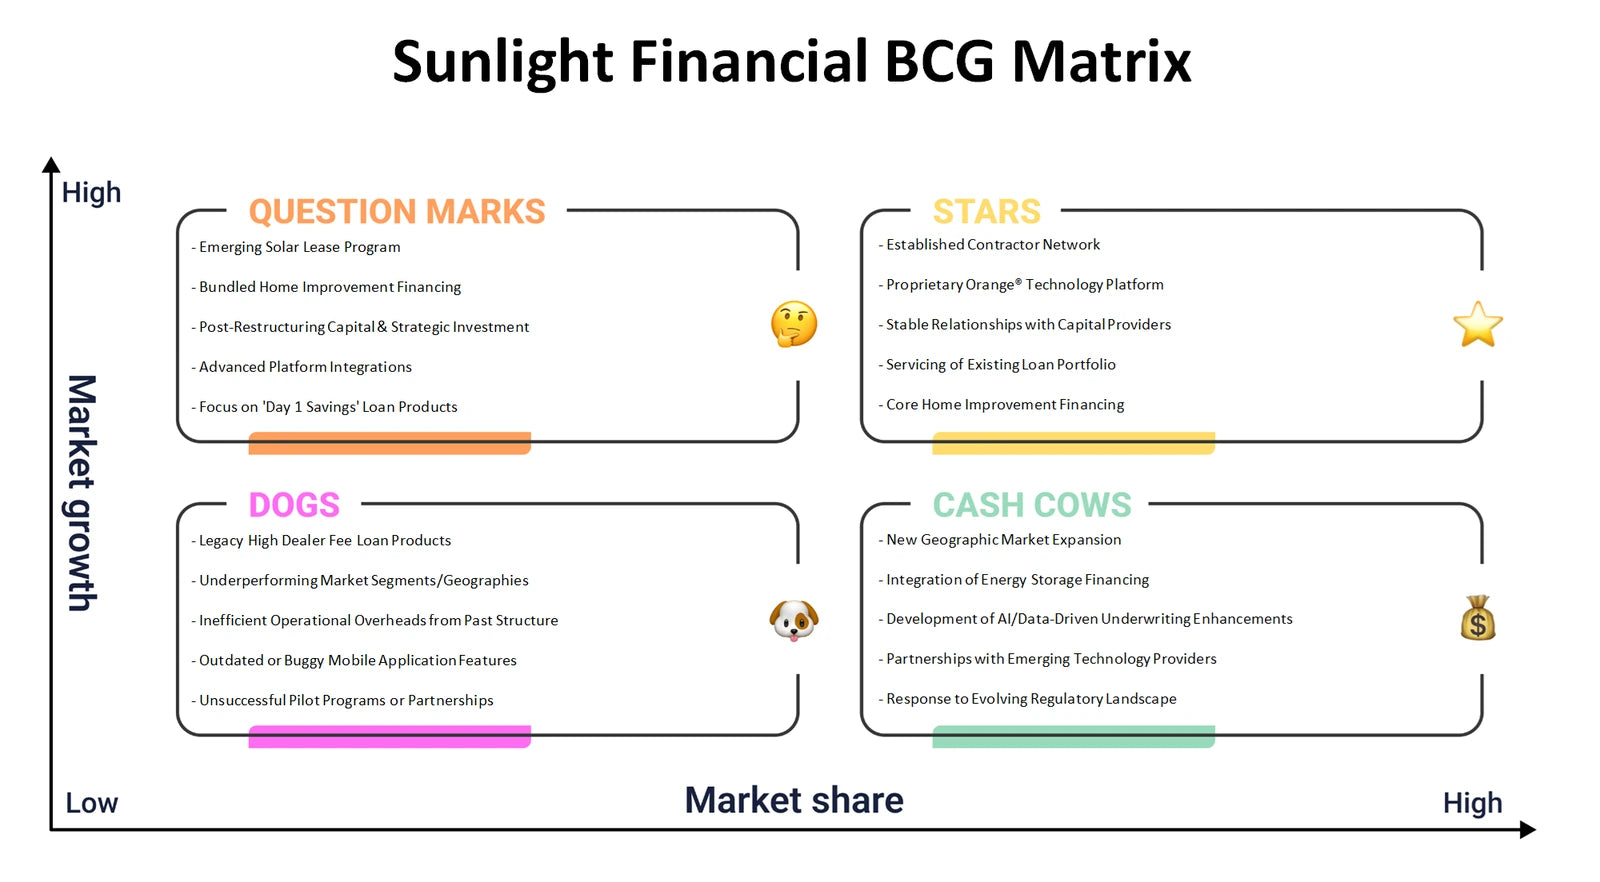
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do contractor distribution, borrower financing needs and institutional funding relationships connect to Sunlight Financial's economic model?
The Sunlight Financial Business Model Canvas maps the links between customer segments, value propositions, channels and customer relationships on one side, and revenue streams, key resources, key activities, key partnerships and cost structure on the other. The supplied business context makes contractor partners and homeowners important segments to examine, while point-of-sale financing tools are a relevant value proposition and channel question. Funding partners, loan-sale arrangements and securitization activity can then be considered as potential key partnerships and activities that influence capital use, product eligibility and economics. The canvas is valuable because it prevents an attractive borrower proposition from being assessed separately from the operational work and financing structure needed to deliver it.
- Value exchange. Trace how a contractor-facing financing offer may reduce sales friction while helping households evaluate payment options for eligible projects.
- Economic linkage. Relate origination activity and potential revenue streams to funding costs, servicing requirements, partner support and other elements of cost structure.
- Connected map. Populate the Excel canvas collaboratively, then use the Word analysis to explain the dependencies and assumptions that deserve management review.
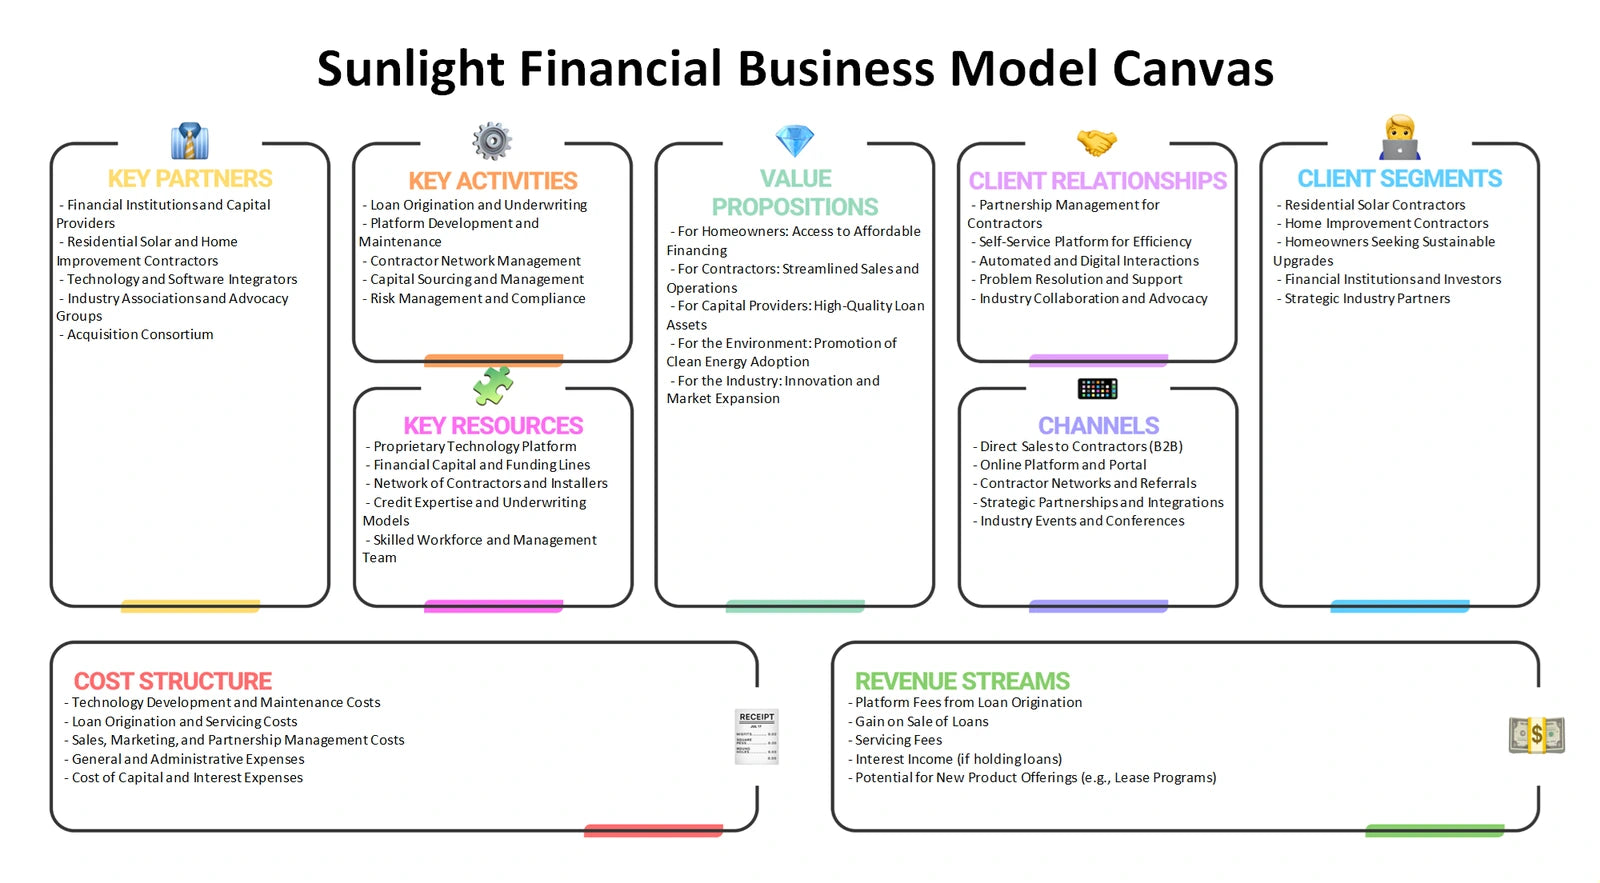
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could shape the attractiveness of installer-mediated consumer financing for residential energy and home-improvement projects?
Sunlight Financial Porter's Five Forces analysis examines the competitive environment around point-of-sale lending rather than treating loan volume as the only strategic measure. Rivalry can be considered among financing providers seeking contractor relationships and qualified borrowers. Supplier power is relevant because banks, warehouse lenders and capital-market investors may influence funding terms and product flexibility. Buyer power has two dimensions: contractors may select among financing partners, while consumers may compare affordability and alternatives. The threat of new entrants asks how technology, compliance capability and capital access affect entry. The threat of substitutes includes cash payment, savings, other consumer credit products, installer-arranged alternatives and decisions to defer a project.
- Funding leverage. Assess how the availability and terms of third-party capital may affect the economics of originated loans and product design.
- Channel choice. Consider why a contractor may value approval experience, integration, programme breadth or support in addition to financing availability.
- Pressure map. Use Excel to compare the five forces and the Word analysis to record evidence, counterarguments and implications for partner and borrower value.
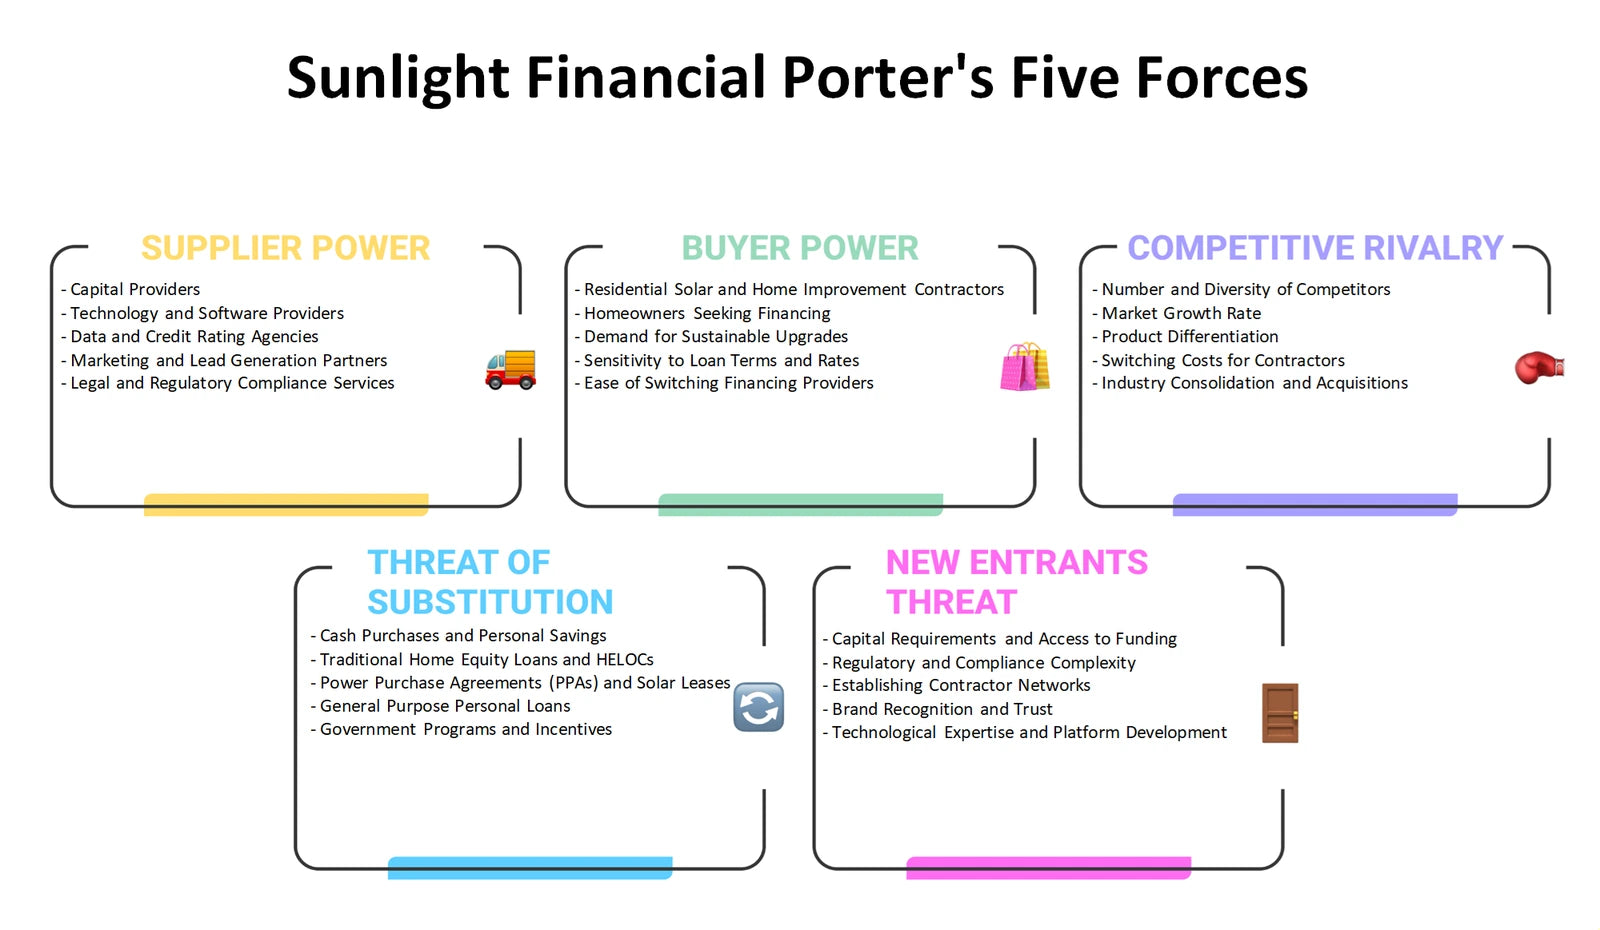
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can the Product, Price, Place and Promotion choices support a credible financing experience for both contractor partners and prospective borrowers?
A Sunlight Financial Marketing Mix frames financing as a service proposition delivered through a business-to-business-to-consumer route. Product analysis can examine the financing offer, application experience and tools used by installers or home-improvement contractors. Price concerns more than the borrower-facing cost: it also helps assess the trade-offs created by funding costs, credit risk, programme terms and partner economics. Place focuses on where the offer is introduced, especially within contractor sales conversations and integrated point-of-sale workflows. Promotion considers how the company and partners can communicate financing clearly and responsibly, with attention to customer understanding rather than unsupported campaign claims. The four Ps help align an acquisition message with the operational reality behind it.
- Offer design. Examine which service features could matter to contractors and households, including a clear path from project discussion to financing application.
- Responsible communication. Compare messaging needs with the requirement to present terms, eligibility and payment considerations in an understandable way.
- Go-to-market brief. Use the Excel framework to organise 4Ps choices and the Word analysis to turn them into discussion points for channel, product and compliance stakeholders.
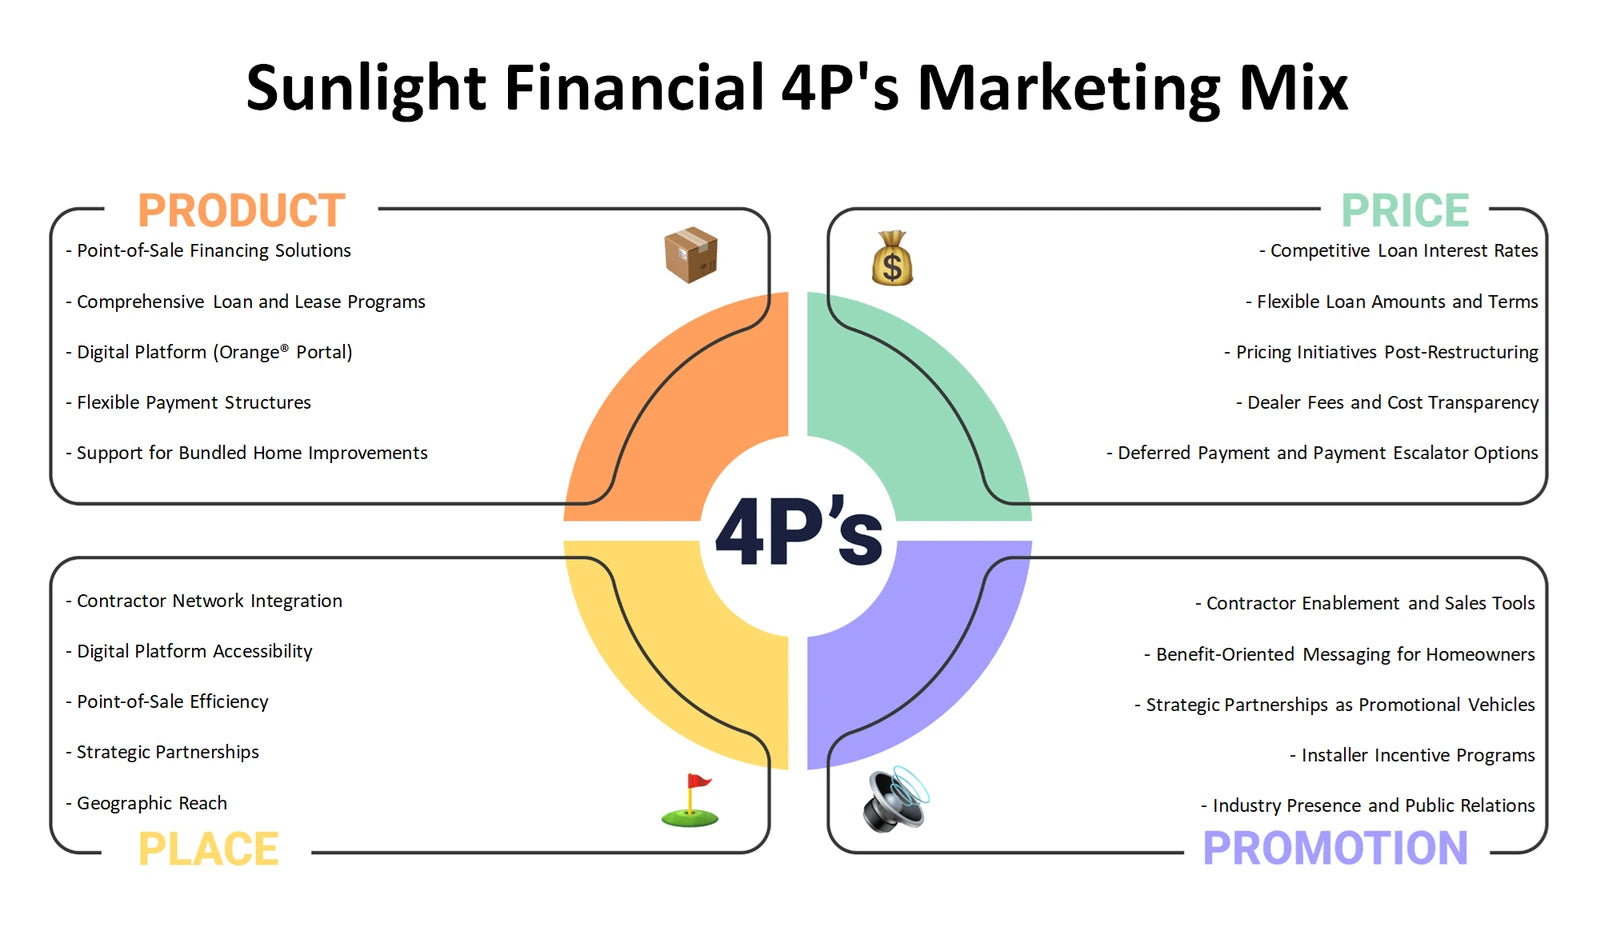
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should Sunlight Financial monitor when financing residential solar and home-improvement purchases through contractor channels?
Sunlight Financial PESTLE analysis, also commonly called PESTEL, separates external change from internal execution. Political factors can include the policy environment affecting household energy upgrades and consumer finance. Economic questions include borrowing affordability, household budgets, credit conditions and access to institutional funding. Social factors address consumer confidence, attitudes toward home investment and the importance of clear financing explanations. Technological change may affect application workflows, contractor integrations, fraud controls and data security. Legal considerations include lending, consumer-protection, disclosure, privacy and securities-related obligations where applicable. Environmental factors connect to demand for energy-related residential improvements and the broader sustainability rationale considered by some households. These are analytical categories, not claims that a specific policy or rate change has occurred.
- External signals. Distinguish changes in regulation or capital conditions from internal choices such as underwriting design and partner support.
- Scenario relevance. Explore how an economic or policy shift could influence borrower demand, contractor activity and funding capacity at the same time.
- Monitoring structure. Use the Excel template to log external factors by category and the Word analysis to explain why selected issues matter to the business model.
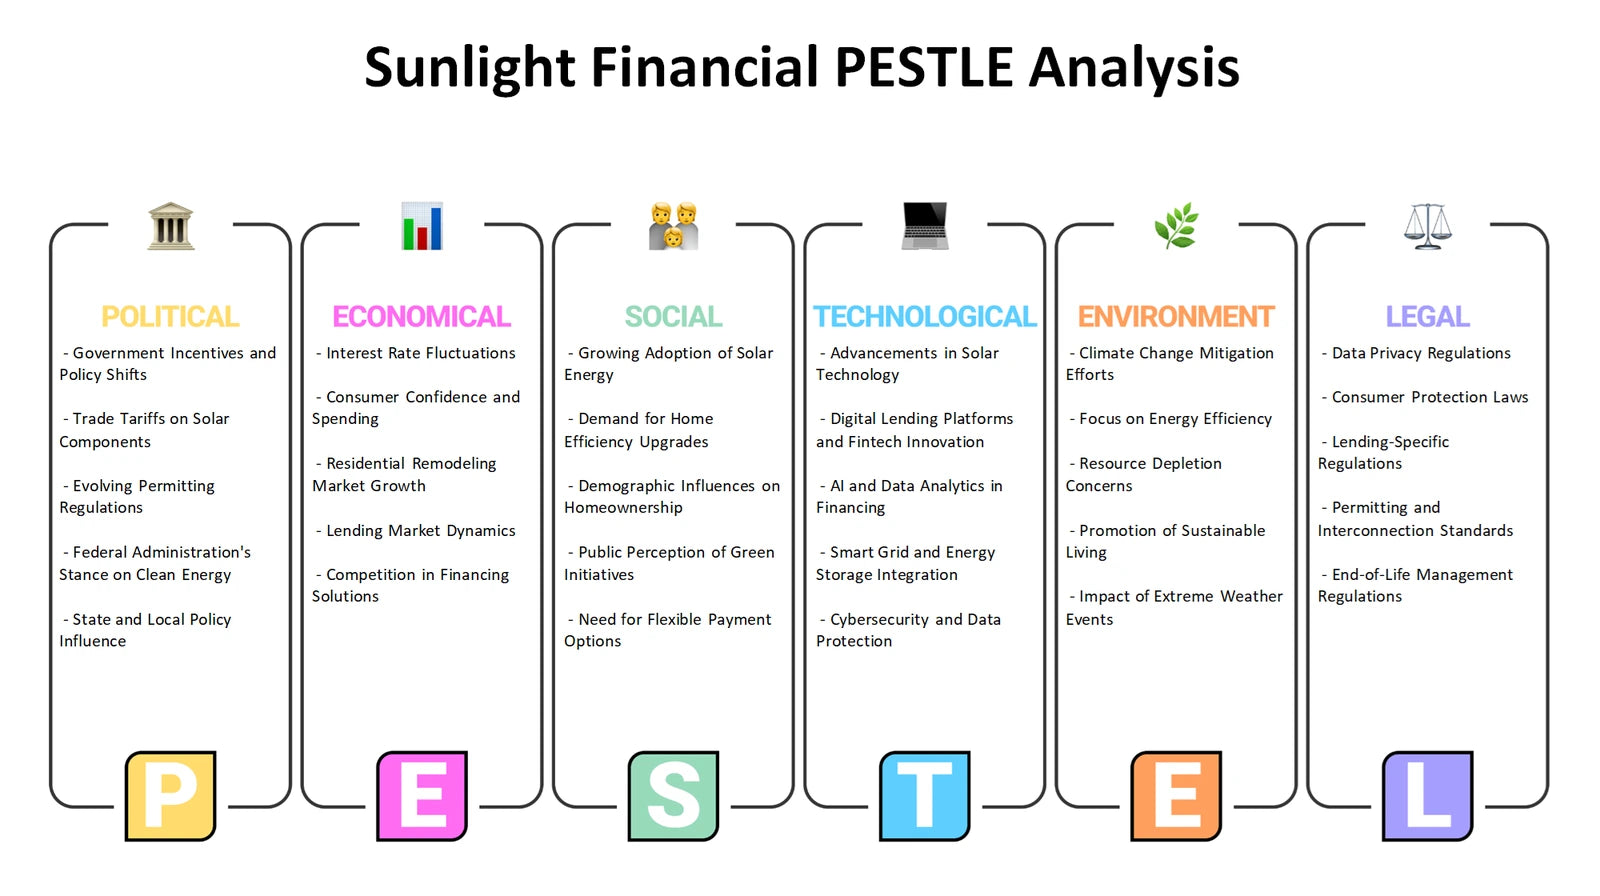
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Sunlight Financial distinguish its internal capabilities and constraints from the market opportunities and threats around its financing model?
A Sunlight Financial SWOT analysis brings the earlier lenses into a concise strategic comparison. Strengths and weaknesses are internal: for example, the ability to support contractor point-of-sale processes, manage origination operations or develop funding relationships can be evaluated as capabilities only where evidence supports them. Opportunities and threats are external: demand patterns for home projects, financing alternatives, capital-market conditions and regulatory change belong on this side of the framework. The distinction matters because a favourable market is not automatically a strength, and an internal operational dependency is not an external threat. Rather than asserting a finished verdict, the analysis helps test how identified capabilities may be used to pursue an opportunity or reduce exposure to a risk.
- Classification discipline. Keep execution capacity, systems and partner-management capability separate from external demand, policy and competitive conditions.
- Strategic fit. Test whether a possible strength could address a defined opportunity, or whether a weakness could heighten exposure to a particular threat.
- Decision record. Use the Excel SWOT grid to prioritise themes and the Word analysis to capture the rationale, evidence required and possible management responses.
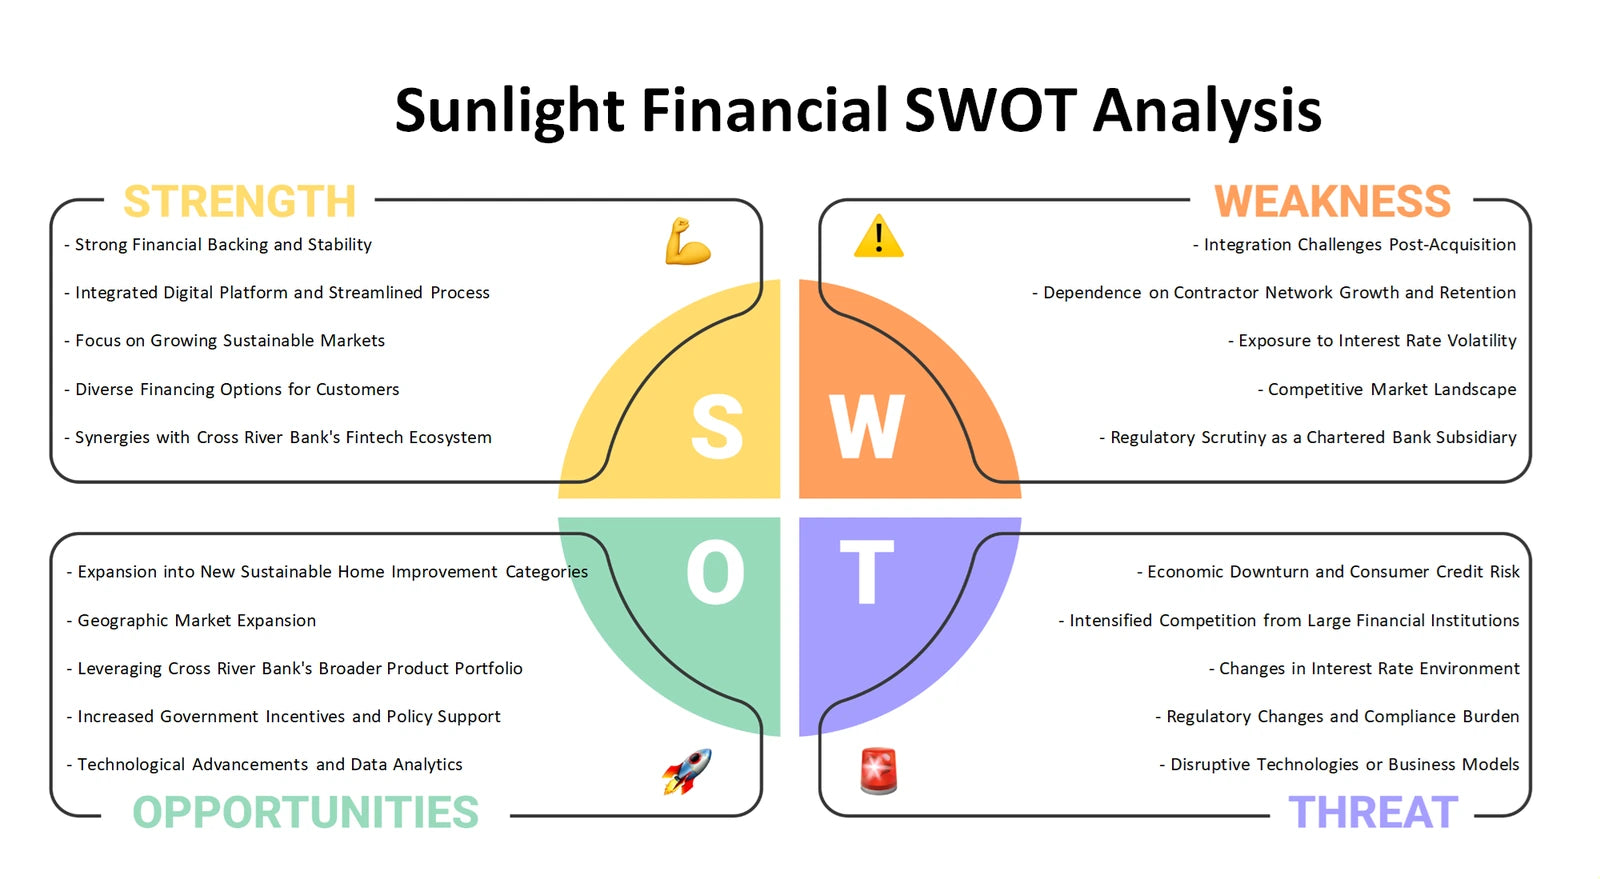
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a more connected strategic view of Sunlight Financial
Together, the six perspectives move from portfolio choices and business-model relationships to competitive pressure, channel design, external change and strategic fit. The Excel frameworks give teams structured places to compare issues, capture assumptions and organise priorities, while the detailed Word analysis provides company-specific context for discussion. Used together, the materials can help develop more disciplined questions about contractor distribution, borrower value, funding dependencies and the trade-offs involved in scaling a point-of-sale financing model.
Company background: Sunlight Financial — PESTLE Analysis product-context page.