

Storebrand: Insurance Business and Distribution – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Storebrand Strategy Analysis Bundle
Storebrand is a Norwegian financial services company serving the Nordic market with long-term savings, pension and insurance offerings. Its business connects individual customers, employers and other organisations with products designed to address protection, retirement saving and longer-term financial needs.
The Storebrand Group describes itself as a Nordic participant in long-term savings and insurance. That context makes portfolio choices, partner-enabled distribution, regulated customer communication and risk management particularly relevant questions. This bundle helps examine those questions through six connected strategy frameworks without assuming unverified results or recommendations.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which savings, pension and insurance activities deserve different levels of investment, protection or review as markets and relative positions change?
A Storebrand BCG Matrix helps organise a portfolio discussion around market growth and relative market share rather than treating every financial-services offering alike. The framework can compare mature customer needs with faster-changing opportunities in retirement saving, insurance distribution or related financial solutions. Its Stars, Cash Cows, Question Marks and Dogs categories are analytical tools: they help frame resource-priority questions, not declare that any Storebrand business belongs in a particular quadrant. For a company balancing long-term customer commitments and capital-sensitive insurance activities, the distinction between cash generation, growth investment and selective rationalisation can be especially useful.
- Portfolio logic. Compare offerings by their market conditions and relative competitive position before discussing where management attention may be needed.
- Capital discipline. Consider how expansion ambitions interact with customer obligations, underwriting capacity and the need to sustain established savings and insurance services.
- Structured comparison. Use the Excel framework to map possible portfolio inputs, then use the Word analysis to interpret the assumptions and strategic trade-offs behind them.
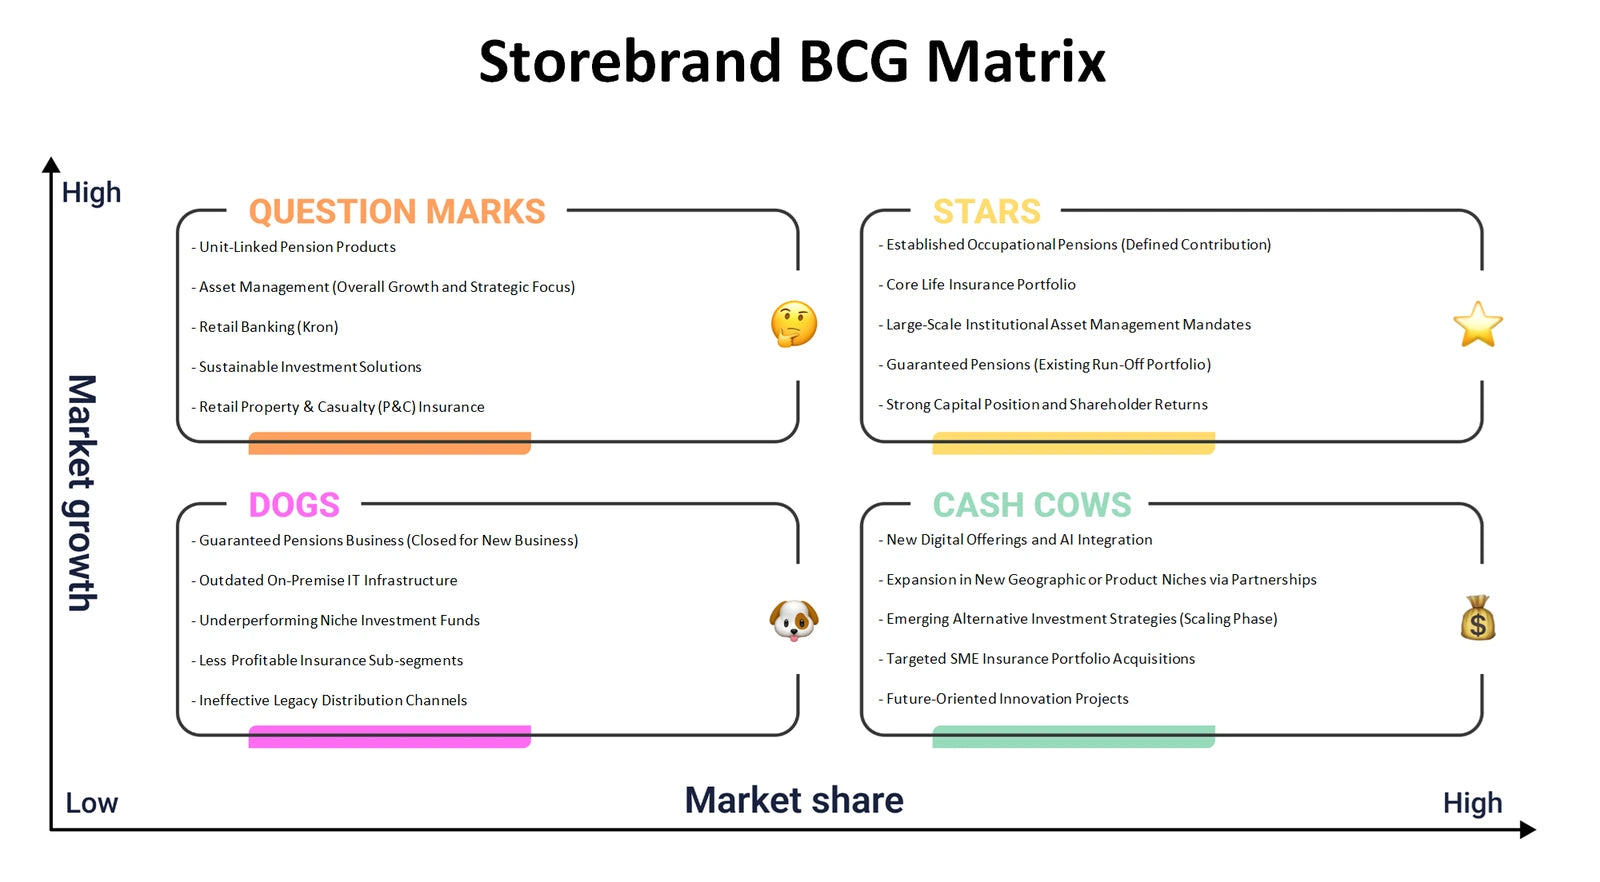
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do Storebrand’s customer relationships, distribution routes and risk-bearing activities fit together to create value and generate income?
The Storebrand Business Model Canvas brings the full operating model into one connected view. It examines customer segments such as individuals and employer-linked pension customers; value propositions around long-term saving, pension and insurance; and channels and customer relationships that may include direct contact, advisers, brokers and institutional partners. It also connects revenue streams to key resources, key activities, key partnerships and cost structure. This is important because financial-services value creation depends not only on attracting customers, but also on administering products, managing risk, meeting service expectations and maintaining the capabilities behind trusted long-duration relationships.
- Value delivery. Trace how pension, savings and insurance needs may move from customer segment to proposition, channel, relationship and recurring service.
- Partner connections. Examine where brokers, financial-institution relationships or reinsurance arrangements could affect reach, expertise, risk-sharing and operating economics.
- Model alignment. Populate the Excel canvas systematically, then use the detailed Word analysis to test whether the nine building blocks support one coherent business logic.
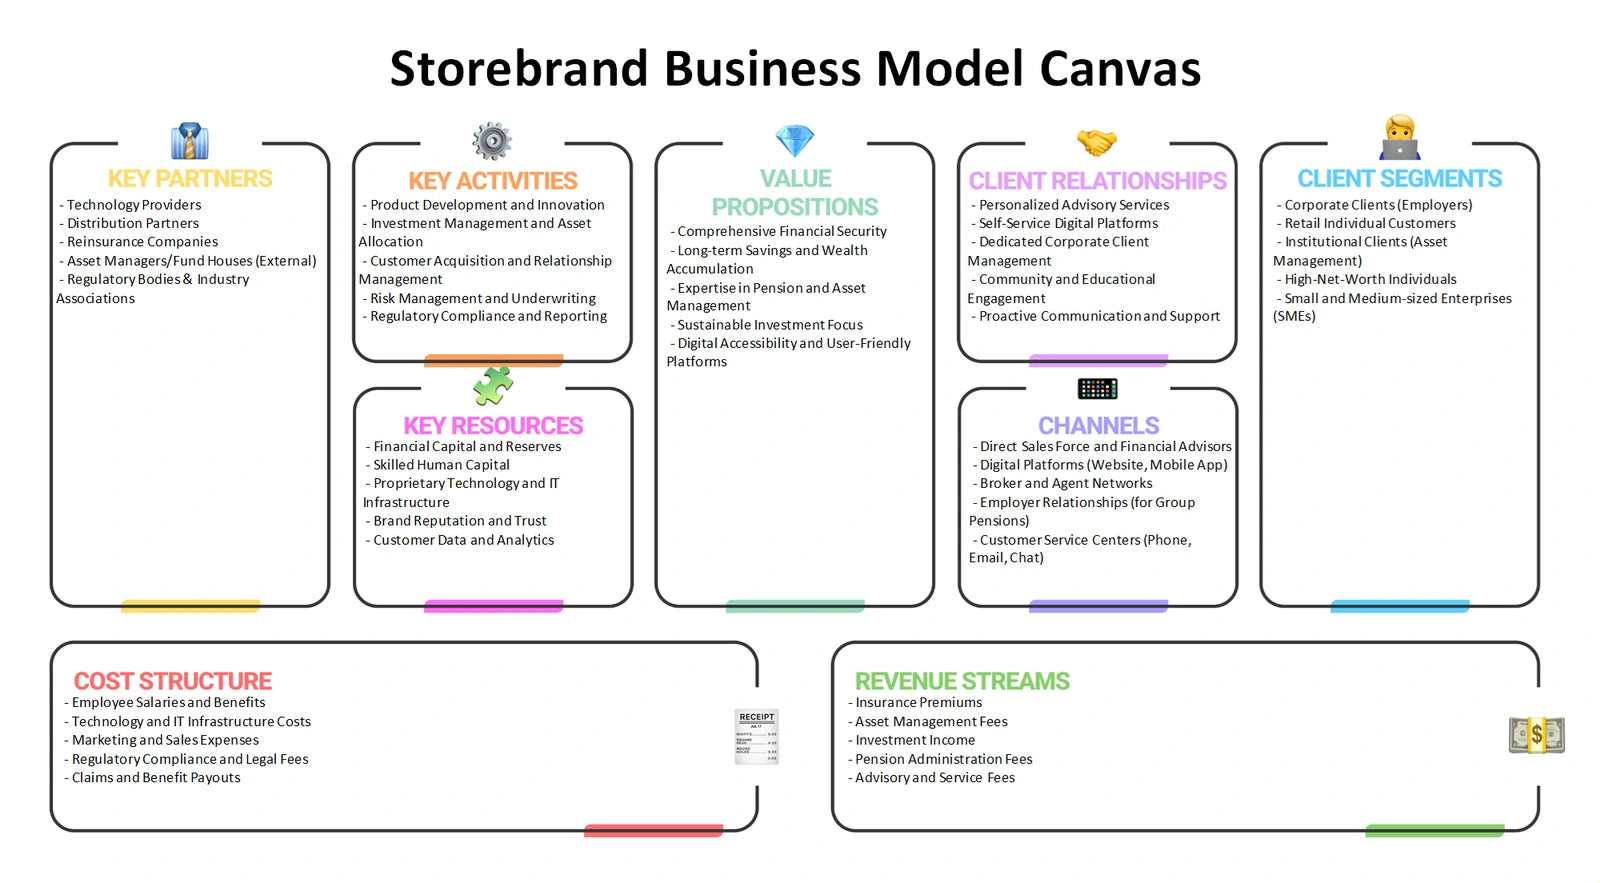
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures shape Storebrand’s ability to serve long-term savings and insurance customers on sustainable terms?
Storebrand Porter's Five Forces analysis focuses on the structure around Nordic savings, pension and insurance activity. Rivalry can arise from firms seeking similar customer assets, employer relationships and insurance demand. Buyer power may differ between an individual policyholder and an organisation evaluating employee-related solutions. Supplier power can include the influence of specialist service providers, technology capabilities, capital-market access or risk-transfer counterparties. The framework also examines barriers facing new entrants and substitutes, such as alternative ways customers can save, protect against risk or obtain financial guidance without using a comparable product. It avoids reducing a complex, regulated market to a simple list of competitors.
- Pressure points. Separate direct competition from supplier dependencies, customer switching considerations and broader alternatives to conventional savings or insurance arrangements.
- Entry barriers. Assess how trust, regulation, capital requirements, data capabilities and distribution relationships may shape the threat of new entrants.
- Evidence trail. Use the Excel framework to record each force and supporting observations, while the Word analysis helps explain why a pressure matters commercially.
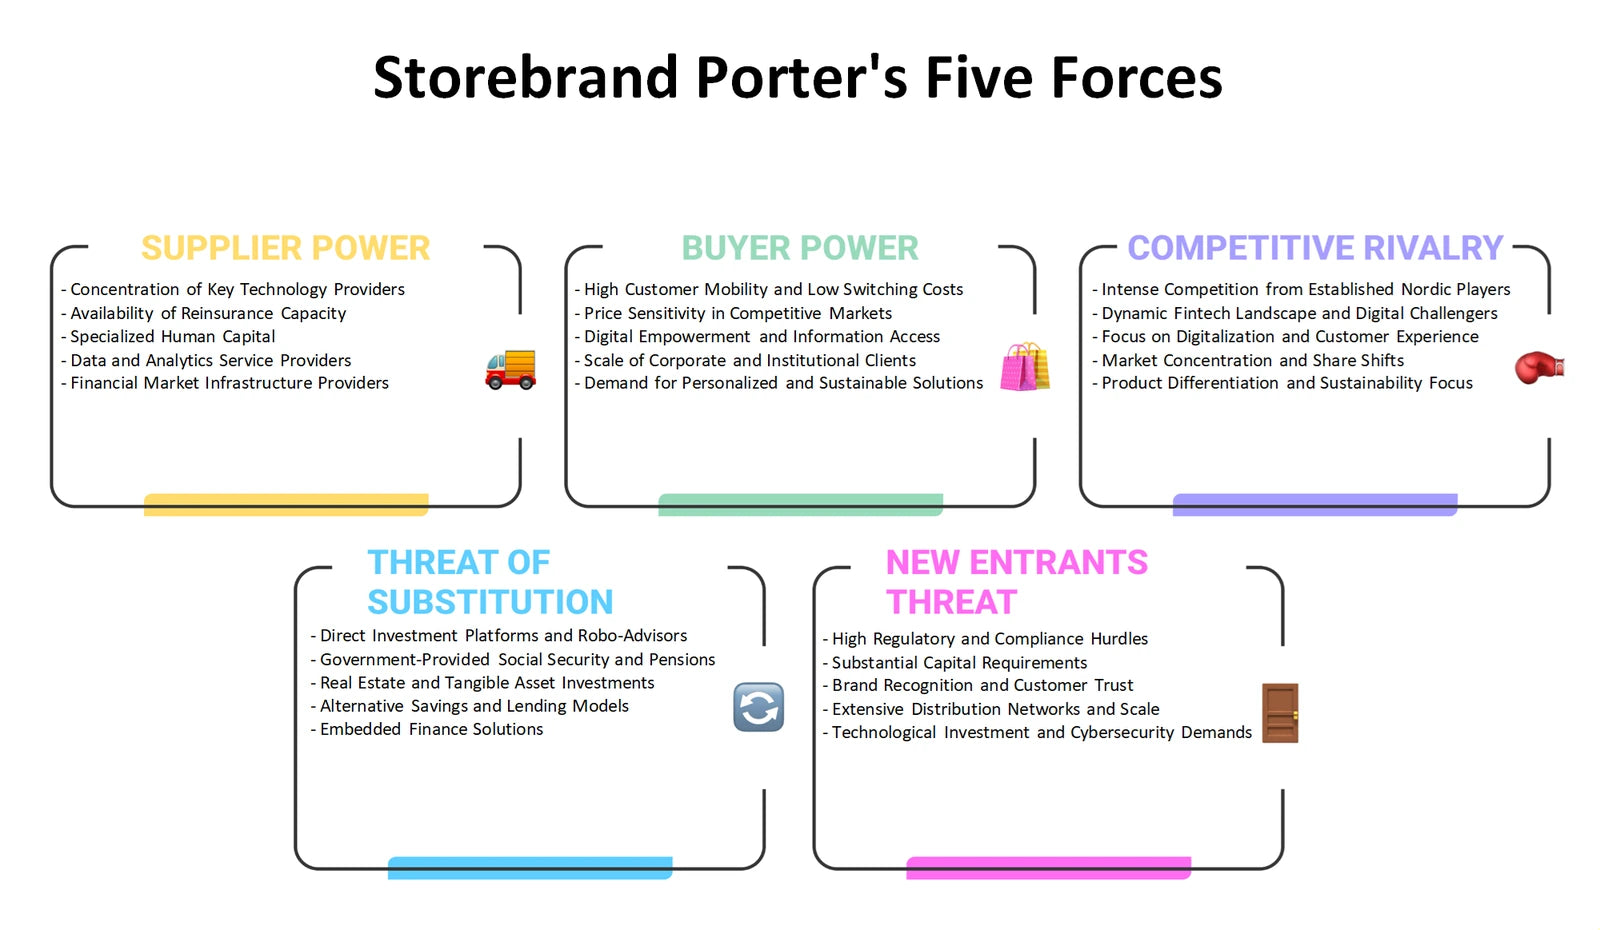
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can Storebrand’s Product, Price, Place and Promotion choices reflect the different needs of savings, pension and insurance customers?
A Storebrand Marketing Mix examines how four commercial decisions work together in a regulated, trust-dependent service environment. Product covers the design and clarity of savings, pension and insurance propositions. Price considers fees, premiums and other customer cost questions without assuming any particular price level. Place addresses how customers reach the business, including direct routes and distribution or brokerage networks relevant to individual and organisational customers. Promotion explores the communication of long-term financial value, coverage and conditions in a way that supports informed decisions. The four Ps matter together: a strong proposition can still be weakened if it is difficult to access, hard to understand or poorly matched to its target audience.
- Offer architecture. Explore whether different customer needs call for distinct product framing, service support and information at the point of decision.
- Channel fit. Compare the role of direct engagement, employer-related routes and intermediaries in making complex long-term products accessible.
- Commercial workshop. Use the Excel framework to organise the four Ps, then use the Word analysis to connect customer communication and channel choices to the wider strategy.
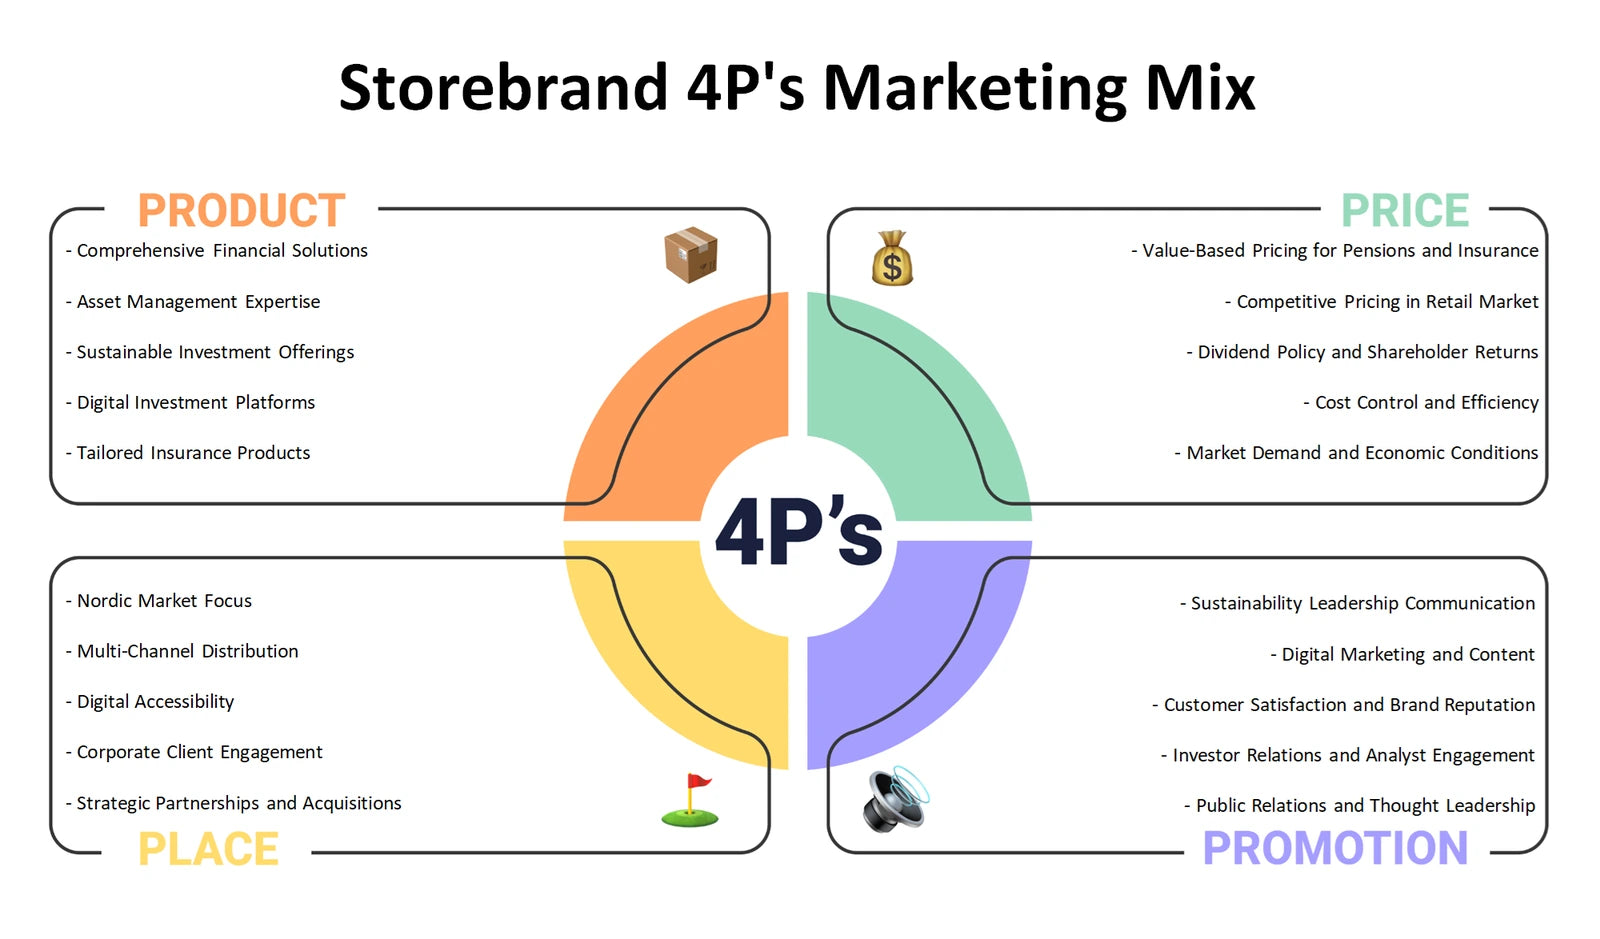
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could alter the environment for Storebrand’s Nordic savings, pension and insurance activities?
Storebrand PESTLE analysis, also commonly called PESTEL, provides a structured way to scan forces outside the company’s direct control. Political and Legal factors can include the policy and regulatory setting surrounding pensions, insurance, consumer protection and financial conduct. Economic conditions can affect saving behaviour, investment expectations and the affordability of protection. Social changes may influence retirement planning, customer preferences and the demand for understandable financial guidance. Technological developments raise questions about digital service, data use and cyber resilience. Environmental considerations matter where climate-related risks, customer expectations and long-term asset decisions influence financial services. The framework identifies questions to monitor rather than claiming that a particular change has already occurred.
- External scan. Separate macroeconomic, demographic, technological and environmental influences so that one broad trend does not obscure another.
- Regulatory relevance. Examine how policy or legal questions could affect product design, disclosure, distribution and risk practices without assuming specific new rules.
- Monitoring map. Use Excel to prioritise external factors by relevance and uncertainty, supported by the Word analysis for context and implications.
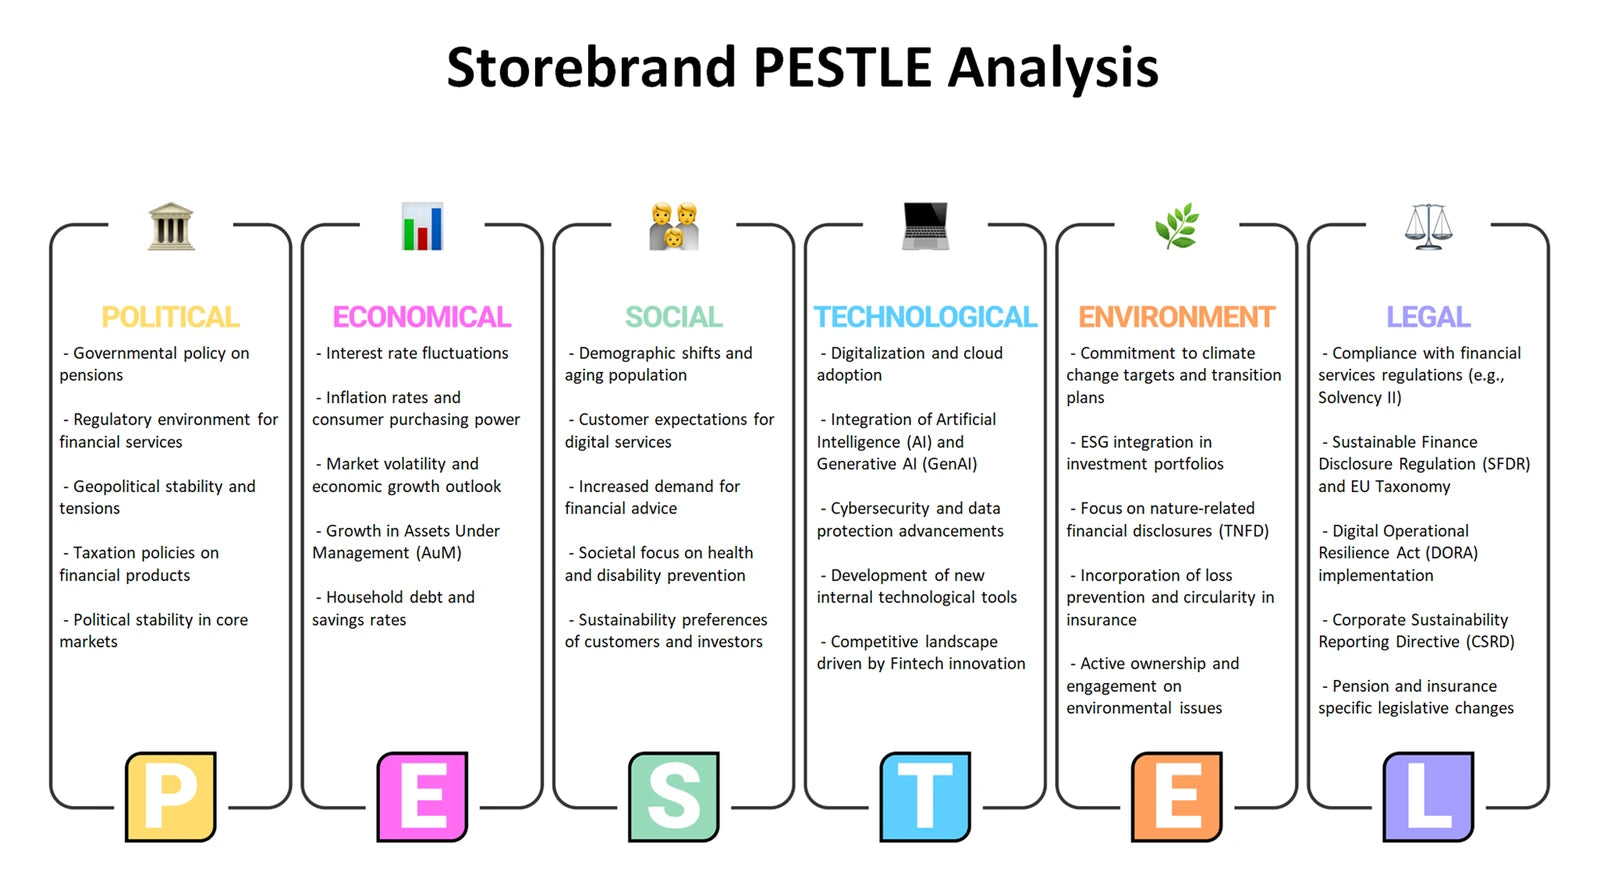
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Storebrand distinguish its internal capabilities and constraints from the external opportunities and threats it must respond to?
A Storebrand SWOT analysis brings the previous lenses into a clear internal-versus-external comparison. Strengths and Weaknesses concern capabilities under the company’s influence, such as the depth of its product knowledge, customer relationships, distribution arrangements, operating processes or risk-management resources. Opportunities and Threats arise outside the business, including changes in customer needs, market structure, regulation, technology or economic conditions. The framework is useful because it prevents attractive market possibilities from being confused with proven internal advantages. It can also expose where a capability gap may limit a response to an external development. Plausible themes should be tested as analysis topics, not presented as established findings without evidence.
- Clear classification. Keep internal resources and limitations separate from external market possibilities and risks when evaluating strategic priorities.
- Strategic fit. Explore whether existing savings, pension, insurance and partner capabilities are suited to particular customer or market opportunities.
- Decision narrative. Use the Excel matrix to group observations, then use the Word analysis to build a reasoned narrative around the most important combinations.
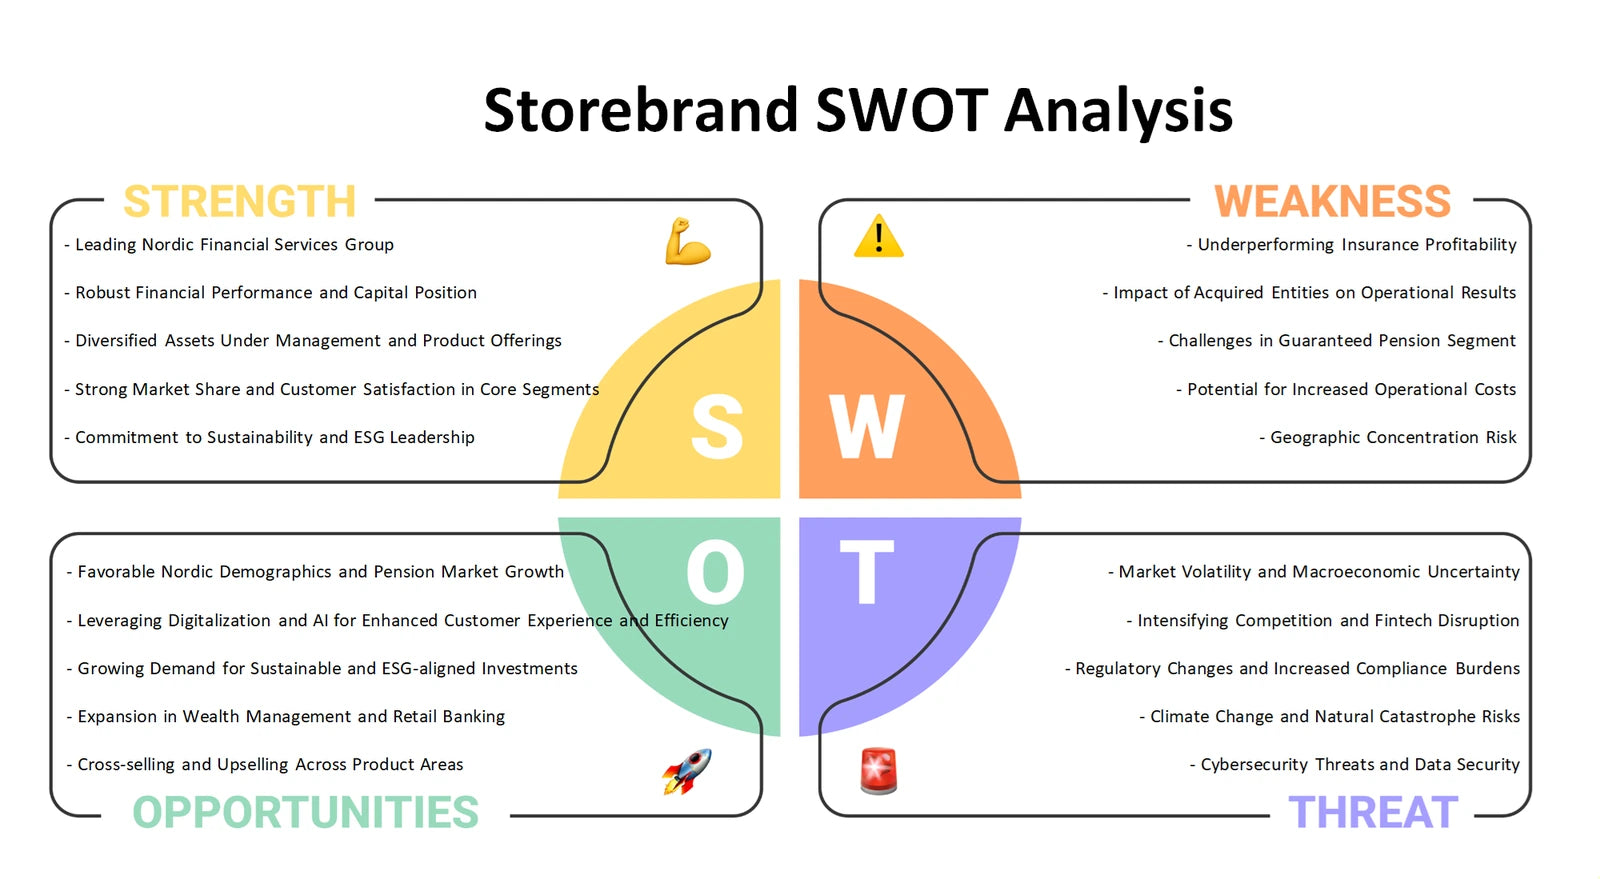
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of Storebrand’s strategic choices
The six perspectives work best together: BCG considers portfolio priorities, Canvas maps value creation, Five Forces tests industry pressure, Marketing Mix examines customer delivery, PESTLE scans external change and SWOT connects internal and external considerations. The Excel frameworks and detailed Word analysis give you a structured basis for developing company-specific discussion, comparison and strategic planning around Storebrand.
Company background: Storebrand — The Storebrand Group website.