

Spandana Sphoorty Financial: Business Model and Market Pressures – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Spandana Sphoorty Financial Strategy Analysis Bundle
This bundle examines Spandana Sphoorty Financial as the intended microcredit business described in the matching product context. Its operating model centres on lending to microcredit customers and managing a loan portfolio, while funding capacity can depend on relationships with banks, debt investors and securitisation counterparties. That combination makes customer access, underwriting discipline, funding resilience and portfolio quality central business questions.
The available business context describes a funding mix that can include bank borrowings, non-convertible debentures and loan-portfolio securitisation. The six connected frameworks help customers examine how those funding choices relate to product priorities, customer value, competitive pressure, distribution, external conditions and organisational capability. They are analytical tools for evaluating strategic choices, not claims about current company results or investment advice.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending products, customer segments or operating priorities merit scarce capital and management attention?
The Spandana Sphoorty Financial BCG Matrix applies market growth and relative market share to possible portfolio areas rather than assuming that any activity already occupies a quadrant. For a lender dependent on both borrower demand and reliable funding, the framework helps compare where growth may require more branch capacity, collections resources, technology investment or debt funding. It also distinguishes an attractive market from a unit that can generate sustainable cash after credit, operating and funding costs. Stars, Cash Cows, Question Marks and Dogs provide a disciplined vocabulary for resource priorities, not a pre-set verdict on the company’s products.
- Portfolio logic. Compare lending opportunities by relevant market growth, relative share, capital needs and the demands they place on portfolio management.
- Capital trade-offs. Test whether cash generated by established activities could support carefully selected growth areas without weakening funding flexibility.
- Structured comparison. Use the Excel framework to organise candidate activities and assumptions, then use the Word analysis to interpret the strategic implications behind each placement.
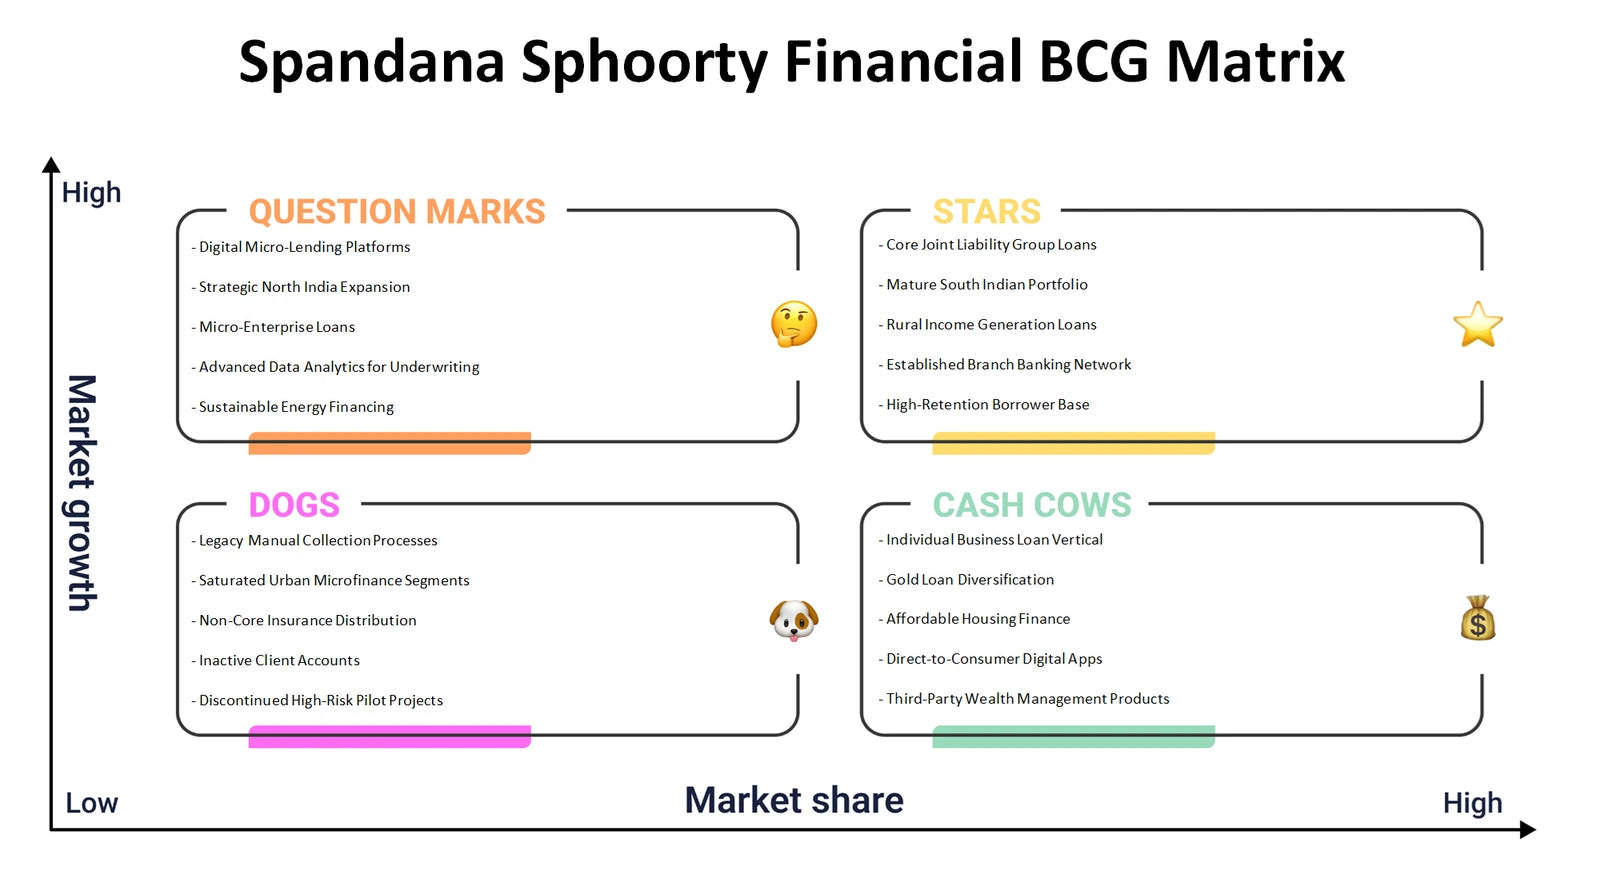
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer need, lending delivery, funding access and cost discipline connect in one economic model?
The Spandana Sphoorty Financial Business Model Canvas brings together all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For a microcredit business, the useful question is not simply whether loans are offered; it is how an accessible lending proposition reaches and serves borrowers, how repayment relationships are sustained, and how interest-related income must support credit, operating and funding costs. The supplied context makes funding partners especially relevant because bank facilities, debt issuance and securitisation can affect the resources available to originate and hold loans.
- Value-to-economics link. Trace how borrower service, loan delivery, repayment support and revenue logic must work alongside portfolio quality and cost control.
- Partnership dependency. Examine how lenders, capital-market participants and securitisation counterparties may enable funding while also creating concentration or execution questions.
- Model mapping. Complete relationships among the nine blocks in Excel and use the Word analysis to assess where a change in one block could affect the wider model.
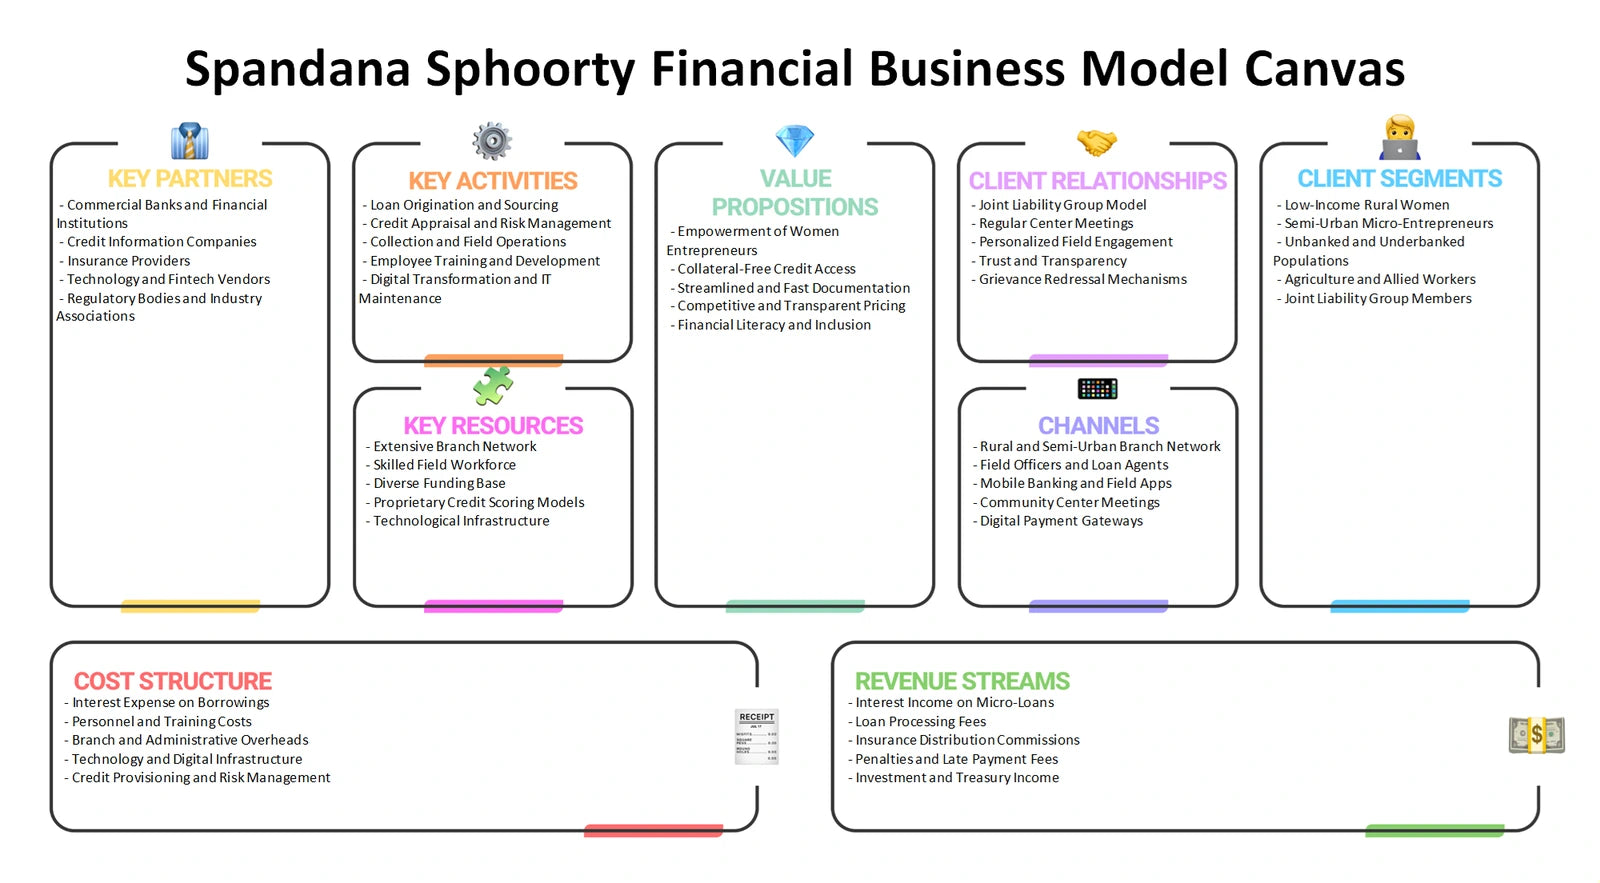
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry forces can shape the attractiveness and resilience of microcredit lending?
Spandana Sphoorty Financial Porter's Five Forces considers the competitive environment around lending rather than presenting unsupported force scores. Rivalry can arise where lenders seek similar borrower groups and local operating reach. Supplier power is particularly material because funding providers, debt markets and securitisation structures influence the availability and cost of capital. Buyer power concerns borrowers’ ability to compare credit options or change provider. New entrants may be constrained by regulation, capital, risk systems and distribution capability, while substitutes include informal borrowing, savings, family networks and other ways households finance urgent needs. Each force can alter pricing headroom, customer retention and required operating discipline.
- Funding-side pressure. Assess how dependence on external capital can affect bargaining power, refinancing risk and the economics of loan growth.
- Alternative credit routes. Compare direct lending competition with substitutes that can meet a customer’s borrowing need outside a conventional microcredit relationship.
- Evidence-led review. Use the Excel template to record force indicators and questions, then use the Word analysis to connect those pressures to strategic responses.
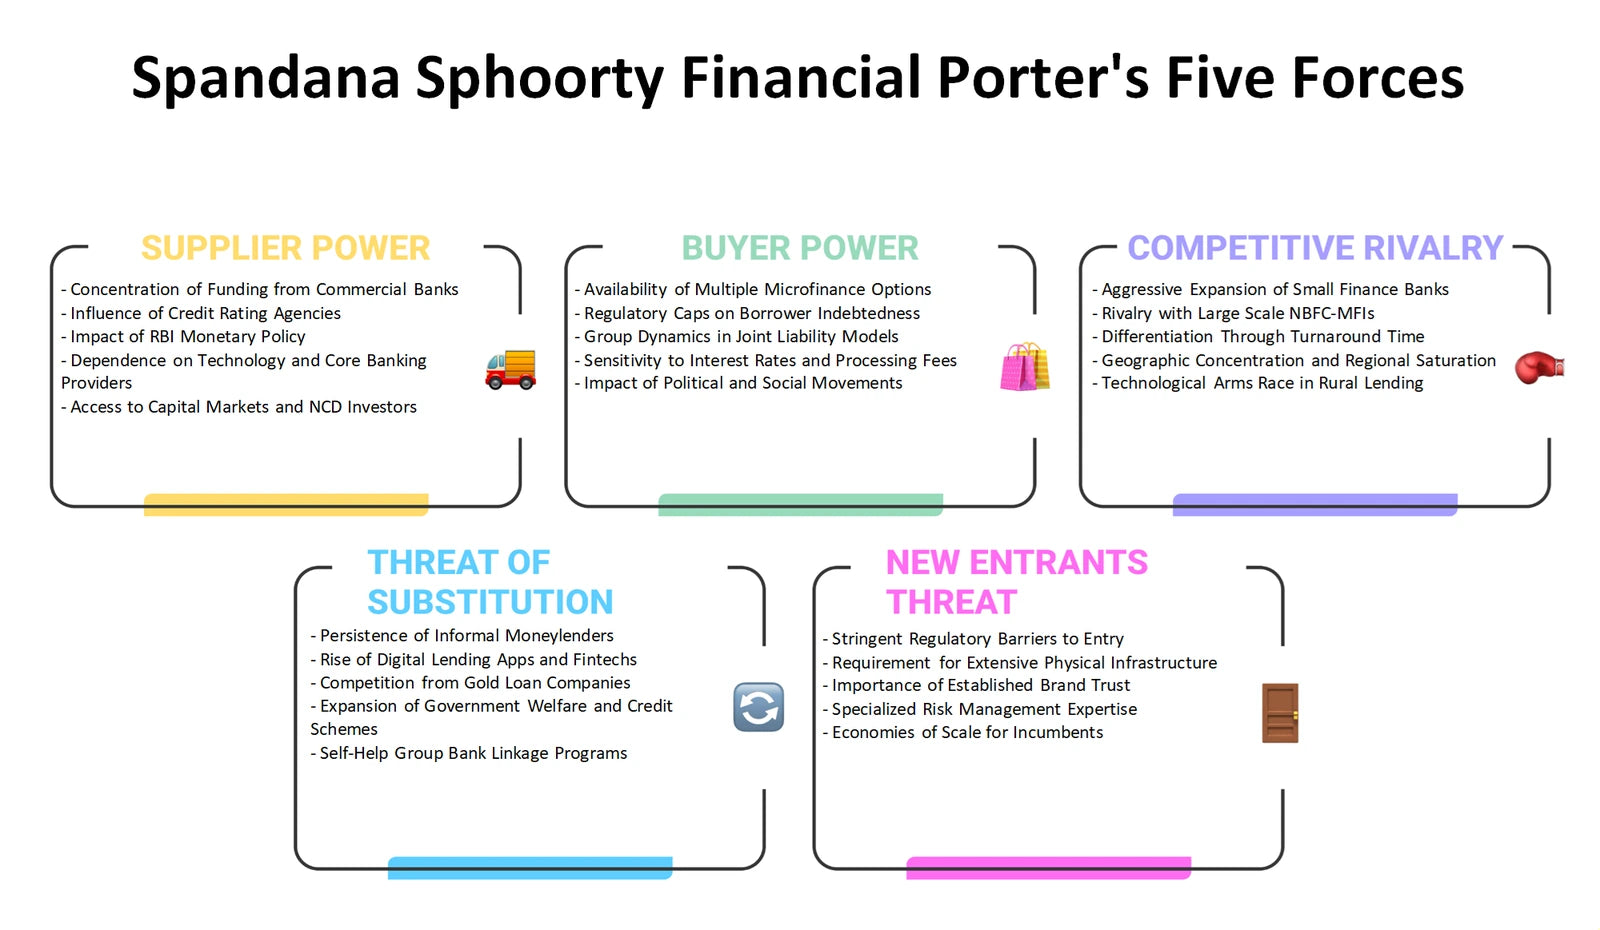
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can lending propositions be communicated and delivered in a way that matches borrower needs and responsible credit expectations?
The Spandana Sphoorty Financial Marketing Mix examines Product, Price, Place and Promotion in a financial-service context. Product analysis can consider loan features, service experience and repayment support without assuming particular terms or product ranges. Price is broader than an advertised rate: it includes the customer’s understanding of borrowing costs, repayment obligations and value received. Place asks how borrowers access information, applications, disbursement and service through appropriate physical or digital routes. Promotion considers clear, responsible communication that helps customers understand the offering rather than treating credit like an ordinary consumer packaged good.
- Product fit. Explore how lending design and service processes could address customer needs while remaining operationally manageable and credit-conscious.
- Trust and clarity. Assess how transparent pricing communication and suitable customer touchpoints can support informed borrowing decisions and durable relationships.
- 4P planning. Use the Excel framework to compare Product, Price, Place and Promotion choices, then consult the Word analysis for company-relevant marketing questions.
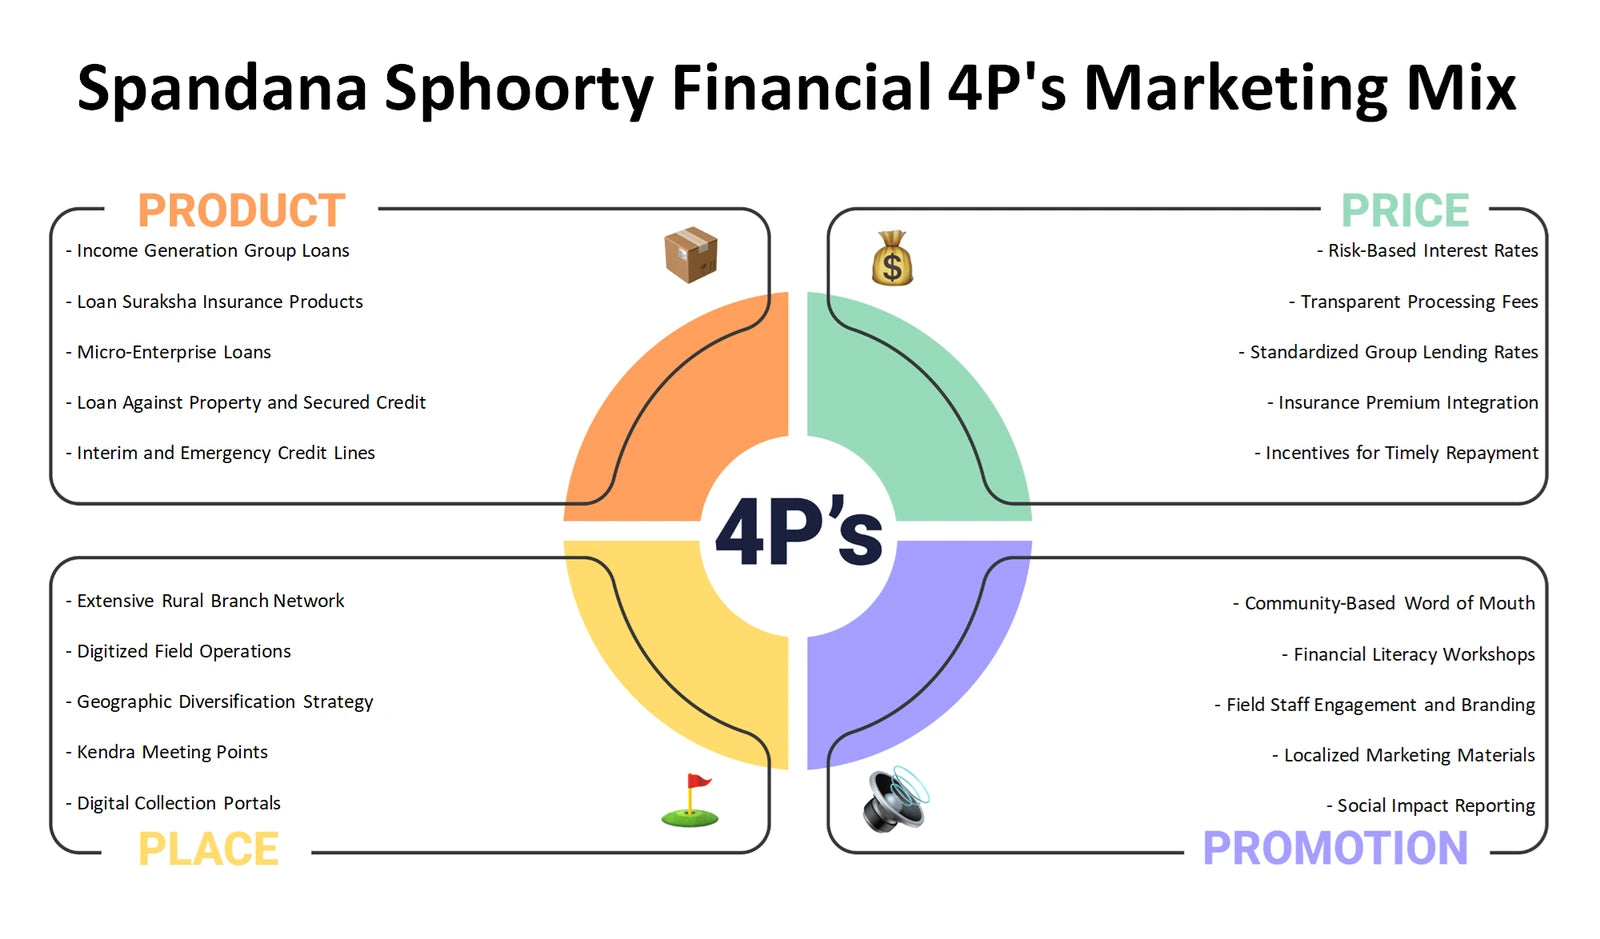
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter borrower demand, funding conditions, operating requirements or portfolio risk?
The Spandana Sphoorty Financial PESTLE analysis, also commonly called PESTEL, separates external influences that may affect a microcredit lender. Political factors can include public-policy priorities affecting financial inclusion; economic conditions can shape household cash flow, borrowing demand and funding costs. Social factors matter because trust, financial awareness and local repayment behaviour influence service design. Technology can change onboarding, collections, data use and customer access. Legal considerations cover financial regulation, consumer protection and compliance expectations, while environmental conditions may affect customers whose income depends on climate-sensitive local activity. These are areas to monitor and assess, not claims that a specific policy or event has occurred.
- External exposure. Identify macroeconomic, regulatory and social questions that could influence loan demand, repayment capacity or the availability of funding.
- Operating adaptation. Consider where technology, compliance processes and environmental resilience may become important to customer service and risk management.
- Monitoring agenda. Use Excel to log external factors by category and priority, while the Word analysis provides context for translating observations into strategic discussion.
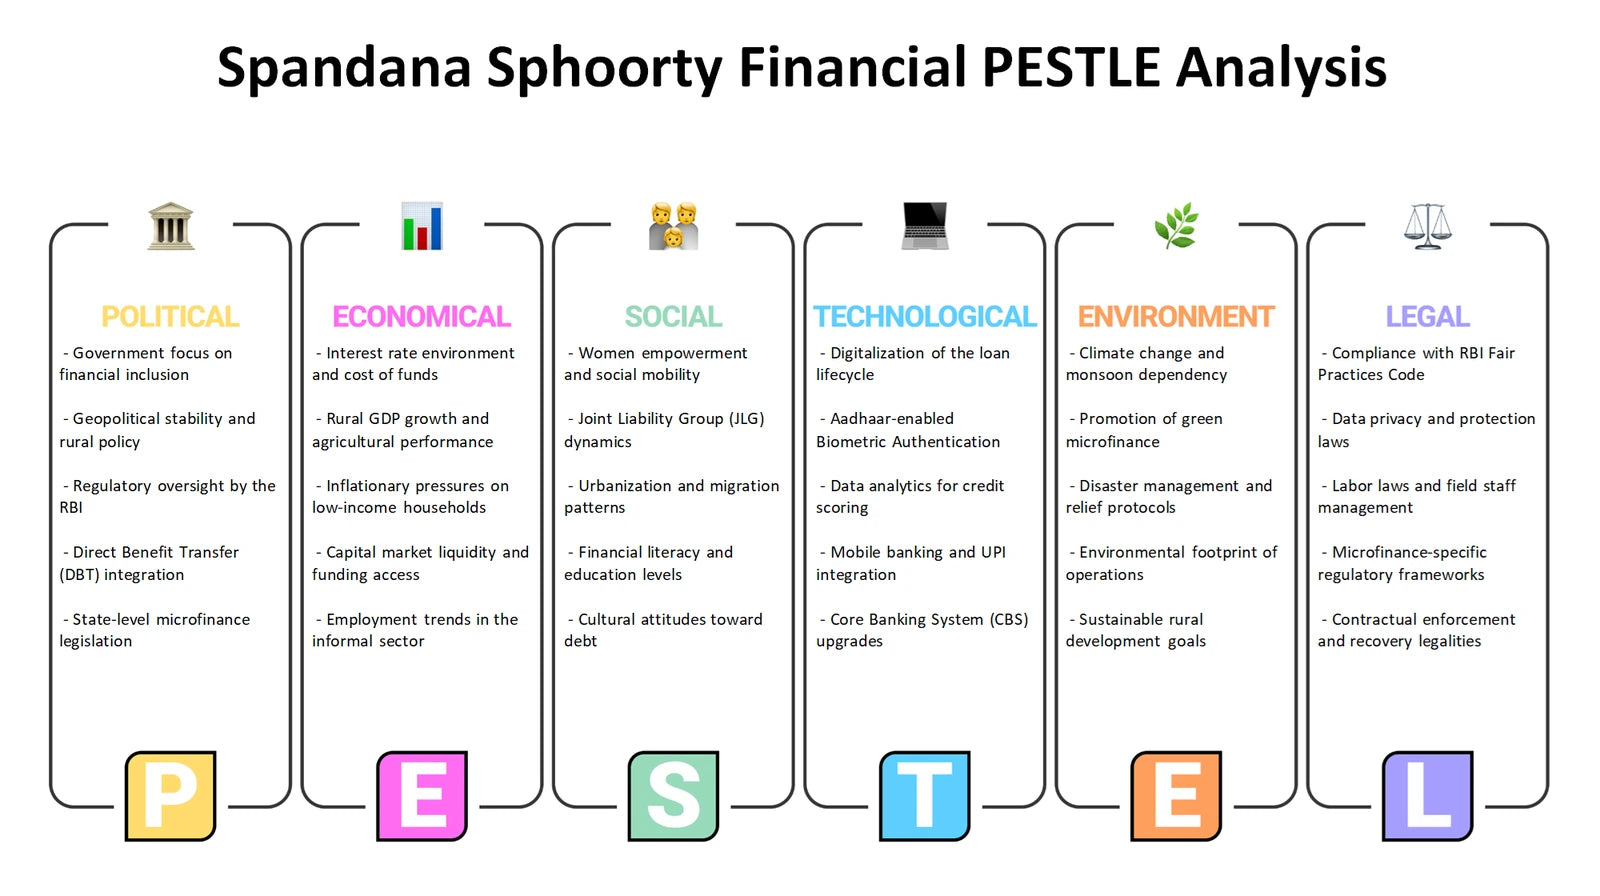
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal lending capabilities and constraints be weighed against external market opportunities and threats?
The Spandana Sphoorty Financial SWOT analysis separates internal Strengths and Weaknesses from external Opportunities and Threats. Potential internal themes for examination include underwriting processes, borrower relationships, collections capability, operating reach, funding diversification and governance arrangements; the framework does not state that any of these are established strengths or weaknesses. Opportunities may arise from unmet credit needs, improved service delivery or broader funding access. Threats can include competitive intensity, borrower stress, refinancing pressure, regulatory change or disruption to local customer incomes. Keeping the categories separate prevents a market event from being mistaken for a company capability, and makes strategic choices easier to test.
- Internal diagnosis. Review which capabilities, processes and resource constraints could materially affect lending quality, customer service and funding resilience.
- External fit. Match possible opportunities and threats with the internal conditions needed to pursue growth or protect the portfolio responsibly.
- Decision synthesis. Populate the Excel SWOT grid with evidence and open questions, then use the detailed Word analysis to develop priorities from the resulting combinations.
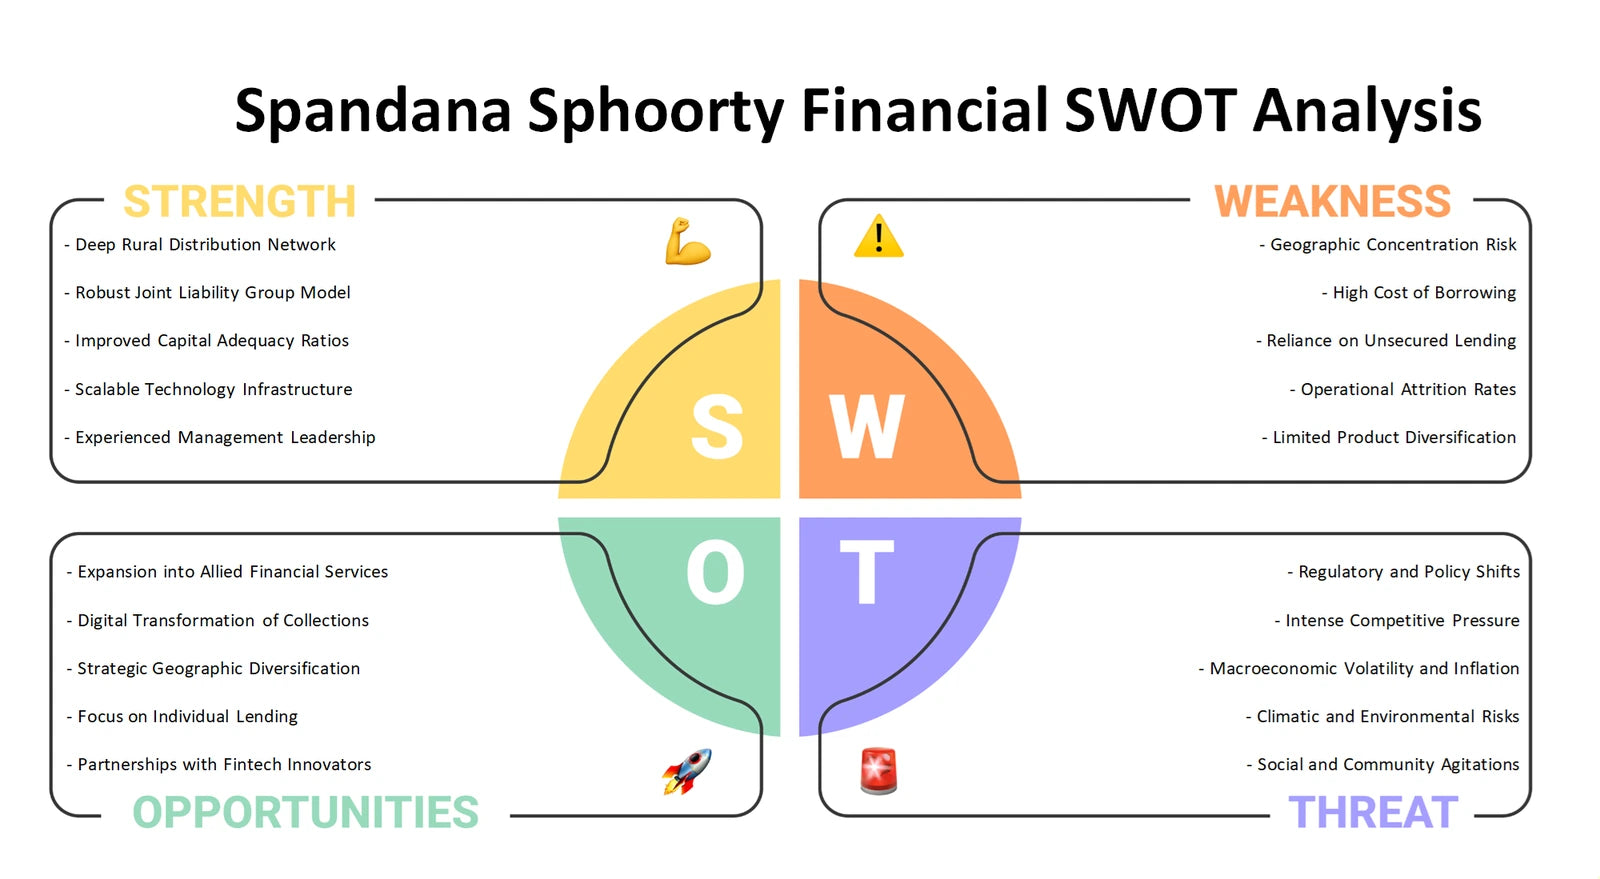
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of lending strategy
Together, the six perspectives move from portfolio priorities and business-model economics to industry pressure, customer-facing choices, external change and strategic fit. The Excel frameworks help organise comparisons and questions, while the Word files provide detailed company analysis to support more informed discussion of Spandana Sphoorty Financial’s microcredit model, funding dependencies and operating trade-offs.
Company background: Spandana Sphoorty Financial — matching product-context page.