

Selective Insurance Group: Insurance Business and Licensing in Six Frameworks

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
Selective Insurance Group Strategy Analysis Bundle
Selective Insurance Group is the display name used for Selective Insurance Group Inc., a fire, marine and casualty insurance holding company classified by the SEC under SIC 6331. Its operating context includes policy underwriting, risk selection, pricing, claims activity, capital management, reinsurance relationships, technology modernization and compliance with insurance regulation. This bundle examines how those connected activities can be assessed through six practical strategy frameworks.
In its 10-Q filed July 24, 2026, the company reported revenue of USD 1.387 billion and GAAP net income of USD 129.385 million for April 1 through June 30, 2026. These quarterly figures provide a dated company-context snapshot, not evidence that the downloadable files were updated in 2026. They make questions about portfolio priorities, risk-transfer economics and customer-value delivery especially relevant.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance portfolios or customer opportunities deserve more capital, specialist attention and distribution effort?
A Selective Insurance Group BCG Matrix helps organize possible product, customer or underwriting portfolios around market growth and relative market share. For an insurer, the framework is useful because growth alone can consume underwriting capacity, regulatory attention and reinsurance protection, while a mature portfolio may generate dependable cash but require disciplined retention and claims management. Stars, Cash Cows, Question Marks and Dogs are analytical categories, not claims about Selective's current lines of business. The materials help users compare the evidence needed before setting resource priorities.
- Portfolio logic. Compare coverage areas or customer niches by growth conditions, relative market position and the capital demands of expanding them.
- Risk-adjusted priorities. Consider how catastrophe exposure, loss experience and reinsurance needs may change the attractiveness of a growing portfolio.
- Structured comparison. Use the Excel framework to map candidate portfolios, then use the Word analysis to interpret assumptions and discuss priority trade-offs.
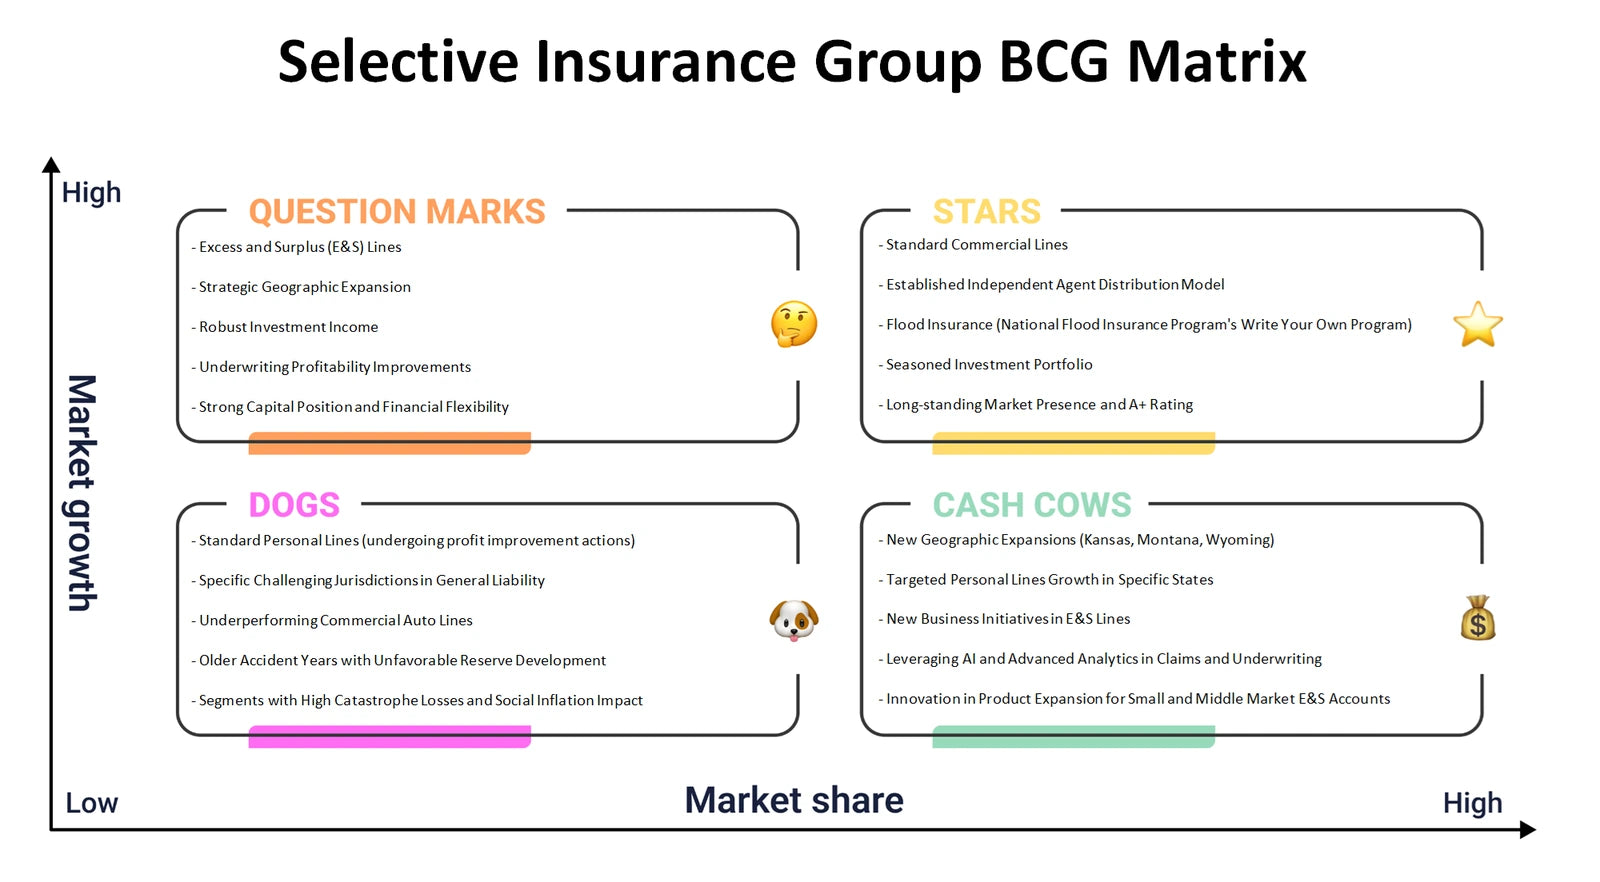
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do underwriting capability, risk transfer, service operations and compliance fit together to create insurance value?
The Selective Insurance Group Business Model Canvas connects the nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. It is particularly relevant where premium revenue must support claims obligations, underwriting expertise, technology investment, regulatory compliance and capital resilience. Reinsurance relationships can be examined as key partnerships that transfer selected risks and support underwriting capacity, while technology providers can be considered in relation to risk selection, pricing and claims workflows. The canvas does not assume a specific customer mix or channel model; it gives those questions a coherent operating and economic structure.
- Value chain links. Trace how policyholder needs, underwriting decisions, claims service and financial resilience influence the value proposition.
- Economic dependencies. Examine how premiums, costs, retained risk and partner arrangements may interact within the insurance model.
- Connected evidence. Populate the Excel canvas by building block and use the Word analysis to connect individual entries into an overall business-model narrative.
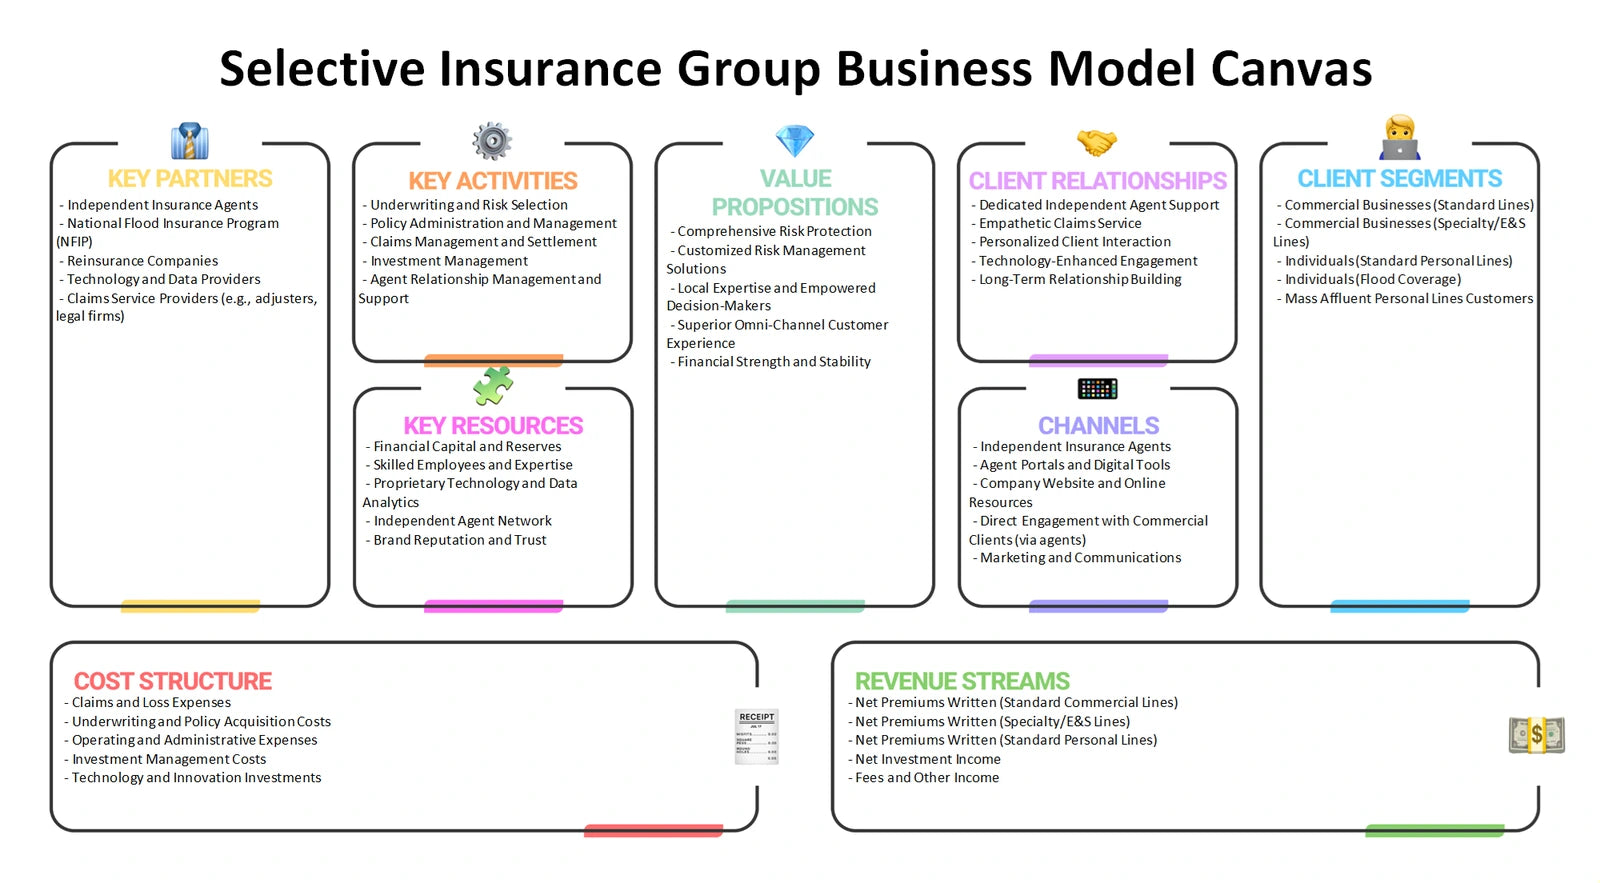
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can shape underwriting margins, customer retention and strategic room to maneuver?
Selective Insurance Group Porter's Five Forces examines the competitive setting around property and casualty insurance without assigning unsupported force scores. Rivalry can be considered through competition for desirable risks and sustainable pricing. Buyer power concerns customers' ability to compare coverage, terms and service alternatives. Supplier power may arise where reinsurance capacity, technology tools or specialist services are important inputs. Entry barriers matter because insurers need capital, licensing, risk expertise and regulatory credibility, while substitutes include risk retention or other ways customers may address financial exposure rather than buying comparable coverage.
- Competitive discipline. Assess where rivalry may pressure terms or pricing and where underwriting differentiation could matter more than scale alone.
- Partner exposure. Explore how reliance on reinsurance and technology relationships may affect negotiating leverage, resilience and cost.
- Force-by-force review. Use the Excel structure to record evidence for each force, with the Word analysis providing context for the five linked pressures.
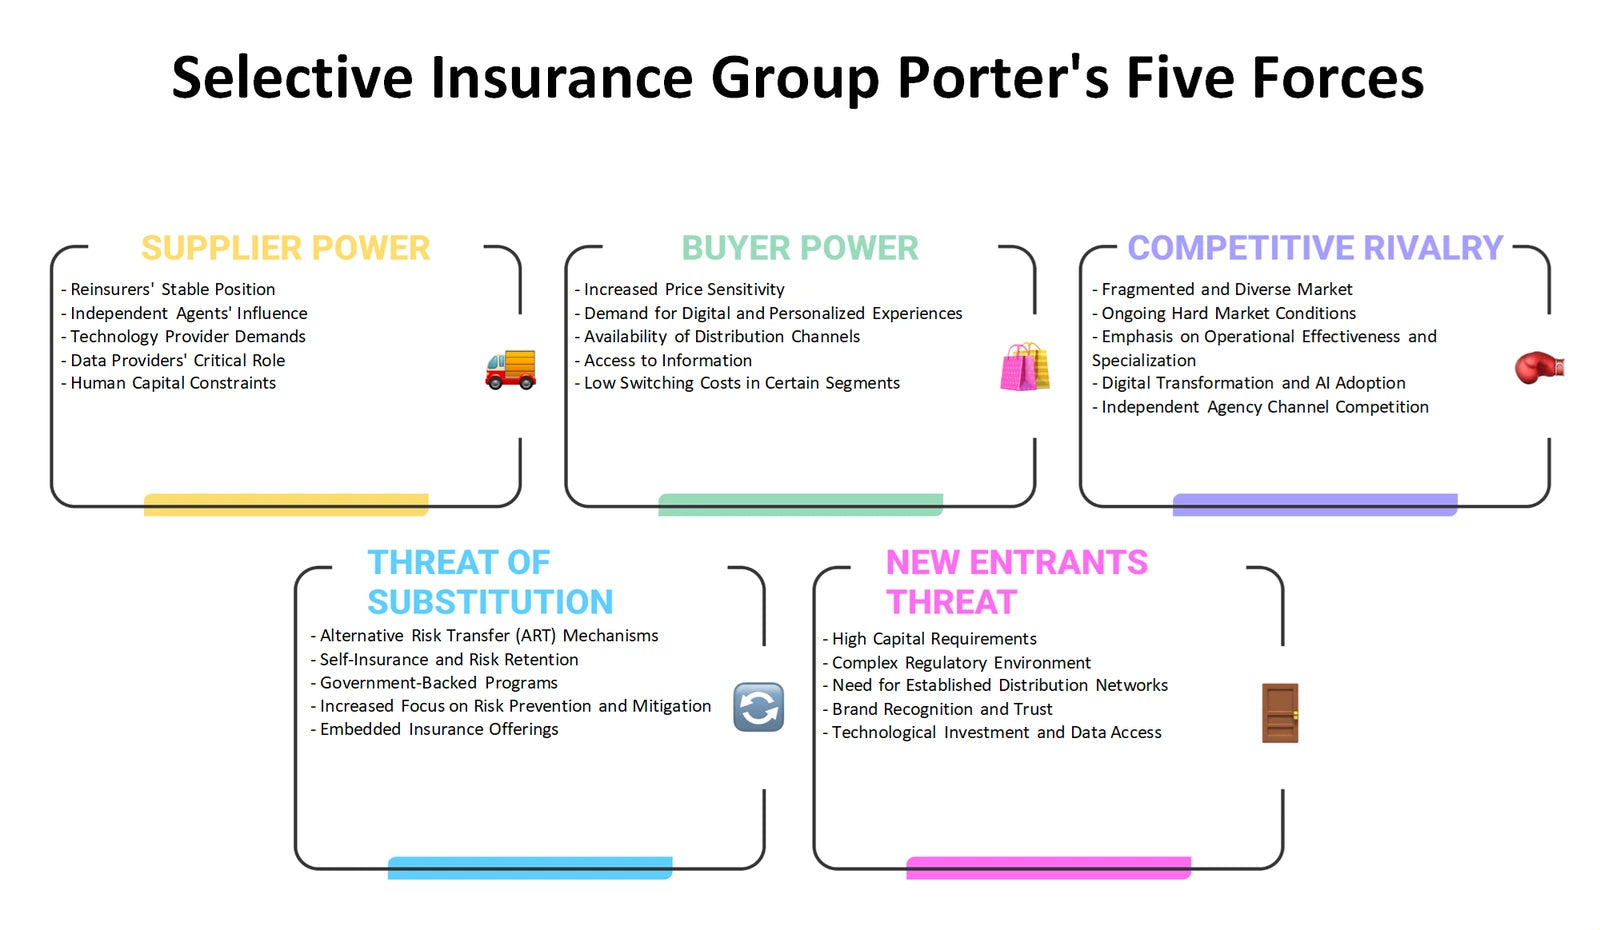
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can insurance offerings, underwriting-led pricing, access routes and communications work together for intended customers?
The Selective Insurance Group Marketing Mix applies Product, Price, Place and Promotion to a regulated insurance context. Product can include the coverage design, service experience and claims-related confidence that customers evaluate when transferring risk. Price is not simply a listed premium: it is tied to risk selection, underwriting terms, loss expectations and appropriate return for assumed exposure. Place considers the routes through which customers obtain information, policies and service, while Promotion examines how coverage terms, risk expertise and trust can be communicated clearly. The 4Ps framework helps keep customer-facing decisions connected to operational and regulatory realities.
- Offering clarity. Examine how policy features, service expectations and claims support may shape perceived value for different customer needs.
- Pricing coherence. Compare the strategic role of risk-based premiums, coverage terms and underwriting discipline without assuming actual prices.
- Decision alignment. Use the Excel framework to test consistency across the four Ps, then consult the Word analysis for sector-specific interpretation.
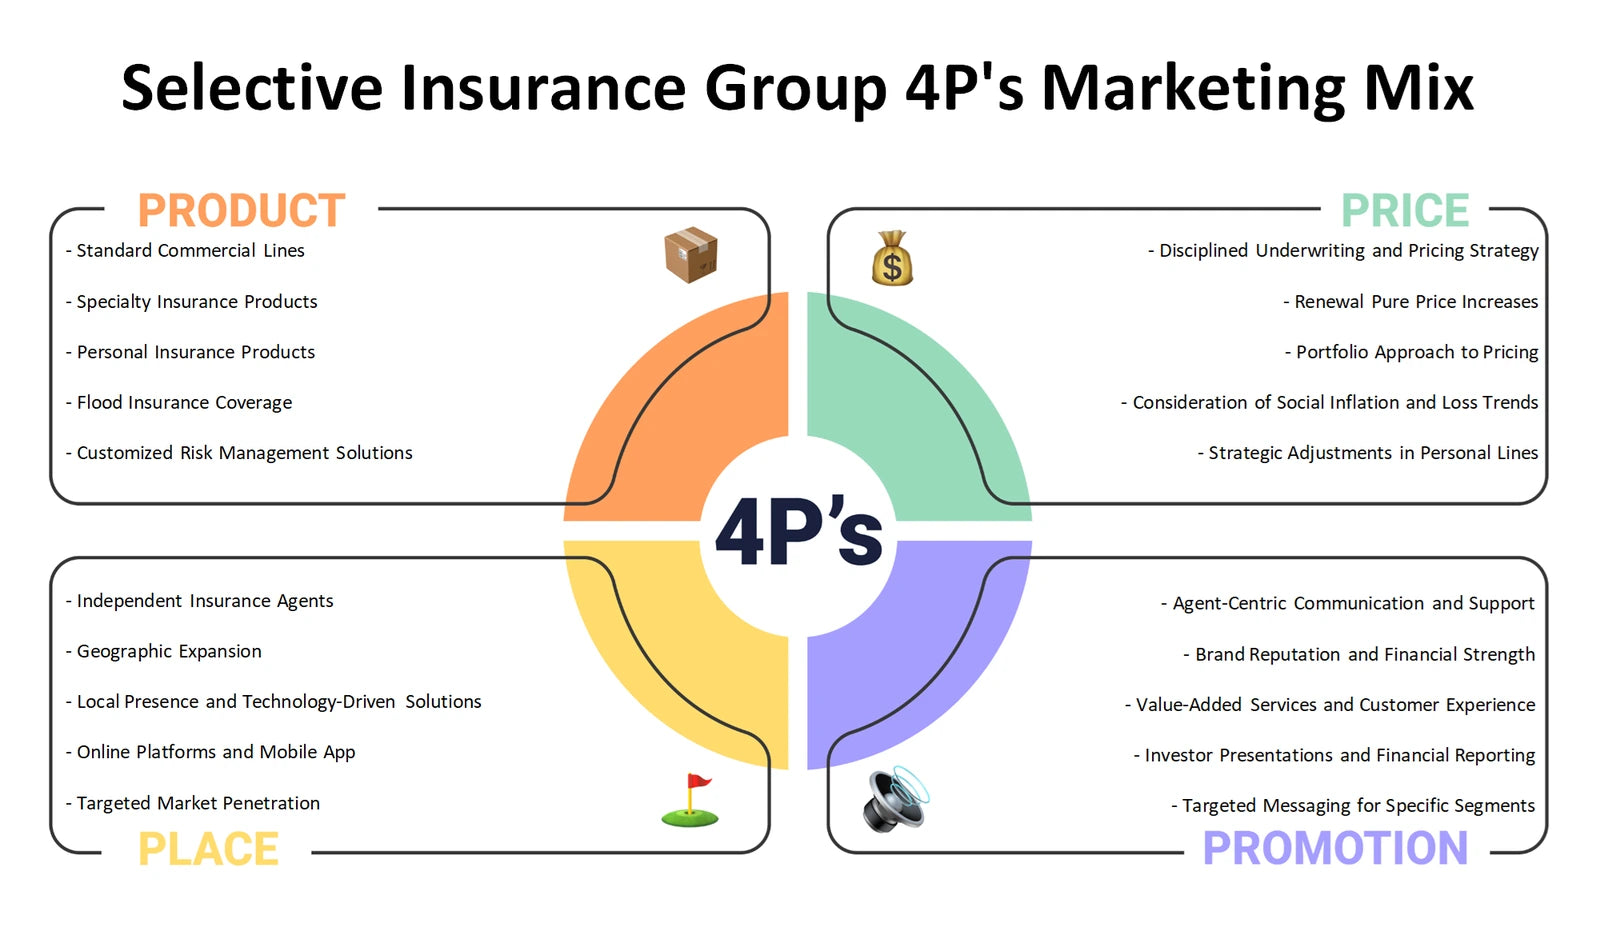
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter insurance demand, underwriting conditions, compliance obligations and catastrophe-risk management?
A Selective Insurance Group PESTLE analysis, also commonly called PESTEL, organizes Political, Economic, Social, Technological, Legal and Environmental influences around the insurer's operating environment. Political and legal questions include the effect of state and federal oversight on licenses, reporting and conduct requirements. Economic conditions can affect customer affordability, claims costs and financial assumptions. Social expectations may change the service and responsiveness customers expect after a loss. Technology raises questions about modernized systems, data use and operational efficiency. Environmental conditions are relevant where catastrophe risk affects underwriting and reinsurance planning. These are areas for structured examination, not assertions that a particular change has occurred.
- Regulatory horizon. Identify policy and legal questions that may influence compliance resources, product design or operating permissions.
- Risk environment. Connect economic, social, technological and environmental developments to potential effects on claims and risk selection.
- External scan. Use Excel to organize signals by PESTLE category and use the Word analysis to turn those signals into focused discussion topics.
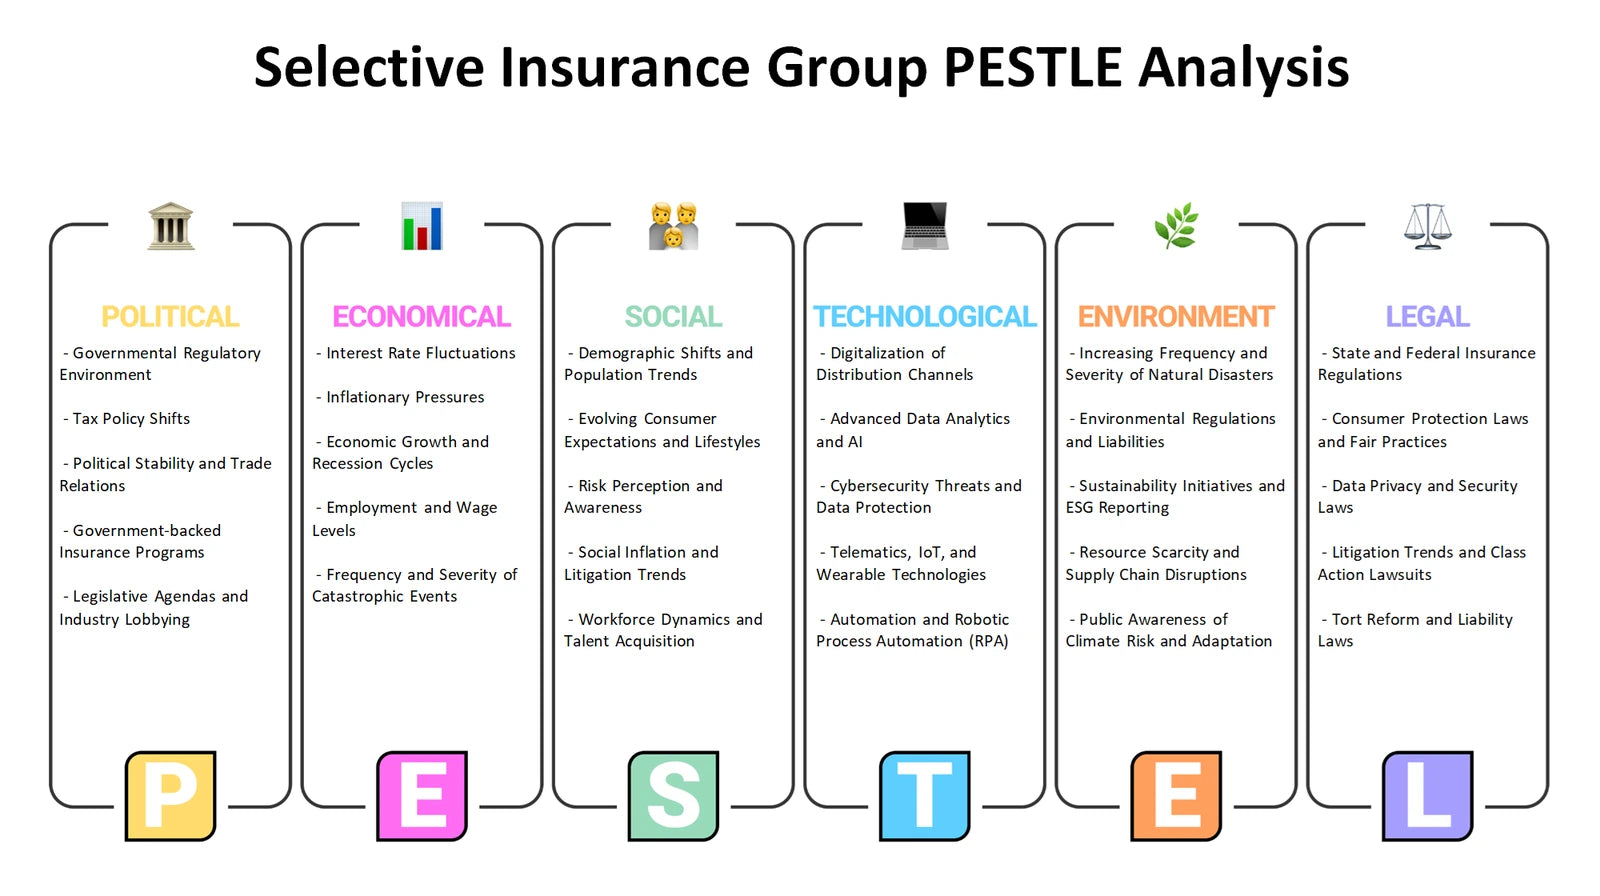
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal underwriting and operating capabilities be assessed alongside external insurance opportunities and threats?
The Selective Insurance Group SWOT analysis separates internal Strengths and Weaknesses from external Opportunities and Threats. This distinction is important for an insurance business: reinsurance arrangements, technology collaboration, underwriting expertise and compliance practices may be internal capabilities or constraints to evaluate, whereas changing customer needs, regulation, economic conditions and catastrophe patterns are external conditions. The framework does not present plausible themes as proven findings. Instead, it helps users test whether resources and processes are sufficient for the outside environment Selective faces, and whether vulnerabilities need attention before pursuing a market opportunity.
- Internal reality. Examine capabilities such as risk selection, partner management, system modernization and regulatory discipline as potential strengths or weaknesses.
- External fit. Compare those internal factors with opportunities and threats arising from customer, market, regulatory and environmental conditions.
- Actionable synthesis. Use the Excel SWOT grid to prioritize evidence, then use the Word analysis to develop balanced strategic discussion around the resulting combinations.
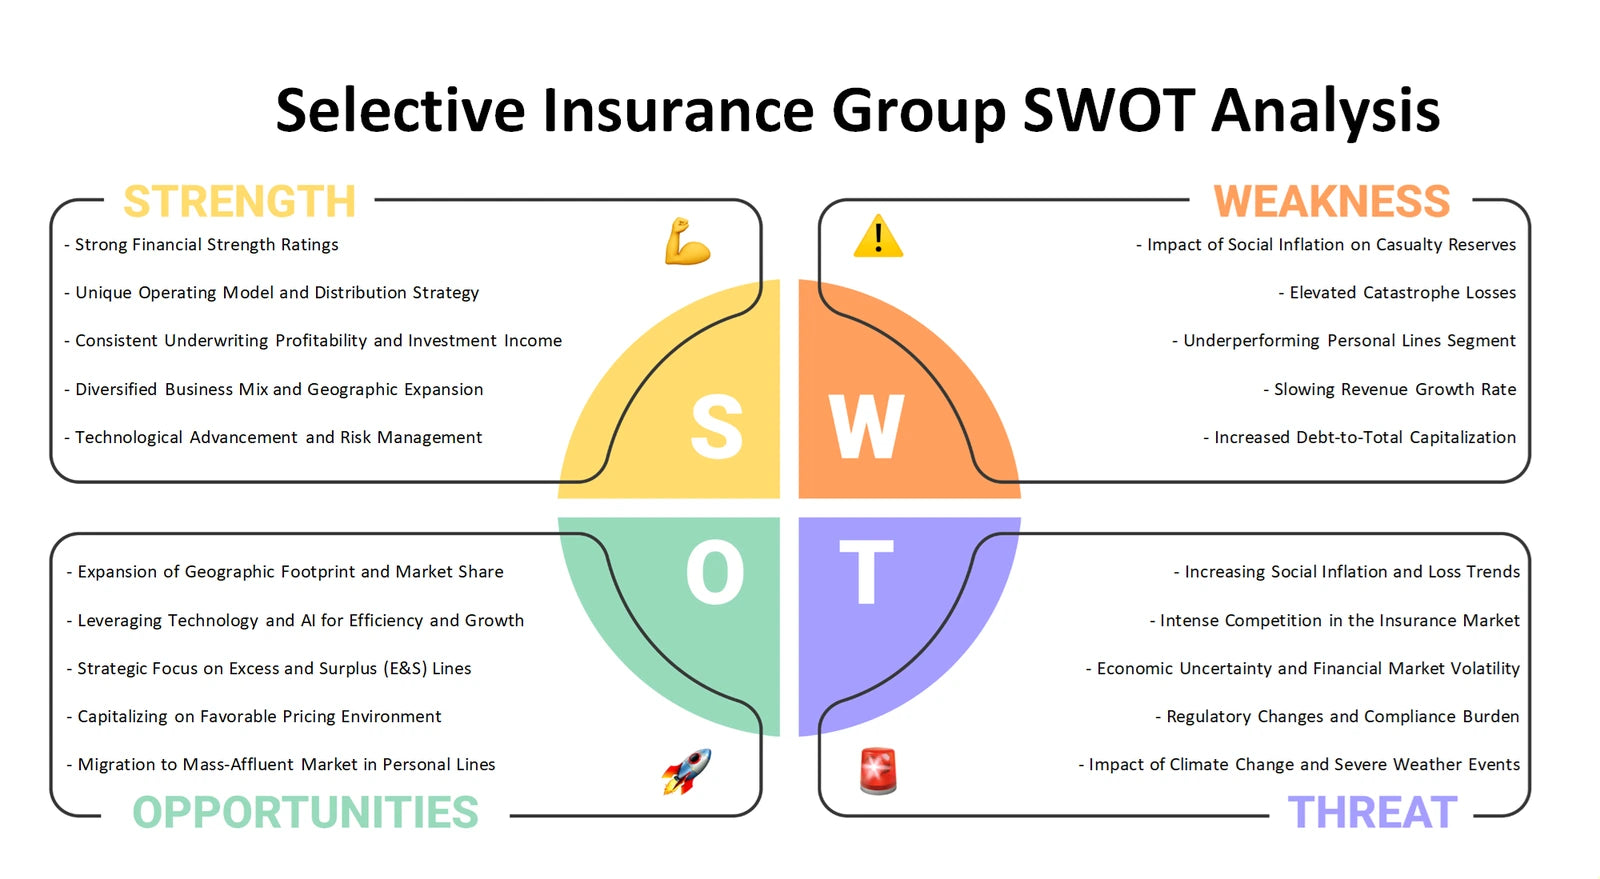
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of Selective Insurance Group
Together, the six perspectives move from portfolio choices and business-model economics to industry pressure, customer delivery, external change and strategic fit. The Excel frameworks provide a structured way to organize questions and comparisons, while the detailed Word files help users interpret those topics in the context of Selective Insurance Group's insurance operations, reinsurance relationships, technology priorities and regulatory environment.
Company background: Selective Insurance Group — SEC company submissions profile.