

Secure Trust Bank: Banking Business and Lending Economics – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Secure Trust Bank Strategy Analysis Bundle
Secure Trust Bank is a British retail bank serving savings and lending customers. Its official website describes a business providing savings accounts and lending services to more than one million customers, with roots dating to 1952. That combination makes customer trust, responsible credit decisions, deposit funding and accessible service channels central subjects for strategic analysis.
The bundle helps turn those connected questions into a structured view: which activities merit portfolio attention, how deposits and lending create value, and how regulation, customer expectations and digital delivery can shape choices. These are analytical questions rather than claims about current results or prescribed decisions for Secure Trust Bank.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which savings, consumer lending and specialist lending activities should receive the greatest management attention under different market conditions?
A Secure Trust Bank BCG Matrix provides a disciplined way to compare activities using market growth and relative market share. Rather than assuming a product belongs in a particular quadrant, it frames the evidence needed to test whether an activity behaves more like a Star, Cash Cow, Question Mark or Dog. For a retail bank, that comparison matters because capital, operational capacity, credit expertise and marketing expenditure cannot be expanded everywhere at once. It can also distinguish stable, cash-generative customer relationships from areas where growth may require greater investment, controls or capability.
- Portfolio logic. Compare lending and savings corridors by their growth context, relative competitive position and resource demands rather than by revenue alone.
- Funding connection. Consider how deposit gathering supports lending capacity, while recognising that the two activities may have different market dynamics and economics.
- Working view. Use the Excel matrix to organise assumptions and comparison criteria, then use the Word analysis to explore the strategic rationale behind possible priorities.
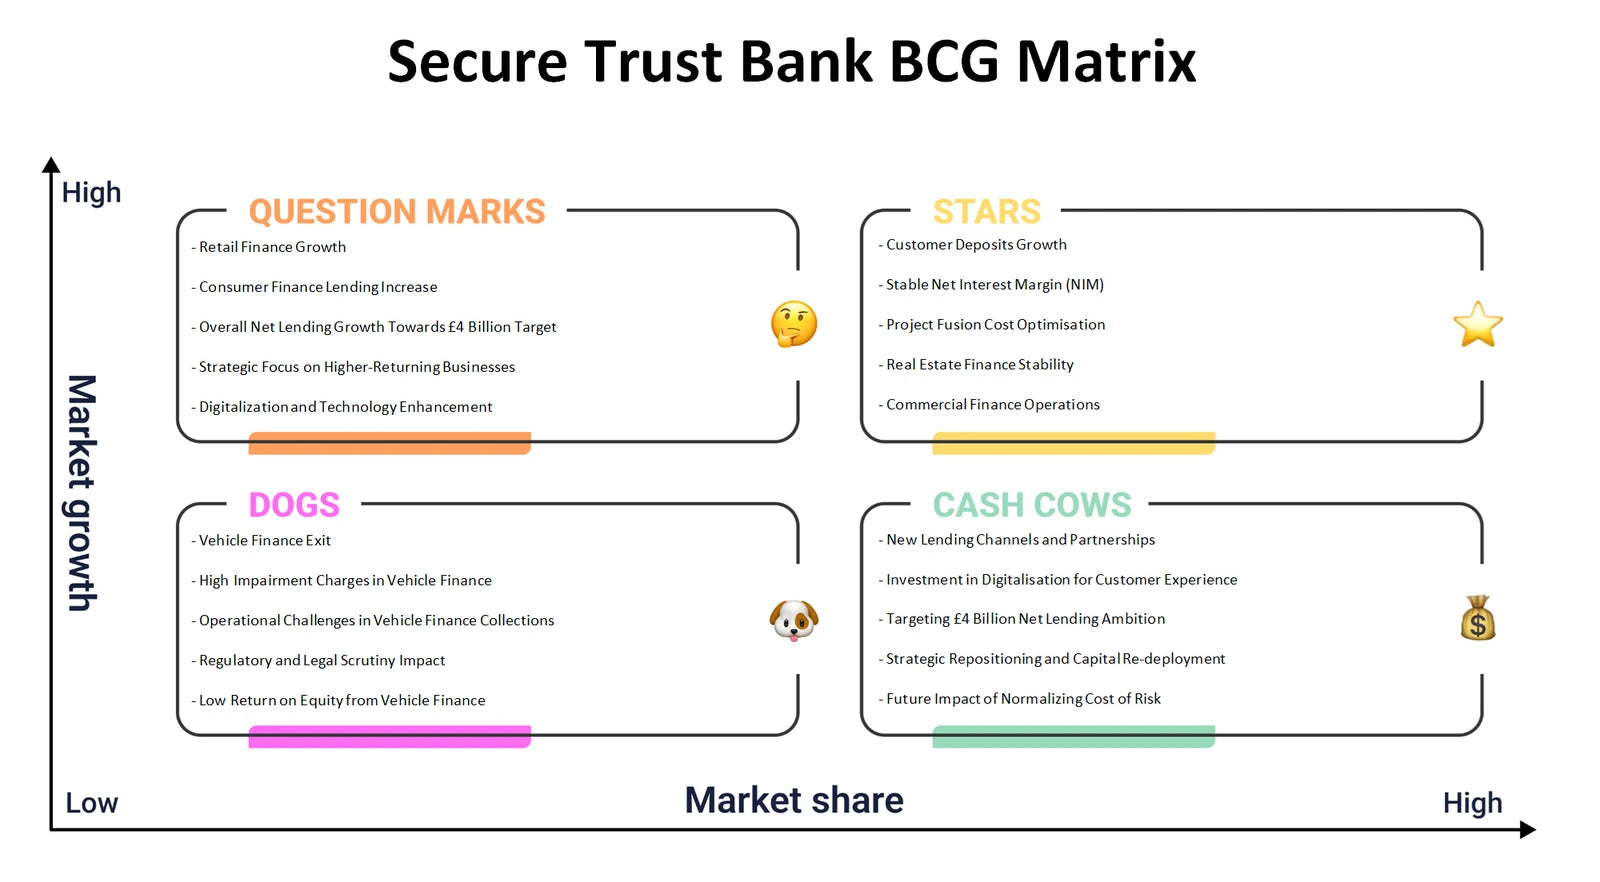
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do Secure Trust Bank’s customer relationships, funding model and lending operations fit together to create and retain value?
The Secure Trust Bank Business Model Canvas examines the full operating logic of a retail bank, not simply its products. It connects customer segments and value propositions to channels and customer relationships, including the practical importance of phone, web, app and chat support. It also considers revenue streams alongside key resources, key activities, key partnerships and cost structure. Savings balances can be explored as a source of funding, while lending, servicing, collections and risk management can be considered as linked activities that influence income, losses, customer outcomes and operating cost. The result is a coherent picture of how value delivery and economics may reinforce or constrain each other.
- Customer journey. Map the needs of savers and borrowers from acquisition through account use, servicing, repayment support and retention.
- Economic links. Test the relationships among deposit funding, lending margins, credit control, customer care and the cost of operating multiple service channels.
- Model alignment. Populate the Excel canvas as a one-page working map, then use the Word analysis to add context to the dependencies between its nine building blocks.
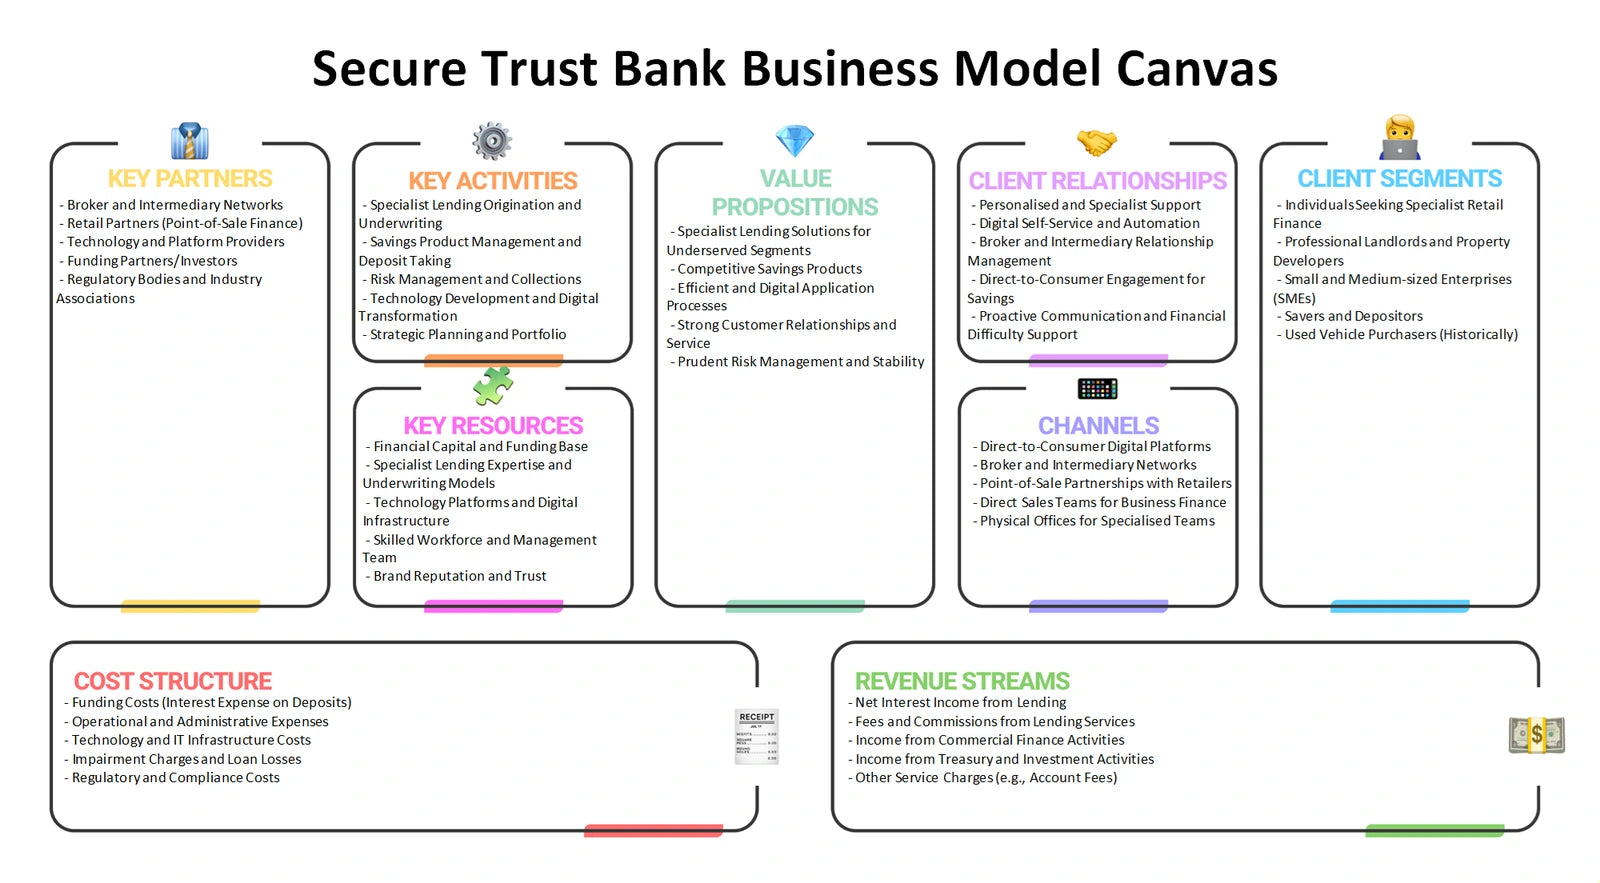
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could affect the attractiveness and resilience of retail savings and lending activities?
Secure Trust Bank Porter’s Five Forces analysis looks beyond the organisation to the conditions surrounding UK retail banking. Rivalry can be examined through competition for deposits, borrowers and trusted customer relationships. Supplier power is relevant to funding sources, technology providers and specialist operational partners, while buyer power reflects customers’ ability to compare rates, switch providers or demand better service. The threat of new entrants considers the barriers created by regulation, capital, trust and infrastructure. Substitutes include other ways customers can save, borrow or manage money, not only direct bank competitors. This lens helps make industry pressure explicit before strategic options are weighed.
- Competitive pressure. Assess where transparent pricing, digital comparison tools and established financial brands may increase rivalry for customer balances and lending demand.
- Dependency tests. Explore how reliance on funding, technology and external partners could influence cost, service continuity or strategic flexibility.
- Evidence trail. Use the Excel framework to record each force and supporting observations, while the Word analysis helps explain why a pressure could matter for the business model.
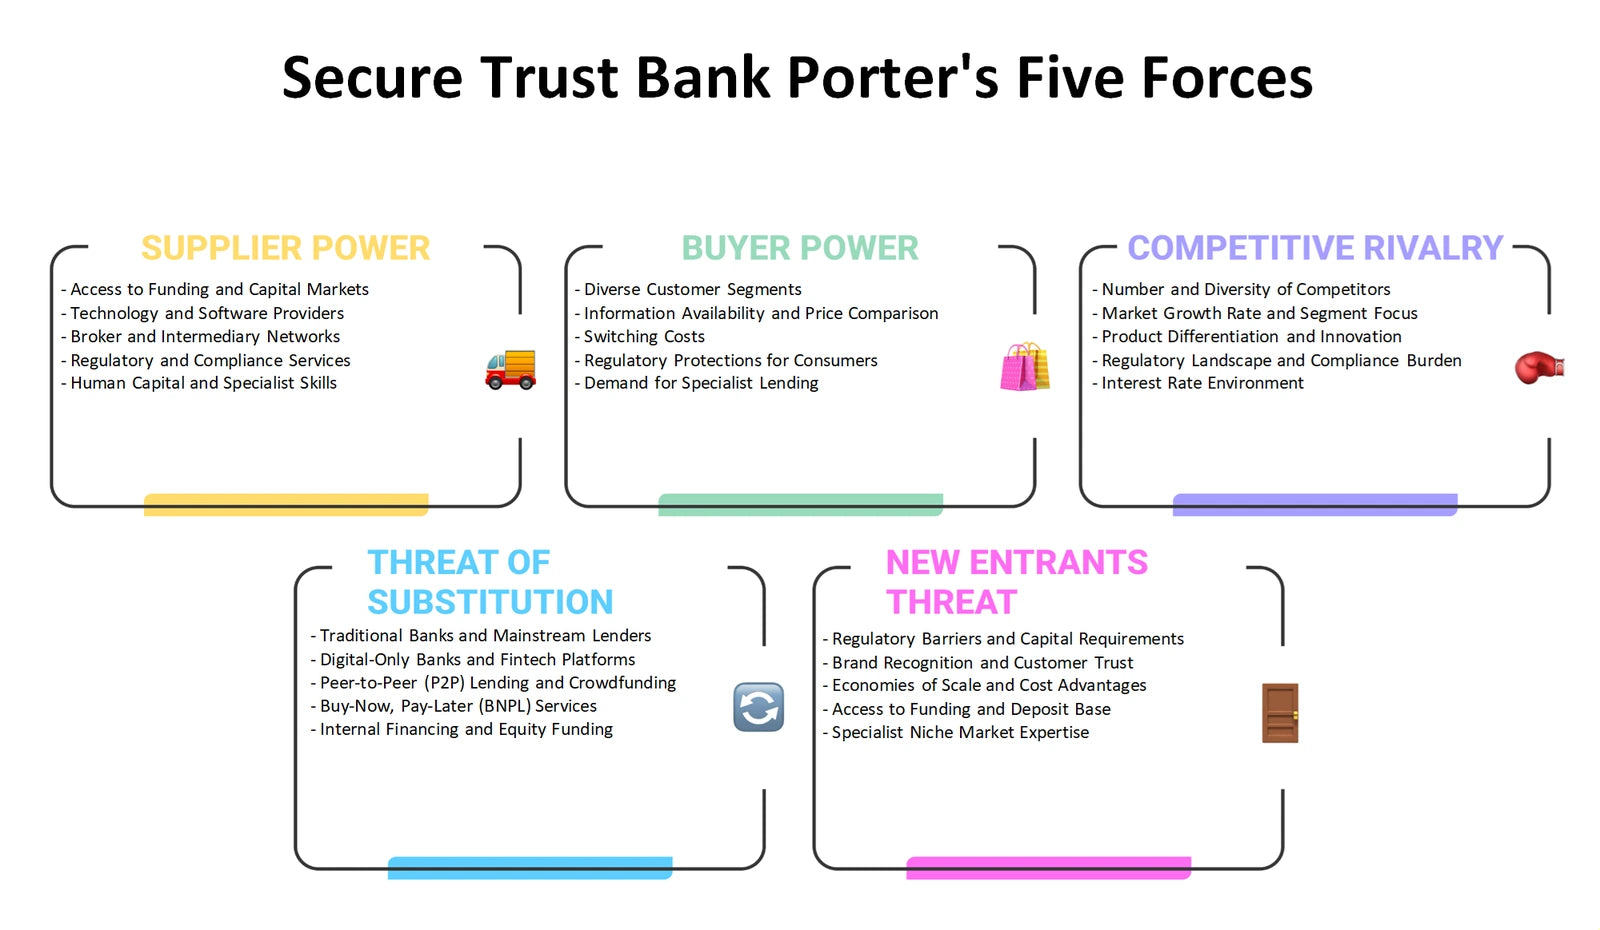
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a regulated retail bank align its offerings, pricing communication, customer access and promotion with trust-based decision making?
The Secure Trust Bank Marketing Mix applies Product, Price, Place and Promotion to savings and lending rather than treating marketing as advertising alone. Product analysis considers account and credit features, customer protections and the clarity of service. Price examines rates, fees and lending terms as information customers compare carefully, while recognising that responsible communication is important in financial services. Place covers the routes through which customers research, apply, transact and seek support, including digital and assisted channels. Promotion considers how a bank explains value, eligibility and risk without creating unrealistic expectations. Together, the four Ps help link customer acquisition to informed choice and long-term relationship management.
- Offer clarity. Compare how savings and lending propositions communicate usefulness, accessibility, eligibility and customer support at different life-cycle stages.
- Channel fit. Examine whether web, app, phone, chat and other service touchpoints support both efficient delivery and customers who need help.
- Campaign planning. Use the Excel 4Ps structure to compare messaging and channels, then consult the Word analysis for the business and regulatory considerations behind each choice.
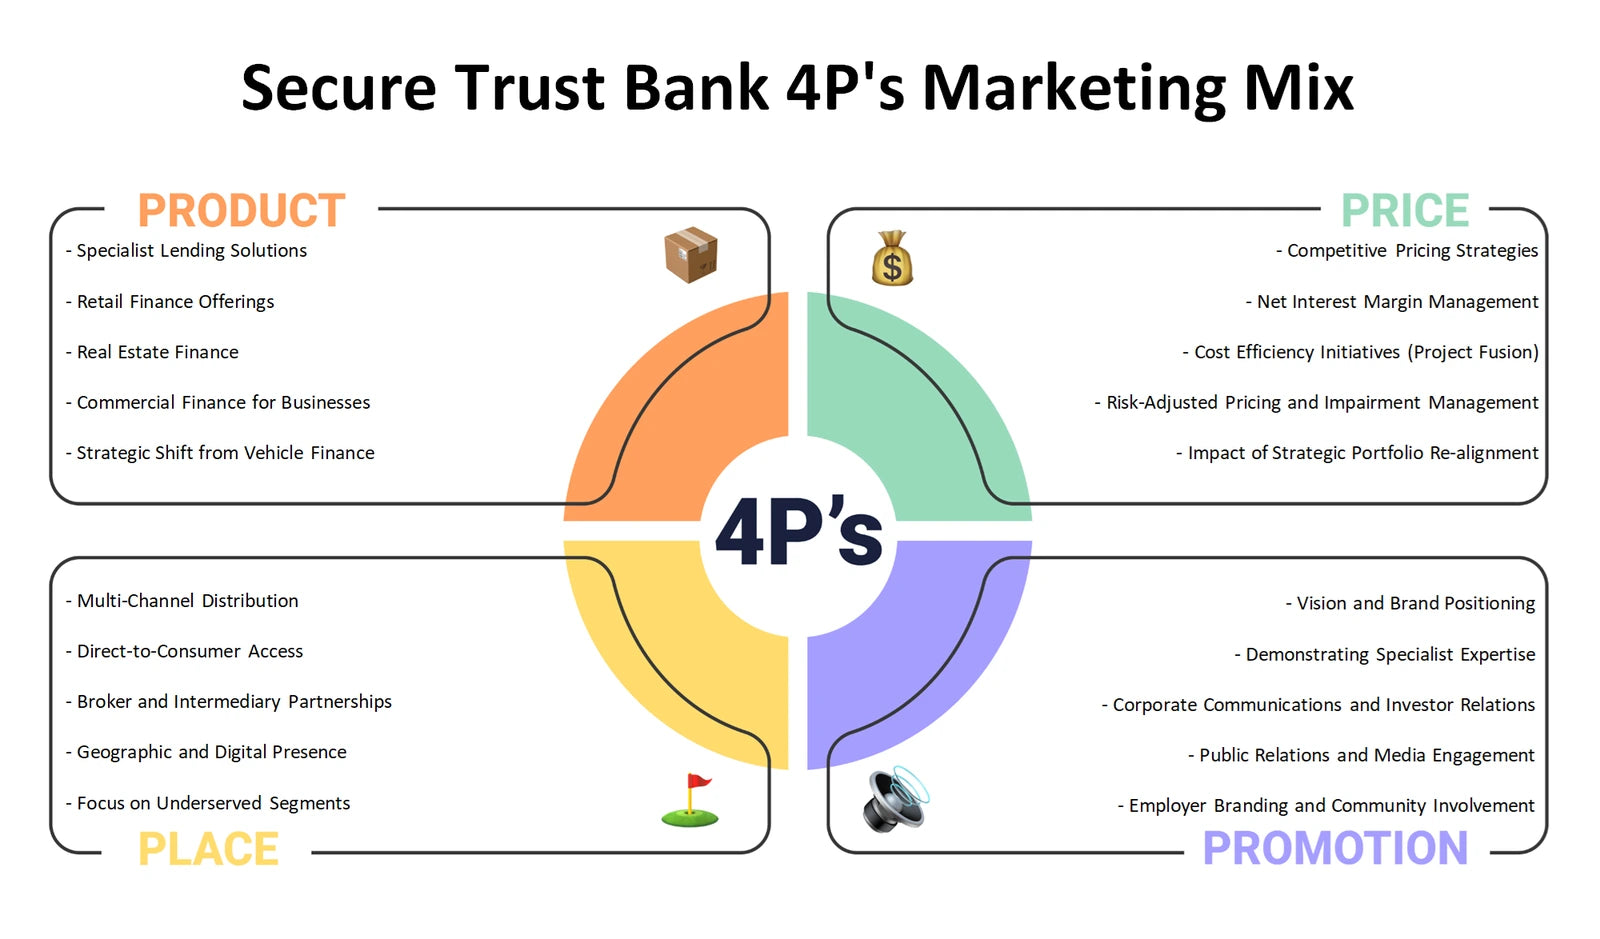
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes should a British retail bank monitor when planning savings, lending and customer-service priorities?
A Secure Trust Bank PESTLE analysis, also commonly called PESTEL, separates external influences from internal capabilities. Political conditions can affect the policy environment for financial services; economic conditions can change savings behaviour, funding costs and borrowers’ repayment capacity. Social factors include confidence, financial wellbeing and expectations for fair treatment. Technological change raises questions about digital access, fraud prevention, data security and service design. Legal considerations include conduct, consumer protection and prudential obligations, while environmental factors can influence risk assessment, customer expectations and operational resilience. The framework does not assume a particular policy, law or interest-rate movement; it helps identify the questions that require monitoring.
- External scan. Separate macroeconomic and policy questions from social, technological and environmental trends that may affect customers or operations differently.
- Risk relevance. Relate external developments to lending affordability, savings demand, service resilience, compliance workload and responsible customer outcomes.
- Monitoring tool. Use the Excel categories to log signals and possible implications, with the Word analysis providing fuller explanations for prioritising discussion topics.
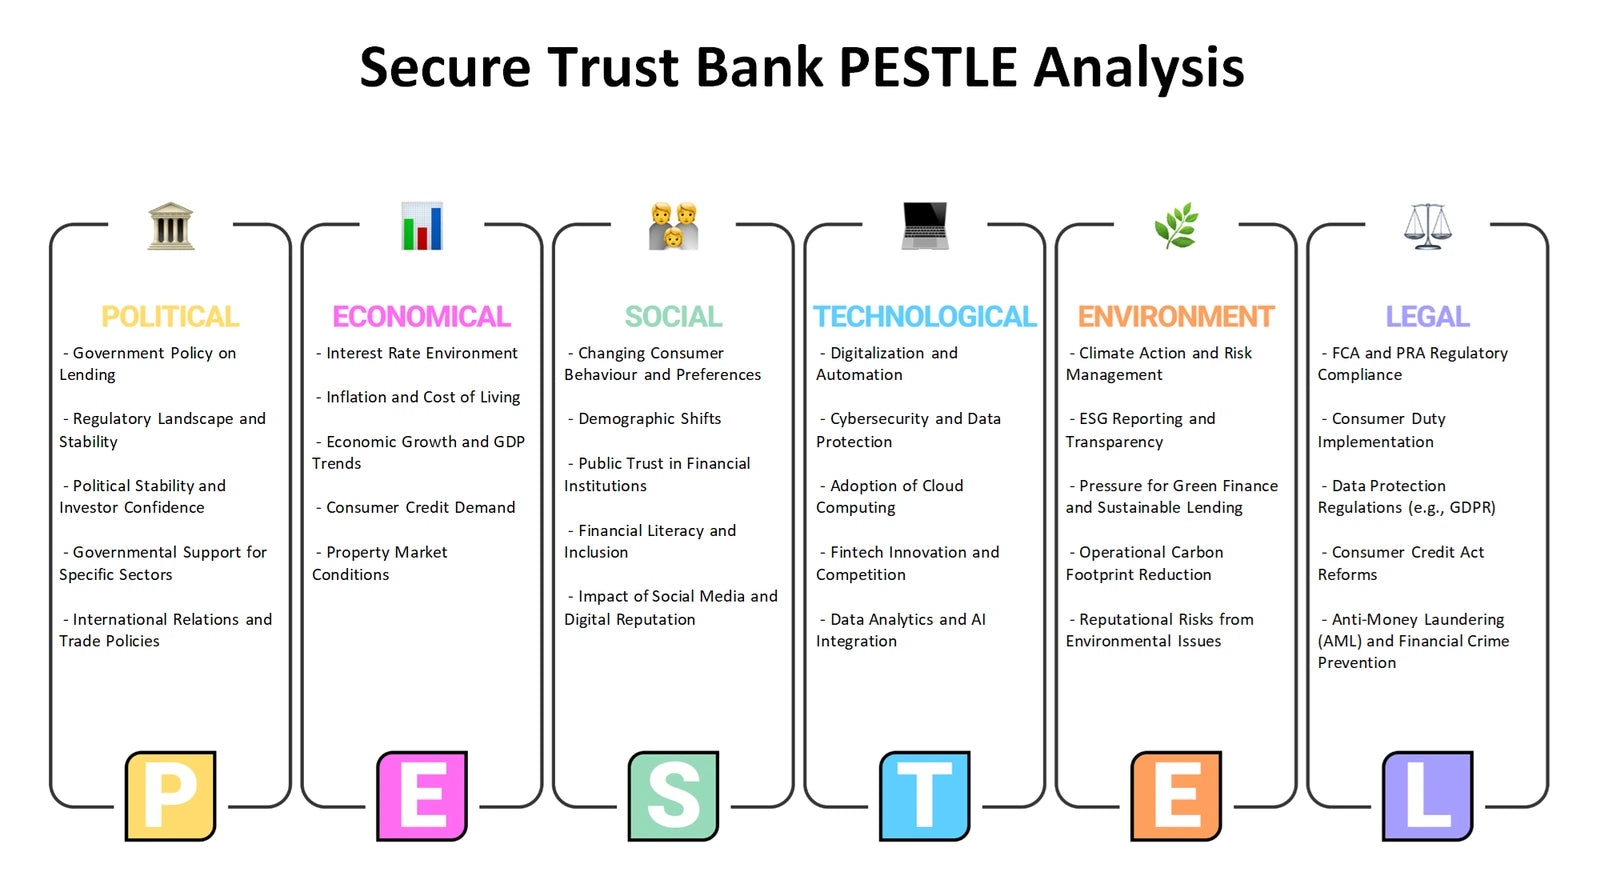
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Secure Trust Bank distinguish what it can control from the market conditions it must respond to?
The Secure Trust Bank SWOT analysis brings the previous lenses together while preserving an important distinction: strengths and weaknesses are internal, whereas opportunities and threats are external. Potential internal discussion areas may include the ability to manage retail deposits, lending expertise, customer servicing processes, collections capability and omnichannel support. Those are not automatic conclusions; the framework helps test whether available evidence supports them as strengths or exposes limitations. External opportunities and threats can then be considered against changes in customer demand, competition, technology, economic conditions and regulation. This prevents a broad list of issues from being confused with a prioritised strategic conversation.
- Internal assessment. Examine capabilities, resources, process constraints and customer-service consistency separately from trends outside the bank’s direct control.
- Strategic fit. Explore which external opportunities may suit existing capabilities and which threats could expose weaknesses in funding, credit management or delivery.
- Decision workshop. Use the Excel SWOT grid to organise evidence and questions, then use the detailed Word analysis to support a more nuanced management discussion.
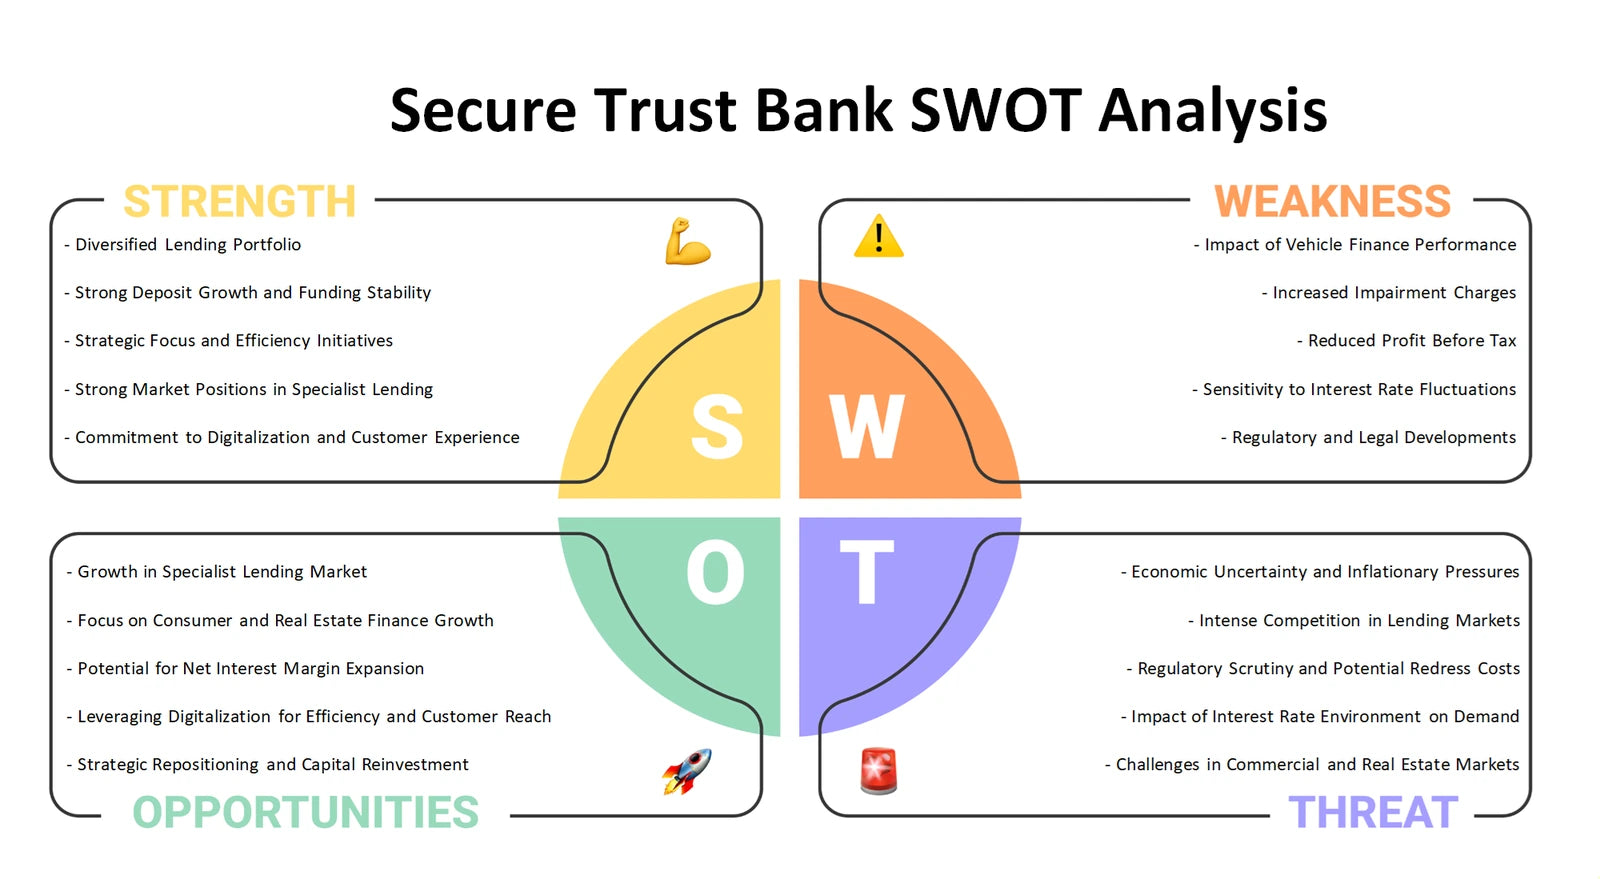
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of Secure Trust Bank
The six perspectives work best together: the Canvas explains value creation, Five Forces and PESTLE examine the outside environment, the 4Ps focuses on customer delivery, BCG supports portfolio questions, and SWOT brings internal and external considerations into one discussion. The Excel frameworks and detailed Word analysis materials provide a practical starting point for structured comparison, workshops and company-specific strategic thinking.
Company background: Secure Trust Bank — official website.