

Shanghai Commercial & Savings Bank: Banking Business and Distribution – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Shanghai Commercial & Savings Bank Strategy Analysis Bundle
The supplied business context for Shanghai Commercial & Savings Bank describes a banking model serving retail and corporate needs through account services, payments and cards, advisory support, wealth and brokerage distribution, and trade-finance services including letters of credit and guarantees. These activities combine relationship-led financial services with regulated risk, compliance and operational responsibilities.
The bundle helps turn that operating model into structured strategic questions rather than unsupported conclusions. It can be used to examine how fee-based services, lending and transaction activity interact; how client needs differ across consumer and business banking; and how regulatory engagement, digital delivery and risk management affect choices over priorities, positioning and resilience.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking services deserve resources when growth potential and relative market share may differ across customer needs?
The Shanghai Commercial & Savings Bank BCG Matrix provides a disciplined way to compare a portfolio of banking activities using market growth and relative market share. Rather than assuming that accounts, cards, transaction banking, advisory, wealth distribution or trade finance have the same strategic role, it helps assess where each activity may sit on the path between Stars, Cash Cows, Question Marks and Dogs. In banking, the analysis also prompts practical questions about capital use, risk appetite, service capacity and cross-selling: a fast-growing service can require investment, while a mature relationship service may provide steadier economics.
- Portfolio comparison. Compare retail and corporate service lines by their market context, competitive position and strategic contribution without assigning unsupported quadrant placements.
- Resource discipline. Consider whether technology spending, specialist staff, compliance support and relationship-management effort match the growth and share evidence available for each activity.
- Working view. Use the Excel matrix to organise service assumptions and evidence, then use the Word analysis to record why a category may warrant investment, protection, testing or restraint.
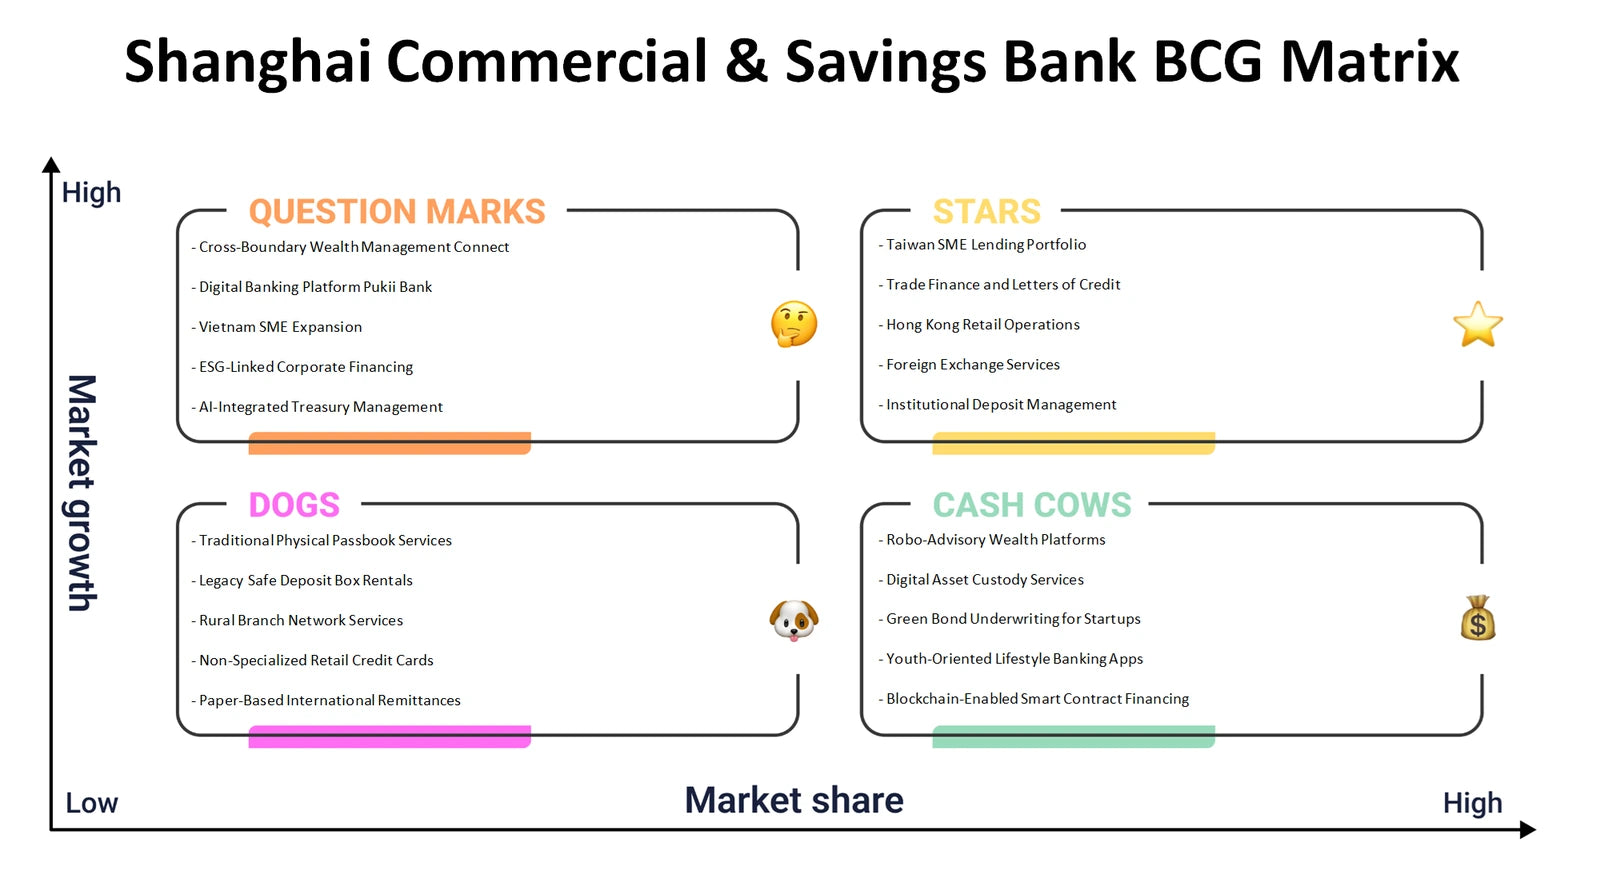
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer relationships, regulated delivery and fee-generating services fit together in one banking model?
The Shanghai Commercial & Savings Bank Business Model Canvas links the nine building blocks behind value creation and economics. It helps map customer segments such as individual account holders and corporate banking clients; value propositions including secure transactions, financial access and trade-finance support; and channels and customer relationships that make those services usable. It also connects revenue streams such as account, payment, card, advisory, wealth-distribution, brokerage and trade-finance fees with key resources, activities, partnerships and cost structure. This matters because a banking offer cannot be understood from income alone: trust, risk controls, technology, skilled staff, regulatory processes and partner networks shape both delivery quality and cost.
- Value chain logic. Trace how a client need moves from account access or payment execution to servicing, controls, relationship support and an identifiable revenue stream.
- Operating dependencies. Examine how key resources, activities and partnerships may influence reliability, compliance, distribution reach and the cost to serve each segment.
- Connected planning. Populate the Excel canvas as a one-page model, then use the detailed Word analysis to test whether changes in one block create consequences for the others.
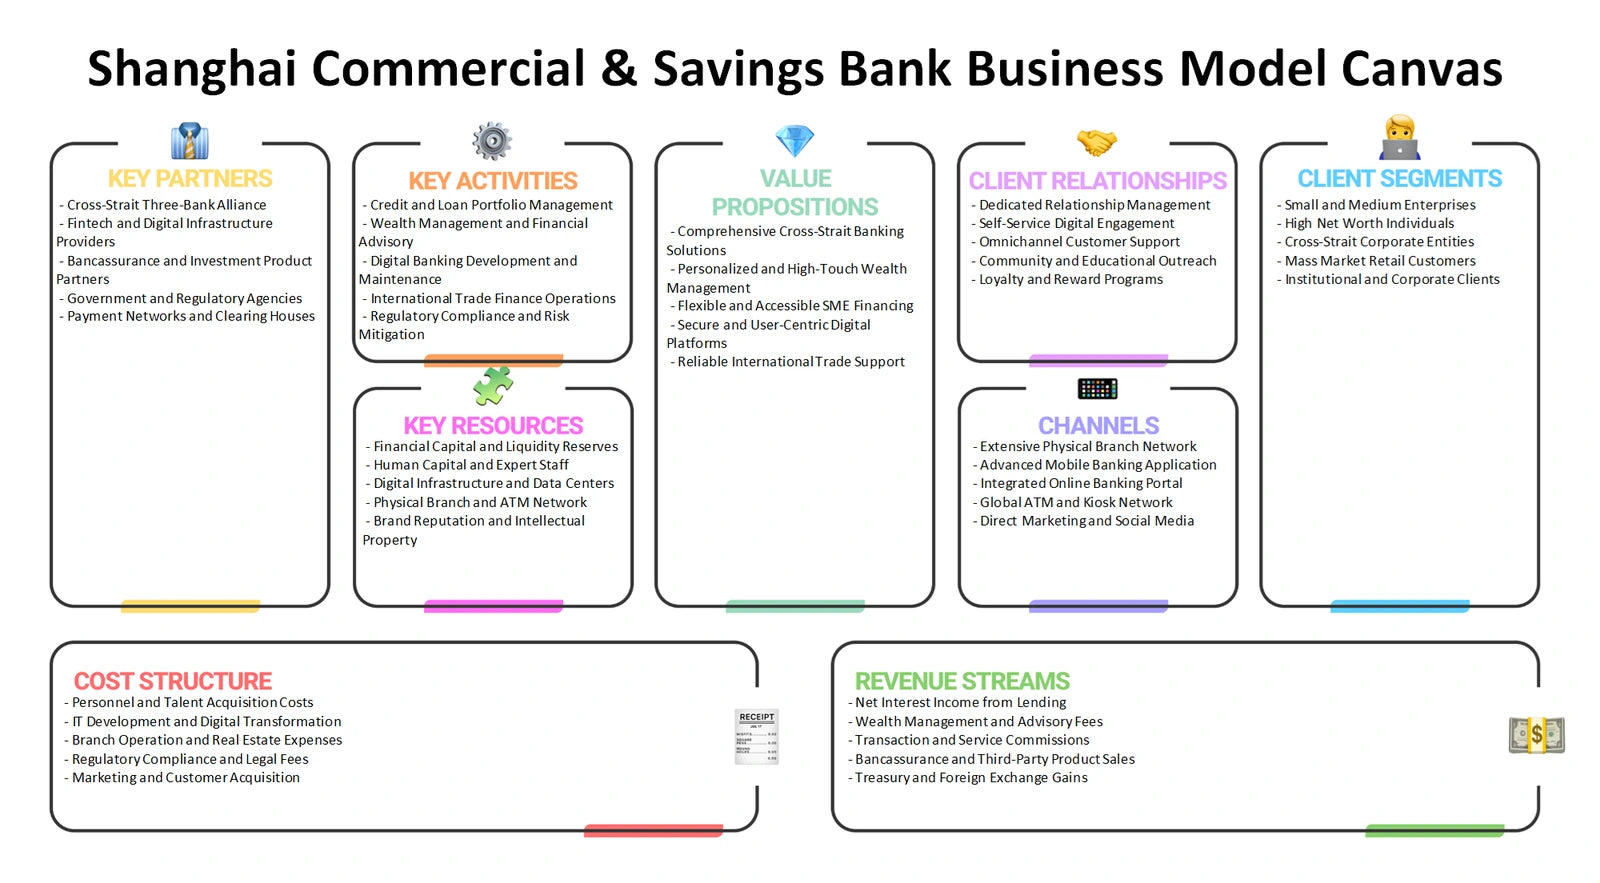
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could shape the economics of transaction, relationship and trade-finance banking services?
Shanghai Commercial & Savings Bank Porter's Five Forces examines the competitive structure around the banking activities described in the supplied context. Rivalry considers competition for deposits, payment activity, corporate relationships and fee income. Buyer power considers how retail customers and business clients can compare service quality, pricing and convenience. Supplier power can include dependence on funding, technology, specialist talent and external infrastructure. The threat of new entrants considers barriers created by licensing, trust, capital and compliance, while substitutes extend beyond direct banks to alternative ways customers make payments, obtain financial advice, manage investments or finance trade. The purpose is not to declare force scores, but to make pricing and service choices more evidence-led.
- Competitive pressure. Identify where client switching, service comparison and product similarity could place pressure on margins or relationship retention.
- Substitution risk. Distinguish direct banking competition from alternative payment, investment, financing and advisory solutions that meet the same customer need.
- Evidence trail. Use the Excel framework to log each force and its indicators, while the Word analysis supports a narrative on implications for service design and risk priorities.
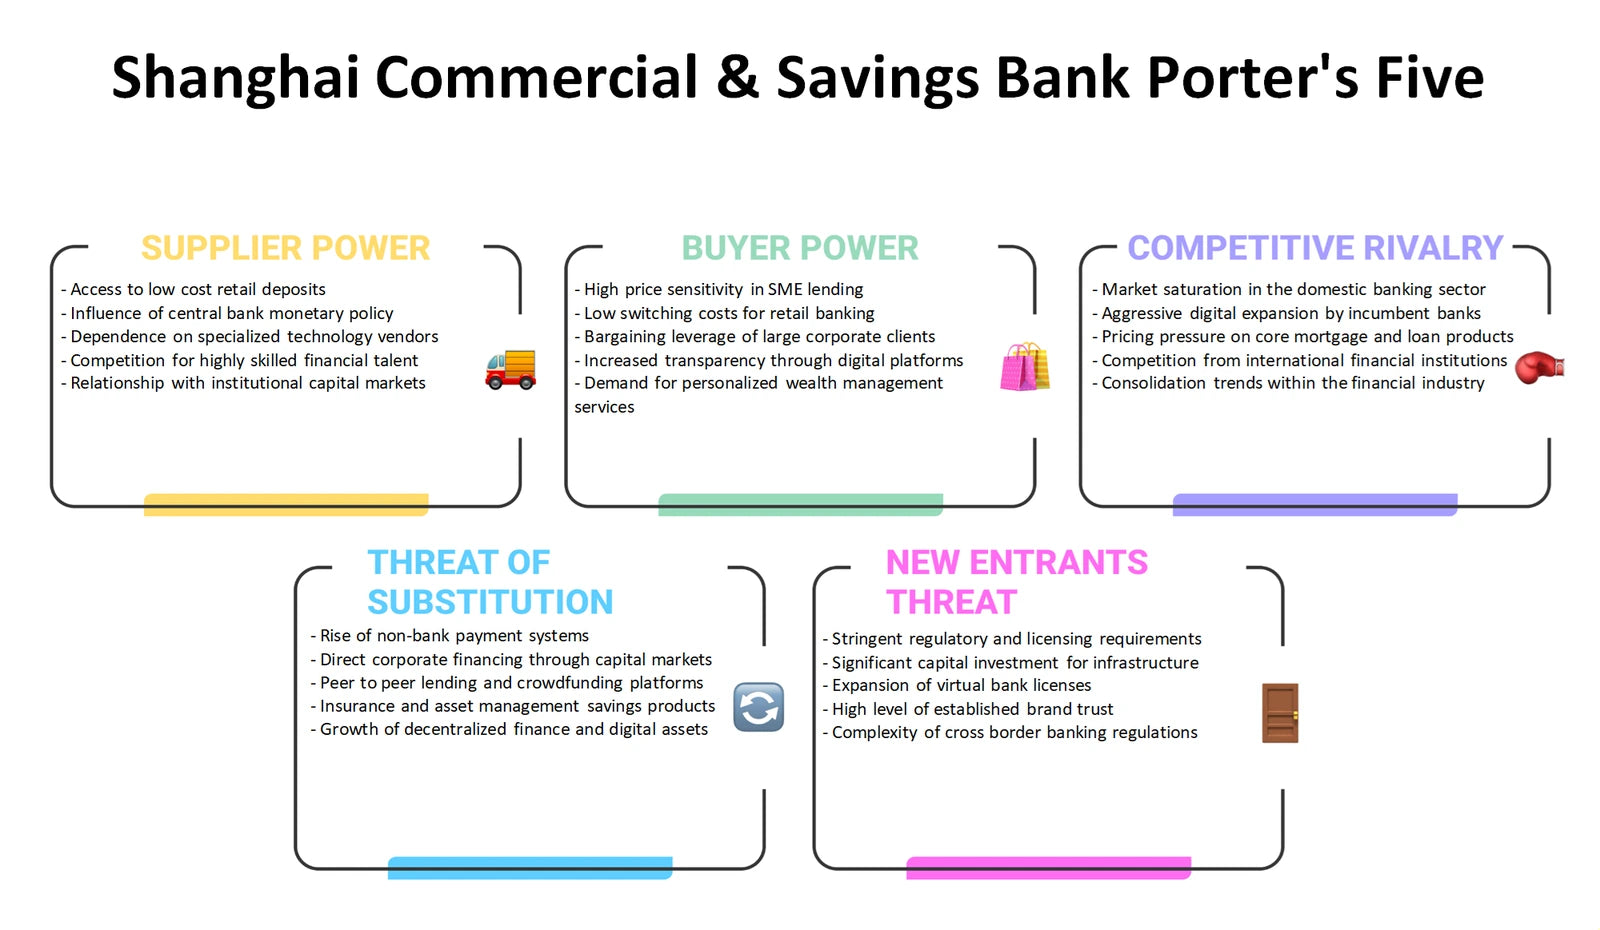
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can banking offers be positioned clearly when trust, pricing transparency and suitable channels affect client decisions?
The Shanghai Commercial & Savings Bank Marketing Mix applies Product, Price, Place and Promotion to a regulated financial-services setting. Product analysis can examine the fit between accounts, payment and card services, advisory, wealth-related distribution and corporate trade-finance support. Price focuses on the logic of fees and commissions, including how account maintenance, transactions, card interchange, advisory work, brokerage activity and guarantees may reflect service complexity, client segment and risk exposure. Place considers the routes through which customers access service, including relationship-led and digital delivery where relevant to the model. Promotion asks how communications can explain value, terms and trust without overstating benefits or overlooking compliance requirements.
- Offer architecture. Assess whether products are understandable for retail clients while still allowing corporate customers to evaluate specialised banking and trade services.
- Price-value fit. Explore how transparent fee tiers and service levels could support perceived value while recognising operational and risk costs.
- Market alignment. Use the Excel 4Ps layout to compare customer-facing choices, then use the Word analysis to document trade-offs across product scope, pricing, access and communication.
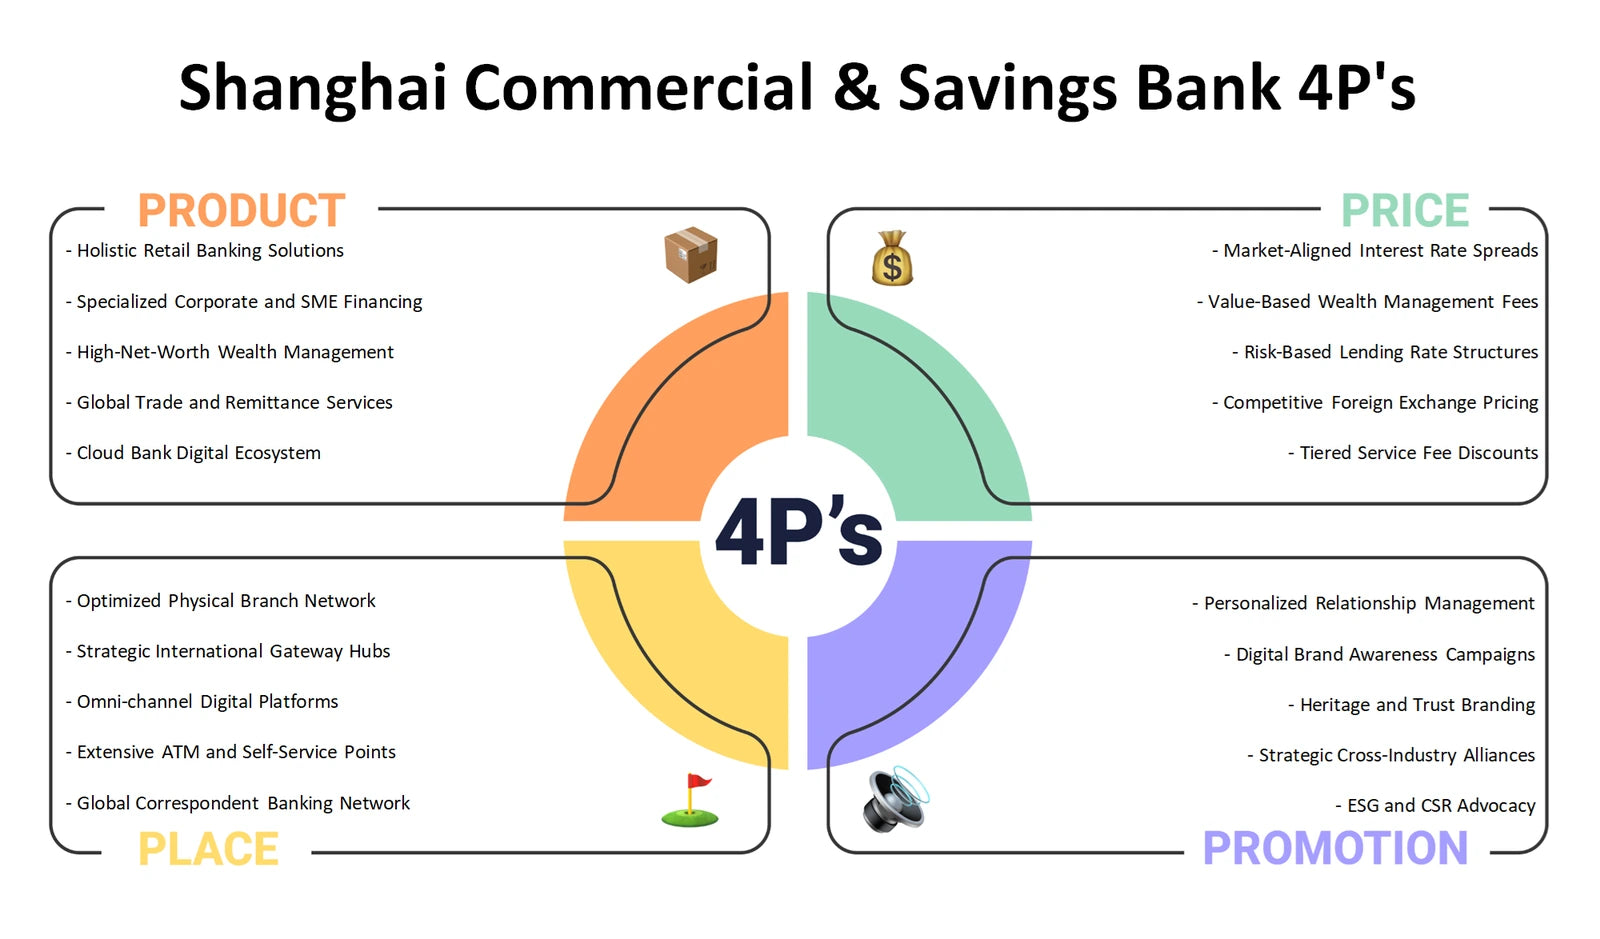
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could alter the operating conditions for a bank reliant on customer confidence and regulatory discipline?
The Shanghai Commercial & Savings Bank PESTLE analysis, also known as PESTEL, separates external influences from internal capabilities. Political factors can include public-policy direction and supervisory priorities; economic factors can include credit conditions, funding costs, trade activity and household or business confidence. Social factors cover changing expectations for convenience, advice, security and responsible treatment. Technological factors address payment innovation, cyber resilience, data governance and service automation. Legal factors focus on licensing, conduct, anti-financial-crime and consumer-protection obligations. Environmental factors can examine how climate-related risk, financed activity and stakeholder expectations could affect lending, trade or operational decisions. These are analytical categories, not claims that a particular rule or rate has changed.
- External scanning. Separate macroeconomic and policy signals from firm-controlled decisions so management discussions do not confuse conditions with capabilities.
- Regulatory readiness. Consider how engagement with regulators and industry forums may help identify implementation questions early and support operational resilience.
- Scenario record. Use the Excel framework to prioritise external signals by relevance, then use the Word analysis to develop concise scenarios, assumptions and response questions.
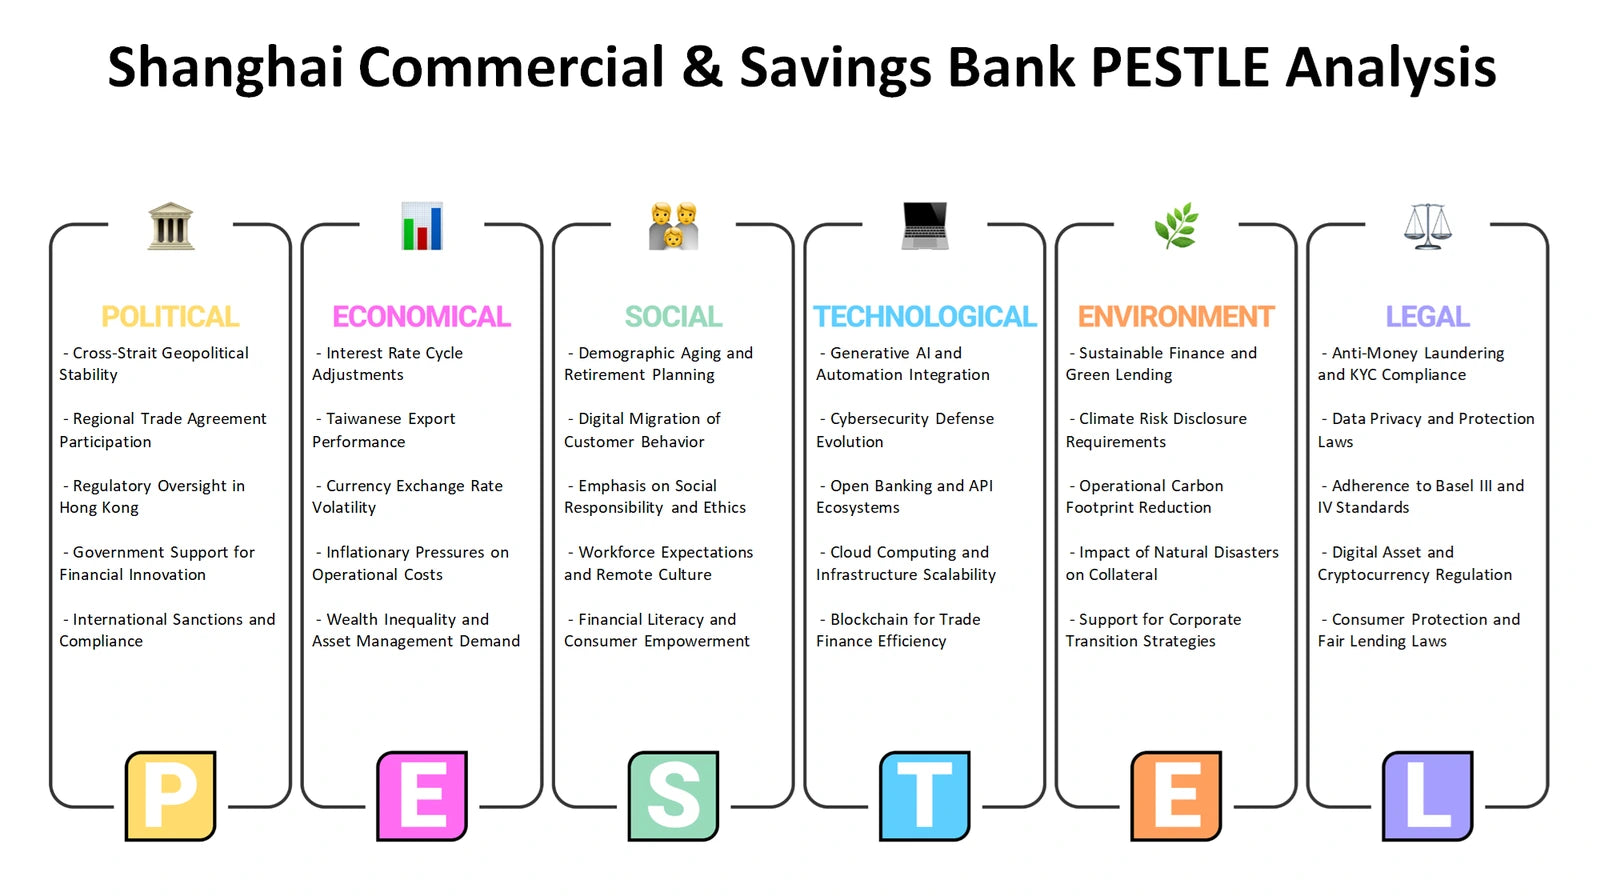
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal banking capabilities be weighed against external opportunities and threats without treating assumptions as proven findings?
The Shanghai Commercial & Savings Bank SWOT analysis brings together internal Strengths and Weaknesses with external Opportunities and Threats. It can help examine possible strengths such as service breadth, client relationships, risk-management processes or regulatory engagement, while testing the evidence rather than declaring them established advantages. Potential weaknesses may include execution complexity, legacy processes, cost pressures or gaps in channel capability; these are internal matters to investigate. Opportunities and threats belong outside the organisation and may arise from changing customer behaviour, payment innovation, trade flows, competition, economic conditions or regulatory expectations. This distinction matters because a useful SWOT does more than list issues: it connects a credible internal condition with an external situation that could amplify or constrain it.
- Clear classification. Keep capabilities and limitations inside the bank, while placing market, technology, policy and competitive developments in the external quadrants.
- Strategic matches. Explore how an evidenced capability could support an opportunity, or how an internal constraint may increase exposure to a particular threat.
- Decision support. Use the Excel SWOT grid to rank themes and ownership questions, then use the Word analysis to explain the reasoning and possible strategic responses.
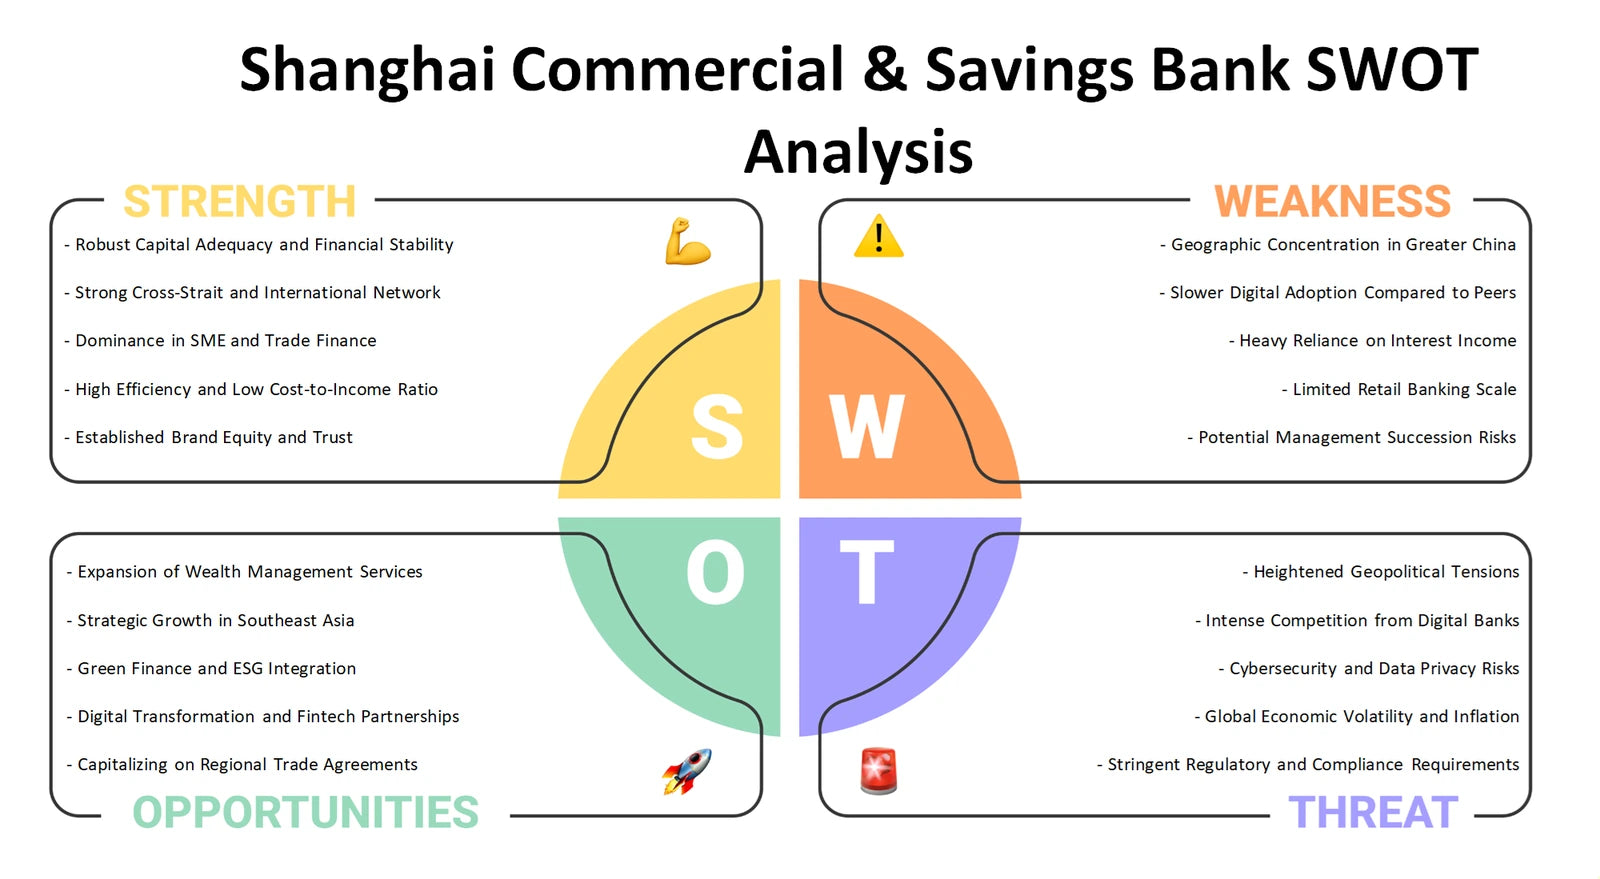
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices with the realities of banking delivery
Together, the six perspectives help customers develop a more connected strategic view of Shanghai Commercial & Savings Bank: BCG frames service priorities, the Canvas links value creation to economics, Five Forces tests industry pressure, the 4Ps focuses customer-facing choices, PESTLE scans the external environment, and SWOT brings internal and external considerations together. The Excel frameworks provide a structured place to organise comparisons and assumptions, while the Word files support deeper company-analysis discussion.
Company background: Shanghai Commercial & Savings Bank — product context page.