

SBI ARUHI: Franchise Relationships and Customer Demand in Six Frameworks

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
SBI ARUHI Strategy Analysis Bundle
This bundle addresses SBI ARUHI as the Japan-focused mortgage business described in the supplied product context: a provider of home-loan solutions serving borrowers through digital banking relationships and a franchise-led physical network. Its customer proposition sits at the intersection of long-term household borrowing, underwriting support and accessible advice, while stated links with SBI Group entities can matter to product delivery and distribution.
The supplied context points to collaboration with SBI Shinsei Bank, SBI Sumishin Net Bank, SBI Credit Guarantee and SBI Estate Finance, alongside a franchise model intended to broaden reach. These are business-background themes rather than independently verified current results. They make practical questions clearer: which activities deserve resources, how partnerships affect economics, and how digital and local channels can work together. The six analyses organise those questions in the accompanying Excel and Word materials.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which mortgage activities or routes to market should receive scarce growth resources?
The SBI ARUHI BCG Matrix examines activities or channel propositions through market growth and relative market share. It does not assume a quadrant placement. Instead, it helps frame choices among Stars, Cash Cows, Question Marks and Dogs: whether a digital referral route, franchise-supported access point or loan-related offering merits investment, maintenance, testing or restraint. That distinction matters when partnerships can extend reach but also create coordination costs.
- Portfolio boundary. Define comparable mortgage activities without mixing SBI ARUHI economics with those of partners or franchisees.
- Share logic. Compare relative share with an appropriate market definition while separating growth potential from a large market alone.
- Working view. Use the Excel framework to organise candidate activities, then use the Word analysis to document assumptions and resource questions.
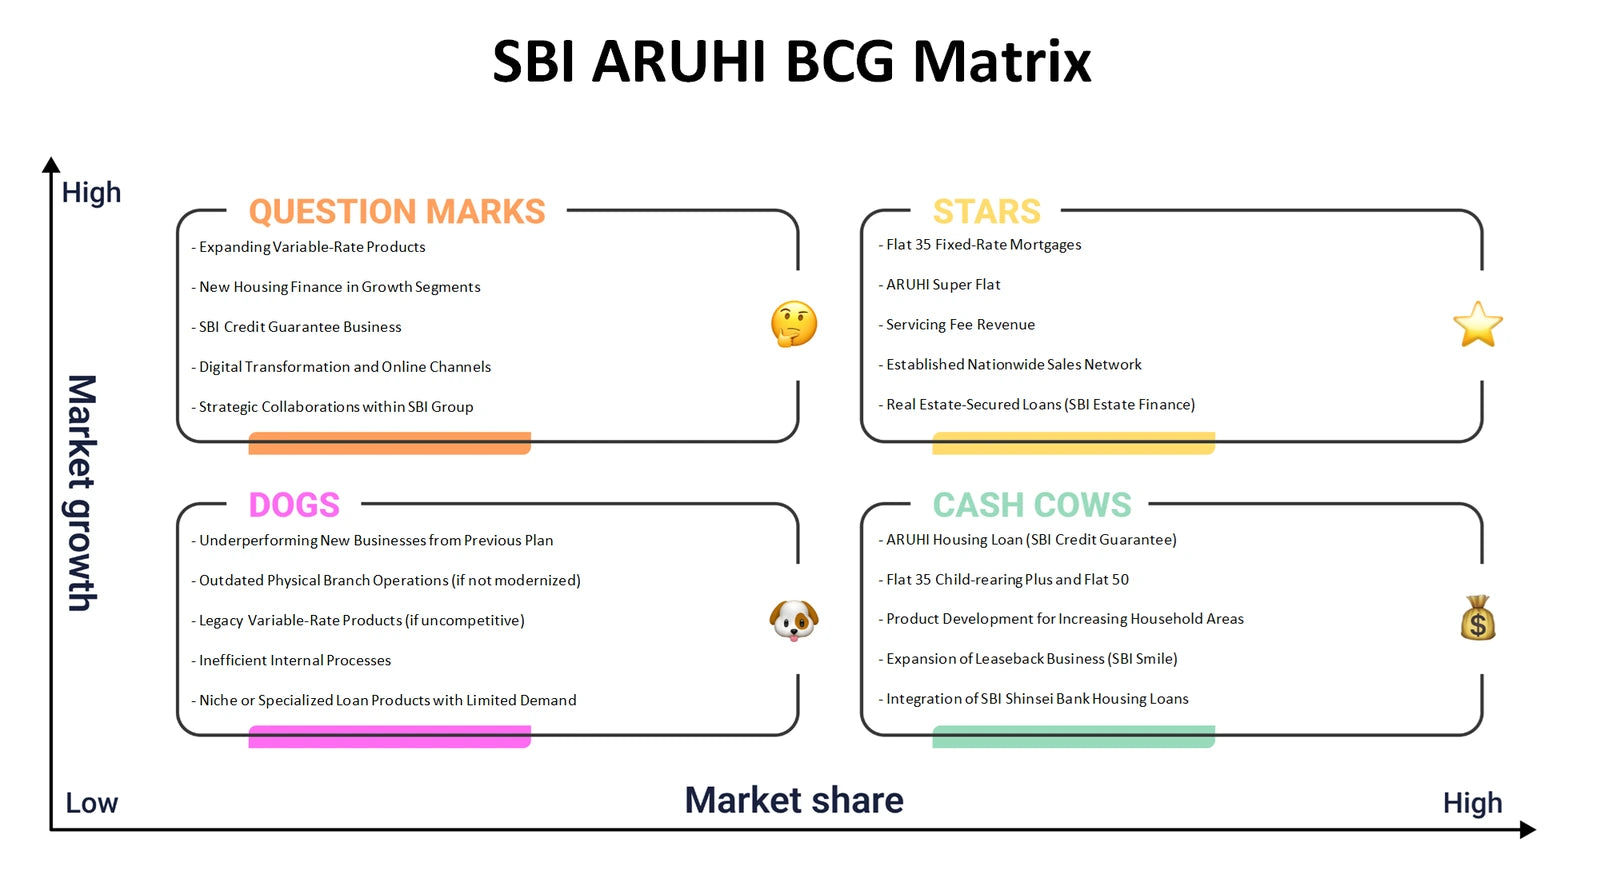
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do mortgage customers, partner institutions and franchise channels connect to value creation and earnings?
The SBI ARUHI Business Model Canvas brings together all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For a mortgage-oriented business, the useful issue is the connection between borrower access, credit-related support, distribution and the economics of originating or arranging loans. The stated SBI Group relationships and franchise model provide relevant themes to examine without assuming their precise commercial terms.
- Borrower journey. Trace how prospective home-loan customers move from information and advice to application, assessment and ongoing service.
- Partnership design. Test how bank, guarantee and estate-finance relationships may support delivery while adding dependencies or shared costs.
- Model mapping. Populate the Excel canvas systematically, using the Word analysis to explain important links and open evidence questions.
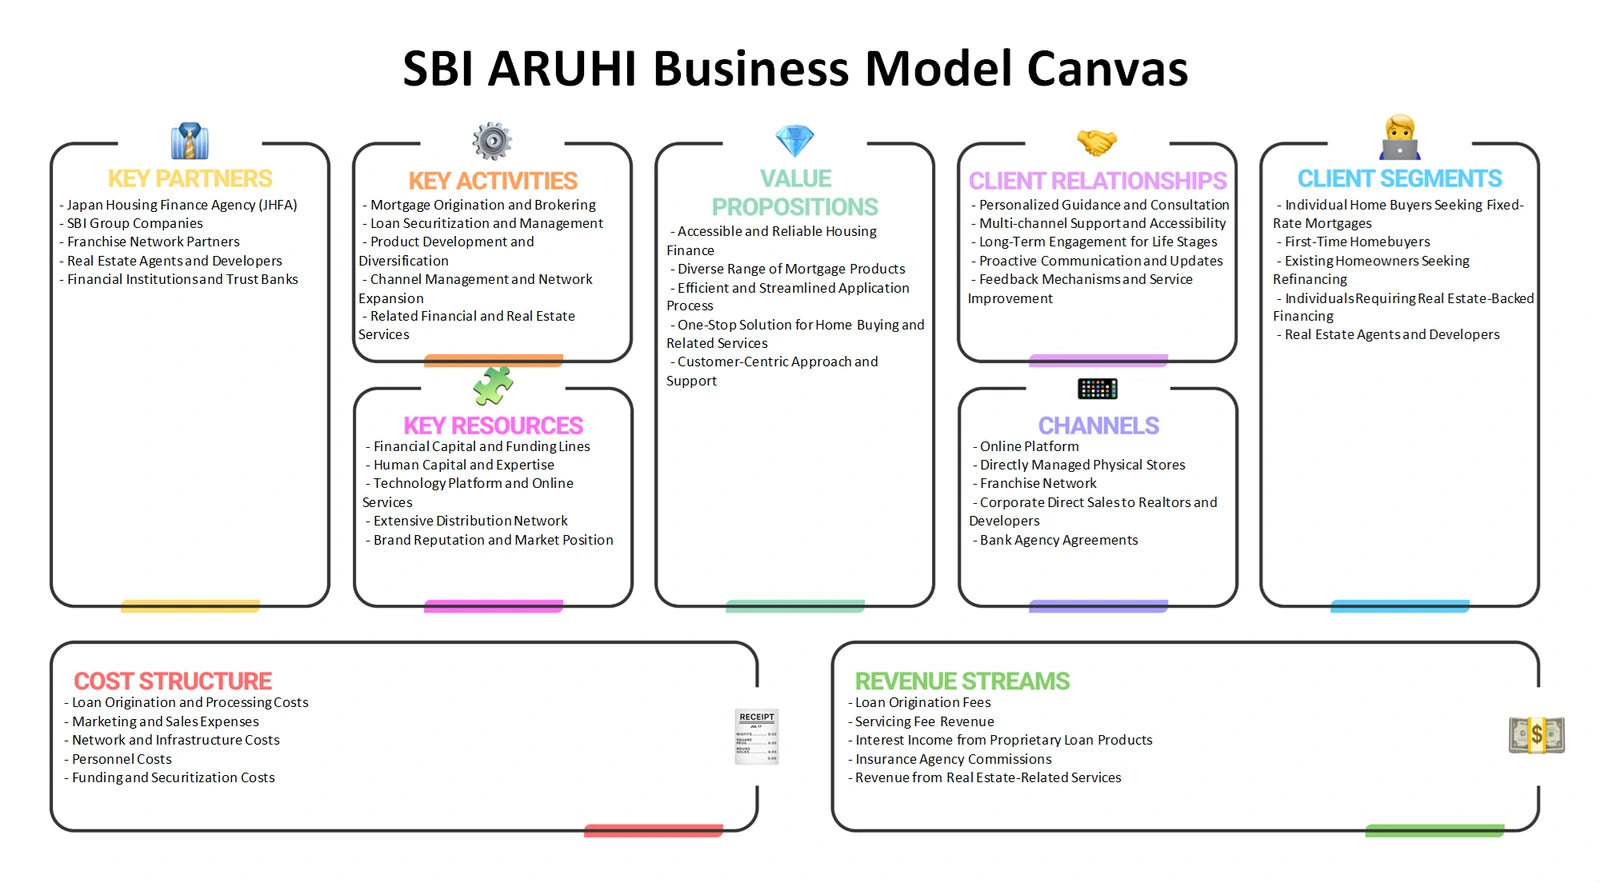
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What pressures shape profitability in the mortgage-finance and home-loan distribution environment?
SBI ARUHI Porter's Five Forces considers rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes around mortgage access. Rivalry may concern competing ways to source and serve borrowers; supplier power can include reliance on funding, technology or partner capabilities. Buyer power reflects borrowers’ ability to compare terms and service. Substitutes are alternative ways to meet housing-finance needs, not merely another direct lender. New entrants test the durability of distribution and trust.
- Industry perimeter. Set a relevant comparison frame for mortgage origination, brokerage, digital discovery and related financial support.
- Pressure points. Examine where pricing transparency, partner dependence or customer switching could influence bargaining positions.
- Evidence trail. Use Excel to record each force and supporting observations, while the Word file helps interpret interactions among them.
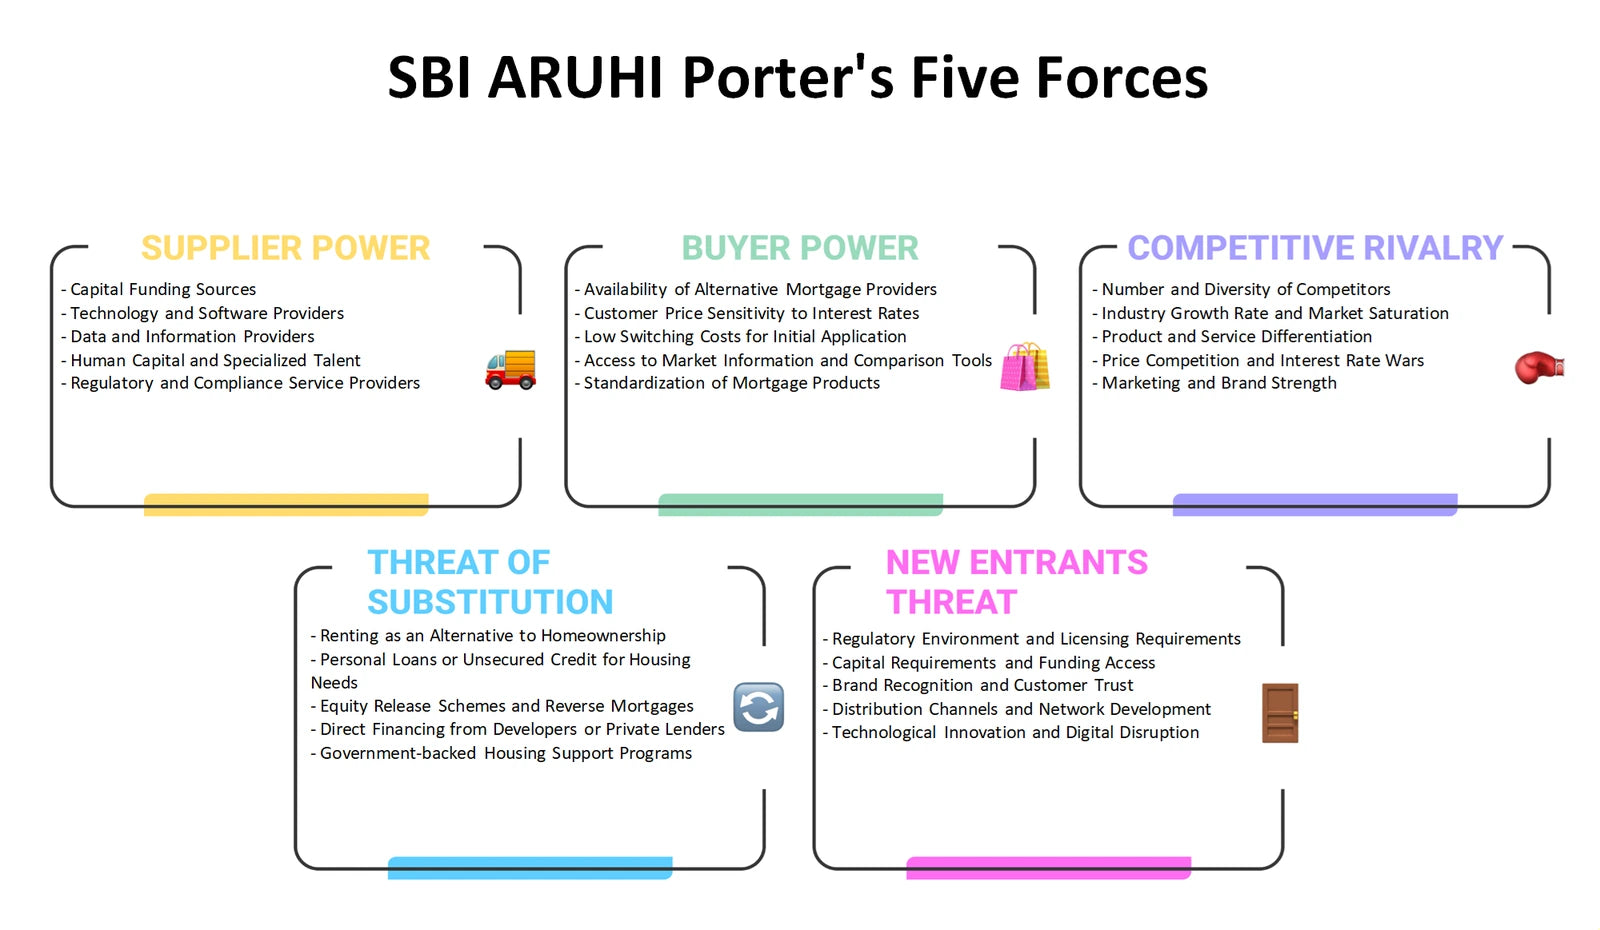
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a regulated mortgage proposition be communicated and delivered consistently across digital and local channels?
The SBI ARUHI Marketing Mix considers Product, Price, Place and Promotion for a customer making a consequential, long-term borrowing decision. Product analysis can distinguish loan structures, advice and supporting services without presuming specific features. Price should examine the logic of rates, fees, eligibility and value rather than inventing quoted terms. Place covers digital banking connections and the stated franchise network; Promotion focuses on clear, responsible communication that helps borrowers understand choices and next steps.
- Offer clarity. Compare which borrower needs each product or service proposition is intended to address and what supporting explanation is required.
- Channel fit. Assess where online discovery, partner referrals and physical consultation can complement rather than duplicate one another.
- Message planning. Structure the 4Ps in Excel, then use the Word analysis to turn the comparison into a coherent customer-facing brief.
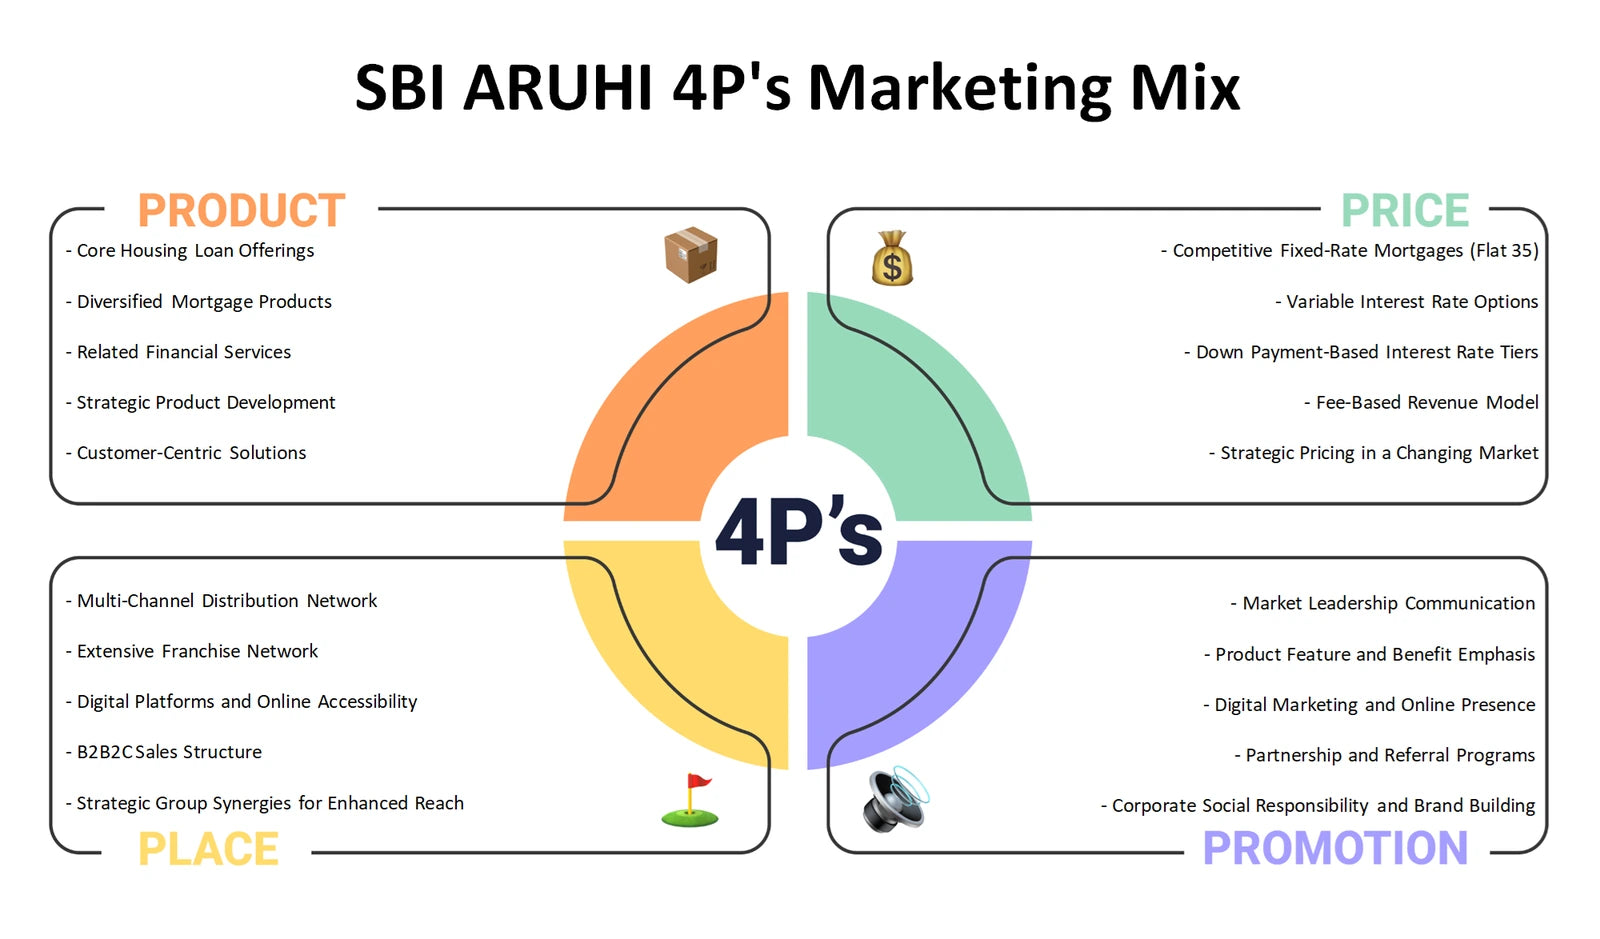
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could reshape demand, compliance obligations and mortgage-distribution choices in Japan?
SBI ARUHI PESTLE analysis, also commonly called PESTEL, separates Political, Economic, Social, Technological, Legal and Environmental influences. For mortgage activity, policy and interest-rate questions can affect affordability and confidence, but should not be presented as documented changes without evidence. Social patterns may alter housing needs; technology can change application and service expectations. Legal and consumer-protection requirements influence processes, while environmental considerations can matter through housing quality, resilience and property-related finance.
- Signal scanning. Distinguish a confirmed external development from a scenario that should be monitored before decisions are made.
- Transmission paths. Connect each external factor to likely effects on borrowers, partners, franchise operations or internal controls.
- Scenario record. Use the Excel grid to rank observations by relevance, with the Word analysis providing context for the most material uncertainties.
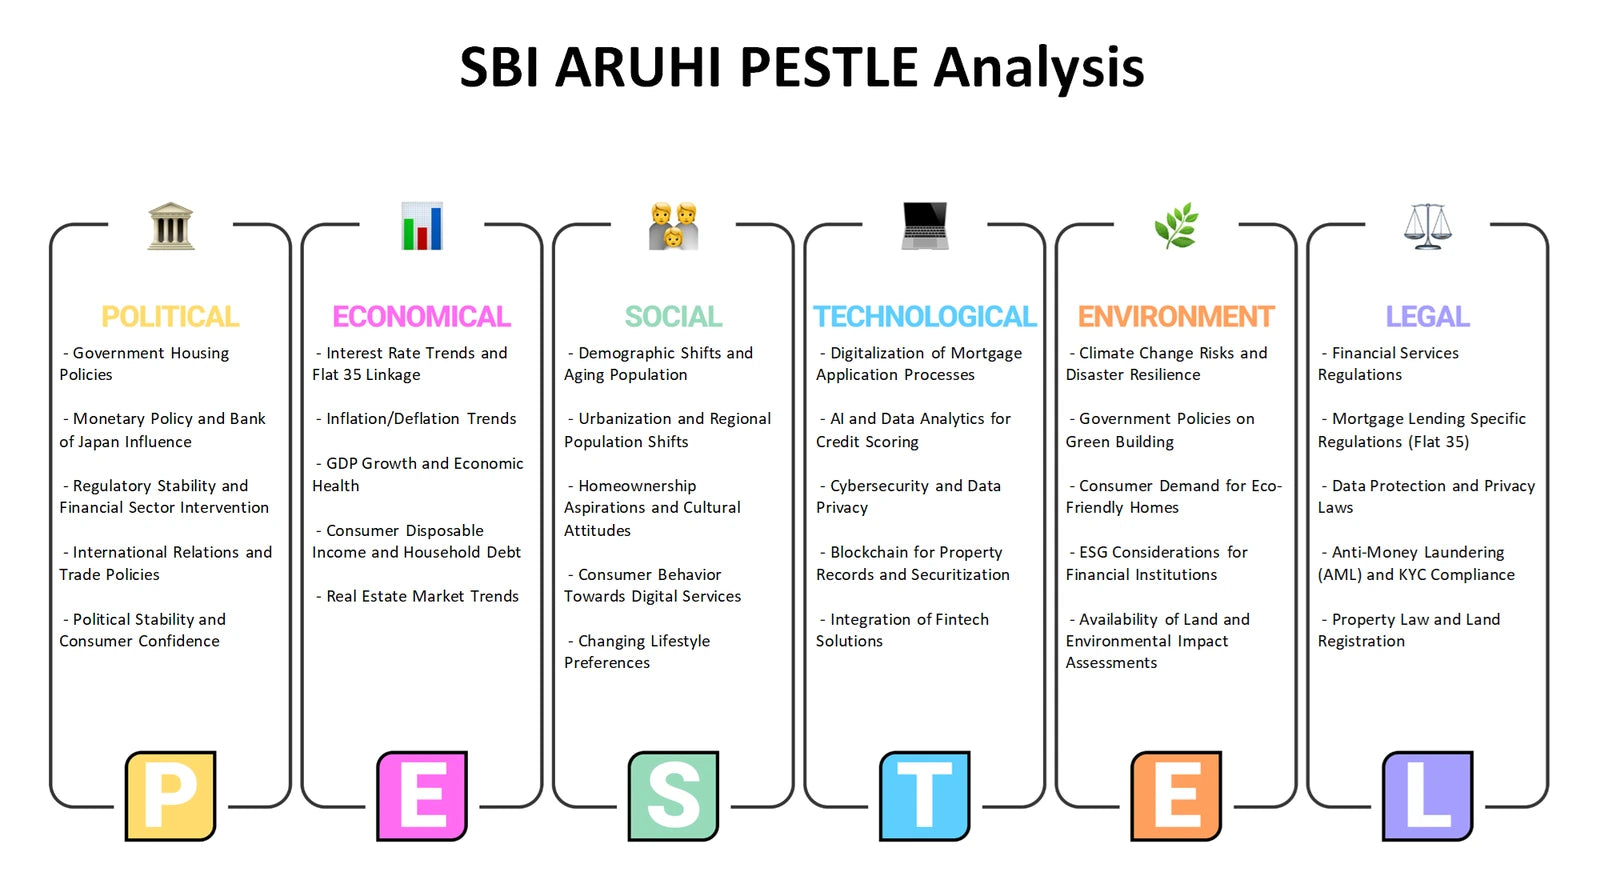
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can SBI ARUHI distinguish controllable capabilities from outside opportunities and threats?
SBI ARUHI SWOT analysis separates internal Strengths and Weaknesses from external Opportunities and Threats. The supplied business context suggests themes to test, including SBI Group relationships, digital banking connections and a franchise-led footprint, rather than proving them as strengths. Internal analysis can examine capabilities, governance, channel coordination and operational constraints. External analysis can draw on mortgage demand, customer expectations, competition, policy conditions and technology change. Keeping these categories separate improves the quality of strategic discussion.
- Internal test. Identify which resources or operating limitations are genuinely within management influence and require evidence.
- External watchlist. Frame market developments and borrower behaviour as opportunities or threats rather than as internal performance measures.
- Action linkage. Use the Excel matrix to pair themes, then consult the Word analysis to develop balanced questions for follow-up.
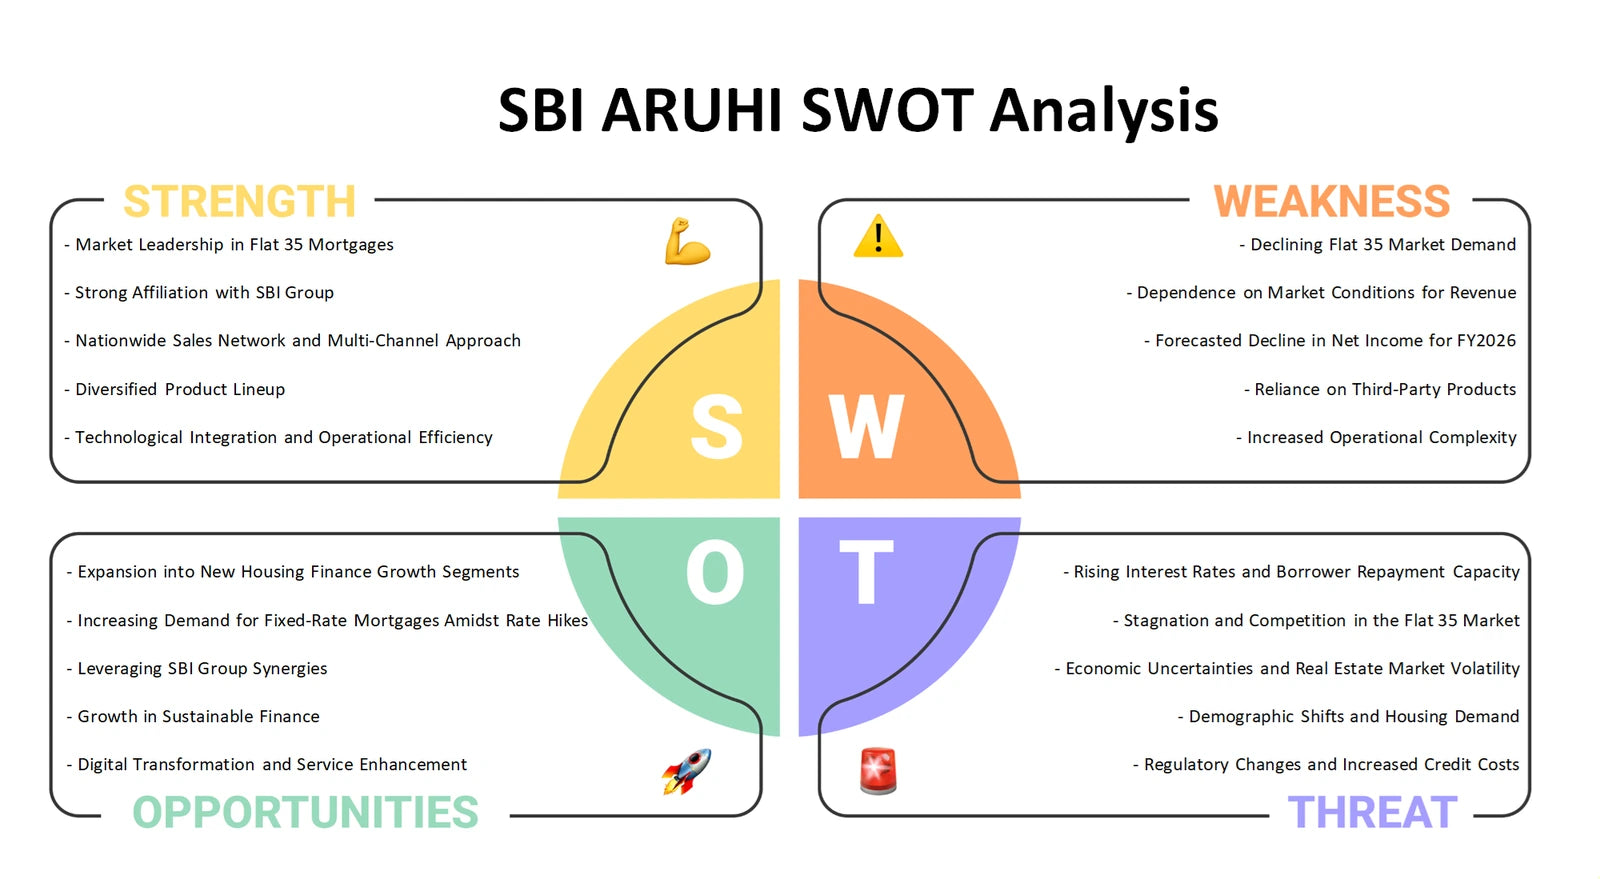
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect the mortgage-business questions
Used together, the six perspectives move from portfolio priorities and business-model logic to industry pressure, customer routes, external change and strategic fit. The Excel frameworks help organise comparisons and assumptions, while the detailed Word analyses help develop a company-specific discussion of SBI ARUHI’s mortgage proposition, partnerships and distribution choices without treating analytical questions as established results.
Company background: SBI ARUHI — supplied product-context page.