

Santander Consumer USA: Financial Services and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Santander Consumer USA Strategy Analysis Bundle
Santander Consumer USA is a U.S. finance company focused on vehicle financing. Its corporate website describes financing for new and pre-owned cars, trucks and SUVs, placing the business at the meeting point of consumers, vehicle retailers, manufacturers and credit-risk decisions. That makes the customer journey, loan economics and partner relationships central subjects for strategic analysis.
The business context supplied for this product also highlights manufacturer-finance relationships, third-party auto-loan servicing and technology-supported underwriting. These are useful starting points rather than pre-set conclusions: the bundle helps examine where to focus resources, how value moves through the operating model, and how external credit, regulatory and automotive-market conditions can affect choices.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending, servicing and partner-supported activities deserve the greatest share of management attention and investment?
A Santander Consumer USA BCG Matrix helps organise a portfolio discussion around market growth and relative market share. For a vehicle-finance business, the relevant units might be defined around customer channels, financing relationships, servicing activities or product categories before any quadrant is considered. Stars, Cash Cows, Question Marks and Dogs are analytical labels, not claims about current Santander Consumer USA positions. The framework is useful because a growing financing opportunity may consume capital and operational capacity, while an established activity may be assessed for cash generation, resilience or selective support.
- Portfolio boundaries. Compare potential business units consistently, using a definition that distinguishes origination, partner-finance and servicing roles.
- Resource trade-offs. Test whether growth potential, relative position, funding needs and operational complexity point toward build, maintain, harvest or review questions.
- Structured comparison. Use the Excel framework to map assumptions and the Word analysis to document the rationale, evidence needs and limits behind each comparison.
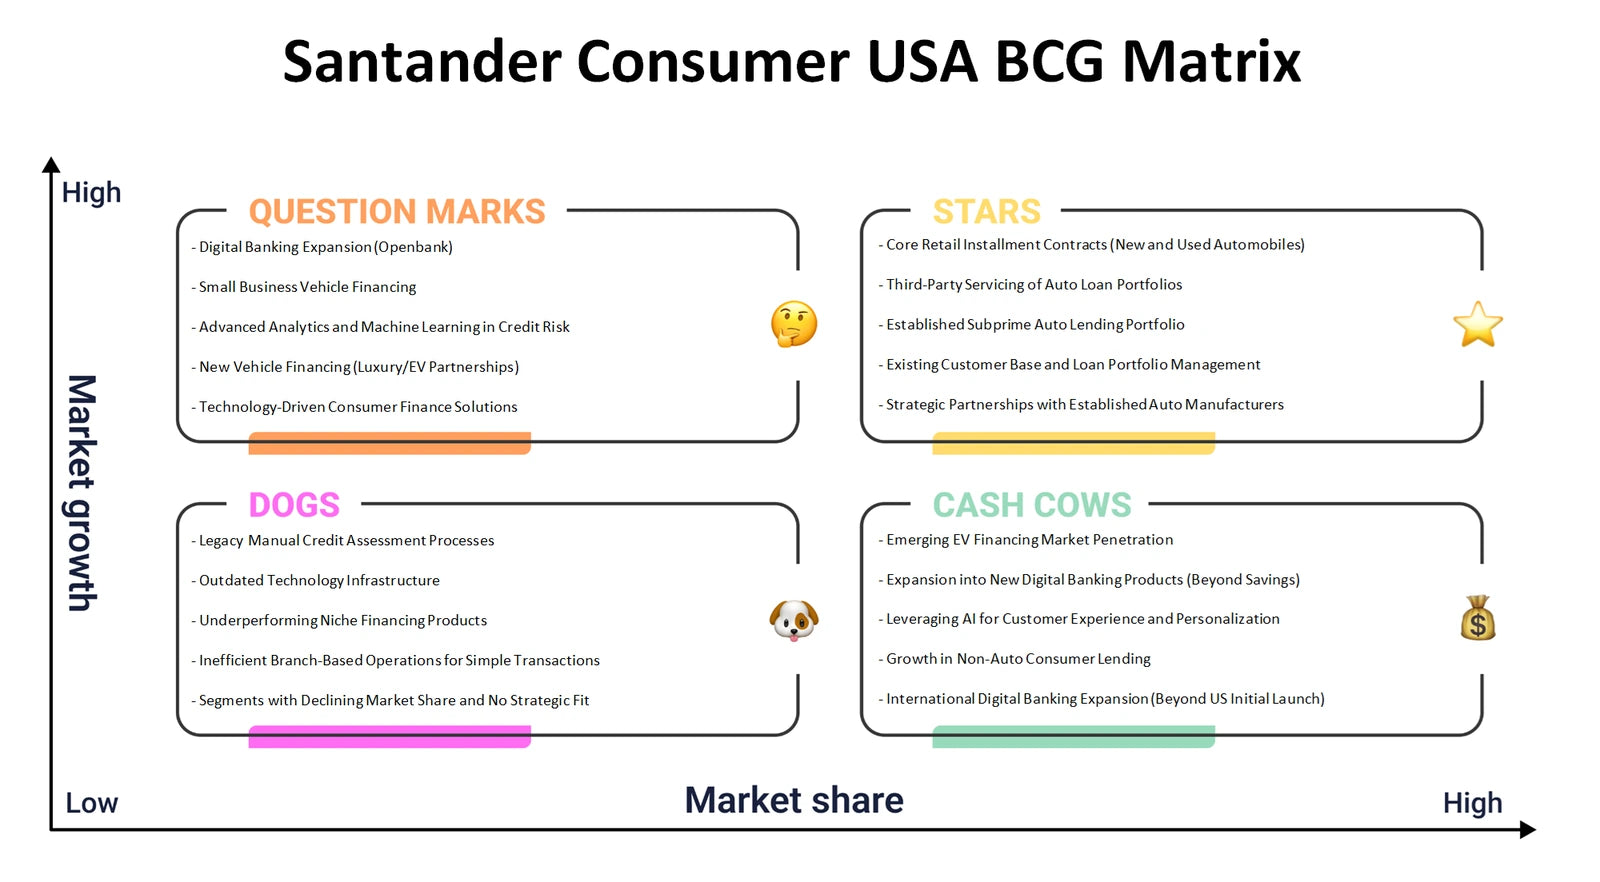
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer needs, vehicle-finance partnerships and loan-servicing capabilities connect to sustainable economics?
The Santander Consumer USA Business Model Canvas examines the full logic of value creation rather than isolating lending from delivery. Customer segments can include borrowers and institutional or automotive partners; value propositions, channels and customer relationships show how financing is accessed and supported. Revenue streams can be considered alongside key resources such as credit expertise, technology and servicing capacity, plus key activities including underwriting and account administration. The canvas also connects key partnerships, including potential OEM relationships, to the cost structure required to operate responsibly at scale. This makes dependencies visible: an attractive channel is only valuable if servicing, risk controls and costs can support it.
- Value flow. Trace how financing access, borrower support and partner services may create value for distinct customer segments.
- Economic links. Examine how revenue streams relate to operating resources, activities, partnership terms and the cost base.
- Model workshop. Populate the nine blocks in Excel, then use the Word analysis to explore the connections and questions that deserve validation.
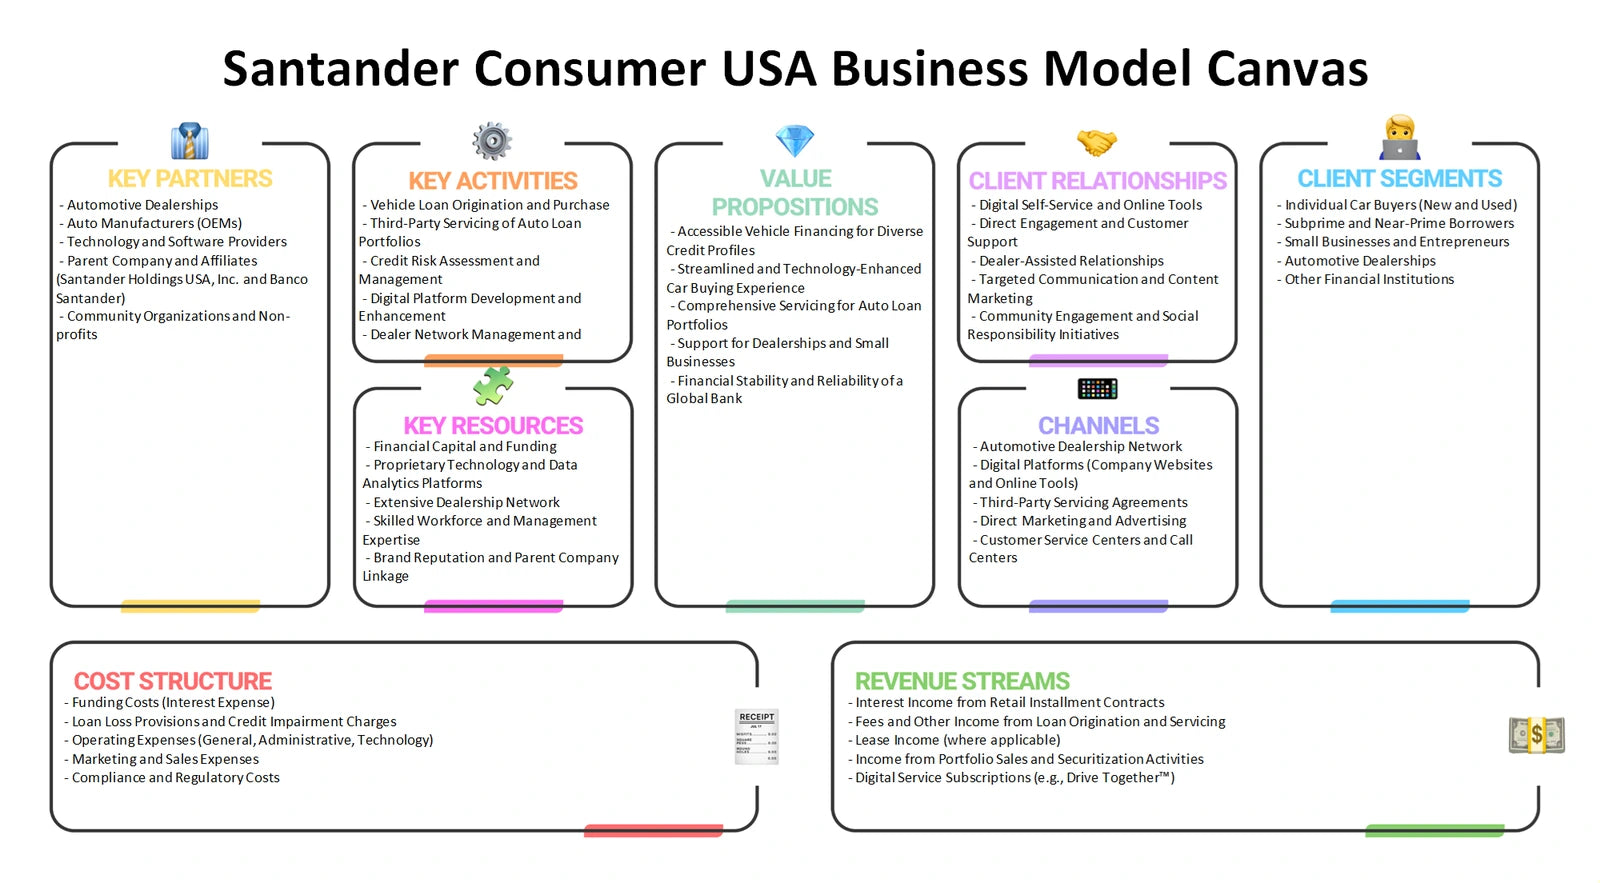
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can shape returns and bargaining power in consumer vehicle financing and loan servicing?
Santander Consumer USA Porter's Five Forces analysis frames the competitive environment around the business rather than assigning unsupported ratings. Rivalry considers the pressure to win borrowers, dealer-linked volume and financing partnerships. Supplier power can include the influence of funding providers, technology vendors and important distribution partners. Buyer power examines how borrowers and institutional partners can compare terms or service. The threat of new entrants asks what compliance, capital, data and servicing capabilities may protect or challenge incumbent positions. Substitutes are broader alternatives for meeting transportation or credit needs, such as cash purchases, leasing, captive finance or other forms of borrowing, not simply direct competitors.
- Negotiating leverage. Identify where partner concentration, funding access or customer choice could alter commercial bargaining positions.
- Barrier testing. Consider how credit expertise, regulatory obligations, data capabilities and servicing scale may affect entry pressure.
- Evidence trail. Use Excel to compare the five forces and the Word analysis to record sector-specific observations, caveats and follow-up research.
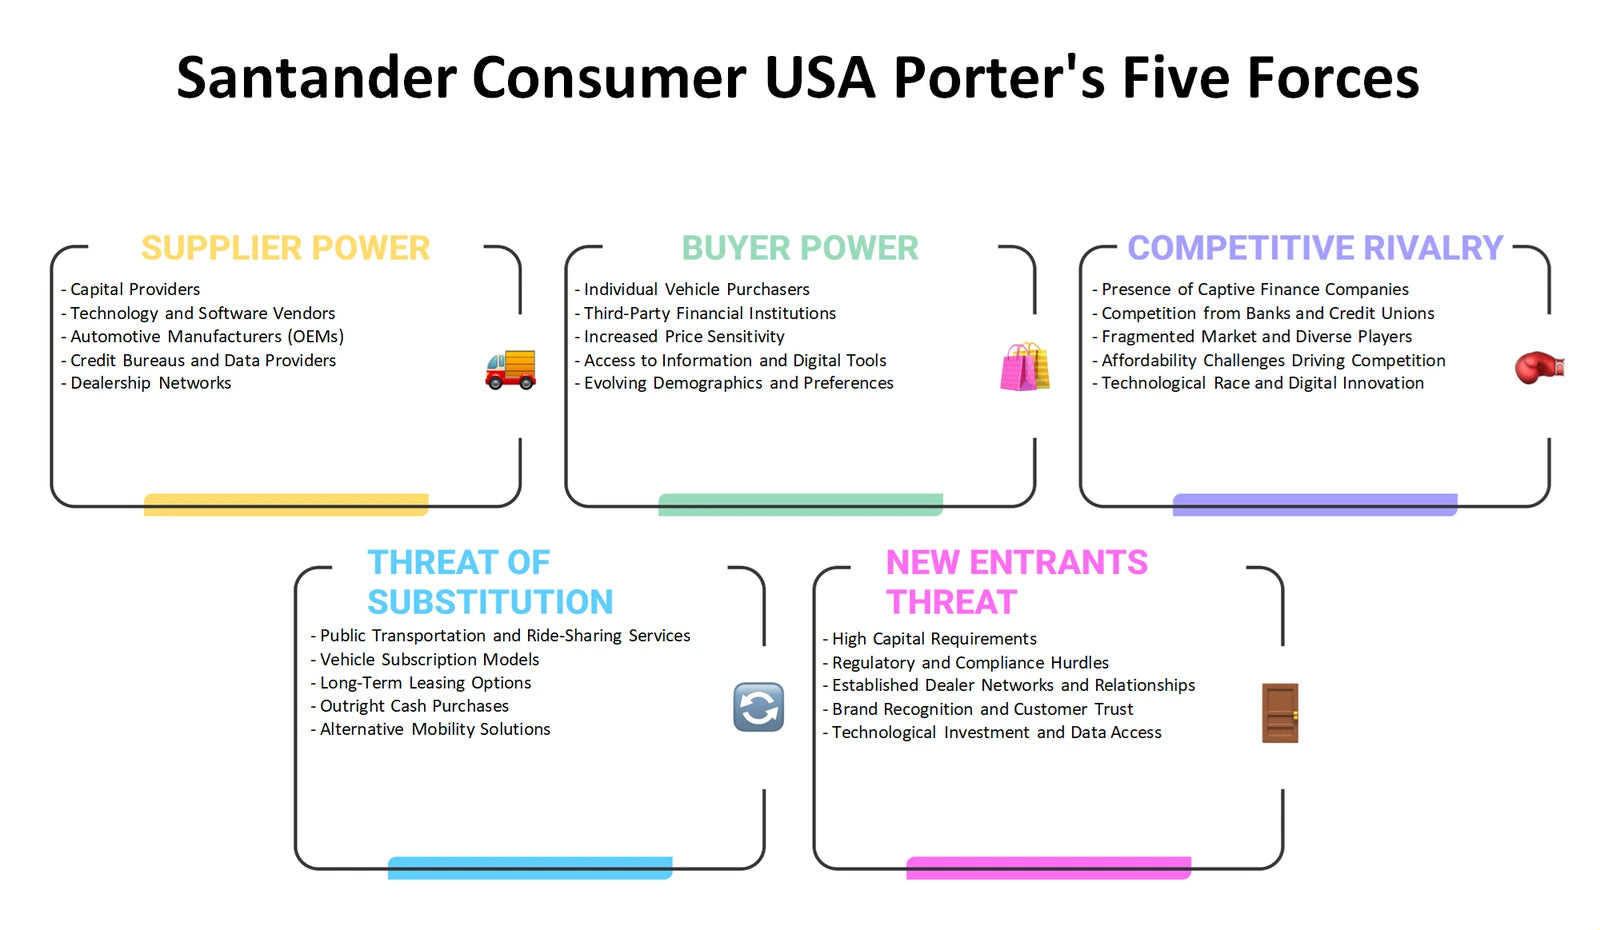
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can financing offers be presented clearly and responsibly across consumer and automotive-partner touchpoints?
A Santander Consumer USA Marketing Mix analysis applies Product, Price, Place and Promotion to a regulated financial service. Product considers financing and related servicing experiences, including the clarity and suitability of the offer rather than a physical good alone. Price examines rate, fee and payment-structure questions without assuming specific terms. Place focuses on how customers may encounter financing through digital journeys, vehicle-retail channels or manufacturer-related relationships. Promotion considers communications that help borrowers understand choices and obligations while supporting partner channels. Looking at the four Ps together matters because an accessible channel or compelling message must align with risk policy, disclosure requirements and the service experience that follows.
- Offer design. Review how product features and repayment communication can be assessed from a borrower-value and risk-management perspective.
- Channel fit. Compare digital, partner and retail-originated routes according to convenience, controls and customer understanding.
- Decision map. Use the Excel 4Ps layout to organise options, then consult the Word analysis for company-relevant prompts and cross-checks.
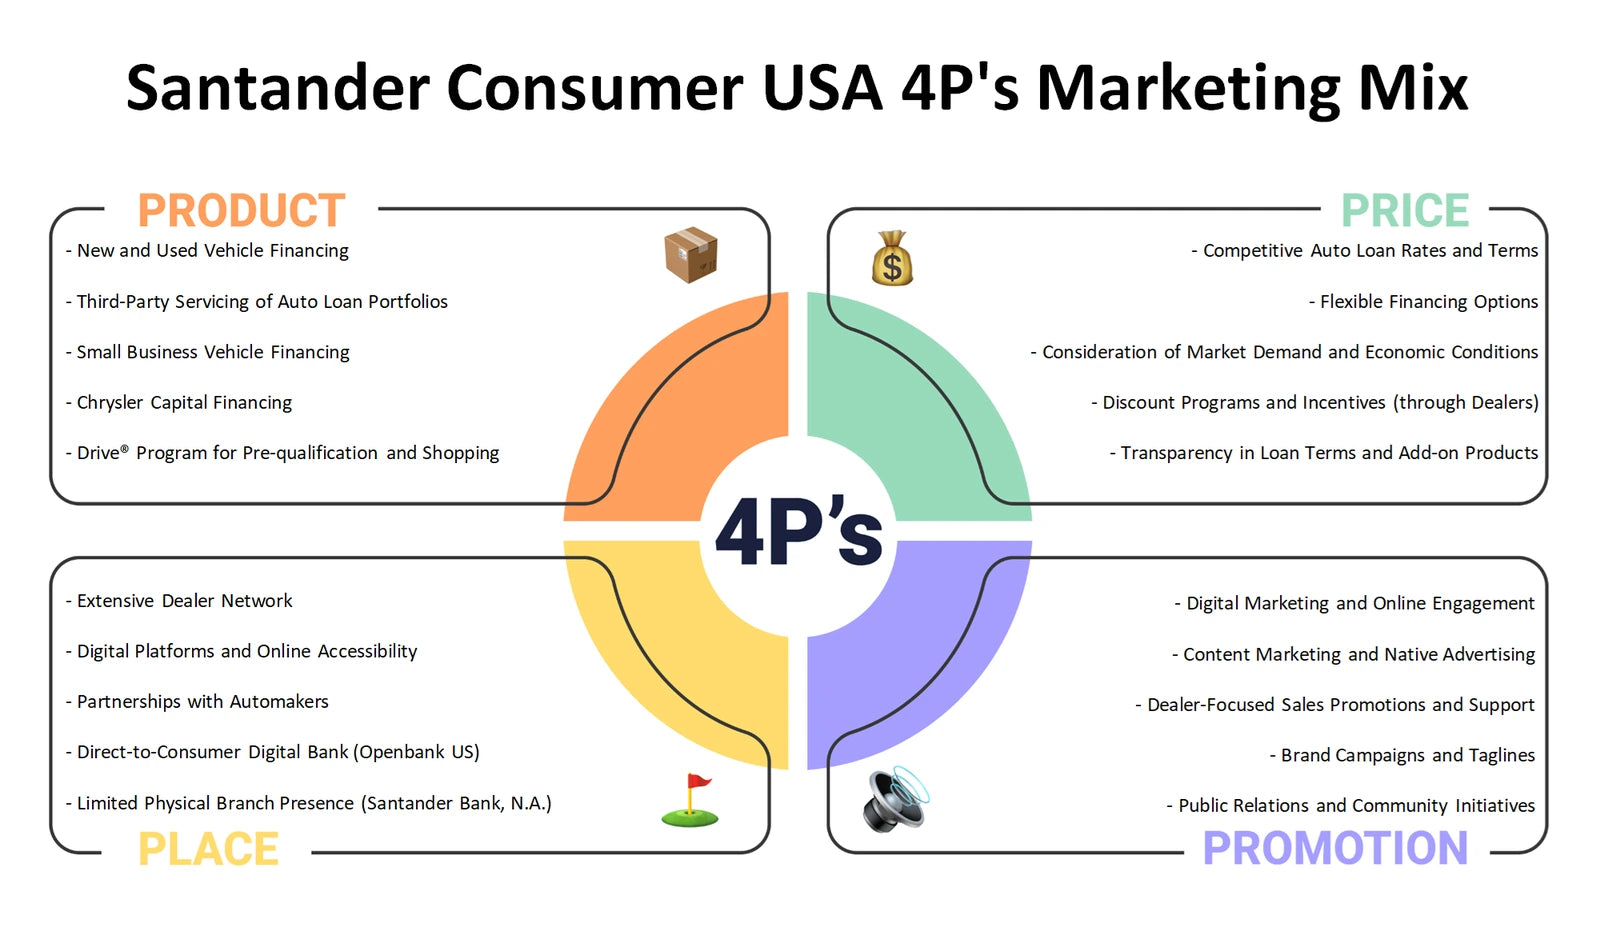
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could alter vehicle demand, borrower affordability, compliance requirements and operating technology?
A Santander Consumer USA PESTLE analysis, also commonly called PESTEL, distinguishes external drivers from internal capabilities. Political factors can include public-policy priorities affecting consumer credit or transportation. Economic conditions raise questions about household budgets, used-vehicle values, funding costs and credit performance; they should not be confused with a claim about current rates. Social trends may influence vehicle ownership preferences and expectations for convenient account service. Technological factors include data, cybersecurity, digital servicing and underwriting tools. Legal considerations cover consumer-finance obligations and privacy requirements, while environmental factors can affect vehicle mix, transport preferences and the transition toward lower-emission vehicles. The purpose is to monitor change and expose planning assumptions.
- External watchlist. Separate policy, economic, social, technological, legal and environmental signals that could matter to auto-finance operations.
- Scenario questions. Explore how a change in affordability, regulation or vehicle demand could affect customers, partners and workflows.
- Planning record. Use the Excel framework to prioritise external factors and the Word analysis to capture implications, uncertainties and review questions.
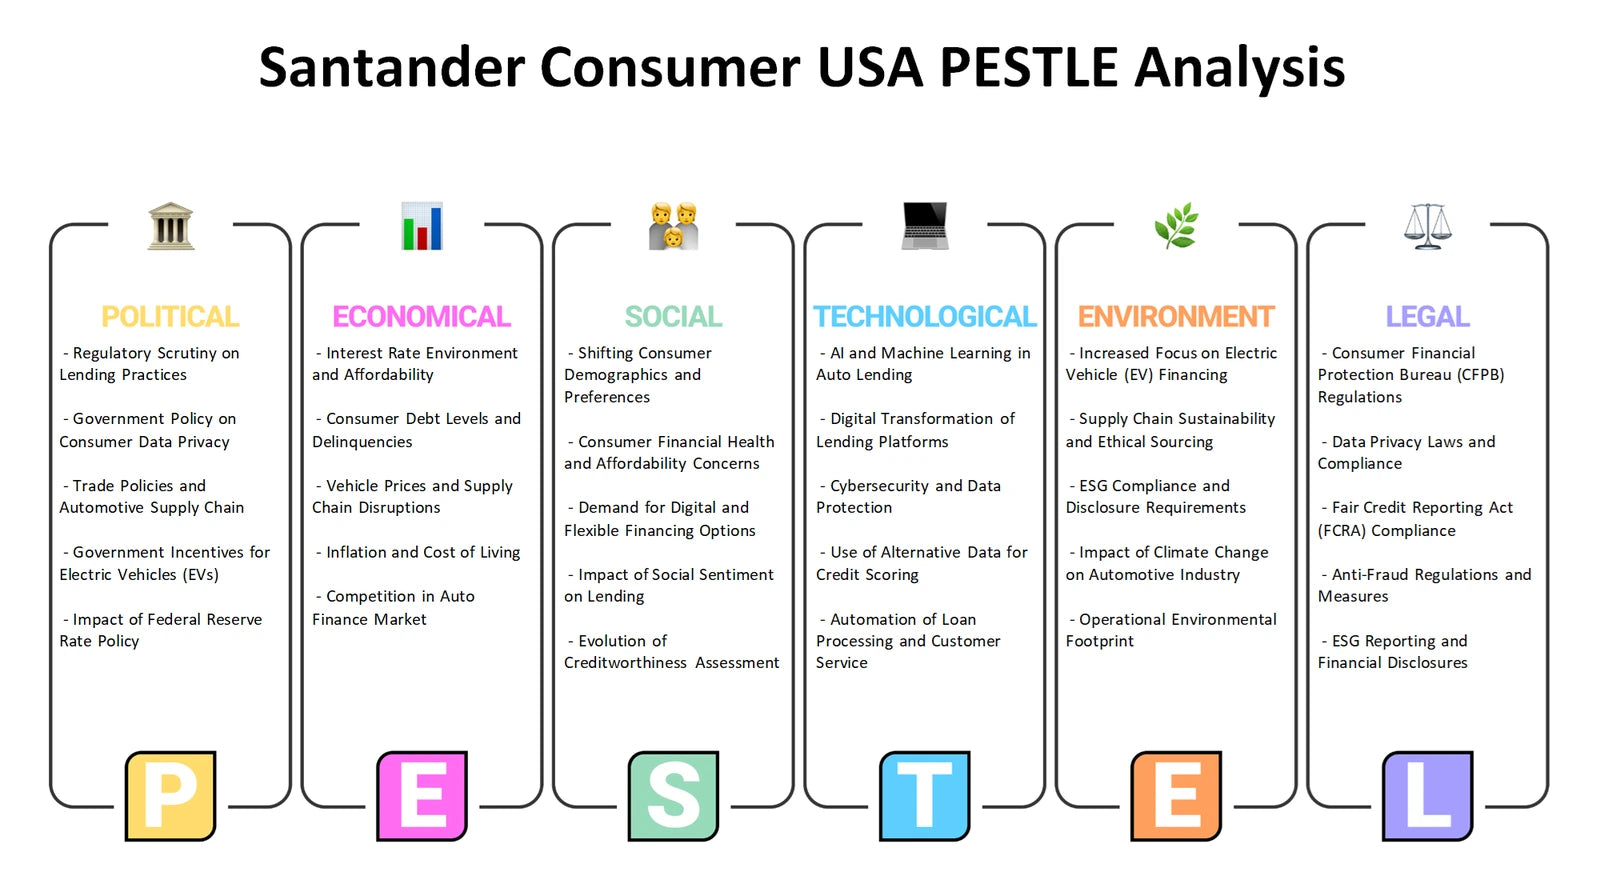
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Santander Consumer USA distinguish its own capabilities and constraints from the market opportunities and risks around it?
A Santander Consumer USA SWOT analysis brings the previous lenses into one decision-oriented view. Strengths and weaknesses are internal: potential examples to assess include underwriting know-how, loan-servicing operations, technology, partner-management capability, cost discipline or process constraints. Opportunities and threats are external, such as shifts in vehicle financing demand, partner needs, borrower expectations, regulation or competitive alternatives. The supplied product context points to OEM relationships, third-party servicing and analytics as relevant areas for investigation, but it does not prove a strength, weakness or outcome. Keeping this classification disciplined is important because a market trend is not an internal capability, and an operational limitation is not an external threat.
- Internal versus external. Classify evidence carefully so managerial capabilities are not mixed with sector conditions or policy changes.
- Strategic fit. Test whether possible opportunities match operational resources and whether potential threats expose a meaningful vulnerability.
- Actionable synthesis. Use the Excel matrix to organise themes and the Word analysis to develop balanced discussion points for review.
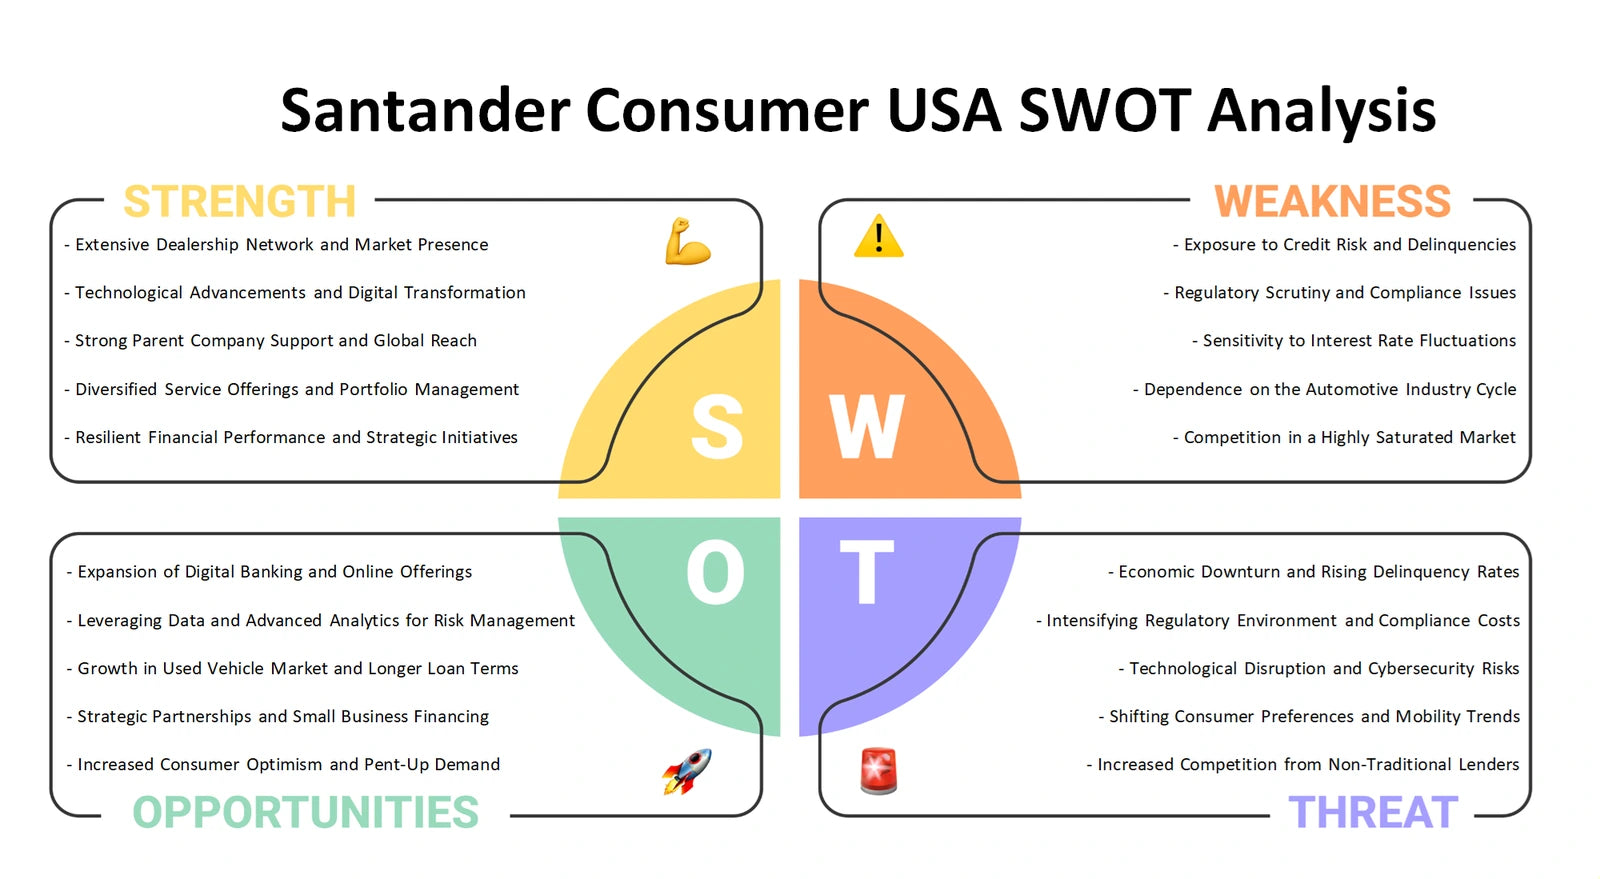
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a joined-up strategic view of vehicle finance
Together, the six perspectives move from portfolio priorities and business-model logic to industry pressure, customer-market choices, external change and strategic fit. The Excel frameworks provide organised structures for comparison and discussion, while the Word files provide detailed company analysis to help develop more informed questions about Santander Consumer USA's consumer-finance, partner and servicing context.
Company background: Santander Consumer USA — company website.