

Samsung Life Insurance: Insurance Business and Market Access – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Samsung Life Insurance Strategy Analysis Bundle
Samsung Life Insurance is a South Korean insurance company serving policyholders and prospective customers through insurance products and related financial-protection relationships. Its business depends on long-term customer trust, risk assessment, distribution reach and the ability to maintain relevant protection and savings-oriented propositions across changing life stages.
The supplied business-model context highlights Samsung Group relationships, dividend-income considerations and a consolidated agency network focused on Samsung Life Insurance products. Those themes create practical questions about portfolio priorities, distribution economics, regulatory boundaries and competitive positioning. This bundle uses six connected frameworks to help examine those questions without treating analytical possibilities as established findings.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which product, customer or distribution areas merit further resources when growth prospects and relative market share may differ?
The Samsung Life Insurance BCG Matrix provides a disciplined way to compare an insurance portfolio using two distinct criteria: market growth and relative market share. Rather than assuming that every insurance line or route to market deserves the same investment, the framework helps distinguish possible Stars, Cash Cows, Question Marks and Dogs for review. For a life insurer, that can mean testing where policy demand, profitability, renewal potential, servicing requirements and competitive position may pull decisions in different directions. It is especially useful when agency-led sales, digital service development and long-duration policy relationships compete for management attention.
- Portfolio comparison. Examine whether protection, savings-linked or customer-segment opportunities appear to have different growth and relative-share profiles before assigning strategic priority.
- Capital discipline. Consider how mature cash-generating activities could support selective investment in uncertain opportunities without assuming a quadrant placement in advance.
- Structured review. Use the Excel matrix to organise candidate businesses or channels, then use the Word analysis to record assumptions, evidence gaps and the reasoning behind each comparison.
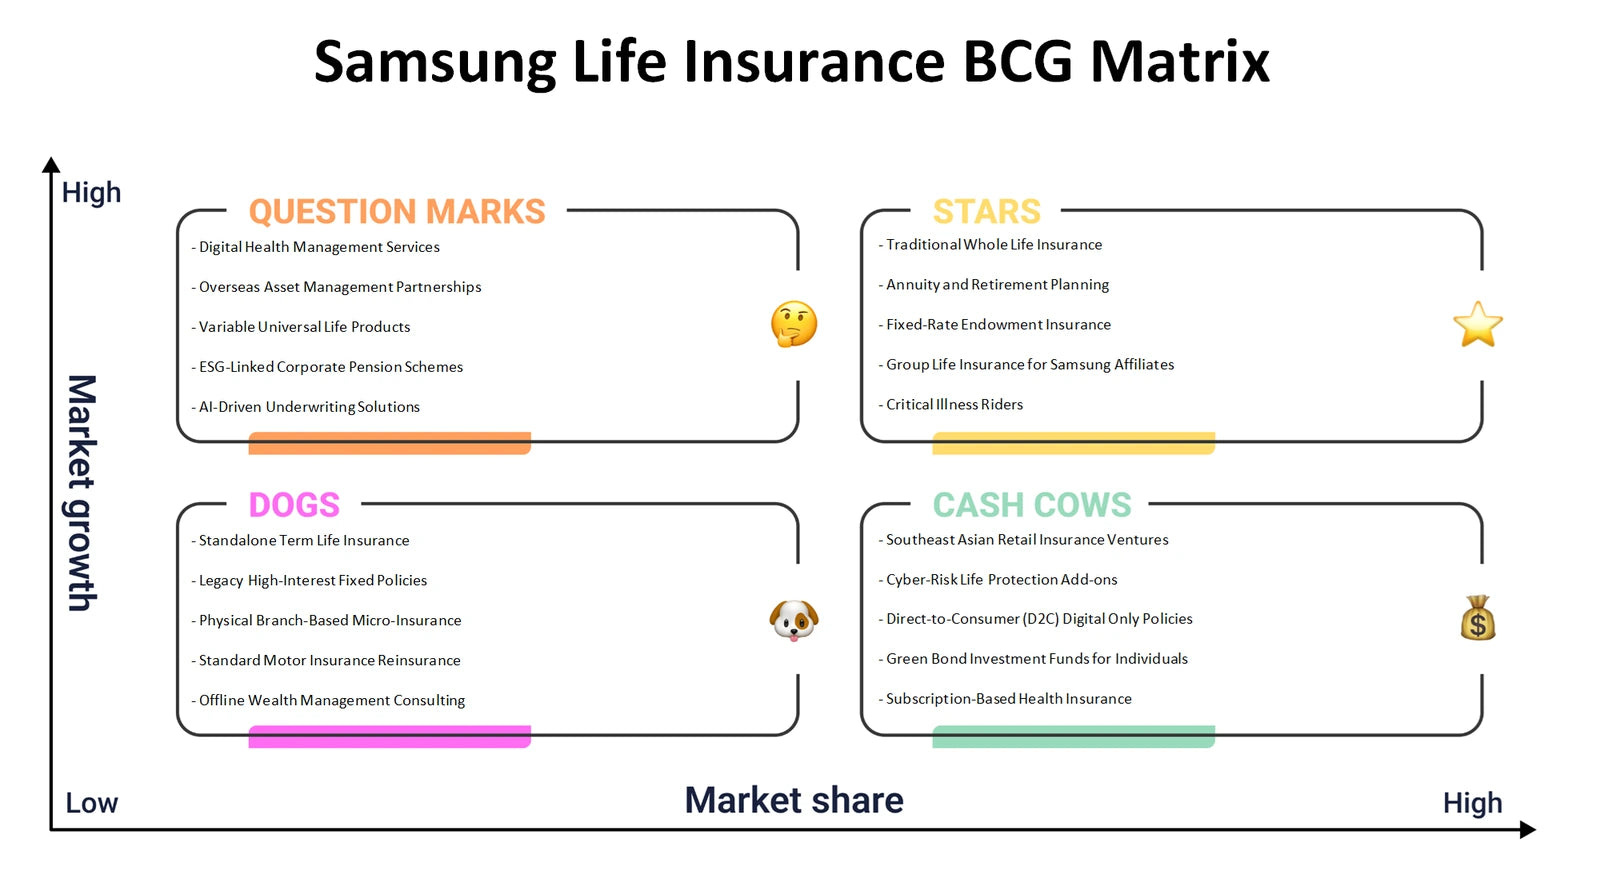
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer trust, advice, distribution and long-term policy economics fit together in Samsung Life Insurance's value-creation model?
The Samsung Life Insurance Business Model Canvas connects all nine building blocks in one view: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For an insurer, the connections matter more than any isolated box. Customer needs for protection and financial security influence proposition design; agency and other channels shape access and advice; ongoing relationships affect retention and service expectations; and premium-based economics depend on underwriting, investment management, claims administration and operating discipline. The supplied context also makes Samsung Group connections and agency-network scope useful topics for structured examination rather than assumptions about guaranteed advantage.
- Value chain links. Trace how policyholder needs, advisory relationships, service delivery and risk management combine to create value over the life of an insurance contract.
- Economic logic. Explore how revenue streams, key activities, partnerships and cost structure may change when distribution or product breadth changes.
- Connected evidence. Map the nine blocks in Excel and use the Word analysis to explain dependencies, uncertainties and strategic trade-offs behind the completed canvas.
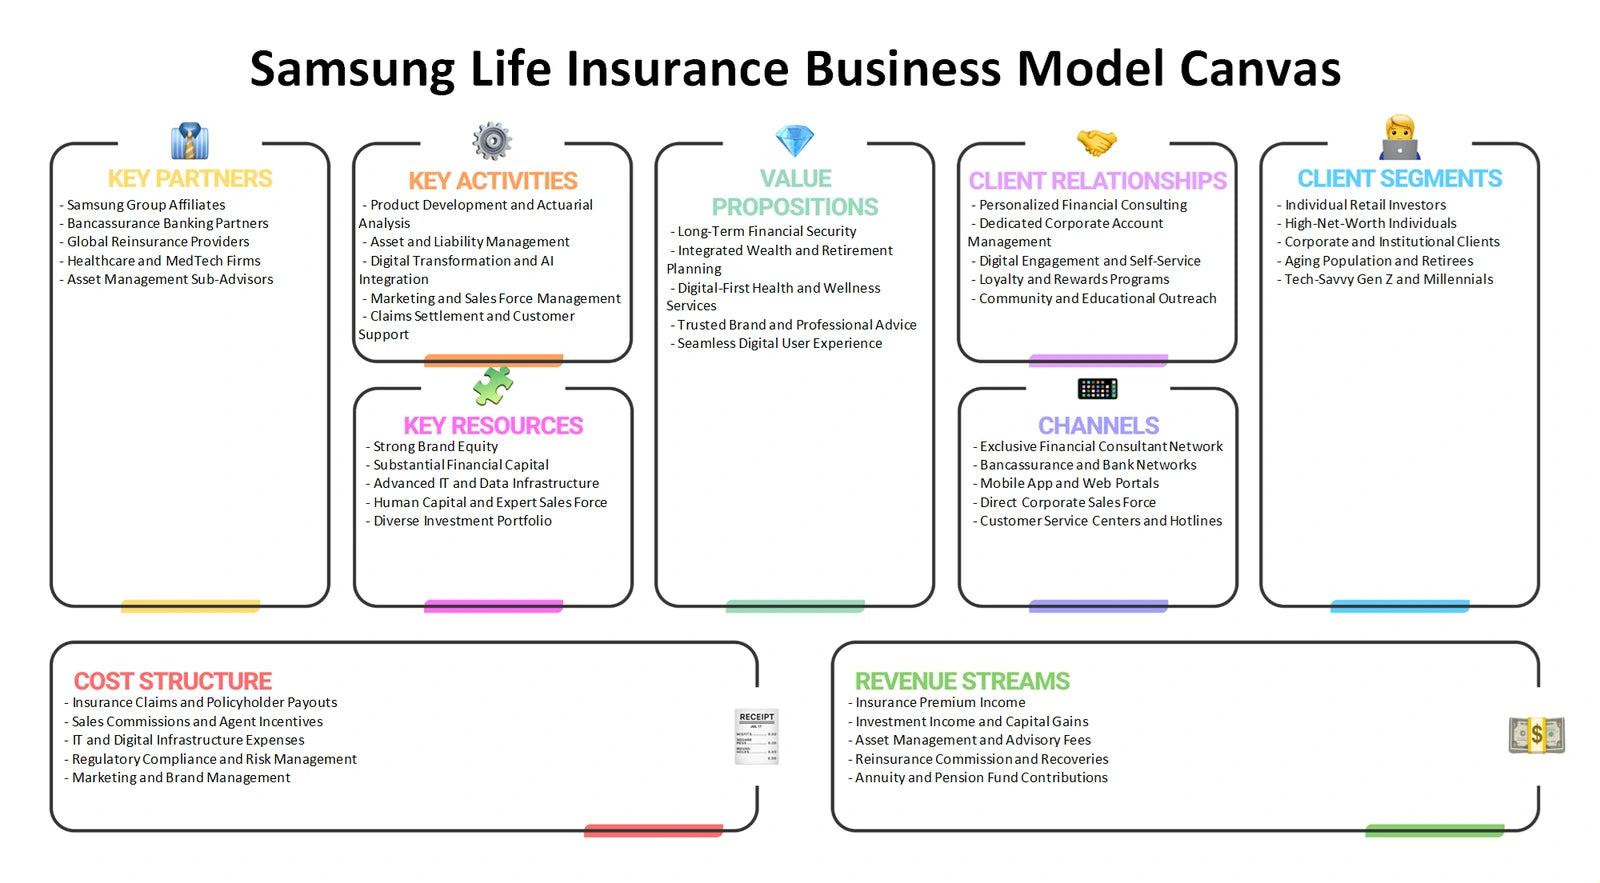
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could affect the attractiveness of South Korean life insurance and Samsung Life Insurance's ability to sustain customer value?
Samsung Life Insurance Porter's Five Forces analysis frames competition as more than direct insurer rivalry. It examines rivalry among providers, buyer power, supplier power, the threat of new entrants and the threat of substitutes. In life insurance, buyer power can be shaped by customer information, product comparability, advice quality and switching perceptions, while supplier-side influence may relate to specialised distribution, technology, actuarial talent or external service capabilities. Substitutes are also broader than another insurer: households may address financial-security needs through savings, investments, public support or other financial products. Entry barriers, regulation, capital requirements and trust can all affect the new-entrant question.
- Competitive pressure. Assess whether competition is concentrated around product features, service quality, distribution access, brand confidence or customer acquisition costs.
- Alternative solutions. Compare insurance needs with non-insurance ways customers may seek savings, protection or financial resilience.
- Force-by-force use. Populate the Excel framework with relevant evidence and use the Word analysis to explain how the five forces may interact instead of relying on unsupported force scores.
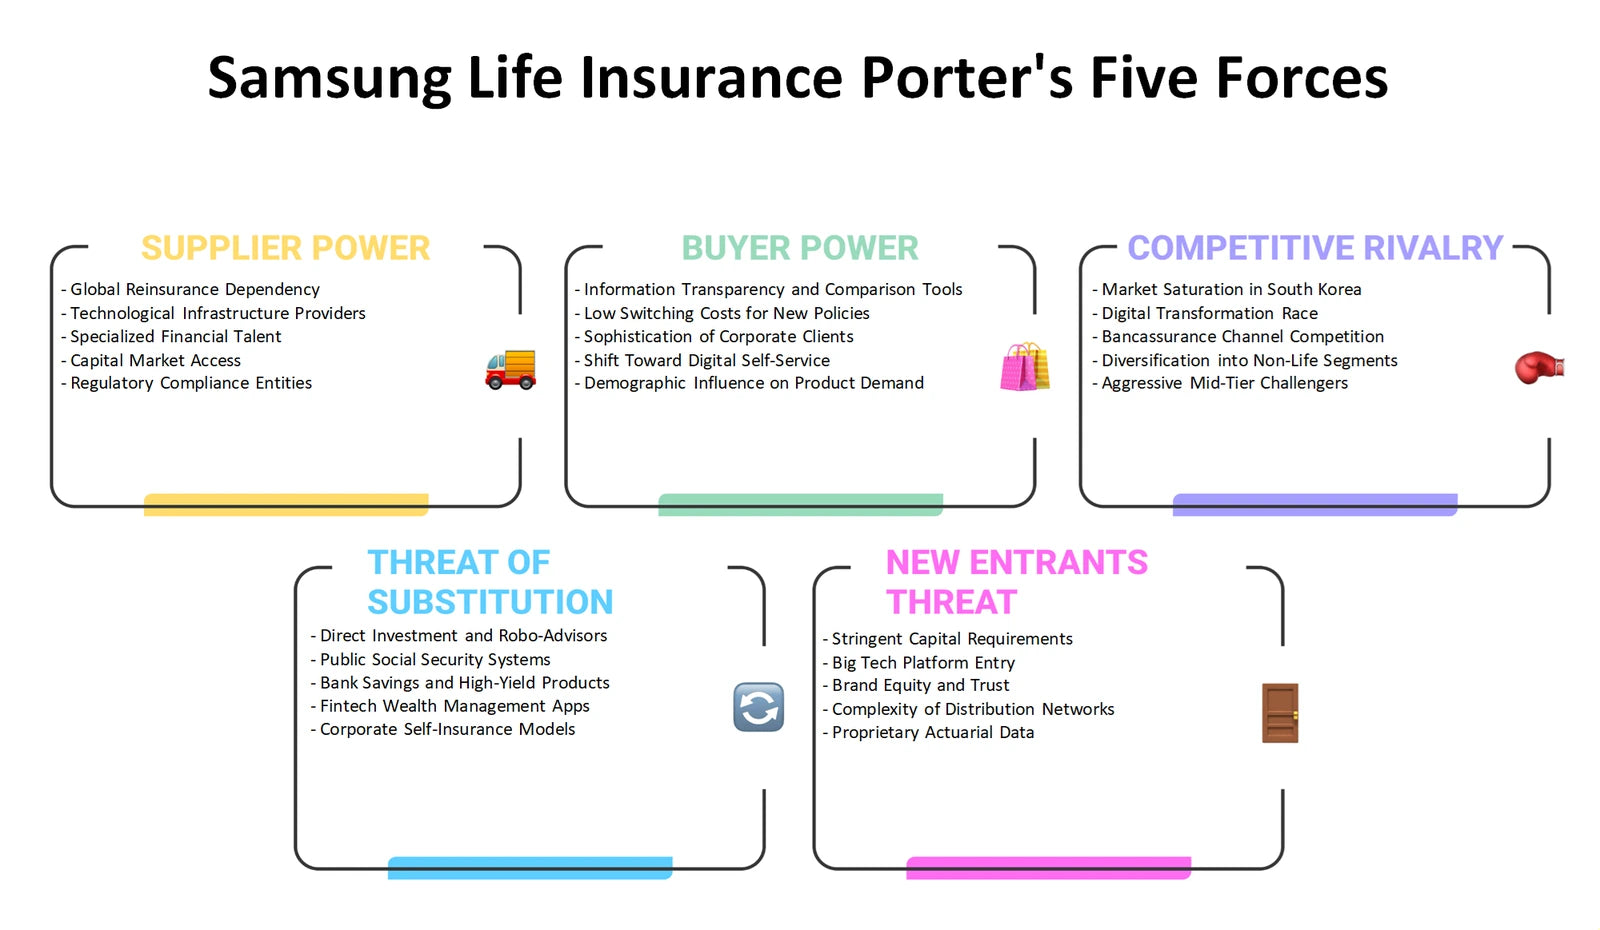
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can product design, pricing logic, distribution and communication work together for a trust-based insurance purchase?
The Samsung Life Insurance Marketing Mix examines Product, Price, Place and Promotion in a regulated, relationship-driven service context. Product concerns the relevance and clarity of insurance protection and related propositions for differing customer circumstances. Price is not simply a retail sticker price: it includes premium affordability, perceived value, risk-based design and the need for transparent customer understanding. Place considers how customers access information, advice, applications and ongoing service through agency networks and other appropriate routes. Promotion concerns clear, responsible communication that can build confidence without reducing a complex long-term commitment to a simple short-term offer. The four Ps help test alignment across the full customer journey.
- Customer fit. Compare how insurance propositions may address different protection needs while remaining understandable for customers making long-horizon decisions.
- Channel consistency. Review whether service, advice, access and communications support the same proposition across agency-led and other possible customer touchpoints.
- Planning application. Use the Excel 4Ps structure to organise observations by decision area, then consult the Word analysis to connect each choice to customer trust and commercial trade-offs.
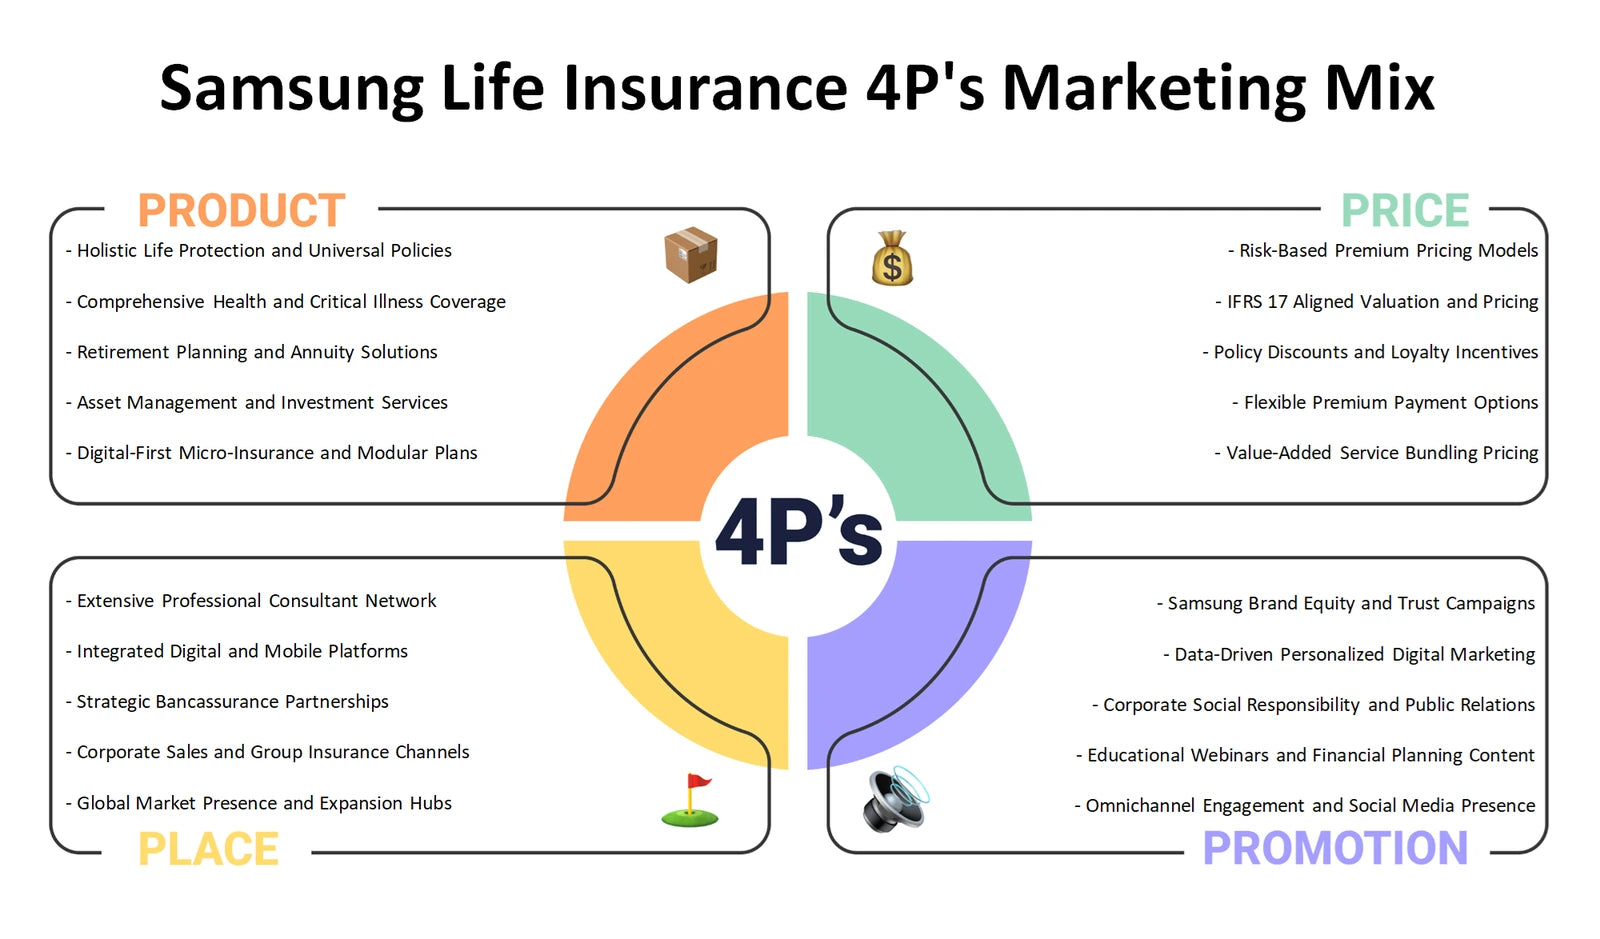
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should be monitored because they could reshape insurance demand, risk management or operating conditions in South Korea?
Samsung Life Insurance PESTLE analysis, also commonly called PESTEL, separates external influences into Political, Economic, Social, Technological, Legal and Environmental dimensions. For a South Korean insurer, political and legal questions can include the policy and supervisory environment without presuming a specific new rule. Economic analysis can consider how household finances, investment conditions and interest-rate sensitivity may affect insurance decisions and insurer economics. Social change may influence ageing, family structures, financial literacy and expectations of care. Technology raises questions around digital service, data governance and customer experience, while environmental conditions may affect risk awareness, investment considerations and resilience planning.
- External scanning. Distinguish broad macro signals from confirmed developments so that policy, economic and demographic questions are not mistaken for documented outcomes.
- Interconnected risk. Consider how a regulatory shift, customer-behaviour change or technology expectation could affect products, channels, compliance and operations at the same time.
- Monitoring tool. Use the Excel framework to log and categorise external factors, while the Word analysis helps turn those entries into company-relevant implications and review questions.
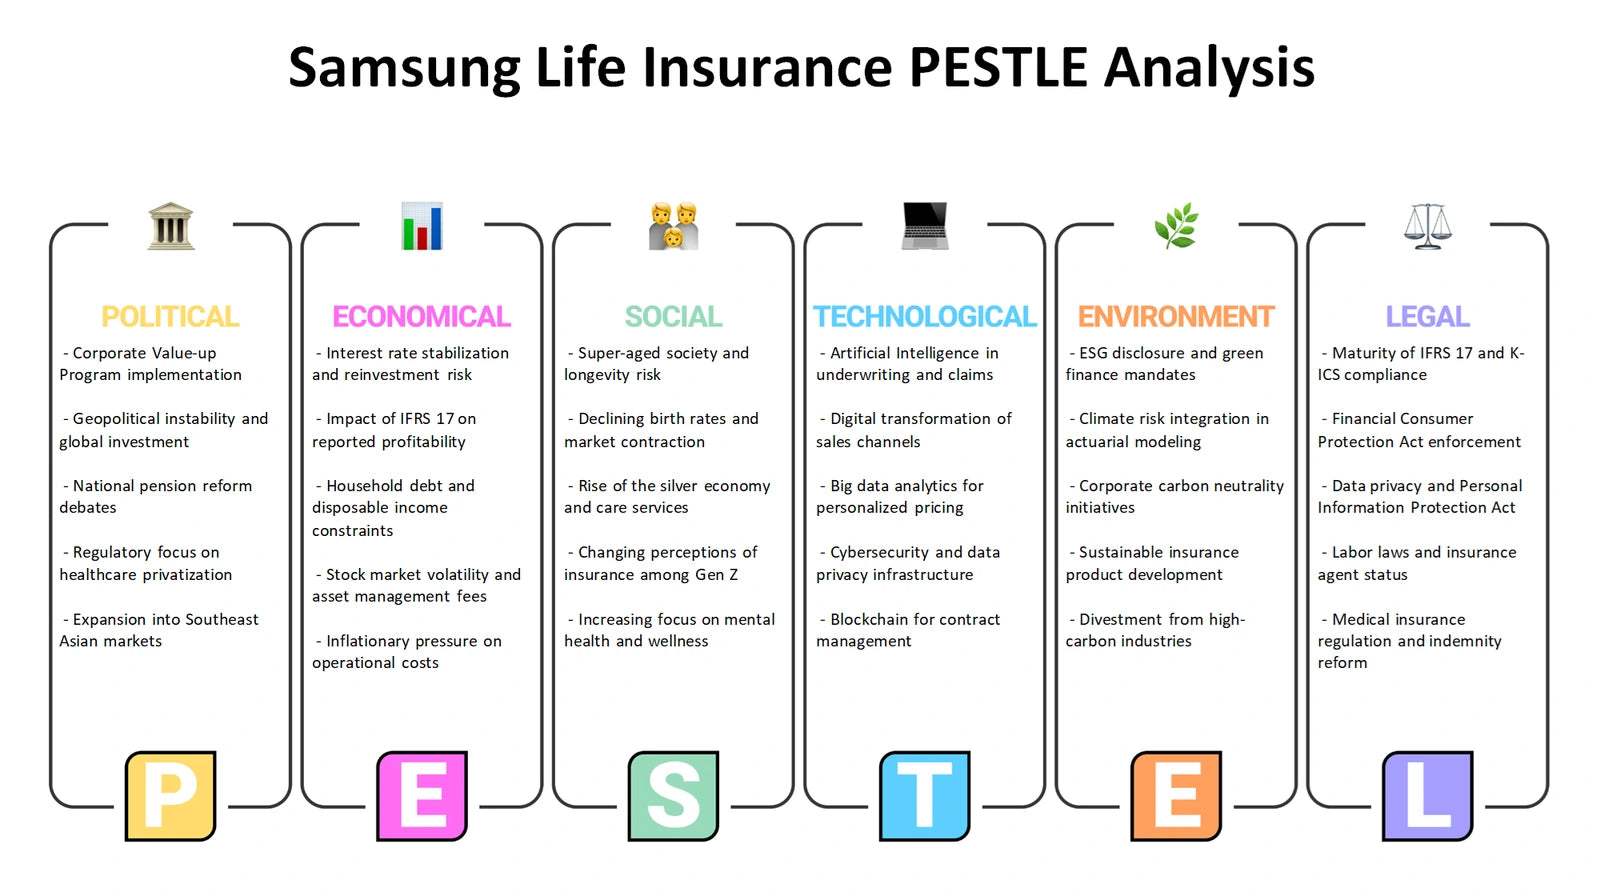
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Samsung Life Insurance separate internal capabilities and constraints from external opportunities and threats before setting priorities?
The Samsung Life Insurance SWOT analysis keeps internal and external factors in their proper categories. Strengths and weaknesses concern capabilities, resources, processes, brand relationships, distribution reach or organisational constraints that need evidence-based assessment. Opportunities and threats arise outside the company, such as changing customer needs, technology expectations, market structure, macroeconomic conditions or regulation. The supplied context suggests that Samsung Group relationships, dividend-income exposure and agency-network evolution may be worthwhile subjects for examination, but a SWOT should not automatically classify them as positive or negative. Their effect depends on strategic fit, governance, regulation, customer relevance and execution capacity.
- Classification discipline. Separate an internal distribution capability from an external regulatory possibility, preventing mixed categories from obscuring the real issue.
- Strategic fit. Test whether potential opportunities can be pursued with available capabilities and whether identifiable weaknesses could increase exposure to external threats.
- Action-oriented synthesis. Use the Excel SWOT grid to compare factors side by side, then use the Word analysis to document implications, dependencies and priorities for further validation.
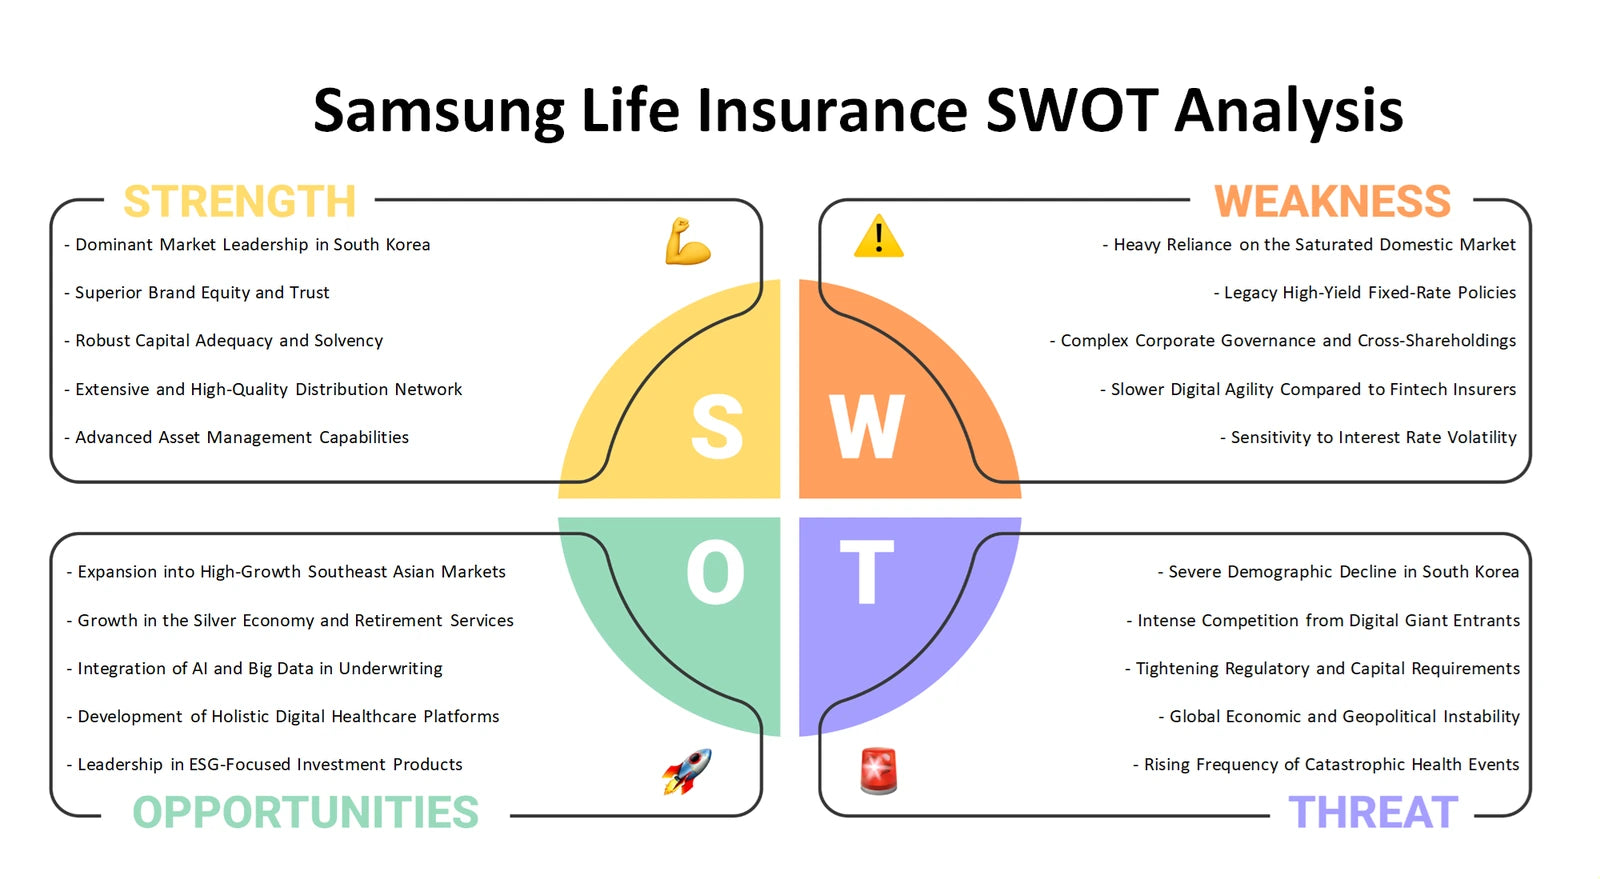
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of Samsung Life Insurance
Used together, the six perspectives move from portfolio choices and business-model logic to industry pressure, customer-facing decisions, external change and strategic fit. The Excel frameworks provide a structured way to compare issues, organise evidence and frame questions, while the detailed Word files help develop the company-specific reasoning behind those assessments. This combination is designed to support informed analysis of Samsung Life Insurance's insurance business, distribution questions and long-term strategic trade-offs without presenting assumptions as confirmed outcomes.
Company background: Samsung Life Insurance — corporate website.