

Republic Bank: Banking Business and Pricing – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Republic Bank Strategy Analysis Bundle
The available product context for Republic Bank describes a banking and lending business supported by consumer and real-estate loan origination pipelines. Mortgage brokers, auto dealers and referral sources can contribute qualified applications, while core banking systems, CRM, analytics and partner integrations support servicing, risk assessment and customer insight. As several institutions use the Republic Bank name, this bundle stays focused on that supplied lending and banking context rather than attributing another same-name bank's filings, geography or corporate structure.
For this operating model, strategy depends on more than loan volume: it requires choices about channel quality, pricing discipline, customer relationships, technology investment and regulatory controls. The six connected frameworks help organise questions around portfolio priorities, lending economics, competitive pressure, customer routes to market and external risk. Excel provides structured frameworks for comparing issues, while the accompanying Word files provide detailed company analysis to support informed discussion.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which Republic Bank lending, deposit or service areas deserve funding, careful maintenance, selective testing or possible exit?
A Republic Bank BCG Matrix helps turn a broad banking portfolio into a resource-allocation conversation. The framework compares market growth with relative market share, then uses the familiar Stars, Cash Cows, Question Marks and Dogs categories to test priorities. It does not presume that a consumer loan product, dealer-sourced auto lending, real-estate financing or a digital service belongs in any category. Instead, it helps examine whether each activity has enough competitive position and market momentum to justify capital, specialist staff, marketing attention and technology capacity. This matters where underwriting, servicing and compliance resources are finite and where rapid growth can create risk as well as opportunity.
- Portfolio boundaries. Compare lending propositions, funding products and supporting service lines at a useful level of detail without confusing pipeline volume with relative market share.
- Capital questions. Consider where growth ambitions may require stronger credit controls, partner oversight or operational capacity before more resources are committed.
- Working view. Use the Excel matrix to map alternative assumptions, then use the Word analysis to record the evidence and decisions that would validate each priority.
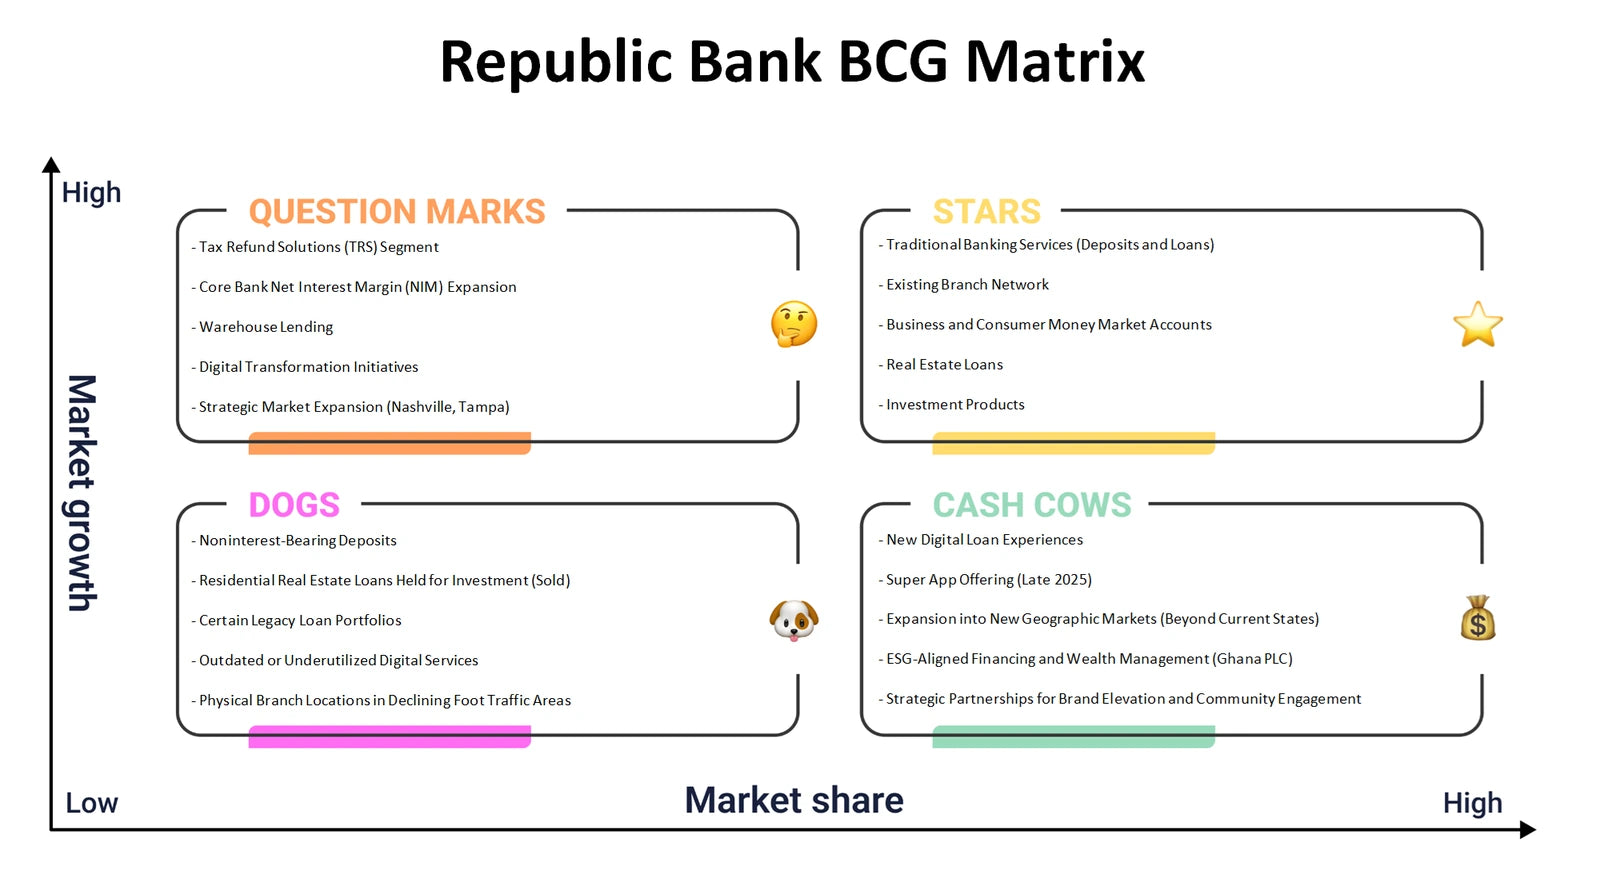
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do referral-led loan origination, banking technology and risk controls connect to Republic Bank's customer value and economics?
The Republic Bank Business Model Canvas examines the whole value-creation system rather than treating products or channels separately. It brings together customer segments, value propositions, channels, customer relationships and revenue streams with key resources, key activities, key partnerships and cost structure. In the supplied context, brokers, auto dealers and referral sources are relevant potential channel and partnership questions; core banking, CRM, analytics, APIs and data governance are relevant resource and activity questions. The canvas helps trace how a qualified application becomes a decision, funded relationship and serviced account, while also identifying where acquisition cost, credit risk, compliance effort and technology spending influence the economics.
- Customer journey. Examine how consumer and property-finance customers may encounter the bank through direct and intermediary routes, and what relationship support each route requires.
- Economic links. Connect revenue-stream questions to origination, servicing, data, risk and partner-management costs instead of viewing each block in isolation.
- Connected planning. Populate the Excel canvas with working hypotheses and use the Word analysis to explore dependencies, gaps and questions for internal review.
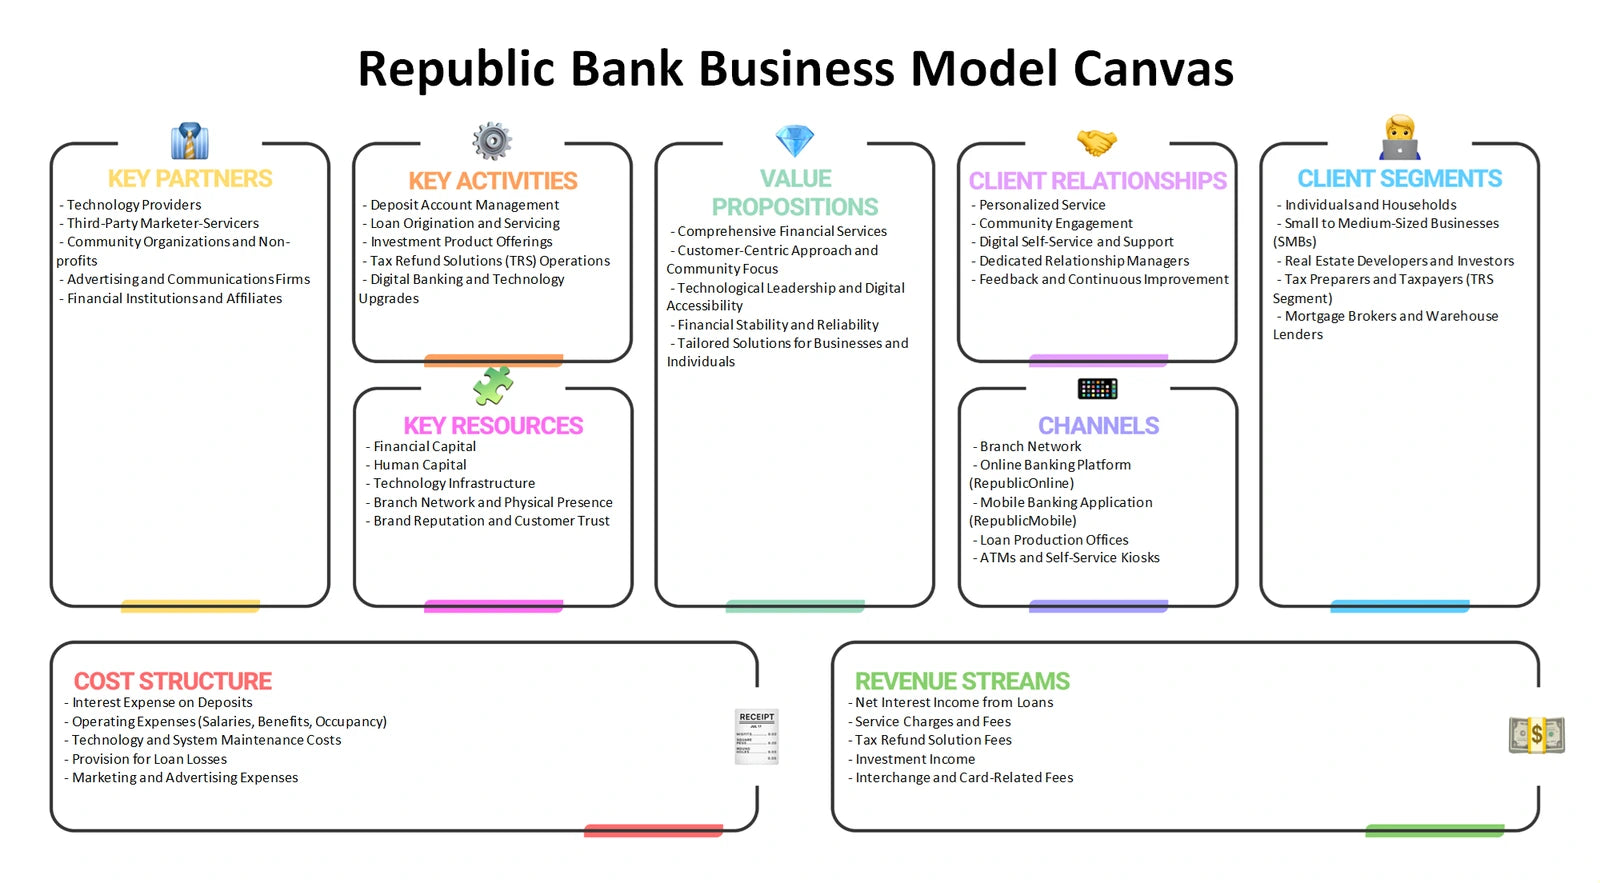
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What pressures could affect Republic Bank's ability to originate, price and retain lending relationships responsibly?
Republic Bank Porter's Five Forces provides a disciplined lens for the competitive environment surrounding consumer and real-estate lending. Rivalry considers the intensity of competing banks and lenders seeking similar borrowers or referral relationships. Buyer power asks how readily customers and intermediaries can compare rates, terms, service and approval speed. Supplier power can include the influence of funding providers, technology vendors and specialised service partners. The threat of new entrants addresses the possibility of digitally enabled lenders or niche providers, while substitutes include other ways customers can finance a home, vehicle or personal need. These are analytical forces, not scores or claims about named competitors.
- Channel dependence. Assess whether reliance on brokers, dealers or referrals creates negotiating leverage, concentration exposure or an opportunity for differentiated service.
- Substitution test. Compare loans with alternative financing, savings-based purchases, leasing arrangements or other solutions that can meet the same customer need.
- Evidence trail. Use the Excel framework to compare force drivers and use the Word analysis to document why a pressure matters for pricing, service or risk controls.
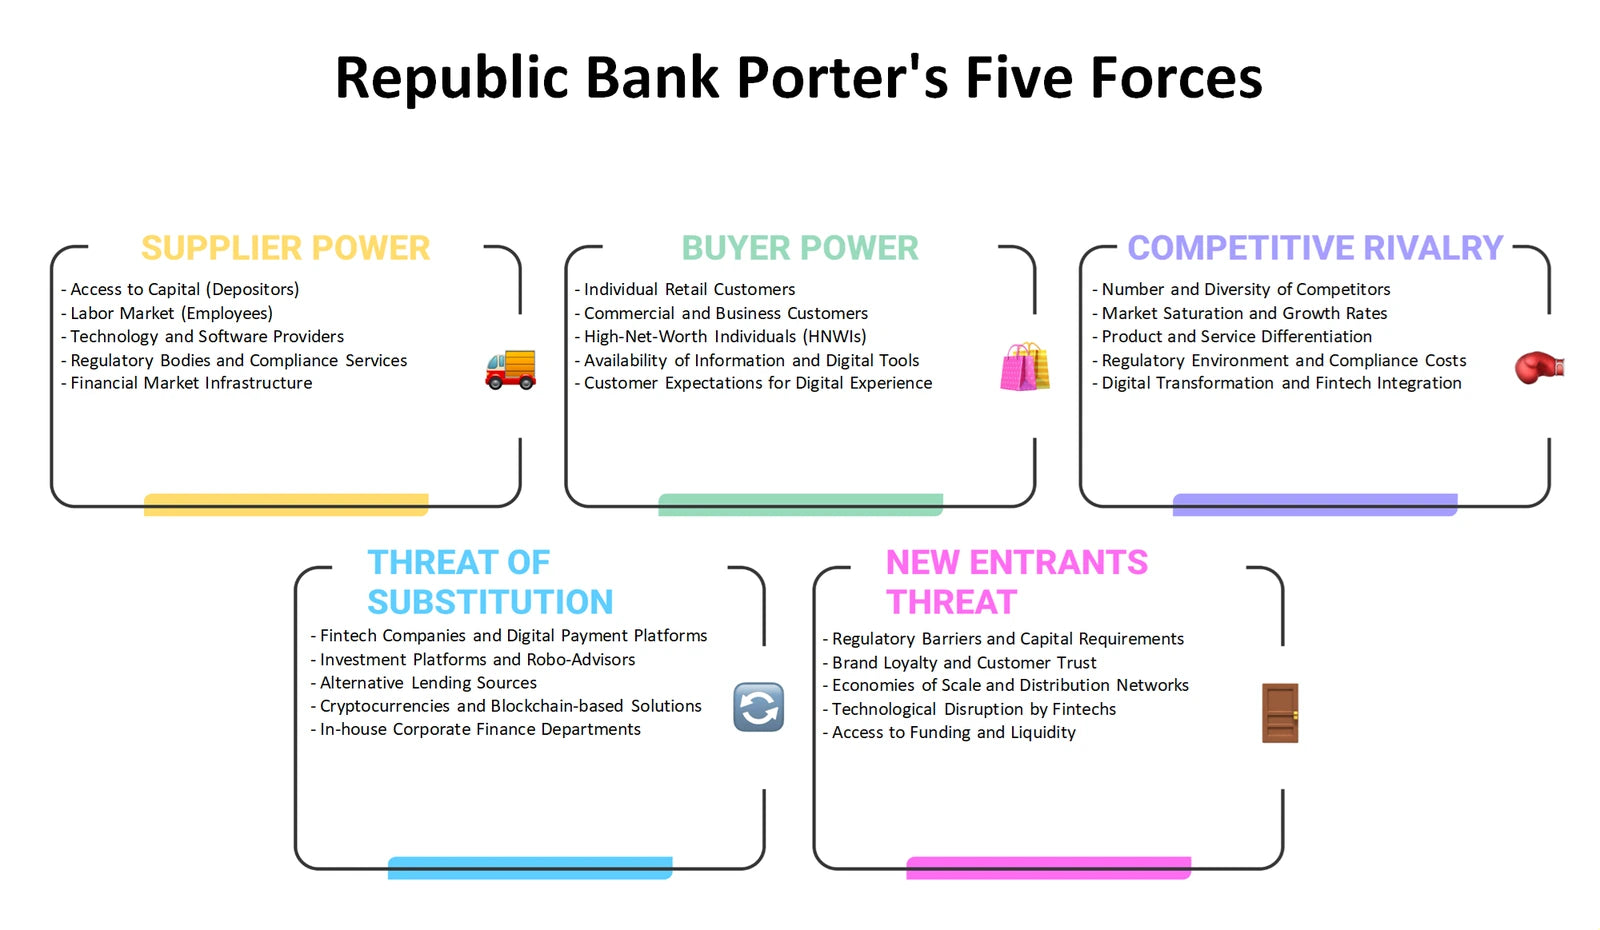
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can Republic Bank align lending propositions, pricing logic, distribution routes and communications with customer needs and banking obligations?
The Republic Bank Marketing Mix considers Product, Price, Place and Promotion as connected choices in a regulated service setting. Product can cover the design of consumer and real-estate lending propositions, supporting account services and the experience around application and servicing. Price is broader than an advertised rate: it can include fees, risk-based terms, affordability and the clarity of customer disclosures. Place examines direct, digital and partner-enabled access, including the role of mortgage brokers and auto dealers. Promotion asks how messages can explain value accurately while setting appropriate expectations. The framework does not invent campaigns, pricing or channel shares; it helps assess whether these choices fit together.
- Offer clarity. Test whether product features and customer benefits are understandable across different borrowing needs, stages and referral routes.
- Pricing discipline. Explore the balance between competitive terms, credit quality, operational cost and transparent customer communication.
- Activation plan. Use Excel to compare the 4Ps by audience or channel, then consult the Word analysis when shaping questions for marketing, lending and compliance teams.
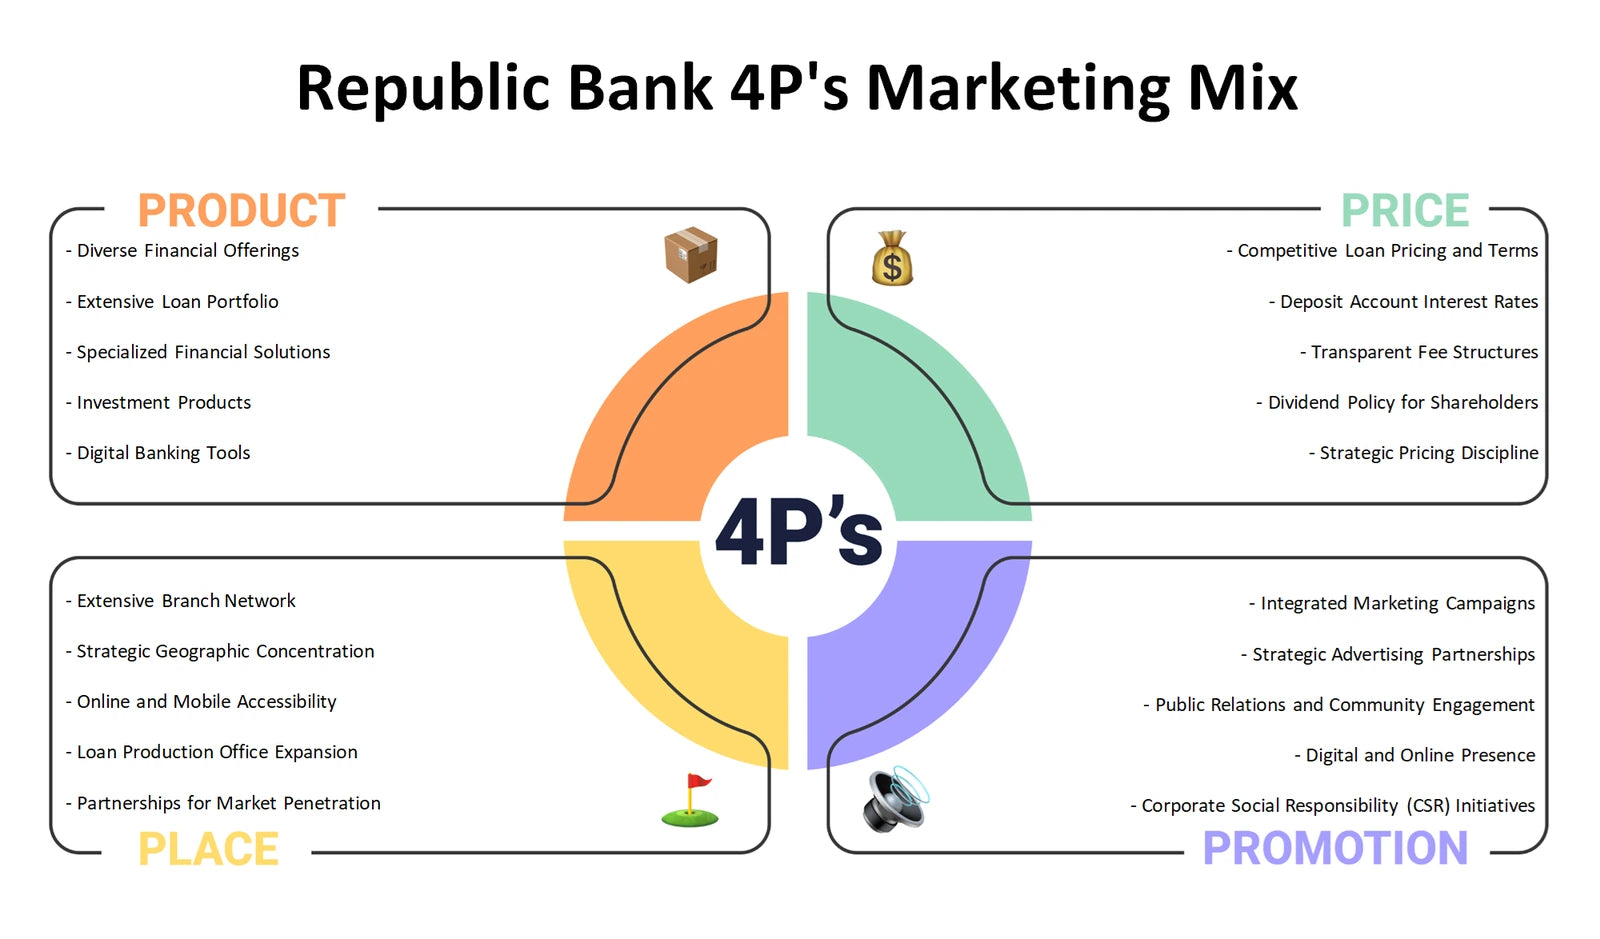
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes should Republic Bank monitor when planning lending growth, technology investment and customer support?
A Republic Bank PESTLE analysis, also commonly called PESTEL, separates external influences from management choices. Political factors can include public-policy direction and regulatory priorities; economic factors can include borrowing affordability, employment conditions, funding costs and property-market conditions. Social themes may affect customer preferences, financial confidence and demand for accessible service. Technological change is relevant to digital onboarding, analytics, APIs, cybersecurity and data governance. Legal factors include consumer protection, privacy, lending and financial-crime obligations. Environmental issues can affect property-related exposure, operating resilience and stakeholder expectations. The framework asks what to watch and prepare for; it does not claim that a particular law, rate or policy has changed.
- Early signals. Distinguish slow-moving structural trends from nearer-term triggers that could affect demand, credit quality, costs or operating controls.
- Cross-functional impact. Link external developments to the teams likely to respond, such as lending, compliance, technology, operations and customer service.
- Monitoring routine. Use the Excel framework to track impact and uncertainty, with the Word analysis providing context for prioritising review questions.
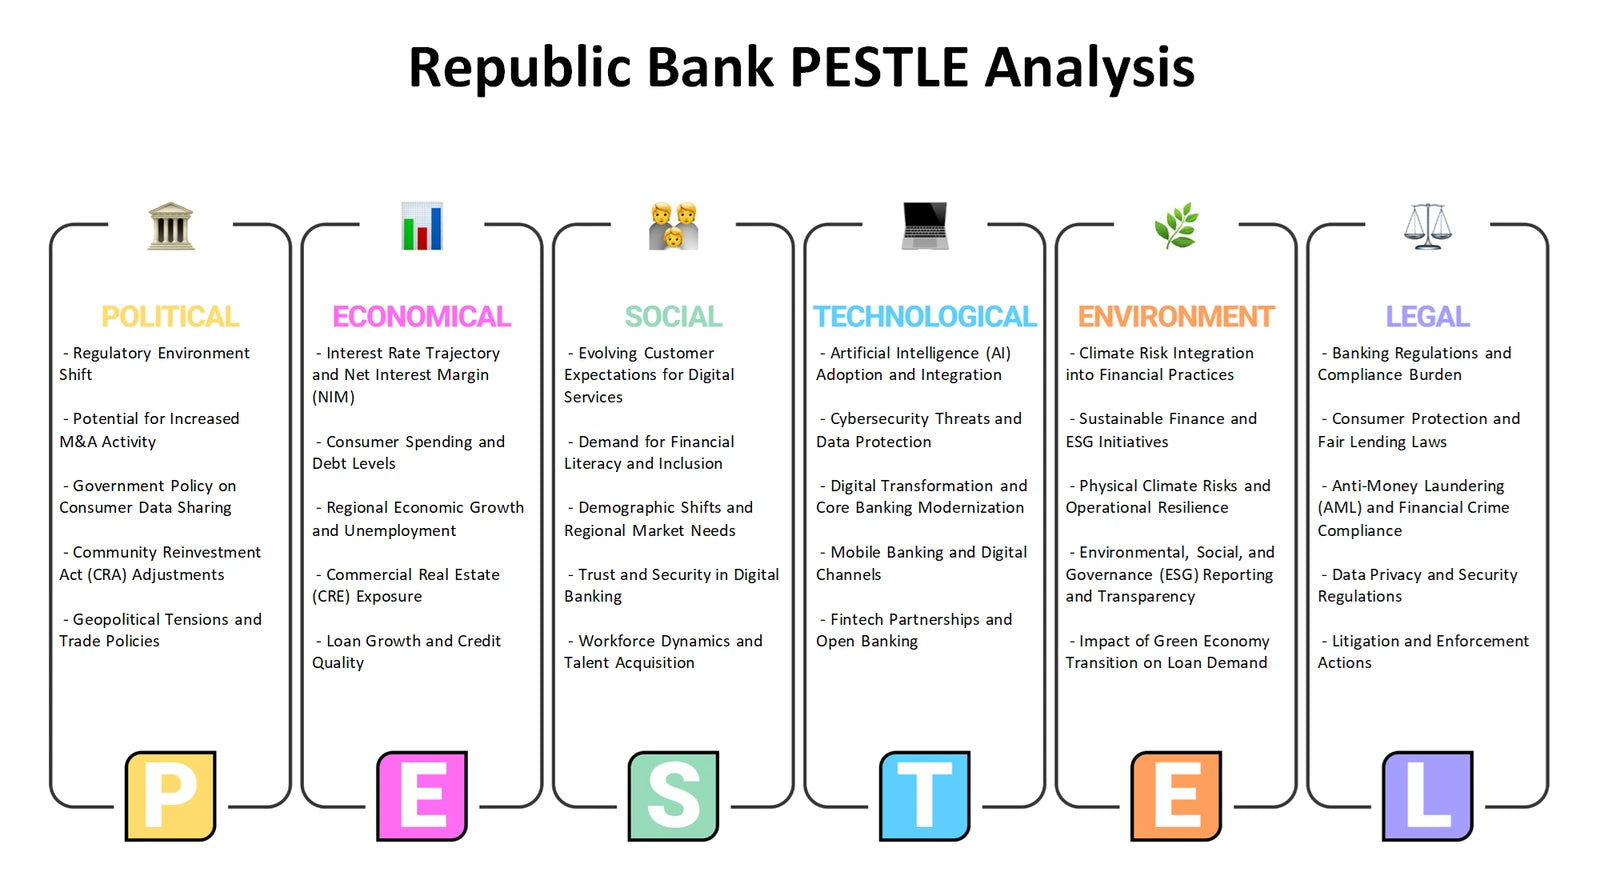
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Republic Bank distinguish internal capabilities and limitations from external opportunities and threats?
A Republic Bank SWOT analysis brings the other lenses into a decision-ready summary. Strengths and weaknesses are internal: for example, the usefulness of loan-origination relationships, banking systems, CRM, analytics, integration capability and data governance should be tested as capabilities rather than assumed advantages. Opportunities and threats are external, such as changing customer demand, channel developments, competitive conditions and regulatory expectations. Keeping this distinction matters because a technology platform is not an opportunity in itself, and a market condition is not a weakness. The framework helps connect potential internal capability with the external context in which it must perform, without claiming that any theme has already been proven.
- Classification discipline. Separate controllable operational matters from outside-market developments so ownership and response options are clearer.
- Strategic fit. Explore whether data, partner integration and customer insight could support selected opportunities while exposing capability gaps needing attention.
- Decision summary. Use the Excel SWOT grid to prioritise relationships among factors, then use the Word analysis to develop the reasoning behind strategic options.
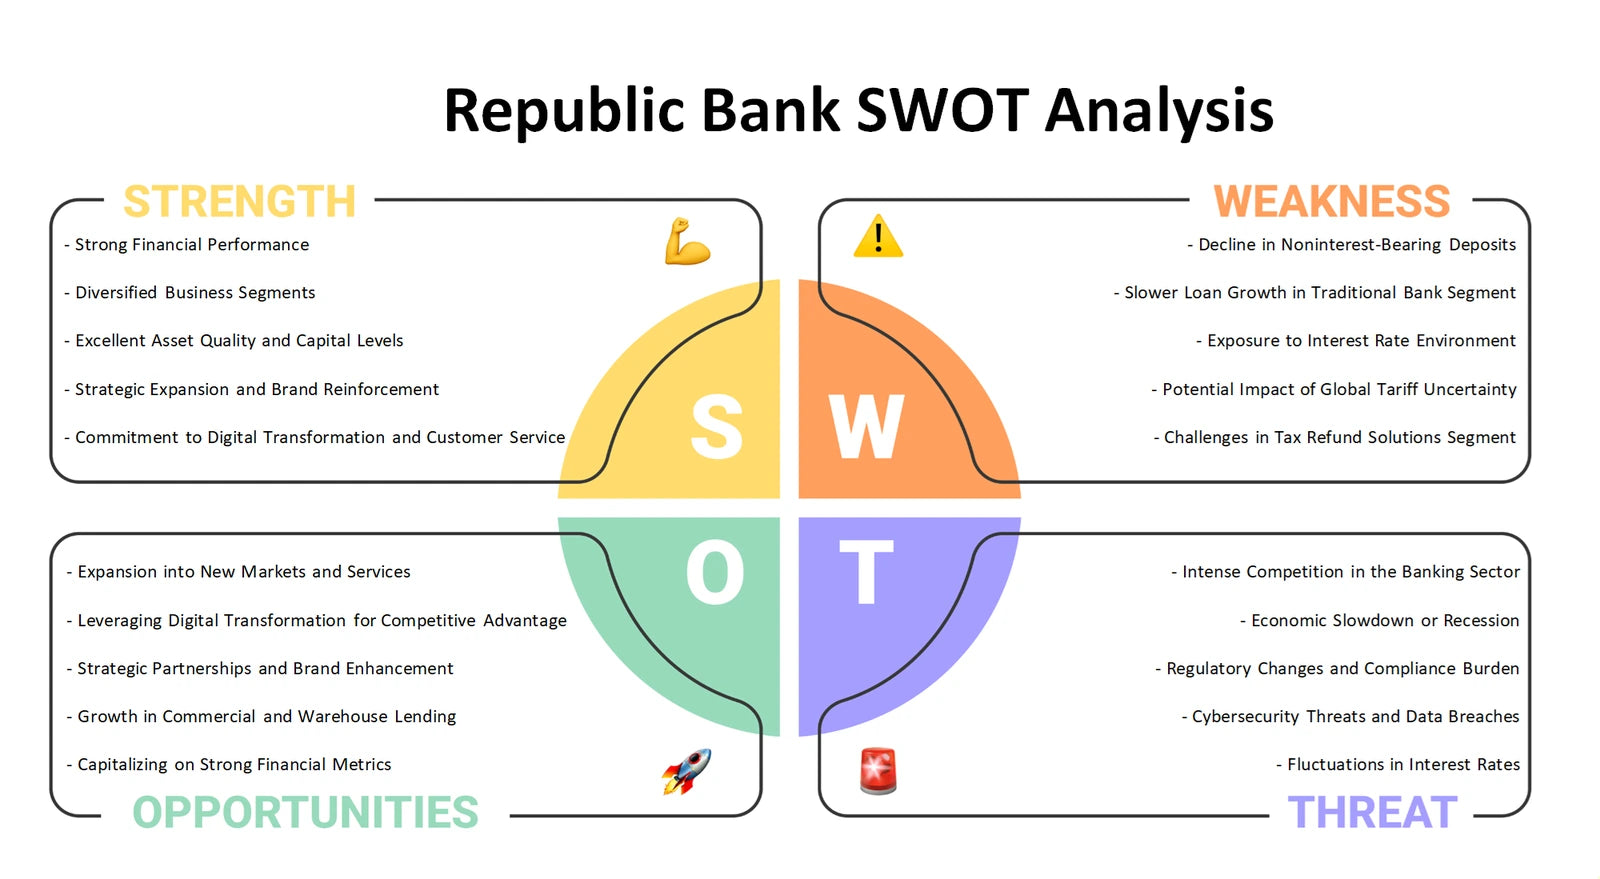
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Bring lending strategy into one connected view
Used together, the six perspectives move from portfolio choices and business-model mechanics to competitive conditions, customer-market decisions, external change and strategic priorities. For Republic Bank, the materials can help organise discussion around referral-led origination, consumer and real-estate lending, banking technology, data governance and operating trade-offs. The Excel frameworks support structured comparison and working sessions, while the detailed Word analysis provides a fuller basis for interpreting the questions behind each framework.
Company background: Republic Bank — product-context page.