

Repco Home Finance: Lending Economics and Distribution – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Repco Home Finance Strategy Analysis Bundle
This bundle is scoped to the Repco Home Finance housing-finance context supplied for this product. It examines a lender serving prospective home-finance customers, with a business model shaped by loan sourcing, underwriting, disbursal, repayment relationships and risk control. The supplied context also describes an affiliation with Repco Bank, alongside relationships with branches, developers, direct selling agents and digital partners that may support customer acquisition and compliant loan origination.
For Repco Home Finance, strategy is not only about lending volume: it also involves balancing accessible borrowing journeys with credit discipline, managing the cost of each sourced file, and deciding where partnerships can extend reach without weakening control. The six connected analyses help organise those questions from portfolio priorities and value creation to competitive pressure, marketing choices, external conditions and internal trade-offs.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which loan offerings, sourcing routes or customer segments deserve greater resource commitment as the business develops?
A Repco Home Finance BCG Matrix helps distinguish portfolio questions from broad growth ambitions. It compares market growth with relative market share, then uses the Star, Cash Cow, Question Mark and Dog categories to structure discussion about products, geographies or distribution routes. For a housing-finance business, the relevant comparison may include the maturity of loan demand, the economics of servicing, the quality of sourced applications and the resources needed to build presence in a segment. The framework does not assign Repco Home Finance to any quadrant; it provides a disciplined way to test priorities before capital, sales effort or technology spend is allocated.
- Portfolio lens. Compare home-finance propositions, channels or target segments using both growth conditions and relative competitive position.
- Resource trade-off. Consider whether a developing area requires patient investment, tighter monitoring, harvest discipline or reduced attention.
- Working view. Use the Excel matrix to map assumptions and the Word analysis to record the evidence, cautions and portfolio questions behind each placement.
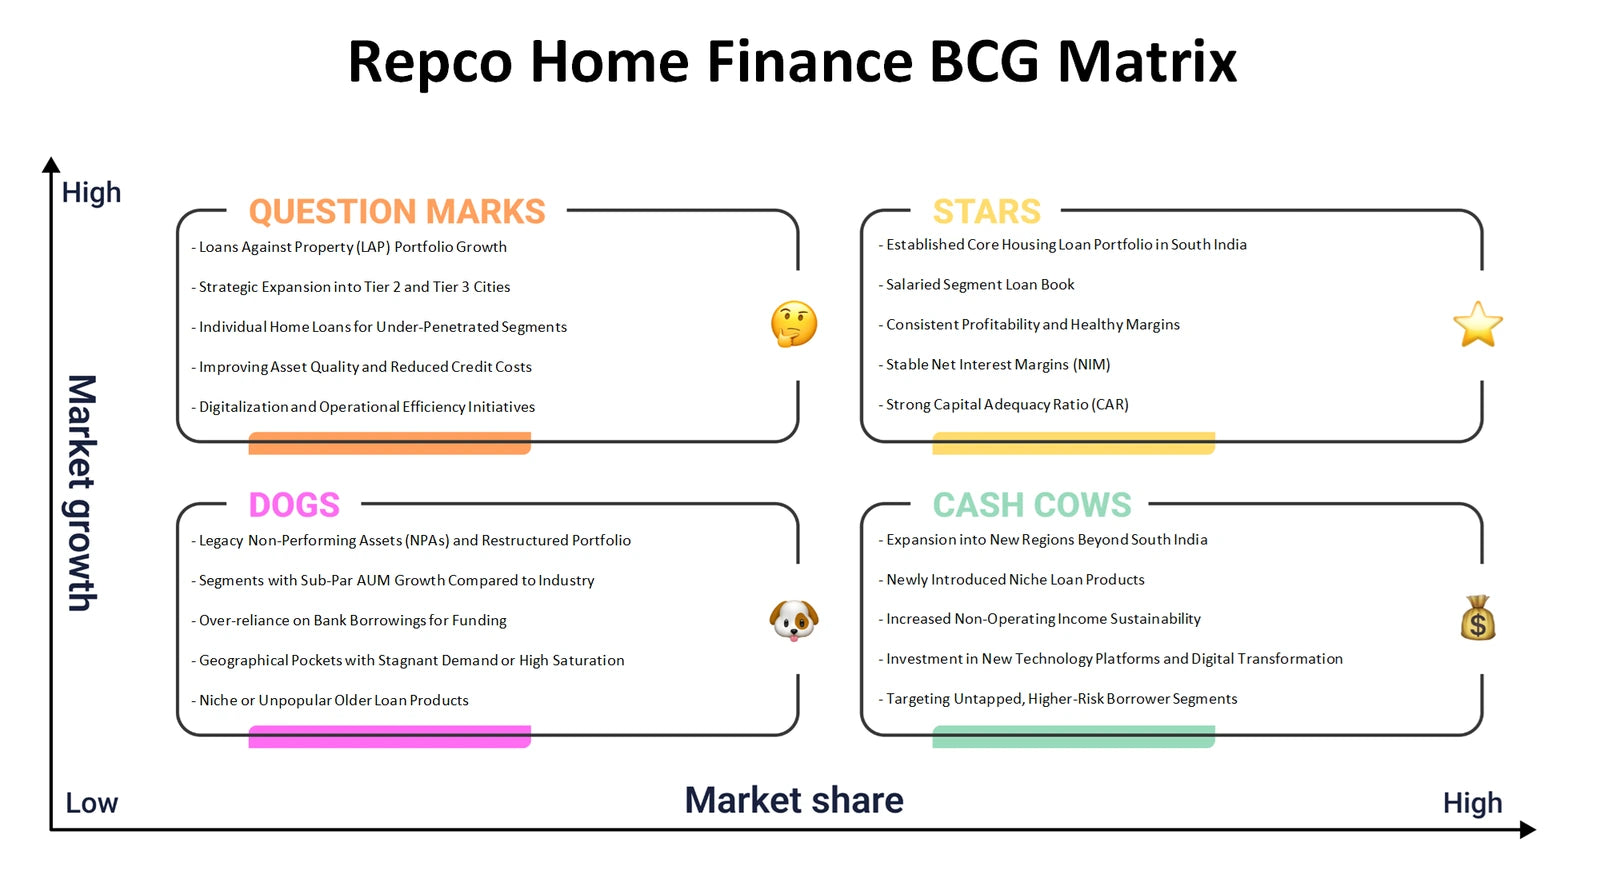
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do borrower needs, trusted access points and disciplined credit processes connect to sustainable lending economics?
The Repco Home Finance Business Model Canvas brings the nine building blocks into one operating picture: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. It is especially useful where branch relationships, developers, direct selling agents and digital partners may influence both reach and cost per application. The canvas helps examine whether the promise of a clear, timely home-finance journey is supported by underwriting, verification, servicing and collections capabilities, while also considering how lending income and operating costs fit together. It is a model for investigating links, not a claim that every channel or partnership performs equally well.
- Borrower journey. Trace how customer segments move from awareness and application through approval, disbursal, repayment and ongoing service.
- Operating logic. Connect resources and activities such as credit assessment, automated verification and compliance with partnerships and cost drivers.
- Model alignment. Populate the Excel canvas collaboratively, then use the Word analysis to explain dependencies, assumptions and questions requiring validation.
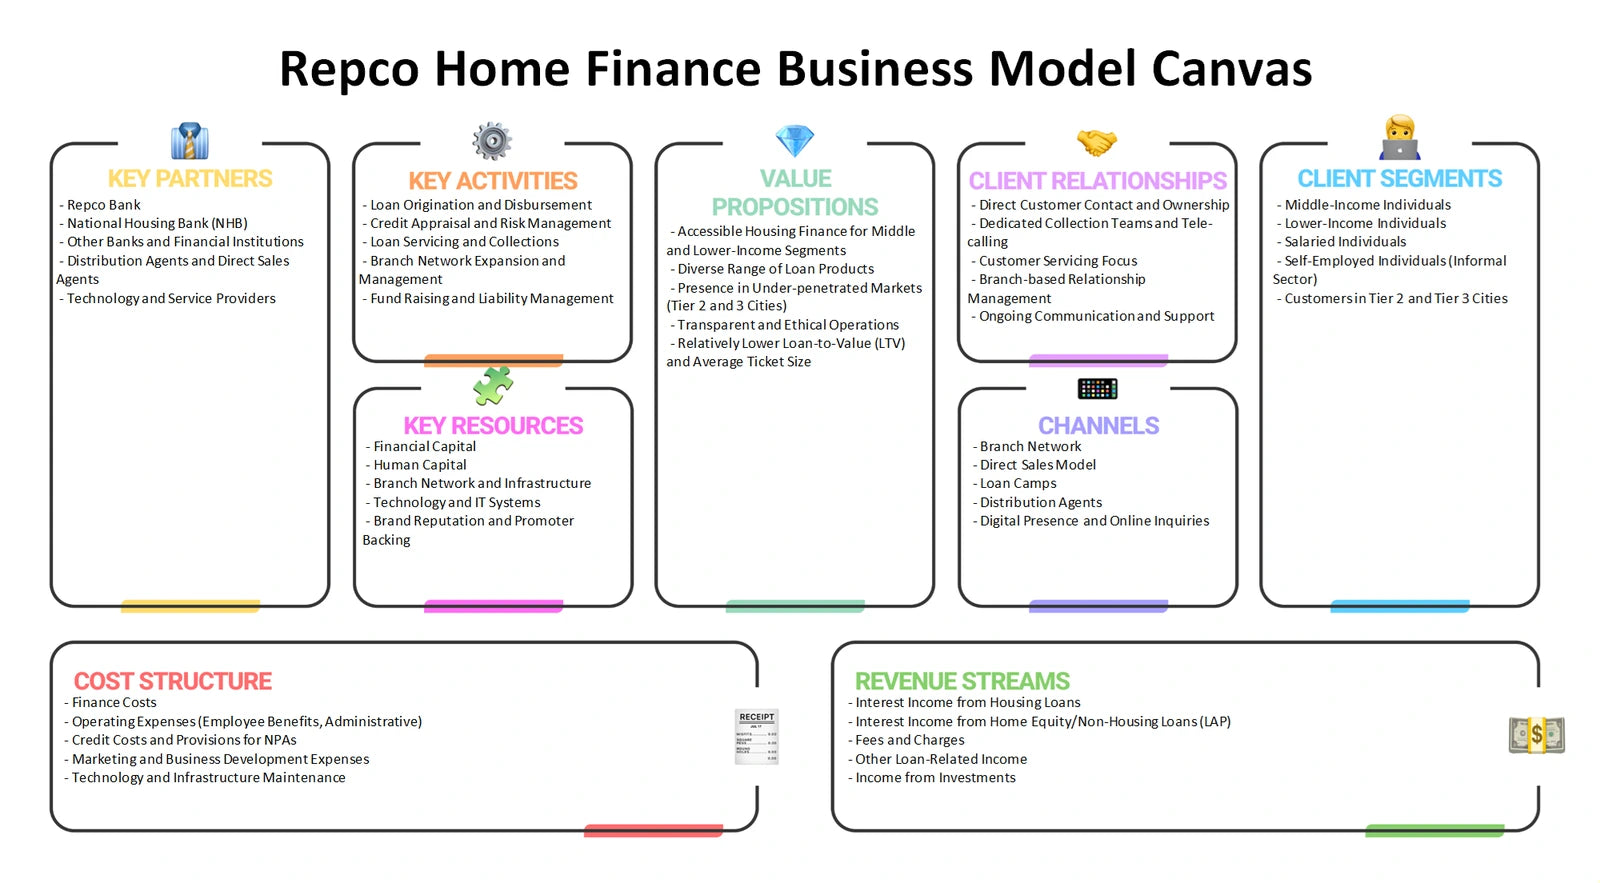
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could affect lending margins, borrower choice and the cost of acquiring and serving home-finance customers?
Repco Home Finance Porter's Five Forces analysis frames the competitive environment around housing finance rather than treating every challenge as a direct rival issue. Rivalry can influence product comparison and service expectations; buyer power reflects how borrowers assess rate, turnaround time, transparency and access; and supplier power may arise in funding, technology, data or intermediary relationships. The threat of new entrants tests the barriers created by regulation, capital, trust and underwriting capability. Substitutes include alternative ways households can fund a property need, such as savings, family support or different credit arrangements. The framework helps compare pressures without assigning unsupported force scores.
- Competitive pressure. Examine how lender choice and comparable borrowing options may shape pricing discipline and service differentiation.
- Control points. Identify where reliance on capital providers, data sources, technology vendors or intermediaries could affect resilience.
- Evidence trail. Use the Excel framework to rank questions for investigation and the Word analysis to capture the reasoning behind each force.
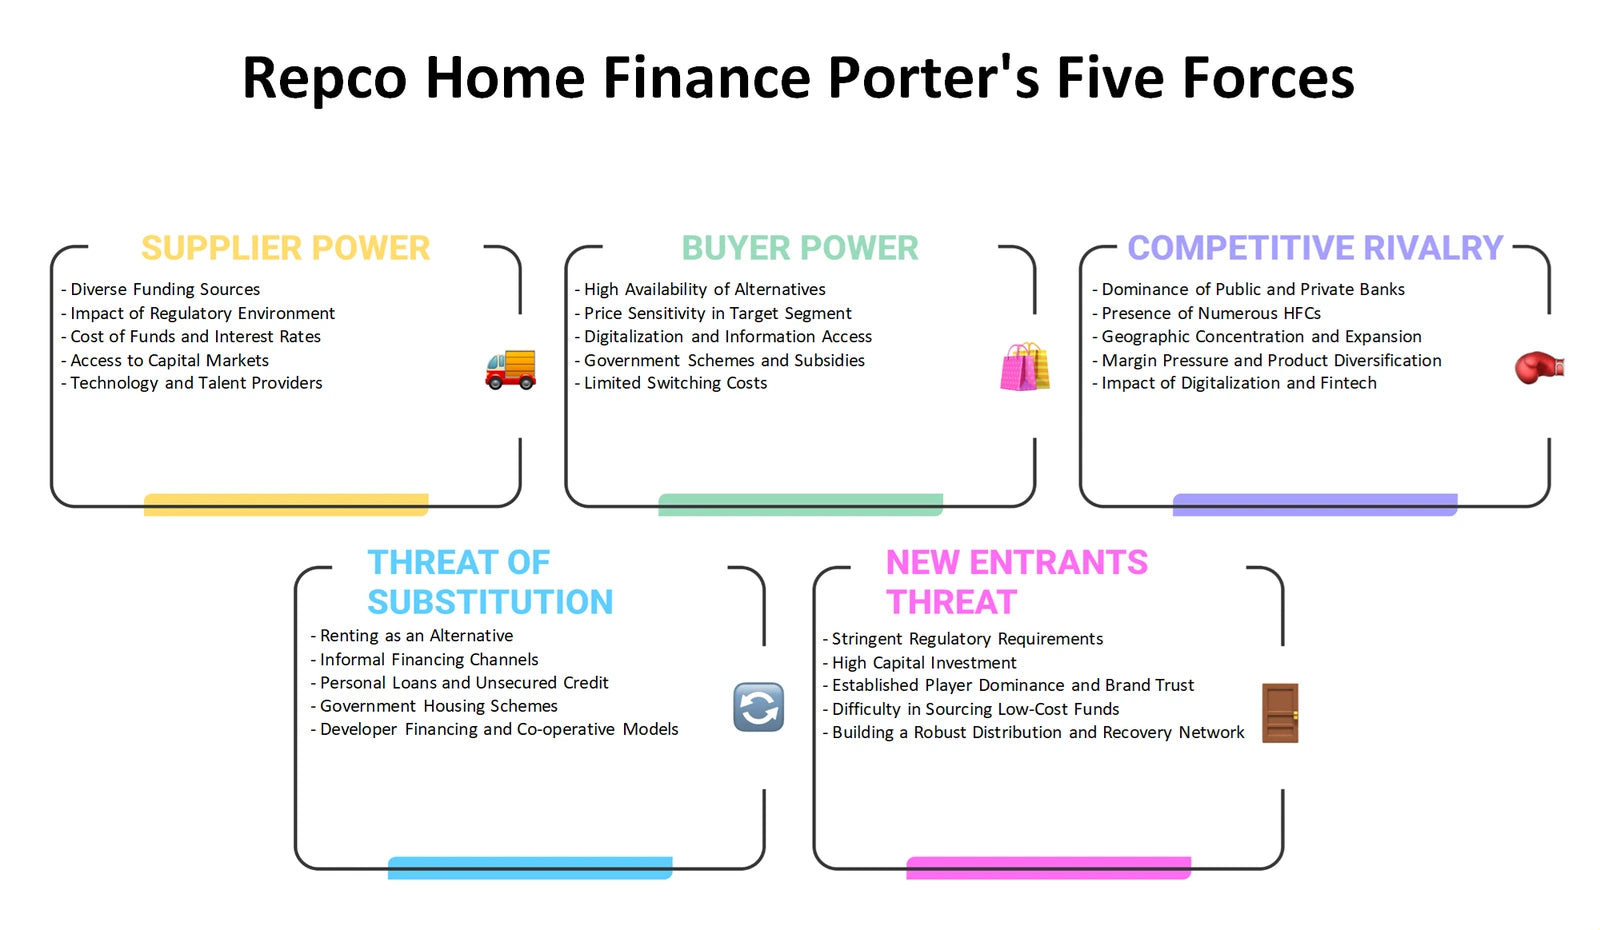
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a regulated home-finance proposition be presented, accessed and communicated in ways that build borrower confidence?
A Repco Home Finance Marketing Mix reviews Product, Price, Place and Promotion as linked customer choices rather than separate campaign elements. Product covers the loan proposition, application experience, documentation guidance and service around disbursal and repayment. Price considers the logic borrowers use to assess interest, fees, affordability and clarity, without assuming any particular price level. Place examines branches, partner referrals, developer connections, direct selling agents and digital journeys. Promotion focuses on credible communication that helps borrowers understand eligibility, process steps and responsible borrowing. For a financial service, alignment across the four Ps matters because a persuasive message cannot compensate for unclear terms or a difficult application path.
- Offer clarity. Assess whether product features and borrower guidance address the practical concerns of home-finance applicants.
- Route to market. Compare how assisted and digital channels may serve different customer needs while preserving process consistency.
- Planning tool. Use the Excel 4Ps structure for channel and message comparisons, supported by the Word analysis for customer-facing implications.
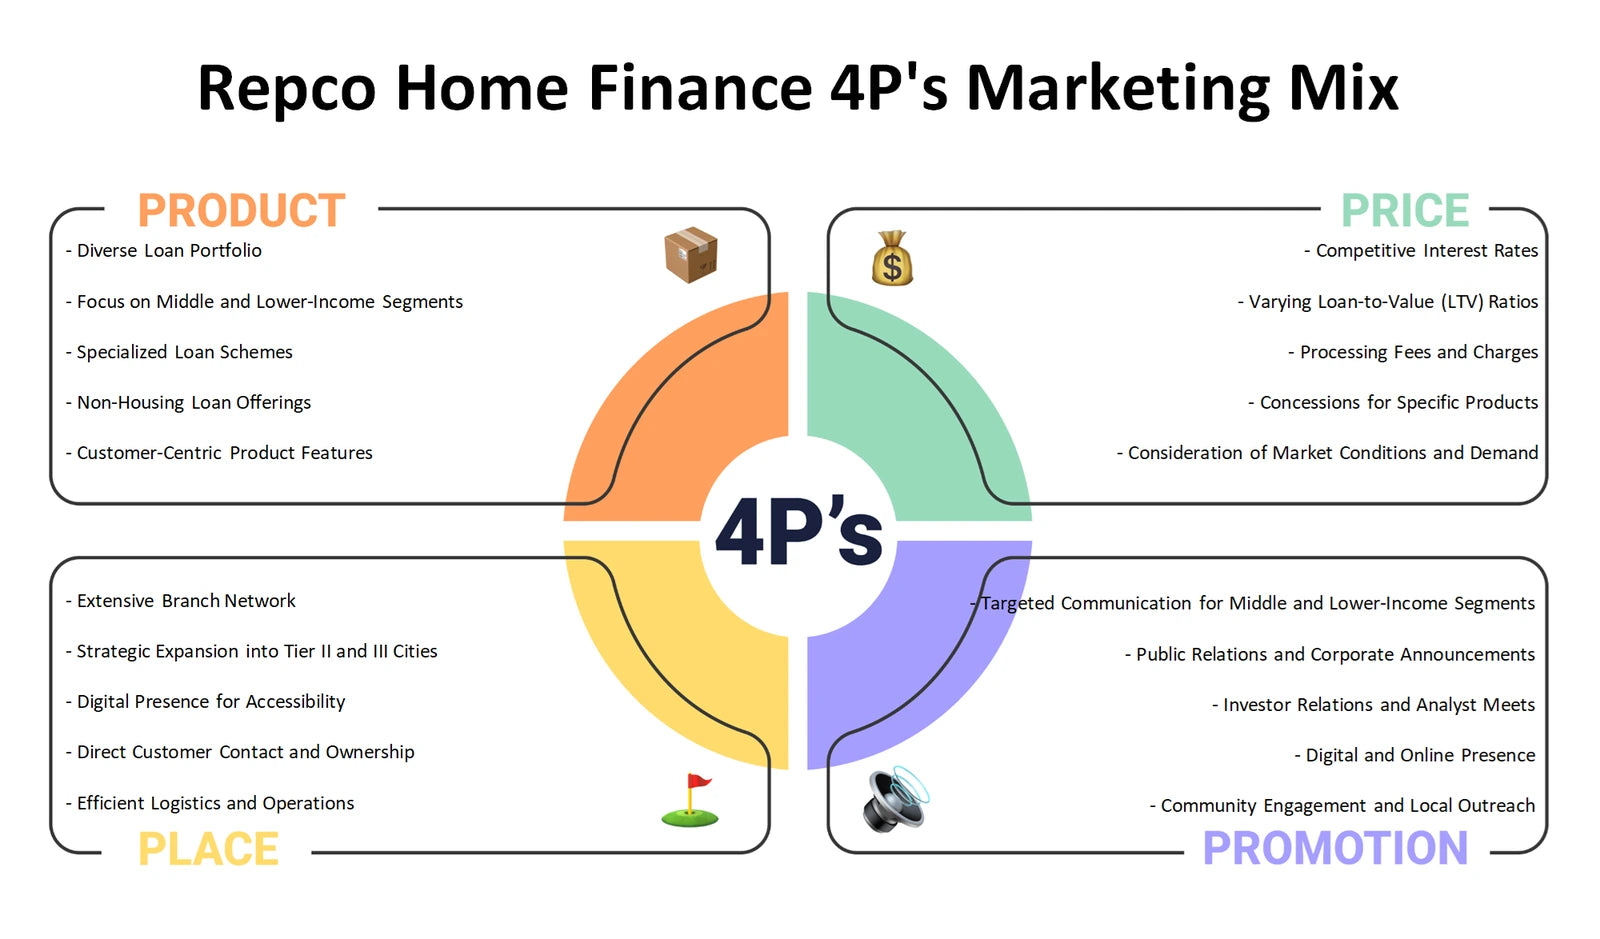
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter demand for housing finance, borrower affordability, operating requirements or credit risk?
A Repco Home Finance PESTLE analysis, also commonly called PESTEL, separates outside influences that management cannot control but must monitor. Political conditions can affect housing priorities and public-policy direction; economic conditions influence incomes, property demand, funding costs and repayment capacity. Social factors include household aspirations, financial awareness and preferences for assisted or digital service. Technology raises questions around verification, fraud prevention, data use and application speed. Legal factors cover lending, consumer protection, privacy and compliance expectations, while environmental factors can influence property resilience, local development patterns and risk assessment. These are analytical areas to examine, not claims that a specific policy, rate or regulation has changed.
- External signals. Separate macroeconomic and policy questions from customer, technology and property-related developments.
- Risk relevance. Link each factor to possible effects on origination quality, affordability, operating cost or compliance workload.
- Monitoring map. Use the Excel framework to prioritise indicators and the Word analysis to document why selected external themes matter.
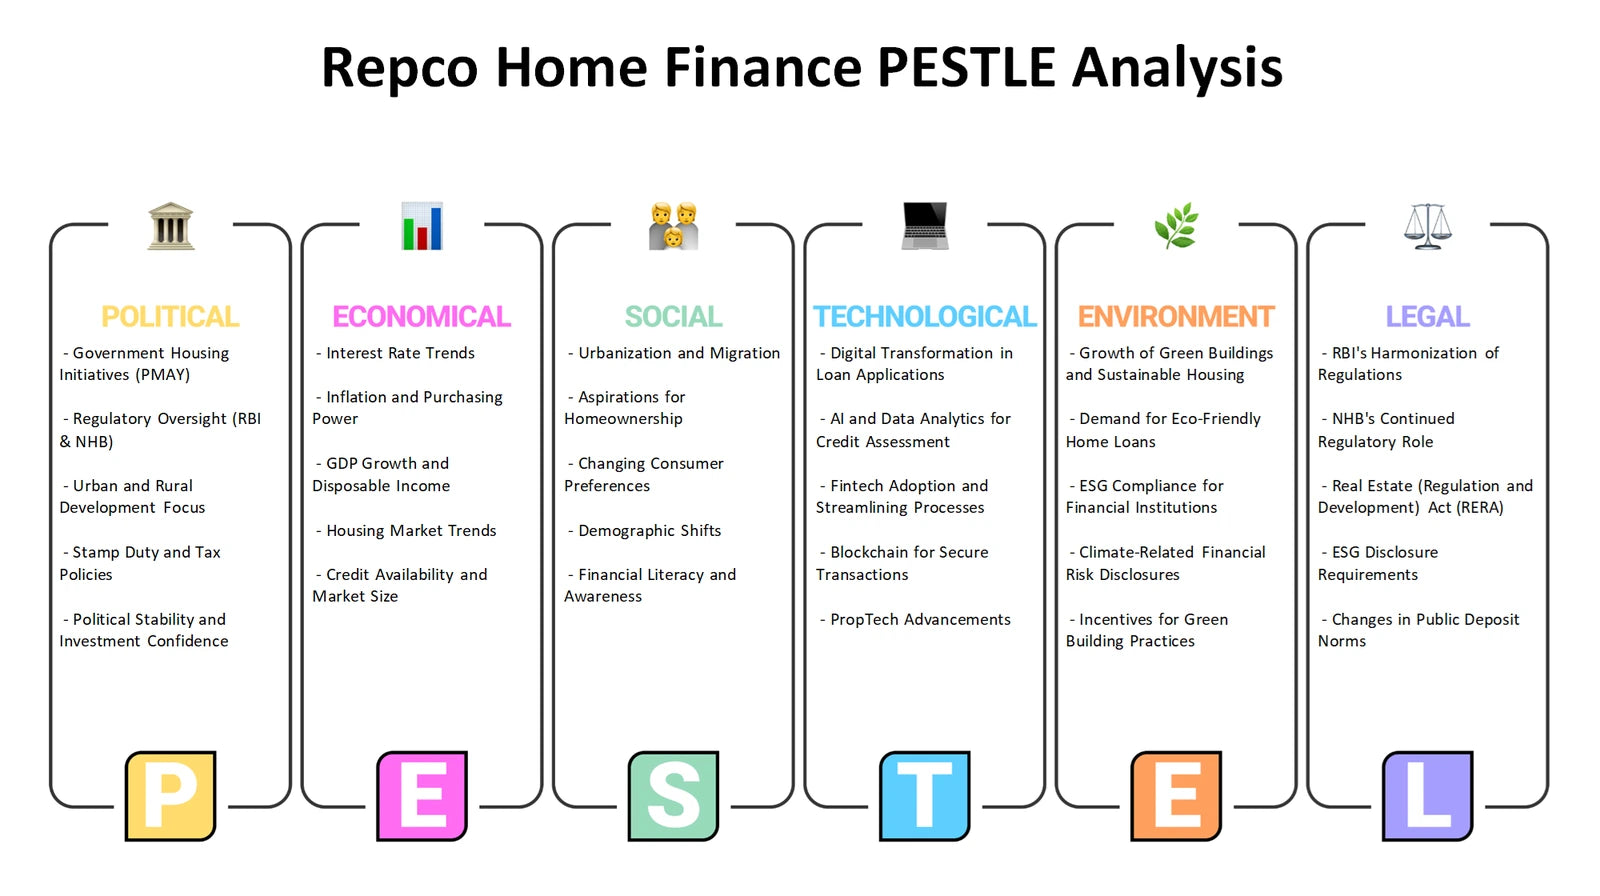
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Repco Home Finance connect its capabilities and constraints with market opportunities and external threats?
A Repco Home Finance SWOT analysis keeps internal and external considerations distinct. Potential internal strengths to investigate may include brand trust, lending knowledge, partner access, underwriting processes or borrower-service capabilities. Possible internal weaknesses may concern capacity, cost-to-serve, process complexity, concentration or data limitations; these require evidence rather than assumption. Opportunities sit outside the business, such as underserved borrower needs or more effective digital access, while threats include economic stress, fraud, competitive intensity and regulatory change. This separation helps avoid describing a market trend as a strength or treating an internal operating gap as an external threat. It also encourages decisions that match capability development to the environment.
- Internal reality. Test which resources, routines and relationships genuinely support dependable loan origination and servicing.
- External fit. Compare market openings and risks against the organisation's ability to respond without weakening credit discipline.
- Decision record. Use the Excel SWOT grid to organise inputs and the Word analysis to turn them into balanced strategic discussion points.
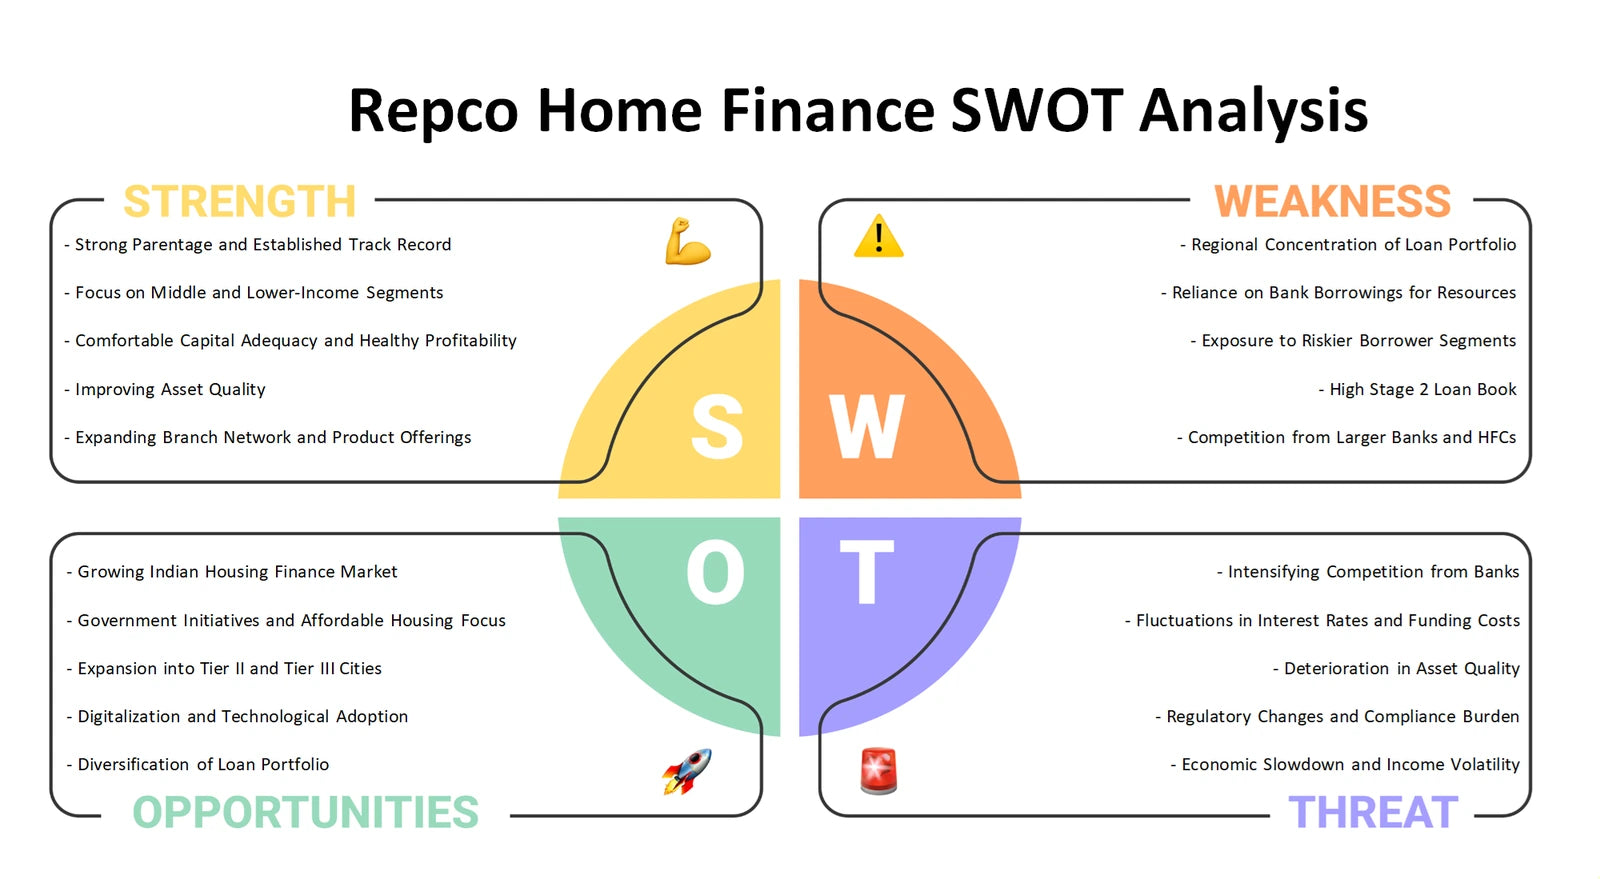
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of the lending business
Together, the six perspectives move from portfolio choices and business-model mechanics to market pressure, customer routes, external change and organisational fit. The Excel frameworks provide a structured place to compare issues, while the detailed Word analysis helps develop a more considered discussion of Repco Home Finance's lending, distribution and risk-management questions.
Company background: Repco Home Finance — business model context from PESTEL Analysis.