

Regional Management: Lending Economics and Partnerships – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
Regional Management Strategy Analysis Bundle
Regional Management is the workbook display name for Regional Management Corp., the SEC-reporting lender considered in this bundle. The supplied company context describes lending for individuals and small businesses through direct consumer loans and retail point-of-sale financing, including purchase categories such as furniture and appliances. Loan origination therefore depends on customer access, underwriting discipline, merchant relationships and dependable funding capacity.
In a Form 10-Q filed July 31, 2026, Regional Management Corp. reported revenue of USD 168.006 million and GAAP net income of USD 8.153 million for the three months from April 1 to June 30, 2026. This dated snapshot raises practical questions about portfolio priorities, funding economics and customer acquisition; it does not show that the downloadable analysis files were updated in 2026.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending products, customer segments or origination routes deserve scarce capital and management attention?
A Regional Management BCG Matrix helps organize portfolio choices using market growth and relative market share rather than treating every lending activity as equally strategic. It can compare direct consumer lending, merchant-linked finance and other relevant product or channel groupings where evidence is available. The framework distinguishes Stars, Cash Cows, Question Marks and Dogs as analytical categories; it does not assume that any Regional Management activity already belongs in a quadrant. This matters where funding capacity and credit-risk oversight may limit how quickly the company can scale an opportunity.
- Capital allocation. Compare growth potential with relative position before prioritizing loan programs, merchant relationships or acquisition routes.
- Portfolio trade-offs. Examine whether mature activities could support investment in newer channels without overlooking servicing and credit costs.
- Working view. Use the Excel matrix to place evidence-backed activities, then use the Word analysis to record assumptions and questions behind each placement.
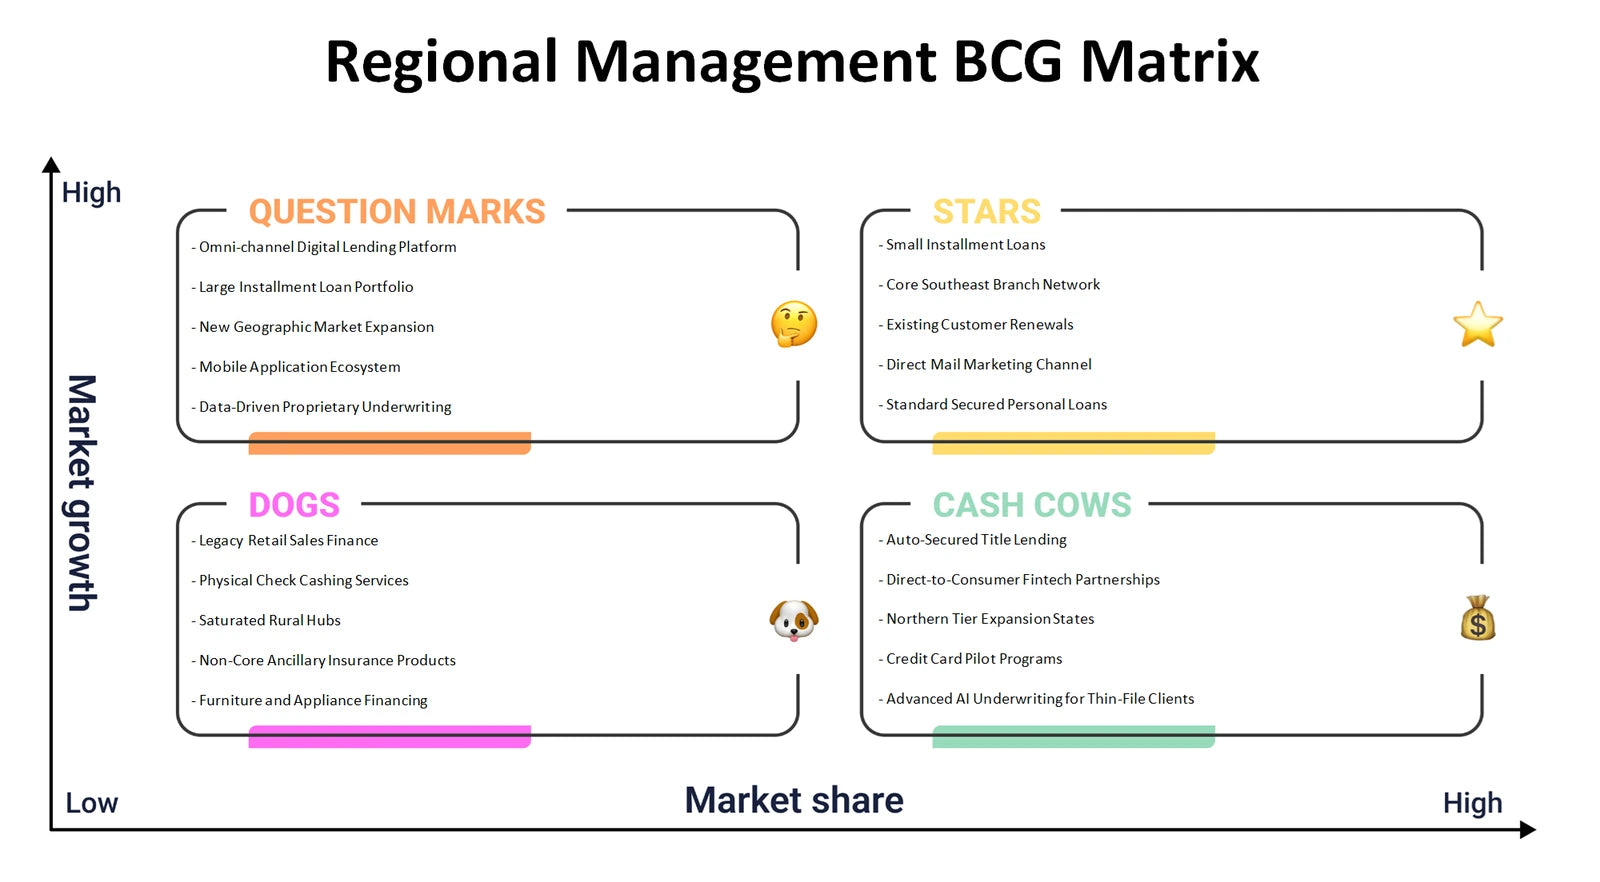
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do borrower needs, merchant access, funding partners and loan economics fit into one operating model?
The Regional Management Business Model Canvas connects all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For a lender, this lens can examine how borrower access and financing convenience connect with underwriting data, servicing, collections, debt facilities and asset-backed securitizations. It also makes the economic connection visible: revenue from lending must be considered alongside funding, credit performance, compliance and operating costs. The goal is to test coherence, not to assert undocumented business-model findings.
- Value chain. Trace how a borrower or retail purchase-finance opportunity moves from acquisition and decisioning through funding, servicing and repayment.
- Partner dependence. Assess why institutional funding relationships and retail partners may matter to origination capacity and liquidity.
- Model mapping. Populate the Excel canvas block by block, using the detailed Word analysis to connect each block to its economic rationale and open questions.
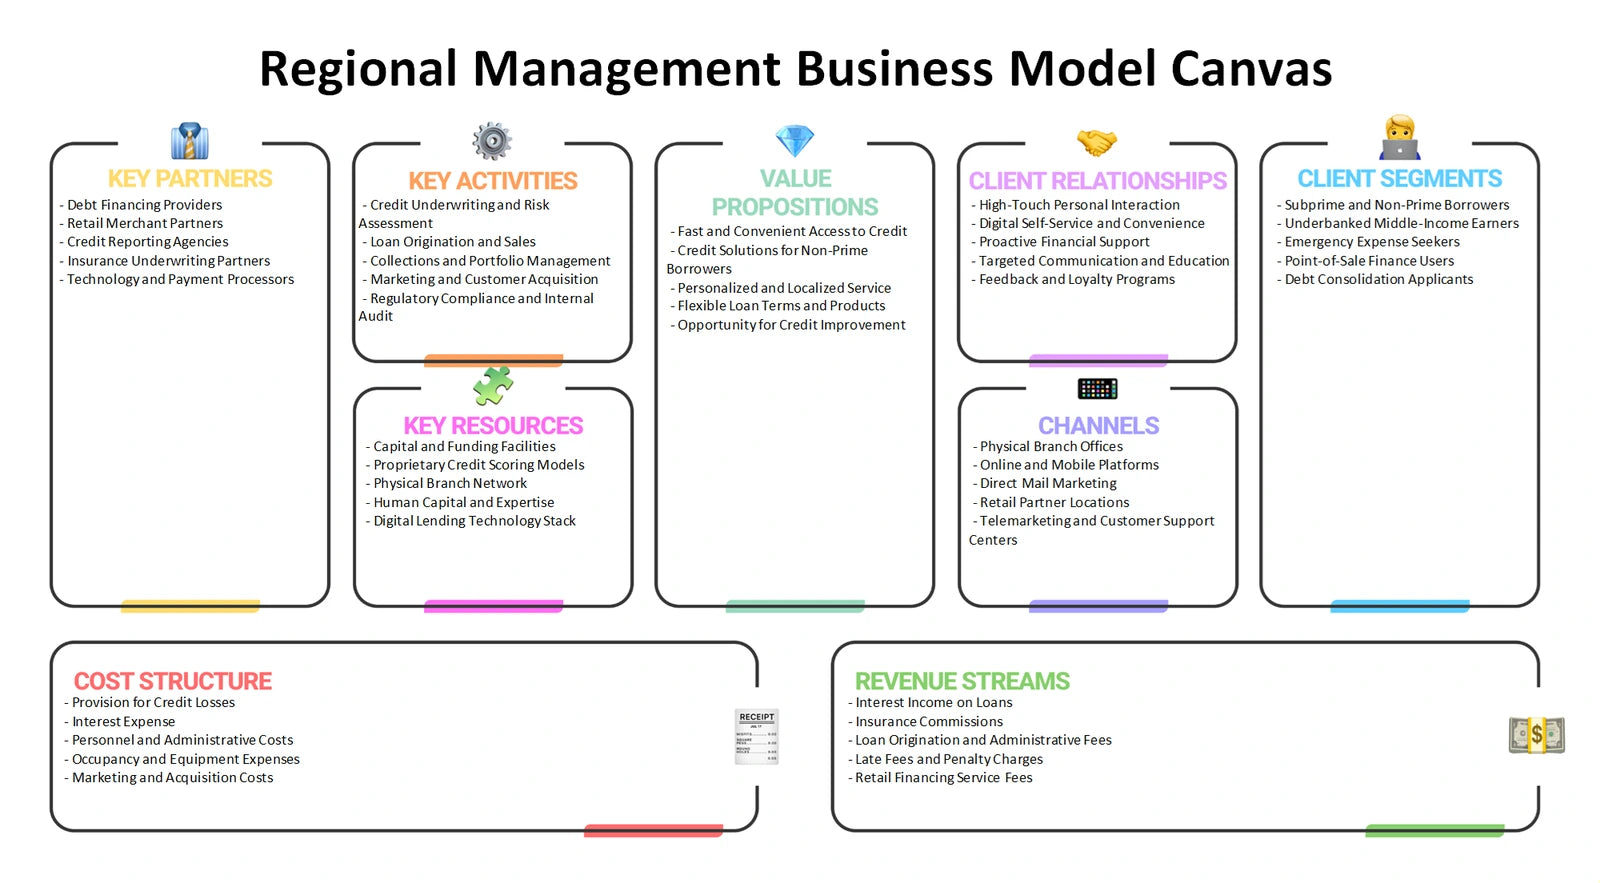
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can affect loan margins, borrower access and the resilience of Regional Management's lending model?
Regional Management Porter's Five Forces examines the consumer-finance environment through rivalry, supplier power, buyer power, threat of new entrants and threat of substitutes. Supplier power is particularly relevant where lenders rely on debt facilities, securitization markets and other capital providers. Buyer power can include borrowers' ability to compare credit options, while substitutes extend beyond direct lenders to credit cards, bank loans, retailer programs or delayed purchases. New digital lenders and distribution models may change entry barriers, and rivalry can influence acquisition costs and pricing discipline without requiring unsupported force scores.
- Funding pressure. Explore how the availability and terms of capital may shape the economics of originating and holding loans.
- Alternative credit. Compare borrower alternatives and retail financing choices that may reduce demand or increase switching.
- Pressure test. Use the Excel framework to rate evidence and uncertainty for each force, then consult the Word analysis for sector-specific interpretation.
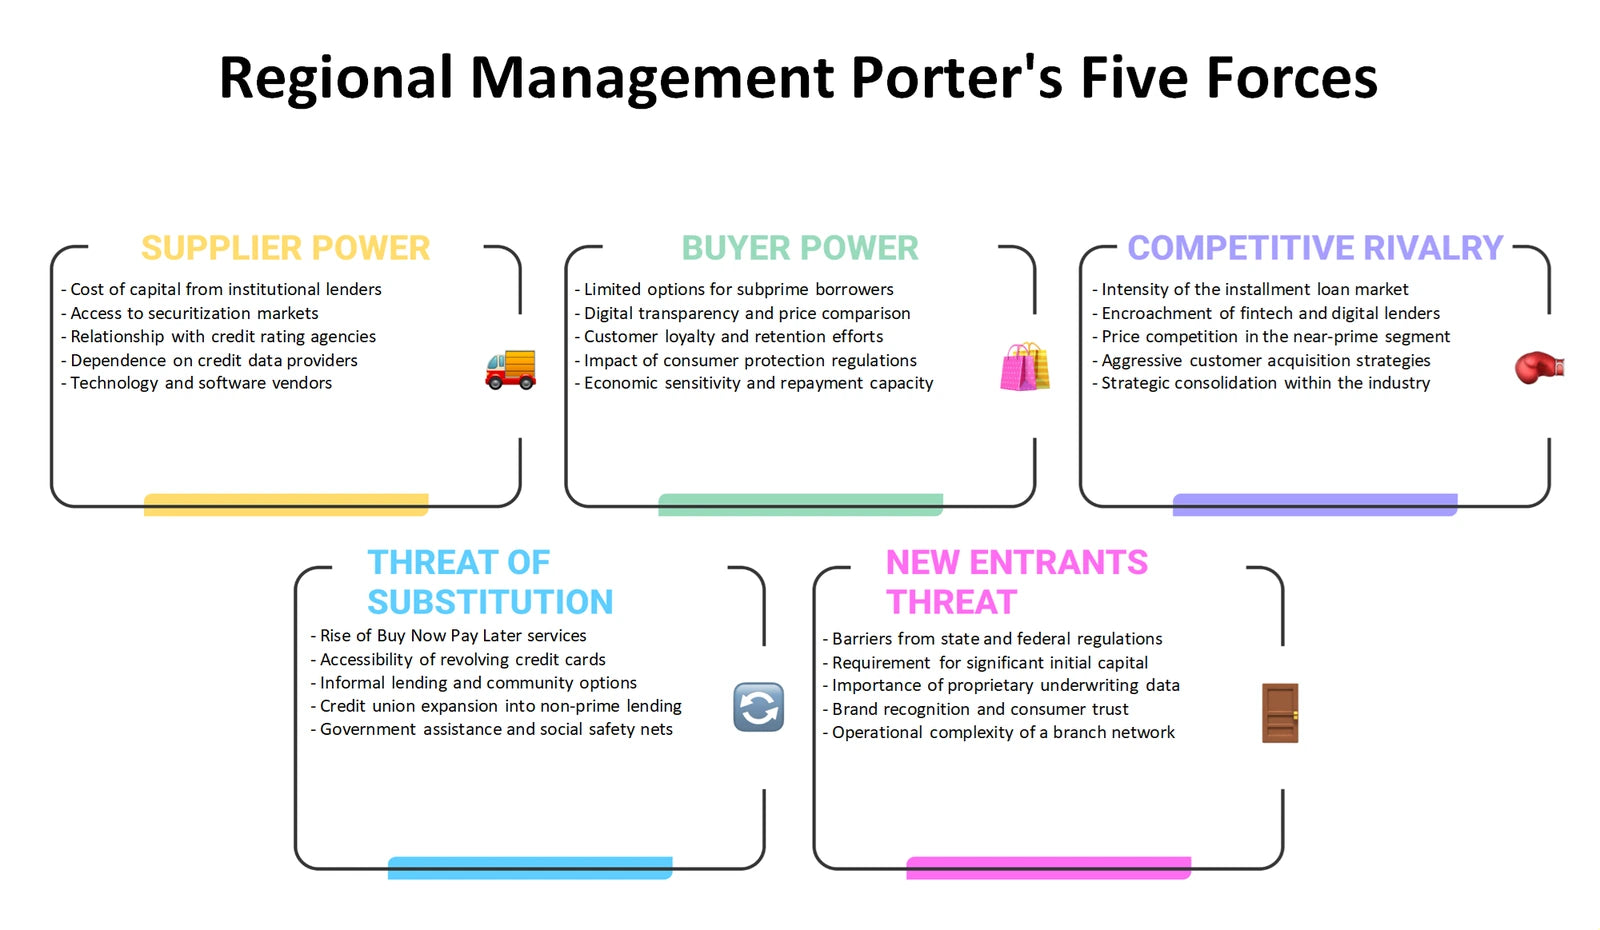
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can lending offers and point-of-sale finance be assessed through Product, Price, Place and Promotion?
A Regional Management Marketing Mix considers Product as the structure and fit of loan or financing offers; Price as the full customer economics and risk-sensitive pricing logic; Place as direct, merchant and other customer-access routes; and Promotion as clear, responsible communication to prospective borrowers. In a regulated credit context, the four Ps are connected rather than separate campaign choices. A convenient checkout finance offer, for example, must be understandable to customers, workable for merchants and aligned with responsible underwriting and servicing. The analysis helps frame these decisions without inventing rates, advertising campaigns or channel shares.
- Offer fit. Assess how different financing needs may call for distinct product features, repayment clarity and customer support.
- Channel quality. Compare direct acquisition with merchant-enabled access in terms of customer relevance, conversion and operational control.
- Go-to-market review. Use the Excel 4Ps structure to compare options, with the Word analysis providing context for interpreting trade-offs in lending communications.
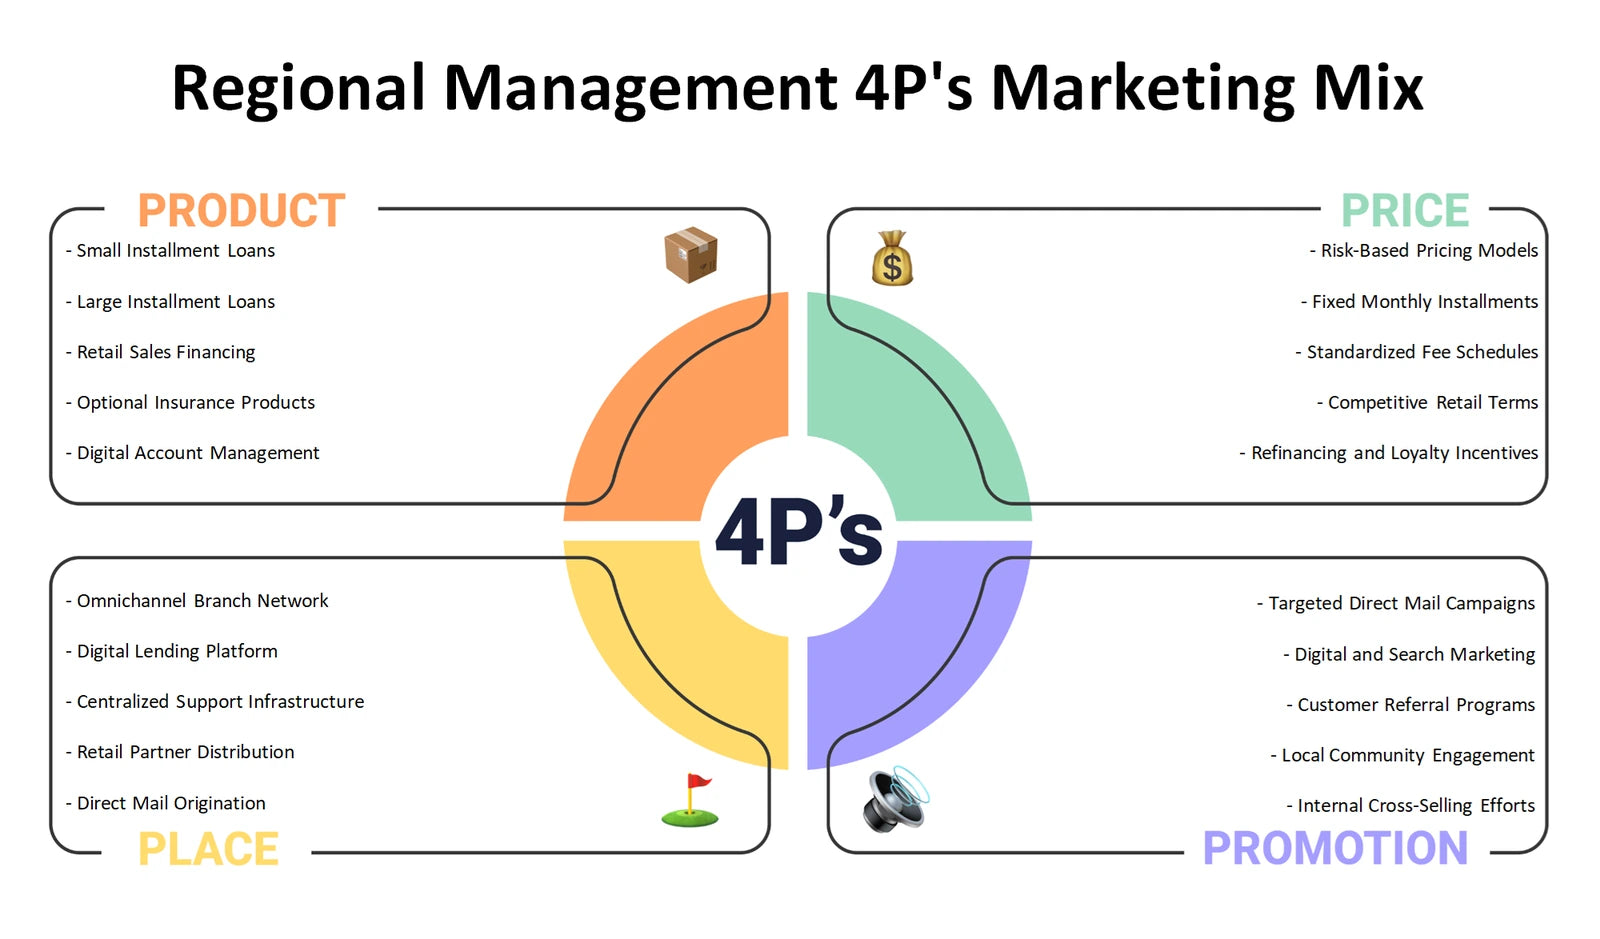
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could alter credit demand, funding conditions, compliance obligations or operating priorities?
Regional Management PESTLE analysis, also known as PESTEL, separates Political, Economic, Social, Technological, Legal and Environmental influences. Political and Legal factors can include policy direction, consumer-credit oversight and disclosure expectations; they should be examined as questions rather than assumed recent changes. Economic conditions may affect borrower demand, repayment capacity and funding costs. Social expectations around fair treatment and financial access can influence trust, while technology affects underwriting data, fraud controls and digital service. Environmental disruption can matter where it affects customers, branches, collateral-linked purchases or operational continuity.
- Macro sensitivity. Identify external variables that could affect both the cost of capital and the credit performance of the loan portfolio.
- Control agenda. Distinguish technology opportunities from legal, privacy, fairness and cybersecurity responsibilities.
- Scenario planning. Organize external signals in the Excel PESTLE framework and use the Word analysis to develop focused discussion prompts for management review.
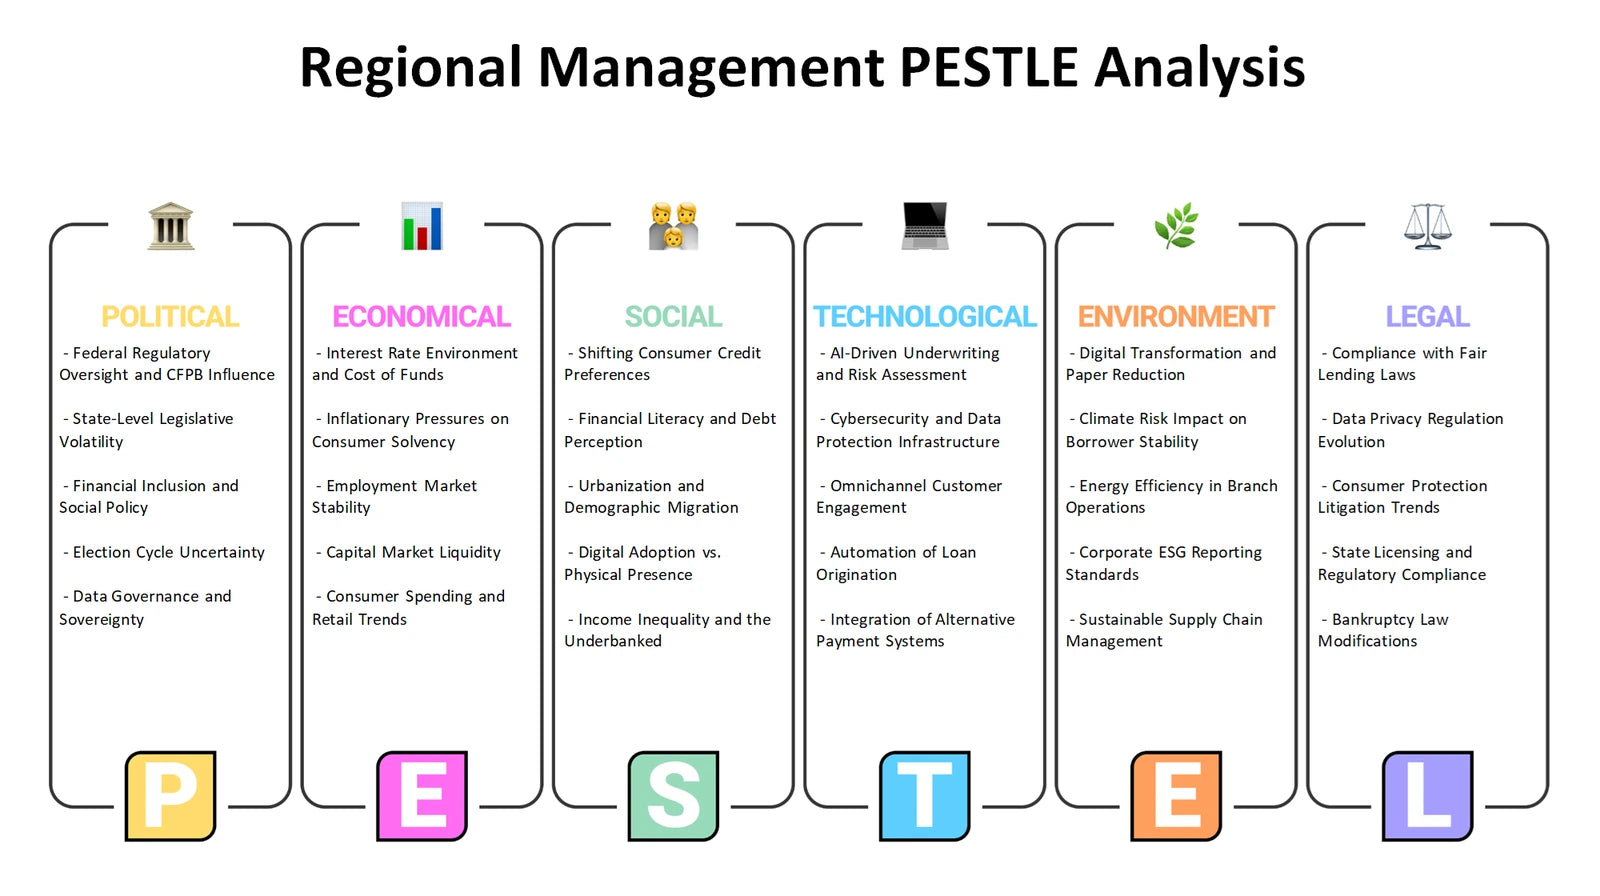
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Regional Management weigh its lending capabilities and constraints against changing market conditions?
A Regional Management SWOT analysis keeps internal and external factors properly separated. Potential Strengths and Weaknesses concern capabilities within the business, such as underwriting processes, funding access, servicing capacity, data use or operational concentration. Opportunities and Threats arise outside the organization, including new customer routes, changes in credit demand, competing finance options, funding-market conditions and regulatory expectations. The framework does not label these themes as proven findings. Instead, it helps users test which capabilities may be meaningful and which external developments may deserve a response.
- Internal reality. Examine whether resources, partnerships and operating processes can support growth while preserving disciplined credit management.
- External fit. Connect market openings and threats to the relevant borrower, merchant, funding and compliance conditions.
- Priority conversion. Capture candidate SWOT factors in Excel, then use the Word analysis to turn the most material intersections into evidence-led strategic questions.
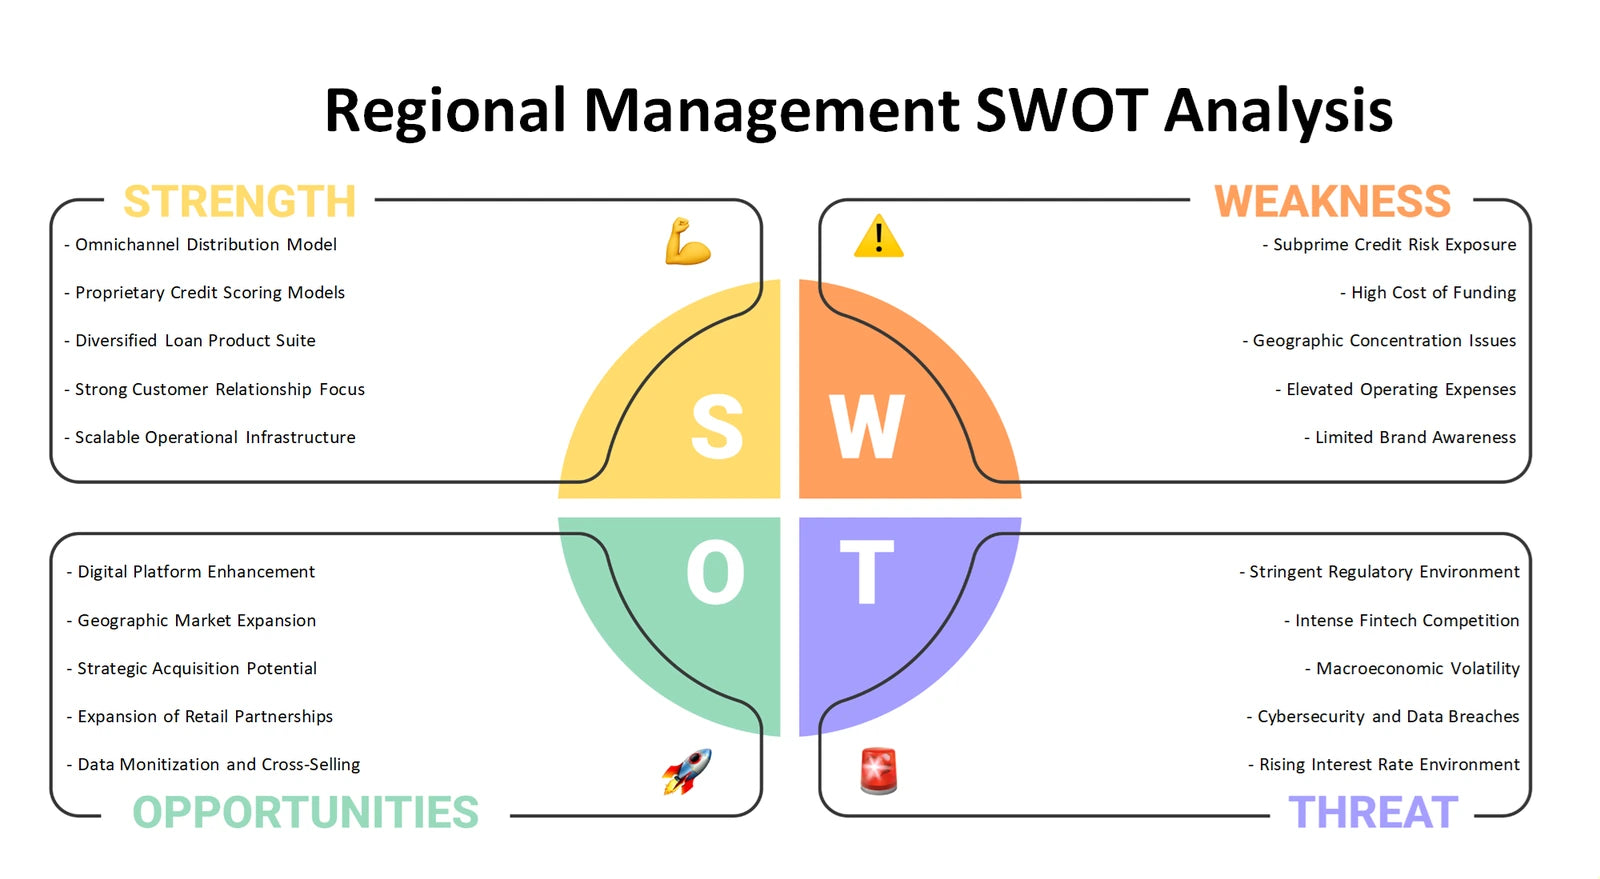
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of the lending business
Used together, the six perspectives move from portfolio priorities and business-model economics to competitive pressure, customer routes, external change and strategic fit. The Excel frameworks help organize comparisons and assumptions, while the detailed Word files support a fuller company-specific discussion of Regional Management's lending, funding and distribution questions.
Company background: Regional Management Corp. — SEC-filed Form 10-Q.