

Radian Group: Insurance Business and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
Radian Group Strategy Analysis Bundle
Radian Group is a United States mortgage insurance company. Its business centres on helping mortgage lenders manage residential credit risk, particularly where borrowers make lower down payments, while balancing underwriting discipline, capital requirements and relationships across the housing-finance ecosystem. This bundle examines the strategic choices behind a regulated risk-management business rather than treating mortgage insurance as a generic consumer insurance product.
In its Form 10-Q filed August 7, 2026, Radian Group Inc reported revenue of USD 574,959,000 and GAAP net income of USD 115,914,000 for April 1 through June 30, 2026. Those figures frame questions about portfolio priorities, risk-transfer capacity and lender value; they provide a dated company snapshot, not evidence that the downloadable files were updated in 2026.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Where should a mortgage insurer direct capital and management attention when housing demand, credit conditions and risk appetite can shift quickly?
The Radian Group BCG Matrix provides a disciplined way to compare portfolio choices through market growth and relative market share. It helps distinguish the criteria used for Stars, Cash Cows, Question Marks and Dogs without assigning any Radian activity to a quadrant or claiming unverified market-share results. For a capital-sensitive insurer, this matters because an attractive growth opportunity can still consume underwriting capacity, regulatory capital and reinsurance protection. The framework supports clearer discussion of which insurance markets, lender relationships or adjacent risk-management opportunities merit further investigation.
- Growth versus position. Compare the pace of opportunity in relevant mortgage-insurance markets with the company’s relative competitive position rather than relying on volume alone.
- Capital priorities. Test whether a potential investment case can justify the risk capacity and operating attention it may require across the underwriting cycle.
- Portfolio working view. Use the Excel matrix to organise possible portfolio items, then use the Word analysis to interpret the assumptions and decision questions behind each placement.
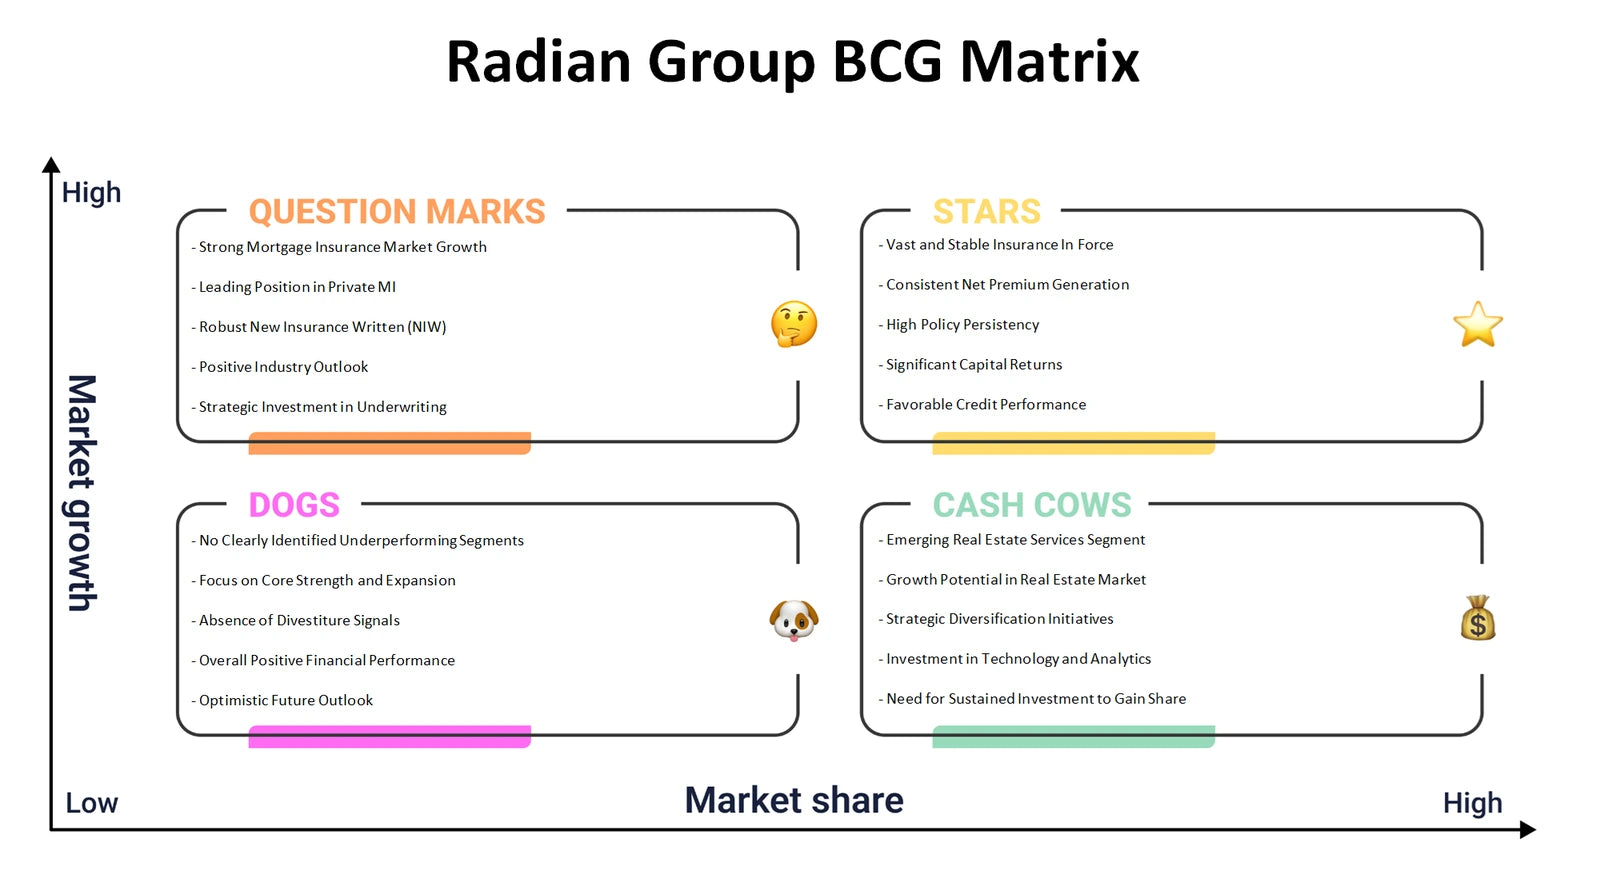
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do lender needs, underwriting economics and risk-transfer relationships connect to the way Radian Group creates and captures value?
The Radian Group Business Model Canvas maps the full operating logic of a mortgage insurance business. It considers customer segments, value propositions, channels and customer relationships alongside revenue streams, key resources, key activities, key partnerships and cost structure. This is useful because mortgage insurance economics depend on more than policy revenue: underwriting expertise, data, capital, claims capability, lender distribution and risk transfer must work together. The canvas helps examine how service to lending partners is connected to the financial and operational resources needed to support insurance obligations over time.
- Value chain connections. Trace how lender-facing risk protection and underwriting support depend on processes, specialist capabilities and trusted counterparties.
- Economic logic. Explore the relationship between insurance revenue streams, claims exposure, operating costs and the capital resources required to write business responsibly.
- Model mapping. Populate and compare the nine Excel building blocks while using the Word analysis to add company-specific context to the links between them.
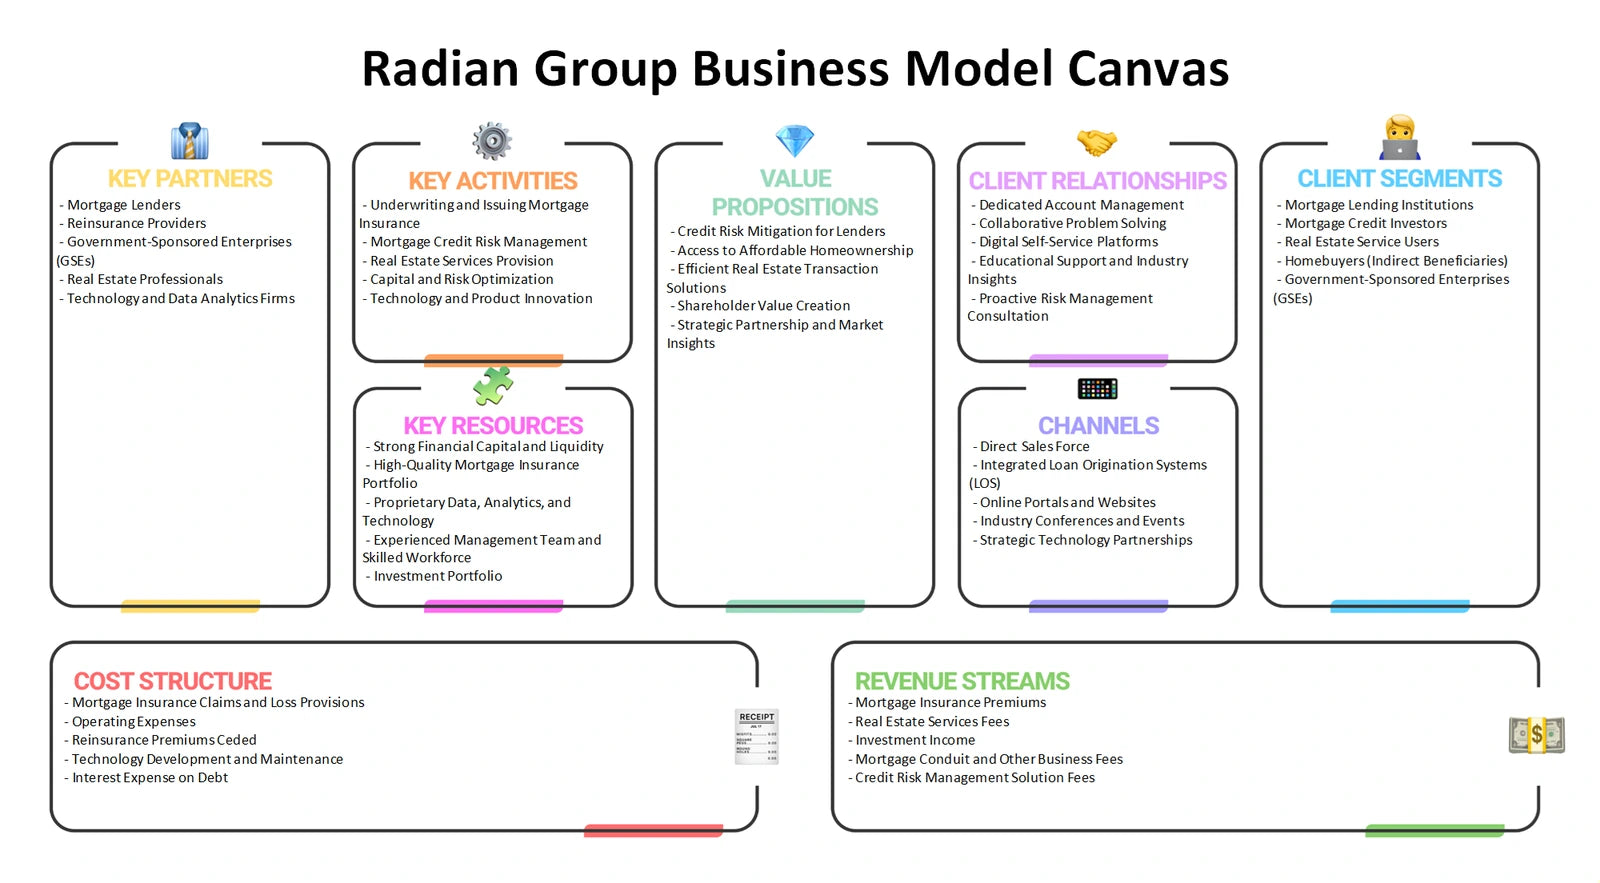
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
Which industry pressures most affect the durability of mortgage-insurance economics and bargaining power with lending partners?
Radian Group Porter's Five Forces analysis examines rivalry among mortgage insurers, buyer power among lenders and loan-originator channels, and supplier power among the providers of capital, data, technology and risk-transfer capacity. It also considers the threat of new entrants in a regulated insurance market and the threat of substitutes, such as other ways lenders, borrowers or housing-finance participants may address credit-risk needs. The lens does not assign force scores or name competitors; instead, it clarifies why pricing discipline, service quality, approval processes and capital strength may influence industry attractiveness.
- Lender leverage. Assess how concentration, procurement choices and switching considerations could shape the negotiating position of mortgage-lending customers.
- Capacity dependence. Examine how access to reinsurance, structured risk transfer and other capital sources can affect flexibility during changing credit conditions.
- Pressure comparison. Use the Excel framework to record evidence and assumptions for all five forces, with the Word analysis supplying context for their possible strategic implications.
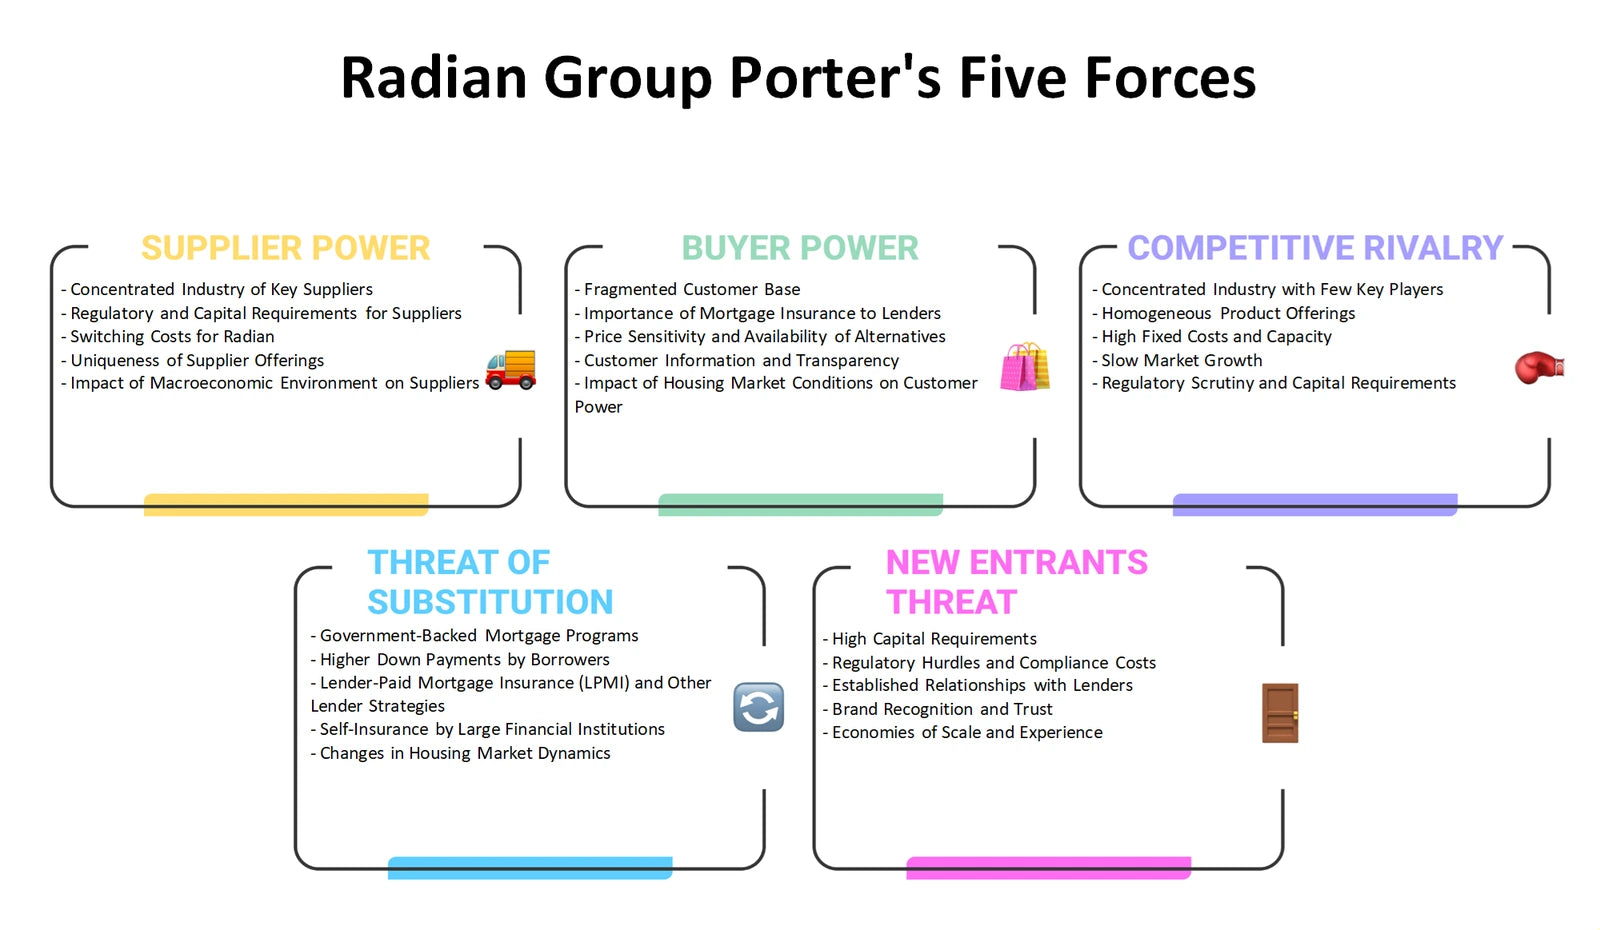
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a business-to-business mortgage insurer align its offering, premium logic, lender access and market communication?
The Radian Group Marketing Mix applies Product, Price, Place and Promotion to a regulated mortgage-insurance context. Product analysis focuses on the protection, underwriting support and risk-management service a lender may evaluate. Price considers premium design and risk-based economics without inventing actual rates. Place examines the practical routes through which mortgage insurance reaches lenders and loan-origination workflows, while Promotion addresses how expertise, reliability and product understanding can be communicated to professional decision-makers. Together, the 4Ps help connect commercial positioning with the realities of credit risk and compliance.
- Product relevance. Examine how insurance protection, underwriting processes and lender support can be framed around the needs of residential mortgage originators.
- Commercial fit. Compare pricing and distribution questions with the need to preserve disciplined risk selection and sustainable underwriting economics.
- Go-to-market review. Use the Excel 4Ps layout to capture options and trade-offs, then consult the Word analysis for detailed prompts tailored to the mortgage-insurance model.
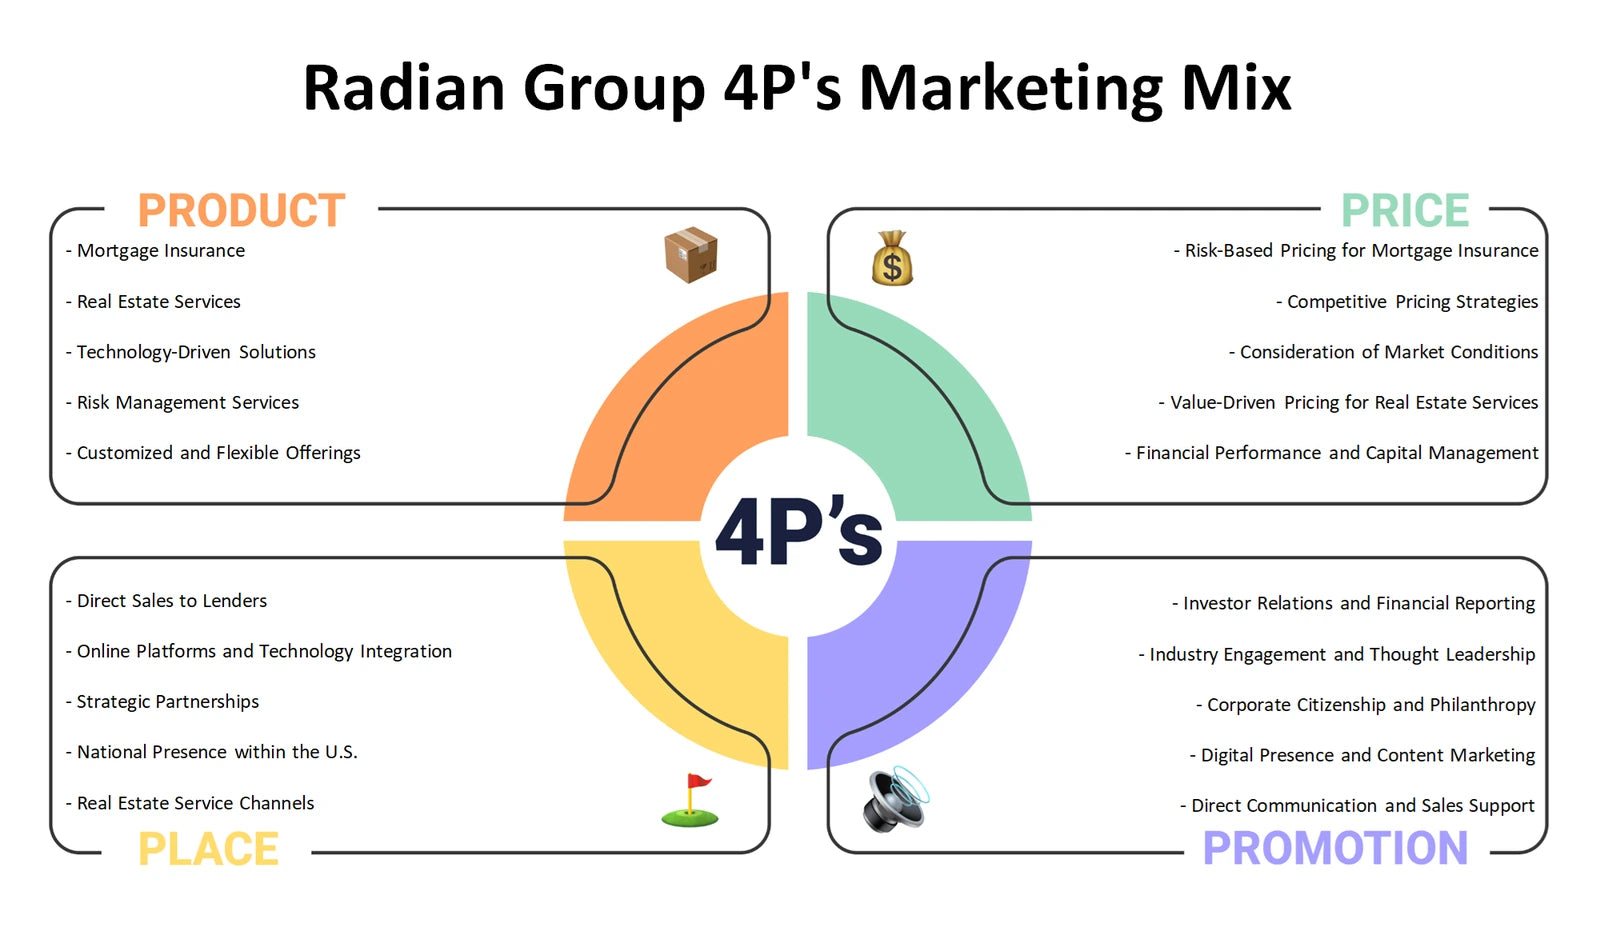
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could reshape the United States housing-finance environment in which Radian Group underwrites mortgage credit risk?
The Radian Group PESTLE analysis, also commonly called PESTEL, separates Political, Economic, Social, Technological, Legal and Environmental influences. For a mortgage insurer, policy and housing-finance oversight can affect operating assumptions; economic conditions can influence borrower affordability and credit performance; and social trends may alter household formation and homeownership demand. Technology raises questions around underwriting data and operational efficiency, while legal obligations and environmental exposure may affect housing markets, claims conditions or risk governance. The framework distinguishes these analytical questions from claims that a particular law, rate or policy change has already occurred.
- Housing-cycle exposure. Identify external economic and social factors that may influence mortgage origination conditions and the quality of insured credit risk.
- Regulatory horizon. Organise political and legal issues that warrant monitoring because mortgage insurance operates within a closely supervised financial system.
- Environmental scan. Use the Excel categories to prioritise external signals, then use the Word analysis to develop notes on relevance, uncertainty and possible response areas.
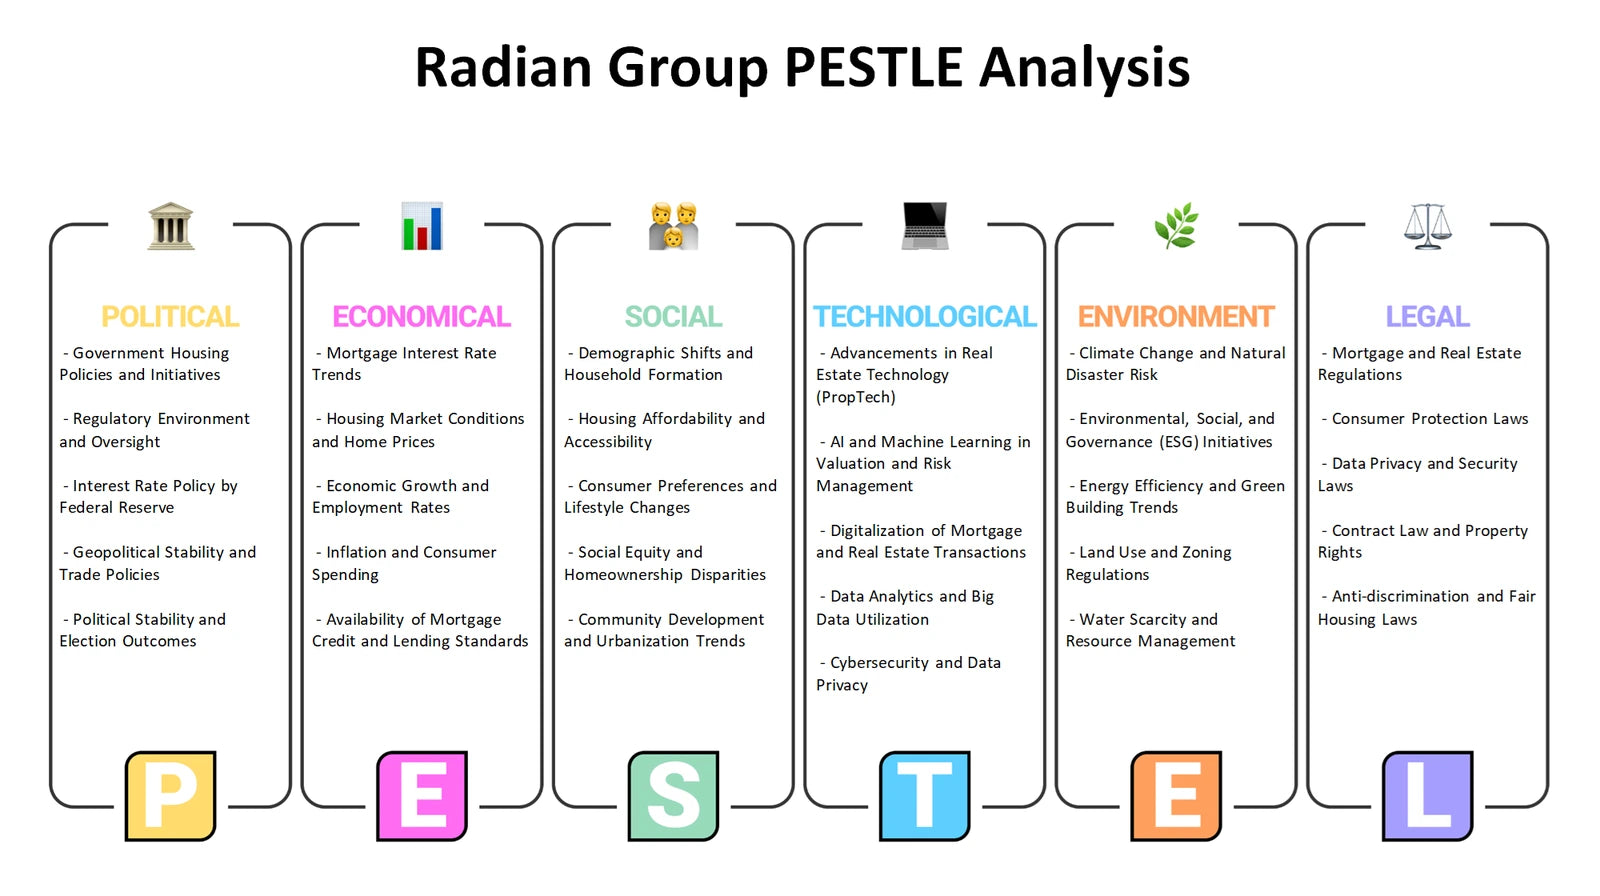
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Radian Group distinguish its internal capabilities and constraints from the external conditions that shape mortgage-insurance choices?
The Radian Group SWOT analysis separates internal Strengths and Weaknesses from external Opportunities and Threats. It provides a useful synthesis after the other frameworks: underwriting knowledge, capital management, lender relationships, operating systems and risk-transfer expertise can be examined as potential internal considerations, while housing-market conditions, regulation, technology shifts and industry competition sit outside the company. These are topics to assess rather than established findings. Keeping the categories separate prevents a market event from being mistaken for a company capability, and turns a broad strategic conversation into an actionable set of questions.
- Internal readiness. Evaluate which capabilities, resources or operating limitations may affect the company’s ability to pursue a chosen mortgage-insurance opportunity.
- External exposure. Contrast market openings with threats such as adverse credit conditions, changing lender demand or shifts in the housing-finance landscape.
- Actionable synthesis. Use the Excel SWOT grid to connect observations across the bundle, while the Word analysis helps explain why each item belongs inside or outside the business.
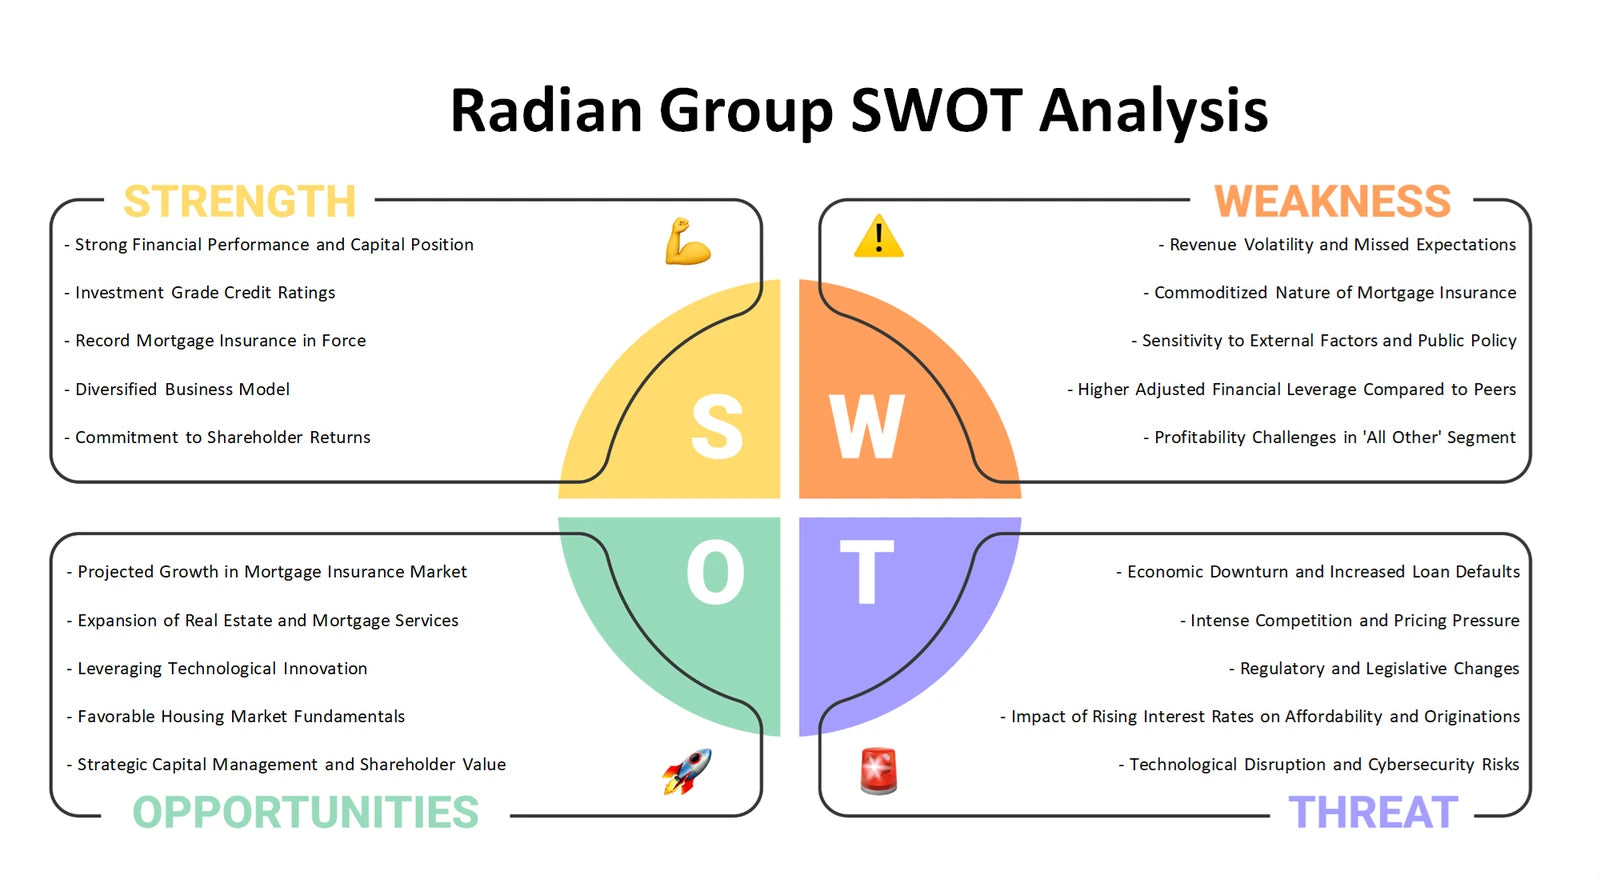
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a more connected view of mortgage-insurance strategy
Used together, the six perspectives help connect Radian Group’s portfolio choices with its business model, competitive pressures, lender-facing commercial approach, external housing-finance environment and internal strategic position. The Excel frameworks provide a clear structure for comparing issues and recording assumptions, while the detailed Word analyses support fuller interpretation of the trade-offs involved in capital-sensitive mortgage insurance.
Company background: Radian Group — Wikidata company profile.