

Grupa PZU: Six Analyses of Underwriting and Digital Investment

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Grupa PZU Strategy Analysis Bundle
Grupa PZU is considered here as the Polish insurance group described in the supplied business context, with life, property and casualty, and health-related insurance activities. Its relationship with policyholders depends on underwriting discipline, claims and benefits administration, distribution, risk protection and long-term customer confidence. The business context also highlights reinsurance, preferred-provider arrangements and technology partners as relevant parts of how insurance value is delivered and risk is managed.
For Grupa PZU, strategic questions extend beyond selling policies: which activities deserve capital, how should product and channel choices fit customer needs, and where can operating resilience protect portfolio quality? The six connected frameworks help examine these questions from portfolio, business-model, competitive, marketing, external-environment and capability perspectives. They are analytical tools for assessing choices, not statements of pre-set company findings or investment recommendations.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance activities should receive attention, investment or tighter resource discipline when growth prospects and relative market share differ?
A Grupa PZU BCG Matrix helps organise a multi-line insurance portfolio around two analytical criteria: market growth and relative market share. Rather than assuming that any product line belongs in a particular quadrant, it provides a disciplined way to compare mature protection needs with faster-changing opportunities in areas such as health, digital service or evolving risk coverage. Stars, Cash Cows, Question Marks and Dogs are useful portfolio categories because they encourage separate questions about cash generation, scale, growth investment and selective rationalisation. For an insurer, those choices may affect underwriting capacity, service investment, distribution effort and the level of management attention assigned to each activity.
- Portfolio comparison. Review insurance lines or customer propositions against relative market share and market-growth evidence instead of relying only on premium volume or familiarity.
- Capital priorities. Consider whether established activities can support investment in emerging areas while preserving risk selection and claims-service quality.
- Structured review. Use the Excel framework to map and compare candidate activities, then use the Word analysis to interpret the assumptions and portfolio trade-offs behind the matrix.
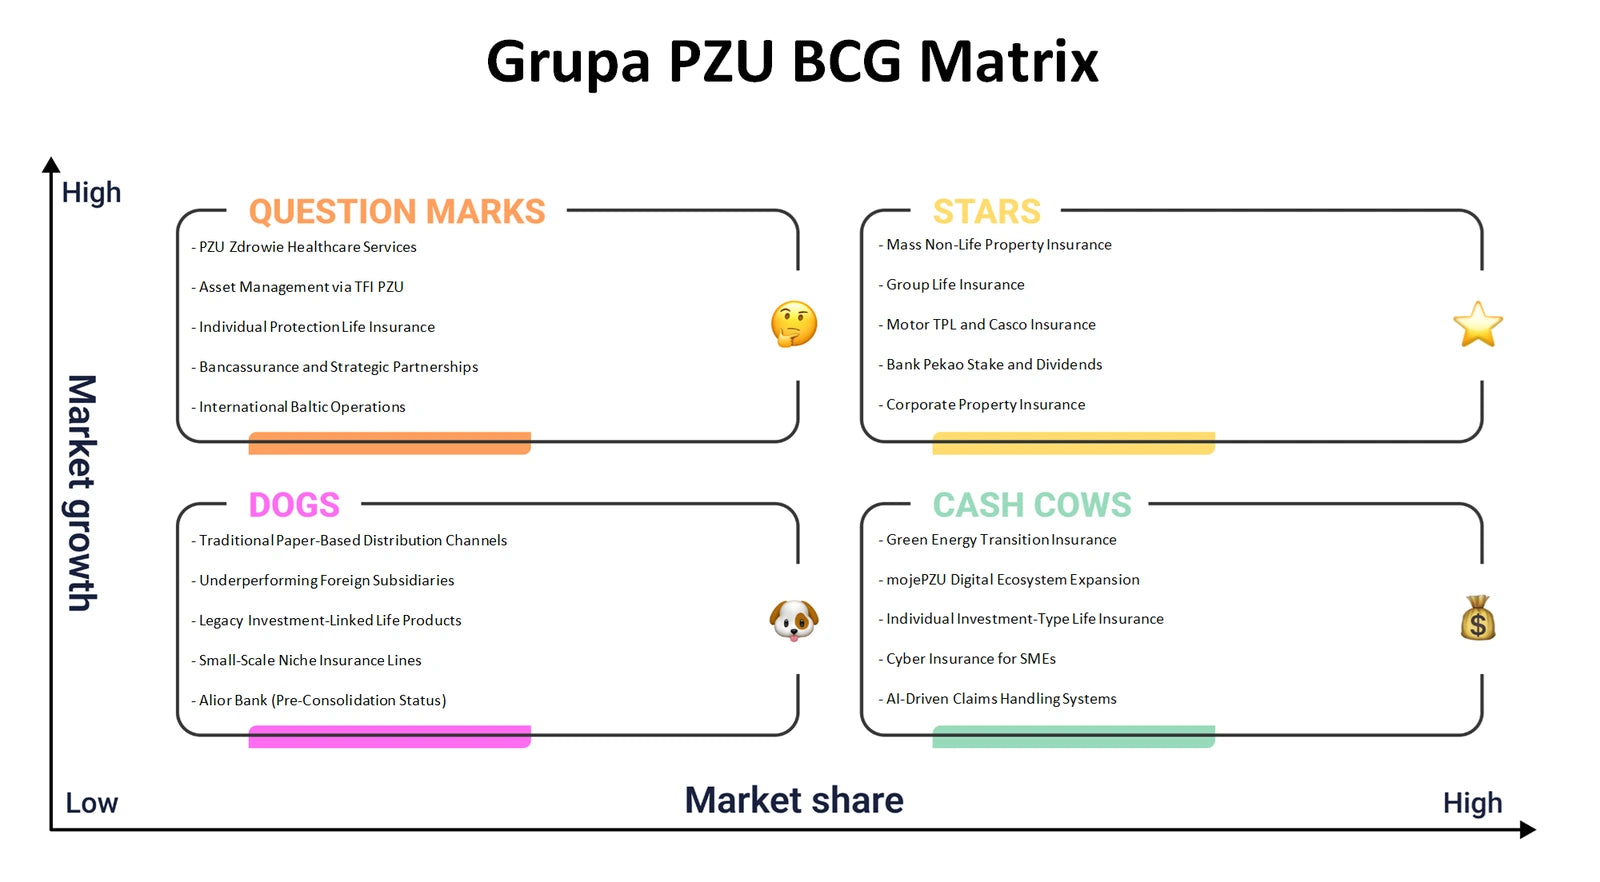
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer needs, risk protection, distribution, claims operations and insurance economics connect across Grupa PZU’s business model?
The Grupa PZU Business Model Canvas examines how an insurer creates and captures value across all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. It helps connect policyholders’ need for protection and dependable service with premium-based revenue, underwriting expertise, capital, data, claims handling and distribution relationships. The supplied business context makes technology vendors, cybersecurity specialists, provider networks and reinsurance arrangements particularly relevant topics to examine as partnerships supporting operating capability and risk control. Cost structure can be considered through claims and benefits, administration, distribution, technology and risk-transfer needs, rather than treated as a generic expense list.
- Value chain links. Trace how insurance propositions, customer service, pricing, underwriting and claims processes reinforce or constrain one another.
- Operating economics. Examine the relationship between premium income, claims and benefits, partner arrangements, technology spending and reinsurance protection.
- Model building. Complete the Excel Canvas block by block, using the Word analysis to add company-specific context and test whether the nine elements fit together coherently.
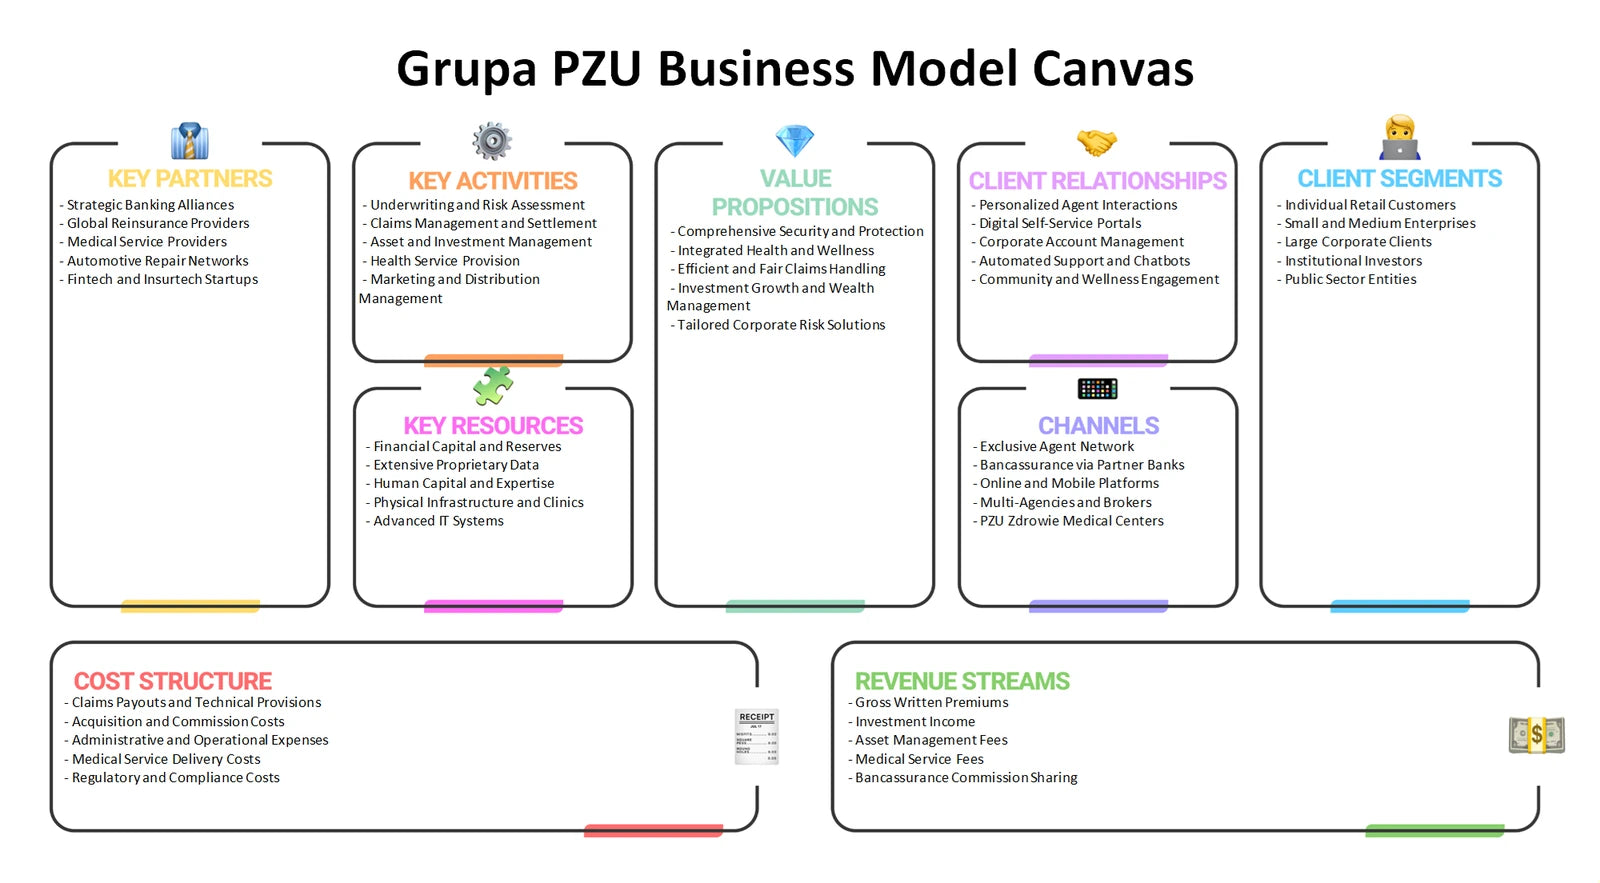
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
Which industry pressures can influence insurance margins, customer retention and the cost of delivering protection?
Grupa PZU Porter's Five Forces provides a way to assess the competitive environment around insurance without reducing competition to a list of named rivals. Rivalry can be examined through product differentiation, service quality, distribution reach and pressure on underwriting and pricing discipline. Buyer power matters because retail and business customers may compare coverage, price, claims experience and convenience. Supplier power is relevant where insurers depend on medical providers, repair networks, technology vendors, data services or specialist expertise. The threat of new entrants includes digital insurers and insurtech-enabled propositions, while substitutes include self-insurance, employer benefit alternatives, savings products or other ways customers may manage financial risk.
- Industry pressure. Compare where market competition may affect premiums, service expectations or the cost of claims-related and technology inputs.
- Alternative protection. Distinguish direct insurance competition from substitute solutions that address customer risk needs in different ways.
- Evidence-led assessment. Use the Excel framework to record force-by-force observations and the Word analysis to explain why each pressure may matter for the group’s operating model.
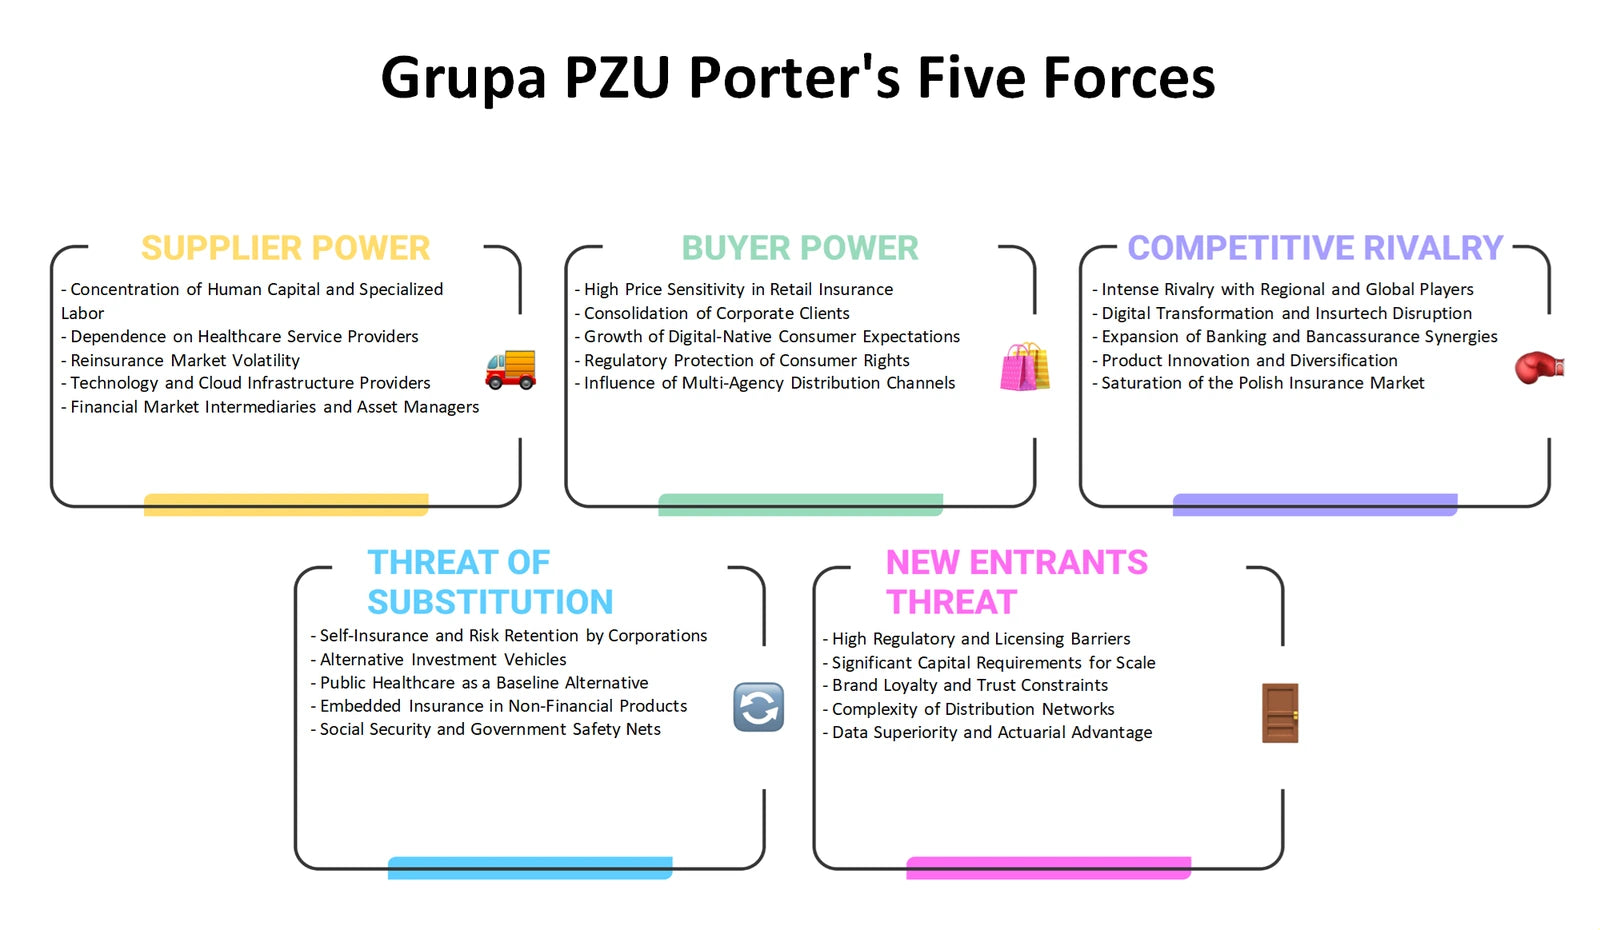
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can Product, Price, Place and Promotion be examined together for insurance customers who need understandable cover and dependable service?
A Grupa PZU Marketing Mix considers the 4Ps in a regulated service context. Product concerns the design and clarity of life, property and casualty, health or related protection propositions, including the customer experience surrounding policies and claims. Price is not simply a promotional lever: insurance pricing must reflect risk selection, exposure limits, expected claims costs and the value customers perceive. Place addresses how customers access policies and support through direct, intermediary, partner or digital routes. Promotion can be assessed through trust-building communication, explanation of coverage and responsible customer education, rather than assumed campaign claims. The framework helps reveal whether the four decisions support the same customer promise.
- Offer design. Compare customer needs with policy features, service expectations and the clarity of exclusions or coverage conditions.
- Channel fit. Examine how digital access, intermediated distribution and service touchpoints may serve different customer situations.
- Planning application. Use the Excel 4Ps structure to organise proposition and channel questions, then refer to the Word analysis for the insurance-specific reasoning behind each choice.
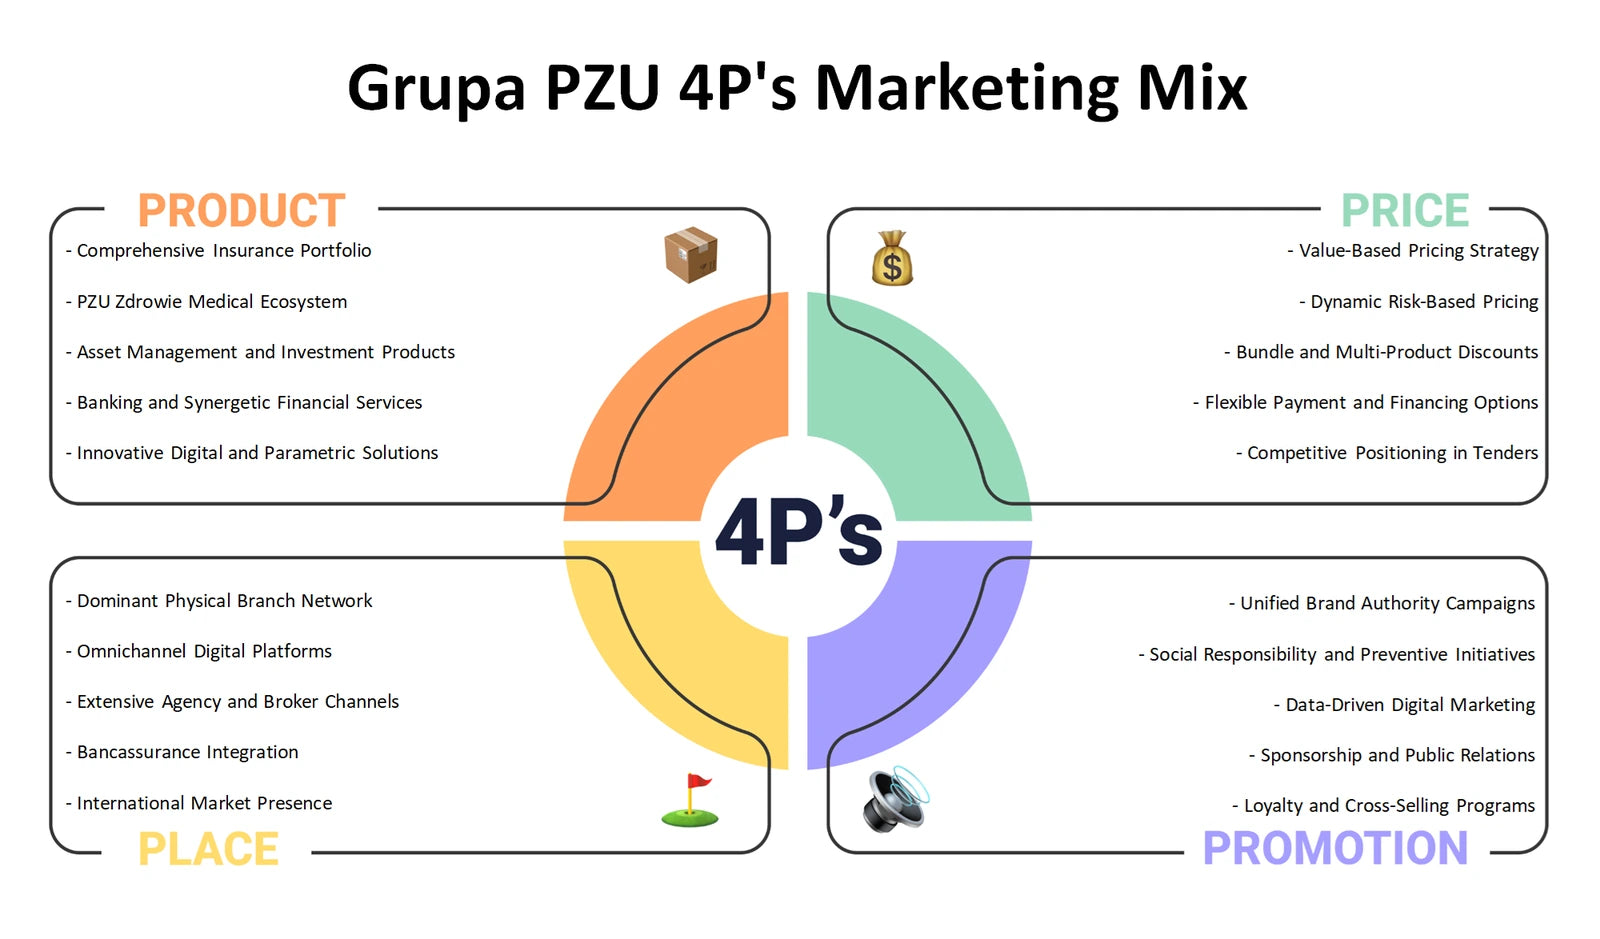
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should be monitored because they can reshape insurance demand, risk exposure, compliance needs and operating costs?
The Grupa PZU PESTLE analysis, also commonly called PESTEL, separates six external lenses that can otherwise become mixed together. Political factors can include public-policy direction and the role of insurance in wider social protection. Economic conditions may influence household affordability, business activity, claims inflation and investment conditions. Social change can affect demographics, health expectations and appetite for protection. Technological developments are relevant to digital service, analytics, automated processing and cyber risk. Legal factors include the regulated obligations surrounding insurance, customer treatment, data and capital. Environmental conditions can alter property-risk patterns, claims severity and the importance of resilience planning. These are questions for analysis, not claims that a particular change has already occurred.
- External signals. Separate macroeconomic, regulatory, social and technological drivers so that their different effects on insurance are not conflated.
- Risk transmission. Consider how environmental exposure or cyber developments could move through underwriting, claims, pricing and customer expectations.
- Monitoring tool. Use the Excel framework to maintain a six-factor issue register and the Word analysis to connect each external factor to relevant strategic questions.
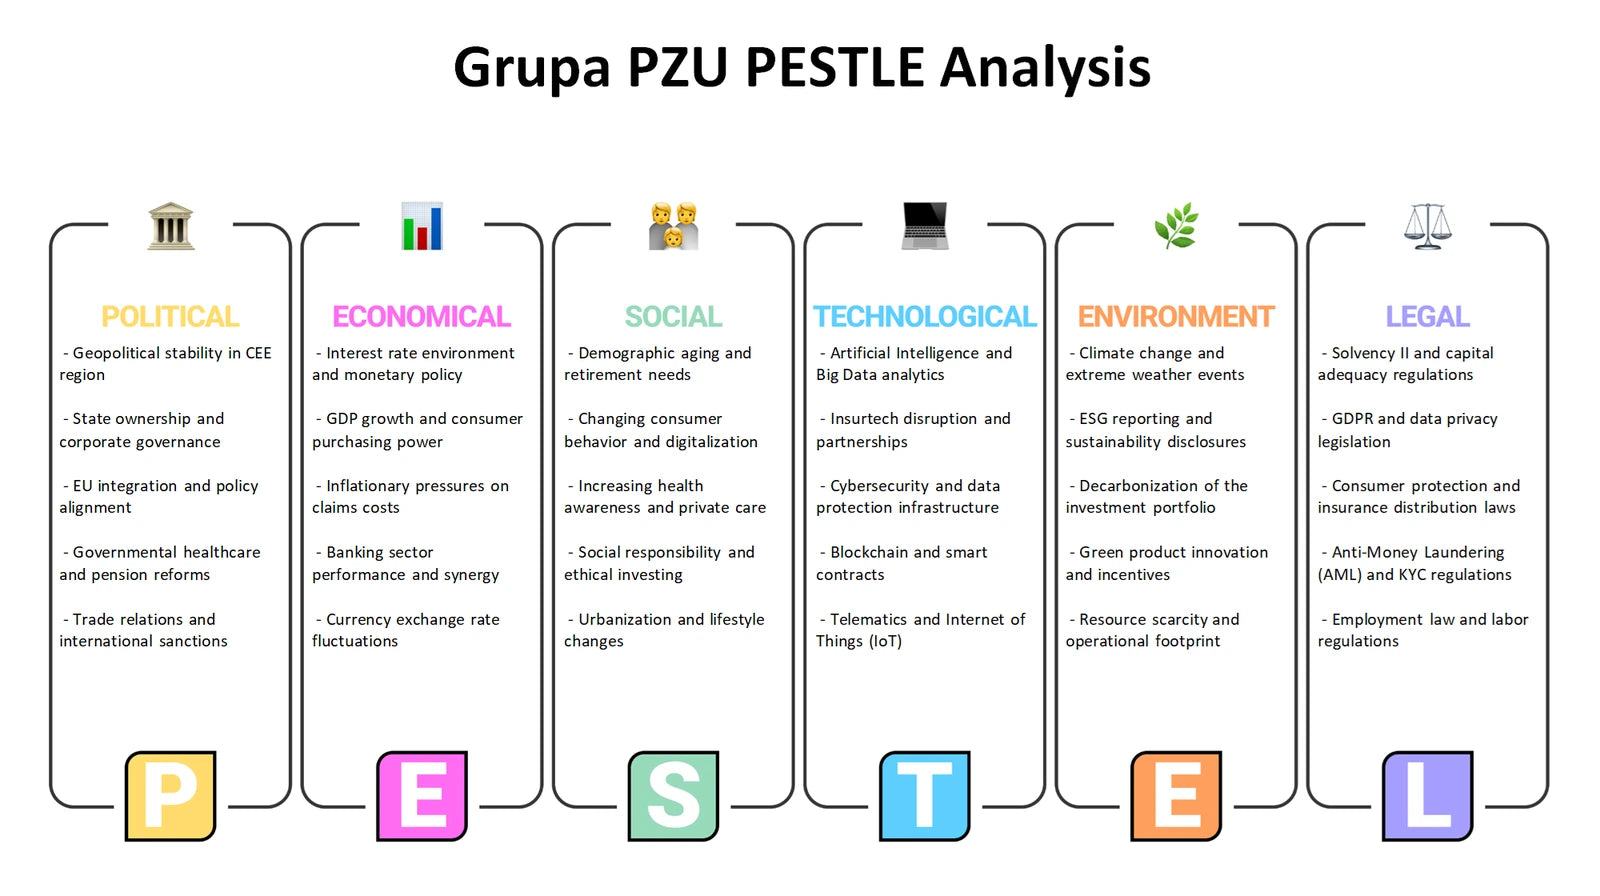
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Grupa PZU distinguish internal capabilities and constraints from external opportunities and threats before setting priorities?
A Grupa PZU SWOT analysis brings together the evidence and questions raised by the other frameworks while keeping internal and external factors correctly separated. Strengths and weaknesses concern controllable or organisation-specific capabilities, such as underwriting expertise, customer relationships, claims operations, technology integration, partner management or possible process constraints. Opportunities and threats arise outside the organisation, including changing protection needs, digital expectations, economic uncertainty, competitive alternatives, regulation and shifting risk patterns. The supplied context suggests useful themes to examine, including modular product architecture, API-enabled processing, cybersecurity support, claims-cost management and reinsurance for tail risk. These topics should be evaluated as analytical considerations, not presented as established strengths, weaknesses or conclusions without supporting evidence.
- Internal versus external. Classify operating capabilities and limitations separately from market conditions, regulatory developments and changing customer needs.
- Strategic fit. Test whether potential opportunities are supported by the resources, partnerships and risk controls needed to pursue them responsibly.
- Decision synthesis. Use the Excel SWOT grid to prioritise observations, then use the Word analysis to develop reasoned links between capability, exposure and strategic response.
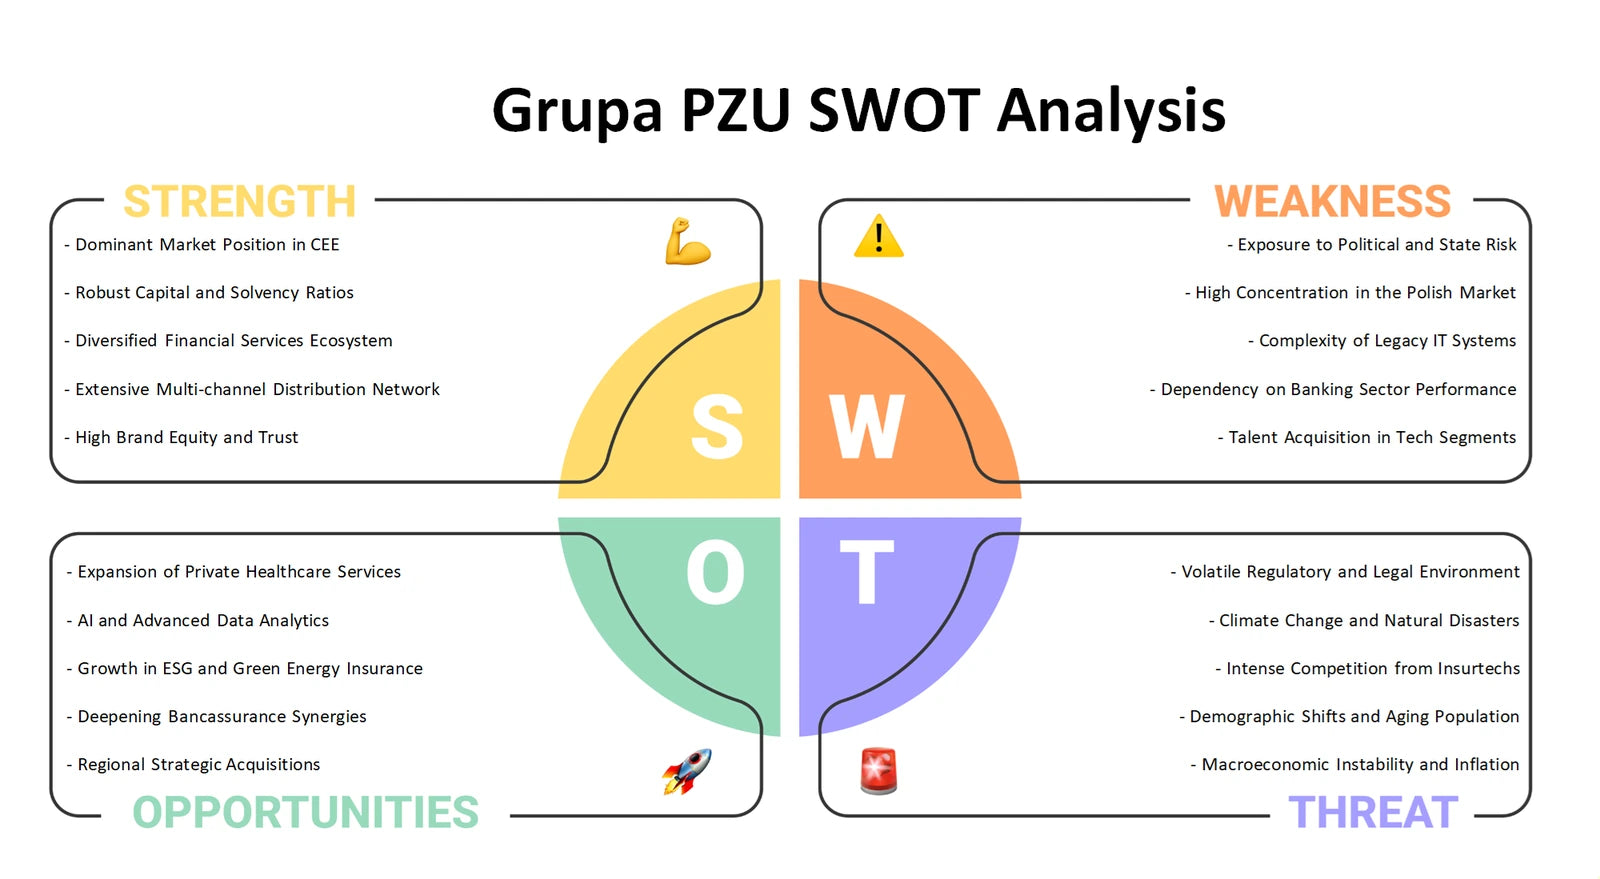
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices with insurance economics and risk
Together, the six perspectives help develop a more rounded view of Grupa PZU: BCG Matrix considers portfolio priorities; the Business Model Canvas links value creation to operating economics; Five Forces and PESTLE assess outside pressure; Marketing Mix examines customer-facing choices; and SWOT consolidates internal and external considerations. The Excel frameworks provide a structured place to organise comparisons and questions, while the detailed Word files support fuller company-specific interpretation.
Company background: Grupa PZU — supplied business-model context.