

ProAssurance: Insurance Business and Sourcing – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
ProAssurance Strategy Analysis Bundle
ProAssurance is a property and casualty insurance business focused on medical professional liability, legal professional liability and workers’ compensation insurance. Its role in helping professional and organizational policyholders manage liability exposure makes underwriting discipline, claims management, distribution access and risk selection central strategic topics.
For the quarter ended March 31, 2026, ProAssurance Corporation’s Form 10-Q filed May 5, 2026 reported revenue of USD 262.634 million and GAAP net income of USD 8.461 million. These quarterly figures help frame questions about portfolio priorities, the economics of specialist insurance distribution and the external pressures that can affect claims costs. They do not indicate that the downloadable analysis files were updated in 2026.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance offerings merit additional underwriting attention when market growth and relative market share point in different directions?
The ProAssurance BCG Matrix provides a disciplined way to compare parts of an insurance portfolio using market growth and relative market share. It applies the familiar Stars, Cash Cows, Question Marks and Dogs categories as analytical criteria, rather than assigning any ProAssurance offering to a quadrant without evidence. For specialist liability and workers’ compensation lines, the useful issue is how premium opportunity, claims volatility, capacity needs and distribution support may affect resource priorities.
- Portfolio comparison. Examine medical, legal and workplace-related coverage opportunities against the growth and share measures that the matrix requires.
- Capital discipline. Consider where underwriting capacity, claims capability or marketing effort may deserve review before resources are spread too widely.
- Structured review. Use the Excel framework to organize portfolio inputs, then use the Word analysis to interpret the strategic questions behind each category.
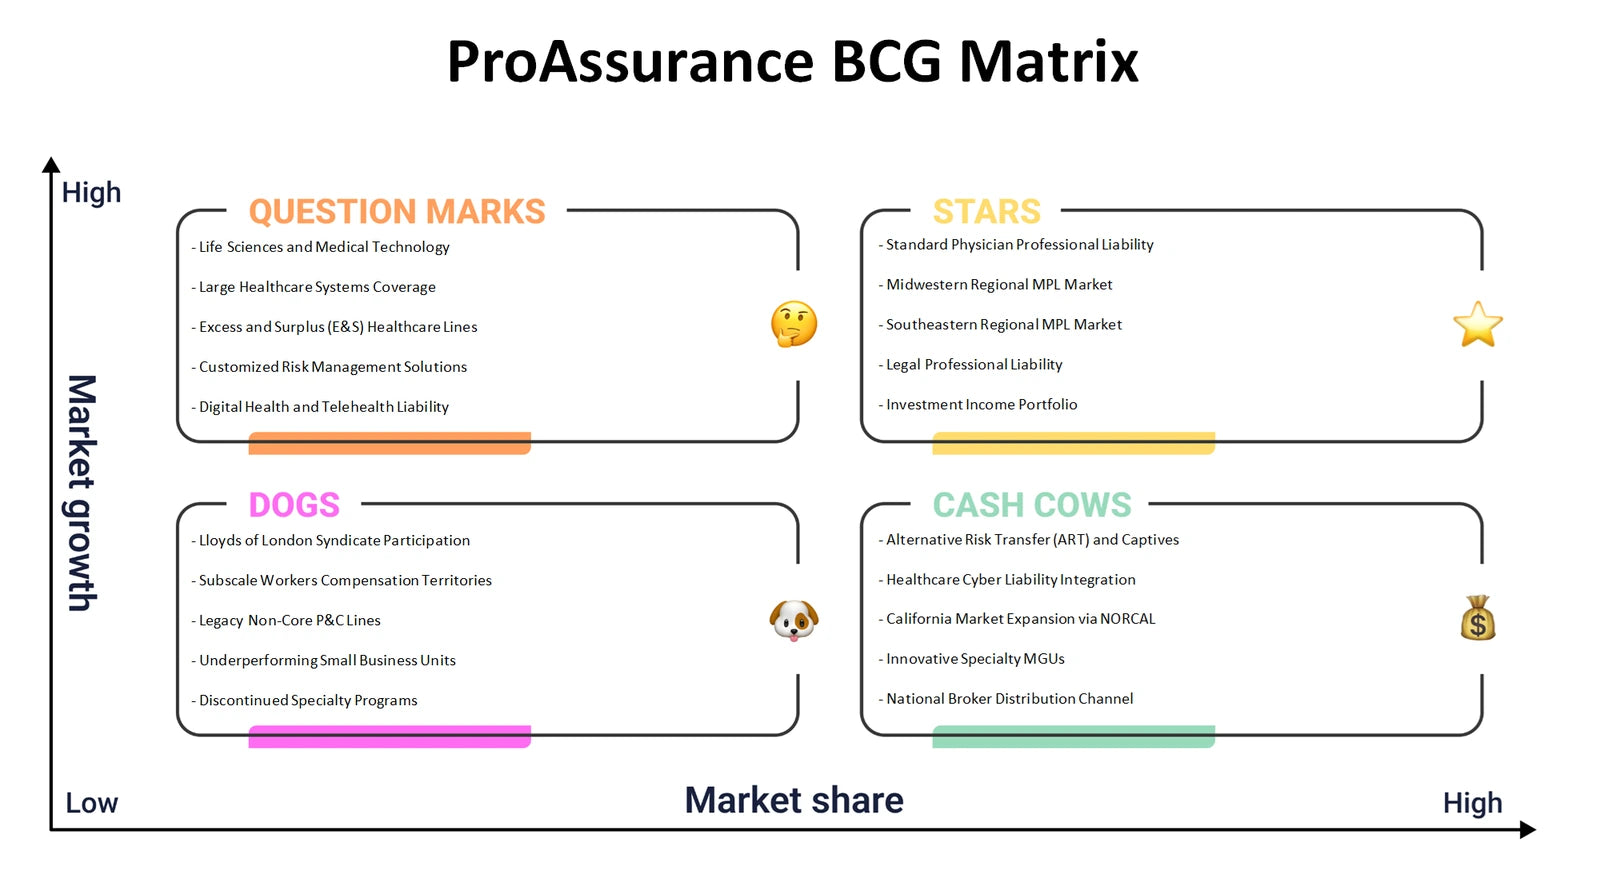
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do specialist insurance coverage, trusted access to professional customers and claims expertise fit together economically?
The ProAssurance Business Model Canvas connects customer segments and value propositions with channels, customer relationships and revenue streams. It also considers the key resources, key activities, key partnerships and cost structure needed to deliver insurance protection consistently. This is particularly useful where professional associations, distribution relationships, underwriting knowledge and specialist claims support may influence both customer relevance and operating economics. The canvas helps turn a collection of insurance activities into a connected model that can be questioned, compared and refined.
- Customer logic. Map the different needs of medical professionals, legal professionals and employers seeking workers’ compensation protection.
- Delivery system. Explore how underwriting, policy servicing, claims handling and partner relationships reinforce the proposed customer value.
- Model mapping. Populate the Excel blocks systematically and use the Word analysis to connect assumptions across revenue, resources and costs.
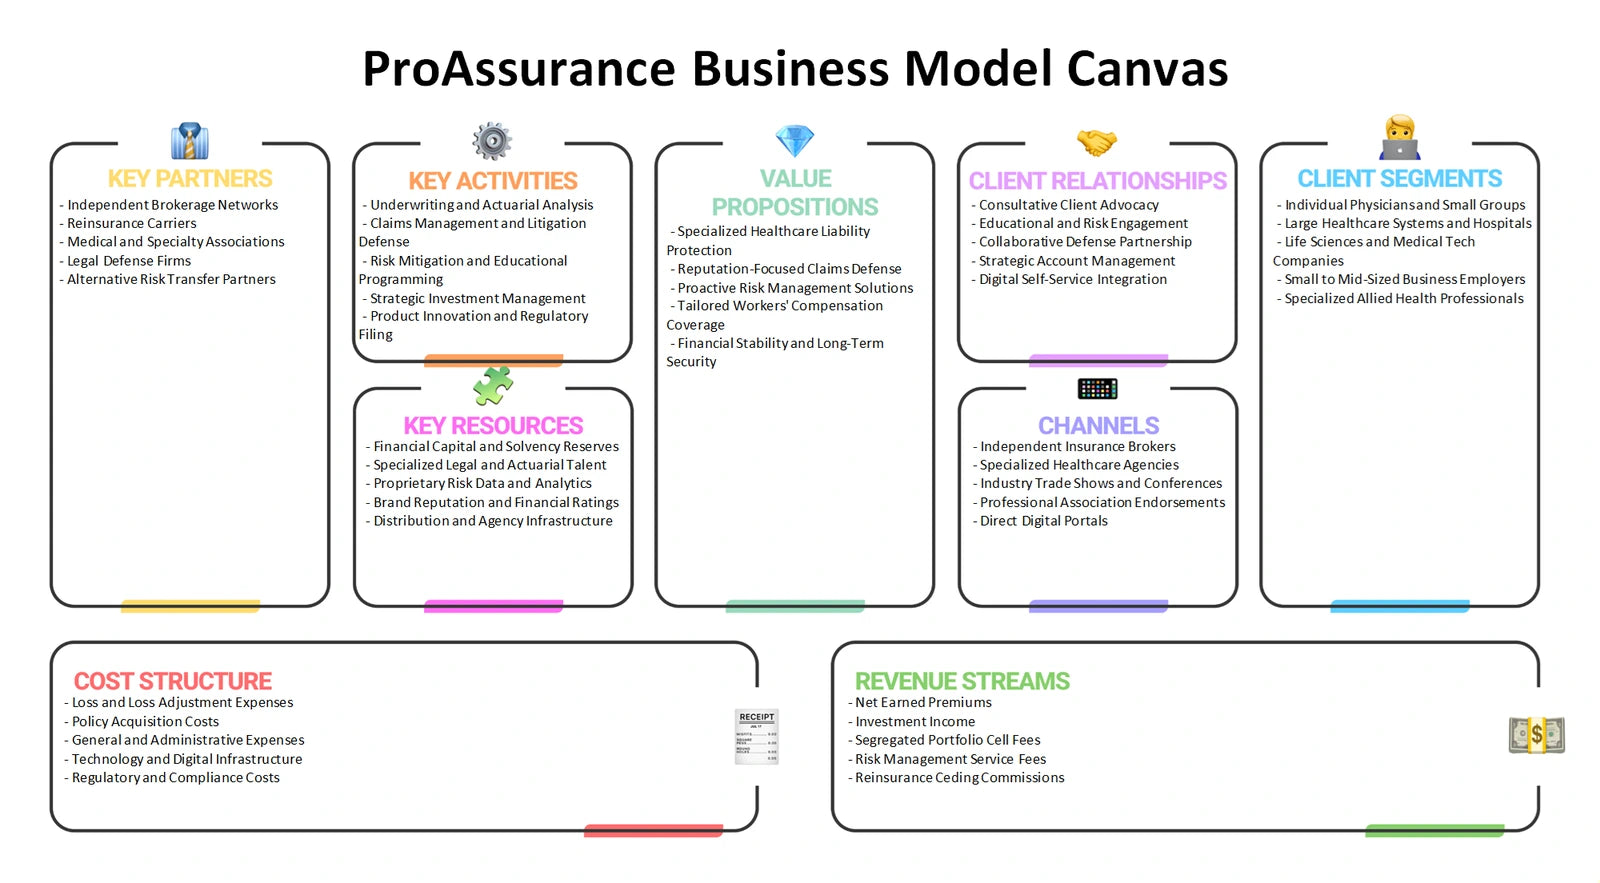
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could shape pricing power and returns in professional liability and workers’ compensation insurance?
ProAssurance Porter's Five Forces examines rivalry among insurers, buyer power among policyholders and intermediaries, supplier power, the threat of new entrants and the threat of substitutes. In this sector, the analysis can test how regulatory capital, specialist underwriting knowledge and claims capability may affect entry barriers. It can also distinguish direct insurance competition from substitutes such as retaining more risk, changing risk-financing arrangements or using alternative protection structures. The framework does not presume a force is high or low; it makes the evidence needed for that judgement visible.
- Buyer leverage. Assess how professional customers may compare coverage terms, carrier relationships, service and price when renewing protection.
- Input dependencies. Consider exposure to reinsurance, specialist legal expertise, technology suppliers and other inputs that can influence cost or service.
- Pressure testing. Record force-by-force observations in Excel and use the Word analysis to relate them to underwriting and market-position questions.
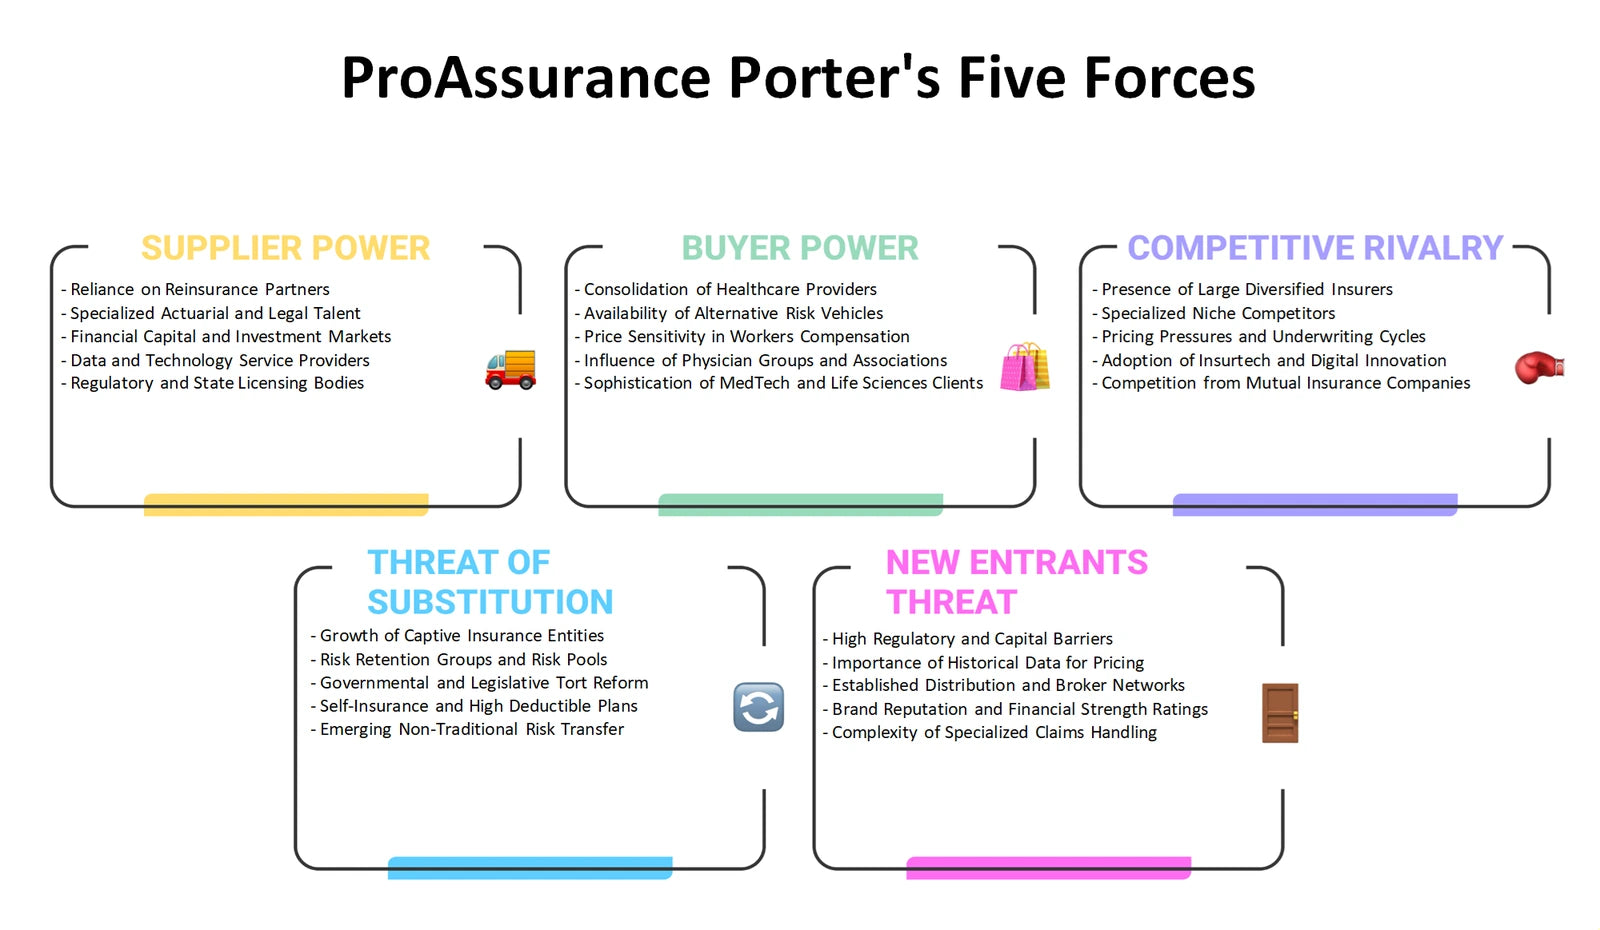
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a specialist insurer align its coverage design, pricing logic, routes to market and communications with professional customers?
The ProAssurance Marketing Mix considers Product, Price, Place and Promotion in a regulated B2B insurance setting. Product analysis can examine the fit of liability or workers’ compensation protection with specific policyholder risks. Price concerns underwriting terms, risk selection and the balance between competitiveness and claims exposure, not an invented rate list. Place asks how direct, broker and association-related routes might reach defined customer groups, while Promotion explores the role of educational content, professional credibility and clear risk communication.
- Coverage proposition. Compare the insurance features and service expectations that may matter to different professional or organizational buyers.
- Route-to-market choices. Evaluate where intermediary relationships, association engagement or direct contact could support informed customer access.
- Mix alignment. Use the Excel framework to place the four decisions side by side, with the Word analysis supplying context for their interaction.
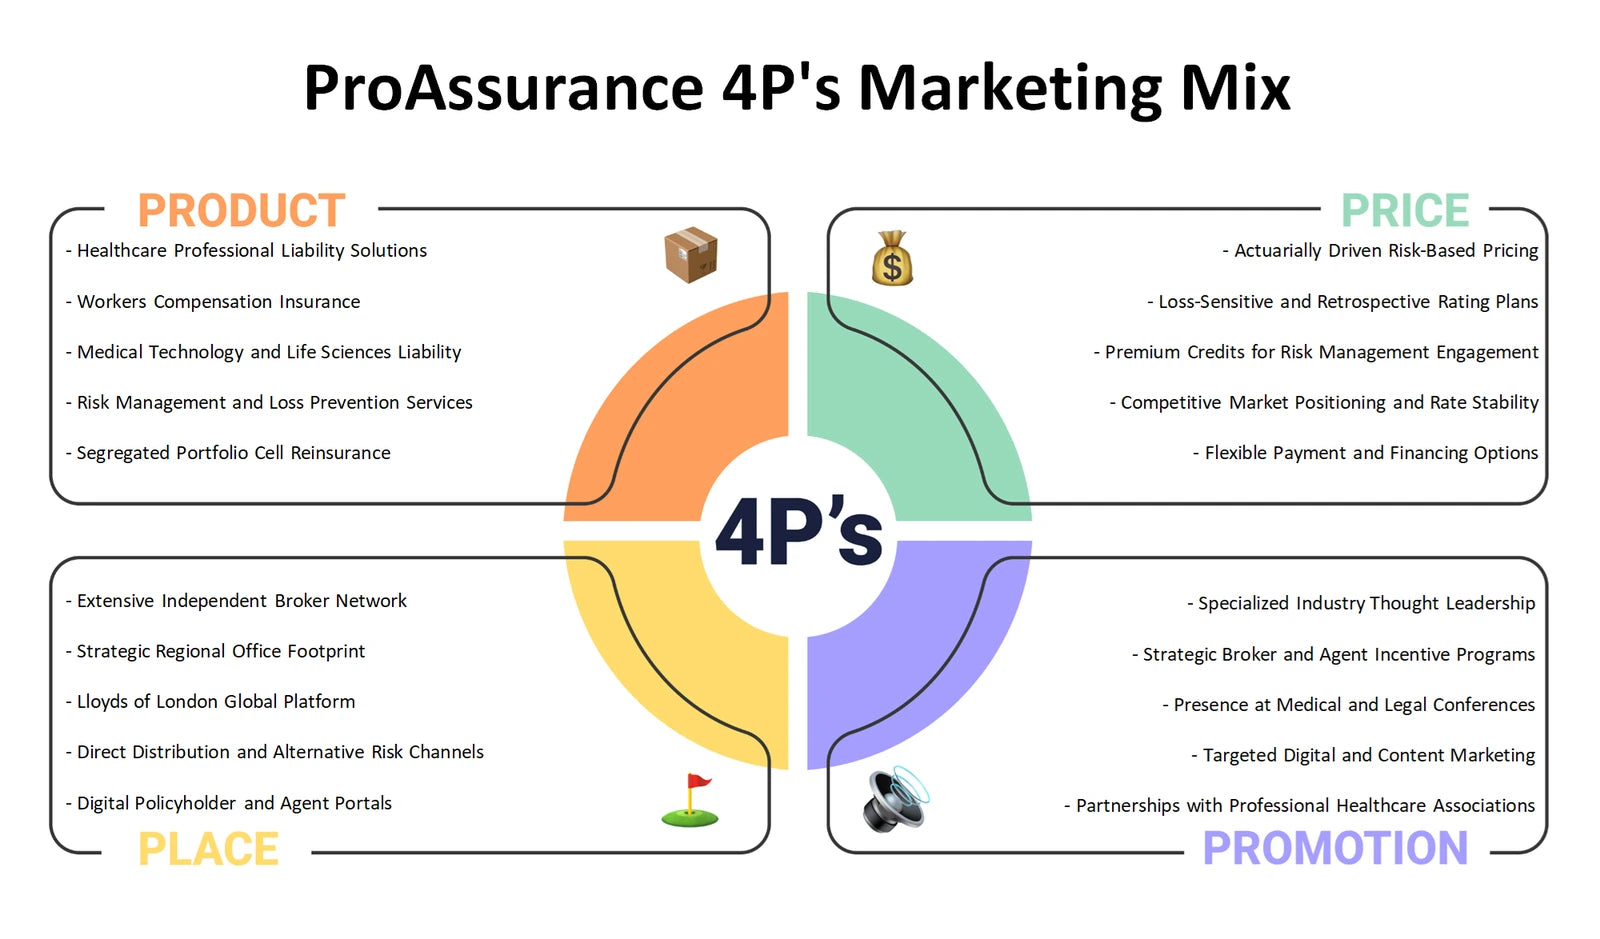
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes should be monitored because they may alter liability risks, customer needs or insurance economics?
The ProAssurance PESTLE analysis, also commonly called PESTEL, organizes Political, Economic, Social, Technological, Legal and Environmental influences around the insurer’s operating environment. Political and legal questions can cover insurance regulation and liability rules; economic questions can examine claims-cost inflation, investment conditions and customer affordability. Social and technological factors may change professional practice and risk expectations, while environmental conditions can affect workplace disruption and operational resilience. These are areas for structured assessment, not claims that a particular law, rate or event has already changed.
- Regulatory horizon. Track policy and legal issues that could affect underwriting requirements, claims handling or coverage demand.
- Risk evolution. Explore how technology, changing professional practices and environmental disruption may reshape insured exposures over time.
- External scan. Build a categorized monitoring list in Excel and use the Word analysis to relate external signals to business-model questions.
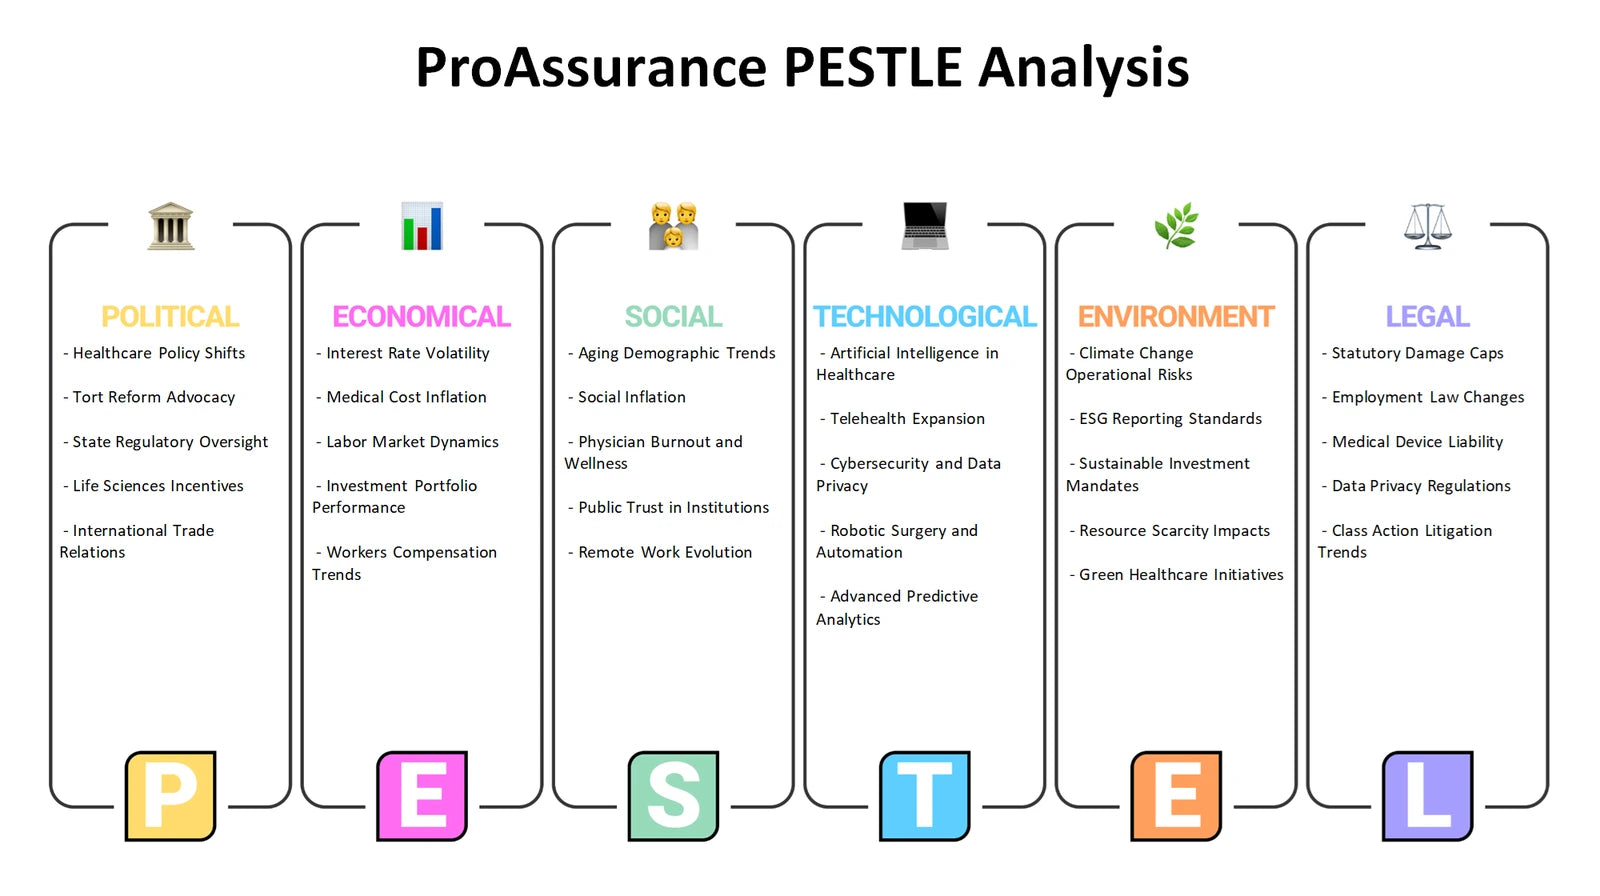
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can ProAssurance distinguish its own capabilities and constraints from opportunities and threats in specialist insurance markets?
The ProAssurance SWOT analysis separates internal Strengths and Weaknesses from external Opportunities and Threats. It can help assess potential internal themes such as specialist underwriting knowledge, claims processes, customer relationships or concentration risks without presenting them as established findings. Opportunities and threats belong outside the organization: evolving professional risks, distribution shifts, regulation, insurance-market competition and economic conditions can be considered there. This distinction matters because an external market change should not be mistaken for a capability, and an internal limitation should not be described as an industry threat.
- Evidence separation. Classify what the company can influence directly apart from conditions created by customers, regulators and competitors.
- Strategic fit. Test whether possible capabilities are relevant to emerging liability, workers’ compensation and distribution opportunities.
- Decision record. Use Excel to prioritize observations by category and the Word analysis to document the reasoning behind the resulting strategic themes.
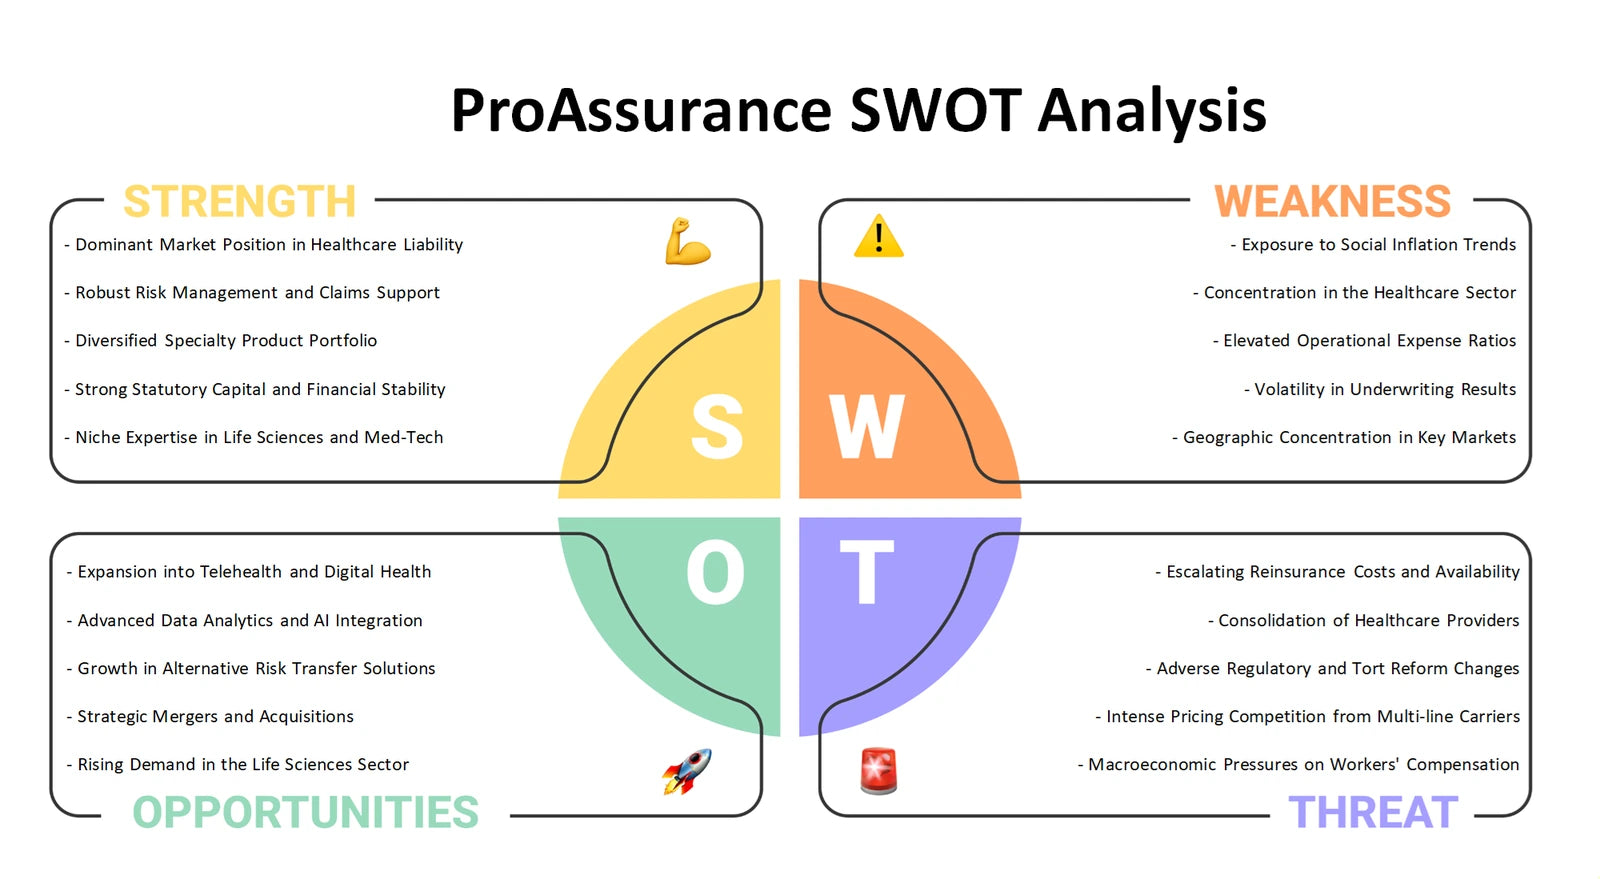
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices with insurance-market realities
Together, these six perspectives help place ProAssurance’s portfolio questions, operating model, industry pressures, customer approach, external environment and strategic position in one connected discussion. The Excel frameworks provide structured places to compare and organize the issues, while the Word files provide detailed company-analysis context for developing more informed questions and priorities.
Company background: ProAssurance — corporate website.