

PNC Financial Services: Banking Business and Lending Economics – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
PNC Financial Services Strategy Analysis Bundle
PNC Financial Services is the U.S.-based North American bank represented by PNC Financial Services Group, Inc., the SEC reporting issuer. Its consumer-facing offer includes checking and savings accounts, credit cards, mortgage lending and auto loans, while relationship-led banking and wealth services provide further ways to examine how customers are supported through digital and human channels.
In its Form 10-Q filed August 5, 2026, PNC Financial Services Group reported revenue of USD 6.875 billion and GAAP net income of USD 2.040 billion for the quarter from April 1 to June 30, 2026. These quarterly figures provide dated context for questions about portfolio priorities, the economics of self-service versus advisory support, and exposure to banking-sector conditions.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking offerings merit different resource priorities as customer demand and relative market position change?
A PNC Financial Services BCG Matrix helps separate the portfolio question from a simple profitability discussion. It uses market growth and relative market share to compare products or service lines that may compete for investment, operational attention or distribution capacity. Deposit accounts, cards, mortgages, auto lending and wealth-related services can face different growth patterns, customer economics and servicing needs. The framework provides a disciplined way to consider the strategic implications of Stars, Cash Cows, Question Marks and Dogs without assigning any PNC activity to a quadrant without evidence.
- Portfolio comparisons. Contrast mature banking propositions with areas where changing customer demand may require additional capability or selective restraint.
- Resource trade-offs. Consider where relationship support, digital journeys, product development and risk capacity could be evaluated together.
- Working view. Use the Excel matrix to organize candidate offerings, then use the Word analysis to interpret the assumptions behind each comparison.
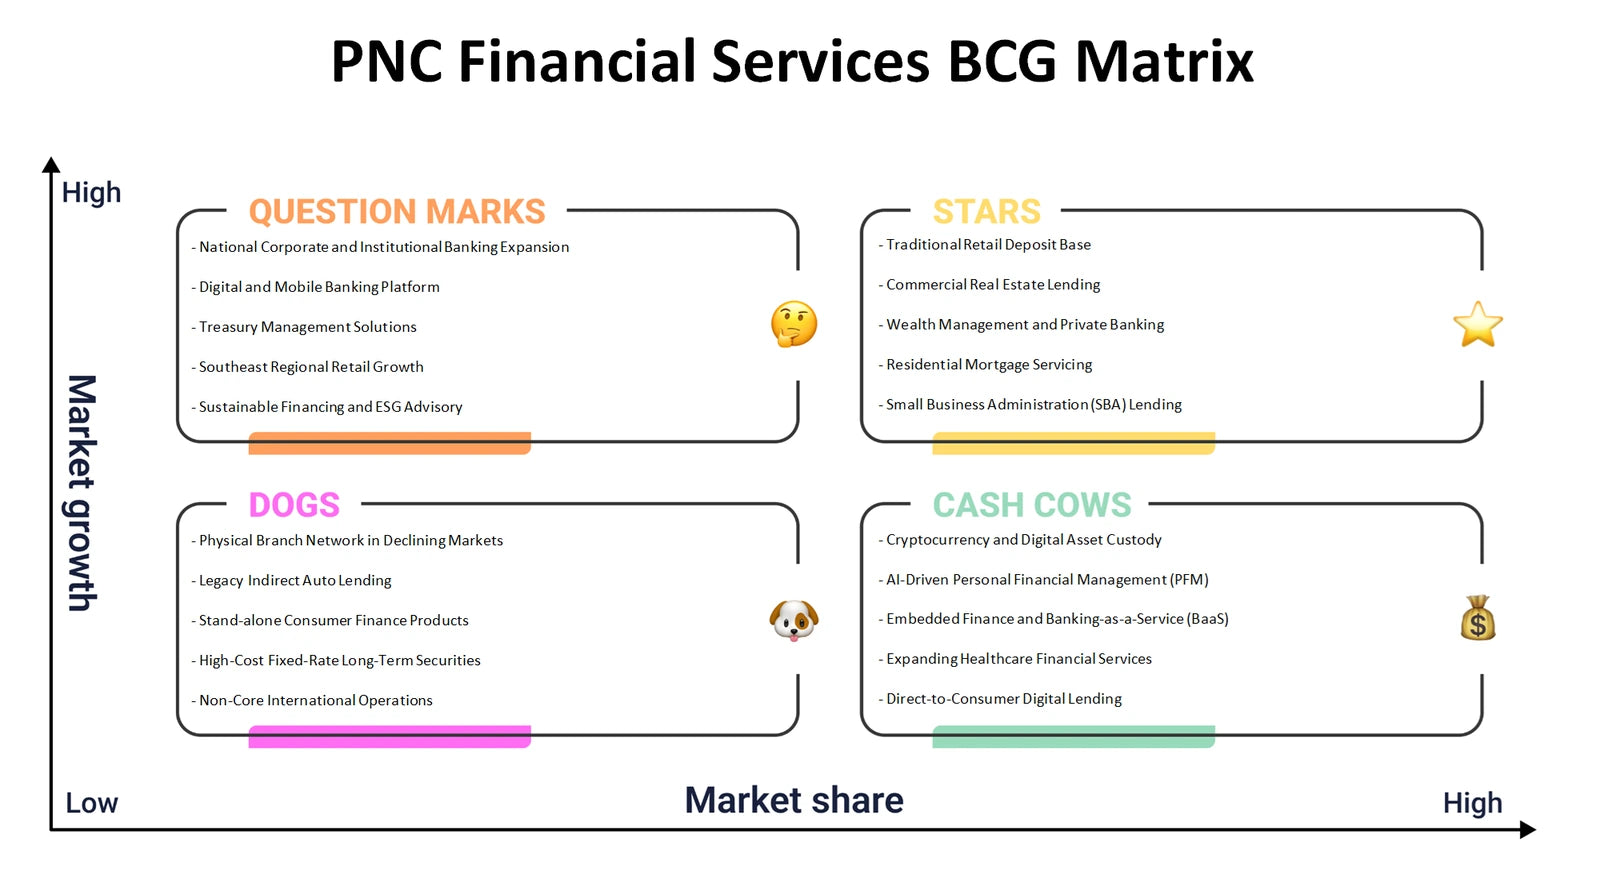
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do PNC's customer relationships, channels and banking economics fit together as one operating model?
The PNC Financial Services Business Model Canvas connects all nine building blocks rather than treating products as isolated offers: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For a bank, the useful question is how account, lending and advisory needs are served through branches, phone, secure messaging, digital journeys and relationship-managed support. It also helps examine how trust, service quality, risk controls and technology shape the cost of delivering those services and the revenue logic behind them.
- Service architecture. Map how digital self-service and banker-led interactions can support different customer needs without losing continuity.
- Economic links. Examine how key resources, compliance-heavy activities and operating costs connect to deposit, lending and fee-related revenue streams.
- Model mapping. Populate the Excel canvas as a shared operating map and use the Word analysis to add context to the relationships between blocks.
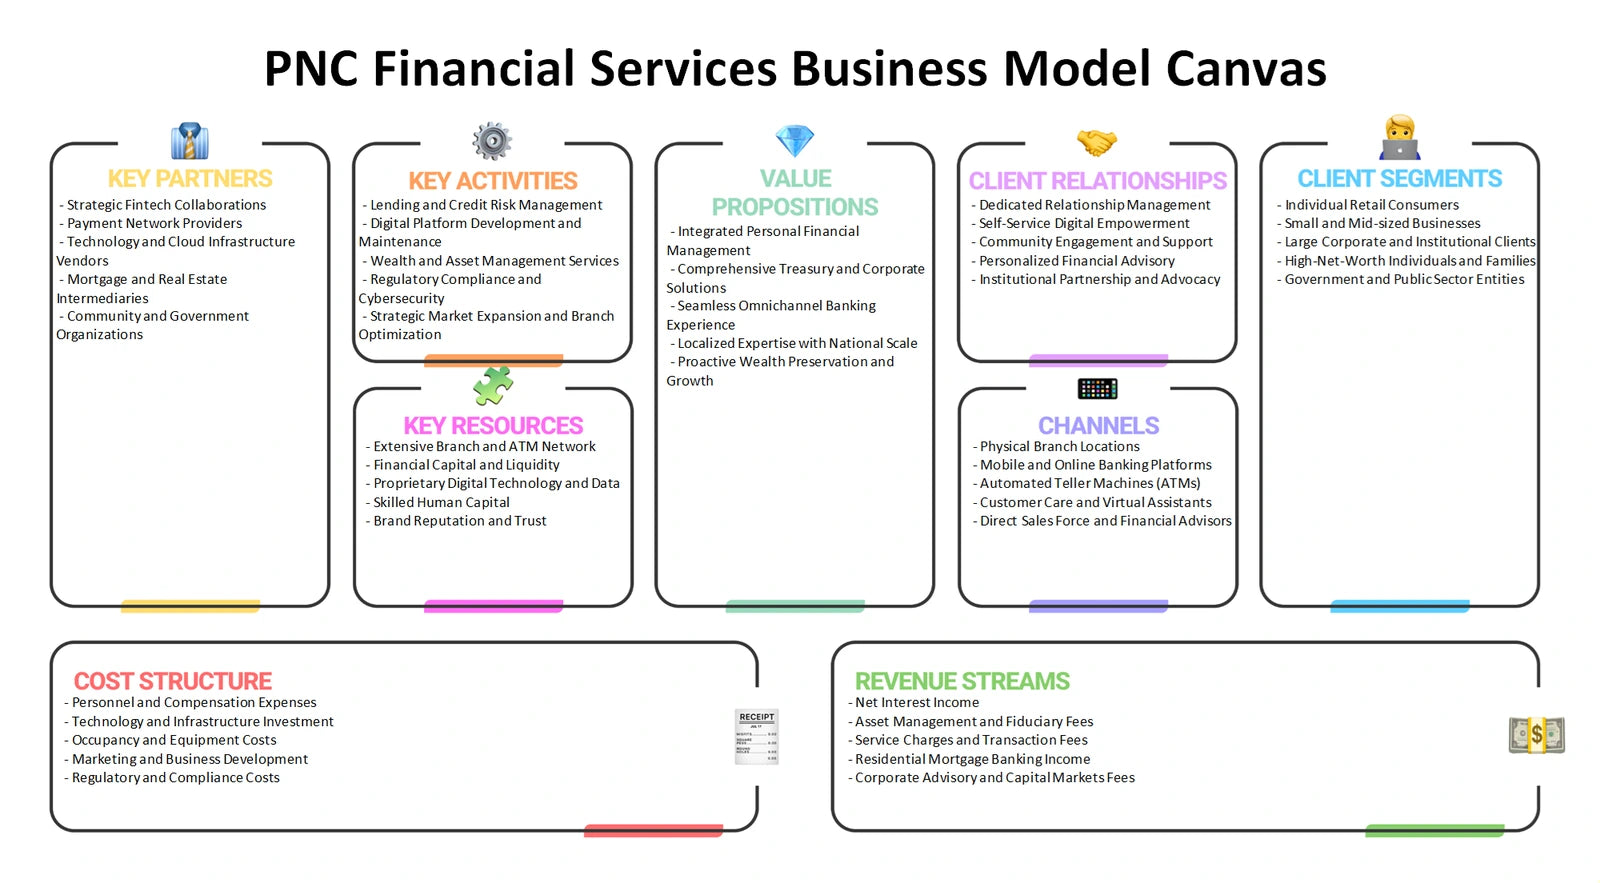
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can influence pricing, customer retention and the cost of competing in U.S. banking?
PNC Financial Services Porter's Five Forces frames the competitive environment around deposits, lending, payments and advice. Rivalry can affect product differentiation and service expectations; buyer power can rise when customers can compare rates, digital experiences or switching options. Supplier power includes dependence on funding sources, technology providers and specialist capabilities. The analysis also considers barriers facing new entrants and substitutes such as non-bank payment tools, digital finance services or other ways customers can store, move or obtain money. These forces help turn broad banking pressure into specific questions for management review.
- Customer choice. Assess where transparent comparisons, switching friction and service quality may shape the bargaining position of different customer groups.
- Industry boundaries. Consider substitutes beyond direct banks, including alternative payment, lending and money-management solutions.
- Pressure testing. Use the Excel framework to record evidence and assumptions for each force, with the Word analysis supporting a reasoned interpretation.
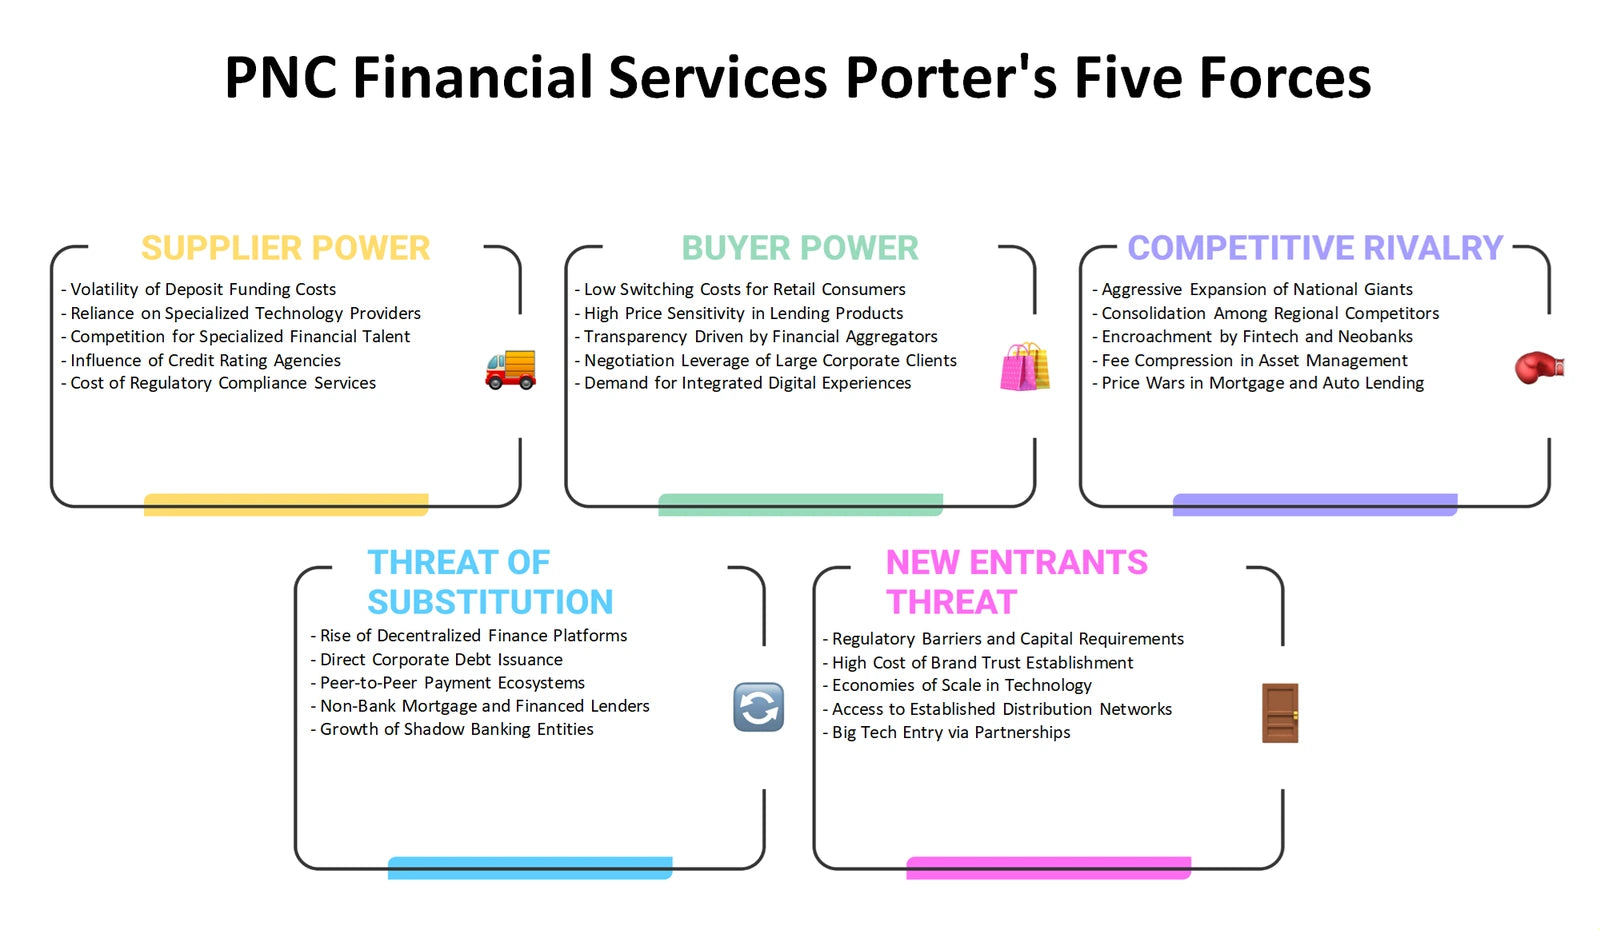
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can product design, pricing logic, access points and communications be assessed in a regulated financial-service setting?
A PNC Financial Services Marketing Mix applies Product, Price, Place and Promotion to banking decisions rather than to a physical-goods template. Product can include account features, cards, lending options and advice; Price includes rates, fees and value communication within applicable rules. Place covers the practical routes customers use, from digital account servicing and secure messaging to phone support and banker interactions. Promotion asks how clear, compliant communication can explain financial choices and build confidence. Reviewing the four Ps together helps expose disconnects between what is offered, how it is accessed and what customers understand.
- Offer clarity. Compare whether product features and service support address everyday banking, borrowing and longer-term financial needs coherently.
- Channel fit. Examine where digital convenience, extended support and relationship contact may matter most in the customer journey.
- Planning tool. Use the Excel framework to organize the four Ps by customer need, while the Word analysis provides detailed context for discussion.
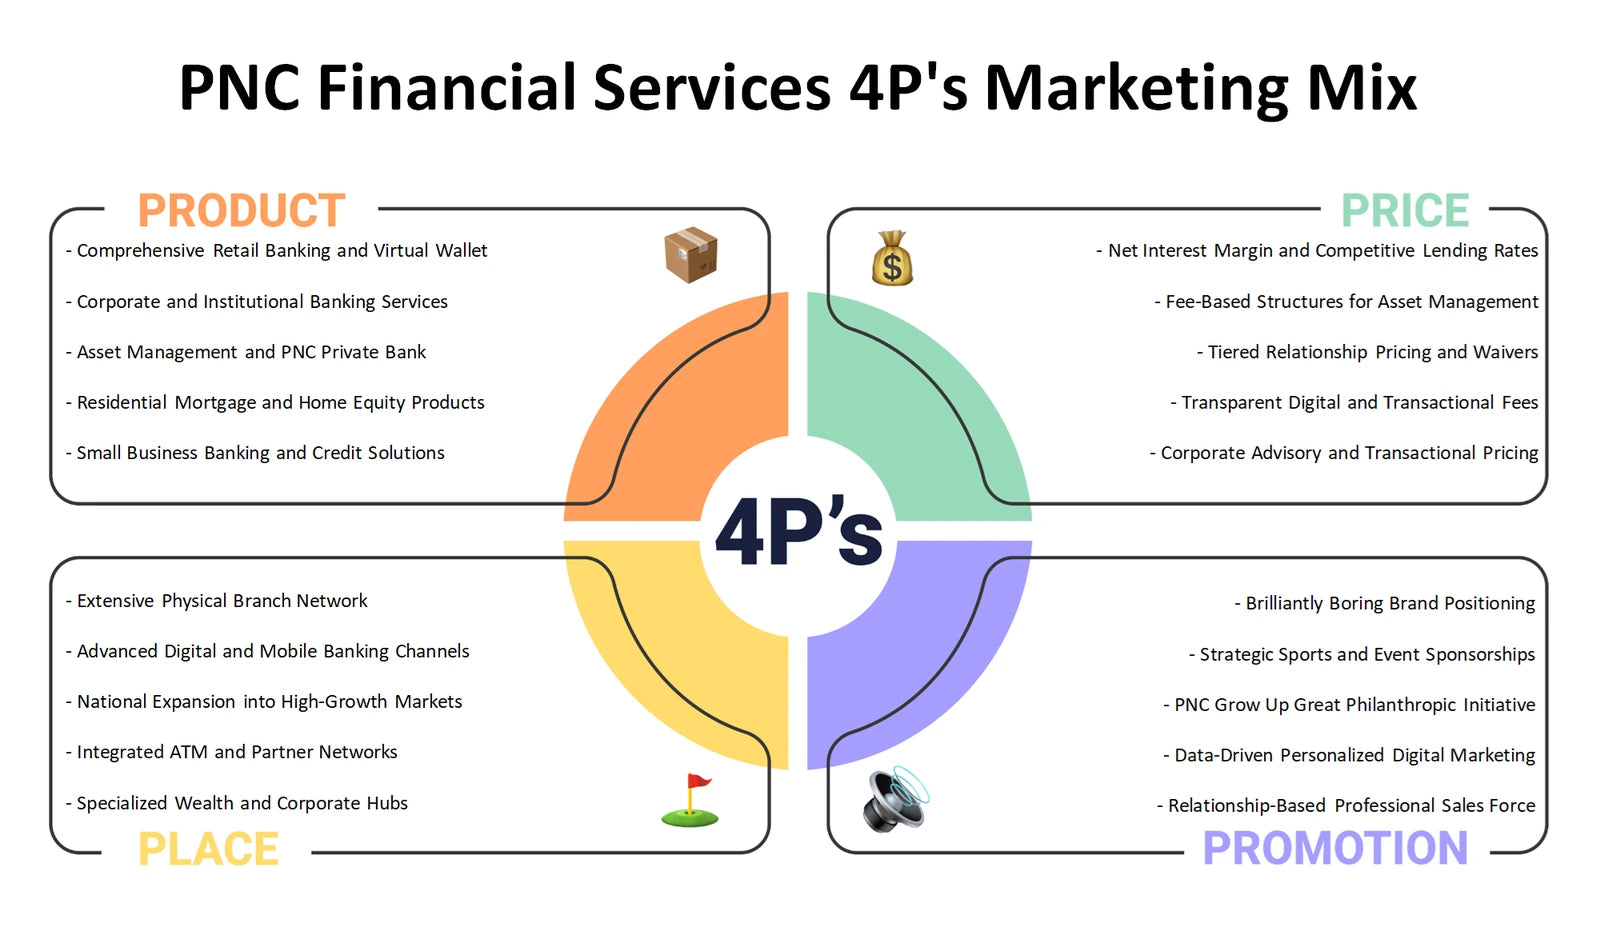
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could reshape demand, regulation, operating costs and risk management for a U.S. bank?
A PNC Financial Services PESTLE analysis, also commonly called PESTEL, organizes the external conditions that can influence a North American bank. Political factors can affect policy priorities; economic conditions can influence borrowing, deposits, credit quality and funding decisions. Social expectations include accessibility, trust and preferences for human or digital support. Technological change raises questions about security, automation and customer experience. Legal obligations shape conduct and controls, while environmental factors can influence risk assessment, property exposure and stakeholder expectations. The framework distinguishes these external influences from internal capabilities or confirmed company actions.
- Rate and credit context. Explore how changing economic conditions could affect customer demand and banking risk without assuming a particular rate path.
- Control environment. Identify policy, legal, cybersecurity and data questions that may alter the cost or design of financial services.
- External scan. Use the Excel categories to track relevant developments and consult the Word analysis when translating them into strategic questions.
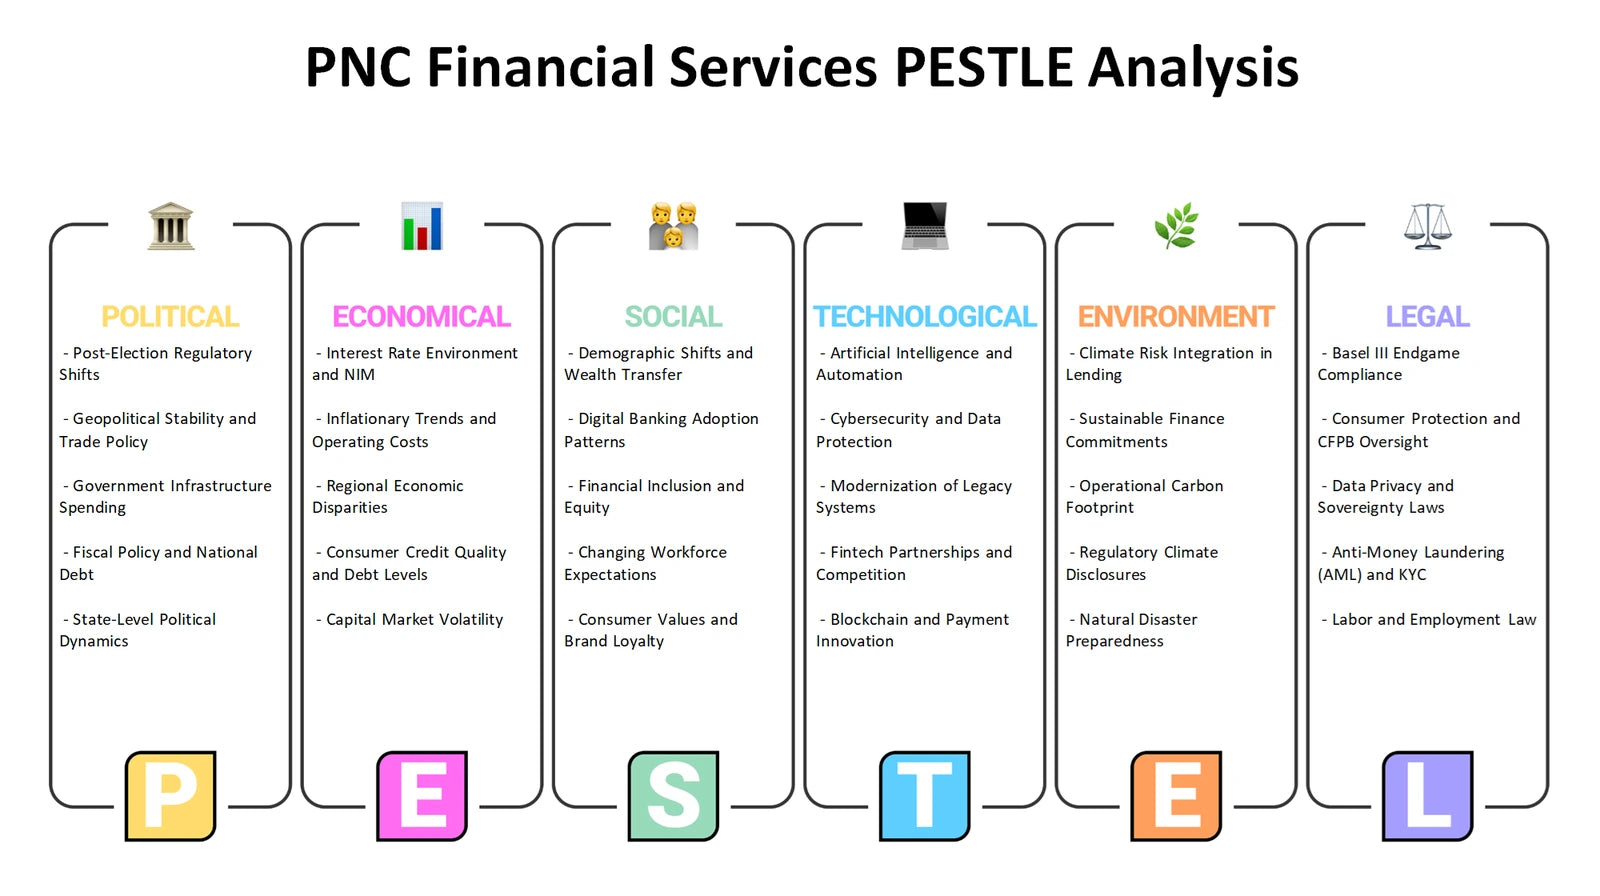
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal banking capabilities and constraints be weighed against external opportunities and threats?
A PNC Financial Services SWOT analysis separates what is internal from what is external. Strengths and weaknesses can be used to examine capabilities such as customer service models, product breadth, technology, risk management or operating complexity, subject to evidence. Opportunities and threats instead concern market conditions, customer behaviour, competitive alternatives and regulatory or economic pressures. This distinction is especially useful for a bank because a potentially attractive market development still requires the internal capacity, controls and customer proposition to respond effectively. The framework helps avoid treating a broad external trend as if it were already a proven company advantage.
- Internal reality. Test which resources, service processes and organisational constraints could support or limit strategic choices.
- External fit. Match possible market opportunities and threats with the capabilities required to respond responsibly.
- Decision synthesis. Use the Excel grid to separate evidence by category, then use the Word analysis to develop balanced implications and priorities.
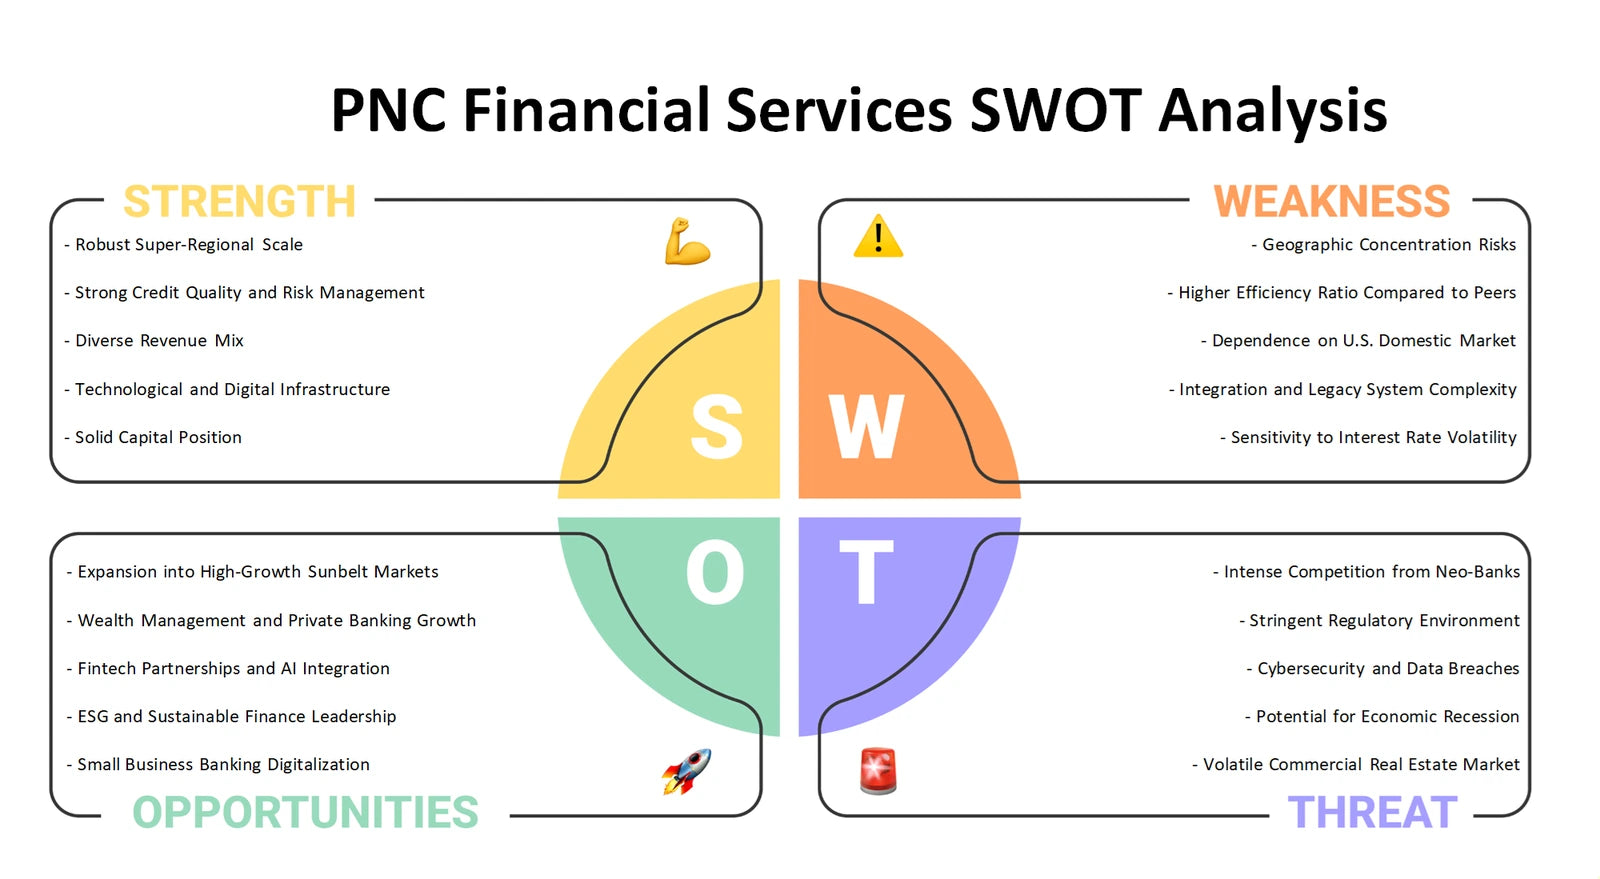
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a joined-up view of PNC Financial Services
Used together, the six perspectives move from portfolio priorities and operating-model economics to customer choices, industry pressure, external change and internal readiness. The Excel frameworks provide structured places to compare issues, while the detailed Word analyses help develop company-specific discussion, evidence checks and strategic questions without treating the preview images as the full product.
Company background: PNC Financial Services — PNC Personal Banking official site.