

Ping An Insurance Group: Agricultural Demand and Distribution – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Ping An Insurance Group Strategy Analysis Bundle
Ping An Insurance Group is treated here as the insurance-led financial-services business described in the supplied product context. That context highlights financial-institution alliances, particularly bancassurance involving Ping An Bank, to connect customers with insurance, banking and investment services. It also references inclusive financial services, agricultural lending and rural education support, combining commercial distribution questions with community-oriented initiatives.
These are business-context themes rather than pre-set conclusions in the downloadable materials. The useful strategic questions are how insurance, banking and investment propositions compete for resources, how cross-selling creates value, and how digital delivery, regulation and rural access can affect economics. The six connected frameworks help organise those questions in Excel and examine them in greater depth through the accompanying Word analysis.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance, banking and investment propositions deserve priority when growth potential and relative market share point in different directions?
A Ping An Insurance Group BCG Matrix helps separate portfolio discussion from assumptions. It compares business areas through market growth and relative market share, then uses the familiar Stars, Cash Cows, Question Marks and Dogs categories to structure resource-priority conversations. For an insurance-led group with bancassurance and cross-selling context, the central issue is not simply scale: it is whether a proposition can build a defensible position, fund other activities or requires careful testing before more capital, management attention or distribution capacity is committed.
- Portfolio boundaries. Compare insurance, banking-linked and investment-related propositions at a sensible business-unit level rather than treating the group as one undifferentiated offering.
- Capital logic. Examine how mature cash-generating activities could support higher-growth opportunities without assuming any unit already belongs in a particular quadrant.
- Structured prioritisation. Use the Excel framework to map comparable units and use the Word analysis to record the evidence, caveats and portfolio questions behind each placement.
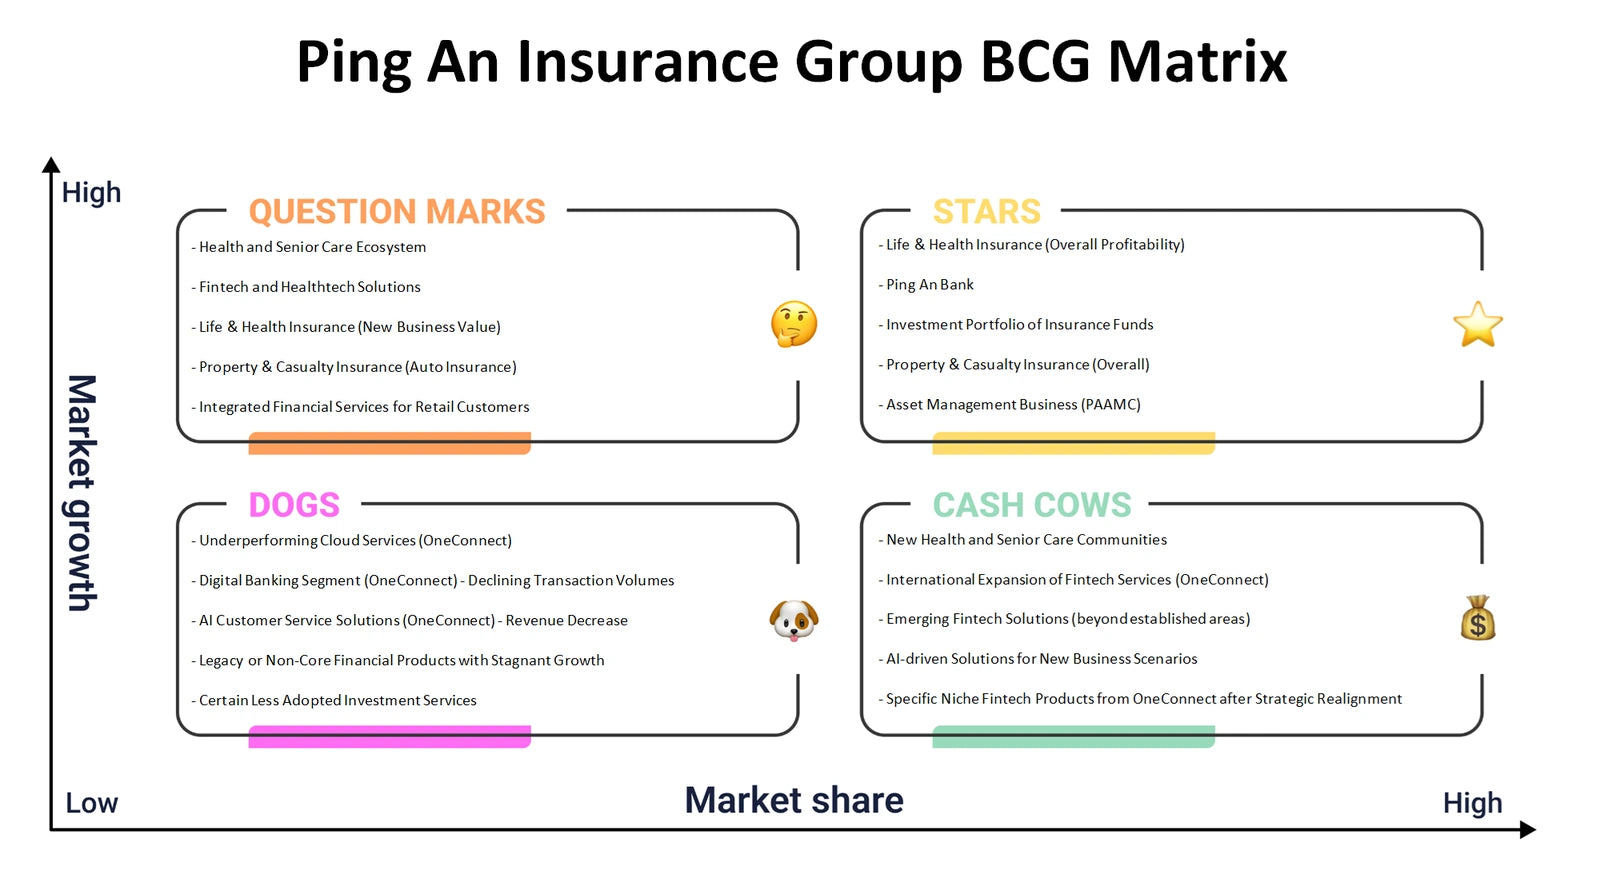
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do alliance-led distribution, customer trust and multiple financial-service needs fit together in one value-creation model?
The Ping An Insurance Group Business Model Canvas brings together all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. The supplied context makes partnerships especially relevant because bancassurance and financial-institution relationships can shape access to customers and opportunities to offer connected services. The canvas helps examine how customer needs are met through channels and relationships, how insurance and related services may generate revenue, and what operating resources, partner dependencies and costs sit behind that promise.
- Connected customer journeys. Trace how insurance customers may encounter banking, investment or inclusive-finance services through partner channels and ongoing relationships.
- Economics behind access. Assess the link between distribution reach, cross-selling potential, partner arrangements, service operations and the cost structure needed to support them.
- Model alignment. Populate the Excel canvas block by block, then use the Word analysis to test whether the proposed value proposition, activities and revenue logic remain mutually consistent.
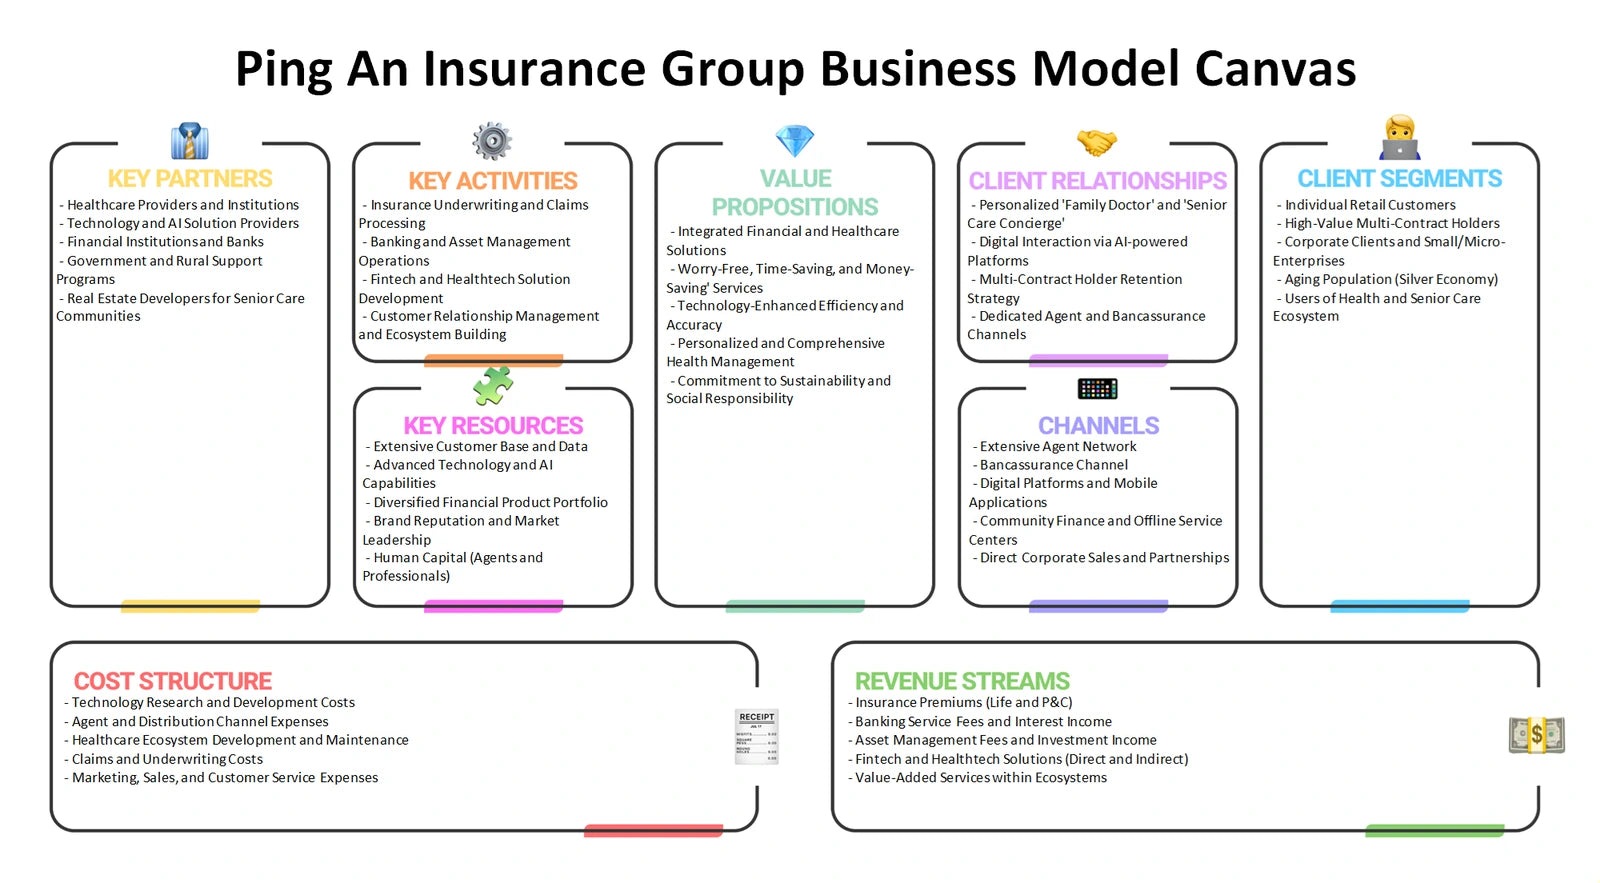
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could influence margins, customer retention and bargaining power across insurance-led financial services?
A Ping An Insurance Group Porter's Five Forces analysis examines the competitive setting around insurance distribution and related financial services without presuming a force score. Rivalry can influence product differentiation and service costs; buyer power can rise when customers can compare policies, savings products or digital providers. Supplier power may involve distribution partners, specialist talent, technology providers or other critical inputs. The framework also considers new entrants and substitutes, including alternative ways consumers and businesses meet protection, savings, lending or investment needs without using a conventional insurer.
- Channel dependence. Explore how reliance on bank alliances or other distribution relationships could affect negotiating leverage, reach and customer ownership.
- Substitution risk. Distinguish direct insurance competition from alternative financial, savings, lending or digital solutions that may meet the same underlying need.
- Evidence-led comparison. Use the Excel grid to compare each force and use the Word analysis to explain which market evidence would be needed before judging pressure as high or low.
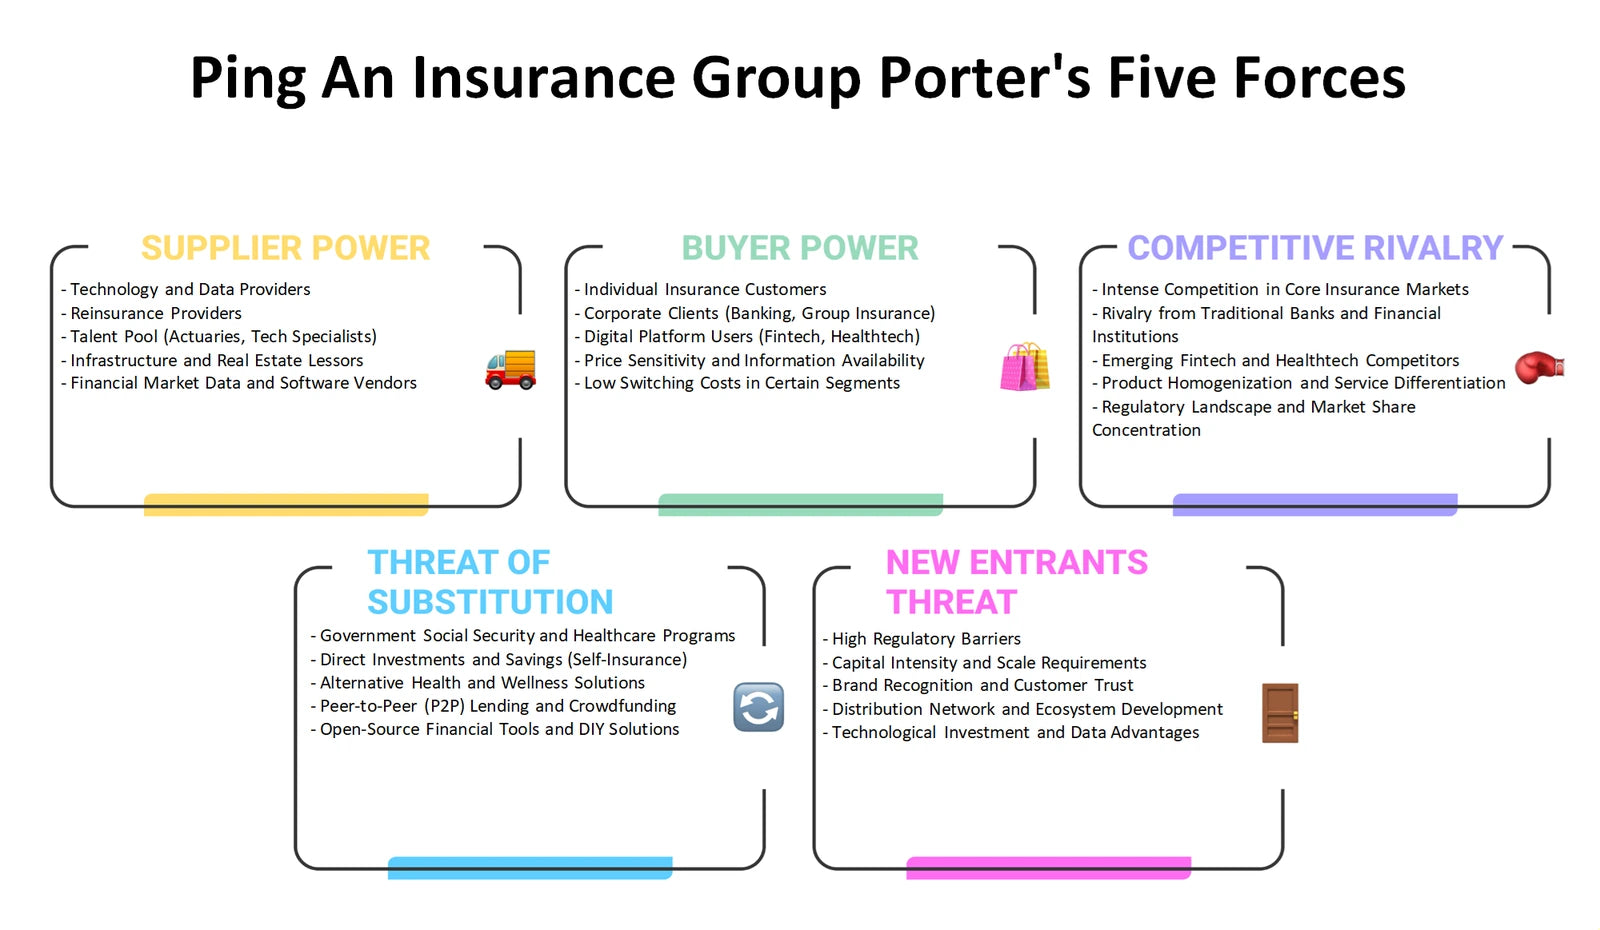
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can Product, Price, Place and Promotion be coordinated when financial services depend on trust, suitability and accessible distribution?
A Ping An Insurance Group Marketing Mix analysis applies the 4Ps to a regulated, relationship-based service context. Product concerns the fit between protection, banking-linked and investment-related needs; Price considers premiums, fees, returns, affordability and value communication without inventing actual price points. Place examines bancassurance, partner networks, digital service routes and access for rural communities. Promotion focuses on clear, responsible communication that helps customers understand benefits, limitations and suitability instead of treating financial services like a simple retail purchase.
- Offer design. Compare how customer segments may value protection, convenience, financial inclusion or bundled service access across different propositions.
- Trust at the channel. Assess whether the selected route to market supports informed decisions, ongoing service and a credible customer experience.
- Marketing coordination. Use the Excel framework to connect the four Ps by segment, then use the Word analysis to explore trade-offs between affordability, distribution cost and responsible communication.
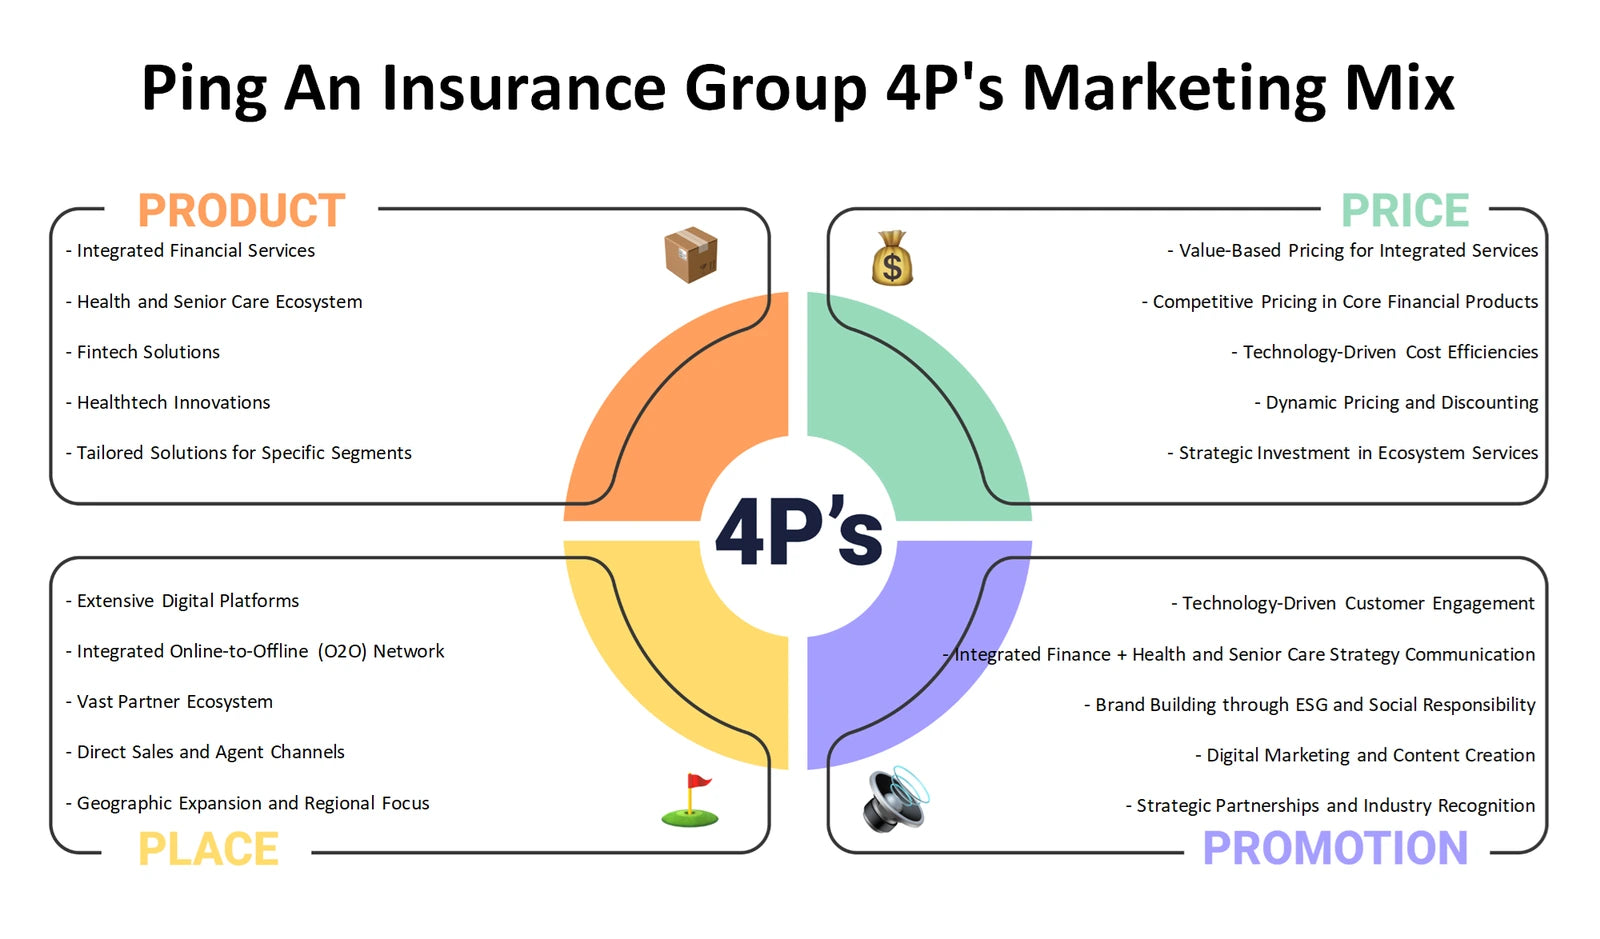
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could reshape demand, operating requirements and partner-led distribution for this financial-services model?
A Ping An Insurance Group PESTLE analysis, also commonly called PESTEL, separates external influences from internal capabilities. Political factors may affect public priorities around inclusion or rural development; Economic conditions can affect household affordability, credit demand and investment behaviour. Social change can alter expectations for protection and accessible service. Technological change matters for digital journeys, data use and service delivery. Legal requirements can affect insurance, banking, customer protection and communications, while Environmental conditions may influence risk exposure, community needs and long-term product considerations. These are areas to investigate, not claims that a particular policy or market change has occurred.
- External signals. Organise policy, demographic, economic, technology, legal and environmental developments according to their potential relevance to customers and operations.
- Rural-access lens. Consider how inclusion initiatives and agricultural-finance context could be affected by infrastructure, climate exposure or changing community needs.
- Scenario preparation. Use Excel to log external drivers, likely effects and uncertainties, while the Word analysis helps turn those observations into reasoned strategic questions.
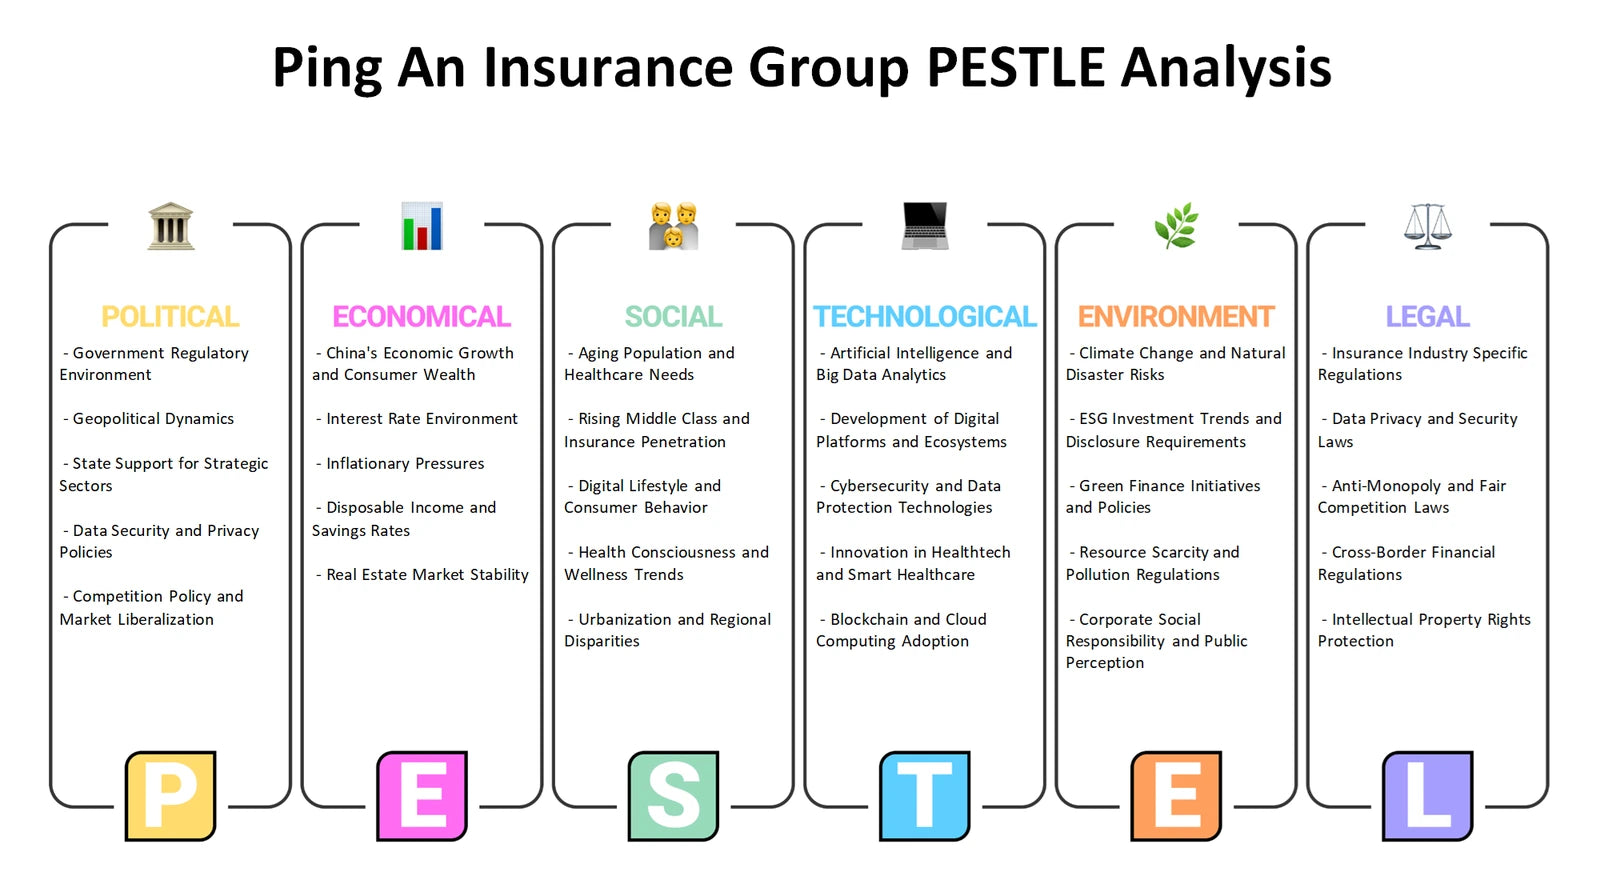
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal capabilities and constraints should be considered alongside external openings and risks in partnership-led financial services?
A Ping An Insurance Group SWOT analysis keeps classification clear. Strengths and weaknesses are internal: for example, analysts can examine the capability to coordinate financial-service relationships, serve customers through partner channels or support complex operations. Opportunities and threats are external: changing customer needs, technology, regulation, competition and wider economic conditions may create openings or risks. The supplied context suggests useful areas to test, including bancassurance relationships, inclusive financial services and rural engagement, but the framework does not present those themes as proven strengths or outcomes without supporting evidence.
- Internal reality check. Separate capabilities, resources, operating complexity and channel dependence from conditions that originate outside the organisation.
- Strategic fit. Explore whether potential opportunities in accessible financial services align with the resources needed to manage risk, service quality and compliance.
- Actionable synthesis. Use the Excel matrix to pair internal and external factors, then use the Word analysis to document assumptions and develop focused questions for management review.
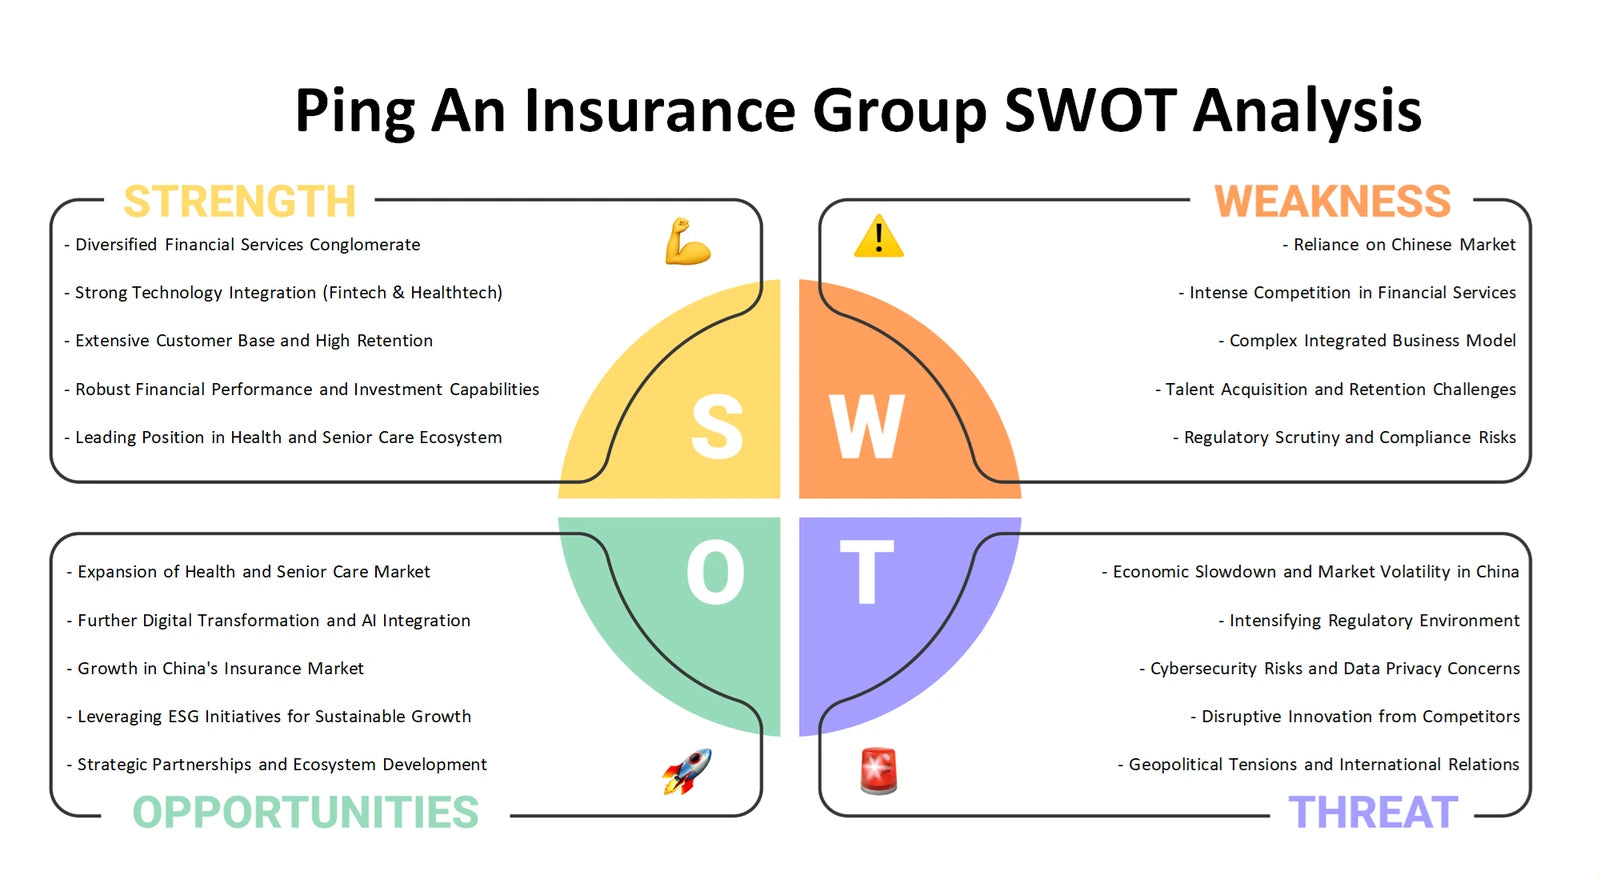
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of Ping An Insurance Group
Used together, the six perspectives move from portfolio choices and value creation to competitive pressure, customer delivery, external change and strategic fit. The Excel frameworks provide a structured way to organise comparisons and assumptions, while the Word files provide detailed company-analysis context for developing more considered questions about alliances, distribution, customer needs and operating trade-offs.
Company background: Ping An Insurance Group — product-context background.