

Pepper: Customer Relationships and Value Creation – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Pepper Strategy Analysis Bundle
For clarity, Pepper in this bundle refers to Pepper Money, the non-bank lending business identified in the available company context, rather than an unrelated same-name company. That context describes broker education and support for non-bank lending solutions, alongside asset-finance distribution through introducers including online auto brokers, commercial and consumer brokers, car dealerships and original equipment manufacturer relationships.
These documented routes to market make portfolio choices, lending economics, intermediary relationships and external risk connected questions. The six analyses help examine how Pepper can compare growth opportunities, map value creation and monitor channel dependence without assuming that the company has already been assigned scores, market shares, BCG positions or recommendations.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending and asset-finance activities merit capital, specialist capability and intermediary attention when market growth and relative market share differ?
A Pepper BCG Matrix helps separate portfolio discussion from broad assumptions about lending demand. It can compare defined activities, such as lending propositions, borrower groups or origination routes, using market growth and relative market share. The familiar Stars, Cash Cows, Question Marks and Dogs are analytical categories, not labels assigned here to Pepper. For a lender, the exercise matters because growth can consume funding, underwriting capacity, servicing resources and partner-management time before it produces durable returns.
- Comparable units. Define each activity carefully so that its growth rate and relative share are measured against a meaningful lending or asset-finance market.
- Resource trade-offs. Consider whether broker support, dealer relationships, credit expertise and operational capacity should be maintained, expanded, tested or reduced across portfolio areas.
- Prioritisation record. Use the Excel framework to plot assumptions and discussion points, then use the Word analysis to document definitions, evidence needs and rationale.
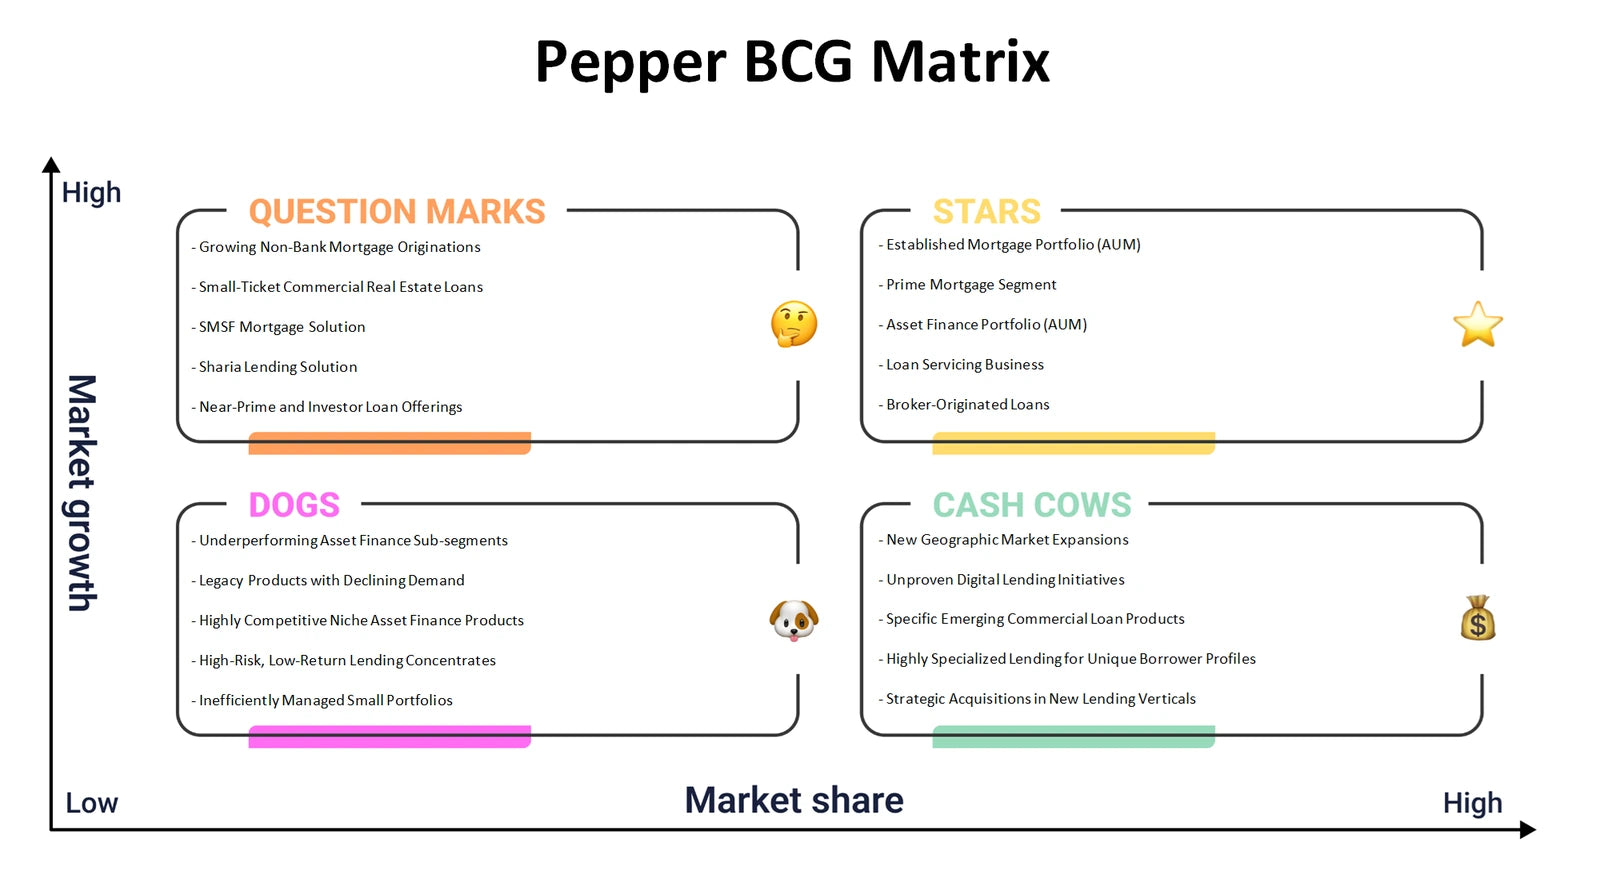
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do Pepper's borrower needs, intermediary relationships and lending operations connect to a viable economic model?
The Pepper Business Model Canvas brings together all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. The available context makes channels and partnerships particularly relevant: brokers, dealers, introducers and OEM connections can help reach borrowers, but they also require enablement, governance and ongoing relationship management. The Canvas helps trace how a lending proposition is delivered from customer access through assessment, funding and servicing, while keeping revenue logic and operating costs in the same view.
- Intermediary journey. Examine how broker education and support may affect customer matching, application quality, service expectations and relationship continuity.
- Economic connections. Link potential revenue streams to the resources, lending activities, partnership costs and operating commitments needed to serve each segment.
- Model alignment. Populate the Excel blocks as a connected map and use the Word analysis to explain where one change may affect channels, costs or customer relationships.
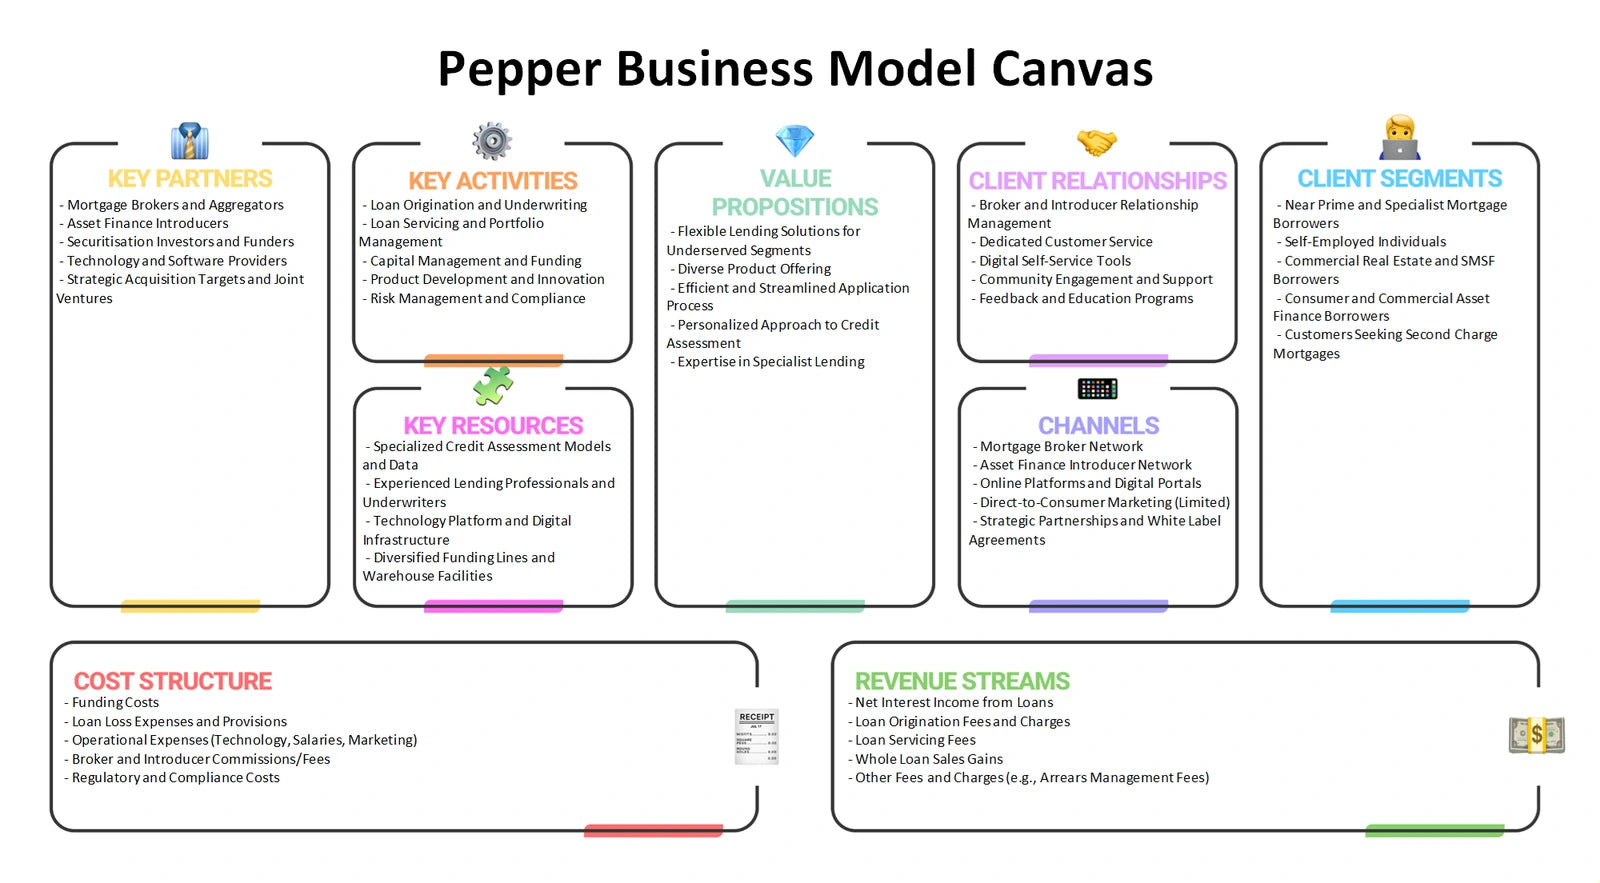
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could influence the attractiveness of Pepper's non-bank lending and asset-finance activities?
Pepper Porter's Five Forces analysis examines rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes around the relevant lending markets. Rivalry may concern other providers seeking similar borrower and introducer relationships. Supplier power can prompt questions about funding, credit information, technology and service inputs. Buyer power is not limited to borrowers: intermediaries may influence product visibility and customer choice. Substitutes include alternative ways to finance vehicles, equipment or other needs, rather than only direct lending competitors.
- Channel bargaining. Assess where brokers, dealers and introducers may have influence over access to demand, service standards or product comparison.
- Entry barriers. Consider the role of underwriting capability, responsible-lending processes, funding access, brand trust and partner networks in deterring new entrants.
- Pressure map. Use the Excel framework to compare evidence for each force, with the Word analysis providing the narrative behind possible competitive pressures.
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can Pepper present lending solutions consistently when borrowers may encounter them through brokers, dealers and other introducers?
A Pepper Marketing Mix analysis applies Product, Price, Place and Promotion to a regulated, intermediary-supported financial-service setting. Product can examine the fit between non-bank lending solutions and customer circumstances, including auto-loan and equipment-finance needs identified in the available context. Price should be considered as a wider value and affordability question involving rates, fees, terms and risk-based conditions, without assuming any actual offer. Place focuses on broker, dealer, online and partner routes, while Promotion examines clear communication and the role of broker training in explaining propositions responsibly.
- Offer clarity. Compare how product features and eligibility information could be communicated across borrower-facing and intermediary-facing touchpoints.
- Distribution consistency. Review how dealer, broker and digital routes may shape discovery, application support, customer expectations and ongoing service.
- Message audit. Use the Excel framework to organise the four Ps and use the Word analysis to connect channel choices with customer understanding and compliance considerations.
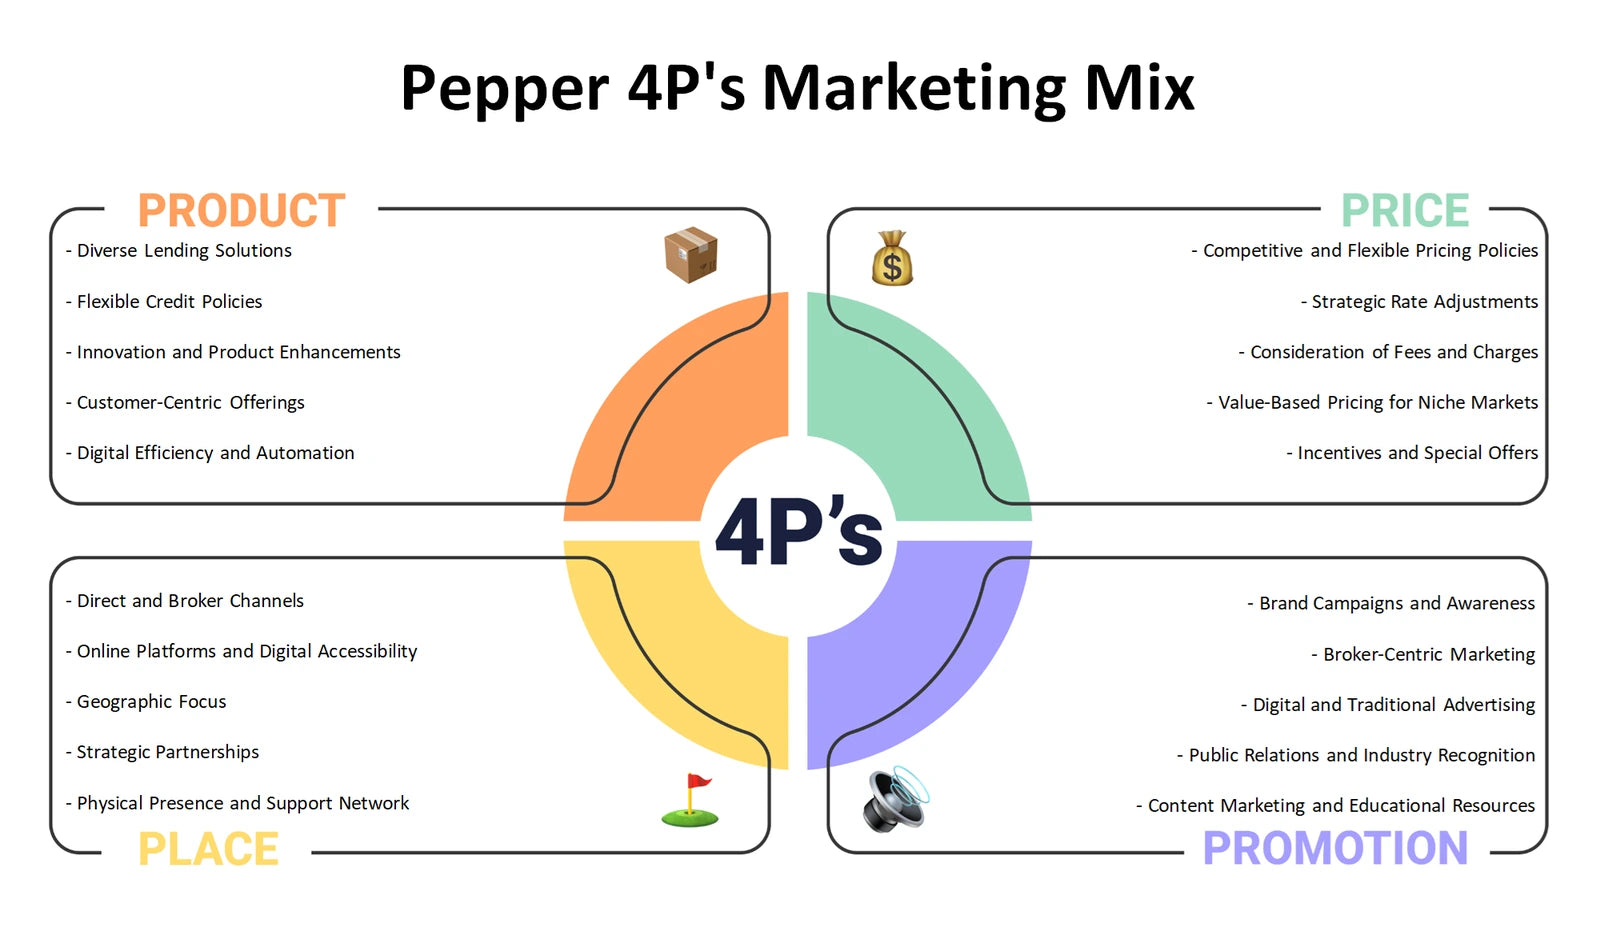
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external shifts could alter borrower demand, intermediary economics and the operating conditions for non-bank lending?
A Pepper PESTLE analysis, also commonly called PESTEL, organizes Political, Economic, Social, Technological, Legal and Environmental influences. Political and legal topics can include policy direction, lending conduct, privacy and consumer-protection obligations; the framework does not presume a particular new law. Economic questions may cover funding conditions, household or business confidence and repayment pressure. Social expectations around transparency and service, technology changes in digital origination and data security, and environmental shifts affecting vehicles or financed equipment can all reshape decisions outside the company's direct control.
- External signals. Distinguish documented developments from items that should be monitored, especially where changes could affect borrowers or introducer partners.
- Transmission paths. Trace how an external factor might flow through demand, affordability, credit assessment, operational processes or partner relationships.
- Monitoring agenda. Use the Excel framework to classify signals by PESTLE category, then use the Word analysis to record implications, assumptions and review questions.
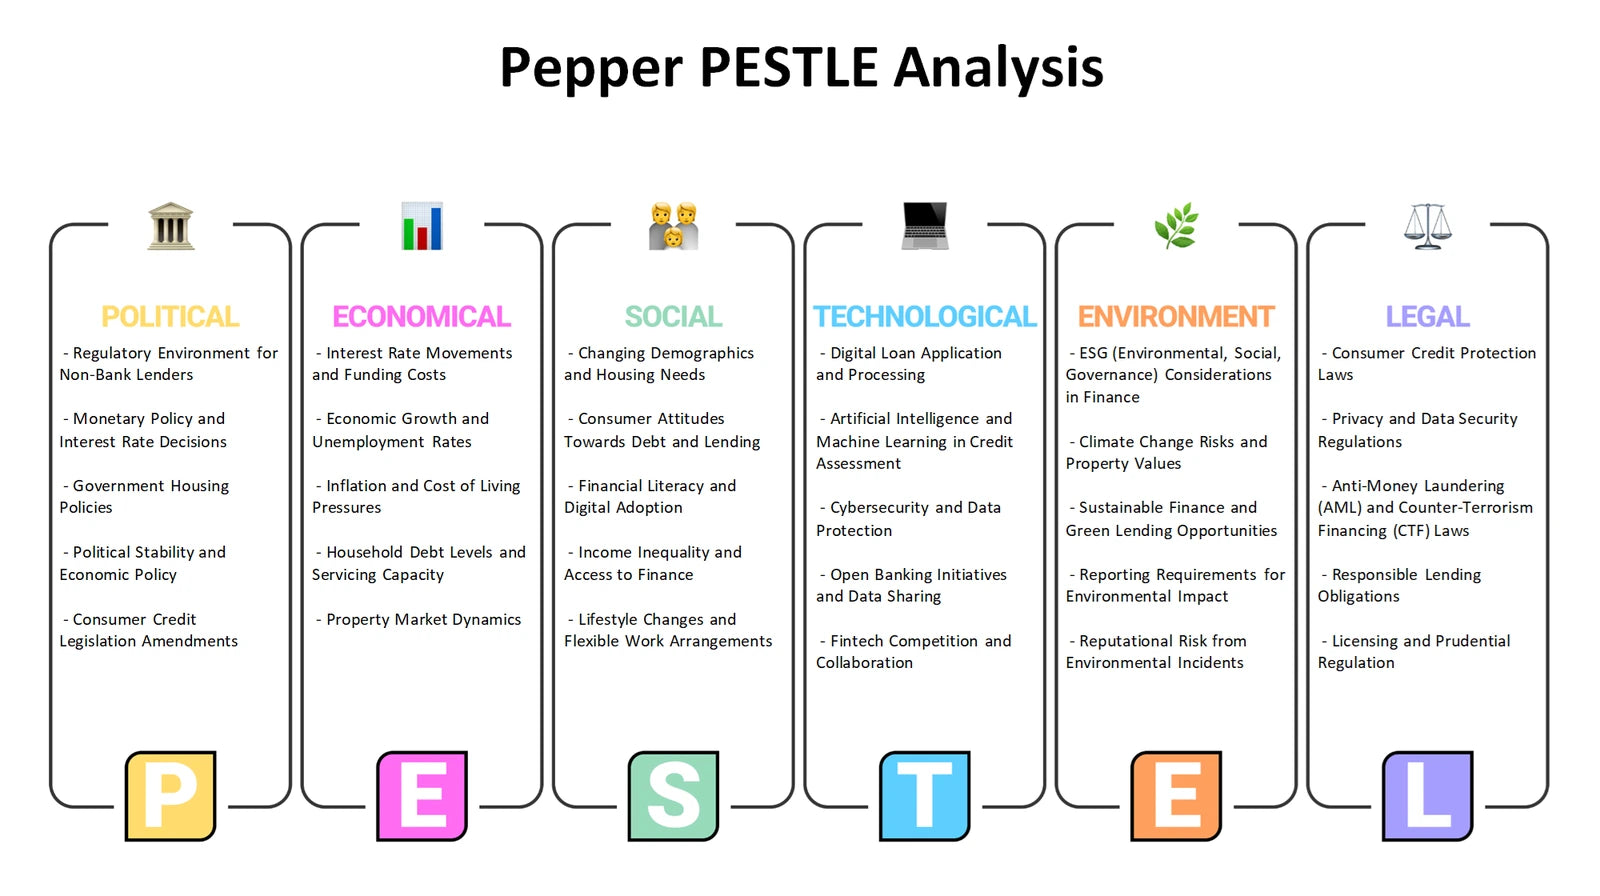
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal capabilities and constraints should Pepper weigh against opportunities and threats in its lending environment?
A Pepper SWOT analysis separates internal Strengths and Weaknesses from external Opportunities and Threats. The available context suggests useful themes to test rather than proven conclusions: the quality of broker support, knowledge of non-bank lending, introducer relationships and asset-finance access may be internal capabilities to assess. Dependence on particular routes, operational complexity or resource requirements may be possible internal constraints. Opportunities and threats belong outside the company, such as changing customer needs, competitive conditions, technology developments or regulatory expectations. Keeping these categories separate makes proposed actions more accountable.
- Evidence discipline. Test whether a perceived capability is repeatable and controllable before treating it as a strength, and identify what would validate a weakness.
- Strategic fit. Match external opportunities or threats with relevant internal responses instead of treating every market trend as automatically actionable.
- Decision bridge. Use the Excel framework to distinguish internal from external factors, with the Word analysis supporting prioritisation questions and evidence notes.
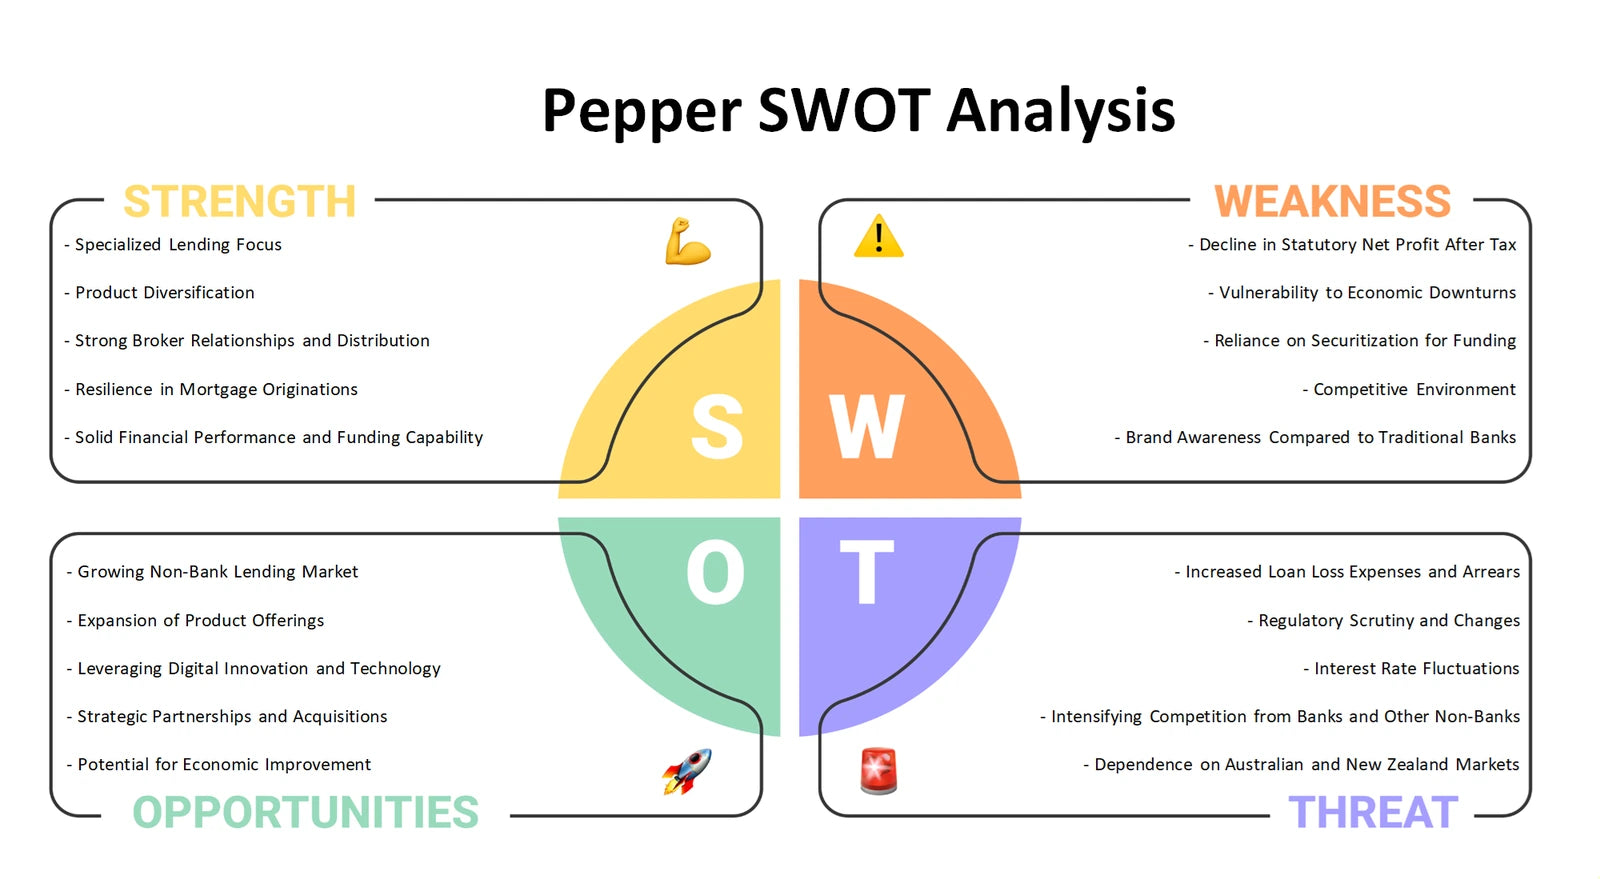
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices to the business behind them
Together, the six perspectives move from portfolio priorities and value creation to competitive pressure, customer routes, external change and strategic fit. The Excel frameworks provide a structured way to compare issues and record assumptions, while the detailed Word analyses help develop the reasoning behind decisions affecting Pepper's lender, broker, dealer and introducer relationships.
Company background: Pepper — third-party Pepper Money business-model context.