

Orrstown Bank: Banking Business and Product Innovation – Six-Framework Review

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Orrstown Bank Strategy Analysis Bundle
This bundle examines Orrstown Bank in the Pennsylvania banking and regulatory context identified in the supplied company material. Its operating model connects deposit and lending relationships with digital banking access, requiring the bank to balance customer convenience, prudent risk management, security and service quality.
The supplied context highlights oversight involving the FDIC and Pennsylvania Department of Banking and Securities, alongside technology and fintech-provider relationships supporting digital banking and cybersecurity. Those circumstances make portfolio focus, customer economics, industry pressure and external change useful questions for the six connected strategy frameworks in this bundle.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking products, customer propositions or service priorities deserve attention when growth potential is weighed against relative market share?
An Orrstown Bank BCG Matrix helps organise potential portfolio choices without assuming that any product already belongs in a particular quadrant. It applies market growth and relative market share to possible banking activities, such as deposit relationships, lending propositions or digital-service priorities. The Stars, Cash Cows, Question Marks and Dogs categories are analytical tools for comparing where resources may be committed, defended, tested or reduced. For a regulated bank, that comparison matters because growth can require capital, operational capacity, credit discipline and secure customer support rather than promotional spending alone.
- Portfolio lens. Compare business areas by their local-market relevance, competitive position and capacity demands instead of treating every offering as equally strategic.
- Resource trade-off. Consider whether investment in digital access, relationship banking or product development could support growth while preserving dependable service and risk controls.
- Structured review. Use the Excel matrix to sort candidate activities and the detailed Word analysis to document the assumptions behind each possible quadrant discussion.
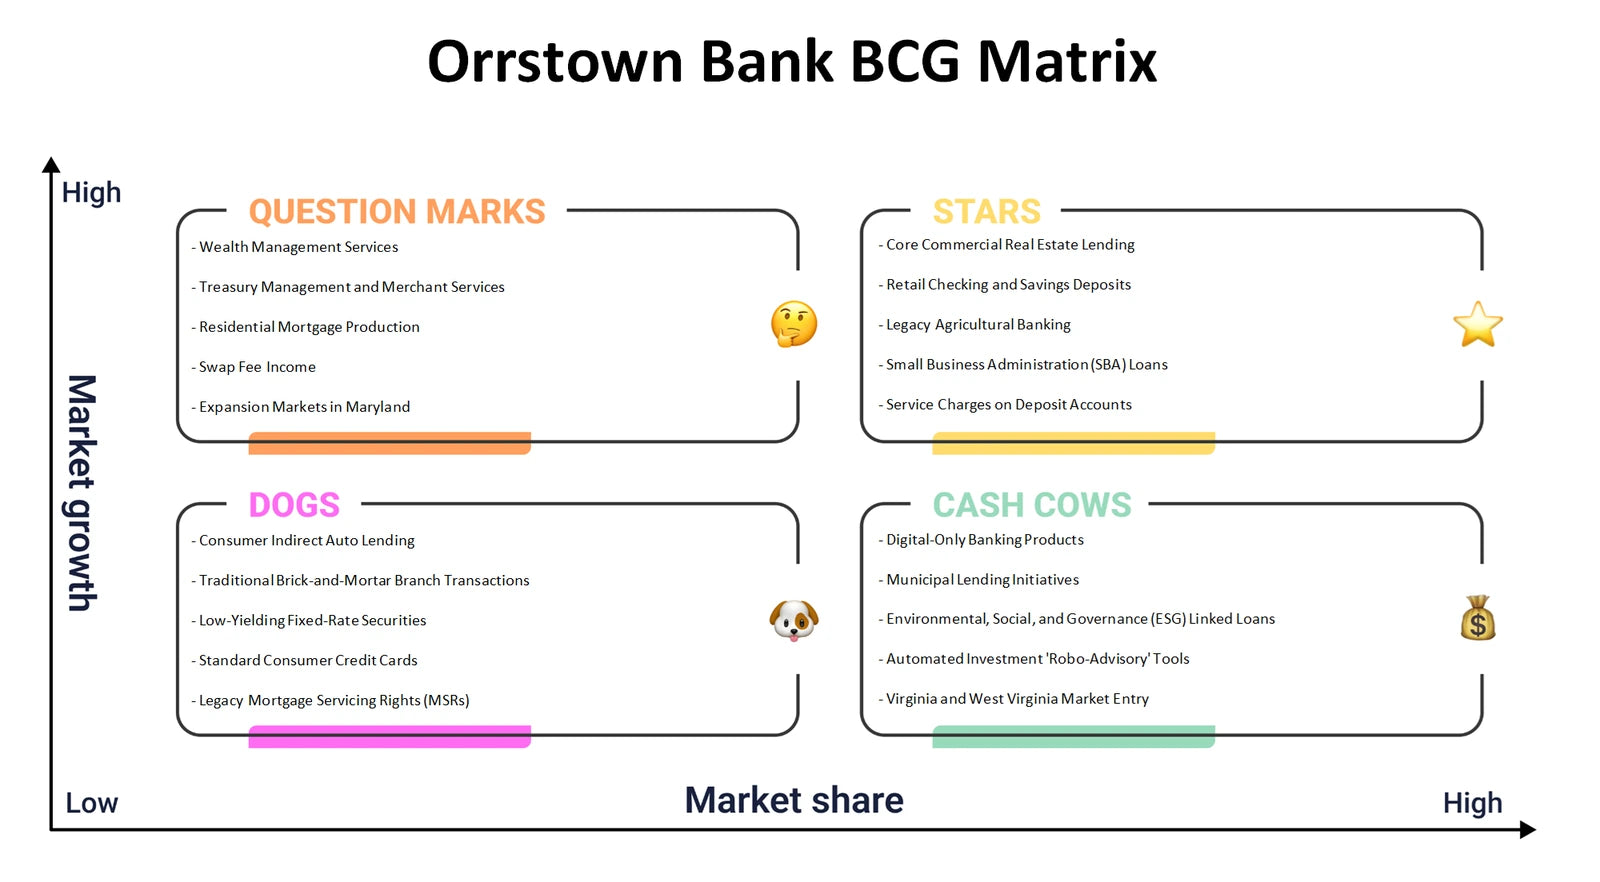
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer needs, regulated delivery, digital access and banking economics fit together in one operating model?
The Orrstown Bank Business Model Canvas connects all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. It helps examine how depositors and borrowers may receive value through banking relationships and online or mobile channels, while the bank earns through its banking revenue logic and bears the costs of compliance, technology, service and risk management. The supplied context makes technology and fintech relationships especially relevant to the partnerships and resources discussion, but the framework also tests how those relationships connect to customer experience and sustainable economics.
- Customer-to-channel fit. Map possible customer segments against relationship needs, digital touchpoints and the service expectations attached to secure banking access.
- Economic connections. Trace how revenue streams depend on key activities, resources and operating costs rather than viewing products in isolation.
- Model mapping. Populate the Excel canvas as a concise working map, then use the Word analysis to explore the reasoning and dependencies within each building block.
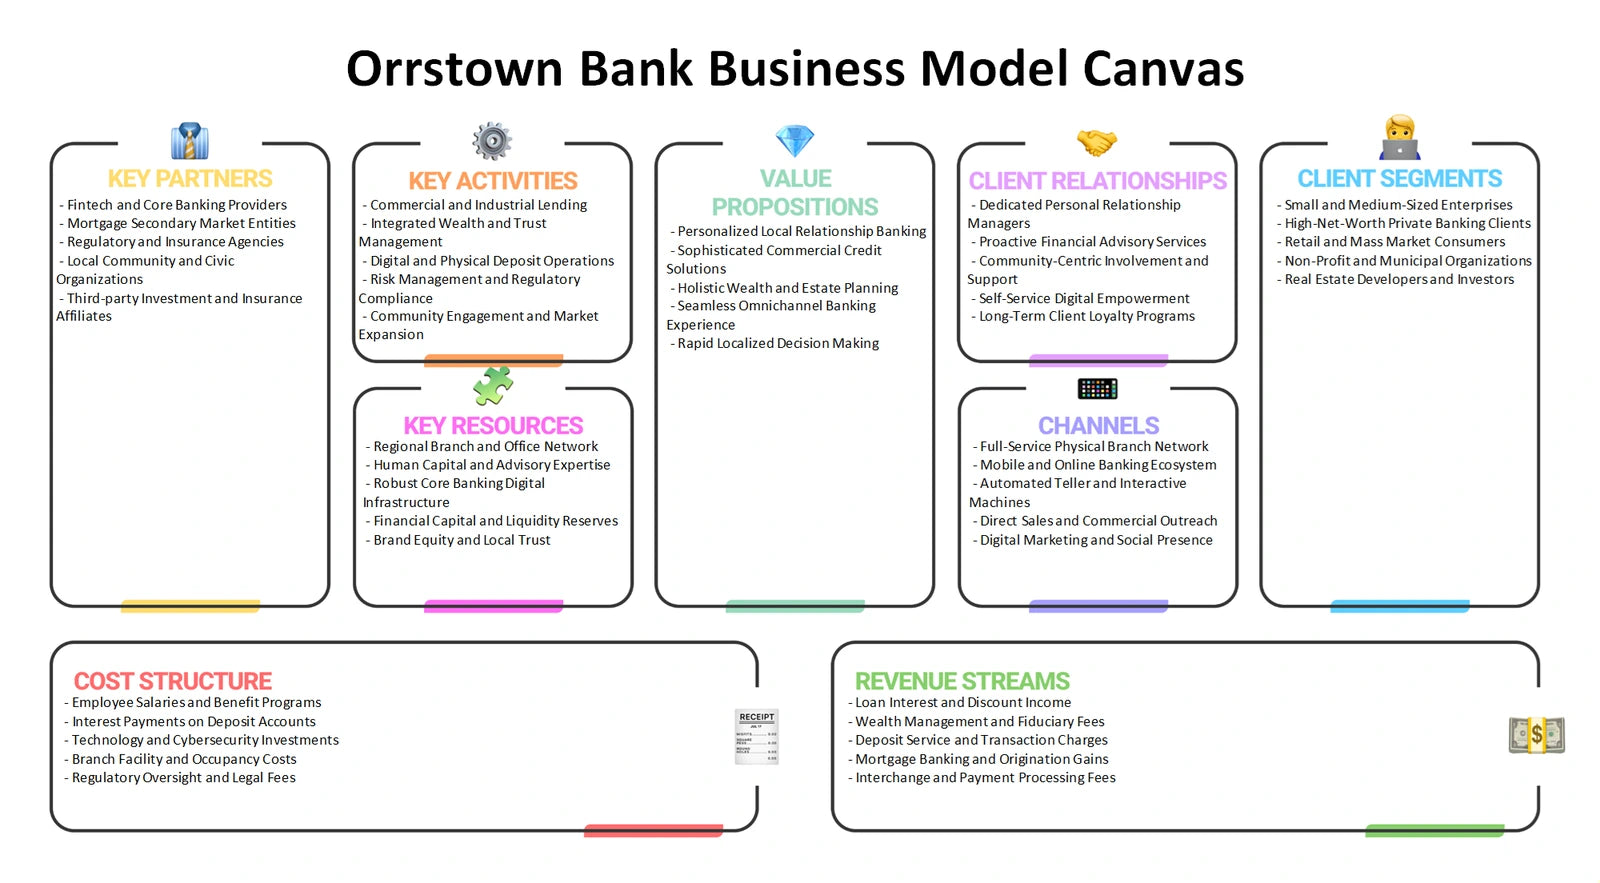
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can affect Orrstown Bank's ability to retain relationships, price services and fund secure delivery?
Orrstown Bank Porter's Five Forces analysis examines rivalry among banking providers, buyer power held by customers able to compare accounts or borrowing options, and supplier power from technology, specialist service and funding dependencies. It also considers the threat of new entrants, including digitally oriented financial providers, alongside banking charter and compliance barriers. Substitutes extend beyond direct banks: customers may meet payment, saving, credit or financial-management needs through other forms of financial service. This lens does not assign force scores; it provides a disciplined way to distinguish competitive pressure from the operational requirements of a regulated banking business.
- Relationship pressure. Assess where customers may have choice and where trust, convenience, pricing and responsive service could influence retention.
- Dependency exposure. Examine how technology providers, cybersecurity needs and specialised banking infrastructure can shape supplier leverage and resilience.
- Force comparison. Use the Excel framework to compare the five pressures consistently, with the Word analysis providing context for why each pressure matters to banking decisions.
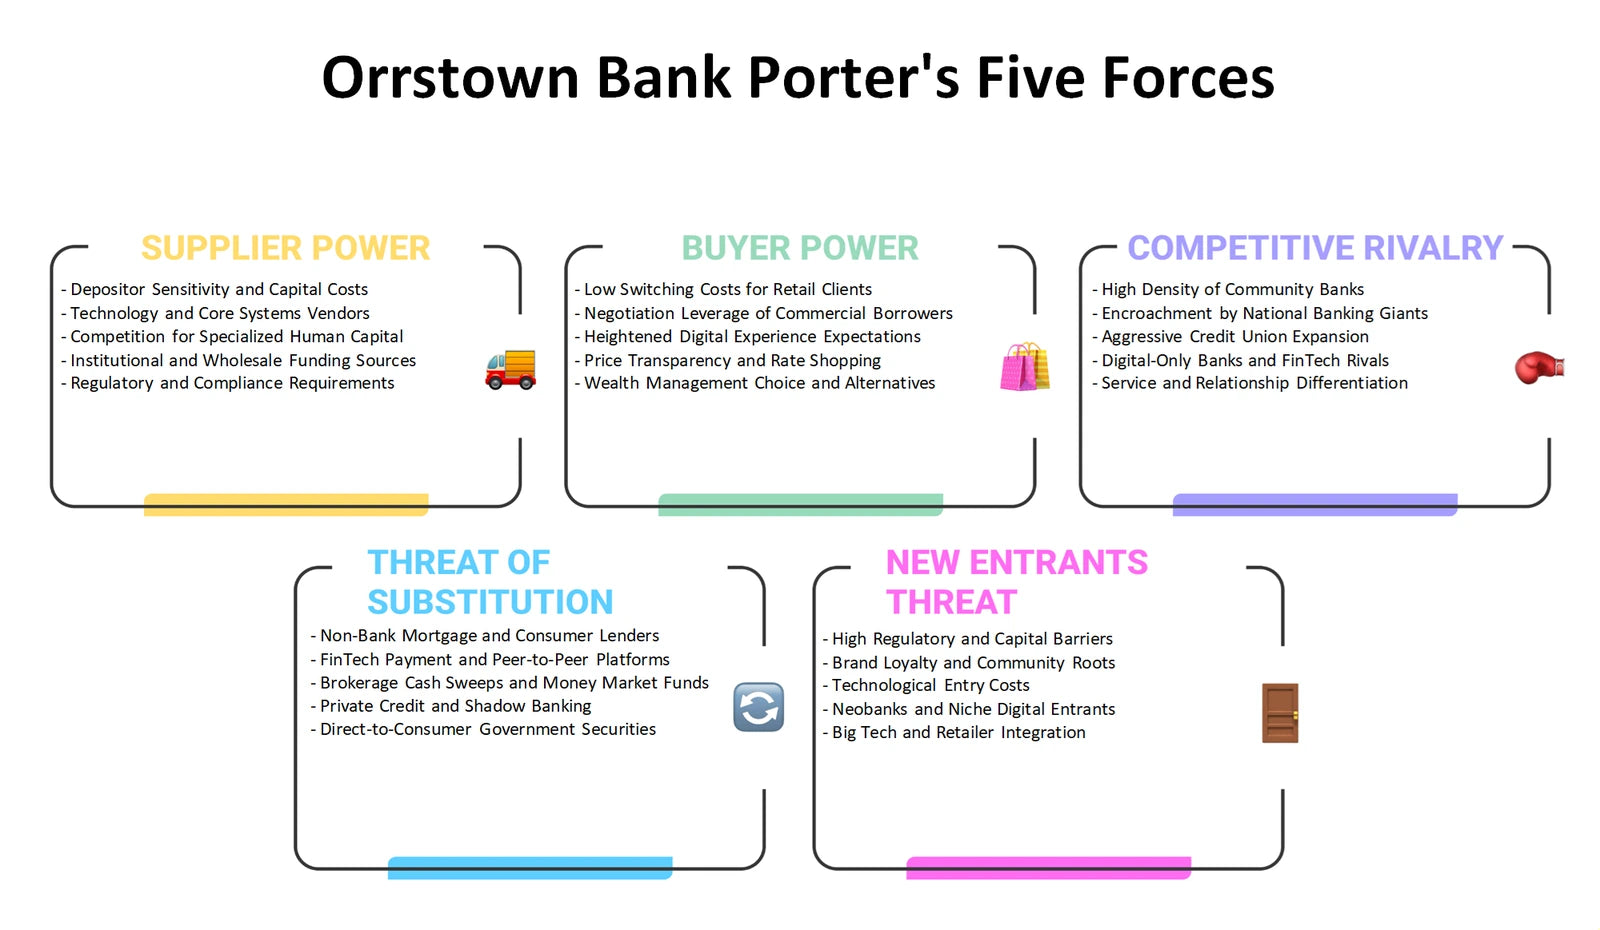
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a regulated bank align its services, pricing logic, access routes and communications with customer trust?
The Orrstown Bank Marketing Mix considers Product, Price, Place and Promotion in a banking setting where the service experience is closely tied to confidence and compliance. Product can cover the way deposit, lending and digital banking needs are framed for customers. Price examines rate, fee and value considerations without inventing actual prices. Place includes relationship-based access and digital channels, where usability and security both affect convenience. Promotion considers clear, responsible communication rather than assuming any specific campaign. Together, the 4Ps help test whether the customer proposition is consistent from first message through account use and ongoing service.
- Service proposition. Examine how financial products and digital capabilities can be described in ways that match distinct customer needs and risk-aware expectations.
- Access consistency. Compare in-person and digital routes to customers, focusing on convenience, support and the importance of secure authentication.
- Planning application. Organise 4Ps observations in the Excel framework and use the Word analysis to connect communication choices with service delivery and pricing considerations.
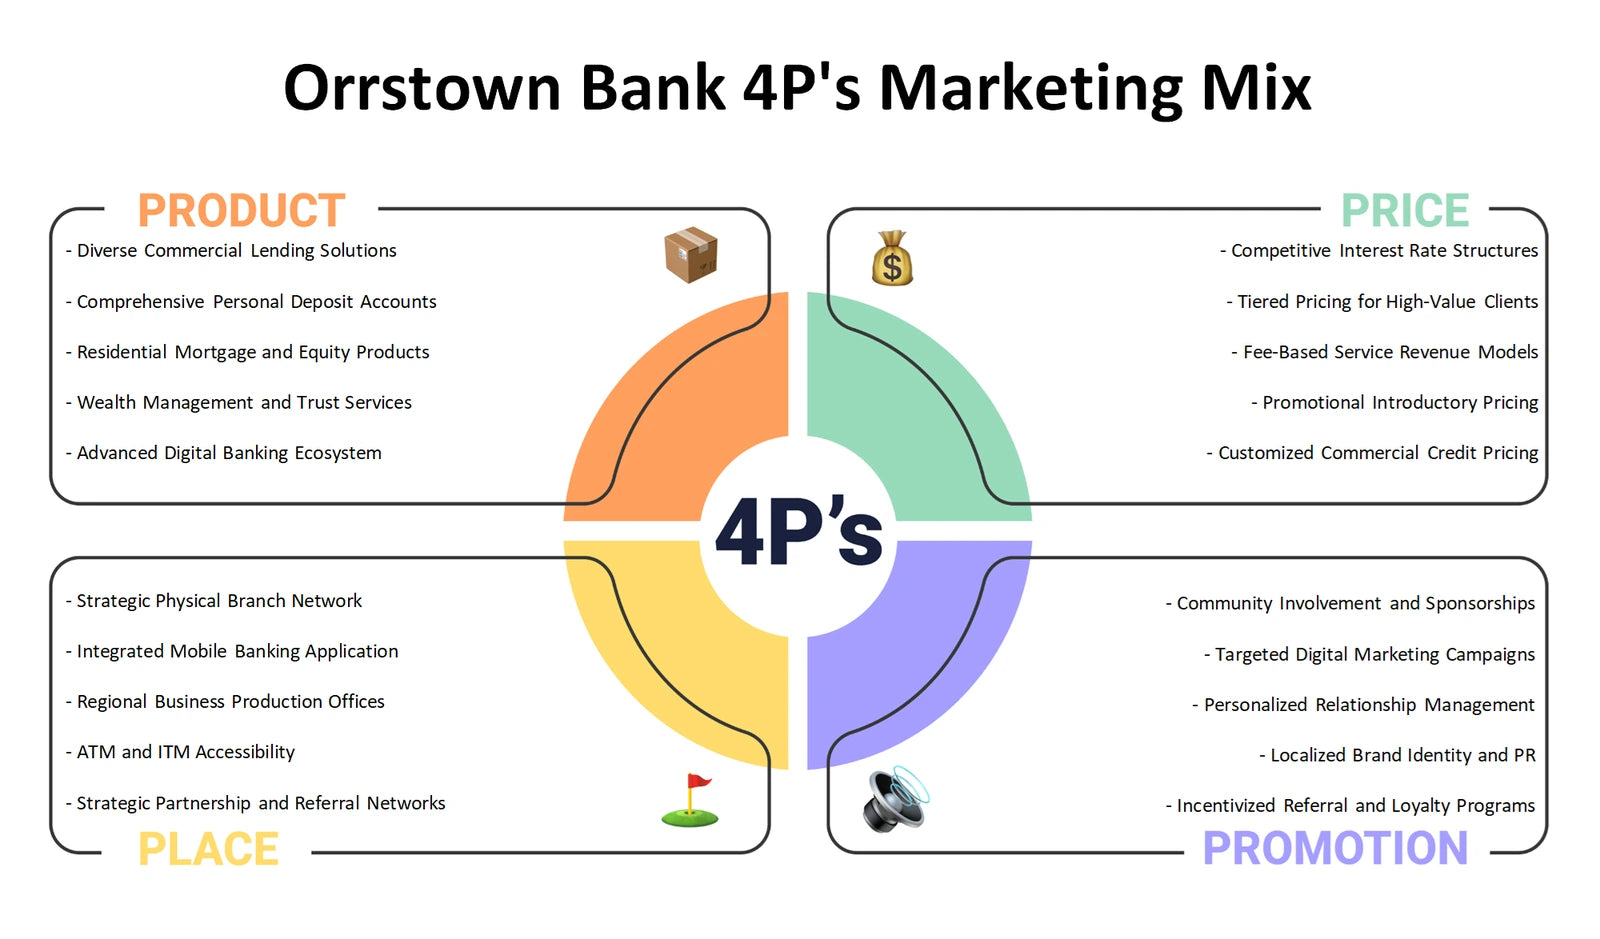
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes should be monitored because they may alter banking demand, compliance obligations or digital operating requirements?
An Orrstown Bank PESTLE analysis, also commonly called PESTEL, scans Political, Economic, Social, Technological, Legal and Environmental influences around the bank. Political and legal factors include the continuing importance of banking supervision and regulatory expectations. Economic questions can examine changing borrowing, saving and credit conditions without claiming a current rate environment. Social factors address evolving preferences for convenient, understandable financial services. Technology brings digital-platform, fraud and cybersecurity considerations, while environmental factors can inform questions about physical continuity, customer needs and risk awareness. The framework distinguishes external conditions to monitor from documented company outcomes.
- Regulatory horizon. Track questions arising from federal and Pennsylvania banking oversight, including how changing expectations may affect processes and customer communications.
- Digital resilience. Consider how technology adoption, cybersecurity threats and third-party dependencies can change the requirements for secure banking access.
- External scan. Use the Excel categories to record signals and implications, then consult the Word analysis to interpret how external forces may connect across the business.
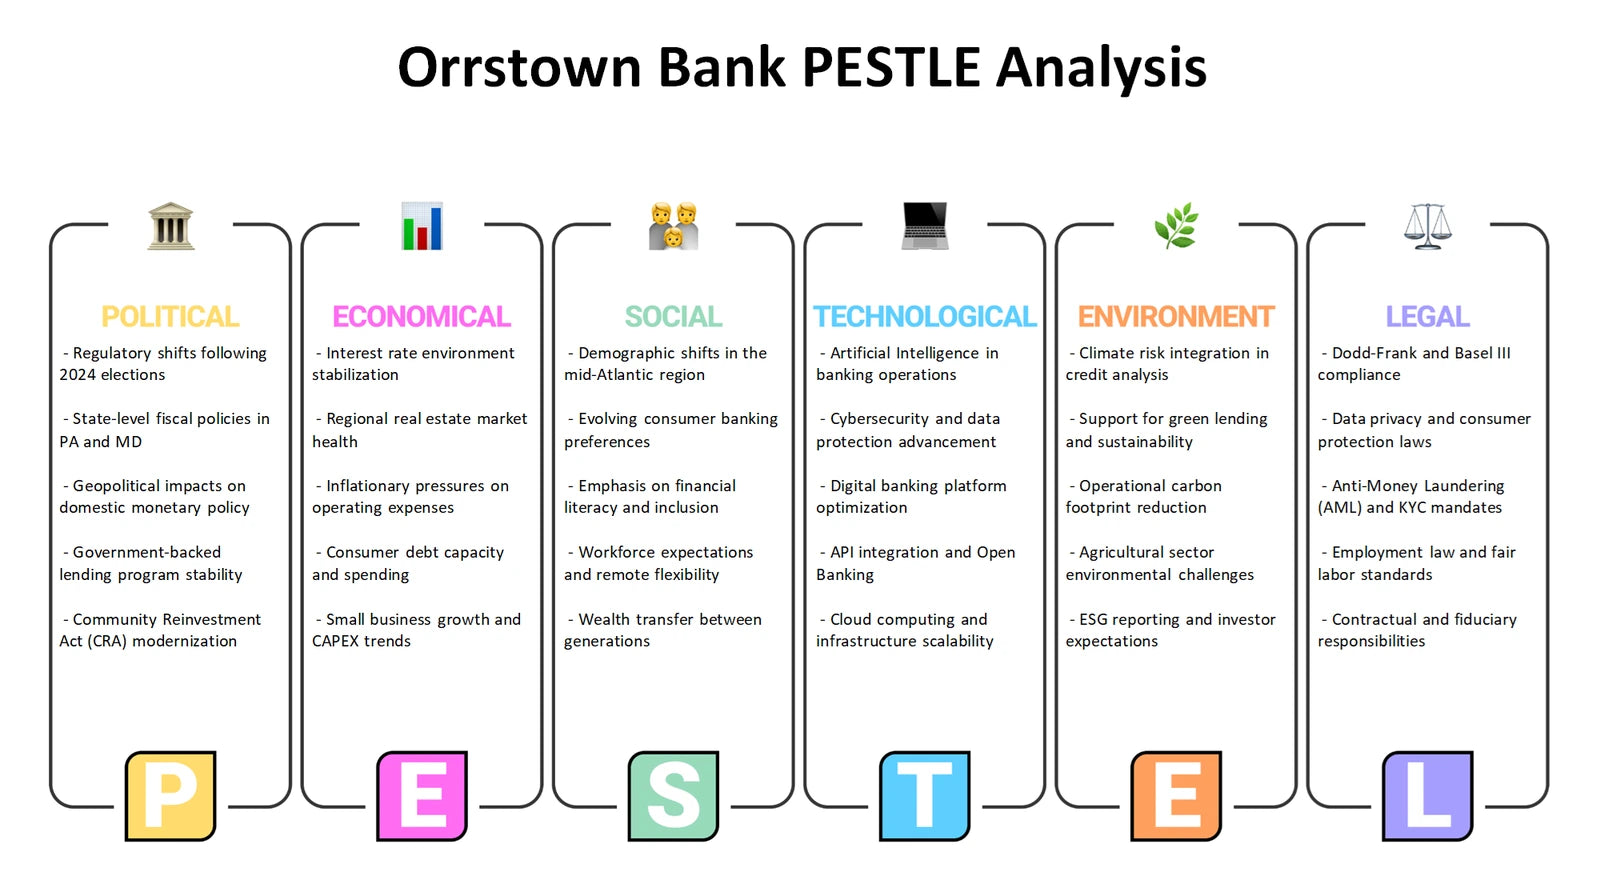
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Orrstown Bank distinguish its internal capabilities and constraints from external opportunities and threats?
The Orrstown Bank SWOT analysis separates internal Strengths and Weaknesses from external Opportunities and Threats. Internal discussion can examine capabilities relevant to regulated banking, customer relationships, digital delivery, technology governance and operational discipline. Weaknesses are internal limitations or capability gaps to investigate, not assumed defects. Opportunities and threats arise outside the organisation, such as changing customer expectations, financial-service alternatives, regulatory developments or cybersecurity risks. This distinction is valuable because an external market shift should not be labelled a weakness, and an internal capability should not automatically be treated as an opportunity. The framework supports a more precise strategic conversation than a simple list of positives and negatives.
- Capability boundary. Separate matters the bank can influence directly, such as service processes and technology governance, from market and regulatory conditions it must respond to.
- Strategic pairing. Explore how a potential internal strength could support an external opportunity, or how a limitation could increase exposure to a threat.
- Decision record. Use the Excel grid to classify evidence and discussion points, while the Word analysis helps develop the implications behind each potential pairing.
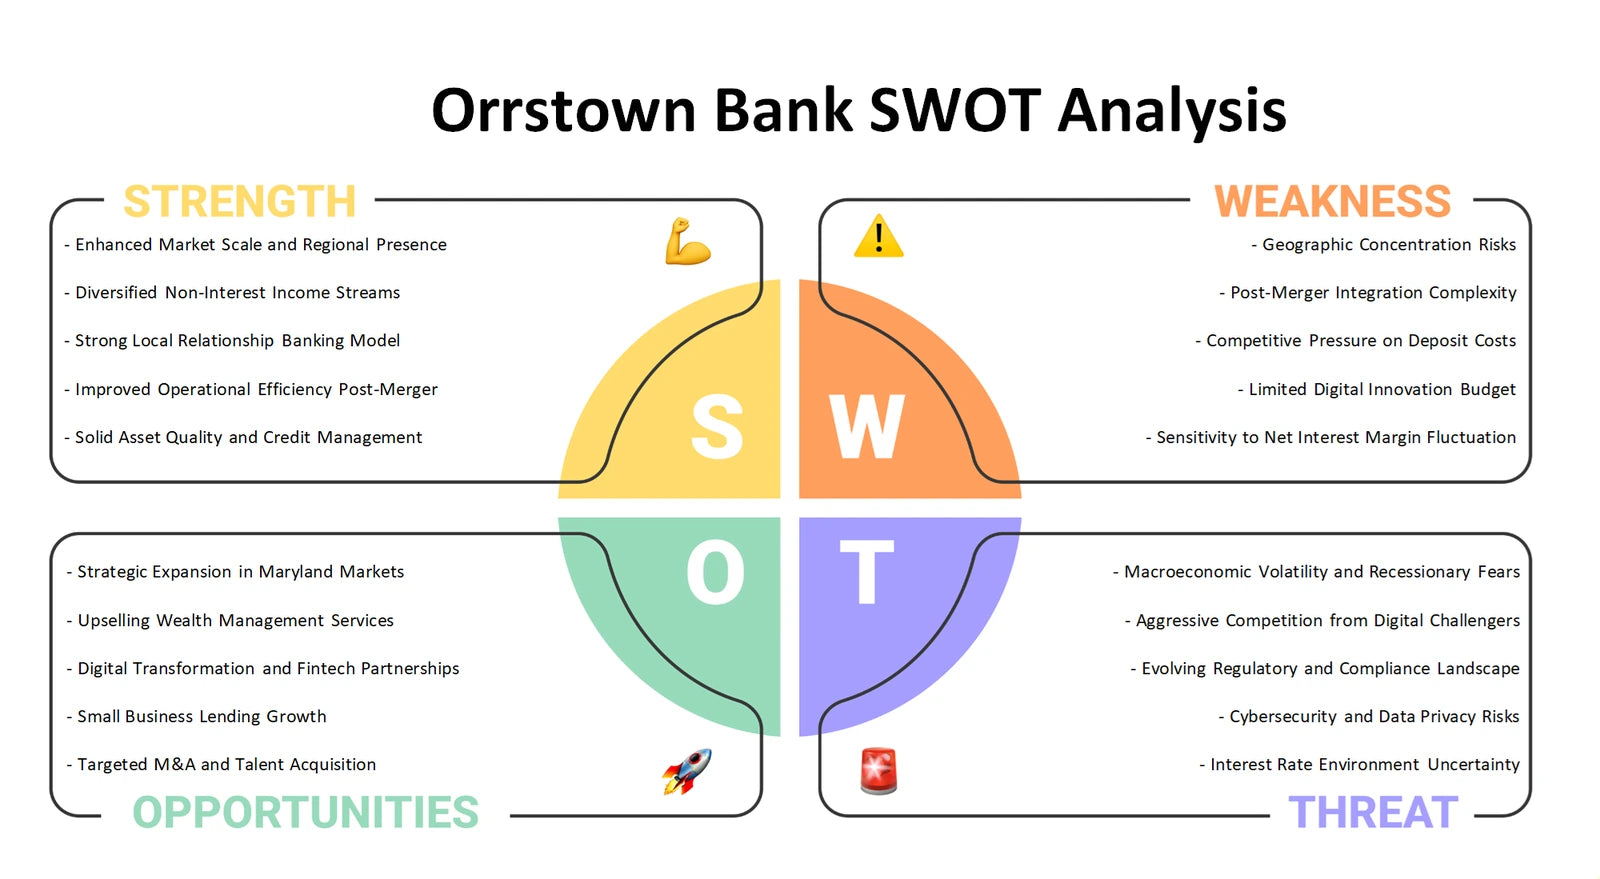
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of banking strategy
Used together, the six perspectives move from portfolio priorities and value creation to industry pressure, customer delivery, external conditions and strategic fit. The Excel frameworks provide structured places to compare issues, while the Word files provide detailed company analysis that can support more informed discussion of Orrstown Bank's banking model, digital priorities and operating context.
Company background: Orrstown Bank — Business Model Canvas product context.