

OneMain Holdings: Financial Services and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
OneMain Holdings Strategy Analysis Bundle
OneMain Holdings is the workbook display name for the U.S. consumer-finance business represented publicly by OneMain Financial. Its website describes personal loans for needs including home improvement, debt consolidation and vehicle purchases. The business therefore operates where consumers seek installment credit for planned projects or unexpected expenses, and where underwriting, servicing and trust shape the customer experience.
That lending focus makes portfolio priorities, customer economics and external risk closely connected. The bundle helps examine how personal-loan propositions, credit-data inputs, customer acquisition, optional protection products and complementary credit access may fit together, while keeping analytical questions distinct from documented company conclusions.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending and adjacent propositions merit investment, harvesting, testing or tighter limits?
The OneMain Holdings BCG Matrix distinguishes analysis from assertion by comparing market growth and relative market share across personal-loan propositions and adjacent credit or protection offers considered in the portfolio. Stars, Cash Cows, Question Marks and Dogs provide a common resource-allocation language, not pre-assigned labels. This matters when underwriting capacity, marketing budgets and compliance attention cannot be expanded without trade-offs.
- Portfolio boundaries. Define comparable offerings, customer needs and markets before judging relative share or growth.
- Capital discipline. Compare where a mature credit need may support cash generation against areas requiring measured experimentation.
- Workbook review. Use the Excel matrix to organize assumptions, then use the Word analysis to document the reasoning behind each priority.
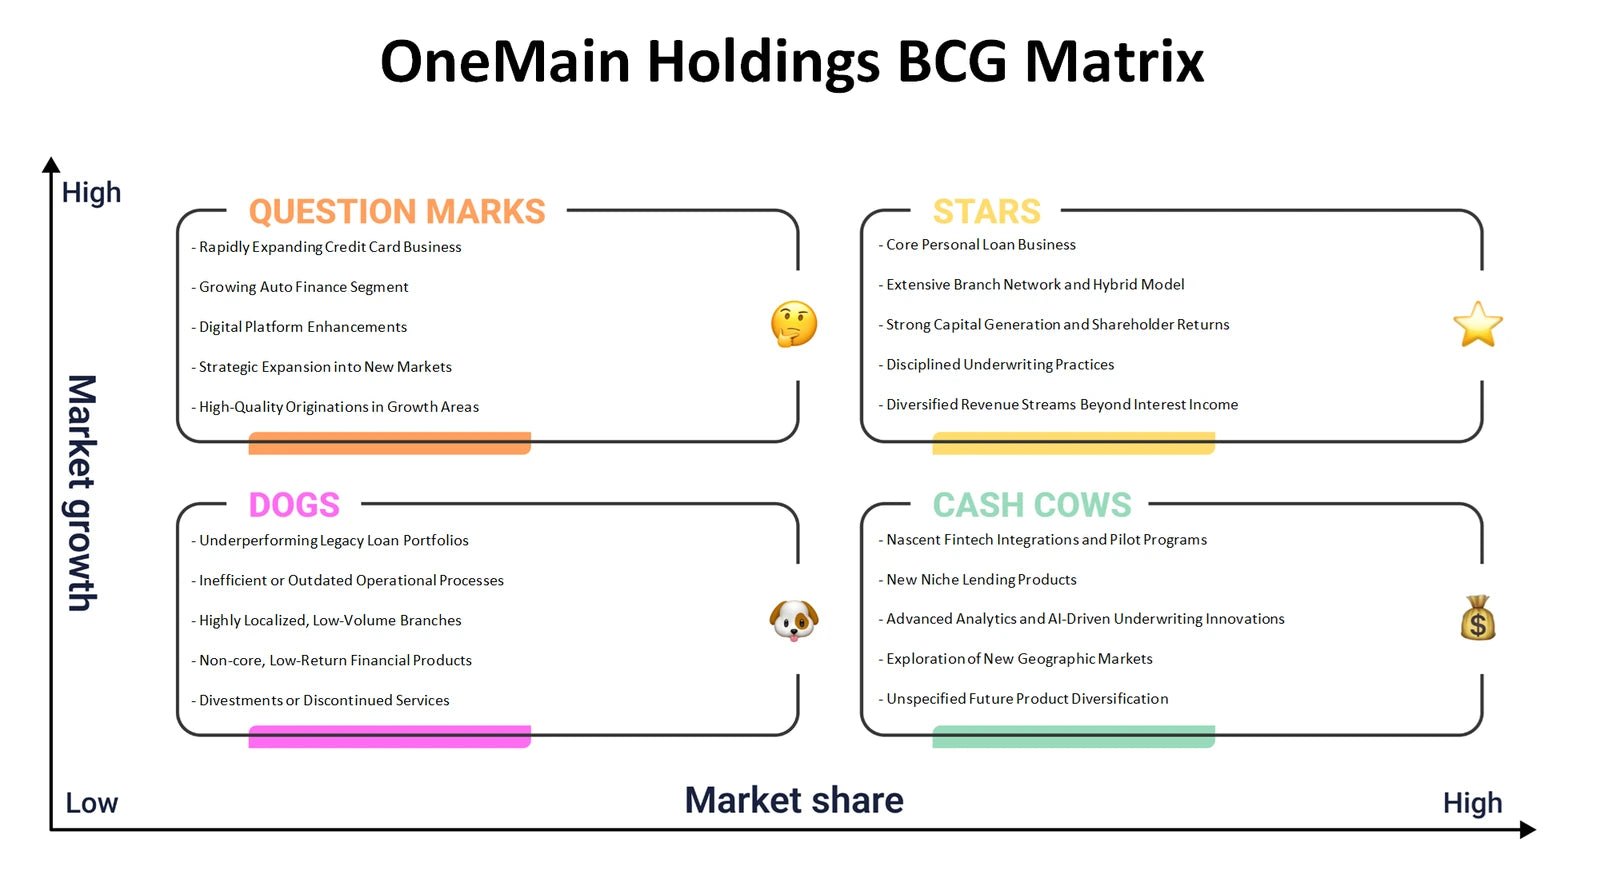
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do consumer needs, underwriting decisions and loan servicing combine into a viable lending model?
The OneMain Holdings Business Model Canvas maps customer segments, value propositions, channels and customer relationships alongside revenue streams, key resources, key activities, key partnerships and cost structure. For a consumer lender, the connections matter: borrowers need understandable access to credit, while the business must originate, price, service and monitor loans responsibly. The framework helps trace how customer value and economic discipline depend on one another.
- Decisioning inputs. Examine how credit-bureau information, verification processes and alternative data questions could affect risk assessment and reach.
- Economics chain. Connect loan-related revenue logic with technology, servicing, funding, compliance and credit-loss cost considerations.
- Model mapping. Populate the Excel blocks systematically and use the Word analysis to explain dependencies that a one-page canvas cannot fully show.
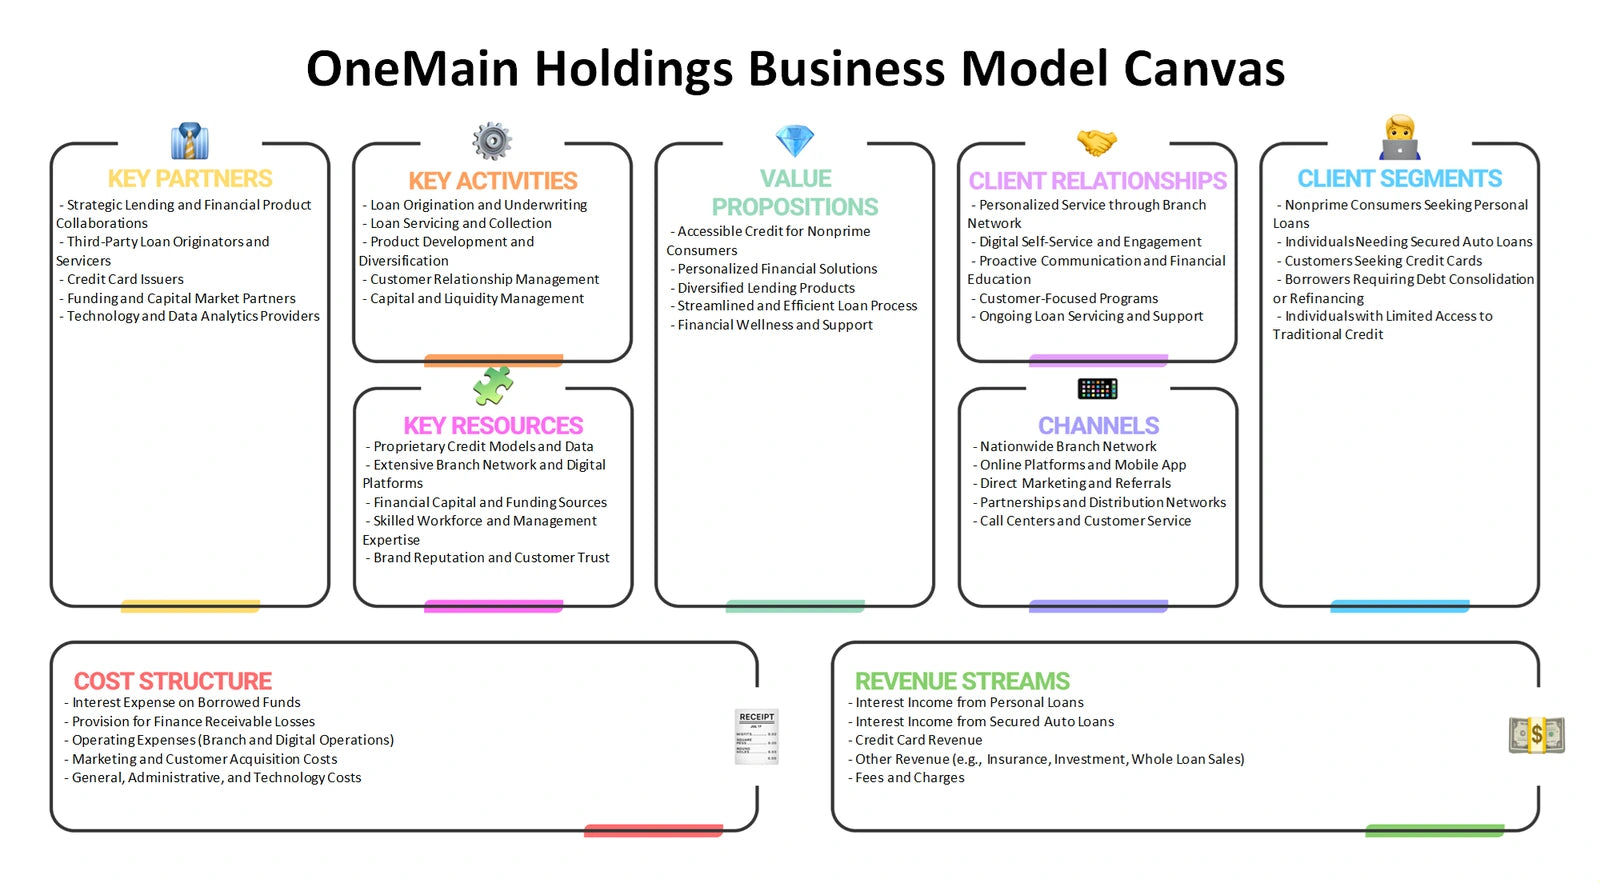
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can influence the attractiveness and resilience of consumer installment lending?
OneMain Holdings Porter's Five Forces frames rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes around the U.S. consumer-credit market. It goes beyond direct lenders: substitutes can include savings, family support, secured borrowing, payment plans or other ways to manage a household expense. The lens helps assess why funding access, risk capability, customer trust and regulatory readiness may affect competitive pressure.
- Rivalry and choice. Consider how borrowers compare convenience, transparency, eligibility, repayment terms and service when seeking credit.
- Inputs and barriers. Review the influence of capital providers, data suppliers, technology vendors, compliance obligations and entrants building digital journeys.
- Force comparison. Use the Excel framework to record evidence and assumptions, with the Word analysis adding context for each pressure.
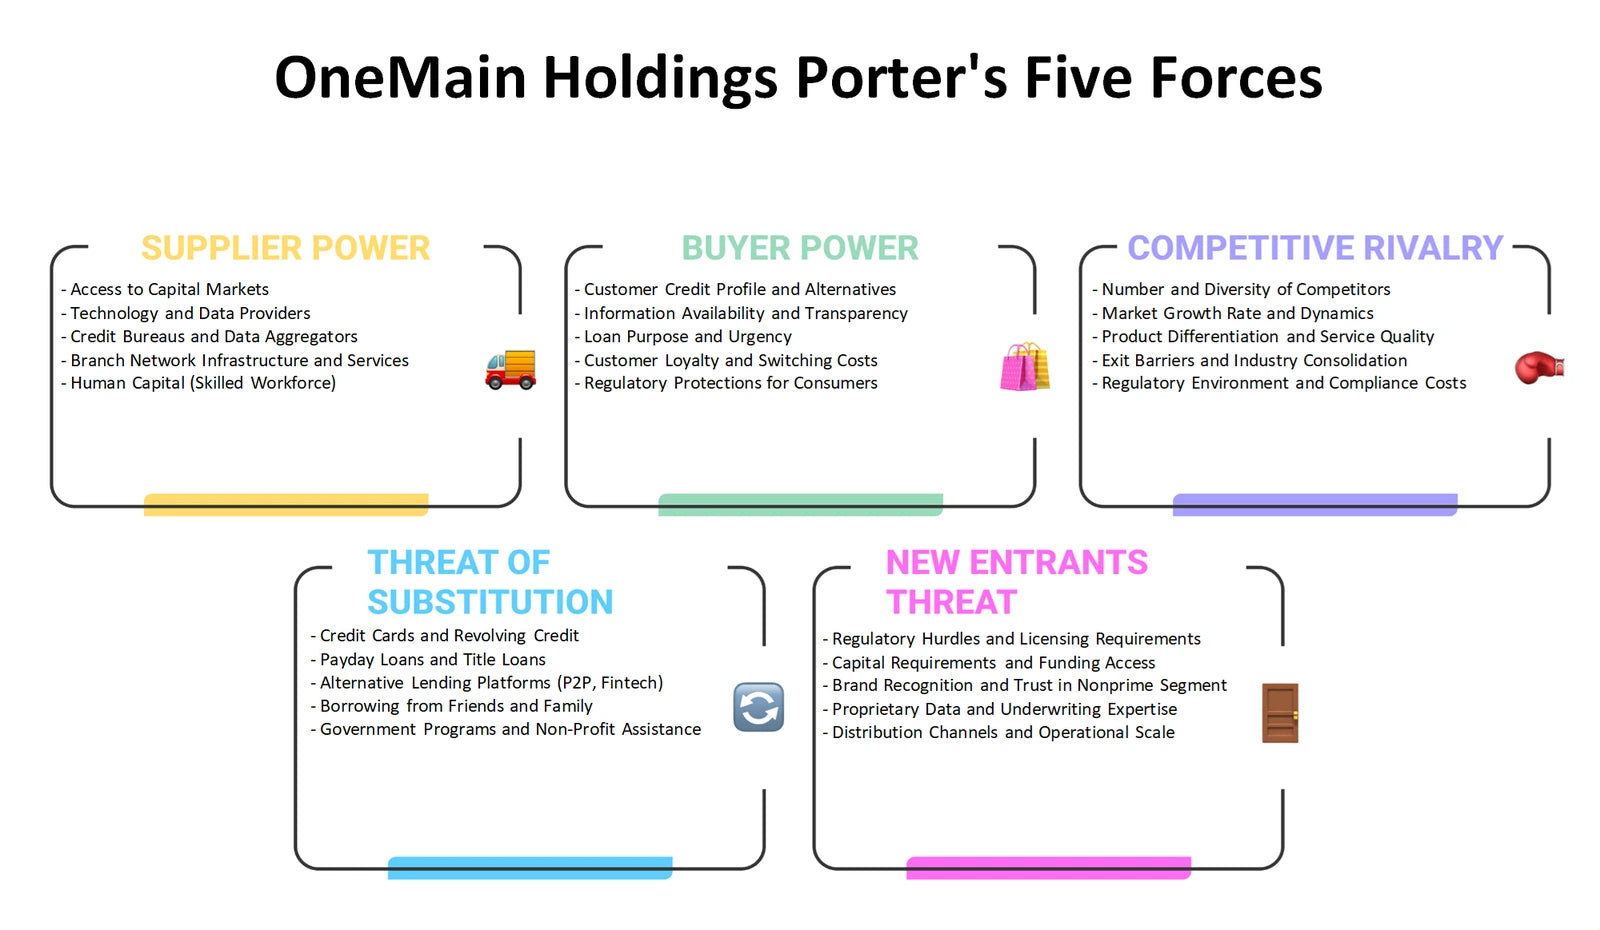
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a consumer lender align its offer, pricing communication, access routes and customer messaging?
The OneMain Holdings Marketing Mix considers Product, Price, Place and Promotion in a regulated consumer-finance setting. Product analysis can compare personal loans with possible complementary card access or optional protection propositions. Price examines how rate, term, fee and repayment disclosures are understood. Place considers digital and assisted routes to customers, while Promotion tests whether messages about intended uses such as debt consolidation or home improvement remain clear and responsible.
- Offer clarity. Assess whether product features and protection choices address a defined borrower need without obscuring repayment obligations.
- Channel fit. Compare where digital convenience, human assistance and servicing touchpoints may matter across customer situations.
- 4Ps planning. Organize product and channel questions in Excel, then use the Word analysis to connect them to customer trust and compliance.
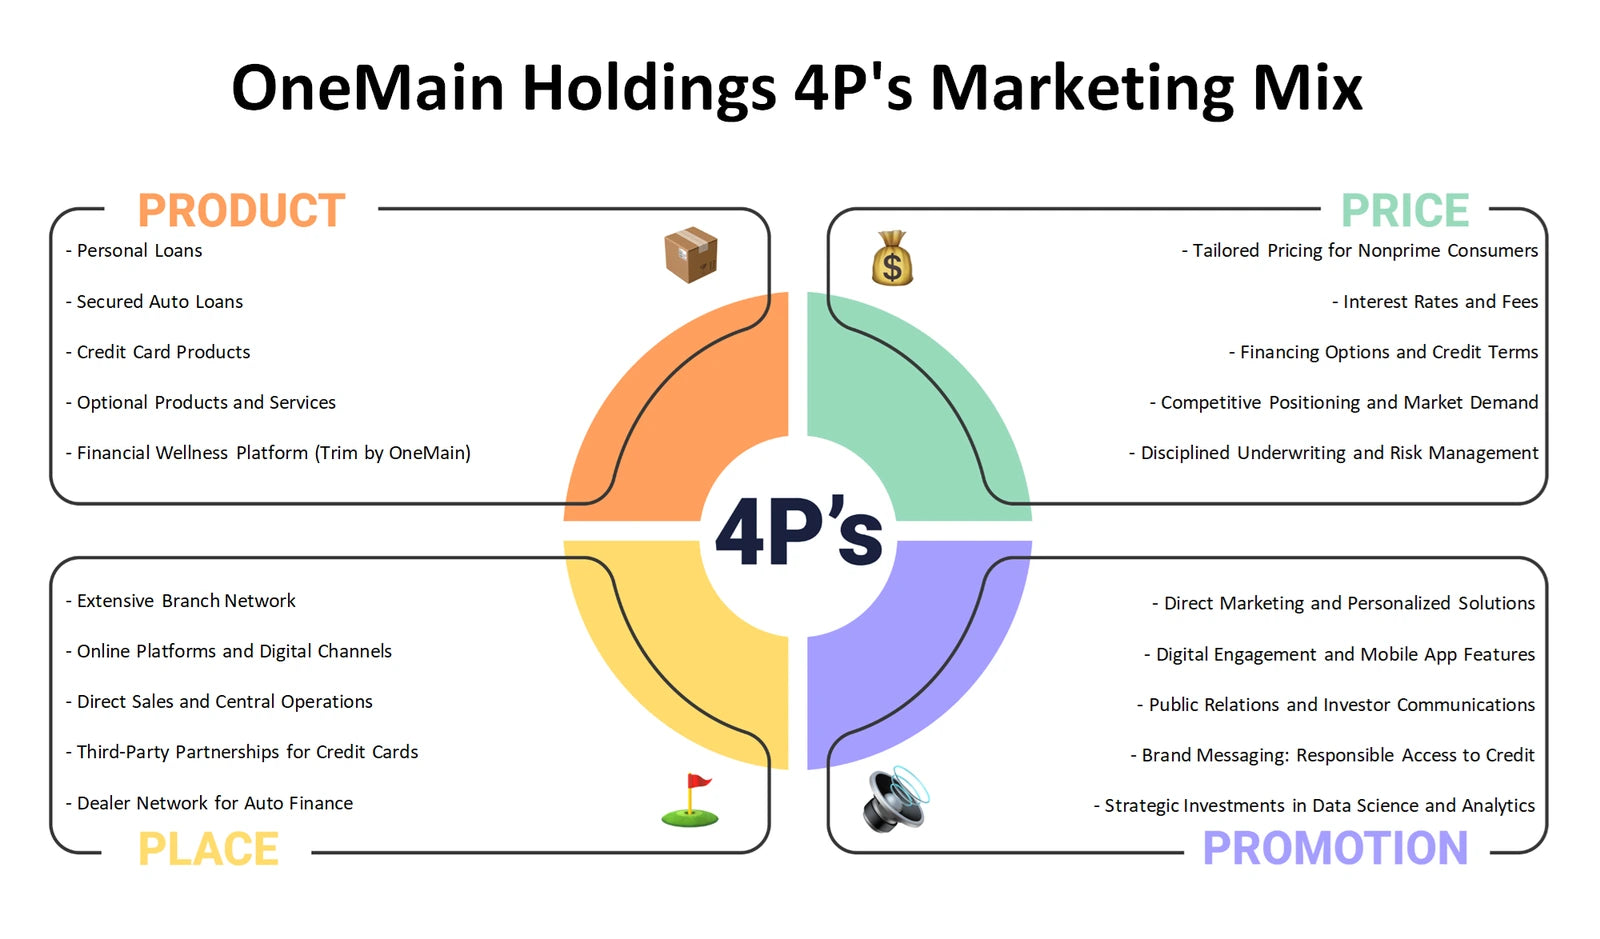
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could reshape demand, risk costs, technology choices and lending oversight?
The OneMain Holdings PESTLE analysis, also commonly called PESTEL, separates Political, Economic, Social, Technological, Legal and Environmental influences on U.S. consumer lending. It can test how policy debates, household financial pressure, changing borrower expectations, automated decisioning, privacy duties and climate-related disruption may affect operations. These are external questions to monitor, not claims that a particular law, interest rate or event has already changed the business.
- Economic sensitivity. Explore how employment conditions, household budgets and credit performance considerations can alter demand and portfolio risk.
- Rules and technology. Review potential implications of licensing, consumer protection, data governance, fraud controls and model oversight.
- External scan. Use the Excel categories to prioritize signals and the Word analysis to preserve the rationale and relevant business links.
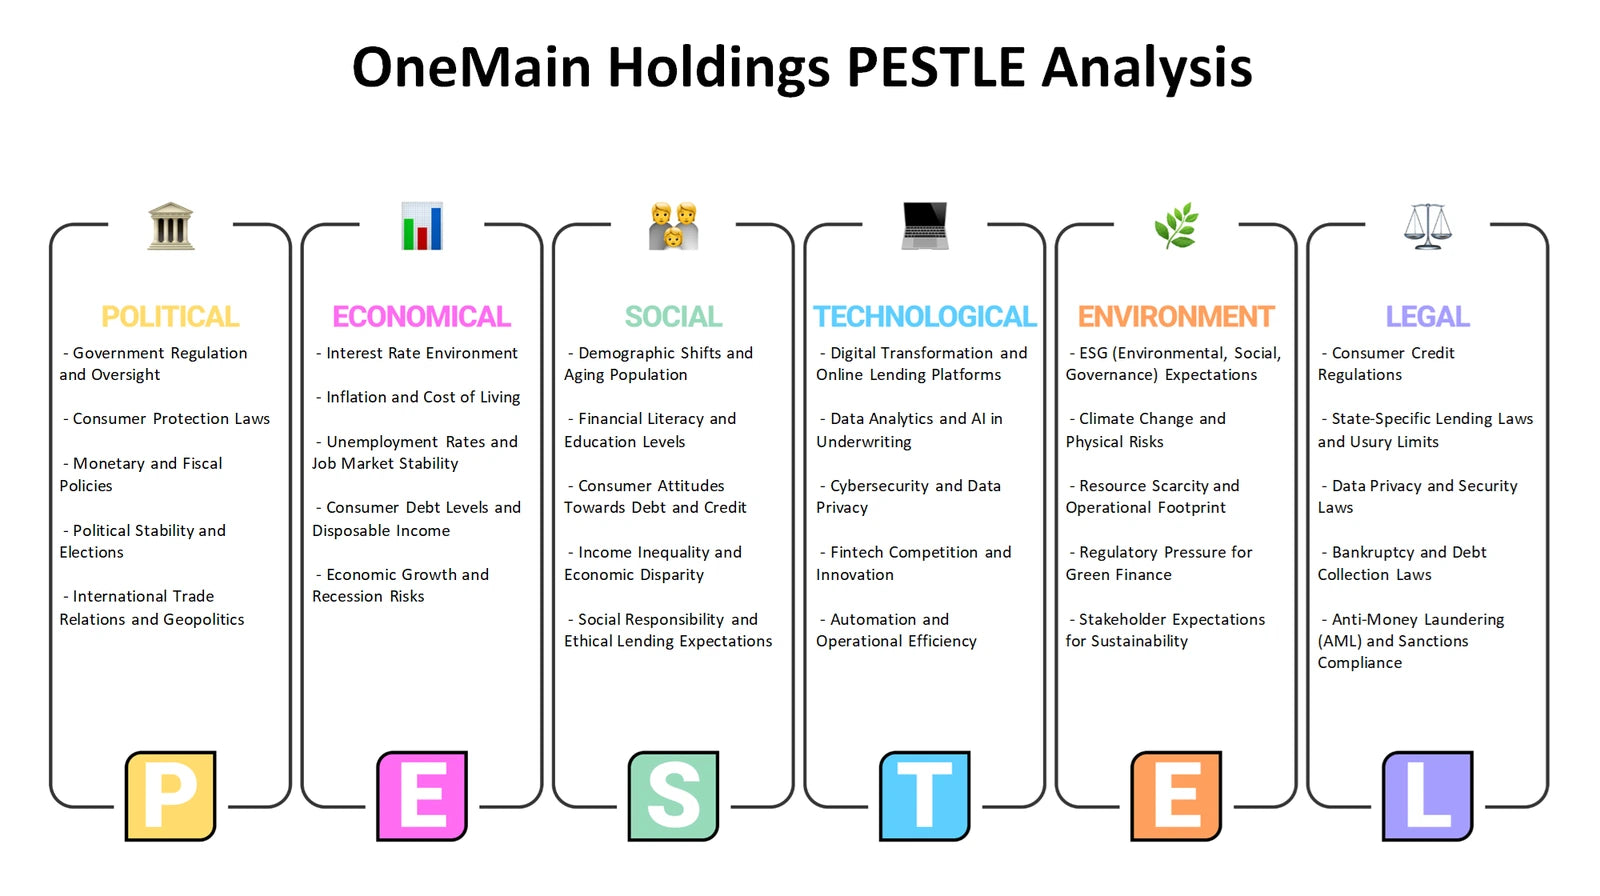
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal capabilities and limitations should be weighed against the opportunities and threats facing consumer credit?
The OneMain Holdings SWOT analysis keeps internal Strengths and Weaknesses separate from external Opportunities and Threats. It can test whether lending experience, servicing capability, customer access routes, credit-data processes or product breadth represent strengths that need validation. It also considers internal constraints such as operating complexity or risk concentration alongside external opportunities in unmet borrower needs and threats from economic stress, substitutes or changing requirements.
- Internal evidence. Classify resources, processes and constraints as internal matters rather than treating market trends as company capabilities.
- External exposure. Compare borrower needs and technology possibilities with credit-cycle, regulatory and reputational risks beyond management control.
- Strategic synthesis. Use the Excel grid to separate categories, then consult the Word analysis to connect credible pairings and questions.
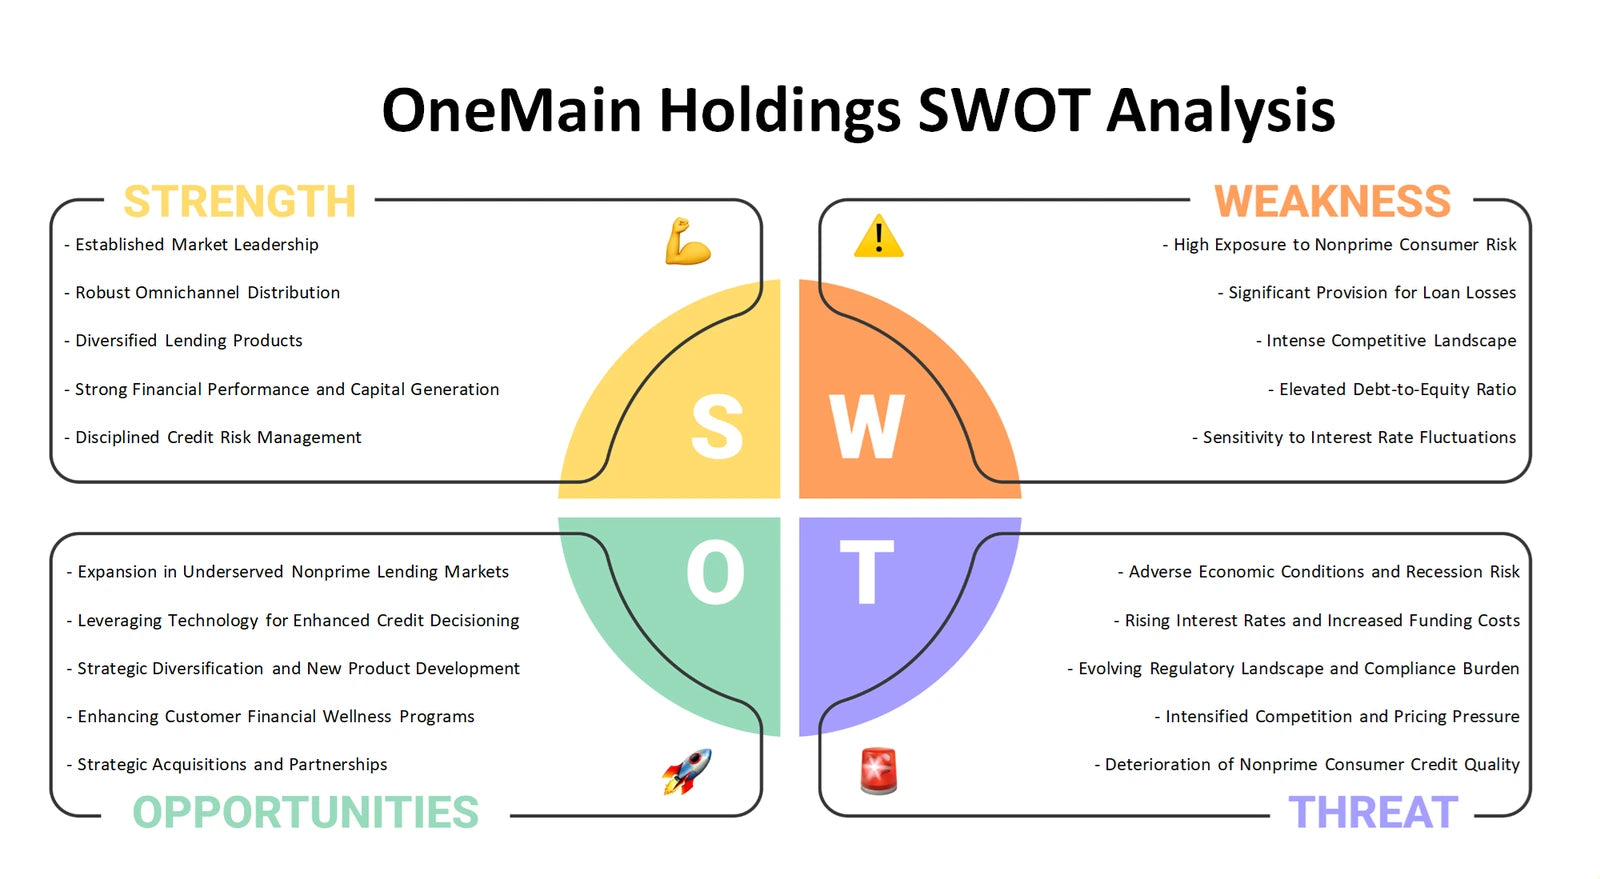
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect the lending model to the strategic choices around it
Together, the six perspectives move from portfolio allocation and business-model logic to competitive pressure, customer-facing choices, external conditions and strategic position. The Excel frameworks help structure comparisons and assumptions, while the detailed Word analysis provides company-specific context for developing more disciplined questions about OneMain Holdings and its consumer-lending model.
Company background: OneMain Financial — official company website.