

OceanFirst Financial: Banking Business and Lending Economics – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
OceanFirst Financial Strategy Analysis Bundle
OceanFirst Financial corresponds to OCEANFIRST FINANCIAL CORP., a banking business classified in SEC records under National Commercial Banks. The supported business context centres on consumer and commercial banking across central and southern New Jersey and the New York and Philadelphia metropolitan areas, where branches, digital access, lending, deposits and advisory relationships all influence how customers are served.
For the quarter from April 1 to June 30, 2026, the corporation reported GAAP net income of negative USD 3.029 million in its Form 10-Q filed August 7, 2026. That dated snapshot raises practical questions about capital and liquidity discipline, relationship-led growth, and the operating choices needed to support customers while managing risk. The bundle helps organise those questions through six complementary lenses.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking products or customer-growth initiatives deserve resources when growth potential and relative market share may differ?
An OceanFirst Financial BCG Matrix helps structure portfolio priorities across areas such as deposit relationships, lending activity, branch-supported services and digital customer acquisition. The framework compares market growth with relative market share, then uses the familiar Stars, Cash Cows, Question Marks and Dogs categories to test where investment, protection, selective experimentation or review may be appropriate. It does not assign OceanFirst Financial offerings to a quadrant; instead, it creates a disciplined way to compare product economics, demand potential and management attention.
- Portfolio balance. Compare mature relationship-based banking activity with initiatives that may require more spending to gain customer adoption or scale.
- Funding relevance. Consider whether deposit-led services support lending capacity and whether a priority fits capital, liquidity and risk-management constraints.
- Structured comparison. Use the Excel framework to map candidate activities consistently, then use the Word analysis to interpret the assumptions and strategic trade-offs behind each placement.
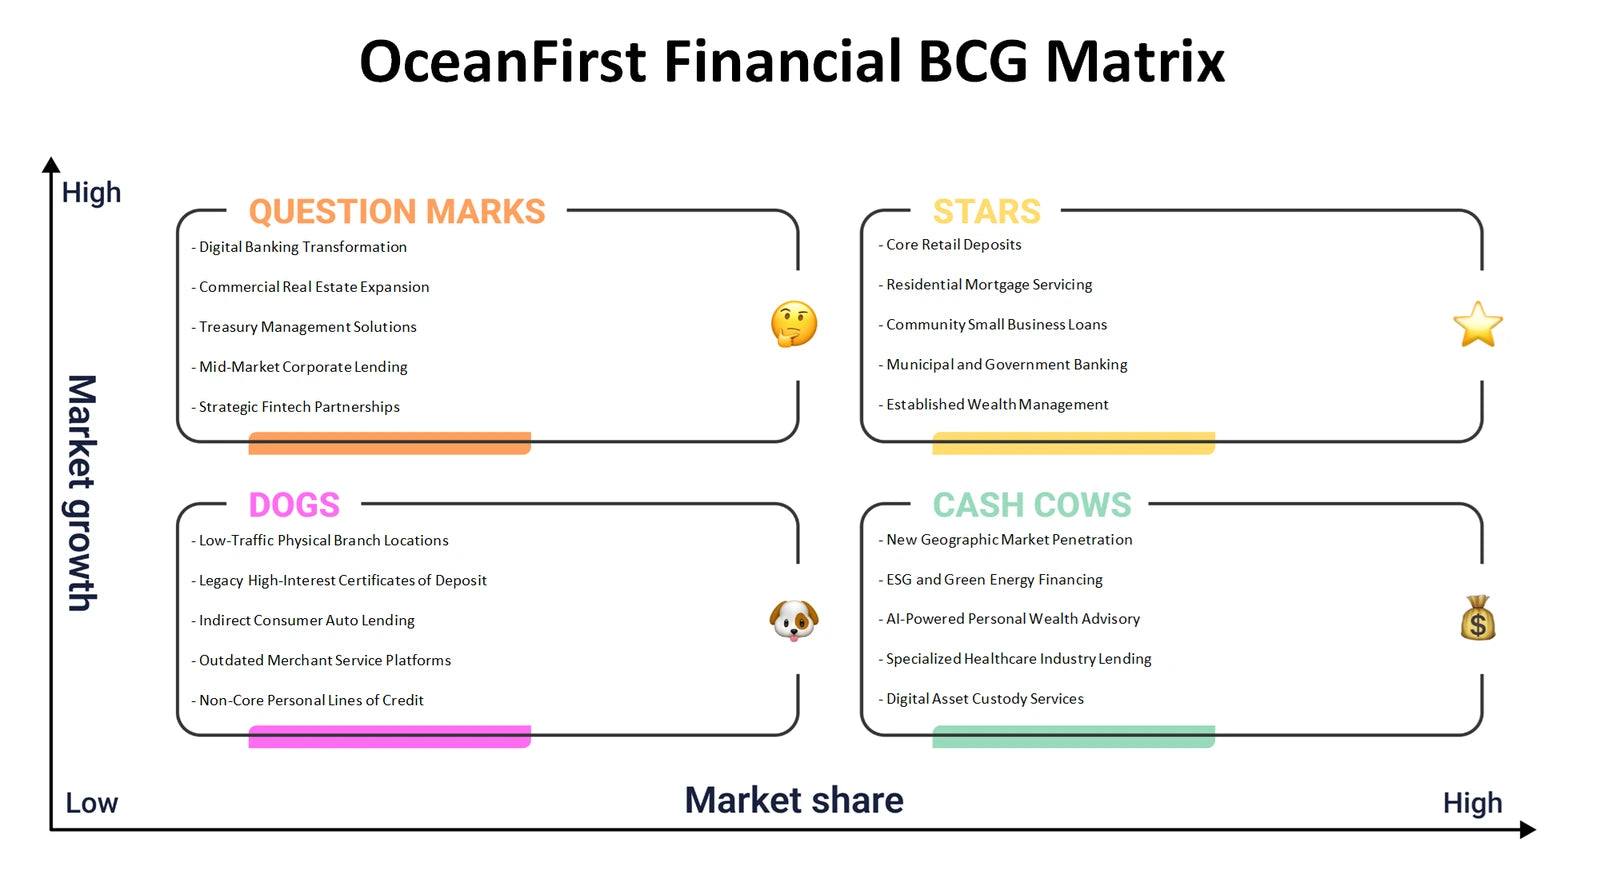
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer relationships, local access and risk-controlled banking operations connect to value creation and earnings?
The OceanFirst Financial Business Model Canvas examines the nine connected building blocks of a banking model: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. It helps connect consumer and commercial needs with branch and digital channels, relationship-led service and the economics of deposits, lending and advisory activity. It also makes operating dependencies visible: funding access, skilled staff, technology, compliance processes and risk controls can affect both the customer promise and the cost of delivering it.
- Customer logic. Examine how households, local businesses and commercial clients may require different service journeys, advice and access points.
- Economic links. Trace how relationship depth, lending and deposit activity can interact with operating costs, funding needs and regulatory obligations.
- Model workshop. Populate and compare the Excel canvas blocks, then use the detailed Word analysis to explore dependencies that a one-page map cannot fully explain.
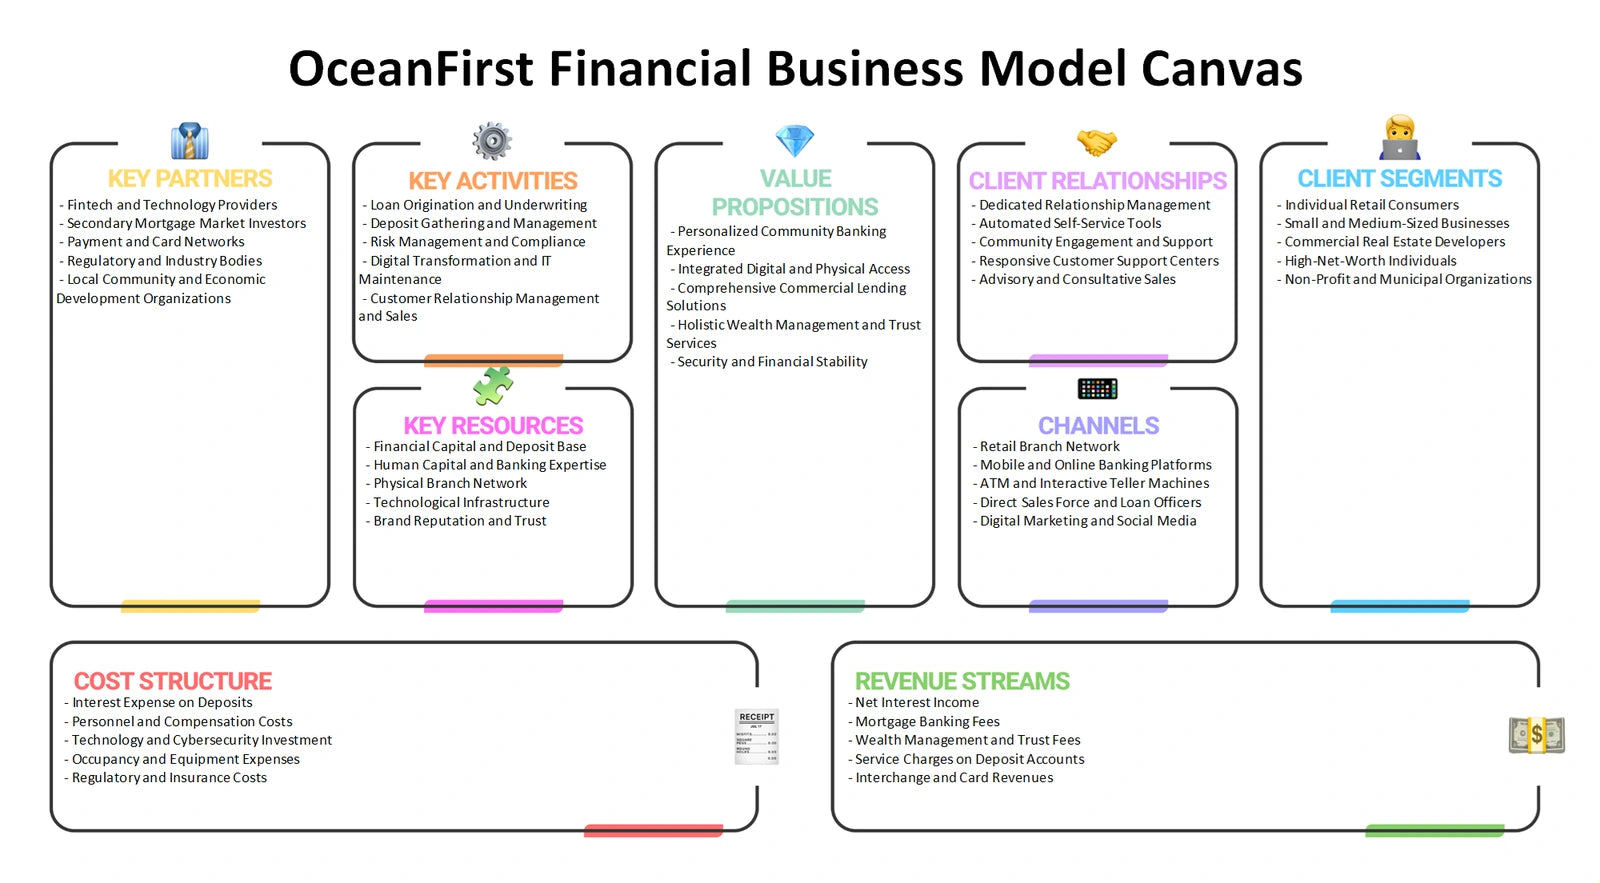
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could influence pricing power, customer retention and the cost of delivering banking services?
OceanFirst Financial Porter's Five Forces analysis considers rivalry among financial-service providers alongside buyer power, supplier power, new-entry risks and substitutes. In banking, customers can compare deposit, loan and payment options, while funding sources, technology providers and specialist service partners may influence cost and operating flexibility. Substitutes are broader than direct banks: digital payment tools, non-bank lenders, investment platforms and other ways to save, borrow or transact can meet parts of the same customer need. This lens helps separate market pressure from internal execution questions.
- Competitive choice. Assess where local relationships and branch visibility may matter most relative to digital convenience and product comparability.
- Dependency pressure. Explore how vendors, funding conditions and third-party technology arrangements could shape cost, resilience and service design.
- Evidence trail. Use the Excel framework to record force-specific observations and use the Word analysis to connect those observations to strategic responses worth evaluating.
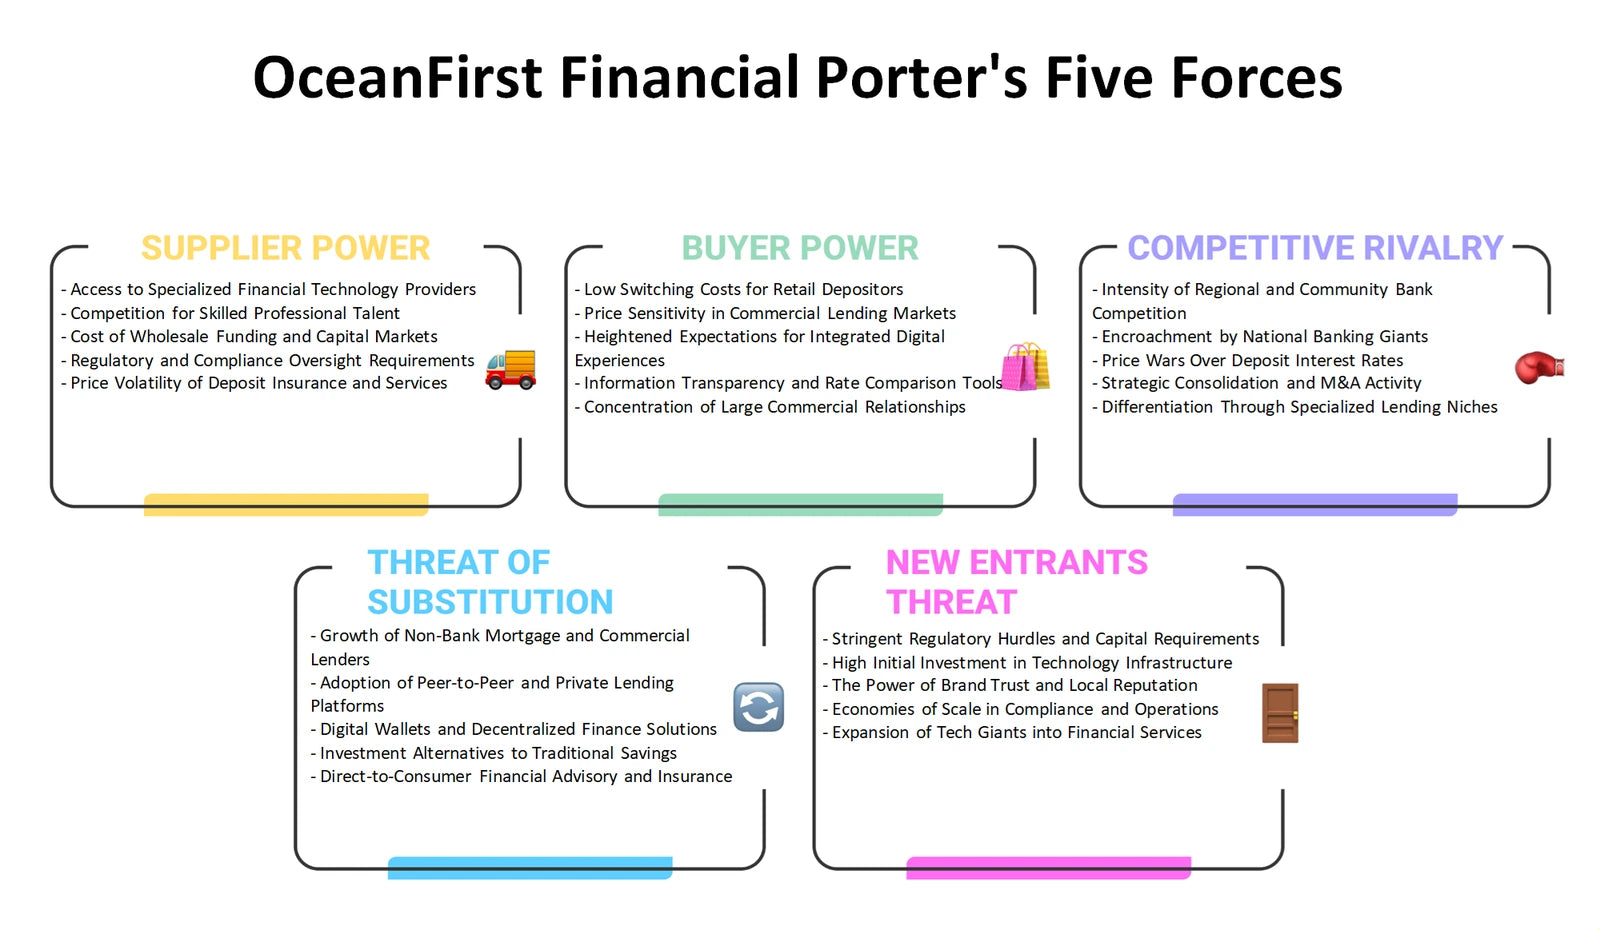
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can banking offers, pricing logic, distribution and communications reinforce a trusted regional customer proposition?
The OceanFirst Financial Marketing Mix considers Product, Price, Place and Promotion in a regulated service context. Product analysis can examine the fit between deposit, lending, advisory and transaction needs. Price covers more than a posted rate or fee: it helps assess value, transparency, risk-adjusted economics and customer sensitivity. Place considers branches across the supported New Jersey and metropolitan footprint alongside digital access. Promotion addresses how local visibility, relationship managers and clear communications can help customers understand services without overstating claims or overlooking compliance responsibilities.
- Offer design. Compare how consumer and commercial banking needs may influence product packaging, service levels and advice requirements.
- Channel consistency. Test whether branch conversations and digital journeys communicate a coherent experience across local markets.
- Go-to-market review. Organise 4Ps observations in Excel and consult the Word analysis when translating them into questions for customer, channel and pricing discussions.
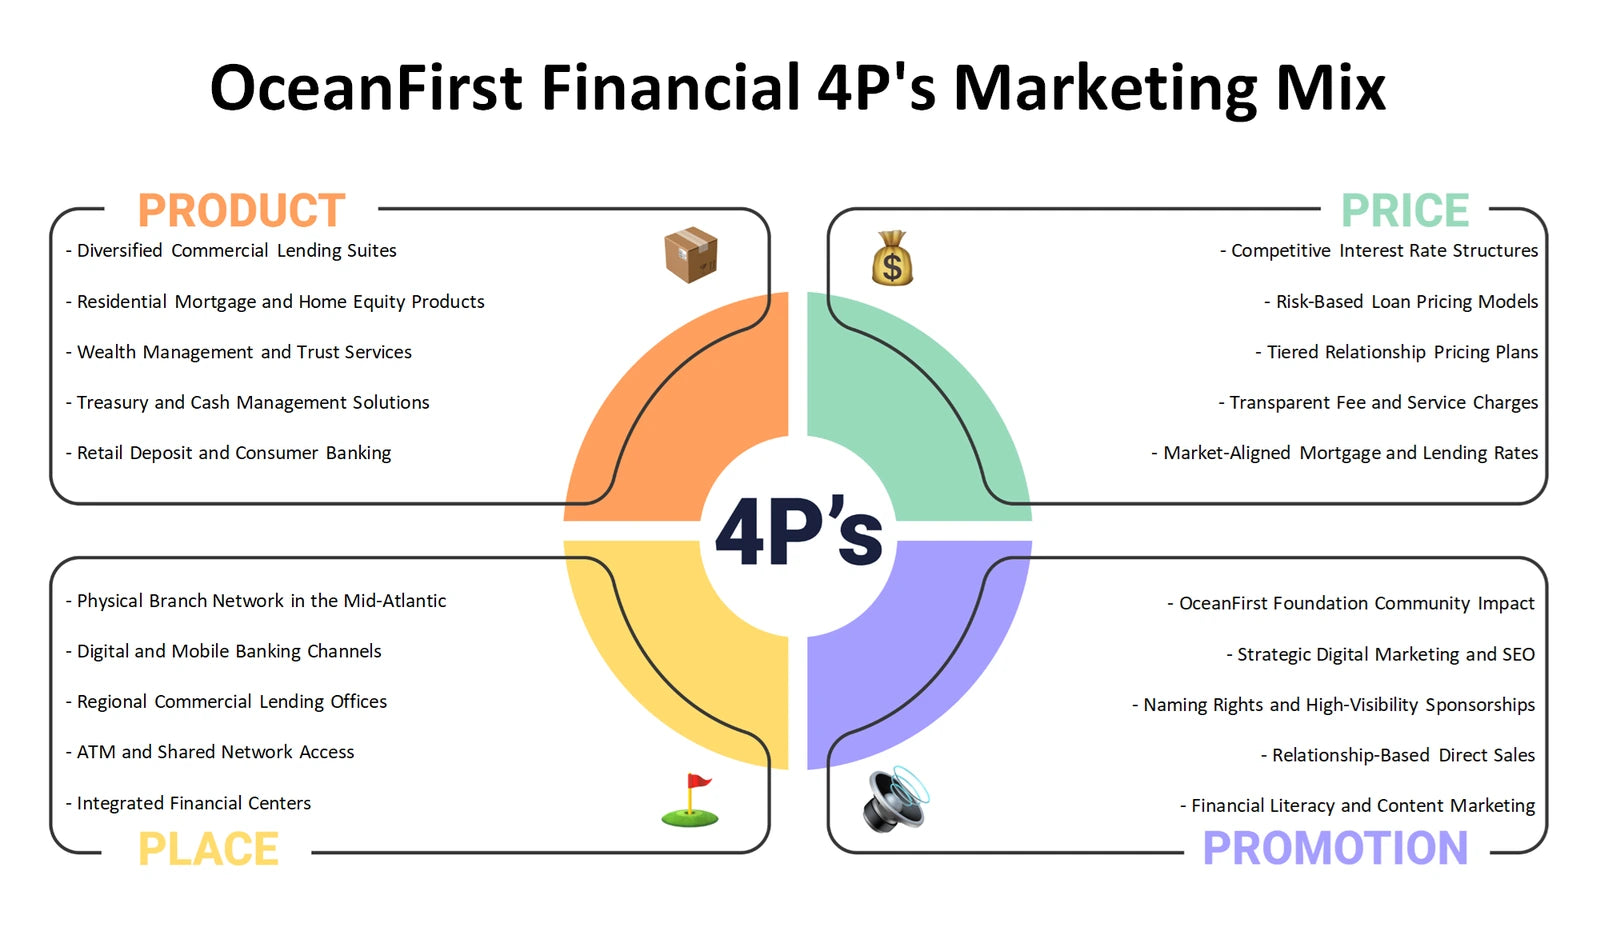
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should a regional banking business monitor when planning customer access, risk controls and growth?
OceanFirst Financial PESTLE analysis, also commonly written as PESTEL, organises Political, Economic, Social, Technological, Legal and Environmental influences around the business. Political and legal factors can include supervisory priorities, consumer protection, fair-lending, privacy and anti-money-laundering expectations. Economic questions may concern local borrowing conditions, funding costs and credit quality. Social changes can affect expectations for advice and convenience, while technology raises cybersecurity and payment-resilience requirements. Environmental considerations can be explored through physical-risk exposure and the implications of changing community, property and lending conditions.
- External watchlist. Distinguish a documented operating condition from a policy, rate, technology or community trend that warrants monitoring.
- Risk connection. Relate outside change to liquidity planning, customer trust, operational continuity and the ability to serve local markets.
- Scenario planning. Use the Excel categories to capture signals and possible implications, with the Word analysis providing fuller context for prioritising discussion topics.
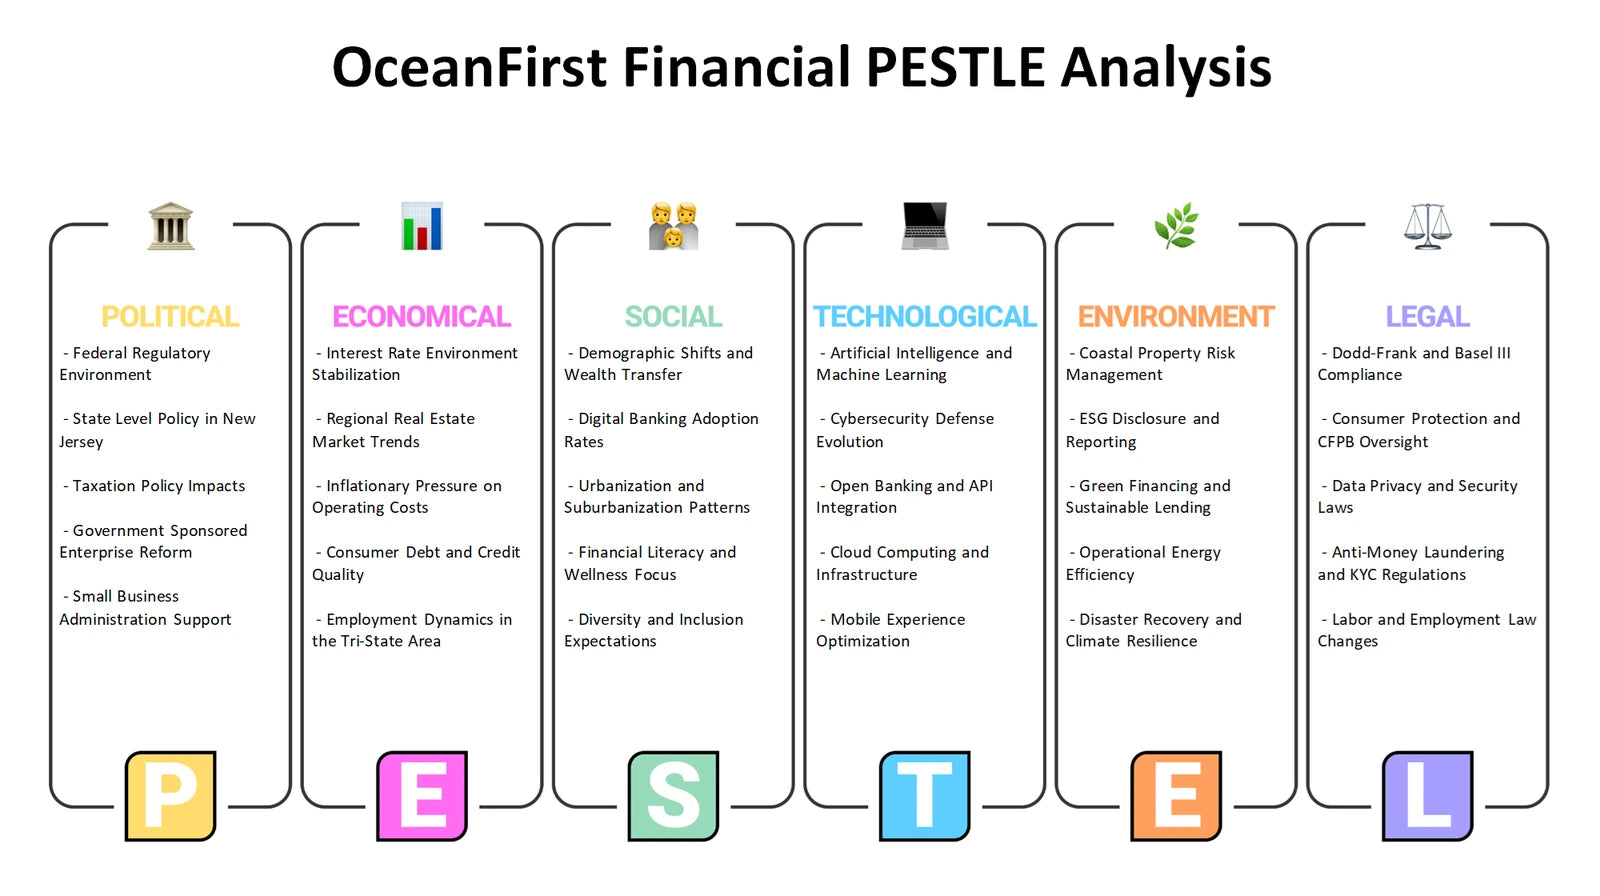
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal banking capabilities and constraints be considered alongside changing regional market conditions?
The OceanFirst Financial SWOT analysis separates internal Strengths and Weaknesses from external Opportunities and Threats. Supported context suggests useful themes to examine, including community presence, branch-based access, relationship expertise, digital service delivery, compliance infrastructure and risk discipline. These are analytical topics rather than pre-established SWOT findings. The framework then connects internal capabilities or constraints with outside possibilities such as customer needs, local business activity and technology adoption, as well as threats from competitive choice, cyber risk, economic uncertainty and regulatory change. Correct classification matters because management can influence internal capabilities more directly than external conditions.
- Internal reality. Identify capabilities, resource limits and operating dependencies that could affect service quality, growth capacity and resilience.
- External fit. Compare those internal factors with opportunities and threats arising from customer behaviour, market pressure and the regulatory environment.
- Decision support. Build a traceable SWOT inventory in Excel, then use the detailed Word analysis to test which combinations deserve further validation or action planning.
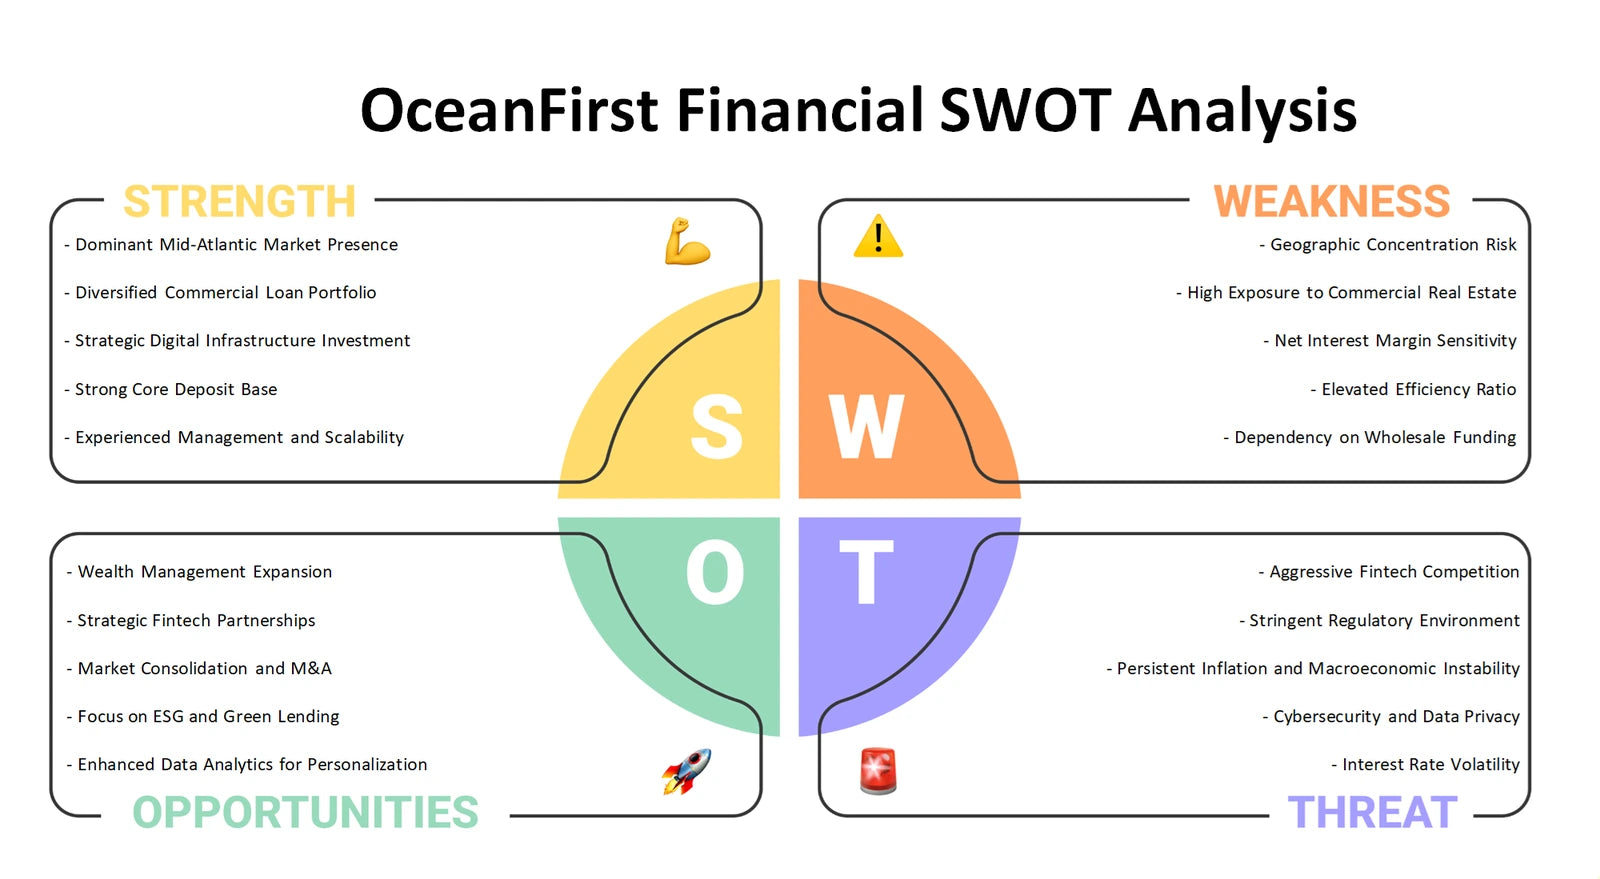
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Six lenses for a more connected banking strategy discussion
Together, the BCG Matrix, Business Model Canvas, Five Forces, Marketing Mix, PESTLE and SWOT frameworks help customers examine OceanFirst Financial from portfolio, value-creation, industry, customer, external-environment and capability perspectives. The Excel materials provide structured places to organise comparisons and questions, while the Word files provide detailed company analysis to support more informed review of trade-offs involving relationships, channels, funding, risk and growth.
Company background: OceanFirst Financial — SEC company submissions profile.