

New York Community Bancorp: Banking Business and Deposit Funding – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
New York Community Bancorp Strategy Analysis Bundle
New York Community Bancorp is a United States commercial-bank holding company identified in public sources with Flagstar Financial and the Flagstar Bank franchise. Its banking model serves consumer and business needs through deposit and lending relationships, supported by branch locations as well as digital and assisted service channels.
Available company-context material describes access to Federal Home Loan Bank advances and secured repo lines, local community engagement, and service through phone, chat and secure messaging. Those details make funding resilience, channel economics, customer trust and portfolio priorities useful questions for the six connected strategy analyses in this bundle.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking activities deserve greater attention when growth prospects and relative market share point in different directions?
A New York Community Bancorp BCG Matrix helps frame portfolio priorities across deposit gathering, lending, customer servicing and other banking activities. Rather than assuming that any activity belongs in a quadrant, it compares market growth with relative market share to test whether an area resembles a Star, Cash Cow, Question Mark or Dog. This matters for a bank balancing relationship banking, funding needs, risk capacity and investments in service delivery.
- Portfolio logic. Compare mature activities that may generate dependable contribution with faster-changing opportunities that could require more resources, controls or distribution support.
- Capital discipline. Use the matrix to ask where management attention, technology spending and balance-sheet capacity may be most consequential without treating a quadrant as investment advice.
- Structured comparison. The Excel framework organizes the growth and relative-share review, while the detailed Word analysis explains how the categories can be interpreted for a commercial-bank portfolio.
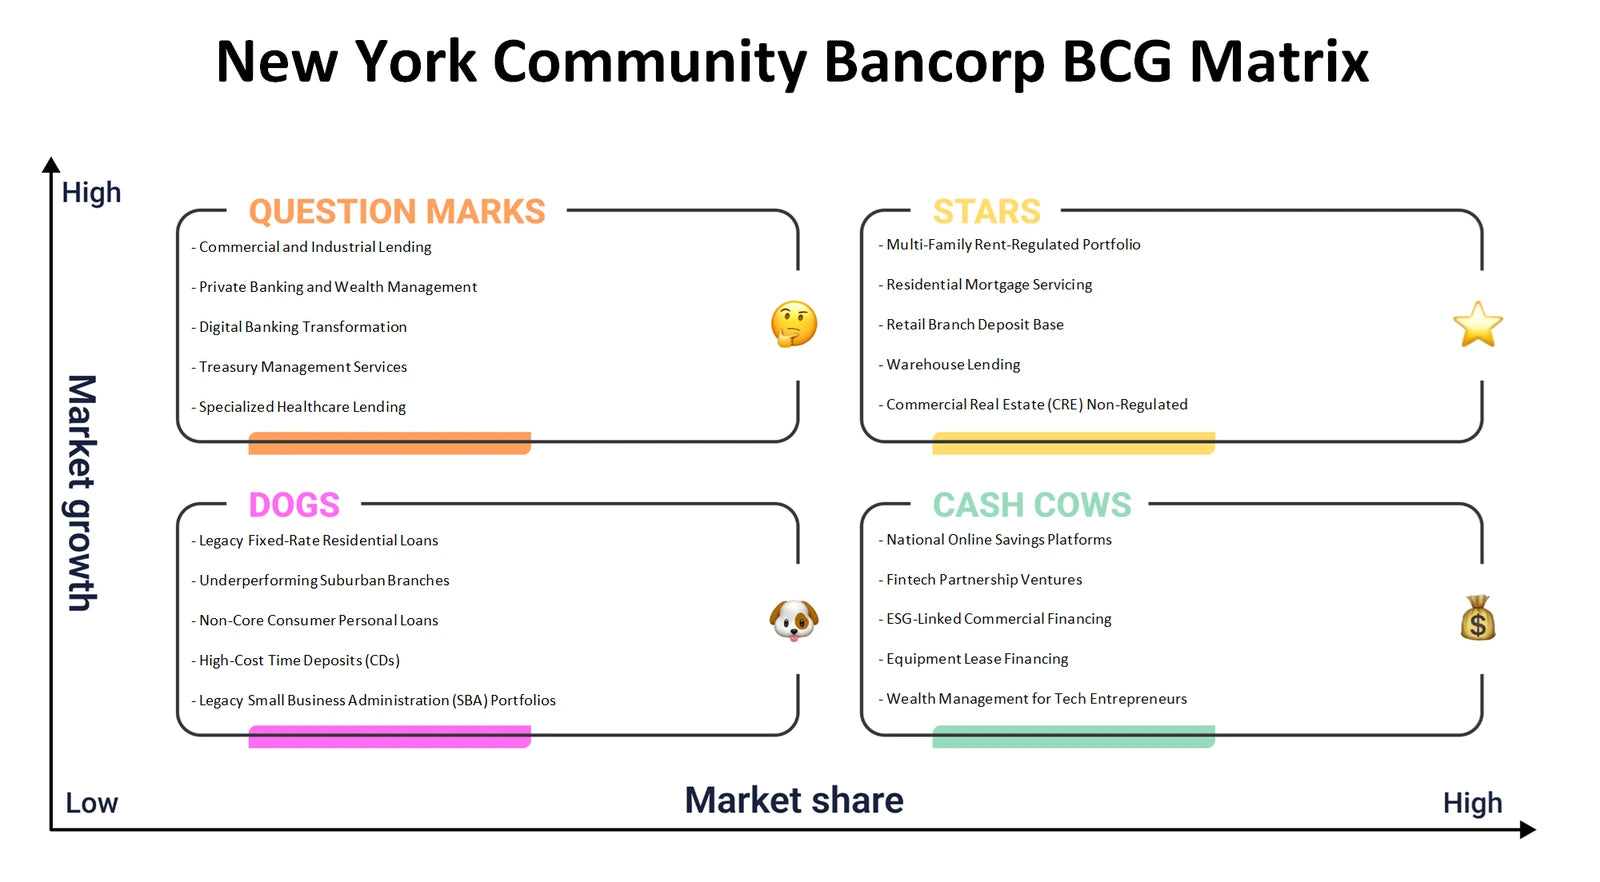
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer relationships, funding, delivery channels and operating costs fit together in the bank's value-creation model?
The New York Community Bancorp Business Model Canvas connects consumer and business customer segments with banking value propositions, channels and customer relationships. It also links revenue streams from banking activities to key resources such as funding, systems and people; key activities including underwriting, servicing and risk management; key partnerships such as funding counterparties; and the cost structure required to operate safely. The canvas is useful because a change in one block can affect several others.
- Service architecture. Examine how branches, digital access, phone support, chat and secure messaging can work together for acquisition, service and retention.
- Economic connections. Trace how deposits, lending, liquidity arrangements and operating controls influence the relationship between revenue logic, resources and costs.
- Model mapping. Use the structured Excel framework to keep the nine building blocks connected, then use the detailed Word analysis to interpret the relationships and trade-offs.
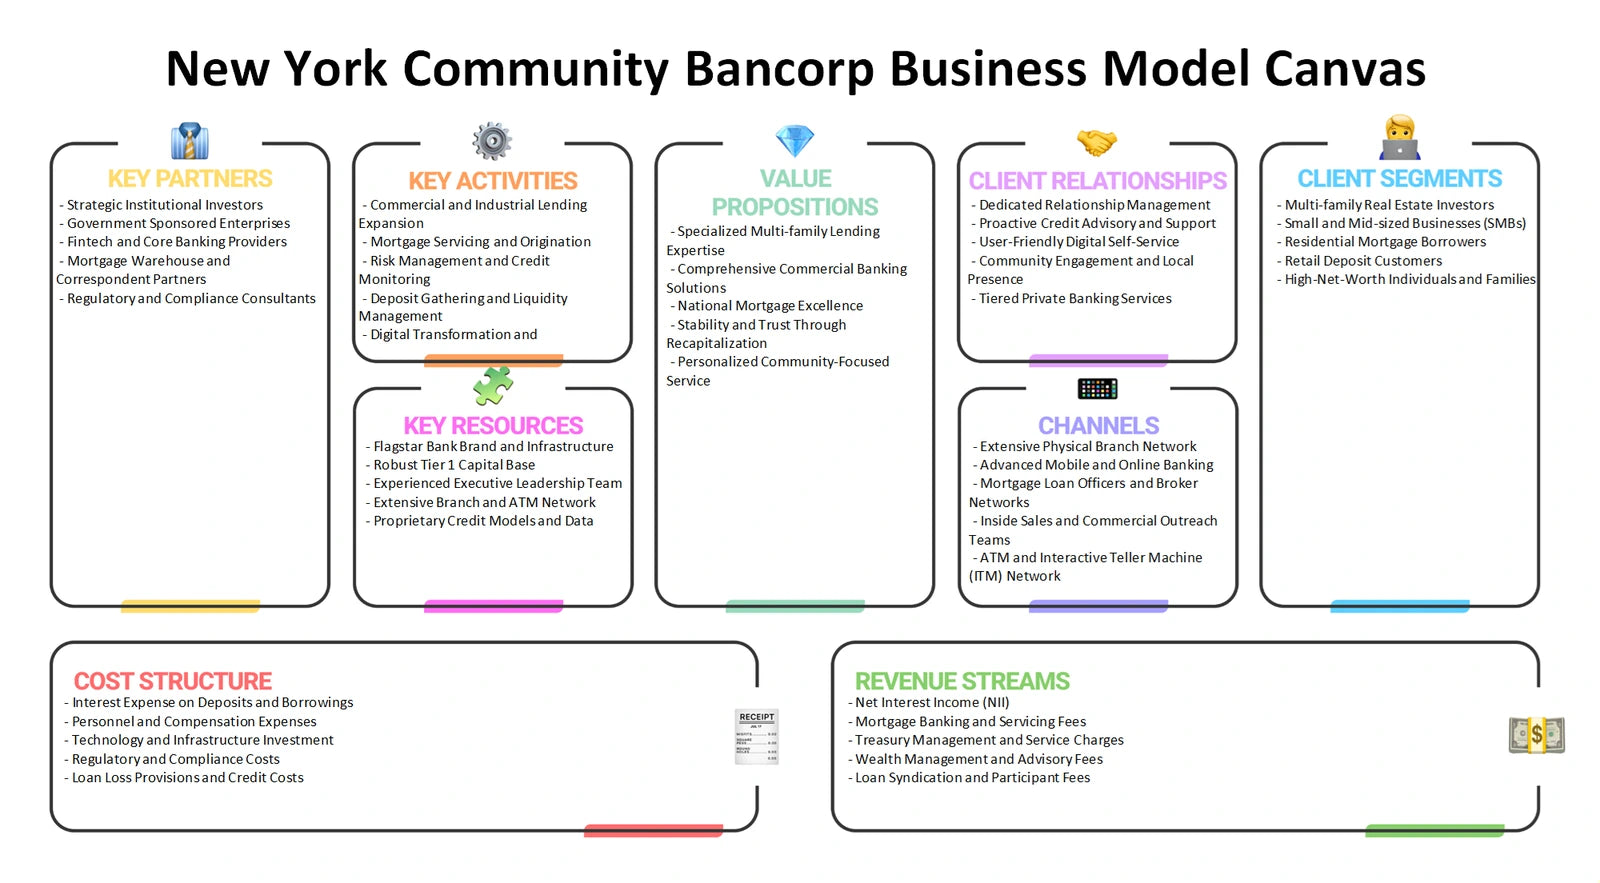
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures shape the bank's ability to attract deposits, price lending and maintain customer relationships?
A New York Community Bancorp Porter's Five Forces analysis examines the competitive setting around U.S. commercial banking without reducing it to a list of direct rivals. Rivalry can affect rates, service expectations and product breadth. Supplier power includes the influence of deposit funding, wholesale funding sources and specialist providers. Buyer power reflects how easily customers can compare banking options, while new entrants and substitutes include fintech services, nonbank lenders, money-market products and other ways to meet saving or borrowing needs.
- Funding competition. Assess how competition for deposits and access to wholesale liquidity can influence the cost and stability of funding.
- Customer alternatives. Compare the convenience, pricing and trust expectations that can shift households or businesses toward alternatives outside a traditional branch relationship.
- Pressure testing. The Excel framework separates the five forces for disciplined review, and the detailed Word analysis gives context for discussing their implications together.
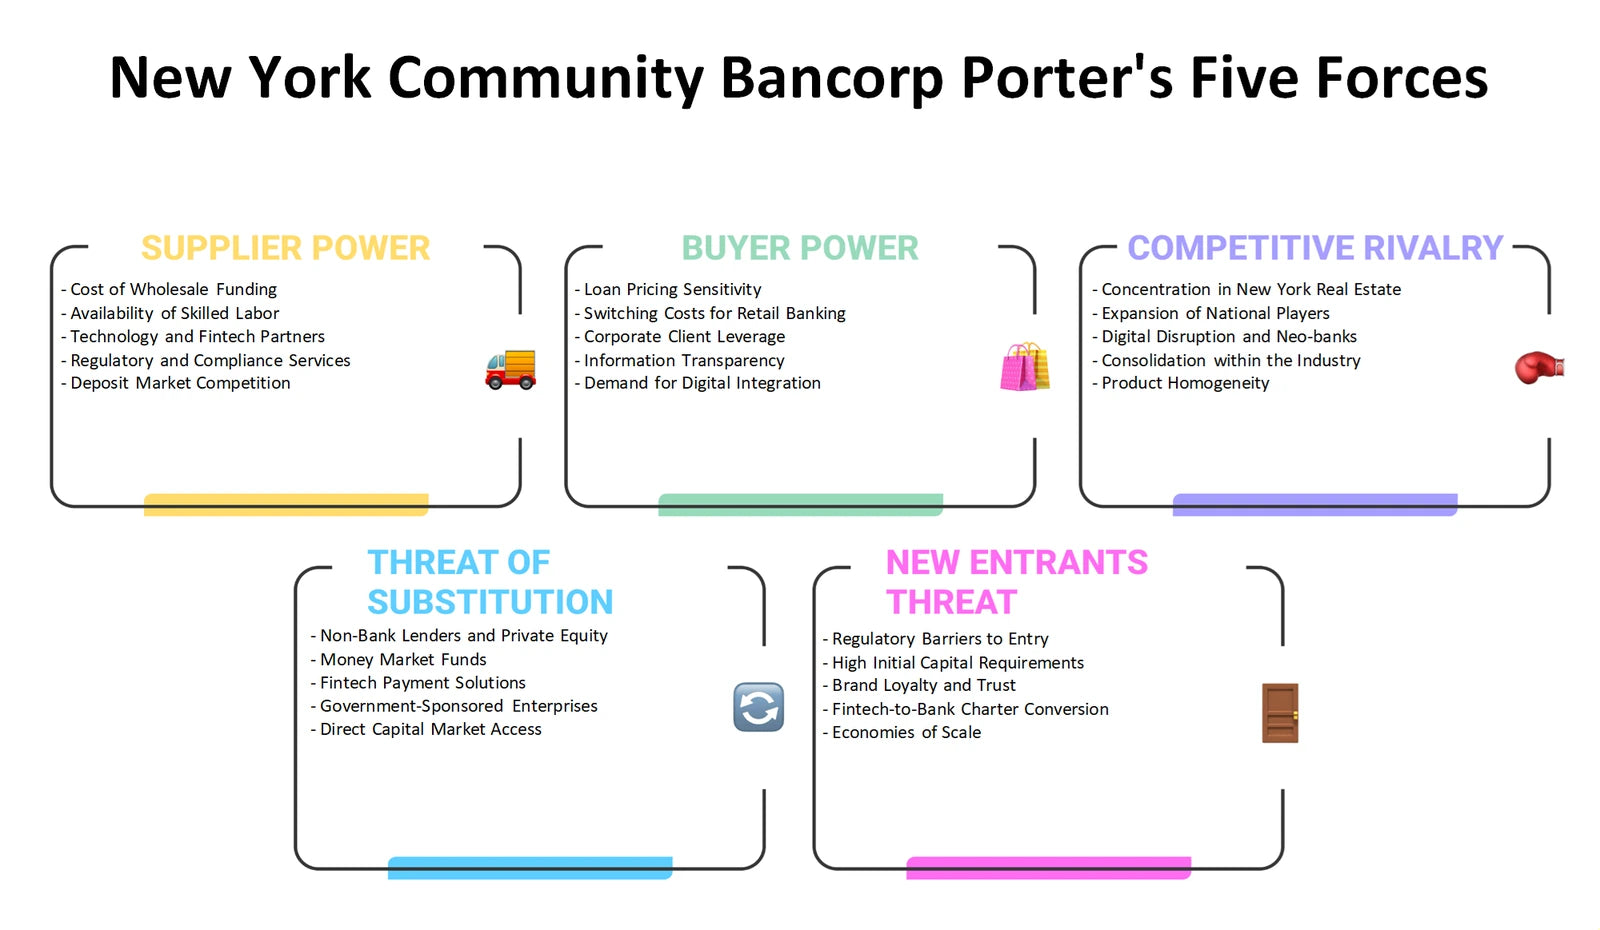
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can product design, pricing logic, access points and communications support trusted banking relationships?
The New York Community Bancorp Marketing Mix considers the 4Ps in a regulated, relationship-based service setting. Product covers deposit, lending and service propositions that solve customer financial needs. Price considers interest rates, fees, yields and the value customers receive, while recognizing that pricing is shaped by funding costs, risk and regulation. Place covers branches, digital journeys and assisted channels. Promotion examines how clear communication, community presence and financial education can reinforce credibility without assuming any specific campaign or price.
- Offer design. Review whether banking products and service support match the needs of consumers and businesses at different moments in their financial lives.
- Channel consistency. Compare the customer experience across branch, online, phone, chat and secure-message touchpoints so access does not undermine trust.
- Decision alignment. Use the Excel framework to place Product, Price, Place and Promotion side by side, with the detailed Word analysis supporting a more contextual review.
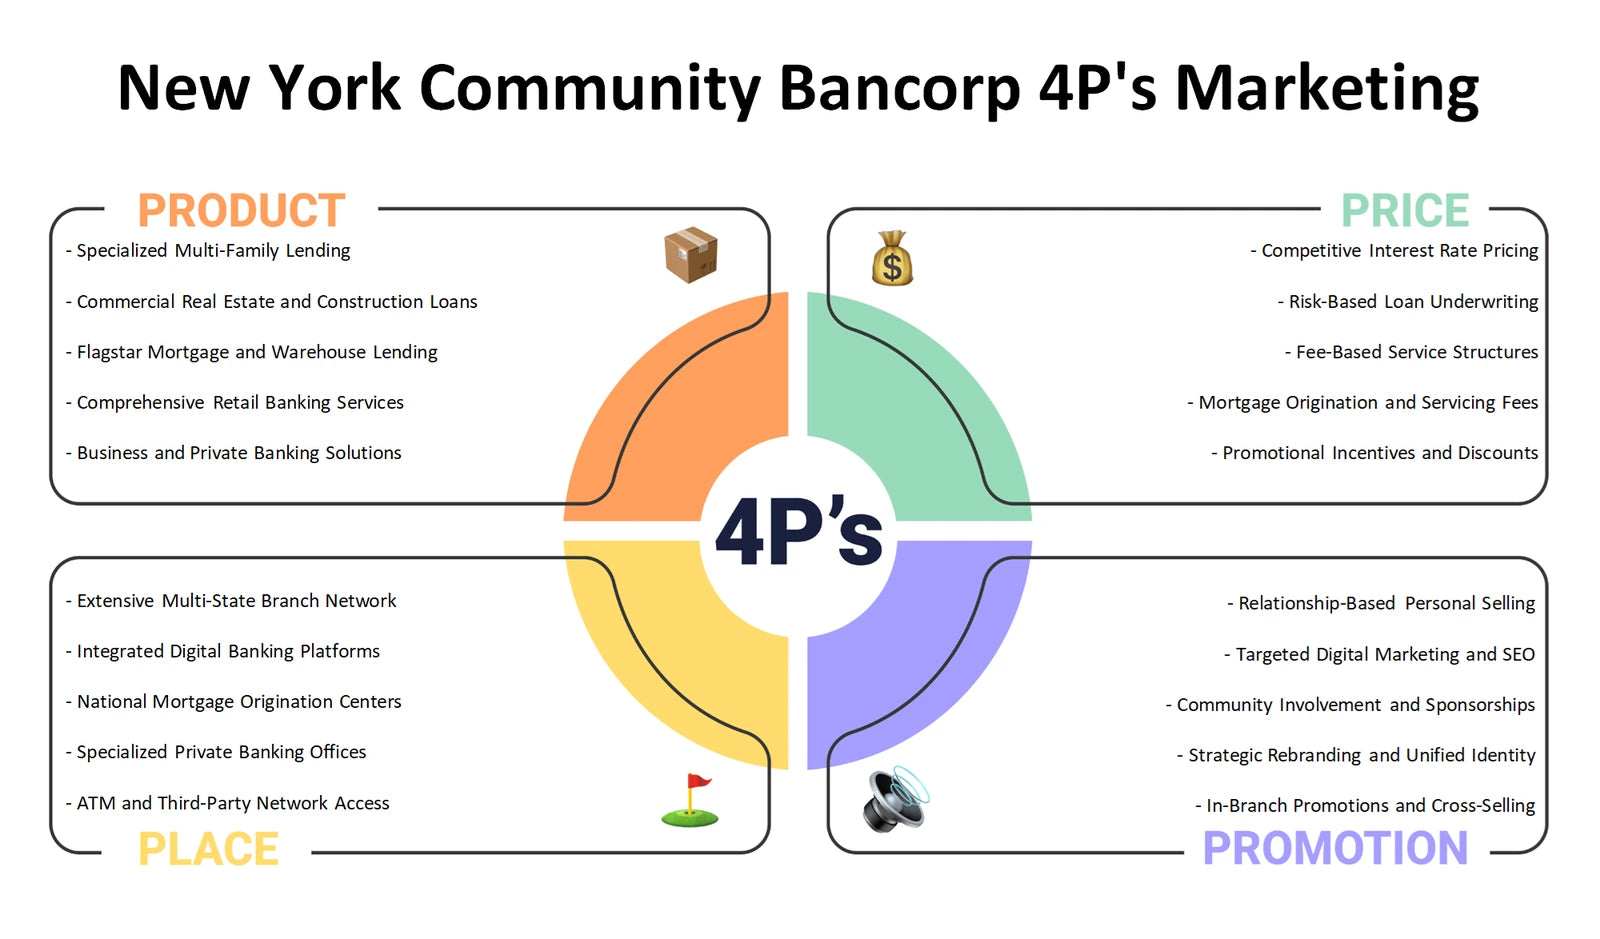
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could most affect bank funding, credit decisions, customer behavior and operating obligations?
A New York Community Bancorp PESTLE analysis, also commonly called PESTEL, organizes external influences that a bank cannot control directly. Political questions include public-policy priorities and the supervisory environment. Economic conditions affect credit demand, deposit competition and funding costs. Social factors include trust, financial inclusion and changing preferences for service. Technology raises digital-access and cybersecurity questions; legal factors cover prudential and consumer obligations; environmental considerations can affect physical operations and collateral exposed to weather or climate-related risk.
- External scan. Distinguish a policy, rate or regulatory question to monitor from a documented change, avoiding assumptions about laws or economic conditions.
- Connected exposure. Consider how external conditions may interact with liquidity planning, underwriting, branch operations, digital security and community engagement.
- Monitoring structure. The Excel framework provides a six-factor scan, while the detailed Word analysis helps connect each external category to relevant banking questions.
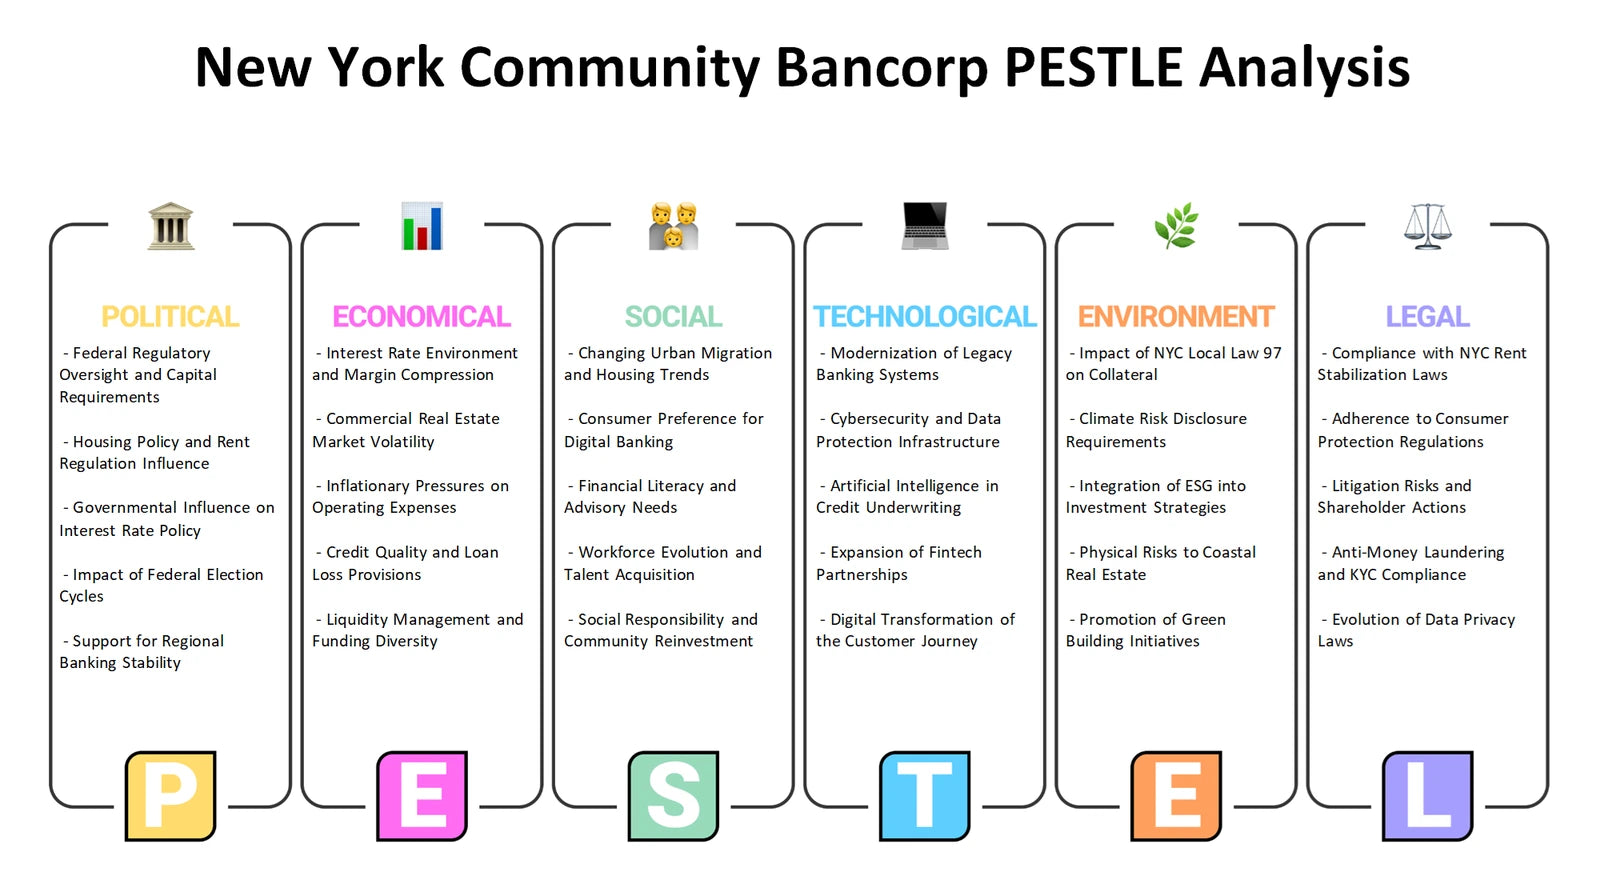
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal capabilities and constraints should be considered alongside the opportunities and threats facing the bank?
A New York Community Bancorp SWOT analysis separates internal factors from external conditions before combining them into practical discussion. Potential strengths and weaknesses may relate to funding access, branch and digital service capabilities, risk controls, customer relationships or operating complexity; these are matters to assess rather than predetermined findings. Opportunities and threats sit outside the organization, including changing customer needs, competitive alternatives, economic conditions, technology expectations and regulatory pressure. The framework helps prevent an external trend from being confused with an internal capability.
- Clear classification. Test whether an item belongs under a controllable strength or weakness, or under an external opportunity or threat that requires a response.
- Strategic fit. Explore how liquidity resources, service channels and community relationships could be considered against market, technology and regulatory conditions.
- Actionable synthesis. Use the Excel structure to compare the four categories, then consult the detailed Word analysis to develop more informed strategic discussion.
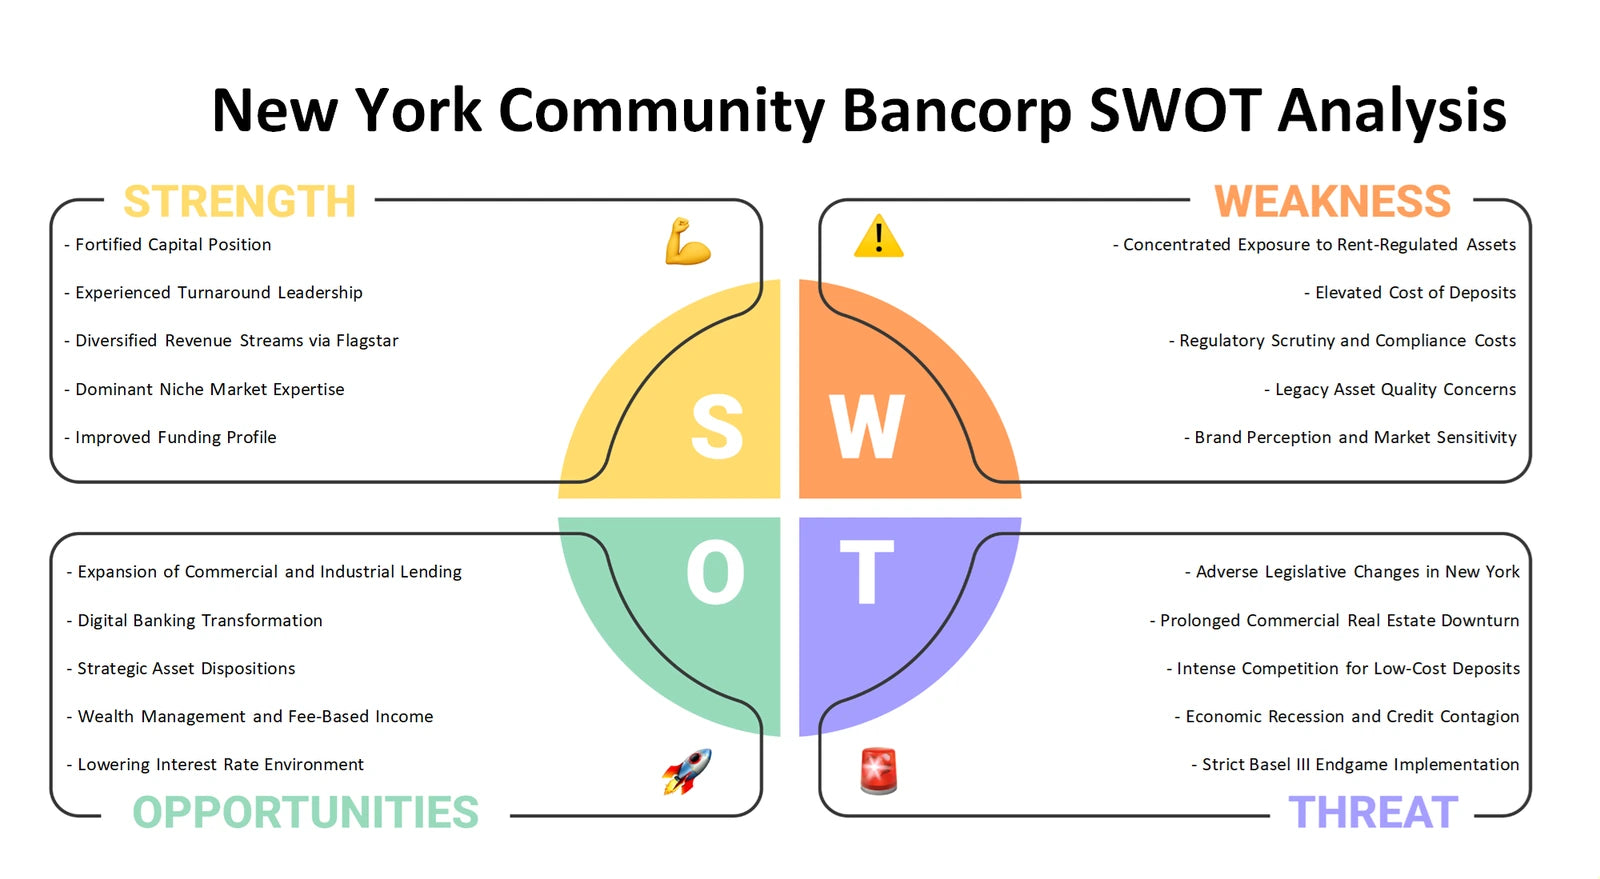
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices with banking economics and external pressures
Together, the six perspectives move from portfolio priorities and business-model connections to industry pressure, customer delivery, external change and strategic fit. The Excel frameworks provide a structured way to organize the questions, while the detailed Word analyses help customers develop a more considered view of New York Community Bancorp's banking model, funding context, channels and strategic trade-offs.
Company background: New York Community Bancorp — Wikidata entity profile.