

Northrim Bank: Banking Business and Lending Economics – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Northrim Bank Strategy Analysis Bundle
Northrim Bank is presented in this bundle as a regulated banking business built around deposit relationships and lending capacity. The available product context highlights the importance of stable, diversified deposits in supporting measured balance-sheet growth, while relationship banking can also involve tenure-based and multi-product customer engagement. These operating themes matter because funding, credit quality, service and trust are closely connected in banking.
The bundle helps turn that context into structured strategic questions rather than unsupported conclusions. It can help examine where lending and deposit activity merit attention, how customer relationships contribute to economics, and how credit, compliance, insurance and market conditions affect resilience. The Excel frameworks organise the comparisons; the Word analyses provide detailed company-focused discussion to support more considered planning.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking activities should receive attention when relative market share and market growth point in different directions?
The Northrim Bank BCG Matrix provides a disciplined way to compare a portfolio of lending, deposit and relationship-led activities using relative market share and market growth as analytical criteria. It does not assume that any activity belongs in a Star, Cash Cow, Question Mark or Dog quadrant. Instead, it helps distinguish activities that may generate dependable funding or income from those that could require additional capability, risk capacity or selective review. For a bank, the exercise is useful because apparent growth can carry funding, credit and operating demands that deserve equal attention.
- Portfolio logic. Compare lending and deposit-related priorities by their strategic role, growth setting and relative position rather than by volume alone.
- Resource trade-offs. Test whether service capacity, risk oversight and funding support fit the priorities suggested by each analytical quadrant.
- Working view. Use the Excel framework to map possible portfolio assumptions, then use the Word analysis to interpret the questions and decision implications.
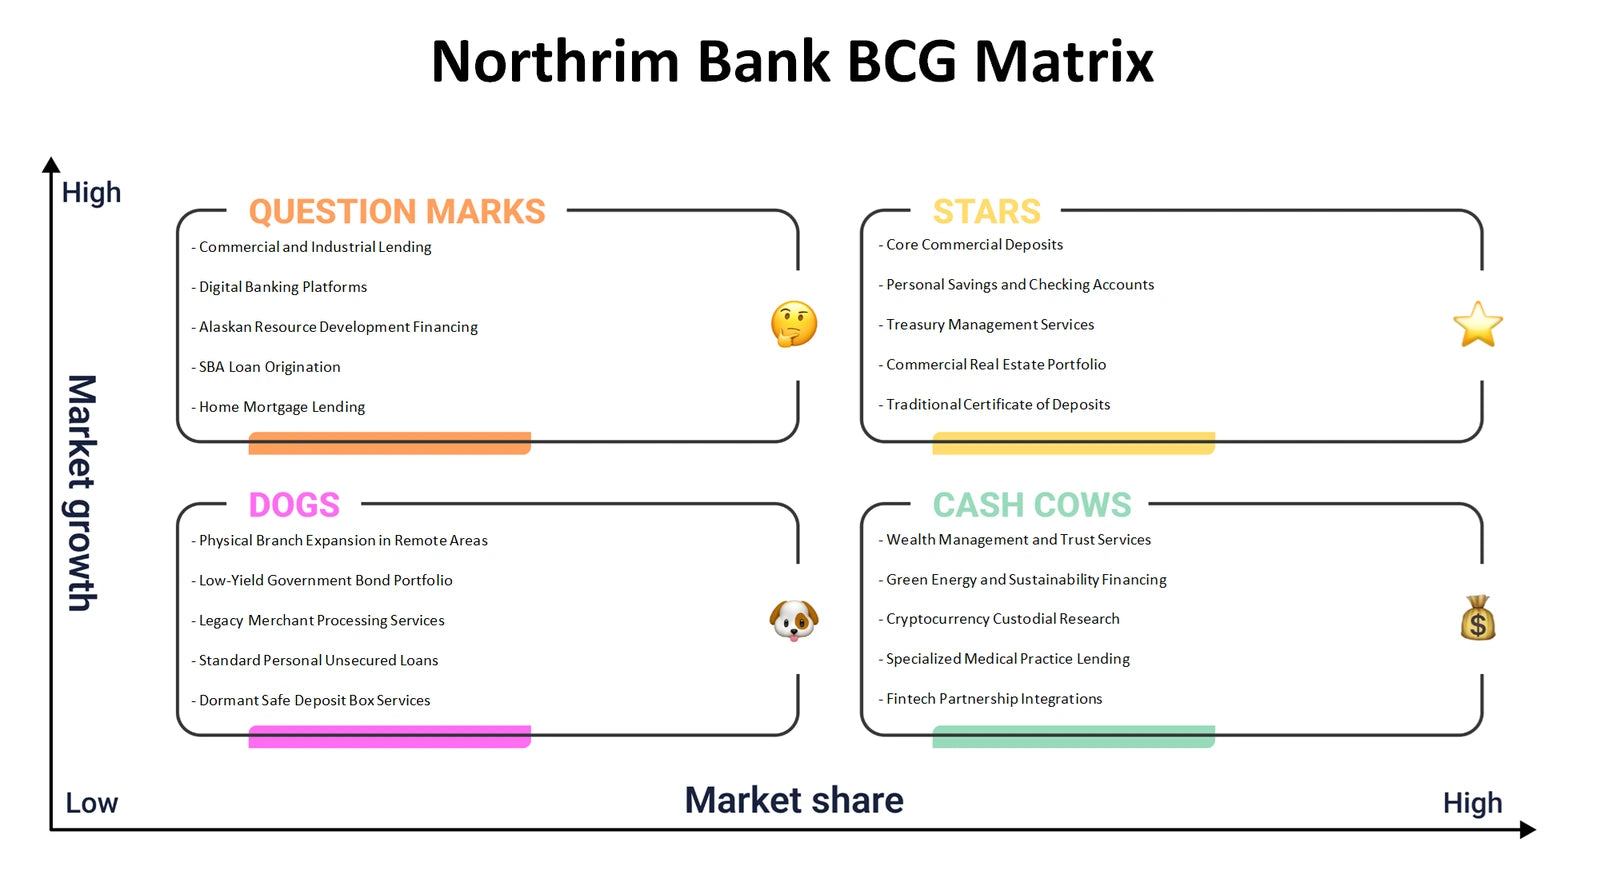
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do deposit relationships, lending activity and customer engagement connect to sustainable banking economics?
The Northrim Bank Business Model Canvas examines the links among customer segments, value propositions, channels and customer relationships, then connects them to revenue streams and cost structure. It also considers the key resources, key activities and key partnerships needed to deliver banking services responsibly. Deposits can be assessed as more than a product: they are part of the funding base for lending. Likewise, tenure and multi-product engagement can be considered in relation to retention, service effort and acquisition efficiency, without assuming a measured outcome. This nine-block lens makes interdependencies visible, including how risk management and compliance shape the model rather than sitting outside it.
- Value exchange. Trace how banking customers receive access, service and relationship value while the business earns through its supported product relationships.
- Economic connections. Relate deposit funding, loan activity, operating costs and risk-related expenses instead of viewing each in isolation.
- Model workshop. Populate the Excel Canvas with evidence and questions, then use the detailed Word analysis to explore the rationale behind each block.
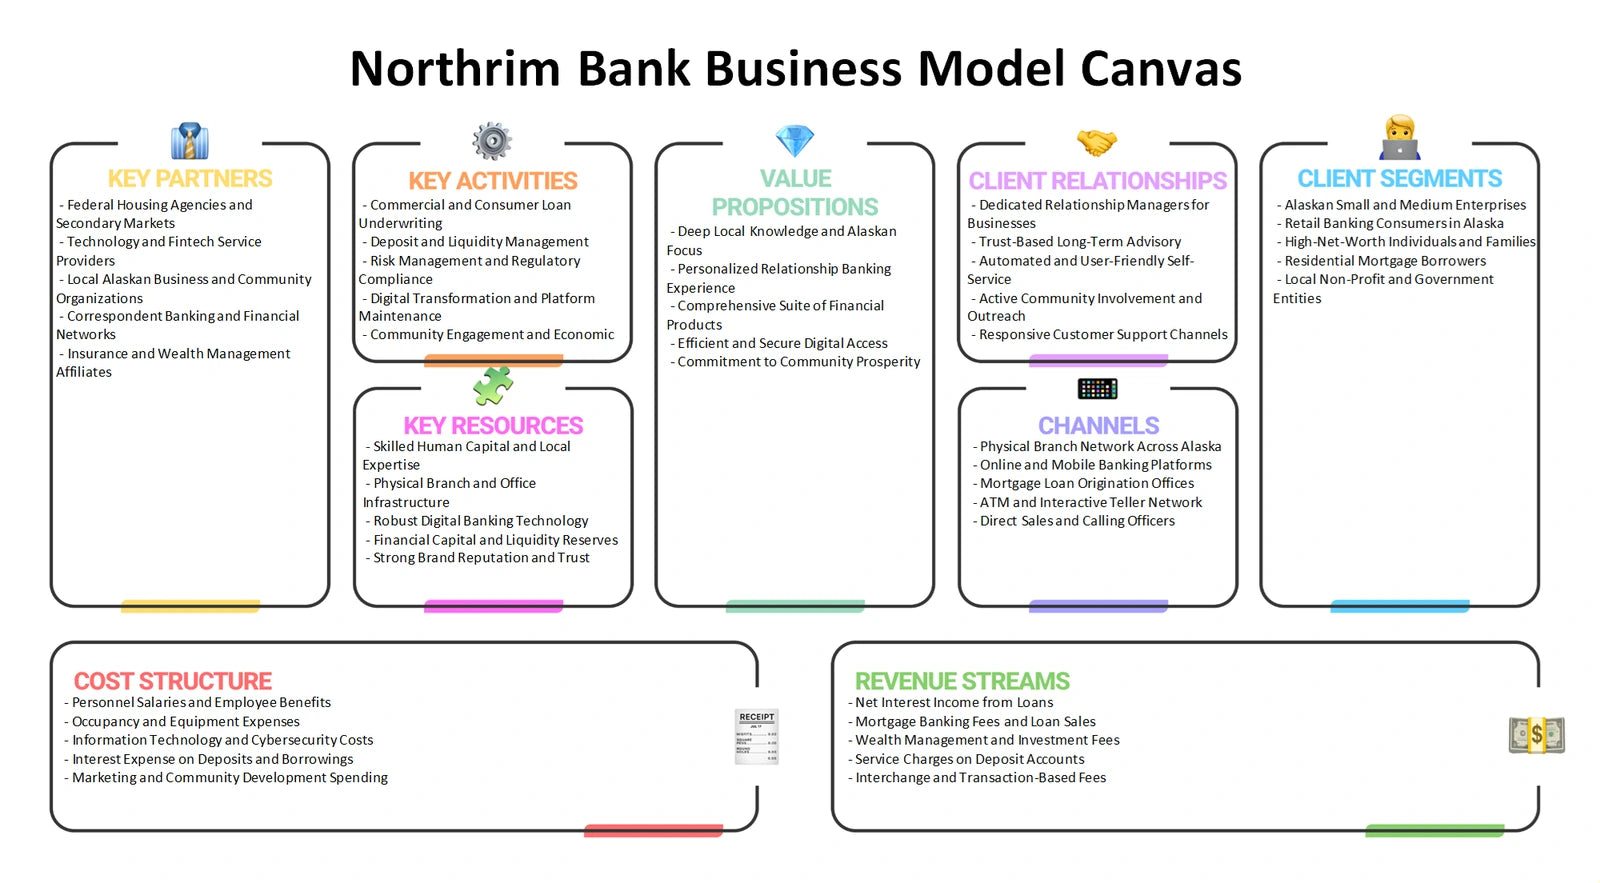
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could affect the attractiveness and defensibility of Northrim Bank's banking relationships?
Northrim Bank Porter's Five Forces focuses on the structure around a banking provider rather than making unsupported claims about a particular competitor. Rivalry can be explored through competition for deposits, lending relationships and service differentiation. Buyer power considers how readily customers can compare providers or move balances; supplier power addresses the influence of funding markets, technology providers and specialist service partners. The threat of new entrants includes the barriers created by regulation, trust and infrastructure, while substitutes include alternative ways for customers to borrow, save, pay or manage money. Each force can influence margins, retention costs and the pace of product change.
- Relationship pressure. Assess where customers may have negotiating leverage and where switching frictions or trusted service could matter.
- Alternative pathways. Compare traditional banking needs with non-bank borrowing, payments and savings alternatives as substitute choices.
- Force comparison. Use the Excel framework to record evidence for each force and the Word analysis to explain how the pressures may interact.
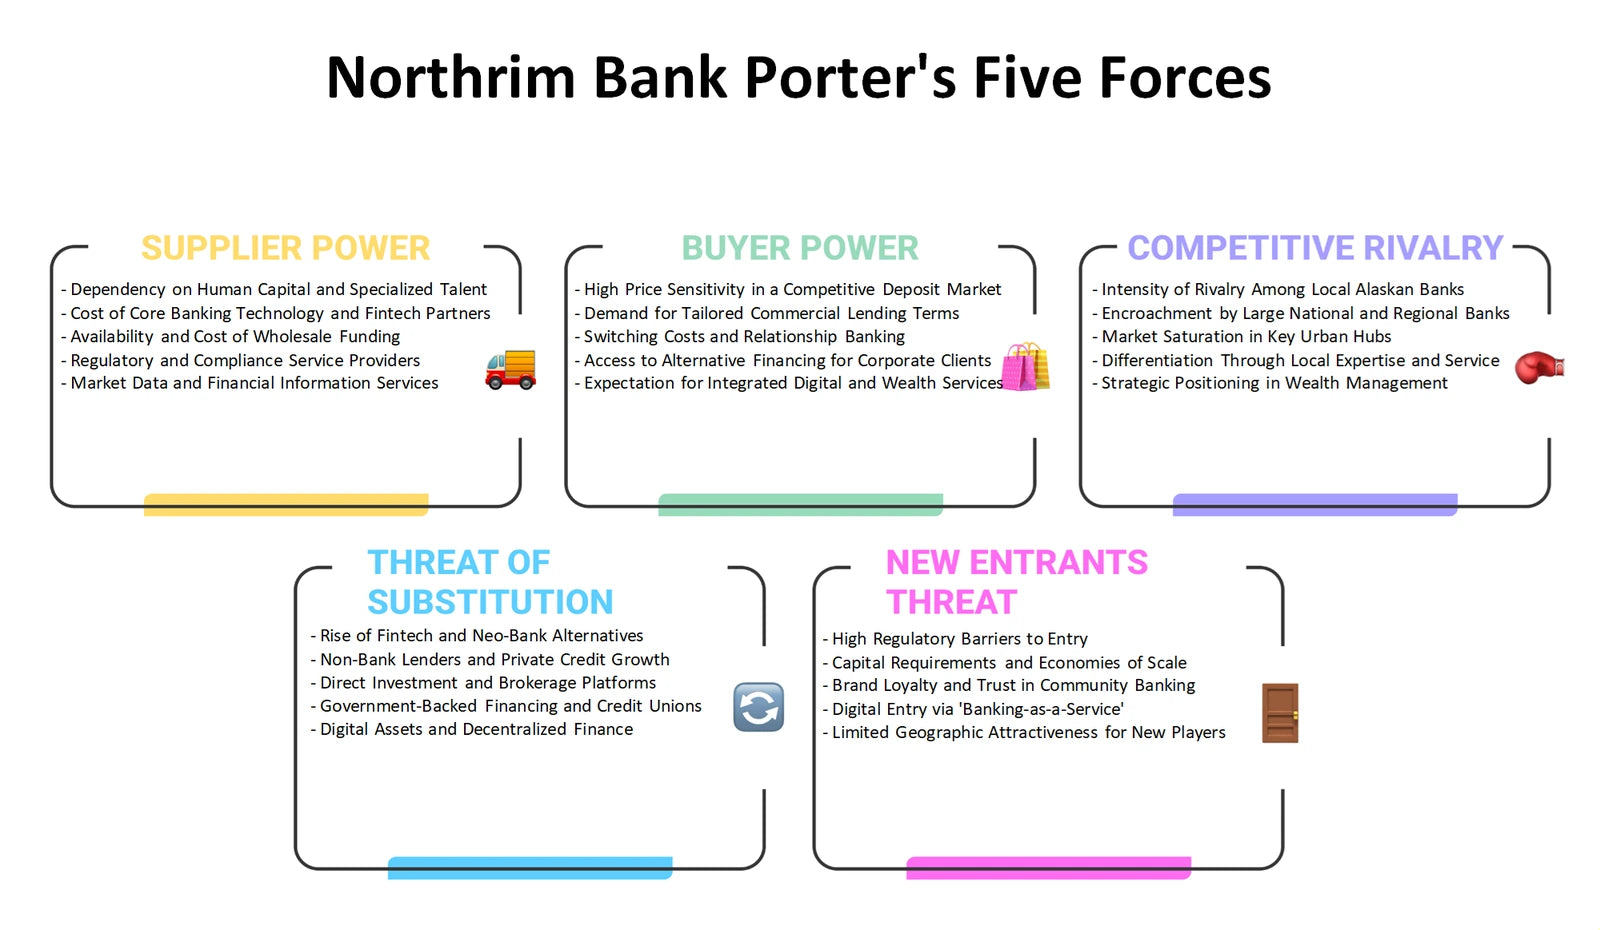
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can product design, pricing logic, access and communication support relationship-led banking without overlooking trust?
The Northrim Bank Marketing Mix applies Product, Price, Place and Promotion to a regulated service business. Product can cover the fit among deposit relationships, lending needs and supporting financial services. Price is broader than a list of rates or fees: it can be examined through value, risk, funding costs and transparent customer communication. Place considers the routes through which customers access advice, service and transactions, while Promotion assesses how relationship benefits and referral activity are communicated responsibly. This framework avoids inventing campaigns, prices or channel shares; its purpose is to organise the choices that influence acquisition, retention and appropriate product use.
- Offering fit. Examine how products can address different banking needs while encouraging sensible multi-product relationships.
- Trust in communication. Consider whether messages about loyalty, referrals and service are clear, balanced and aligned with a regulated environment.
- Planning sequence. Use the Excel 4Ps structure to compare options across the mix, with the Word analysis supplying context for the trade-offs.
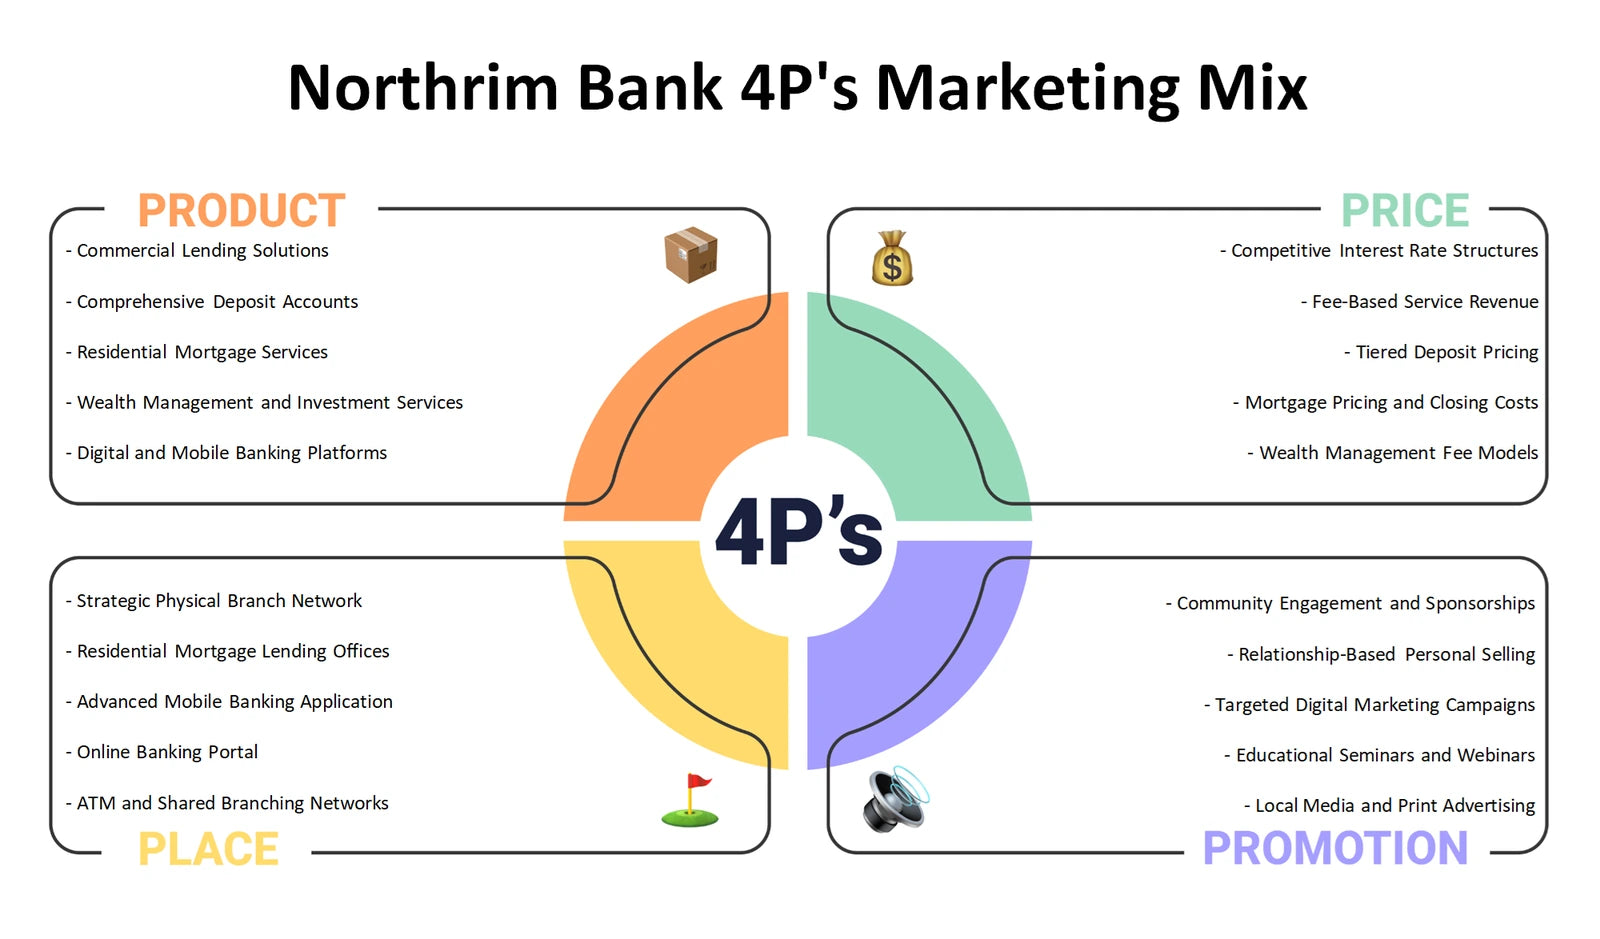
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could alter the conditions under which deposits, lending and banking compliance are managed?
The Northrim Bank PESTLE analysis, also commonly called PESTEL, separates external influences into Political, Economic, Social, Technological, Legal and Environmental categories. Political and legal questions can address the policy and supervisory setting for banks, without claiming a particular new rule. Economic analysis can consider rate, funding, credit and local-demand sensitivity. Social trends can affect expectations for trusted service and relationship banking; technology raises questions around digital access, security and changing payment behaviour. Environmental factors may influence credit assessment, operations and customer needs where physical conditions affect economic activity. Keeping these forces distinct helps avoid treating every external issue as the same type of risk.
- External scan. Separate policy, economic and customer-behaviour questions so their possible effects on banking decisions can be evaluated clearly.
- Resilience lens. Relate technology, legal obligations and environmental exposure to operational continuity and prudent risk management.
- Evidence register. Use the Excel PESTLE framework to track developments and the Word analysis to frame why each category could matter.
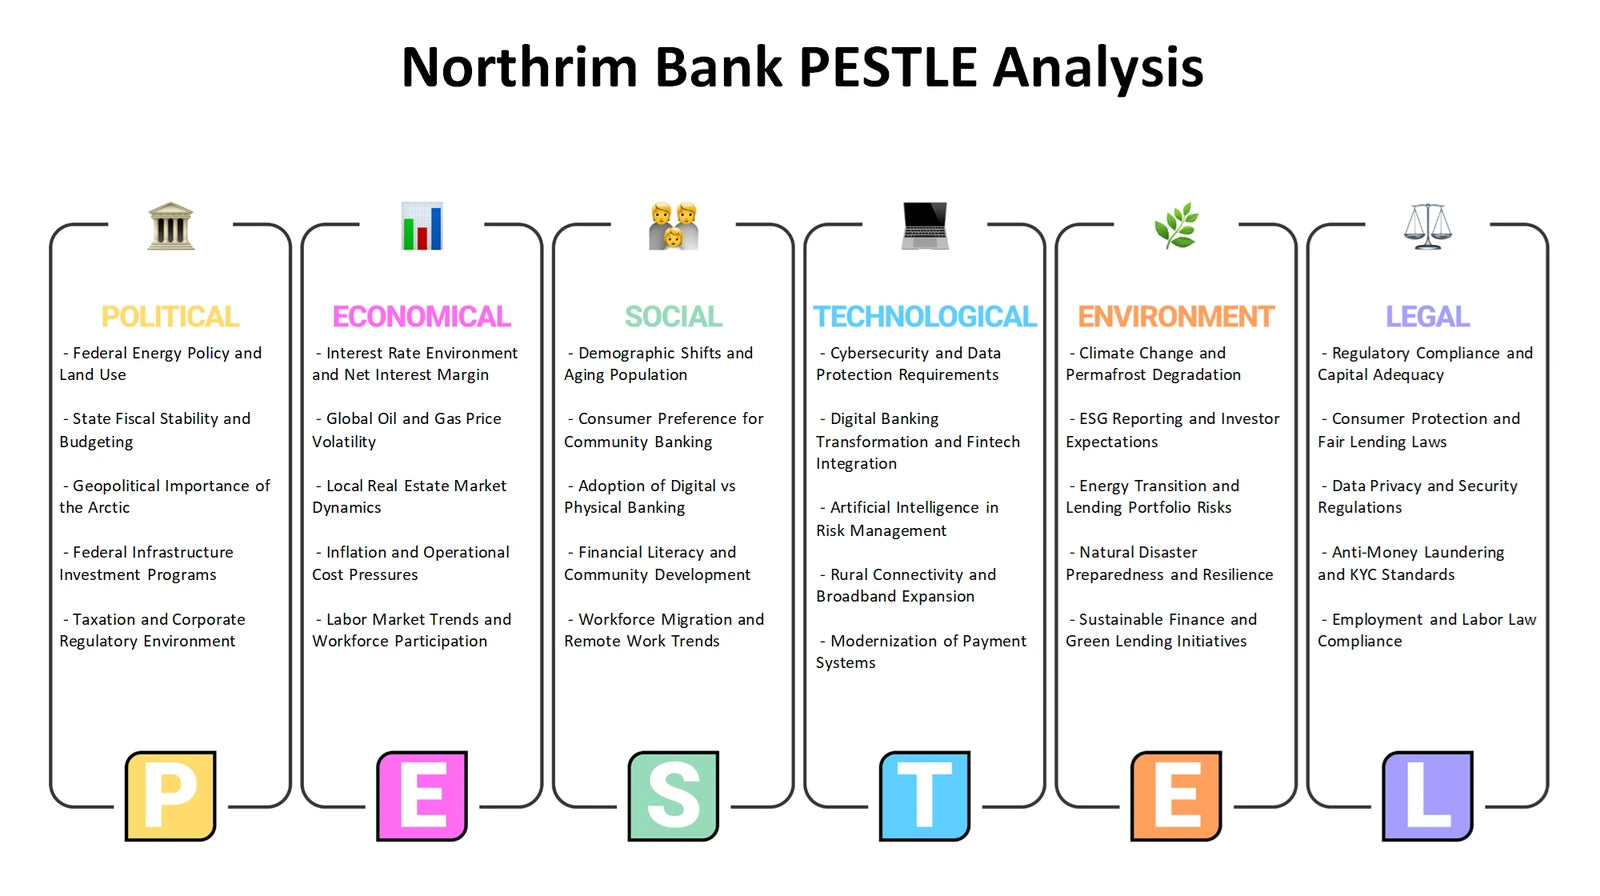
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal banking capabilities and constraints be considered alongside external openings and risks?
The Northrim Bank SWOT analysis distinguishes internal Strengths and Weaknesses from external Opportunities and Threats. The supplied context suggests useful topics to test, including diversified deposit funding, lending capacity, relationship engagement, credit costs, compliance obligations and insurance-related expense. These are not presented as confirmed SWOT findings or ratings. Instead, the framework helps classify what the organisation may control directly, such as capabilities, processes and resource constraints, versus conditions outside its control, such as customer expectations, economic shifts and industry alternatives. Correct classification matters because an internal weakness calls for a different response from an external threat, even when both affect the same product area.
- Internal discipline. Evaluate capabilities and constraints such as funding diversity, credit processes, service capacity and compliance effort as internal considerations.
- External context. Examine potential opportunities and threats arising from customer needs, competitive alternatives and broader banking conditions.
- Action framing. Use the Excel SWOT grid to prioritise questions, then consult the Word analysis to develop balanced discussion around each category.
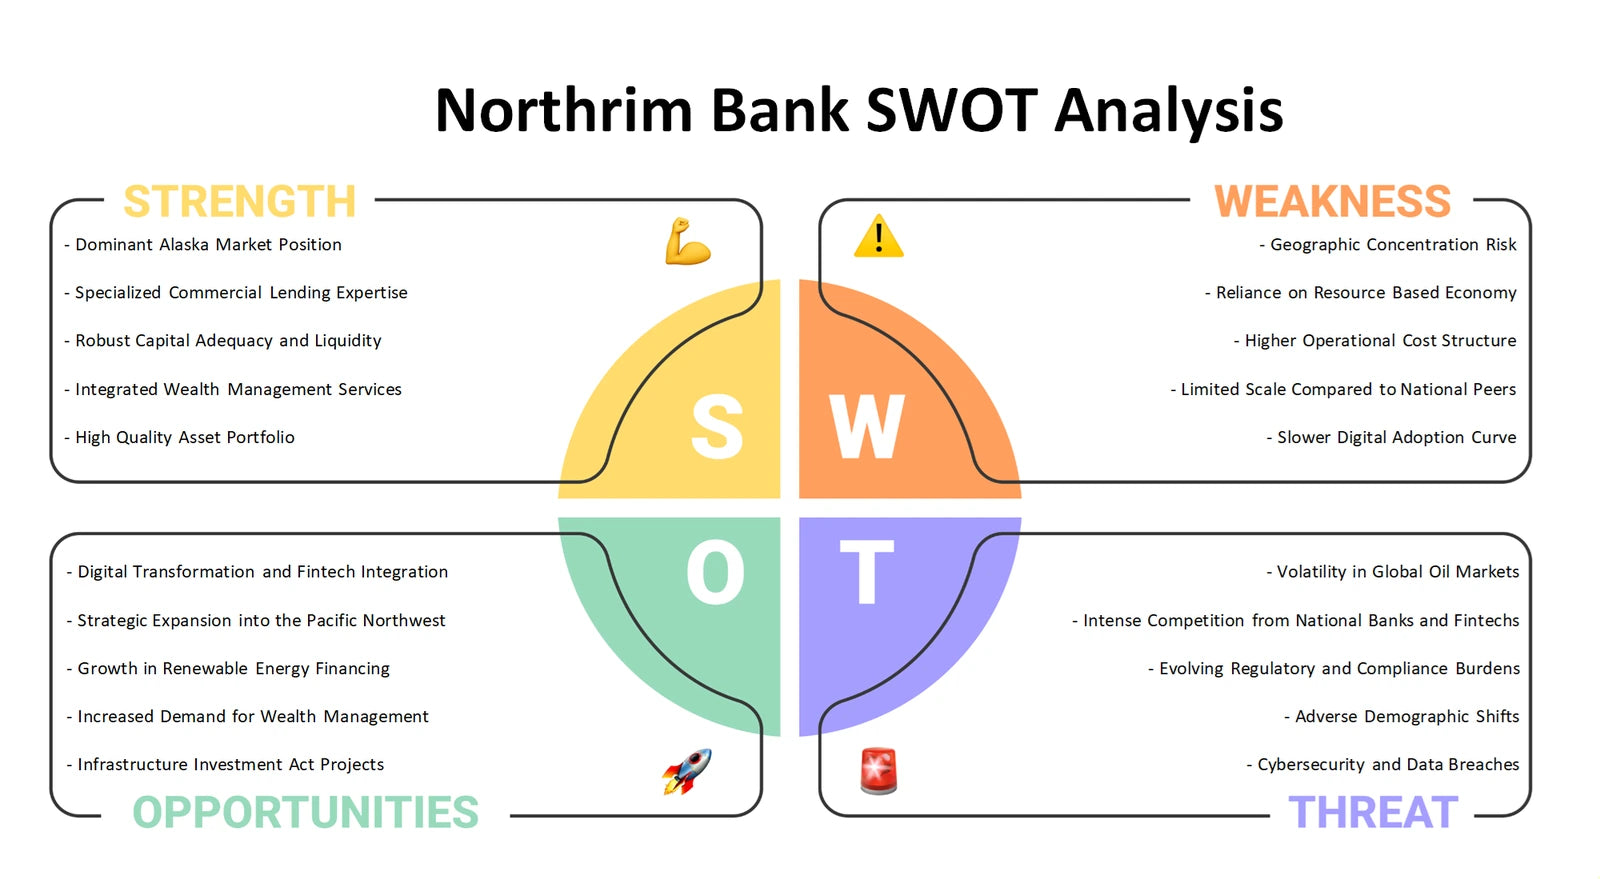
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Bring funding, customer relationships and external conditions into one discussion
Used together, the six perspectives move from portfolio priorities and value creation to industry pressure, customer-facing choices, external change and strategic positioning. The Excel files provide structured places to compare assumptions and evidence, while the Word files provide detailed company analysis for interpreting those comparisons. This combination can help customers develop a more coherent set of questions around Northrim Bank's deposit funding, lending activity, relationship model and regulated operating environment.
Company background: Northrim Bank — matching product-context page.