

Northeast Bank: Banking Business and Lending Economics – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Northeast Bank Strategy Analysis Bundle
The available product context describes Northeast Bank as a relationship-led banking business serving commercial and retail customers through lending, deposit and treasury services. Assigned bankers are presented as key client contacts who coordinate activity across these services, while institutional loan buyers may participate in loan sales, participations or syndications. The available context does not verify a legal entity or geography, so this bundle focuses on the supported banking model rather than attributing facts from similarly named organizations.
For Northeast Bank, strategic questions include how relationship economics support deposit gathering and loan placement, how capital can be allocated across lending opportunities, and how documentation and servicing quality affect institutional counterparties. The six analyses help organize those questions from portfolio, operating-model, market-pressure, marketing, external-environment and capability perspectives without presenting unverified conclusions as company facts.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending, deposit and institutional-market activities deserve capital, management attention and operating capacity?
The Northeast Bank BCG Matrix frames portfolio choices through market growth and relative market share. Rather than assuming that any product belongs in a quadrant, it helps compare lending niches, deposit propositions, treasury relationships and loan-distribution activities against the evidence needed to classify them as Stars, Cash Cows, Question Marks or Dogs. This matters in banking because balance-sheet capacity, relationship-manager time and risk oversight are limited resources. A mature service with dependable economics can require different treatment from a developing opportunity that needs investment before its competitive position is clear.
- Portfolio evidence. Compare relative position and growth conditions before treating a business line as a priority or a candidate for restraint.
- Capital discipline. Relate product choices to funding needs, credit risk, servicing capacity and the potential role of loan sales or participations.
- Working view. Use the Excel matrix to map candidate activities, then use the Word analysis to record assumptions, evidence gaps and the reasoning behind potential priorities.
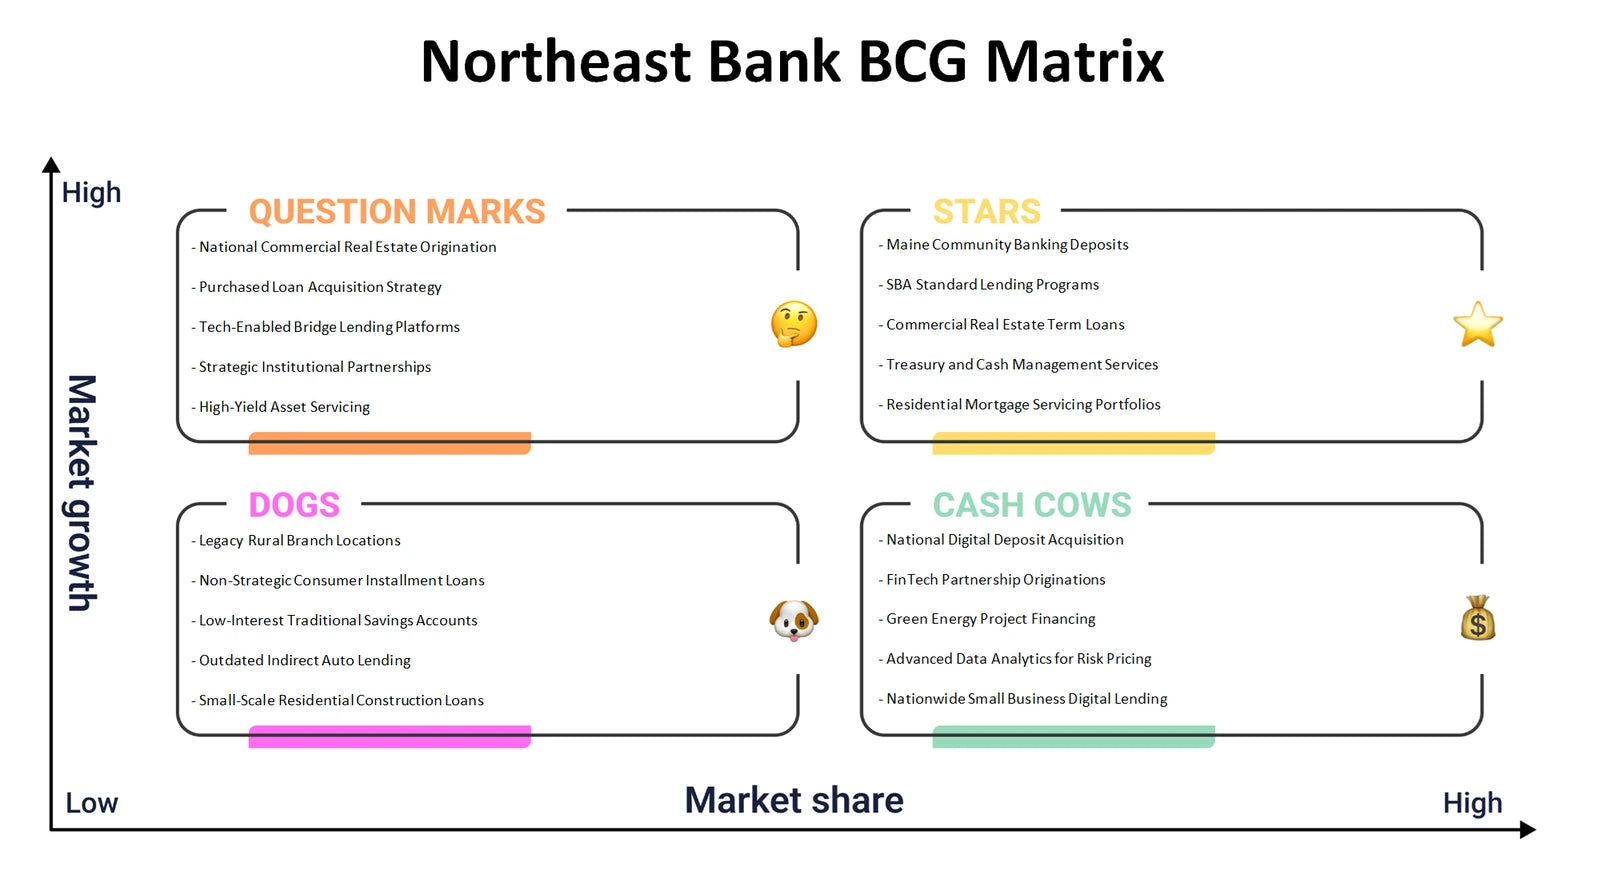
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do relationship banking, loan distribution and coordinated service delivery create value and generate sustainable economics?
The Northeast Bank Business Model Canvas links the full nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. The supplied context points to commercial and retail customers, relationship-led service, lending, deposits, treasury services and institutional loan counterparties. The canvas helps examine how these elements fit together: bankers and servicing capabilities may support trust and execution, while funding, credit processes, documentation and distribution relationships shape the cost and revenue logic. It is a useful way to test whether each promise to a customer can be delivered consistently and profitably.
- Relationship architecture. Examine how assigned bankers, customer contact points and cross-service coordination may support retention and referral activity.
- Economic connections. Trace how deposits, lending income, treasury relationships and loan transactions connect to resources, operating activities and costs.
- Model workshop. Populate the Excel canvas as a one-page operating map and use the Word analysis to explore interdependencies, trade-offs and open questions in greater detail.
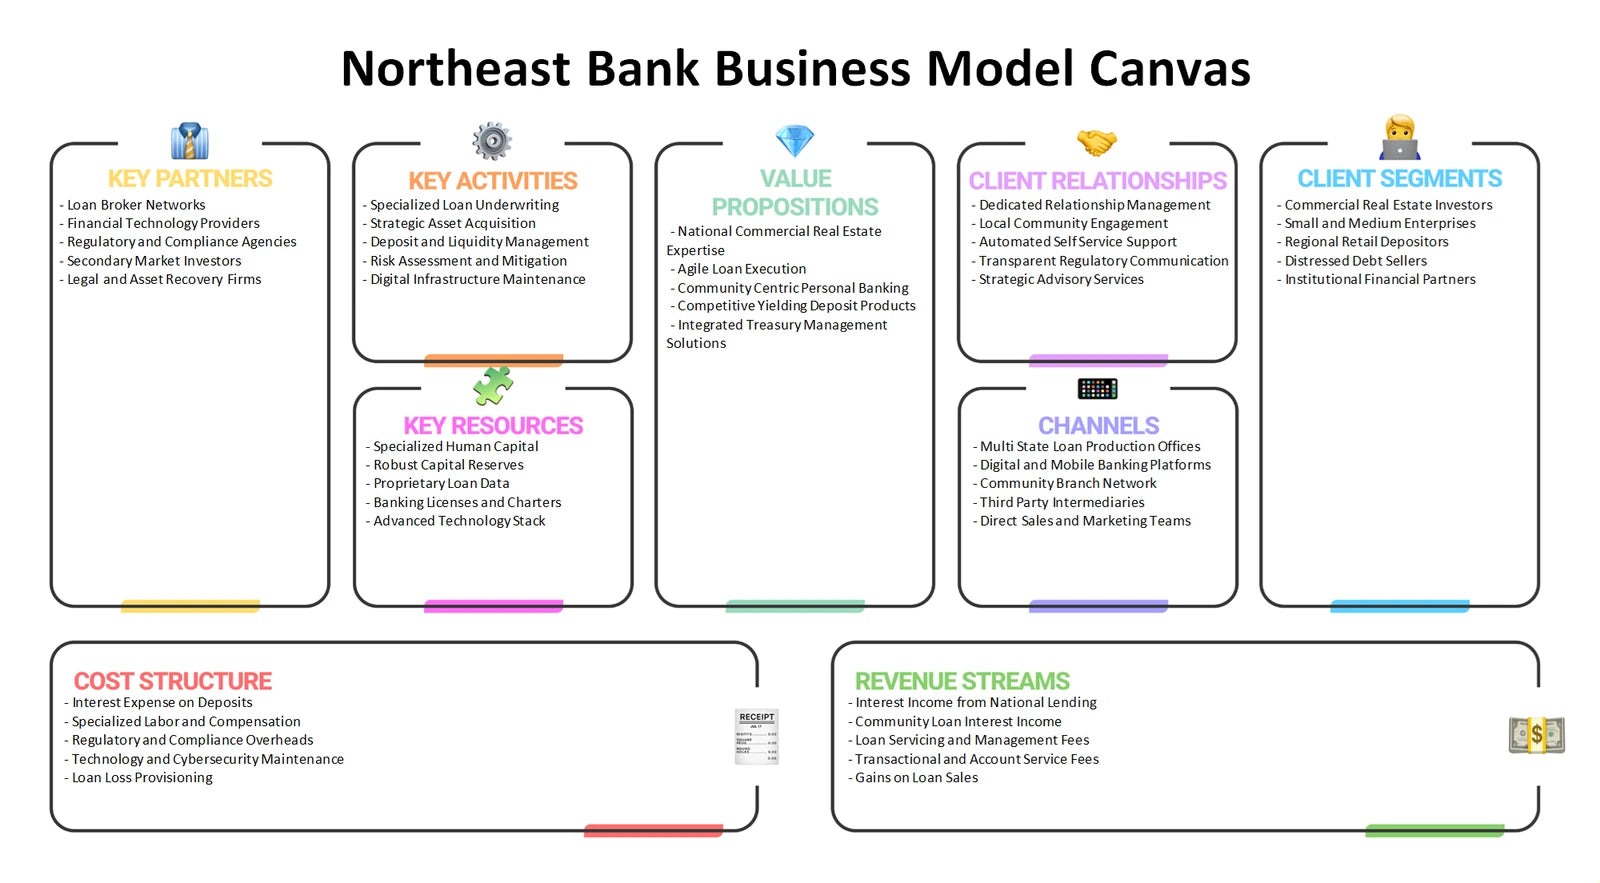
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could affect the attractiveness and bargaining dynamics of relationship-led banking services?
Northeast Bank Porter's Five Forces examines rivalry among financial-service providers, supplier power, buyer power, the threat of new entrants and the threat of substitutes. In this context, suppliers can include funding sources, technology providers and specialized service partners; buyers include depositors, borrowers and institutional counterparties that can compare execution quality and terms. Substitutes are not only other banks: they can include alternative financing, payments, cash-management or investment routes that meet a similar customer need. The framework does not claim force scores; it creates a disciplined basis for considering where price pressure, switching costs, trust, regulation and scale may influence returns.
- Competitive friction. Assess where relationship continuity and reliable execution may matter more than a narrowly comparable product feature.
- Counterparty leverage. Consider how borrower choice, depositor sensitivity and institutional documentation requirements can affect negotiating power.
- Pressure map. Use the Excel framework to compare the five forces and use the Word analysis to document sector-specific implications and monitoring points.
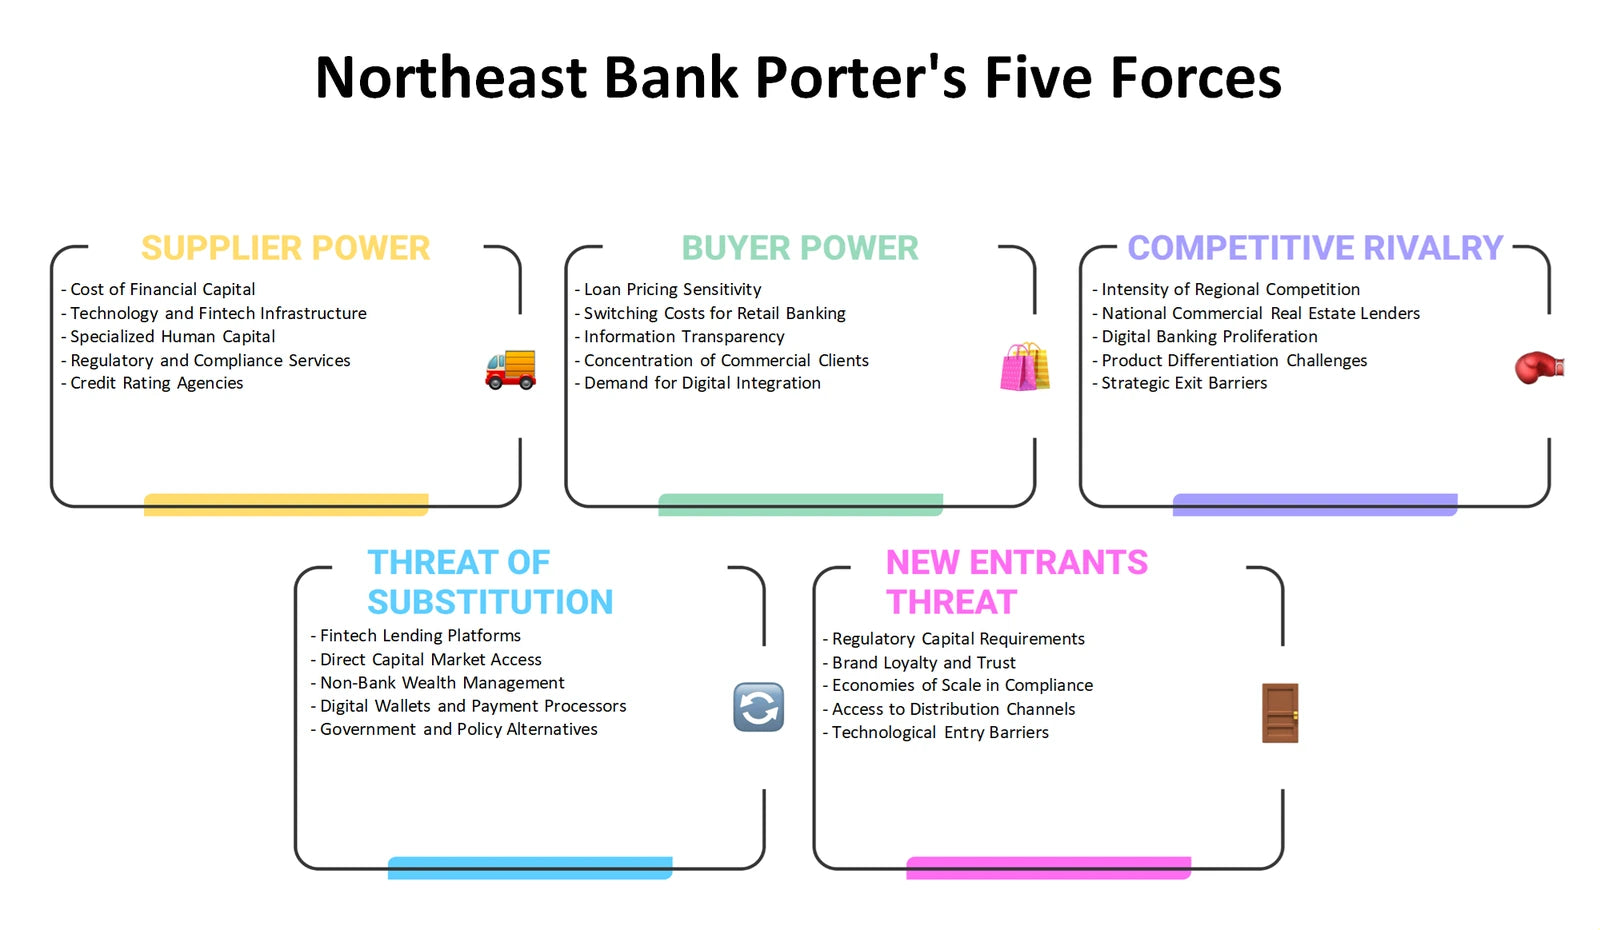
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can lending, deposit and treasury offerings be positioned and communicated while preserving a credible relationship-banking proposition?
The Northeast Bank Marketing Mix considers Product, Price, Place and Promotion in a financial-services setting. Product analysis can distinguish the role of loans, deposit services, treasury support and institutional transaction capabilities. Price is broader than a posted fee: it can include rates, terms, service conditions and the value customers place on speed, certainty and coordinated delivery. Place examines relationship managers, direct service channels and intermediary or institutional routes where relevant. Promotion considers how a bank communicates trust, responsiveness and suitability without assuming particular campaigns or channel shares. Together, the 4Ps help connect customer needs with an offer that operations and risk controls can support.
- Offer design. Compare customer needs across commercial, retail and institutional contexts instead of treating all banking relationships as identical.
- Value communication. Test whether messages about execution, service and fairness align with the practical experience delivered by bankers and processes.
- Planning sequence. Use the Excel 4Ps structure to organize choices by audience and use the Word analysis to develop the rationale behind positioning and channel decisions.
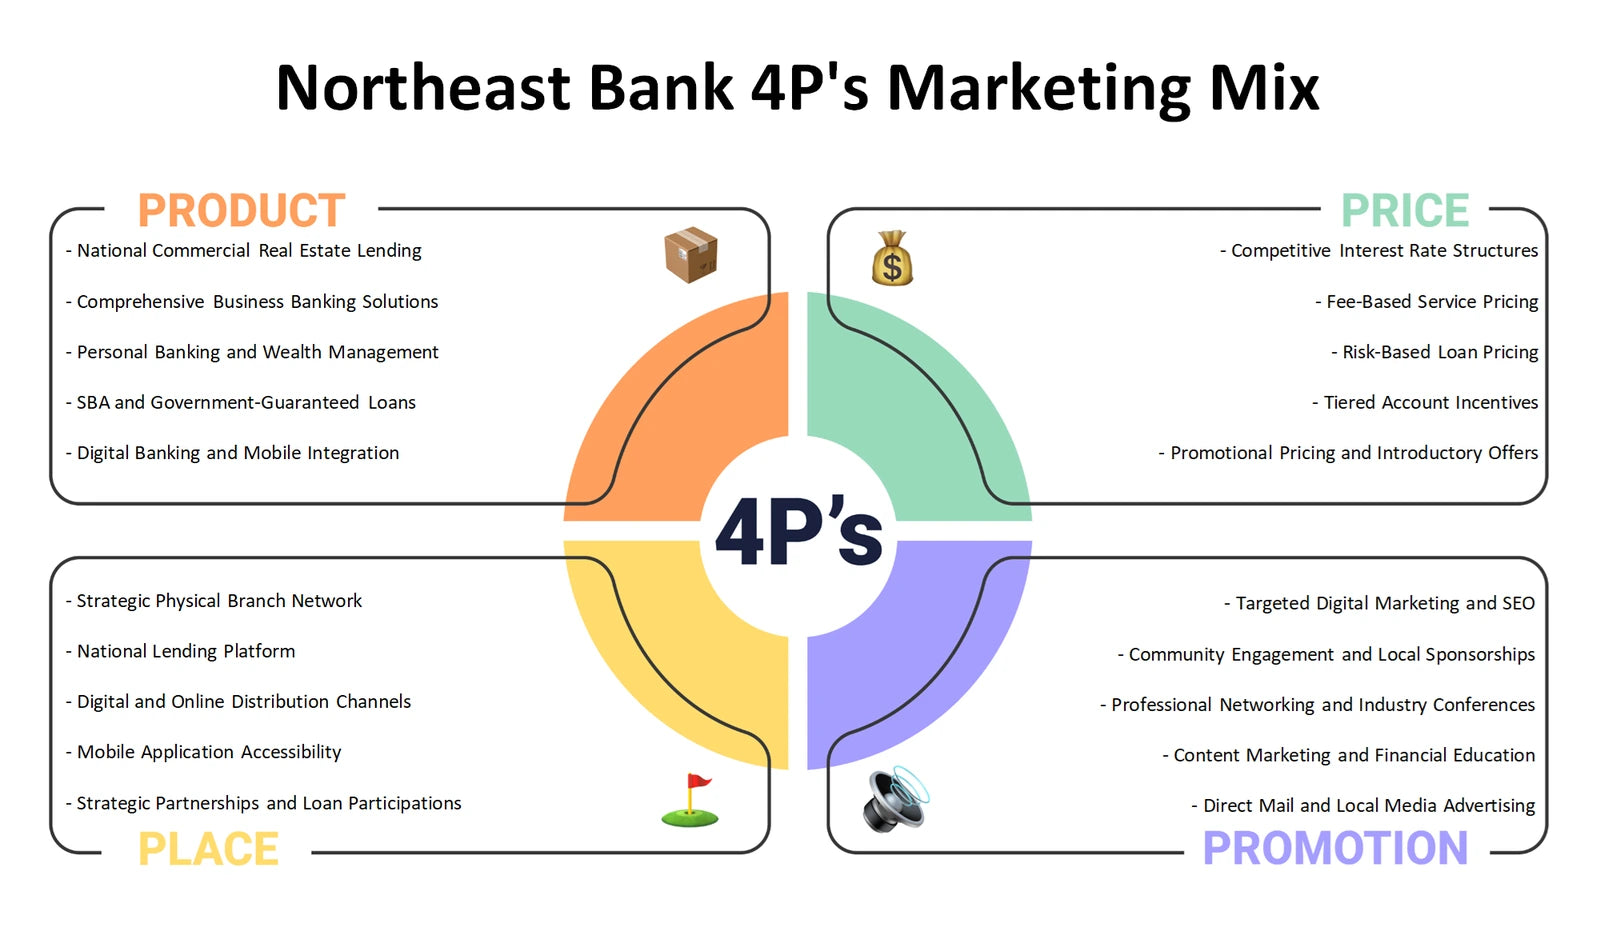
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should be monitored when assessing a relationship-focused bank's lending, funding and service model?
The Northeast Bank PESTLE analysis, also commonly called PESTEL, organizes external influences into Political, Economic, Social, Technological, Legal and Environmental categories. Political and legal factors can shape supervisory expectations and financial-services rules; economic conditions can affect credit demand, funding costs and borrower resilience. Social expectations may influence trust and preferences for human support or digital convenience. Technology can change service delivery, fraud exposure and data-management needs. Environmental conditions can affect borrowers, collateral and operating continuity. The framework treats these as analytical categories to investigate, not as claims that a particular law, rate movement or event has already changed Northeast Bank's position.
- External watchlist. Separate macroeconomic questions from policy, compliance, technology and customer-behavior developments that may require different responses.
- Transmission paths. Link each external factor to possible effects on lending, deposits, treasury service, risk management or institutional transactions.
- Scenario record. Use the Excel grid to rank relevance and timing, then use the Word analysis to explain assumptions, signals to monitor and possible strategic implications.
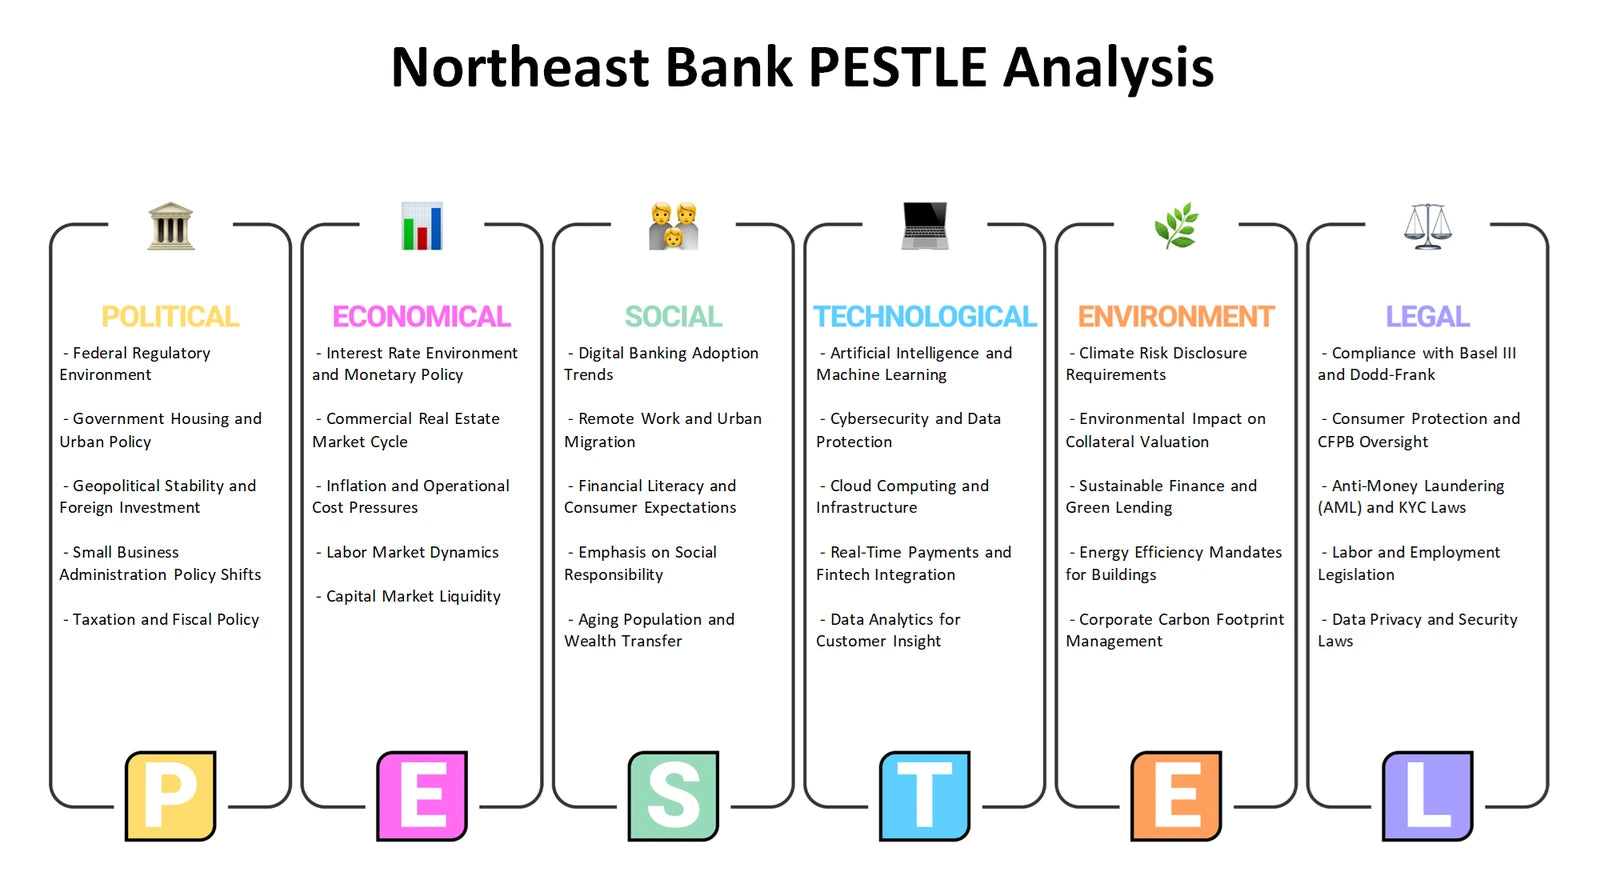
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal relationship and execution capabilities be considered alongside external opportunities and threats facing the banking model?
The Northeast Bank SWOT analysis separates internal Strengths and Weaknesses from external Opportunities and Threats. The available context makes relationship continuity, coordinated banker support, loan-placement capability and servicing quality relevant subjects for internal assessment, but it does not establish them as scored advantages. Potential internal constraints may include capacity, process complexity, funding dependence or concentration questions that require evidence. Opportunities and threats should be assessed outside the organization: changing customer needs, credit conditions, technology expectations, competitive alternatives and regulatory developments can alter the environment. Keeping these categories distinct makes the analysis more useful than a broad list of positive and negative observations.
- Capability test. Examine whether relationship practices, documentation quality and cross-service coordination are repeatable internal capabilities or areas requiring reinforcement.
- Market alignment. Compare those capabilities with external openings and risks rather than presenting a plausible opportunity as an internal strength.
- Decision trail. Use the Excel SWOT layout to prioritize issues and use the Word analysis to capture evidence, dependencies and possible responses for discussion.
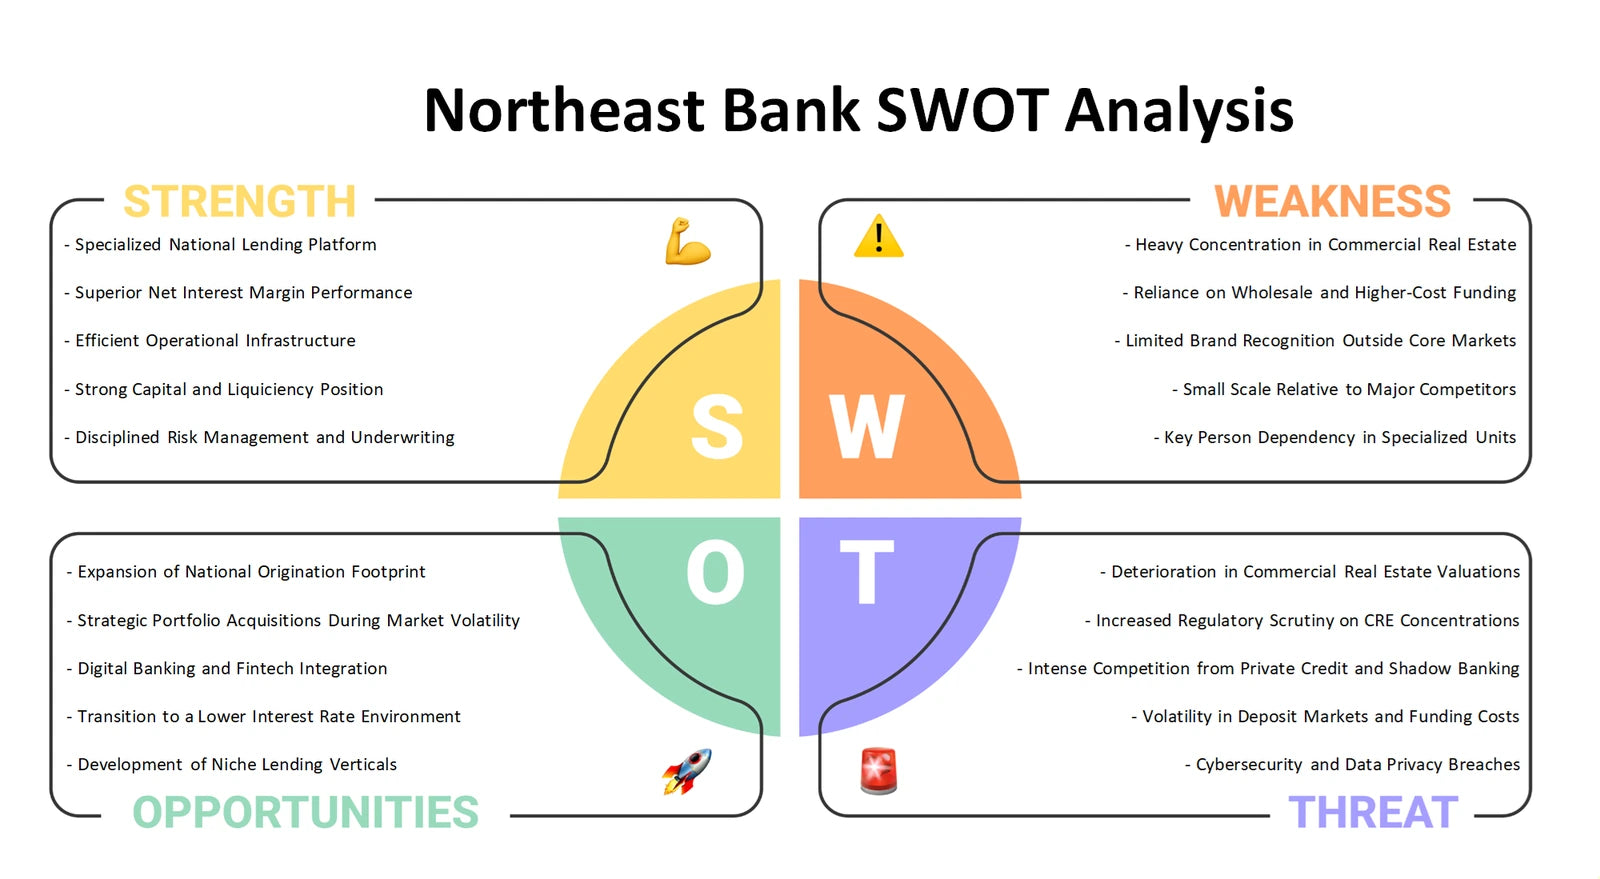
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices with the banking model
Used together, the six perspectives connect Northeast Bank's relationship-led service model with portfolio priorities, competitive pressure, customer-facing choices, external conditions and capability questions. The Excel frameworks provide structured places to compare issues, while the detailed Word analyses help develop a more reasoned strategic discussion around lending, deposits, treasury services and institutional transaction relationships.
Company background: Northeast Bank — supplied product-context page.