

NI Holdings: Insurance Business and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
2026 company context · Six strategic perspectives
NI Holdings Strategy Analysis Bundle
NI Holdings is the workbook display name for NI Holdings, Inc., a publicly reporting fire, marine and casualty insurance business classified under SIC 6331. This bundle examines the strategic questions around a specialist insurance model: serving policyholders through selected risk appetites, applying disciplined underwriting, and working with agent and partner distribution relationships to reach suitable submissions and maintain underwriting quality.
In its second-quarter 2026 Form 10-Q filing, filed August 7, 2026, NI Holdings, Inc. reported revenue of USD 70.234 million and GAAP net income of USD 146,000 for April 1 through June 30, 2026. Those reported quarterly figures make questions about profitable growth, distribution quality and risk-adjusted pricing especially practical topics for the six connected analyses.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance products, distribution niches or growth initiatives deserve capital and management attention when market growth and relative market share point in different directions?
The NI Holdings BCG Matrix provides a disciplined way to compare portfolio priorities rather than treating every underwriting opportunity as equally valuable. It uses market growth and relative market share to organize possible Stars, Cash Cows, Question Marks and Dogs. For an insurer, the useful comparison may involve lines of business, targeted customer niches, geographic opportunities or agent-supported propositions, while recognizing that a quadrant is an analytical test rather than an established company finding. The lens is helpful where growth in written business must be weighed against claims experience, pricing adequacy, underwriting capacity and the resources needed to support a specialty segment.
- Portfolio logic. Compare mature, cash-generating activities with areas where growth may require added underwriting, service or distribution investment.
- Relative position. Test whether a niche has enough competitive presence and attractive growth to justify attention without assuming a market-share result.
- Decision record. Use the Excel matrix to map alternatives and the Word analysis to document the assumptions, evidence needs and resource-priority discussion.
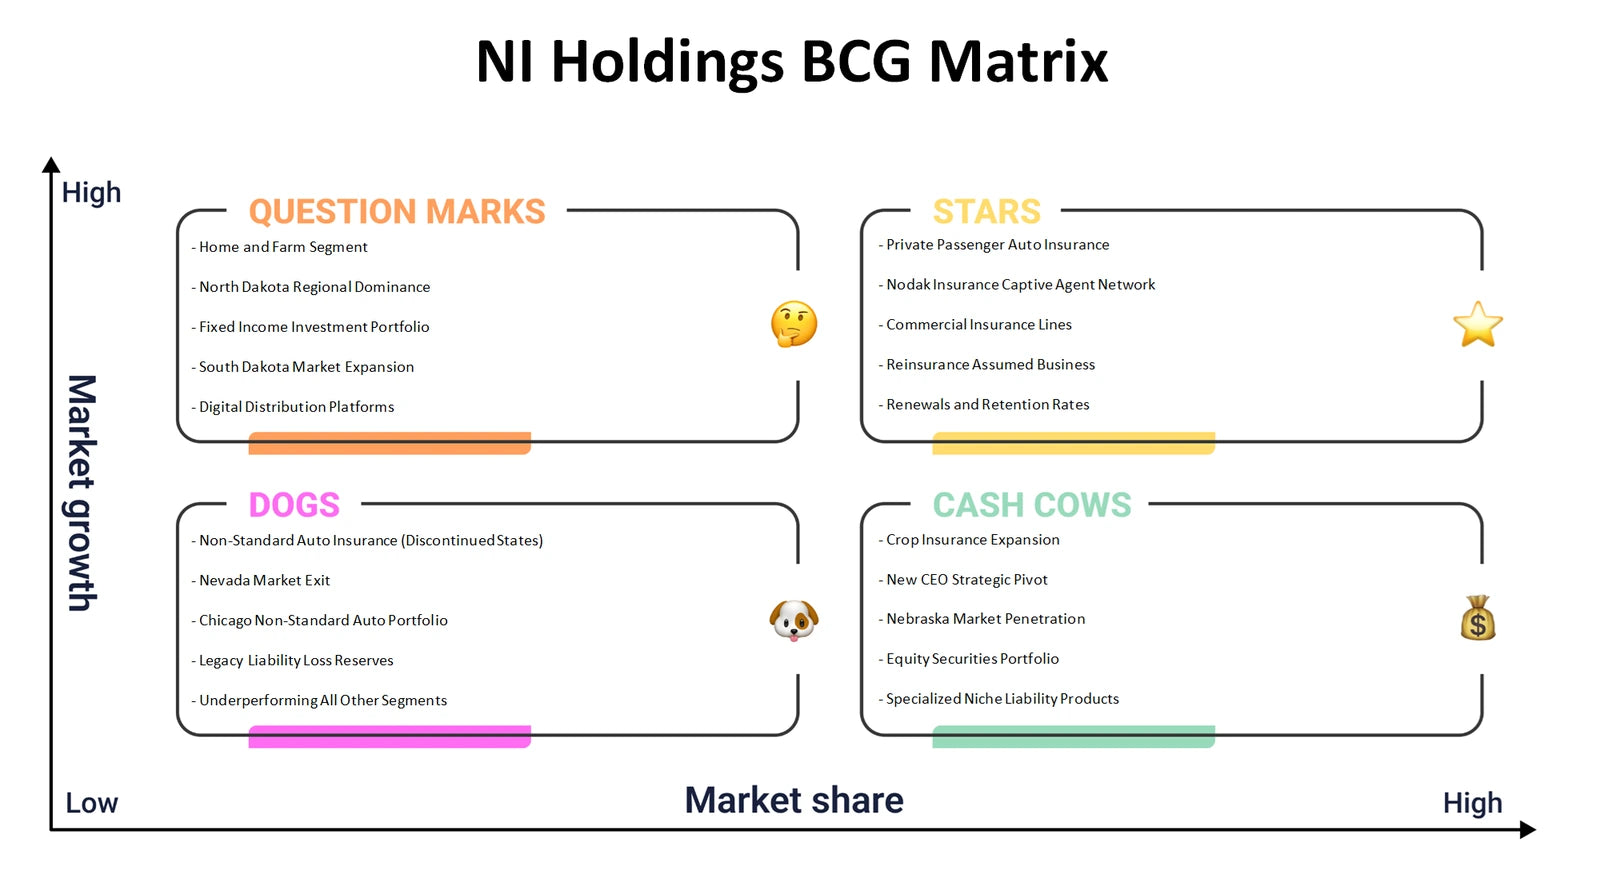
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do risk selection, agent relationships and insurance economics connect from customer need through to sustainable revenue?
The NI Holdings Business Model Canvas brings the operating model into one connected view. It helps examine customer segments and value propositions alongside channels and customer relationships, then links revenue streams to key resources, key activities, key partnerships and cost structure. In this context, policyholders and intermediaries may have different needs: buyers seek appropriate protection and dependable service, while agents need clear appetite guidance and responsive placement decisions. The Canvas helps connect those needs to underwriting expertise, risk data, referral processes, claims capability, technology and distribution partnerships. It also encourages users to test how premium revenue and risk-bearing economics are affected by acquisition costs, loss experience and the cost of supporting disciplined growth.
- Value delivery. Trace how focused insurance propositions move from submission through underwriting, policy service and ongoing relationship management.
- Economic links. Explore how revenue streams, partner incentives and operating costs can reinforce or strain profitability targets.
- Connected view. Populate the Excel blocks for workshop discussion, then use the Word analysis to add context behind the relationships and trade-offs.
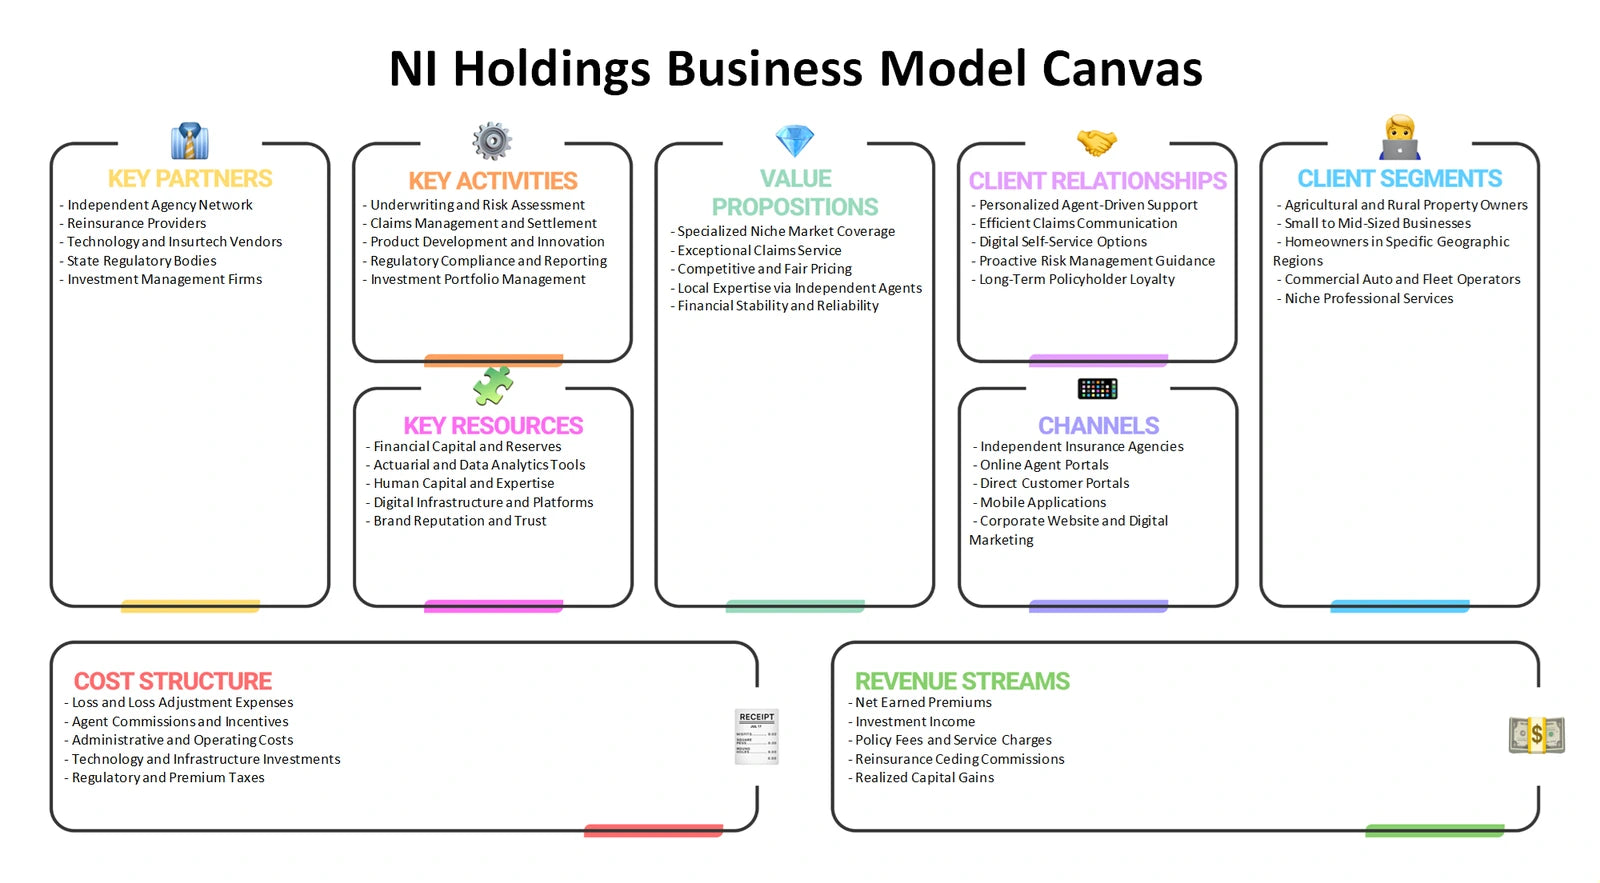
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures can shape underwriting margins and the durability of a niche insurance position?
NI Holdings Porter's Five Forces analysis examines the competitive structure surrounding property and casualty insurance without assigning unsupported force scores. Rivalry can arise when insurers compete for acceptable risks, agent attention and renewal business. Buyer power matters because insureds and intermediaries can compare coverage terms, service and price, while supplier power may include the influence of reinsurance capacity, specialist service providers, technology vendors and distribution partners. The framework also tests the threat of new entrants, including businesses targeting attractive specialist niches, and the threat of substitutes such as self-insurance, alternative risk-transfer arrangements or customers retaining more risk. These pressures matter because growth that appears attractive may still weaken returns if pricing discipline or risk selection is compromised.
- Margin pressure. Identify where competitive pricing, reinsurance conditions or agent expectations may affect the economics of a selected segment.
- Alternative choices. Consider substitutes that meet a customer’s risk-financing need without being a direct insurance competitor.
- Structured comparison. Use the Excel framework to compare evidence across the five forces and the Word analysis to capture implications for underwriting and distribution choices.
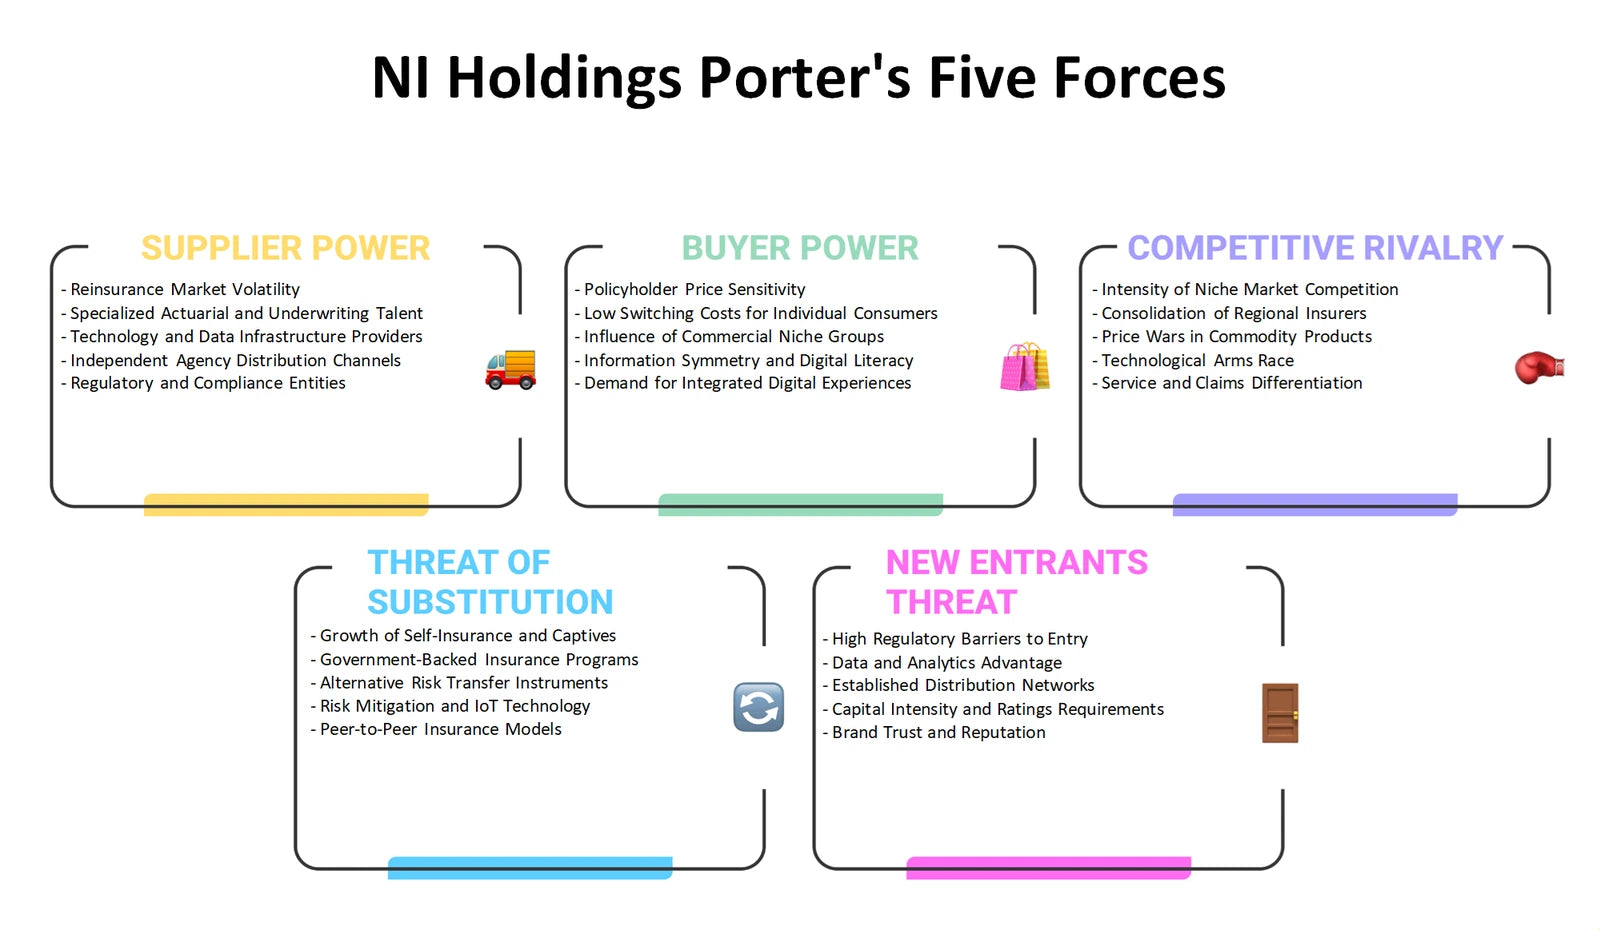
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can product design, pricing, distribution and communication support profitable placement rather than volume for its own sake?
The NI Holdings Marketing Mix considers the 4Ps in a regulated insurance setting. Product is not only an insurance policy; it includes coverage design, eligibility, service expectations and the clarity of underwriting appetite. Price should be examined through risk-adjusted premiums, deductibles, limits and terms rather than as a simple discounting lever. Place focuses on how policies reach suitable customers, including agent and partner relationships that can improve niche access and submission quality. Promotion covers the communication, training and co-marketing activity that help producers understand where a product fits. Bringing these choices together helps users assess whether market messaging attracts the risks the underwriting model is designed to accept.
- Offer fit. Assess whether coverage features and service expectations align with the customer segments and risk types being targeted.
- Channel discipline. Examine how agent guidance, placement support and feedback loops can affect new-business quality and leakage.
- Action planning. Use the Excel 4Ps layout to organize choices by lever, then consult the Word analysis when developing a coordinated product, price, place and promotion discussion.
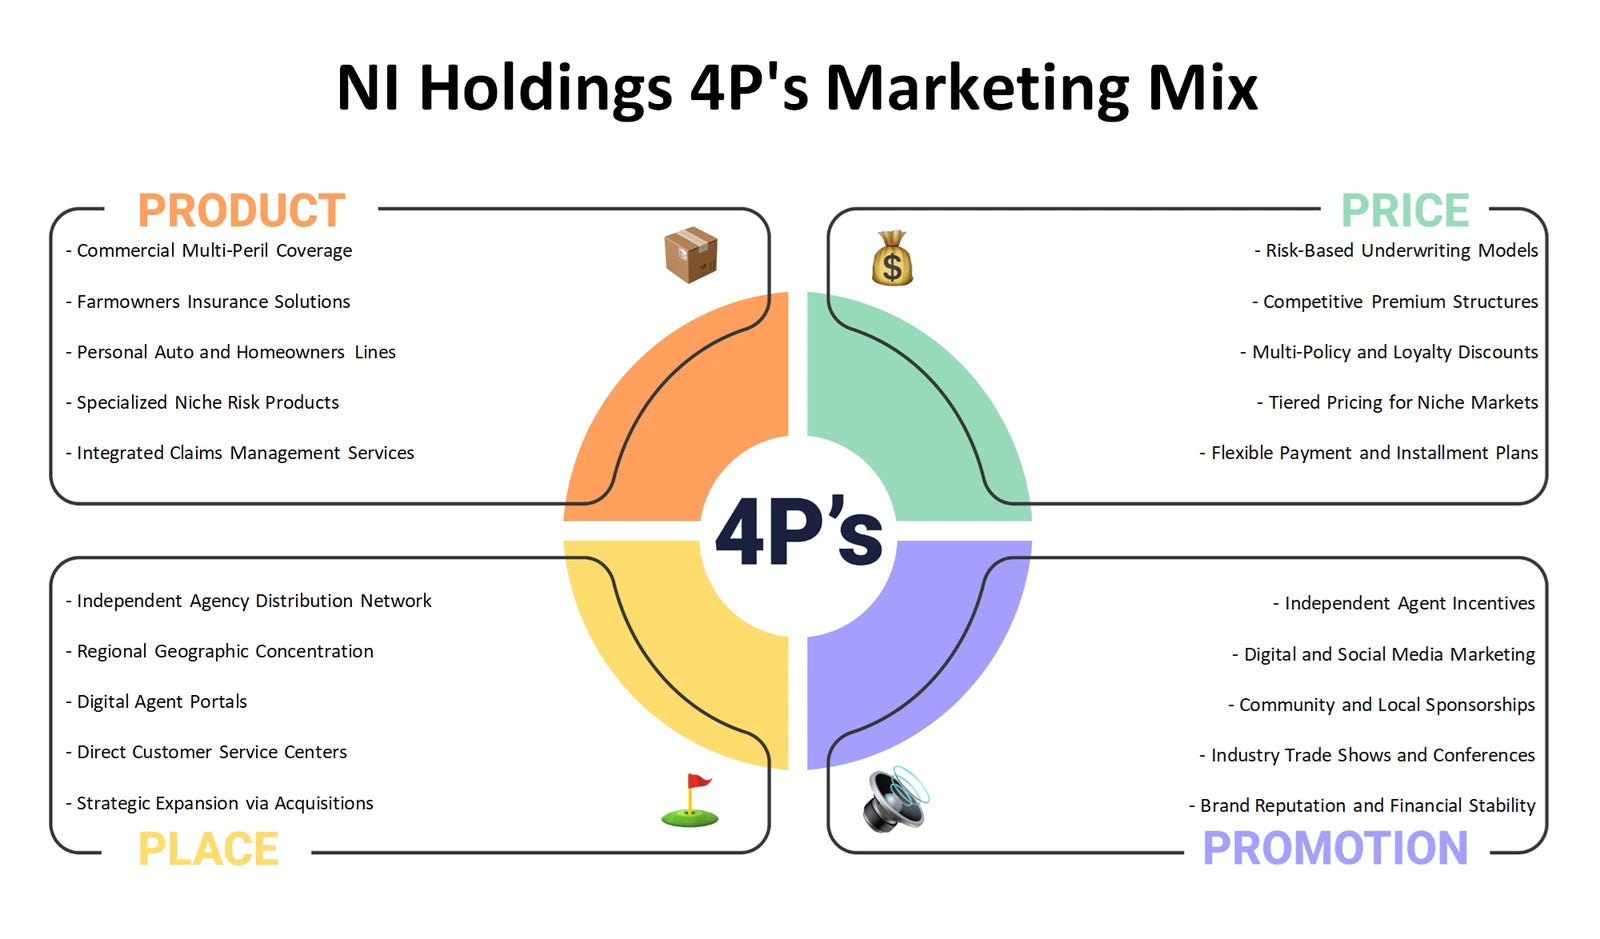
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter insurance demand, claims conditions, distribution economics or compliance requirements?
The NI Holdings PESTLE analysis, also commonly called PESTEL, organizes the external influences that can affect an insurer’s choices. Political and legal factors include insurance regulation, supervisory expectations and changing policy requirements. Economic conditions can influence customer affordability, repair or replacement costs, investment conditions and the pricing environment. Social shifts may change risk awareness, service preferences or the needs of particular customer groups. Technological change can affect data use, cyber exposure, claims handling and the expectations of agents and insureds. Environmental factors matter where weather, catastrophe exposure or resilience considerations affect insured risks. The framework distinguishes issues to monitor from claims that a particular law, rate or event has already changed.
- External scan. Separate policy, economic, social, technology, legal and environmental drivers so different types of uncertainty are not blended together.
- Insurance relevance. Link each potential change to a practical question about pricing, exposure, claims, operations or distribution.
- Monitoring tool. Use the Excel framework to log and prioritize external signals, with the Word analysis supplying explanatory context for review meetings.
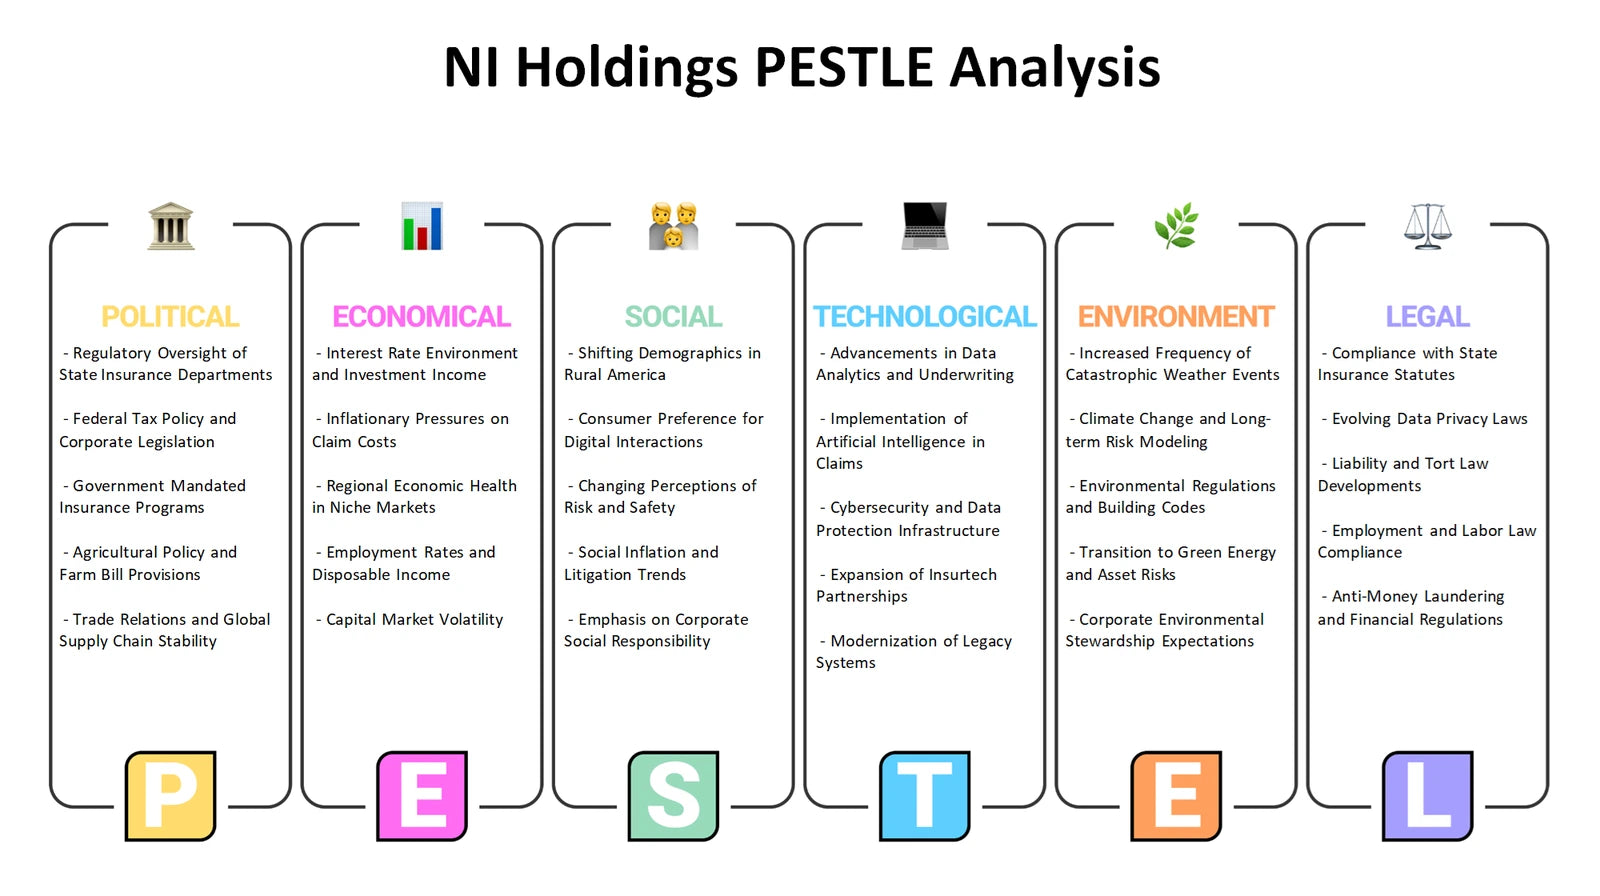
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal underwriting and distribution capabilities be considered alongside the opportunities and threats created by insurance-market conditions?
The NI Holdings SWOT analysis keeps internal and external factors distinct before connecting them. Strengths and weaknesses concern capabilities within the business, such as the potential usefulness of focused risk-selection processes, underwriting authority, agent relationships, data, operational capacity or constraints that should be tested. Opportunities and threats arise outside the company, including evolving customer needs, distribution shifts, competitive conditions, catastrophe exposure or regulatory developments. This distinction is particularly valuable in insurance because an appealing market opportunity is not automatically a strength, and a capable underwriting process does not remove external loss or pricing pressure. The framework supports a more balanced conversation about where capabilities may fit market conditions and where gaps may require attention.
- Clear classification. Keep resources, skills and limitations on the internal side, while placing market developments and external risks in opportunities or threats.
- Strategic match. Explore whether an identified capability could support a specific opportunity without treating the proposed match as an established result.
- Priority synthesis. Use the Excel grid to organize inputs from stakeholders and the Word analysis to develop the reasoning behind possible strategic responses.
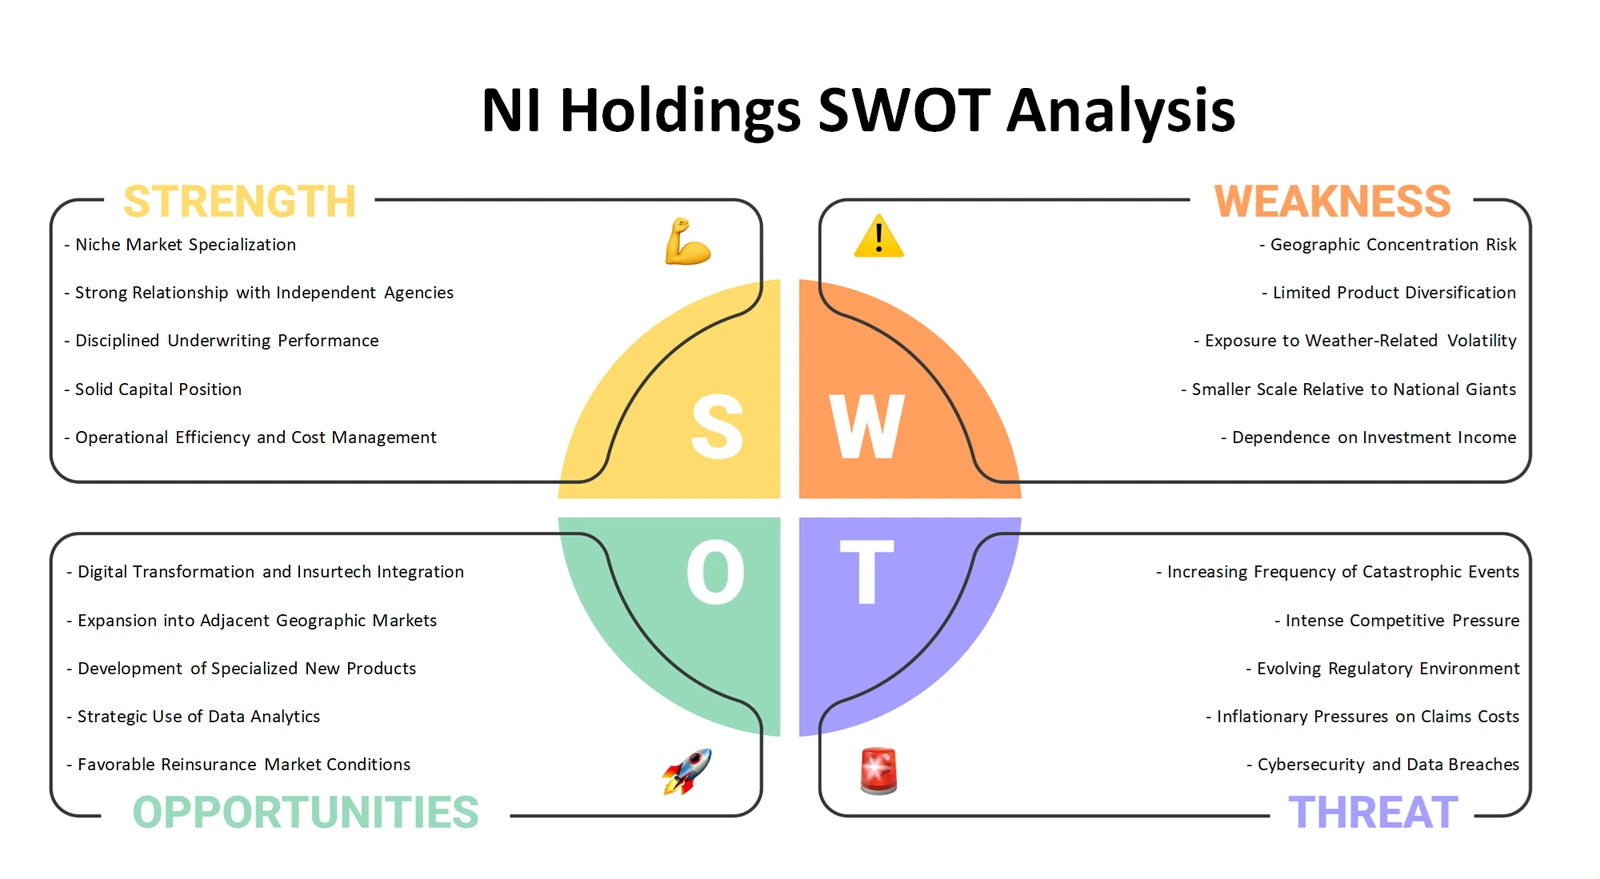
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Six lenses for a more connected insurance strategy discussion
Together, the six perspectives help turn questions about NI Holdings’ portfolio, operating model, industry pressure, market approach, external environment and strategic position into a coherent working agenda. The Excel files provide structured frameworks for comparison and discussion, while the detailed Word files provide company-focused analysis that can support more informed planning, review and team alignment.
Company background: NI Holdings — SEC company submissions profile.