

New York Community Bank: Banking Business and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
New York Community Bank Strategy Analysis Bundle
The supplied product context for New York Community Bank describes a banking business centred on underwriting, originating and servicing multi-family and commercial real-estate loans, with a historic emphasis on rent-regulated multi-family properties in the New York City metropolitan area. It also identifies digital banking services, technology partners, correspondent-bank relationships and interbank liquidity activity as relevant operating context.
This bundle uses that business context to examine how a property-lending bank can balance lending priorities, customer access, funding relationships and external change. Rather than assuming conclusions about any similarly named institution, the six frameworks help organise practical questions about portfolio allocation, digital delivery, competitive pressure and risk-aware strategic choices.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending, deposit and service activities deserve resources when growth potential and relative market position may differ?
The New York Community Bank BCG Matrix provides a disciplined way to compare business activities using market growth and relative market share. For a bank with multi-family and commercial real-estate lending context, the useful question is not whether a loan type is simply large, but whether it has a defensible position, acceptable capacity needs and an attractive growth environment. The familiar Stars, Cash Cows, Question Marks and Dogs categories are analytical tools, not asserted classifications of New York Community Bank activities. They help separate mature funding or relationship businesses from areas that may require careful investment, review or restraint.
- Portfolio comparison. Examine lending categories, deposit relationships and digital service areas against growth and relative-position criteria without assigning unsupported quadrant placements.
- Capital discipline. Consider where credit expertise, technology spending and relationship-management capacity may be most valuable when real-estate markets and funding conditions change.
- Framework use. Use the Excel matrix to organise comparable activities, then use the Word analysis to interpret the assumptions and strategic trade-offs behind each possible priority.
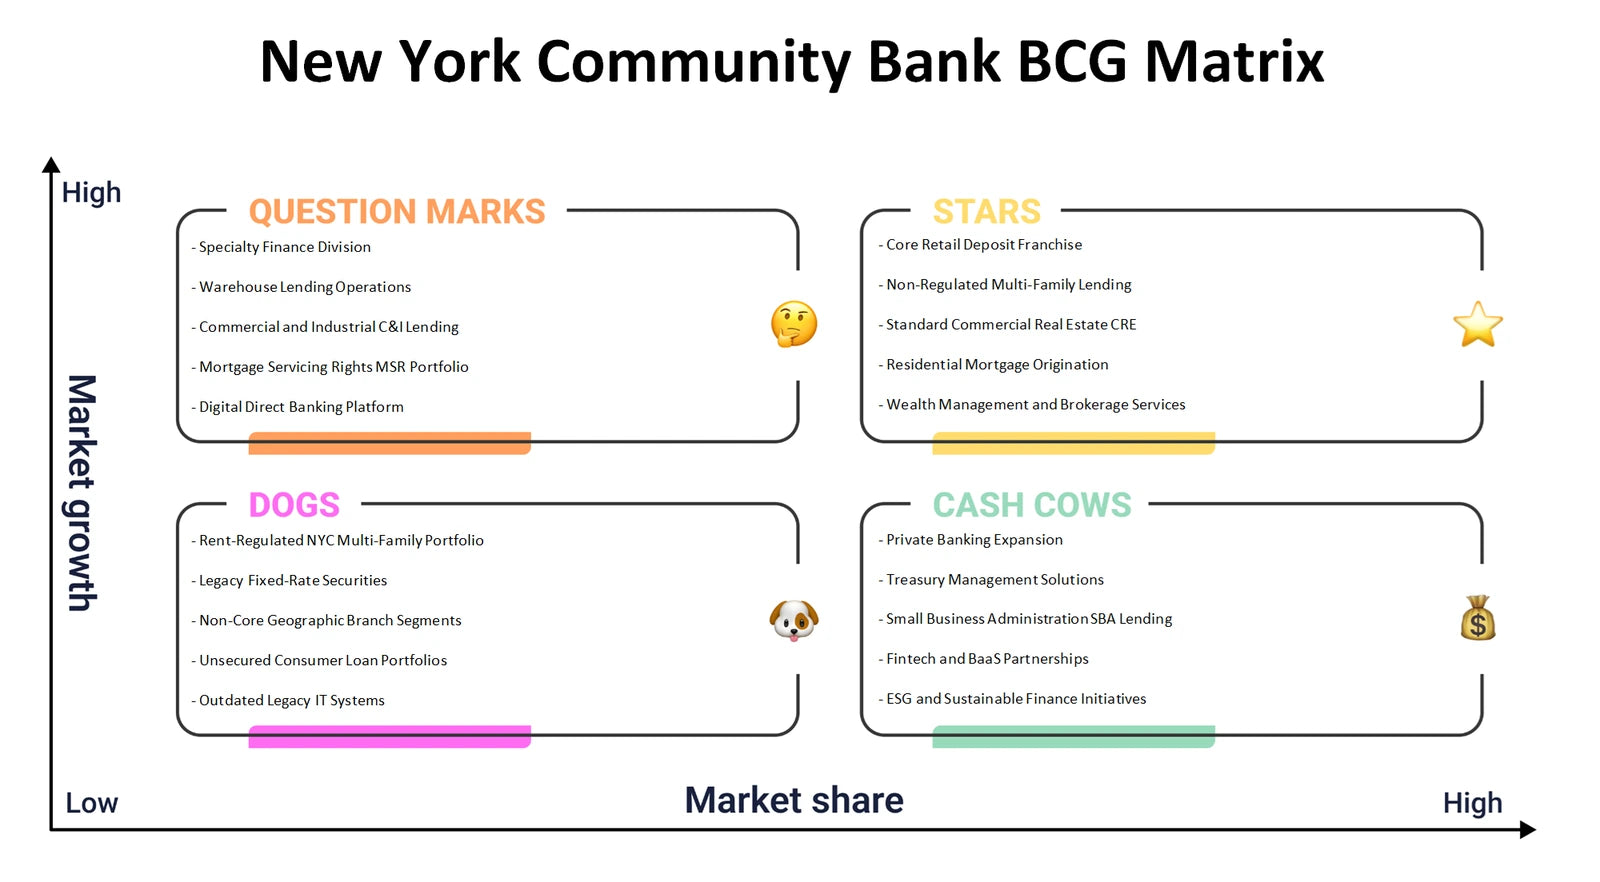
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do property-lending relationships, banking channels, funding partners and operating capabilities connect to value creation?
The New York Community Bank Business Model Canvas maps the logic linking customers, services and economics. It considers customer segments such as borrowers, deposit customers and other financial institutions; value propositions tied to credit access, servicing and banking convenience; and channels that can include branches, digital platforms and relationship-led contact. It also connects customer relationships and revenue streams with key resources, lending and servicing activities, technology and correspondent-bank partnerships, and the cost structure required to operate safely. For a bank, this view is especially useful because funding, risk management and service delivery affect the feasibility of every customer promise.
- Customer-value fit. Explore how multi-family and commercial borrowers may value underwriting knowledge, servicing continuity and access to banking services alongside deposit customers' convenience needs.
- Economic connections. Trace how lending income, deposits, operating systems, credit processes and liquidity relationships interact rather than evaluating any building block in isolation.
- Framework use. Populate the Excel canvas as a single-page operating map and use the Word analysis to examine the dependencies, assumptions and possible pressure points behind the map.
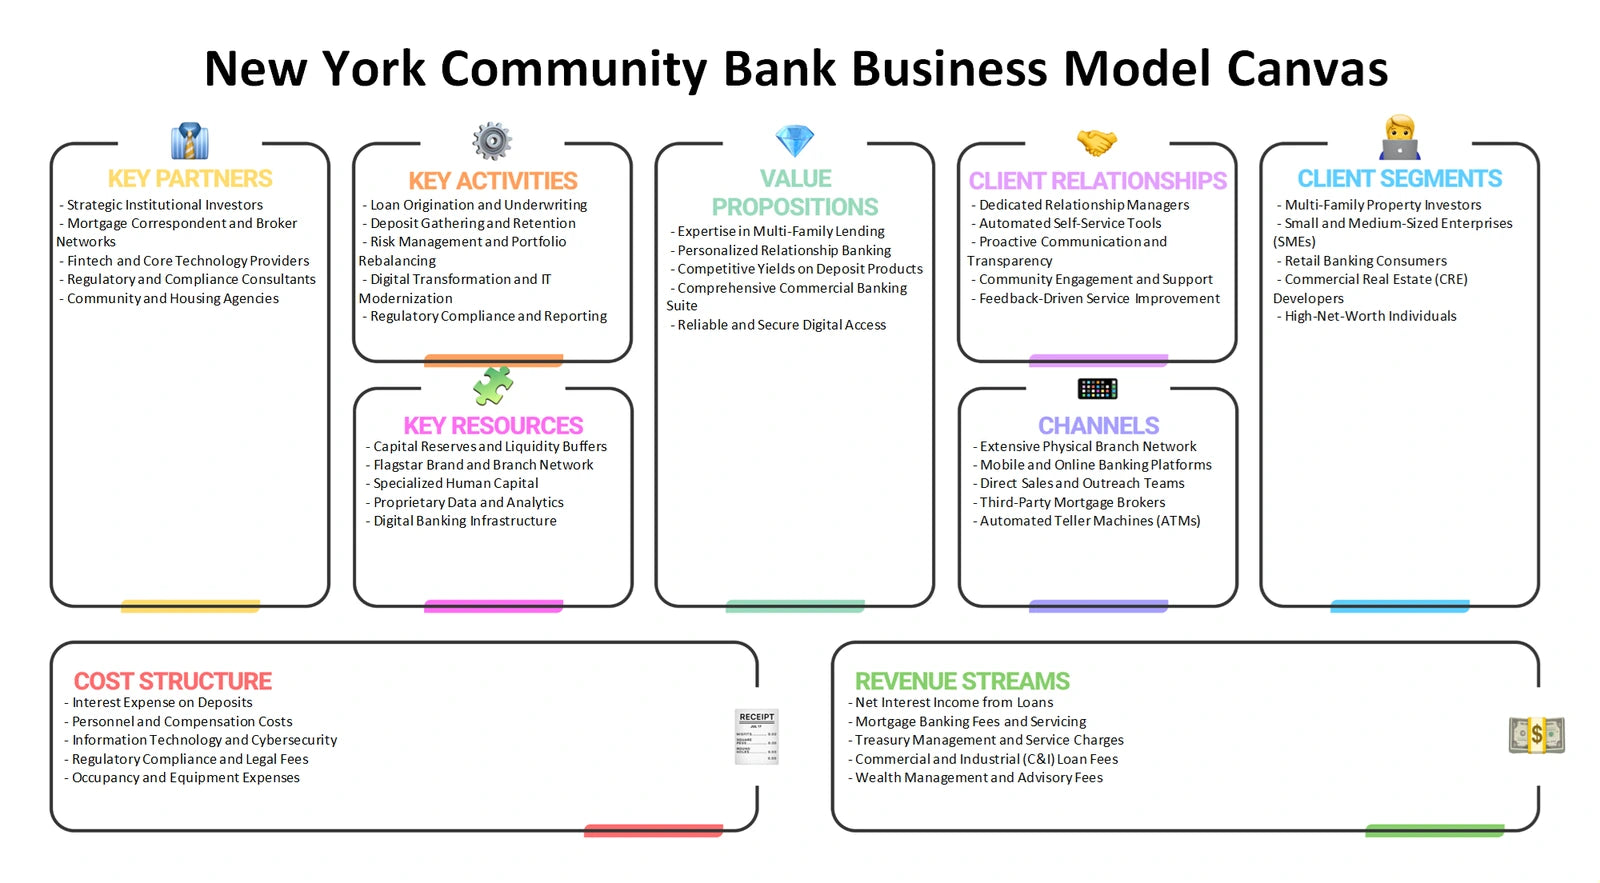
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could shape the attractiveness of relationship banking and commercial real-estate lending?
New York Community Bank Porter's Five Forces analysis examines the banking and property-finance environment through rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes. Rivalry can involve competition for creditworthy borrowers and stable deposits. Supplier power is relevant to funding sources, financial-market access, technology providers and specialist talent. Buyer power can rise when borrowers or depositors have many alternatives. New entrants may use digital models or specialised lending approaches, while substitutes include non-bank finance, capital-market funding, cash-management alternatives and other ways customers meet borrowing or transaction needs. The framework does not assign force scores; it structures a more careful industry discussion.
- Funding and technology. Assess how dependence on deposits, correspondent relationships and digital-platform providers can affect bargaining leverage and operating flexibility.
- Alternatives to bank credit. Compare traditional lending with non-bank lenders and other financing routes that may serve commercial-property customers differently.
- Framework use. Record evidence and discussion prompts in the Excel force map, then use the Word analysis to connect each pressure to customer retention, pricing discipline and operating choices.
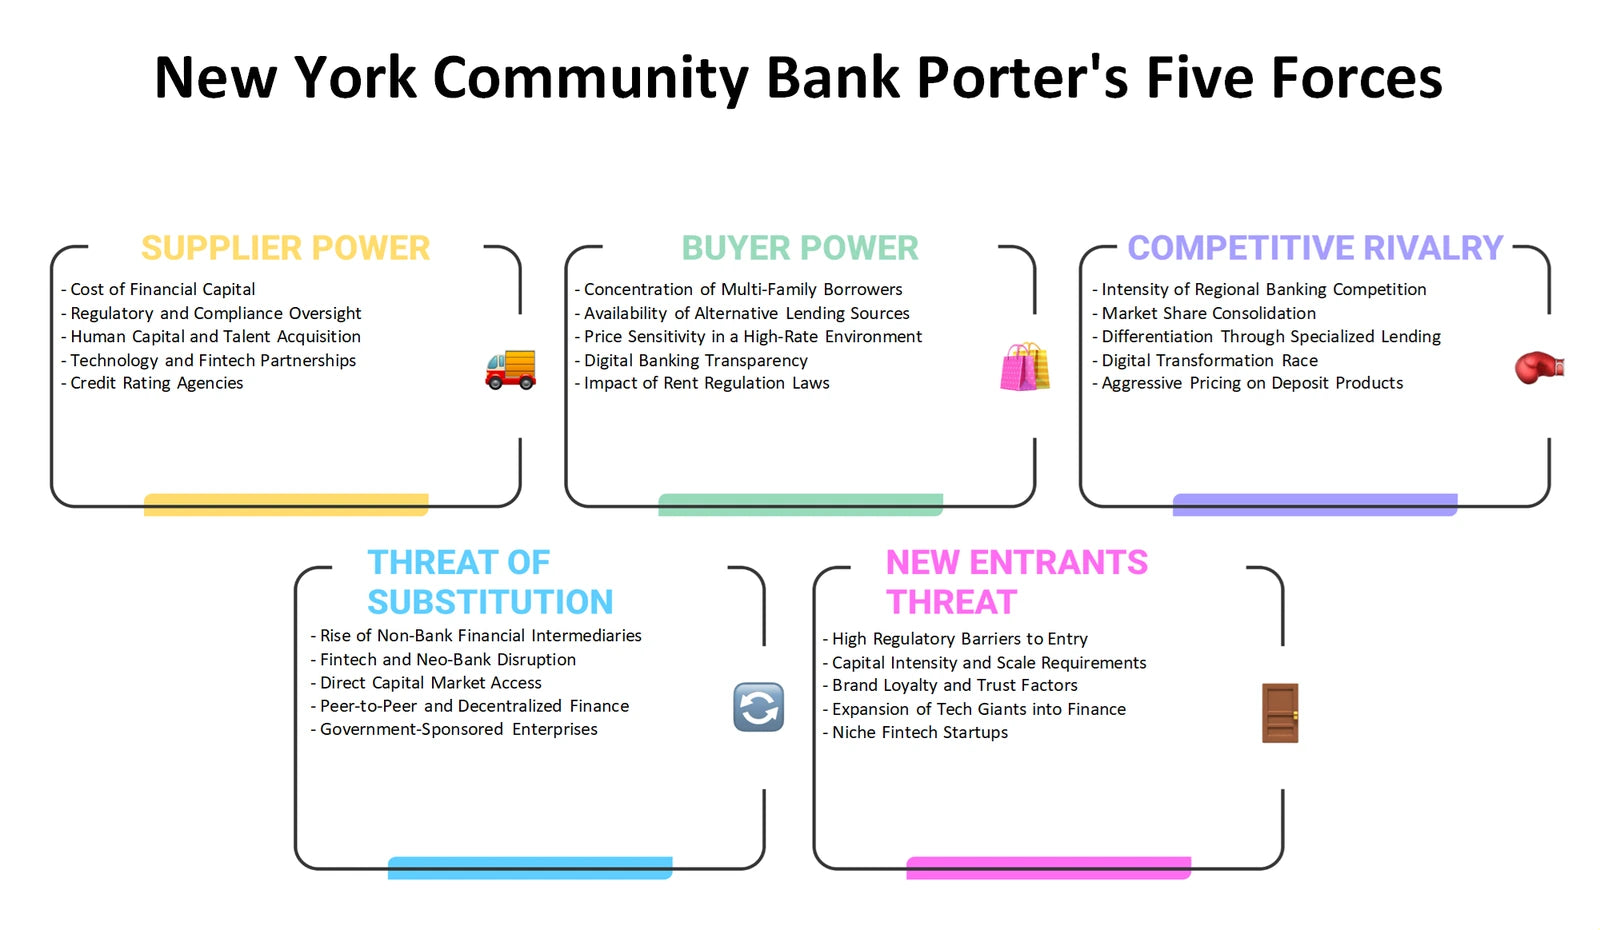
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a regulated banking offer be expressed consistently through product design, pricing, access and communication?
The New York Community Bank Marketing Mix examines Product, Price, Place and Promotion in a relationship-driven financial-services setting. Product can include multi-family and commercial property lending, deposit services and digital banking access. Price is broader than an advertised rate: it can involve loan terms, fees, deposit economics, service value and risk-adjusted return. Place considers branch, digital and relationship-manager routes through which customers research, apply, transact and receive support. Promotion concerns clear, compliant communication of relevant benefits and eligibility rather than unverified campaign claims. Looking across all four Ps helps reveal whether the offered experience supports the needs of property owners, business customers and everyday banking users.
- Offer architecture. Consider how lending expertise, account services and digital tools may be packaged around distinct customer needs without treating every customer as identical.
- Channel consistency. Compare the role of local relationships and digital journeys in making complex credit and simpler banking services accessible and understandable.
- Framework use. Use the Excel 4Ps structure to compare customer-facing choices, while the Word analysis provides context for evaluating alignment, compliance and communication questions.
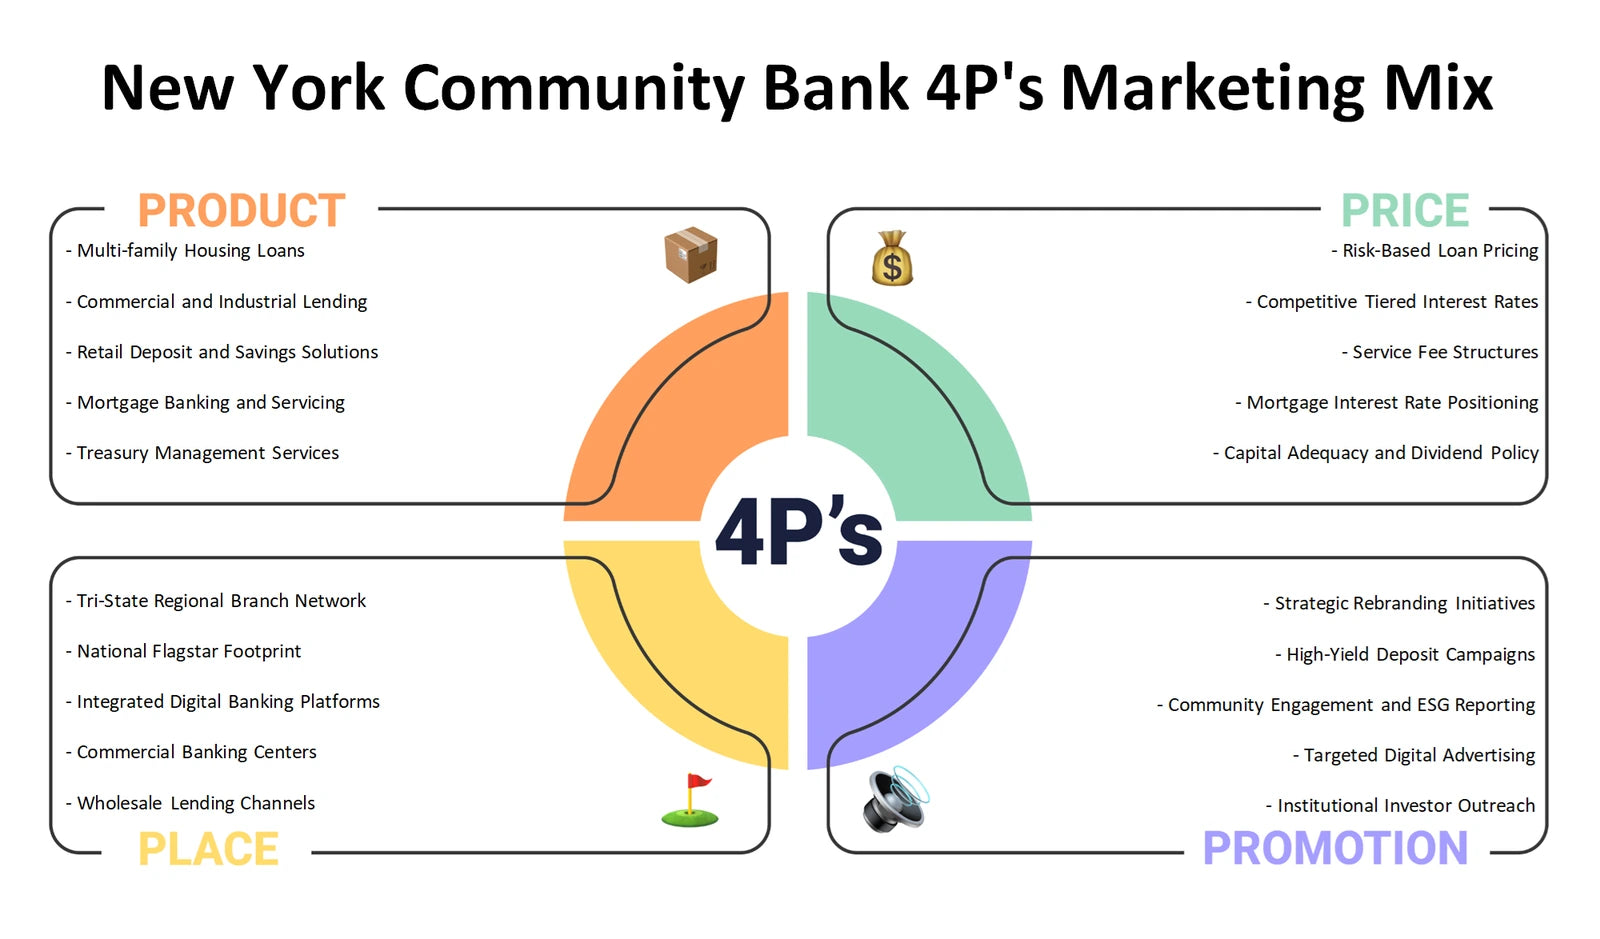
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could alter the operating context for metropolitan property lending, deposits and digital banking?
The New York Community Bank PESTLE analysis, also commonly called PESTEL, separates external influences into Political, Economic, Social, Technological, Legal and Environmental dimensions. Political and legal questions can include the policy and supervisory context affecting banking and property finance. Economic questions can examine borrowing demand, property-market conditions, funding costs and changing interest-rate environments without asserting a current rate or outcome. Social factors may affect housing patterns, customer preferences and demand for digital access. Technology raises questions about platform dependence, security and service expectations, while environmental considerations may be relevant to property exposure and operational resilience. These are outside forces, not predetermined company results.
- Property-market exposure. Explore how broader conditions affecting multi-family and commercial real estate can influence borrower demand, collateral considerations and portfolio monitoring.
- Digital resilience. Consider external technology expectations and cyber-related pressures alongside reliance on partners that support banking delivery and efficiency.
- Framework use. Prioritise external signals in the Excel PESTLE grid, then use the Word analysis to distinguish documented context from scenarios that warrant monitoring.
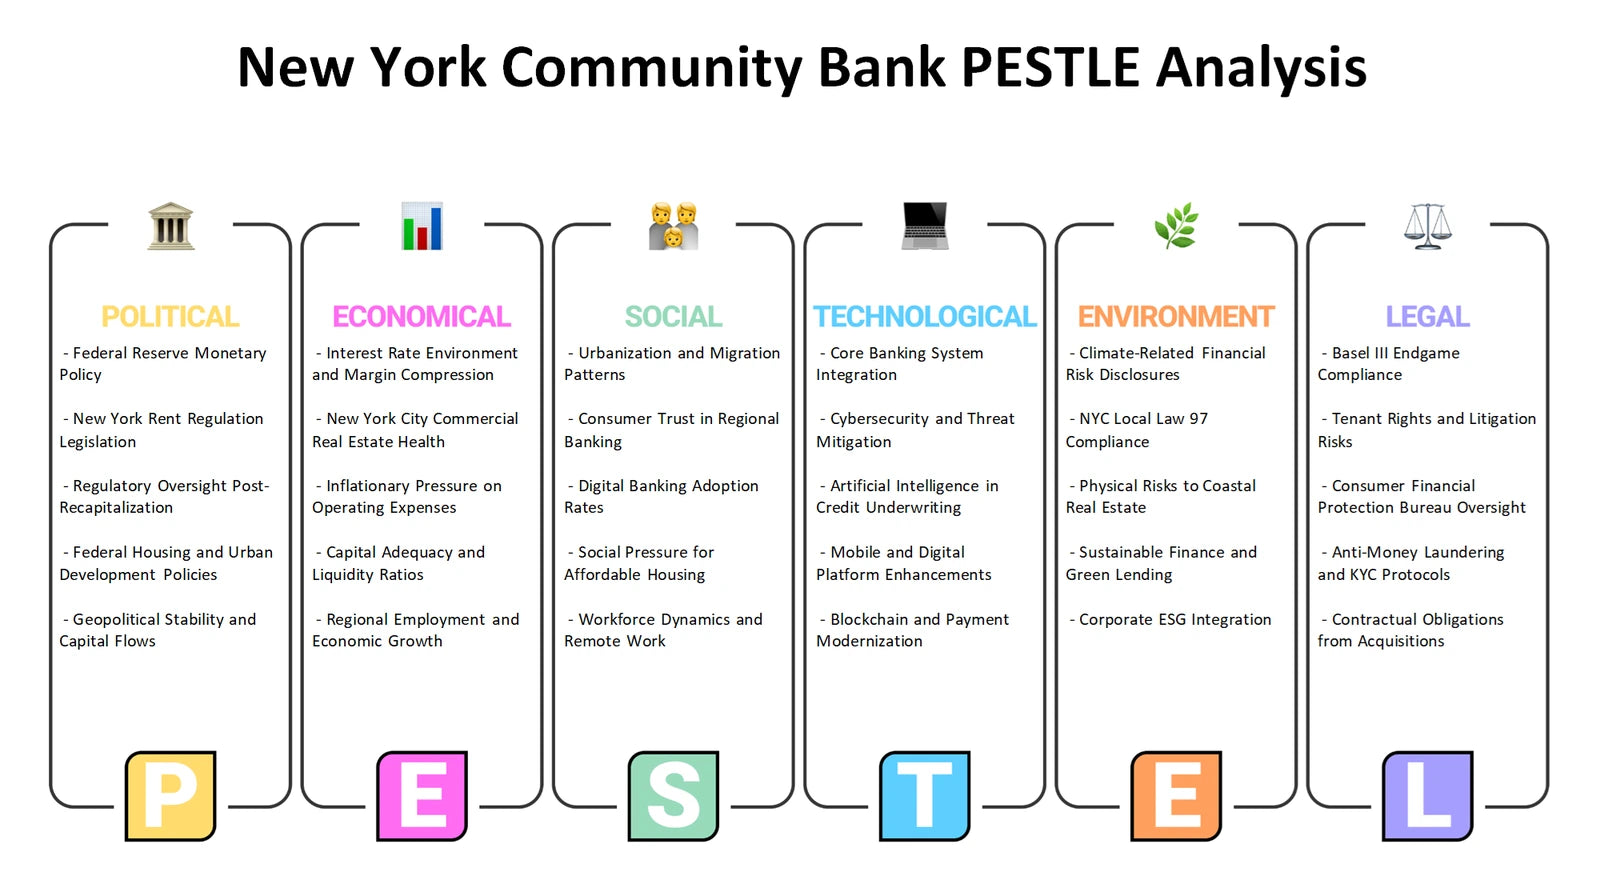
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal lending and service capabilities be weighed against external opportunities and threats?
The New York Community Bank SWOT analysis brings the other perspectives into a clear internal-versus-external comparison. Strengths and weaknesses concern capabilities within the operating model, such as lending specialisation, customer relationships, servicing processes, digital delivery or concentration-related constraints that the analysis may investigate. Opportunities and threats arise outside the organisation, including changing customer needs, property-market conditions, non-bank alternatives, regulation and technology shifts. The framework is useful precisely because it avoids treating a plausible theme as an established fact: each item should be supported, qualified and placed in the correct category. It can then help turn observations into focused questions about fit between capabilities, risk appetite and market conditions.
- Internal distinction. Separate controllable capabilities and limitations from outside conditions, so operational issues are not confused with market opportunities or threats.
- Strategic fit. Test whether property-lending knowledge, relationship banking and digital delivery could be aligned with changing borrower, depositor and partner expectations.
- Framework use. Capture and prioritise candidate factors in the Excel SWOT layout, then use the Word analysis to add rationale, evidence boundaries and implications for discussion.
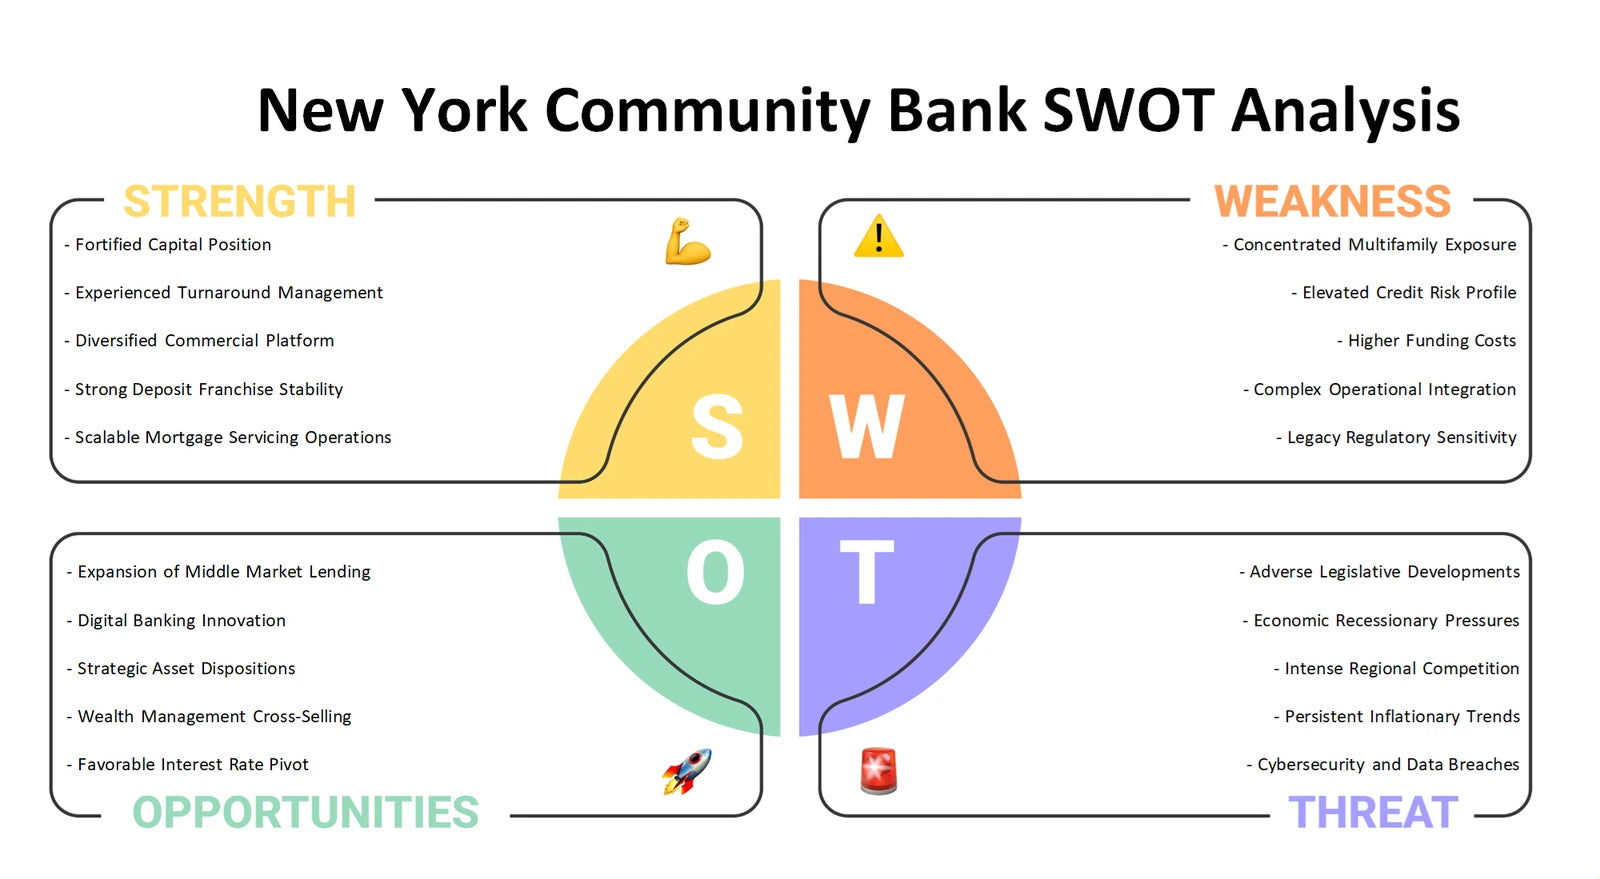
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect lending strategy, customer delivery and external conditions
Together, the six perspectives help build a more rounded view of the New York Community Bank operating context: BCG considers portfolio priorities; Canvas explains value creation; Five Forces and PESTLE examine industry and external pressure; Marketing Mix focuses on customer delivery; and SWOT brings internal and external considerations together. The Excel frameworks support structured comparison, while the detailed Word analysis helps develop informed questions and strategic discussion.
Company background: New York Community Bank — Business Model Canvas product-context page.