

Mizrahi Tefahot Bank: Banking Business and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Mizrahi Tefahot Bank Strategy Analysis Bundle
Mizrahi Tefahot Bank is an Israeli banking company operating through Mizrahi Tefahot Bank Ltd. Its public-facing banking offer includes customer accounts, deposits, loans and mortgages. The bank’s website describes a lending-led business with a prominent position in Israel’s mortgage market, making the balance between customer service, credit decisions, funding and distribution especially relevant.
For Mizrahi Tefahot Bank, strategic questions can include how to prioritise lending and savings propositions, protect trust while expanding digital service, and respond to changing funding, regulatory and household-finance conditions. This bundle brings six connected lenses together so customers can examine those questions in structured Excel frameworks alongside detailed Word analysis.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which banking propositions deserve resources when growth potential and relative market share point in different directions?
A Mizrahi Tefahot Bank BCG Matrix helps separate portfolio discussion from broad statements about banking growth. It can compare propositions such as mortgages, deposits, current-account services, consumer lending or selected business-finance activities using market growth and relative market share. The framework uses Stars, Cash Cows, Question Marks and Dogs as analytical categories, not as pre-assigned labels for the bank’s services. That distinction matters because a large, established lending activity may call for different funding, service and risk priorities than an emerging customer proposition.
- Portfolio boundaries. Compare clearly defined products or customer propositions rather than treating the entire bank as one business unit.
- Capital attention. Consider where management capacity, technology investment, distribution effort and risk appetite may need different levels of attention.
- Working view. Use the Excel matrix to organise possible units and assumptions, then use the Word analysis to interpret the strategic trade-offs behind them.
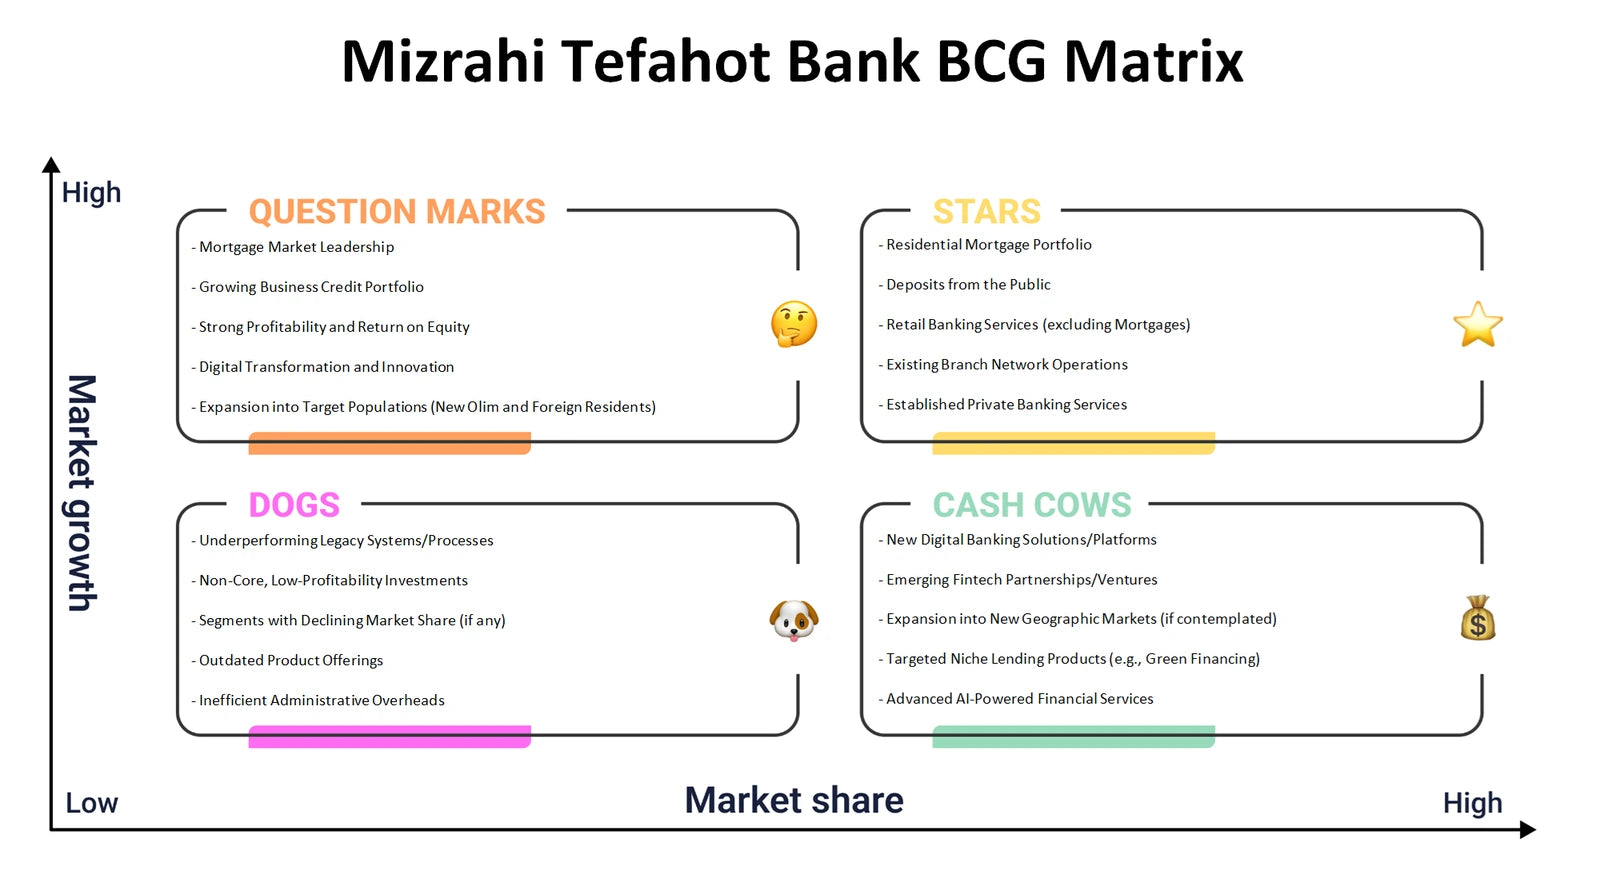
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer value, lending economics, service delivery and funding relationships fit together in one banking model?
The Mizrahi Tefahot Bank Business Model Canvas brings together all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. For a bank serving account holders, depositors and borrowers, the connections are central. Customers may value reliable access, advice and credit availability; the bank must deliver those through branches, digital journeys and operational processes while managing funding, risk, technology and compliance. The canvas helps examine how interest-related income, fees or other revenue logic relate to the resources and costs needed to support the service promise.
- Value-to-delivery link. Map how accounts, deposits, loans and mortgages connect to service channels and ongoing customer relationships.
- Economic dependencies. Examine how key activities, technology, funding relationships and control functions influence revenues and cost structure.
- Connected mapping. Complete the Excel canvas as a one-page working model, using the Word analysis to add context and questions for each block.
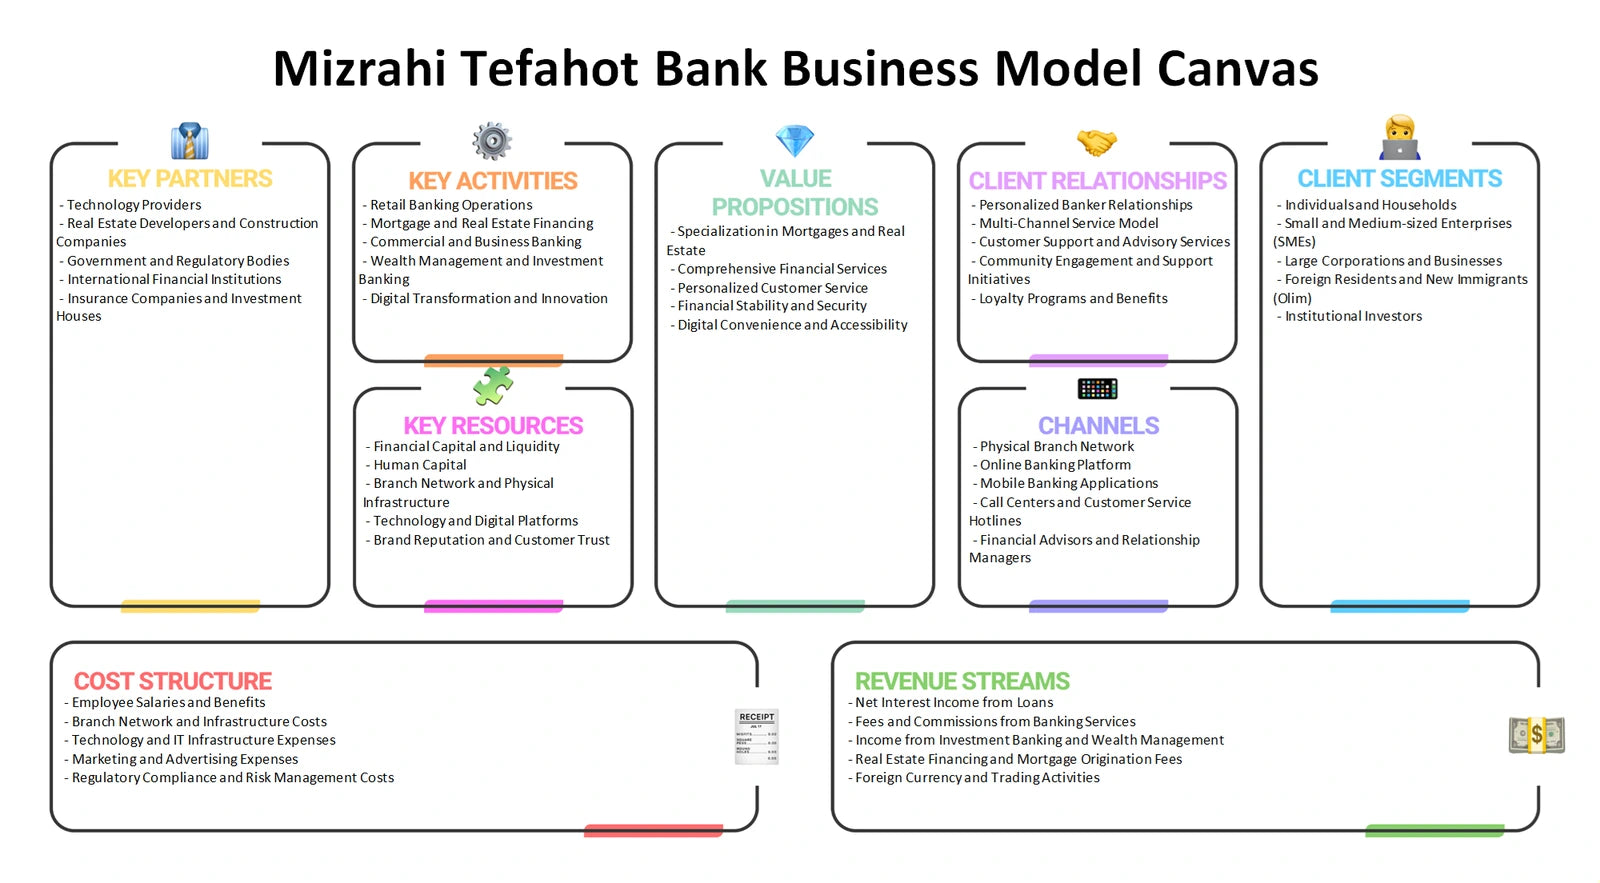
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures shape the attractiveness and defensibility of banking, mortgage and deposit relationships in Israel?
Mizrahi Tefahot Bank Porter's Five Forces analysis examines the structure around the bank rather than judging its performance. Rivalry can affect customer acquisition, product differentiation and service expectations. Buyer power may vary between households, depositors and larger borrowers with alternative providers. Supplier power is relevant to funding sources, technology providers and specialist service partners. The threat of new entrants can be assessed alongside licensing, trust, scale and compliance barriers, while substitutes include non-bank ways to save, borrow, pay or access financial advice. These forces help clarify where industry pressure may alter pricing, service design or operating costs.
- Competitive pressure. Explore how comparable banking offers and mortgage alternatives may influence customer switching and differentiation needs.
- Funding and partners. Consider how capital-market access, wholesale funding relationships and technology dependencies can affect bargaining positions.
- Evidence trail. Use the Excel force-by-force structure to capture observations, then consult the Word analysis for banking-specific interpretation.
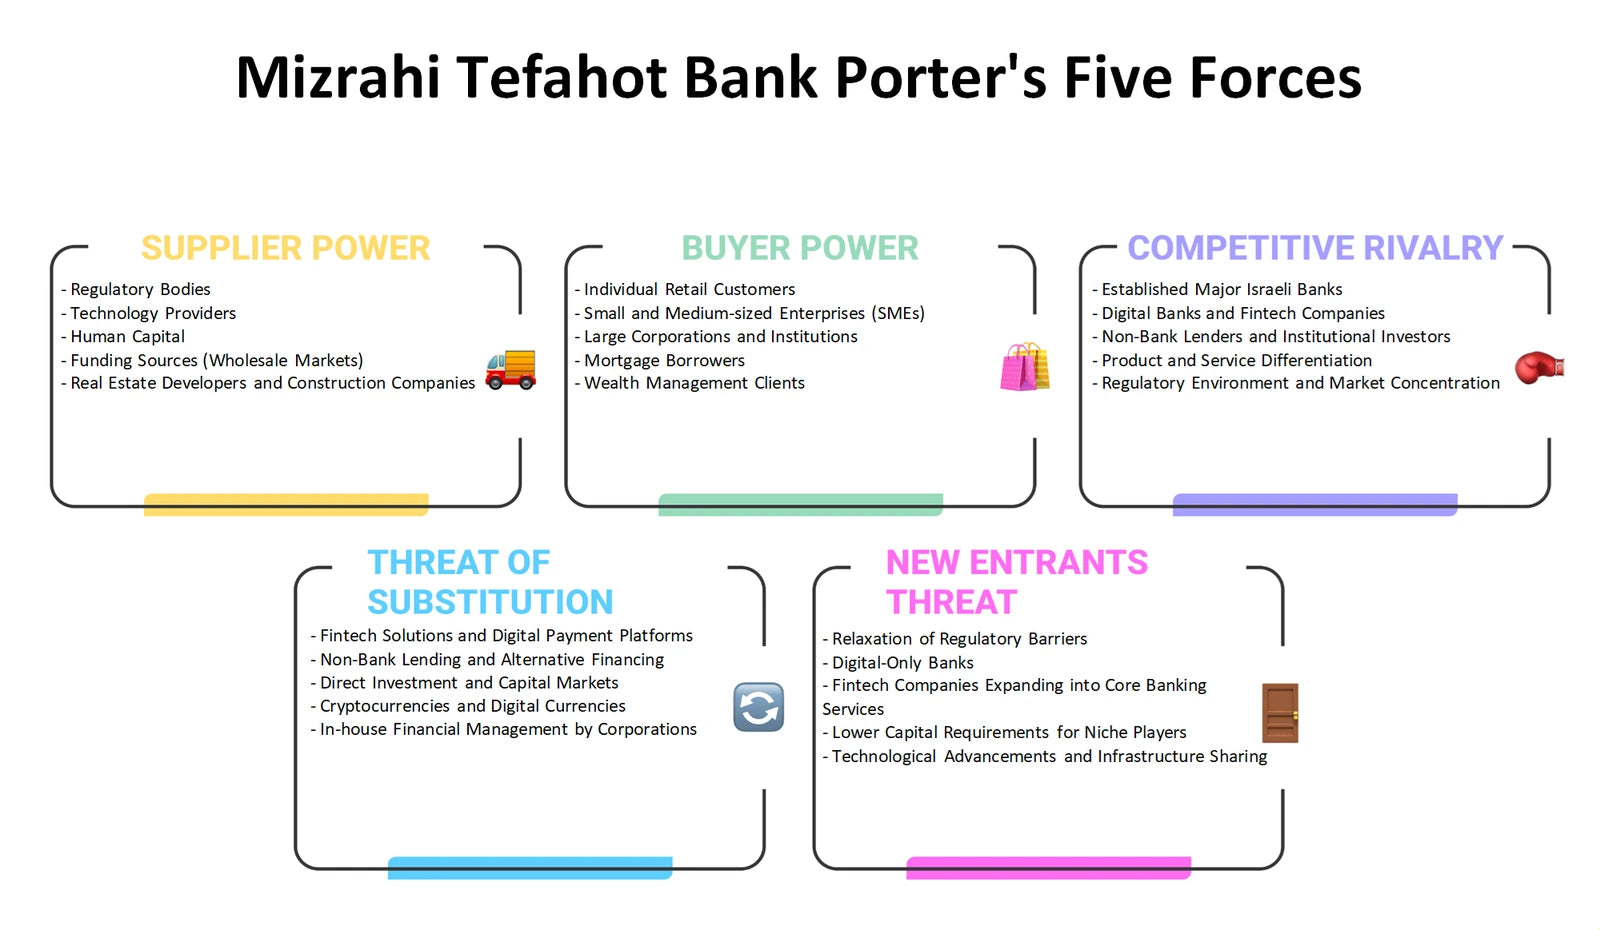
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can banking propositions be positioned clearly while respecting the trust, pricing and disclosure demands of financial services?
A Mizrahi Tefahot Bank Marketing Mix considers Product, Price, Place and Promotion in a customer relationship that may span everyday banking, saving and borrowing. Product analysis can distinguish accounts, deposits, loans and mortgage-related needs rather than treating banking as a single offer. Price is broader than an advertised rate: it can include interest terms, fees, conditions and the clarity with which customers understand them. Place considers branches, digital banking and assisted journeys, while Promotion examines how service, trust, expertise and responsible communication may support customer choice in a regulated category.
- Offer architecture. Compare how products can address different financial needs without obscuring terms, eligibility or customer responsibilities.
- Channel experience. Assess the role of physical and digital routes in discovery, onboarding, advice, servicing and issue resolution.
- Campaign planning. Use the Excel 4Ps grid to test proposition choices and use the Word analysis to frame the customer and compliance considerations.
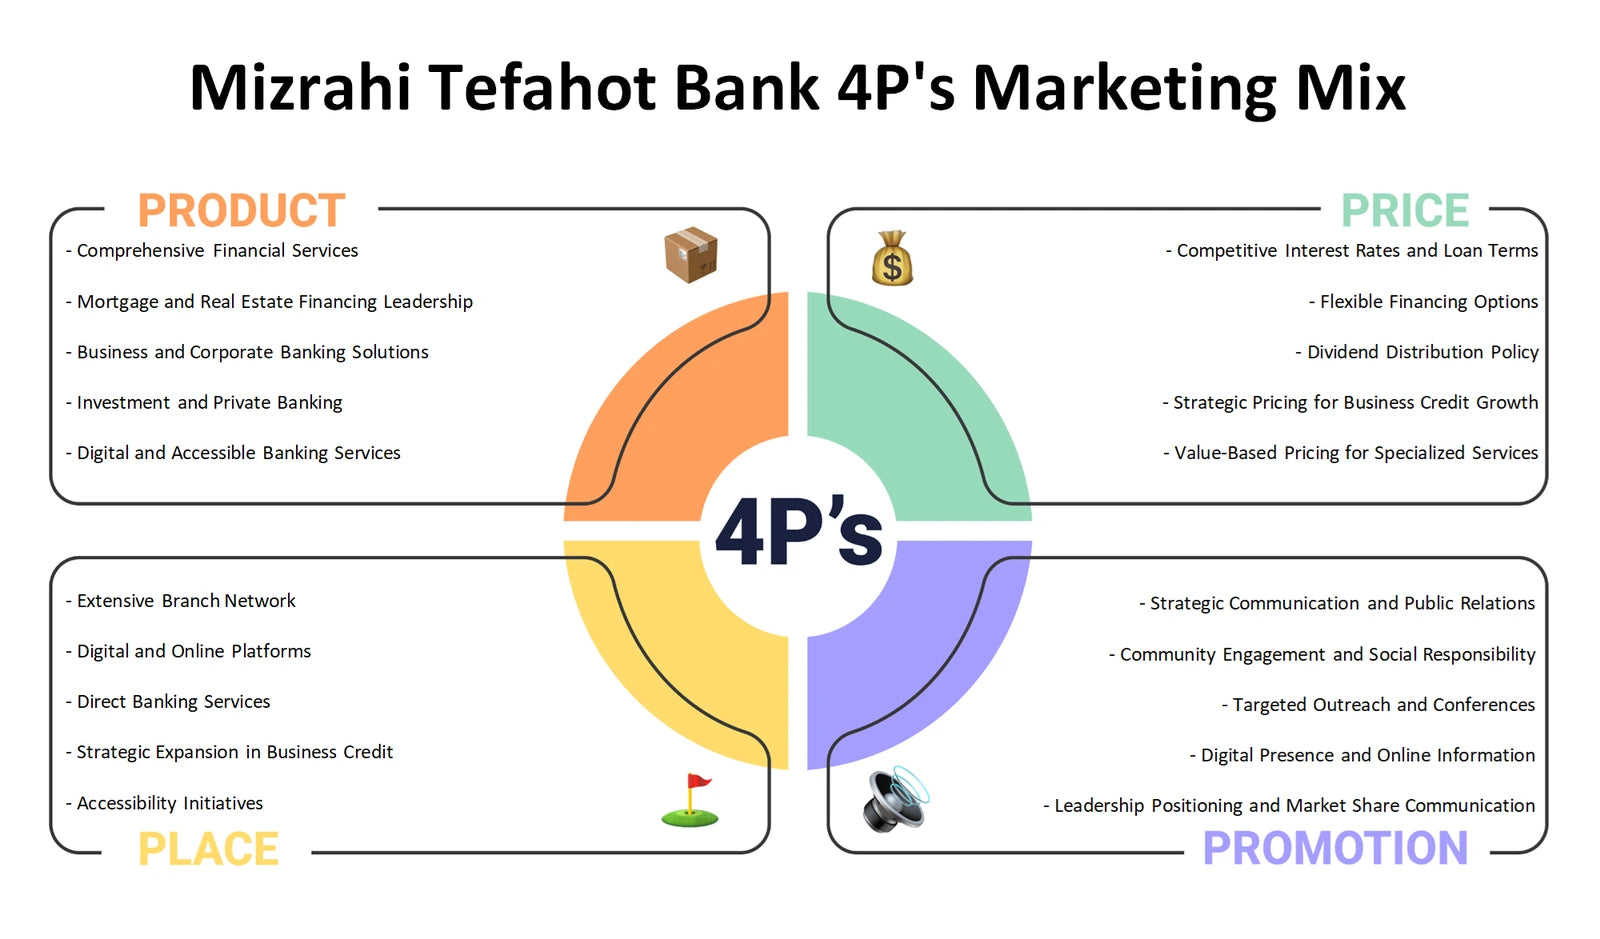
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could reshape demand, risk, customer behaviour and operating requirements for an Israeli bank?
Mizrahi Tefahot Bank PESTLE analysis, also commonly called PESTEL, separates six external dimensions that can otherwise become mixed together. Political factors can include public-policy priorities and the operating environment for financial institutions. Economic conditions affect household borrowing, deposits, property activity and credit risk. Social trends may influence preferences for service and digital access. Technological change raises questions around cybersecurity, data, automation and payment experiences. Legal factors cover banking, consumer-protection and financial-crime obligations, while environmental factors can inform how climate-related exposure or sustainability expectations are considered. These are questions to assess, not claims that any particular change has occurred.
- External signals. Distinguish macroeconomic questions from regulatory, customer-behaviour and technology developments affecting the bank differently.
- Mortgage sensitivity. Explore how housing-related conditions and household affordability can matter to a mortgage-focused banking proposition.
- Scenario workbook. Record possible drivers and implications in the Excel framework, then use the Word analysis to support structured discussion of priorities.
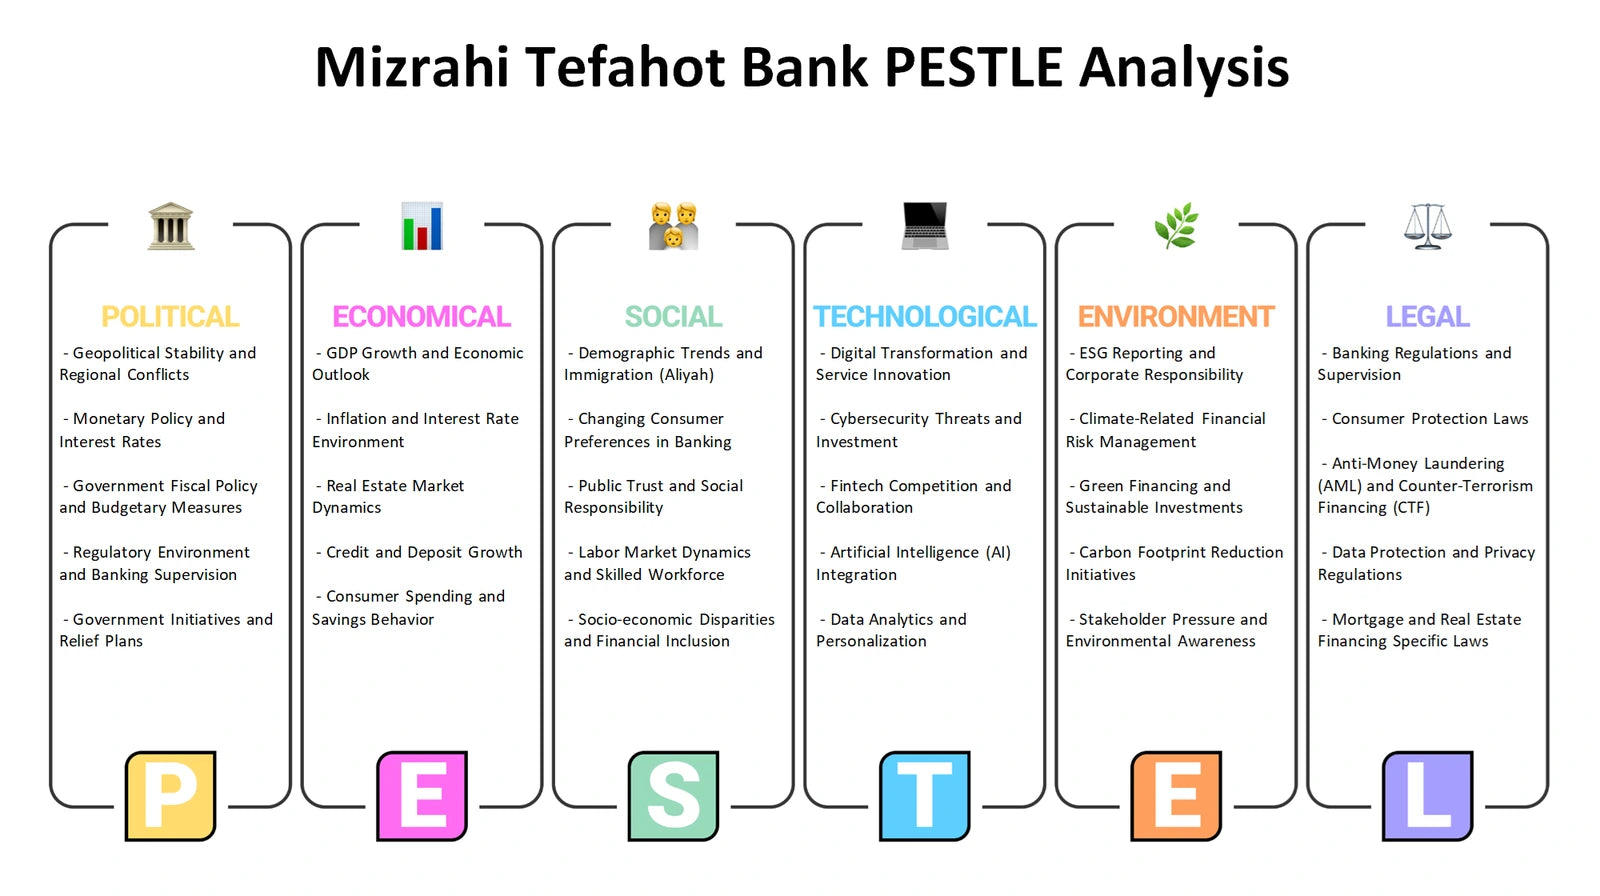
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal banking capabilities and limitations be considered alongside external opportunities and threats?
A Mizrahi Tefahot Bank SWOT analysis provides a disciplined distinction between what is internal and what is external. Strengths and weaknesses concern capabilities, resources, customer relationships, operating processes or constraints within the organisation. Opportunities and threats arise from the surrounding market, customer needs, technology developments, competition, funding conditions or regulation. For a bank with a recognised mortgage presence, the framework can help test how lending knowledge, service delivery and digital capabilities may relate to external changes without presenting plausible themes as established findings. It is especially useful after the other frameworks have identified portfolio, model, industry and environmental questions.
- Correct classification. Keep a capability or operational limitation in the internal columns, and keep market or regulatory conditions in the external columns.
- Strategic fit. Compare possible strengths against opportunities, and consider how weaknesses could increase exposure to threats.
- Decision summary. Use the Excel SWOT layout to prioritise discussion points, then use the Word analysis to preserve the reasoning behind each relationship.
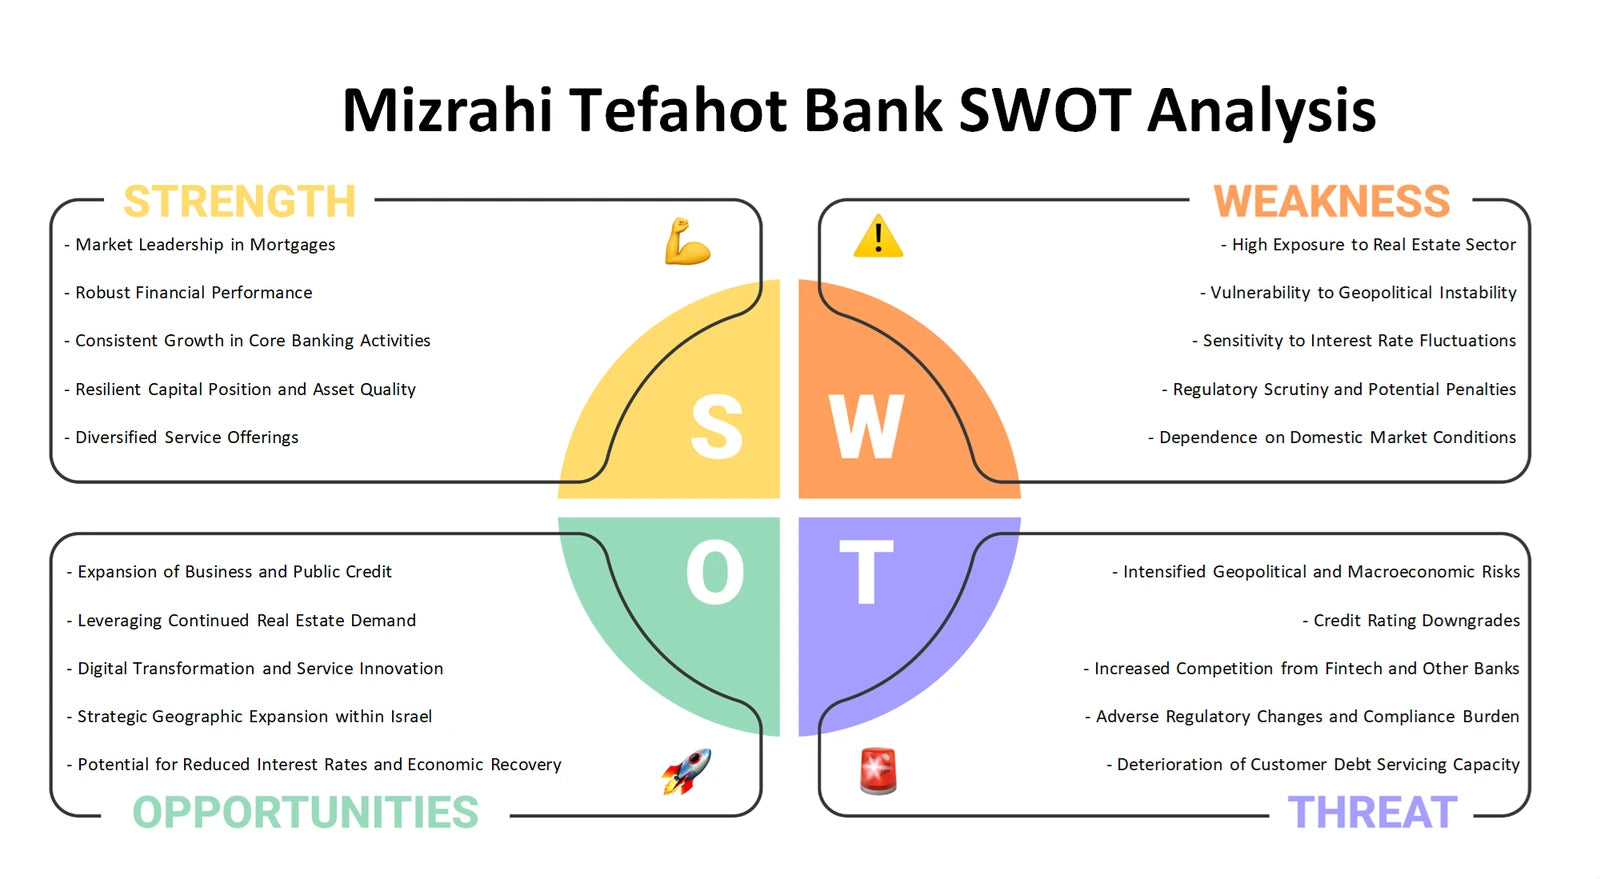
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of Mizrahi Tefahot Bank
Used together, the six perspectives move from portfolio choices and business-model logic to industry pressure, customer-facing decisions, external change and strategic fit. The Excel frameworks provide a structured way to organise questions and comparisons, while the detailed Word files help customers develop a more considered company-specific discussion without treating the preview images as the full analysis.
Company background: Mizrahi Tefahot Bank — official company website.