

Mid Penn Bank: Banking Business and Underwriting – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Mid Penn Bank Strategy Analysis Bundle
Mid Penn Bank is examined here as the relationship-focused community banking business associated with Mid Penn Bancorp (NASDAQ: MPB) in the supplied product context. Its relevant operating themes include household deposits, commercial and real-estate lending, branch engagement, advisor-led conversations, and support for borrowers using SBA and government programs.
That model raises connected strategic questions: which banking activities deserve scarce capital and management attention, how deposits and lending economics fit together, and how regulation, local competition, customer expectations, and technology may affect execution. The Excel frameworks and detailed Word analysis help organize those questions without presenting unverified conclusions as established facts.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which deposit, lending, and relationship-banking activities should receive the greatest attention when growth potential and relative market share are considered together?
The Mid Penn Bank BCG Matrix provides a disciplined way to compare banking activities rather than treating every product line as equally strategic. It uses market growth and relative market share to examine whether a defined activity may behave like a Star, Cash Cow, Question Mark, or Dog. For this community-bank context, useful comparisons may include deposit acquisition, commercial lending, real-estate finance, and specialized government-program lending. The framework does not assign any of these activities to a quadrant; it helps the customer test the evidence needed before making a portfolio priority decision.
- Portfolio boundaries. Separate activities by customer need, market served, and economic role so deposits are not assessed using the same assumptions as lending products.
- Capital trade-offs. Compare growth opportunity with relative position, funding needs, risk capacity, and the management attention required to build a category.
- Structured comparison. Use the Excel matrix to organize candidate activities and the Word analysis to interpret what each possible quadrant implies for resource allocation.
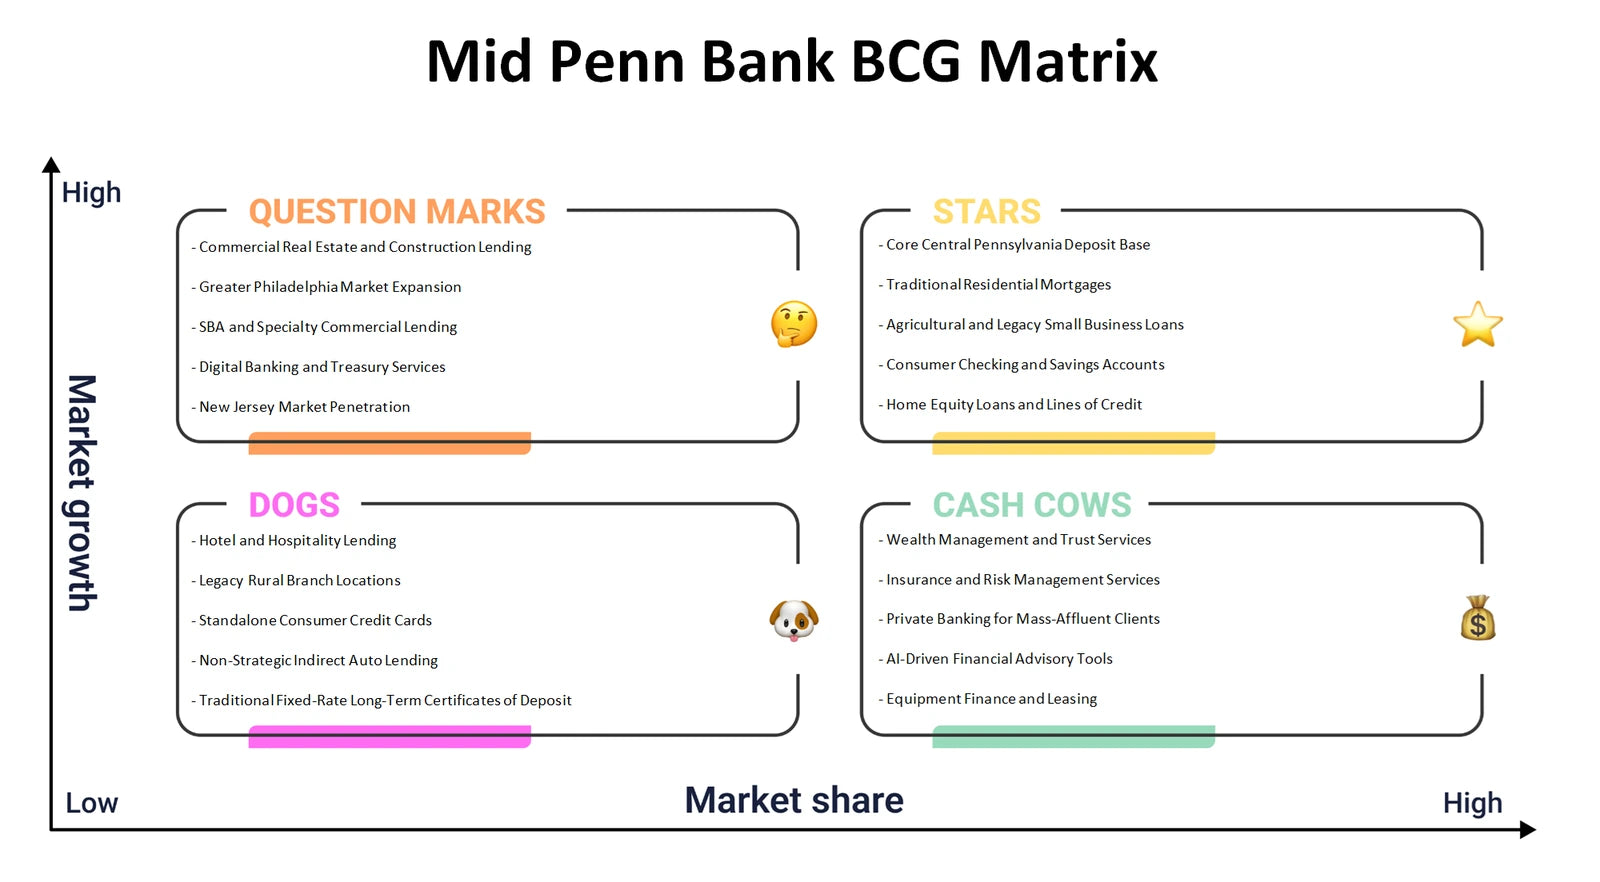
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do relationship banking, local underwriting knowledge, deposit funding, and tailored financing connect to create value and earn sustainable banking income?
The Mid Penn Bank Business Model Canvas brings the operating model into one connected view. It examines customer segments such as households, local businesses, commercial borrowers, and property-finance customers; value propositions such as responsive relationship service and tailored financing; and channels including branches and advisor interactions. It also links customer relationships, revenue streams, key resources, key activities, key partnerships, and cost structure. This matters because deposit relationships, lending decisions, compliance processes, and service delivery are interdependent: a promising customer proposition still has to be funded, controlled, delivered, and priced responsibly.
- Customer-value fit. Assess how checking, savings, time deposits, working-capital lending, and property financing may address distinct customer jobs and relationship needs.
- Economic connections. Trace how interest income, funding costs, service activity, credit processes, branch operations, technology, and compliance obligations interact.
- Model mapping. Populate the Excel Canvas block by block, then use the Word analysis to review the links, assumptions, and strategic tensions across all nine building blocks.
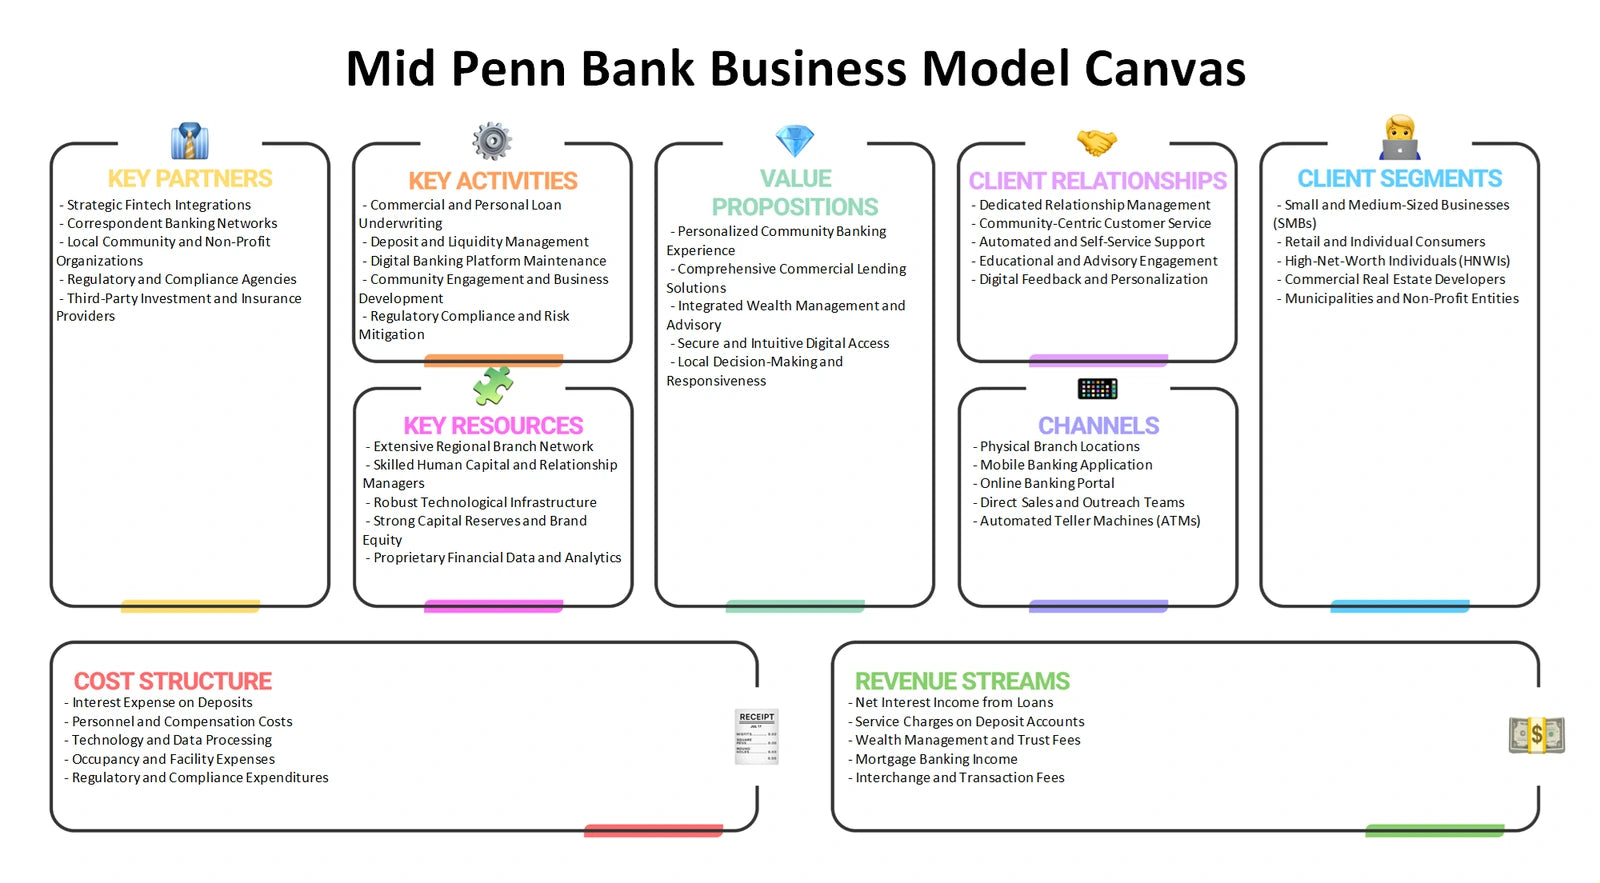
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could influence the attractiveness of community banking and the ability to protect relationship-based lending and deposit economics?
Mid Penn Bank Porter's Five Forces examines the competitive structure surrounding a community-bank model. Rivalry can include competition for deposits, loans, and local relationships. Buyer power considers how households and business customers compare banking alternatives and negotiate terms. Supplier power can arise through funding sources, specialized talent, technology providers, and other essential inputs. The analysis also considers new entrants and substitutes, including nonbank lenders, digital financial providers, payment platforms, and other ways customers can save, borrow, or manage cash. It does not score these forces; it helps frame the evidence behind a considered industry assessment.
- Competitive pressure. Explore where relationship depth, underwriting judgment, service responsiveness, and product availability may matter more than simple rate comparison.
- Funding and alternatives. Consider deposit competition alongside substitutes that may meet borrowing, payment, savings, or cash-management needs outside a traditional bank.
- Evidence-led review. Use the Excel framework to record force-specific observations and the Word analysis to connect them to defensibility, margins, and customer retention questions.
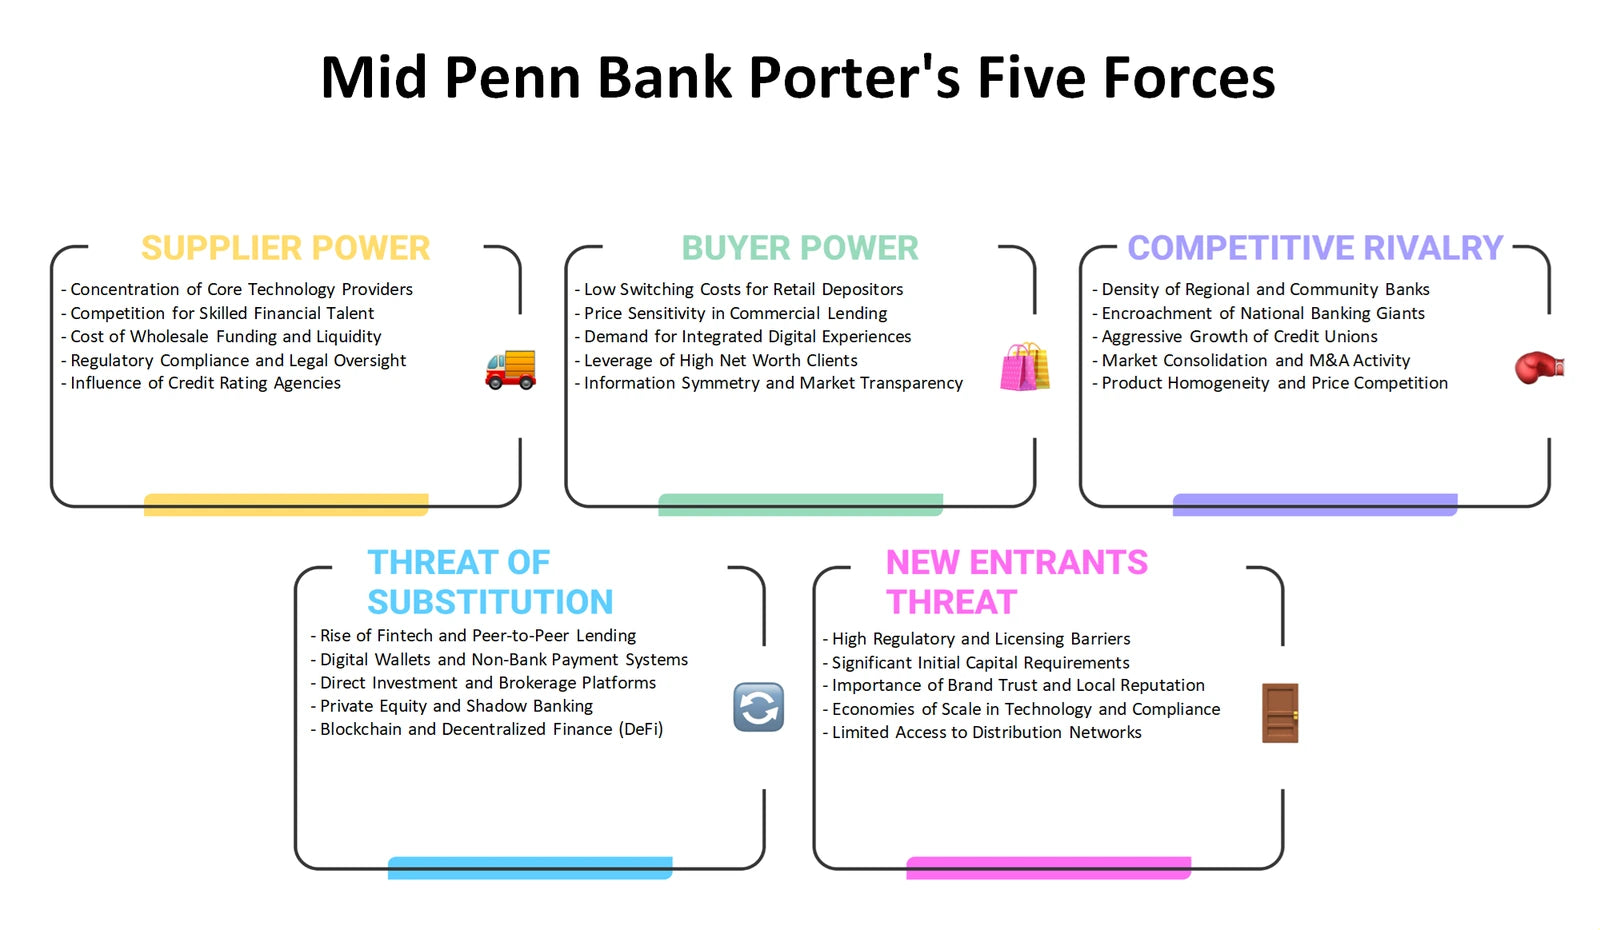
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can deposits, lending, branch relationships, and local communication be assessed as a coherent customer proposition in a regulated banking setting?
The Mid Penn Bank Marketing Mix applies Product, Price, Place, and Promotion to banking choices. Product can cover deposit accounts, time deposits, commercial credit, real-estate finance, and support for eligible SBA or government programs. Price is not simply a headline rate: it can involve interest margins, fees, credit risk, deposit costs, and promotional terms. Place considers branch engagement and advisor-led service, while Promotion examines how local events, relationship conversations, and targeted offers may build trust. The supplied context references targeted CD and HELOC offers, making the trade-off between deposit growth and margin an especially useful analytical topic rather than a claimed outcome.
- Offer design. Compare customer needs with the product range, approval experience, service expectations, and risk considerations attached to each banking offer.
- Channel consistency. Examine whether branch interactions, advisors, local outreach, and customer communications reinforce the same relationship-bank positioning.
- Mix planning. Use the Excel framework to align the four Ps for priority customer groups, then consult the Word analysis for the strategic rationale behind each choice.
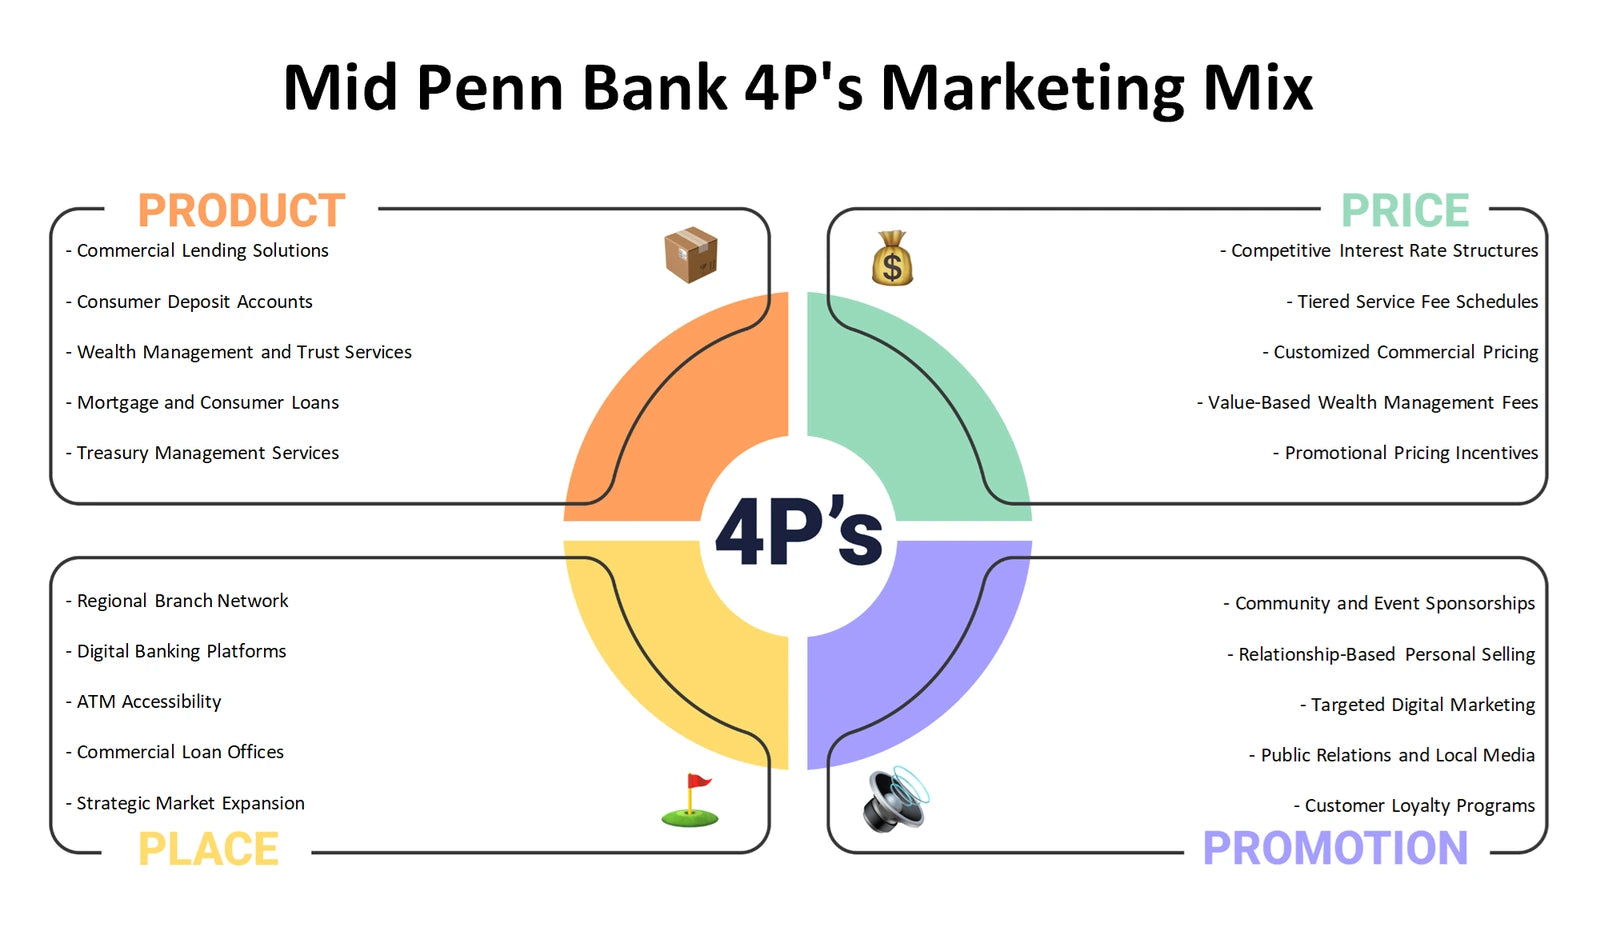
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments should be monitored because they may alter customer demand, lending conditions, deposit behavior, compliance work, or operating costs?
The Mid Penn Bank PESTLE analysis, also commonly called PESTEL, organizes external influences without confusing them with internal performance. Political factors can include public-policy direction and government lending programs. Economic conditions may affect credit demand, property markets, funding costs, and borrower resilience. Social change can reshape expectations for convenience and trusted advice. Technological developments raise questions about digital service, data use, security, and process efficiency. Legal factors include banking supervision, consumer protection, and compliance obligations, while environmental conditions may affect property risk, local businesses, and credit assessment. The framework identifies questions to investigate; it does not claim that a particular law, rate, or disruption has occurred.
- Regulatory readiness. Consider how evolving requirements may affect documentation, training, control design, product approvals, and external advisory support.
- Economic exposure. Map external conditions that could influence deposit pricing, loan demand, commercial borrowers, real-estate finance, and credit quality.
- Monitoring agenda. Use the Excel template to log signals by PESTLE category and the Word analysis to translate those signals into management questions and scenario discussion.
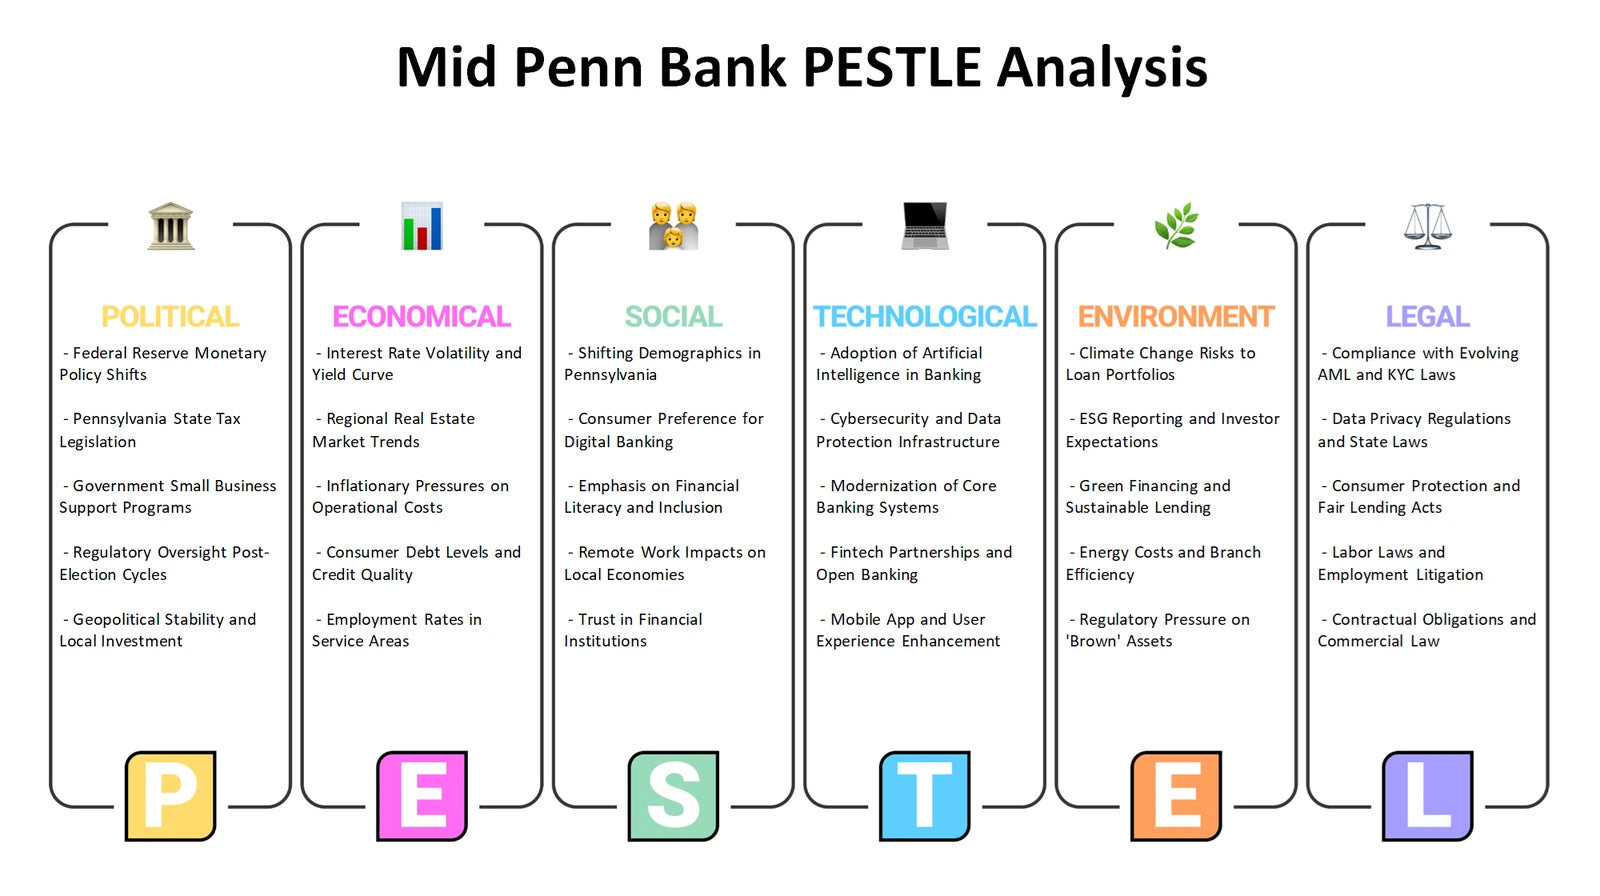
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
Which internal capabilities and limitations should be weighed against external banking opportunities and threats before priorities are set?
The Mid Penn Bank SWOT analysis separates what is internal from what is external. Potential strengths to test may include relationship-oriented service, local-industry knowledge, and the ability to structure commercial or property financing. Potential weaknesses may involve capacity constraints, process complexity, or concentration in particular customer needs, but these require evidence rather than assumption. Opportunities belong outside the organization, such as unmet financing needs or relationship expansion, while threats may include competitive pressure, changing customer behavior, regulatory burden, or adverse credit conditions. Keeping these categories distinct helps avoid calling an external market trend a strength or treating an internal capability as an opportunity.
- Capability test. Identify which service, underwriting, relationship, deposit, and compliance capabilities are sufficiently evidenced to be treated as internal advantages or constraints.
- External match. Compare those internal factors with outside opportunities and threats affecting households, business clients, property borrowers, and funding markets.
- Priority synthesis. Use the Excel grid to rank discussion points by relevance, then use the Word analysis to develop strategic implications without overstating unverified findings.
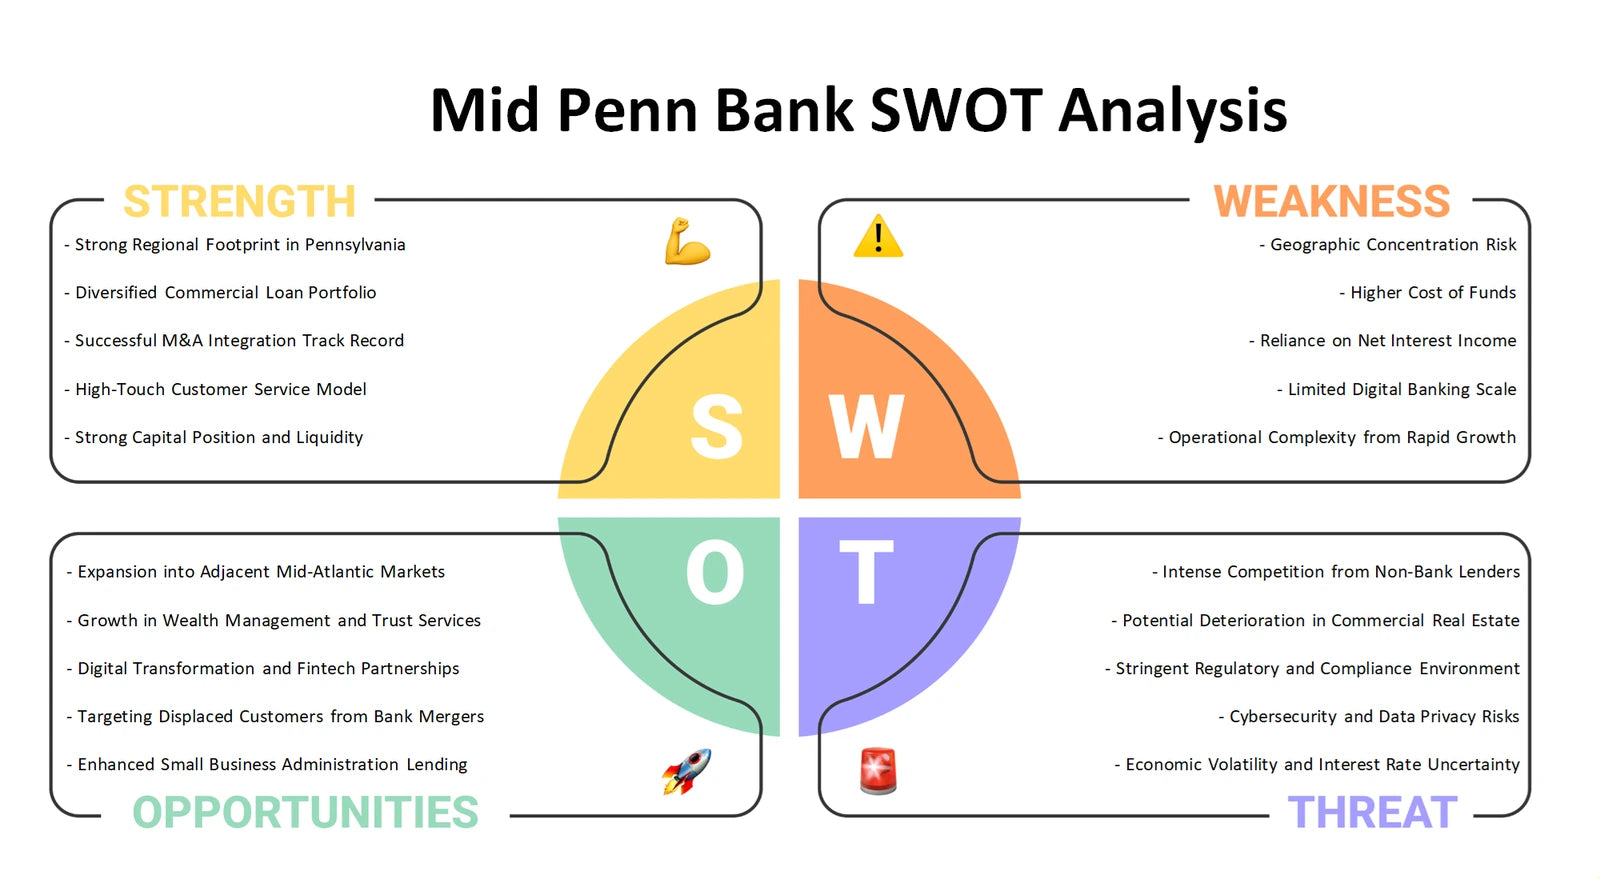
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect portfolio choices with the operating model
Used together, the six perspectives move from portfolio prioritization and business-model logic to competitive pressure, customer-market choices, external change, and strategic fit. The Excel frameworks provide structured places to compare evidence and record assumptions, while the detailed Word analysis helps interpret the relationships between deposits, lending, customer relationships, compliance, and community-banking economics. Customers can use the materials to develop more focused discussion questions for Mid Penn Bank rather than relying on a single generic strategy lens.
Company background: Mid Penn Bank — product-context company background.