

MGIC: Customer Relationships and Value Creation – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
MGIC Strategy Analysis Bundle
This MGIC bundle addresses the United States private mortgage-insurance business described in the supplied product context. Its direct customers are residential mortgage lenders, including banks, credit unions and non-bank lenders that originate mortgages MGIC may insure. The business therefore sits between mortgage origination, credit-risk assessment and the secondary-mortgage-market requirements that shape eligible lending.
MGIC’s relationships with lender customers, government-sponsored enterprises such as Fannie Mae and Freddie Mac, and unaffiliated reinsurers create useful strategic questions about distribution, underwriting discipline, capital and risk transfer. The six connected analyses help customers examine those questions from different angles, using structured Excel frameworks alongside detailed Word discussion rather than treating any one framework as a final investment conclusion.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which MGIC activities or lender-facing propositions deserve resources when market growth and relative market share point in different directions?
The MGIC BCG Matrix provides a disciplined way to compare a portfolio of possible activities rather than assuming that every mortgage-insurance opportunity should receive the same attention. It uses market growth and relative market share to frame the familiar Stars, Cash Cows, Question Marks and Dogs categories. For this business, the exercise can compare lender segments, distribution initiatives, product propositions or geographic lending exposures where reliable evidence is available. It is particularly useful because mortgage volumes and credit conditions can change while the company must continue to protect underwriting and capital priorities.
- Portfolio boundaries. Separate established lender relationships from newer opportunities so that unlike activities are not treated as a single undifferentiated insurance market.
- Resource trade-offs. Test where relationship coverage, underwriting attention, technology spending or risk capacity may be most justified under different growth and share assumptions.
- Working view. Use the Excel matrix to record comparison criteria and assumptions, then use the Word analysis to interpret why a provisional category should be challenged rather than accepted mechanically.
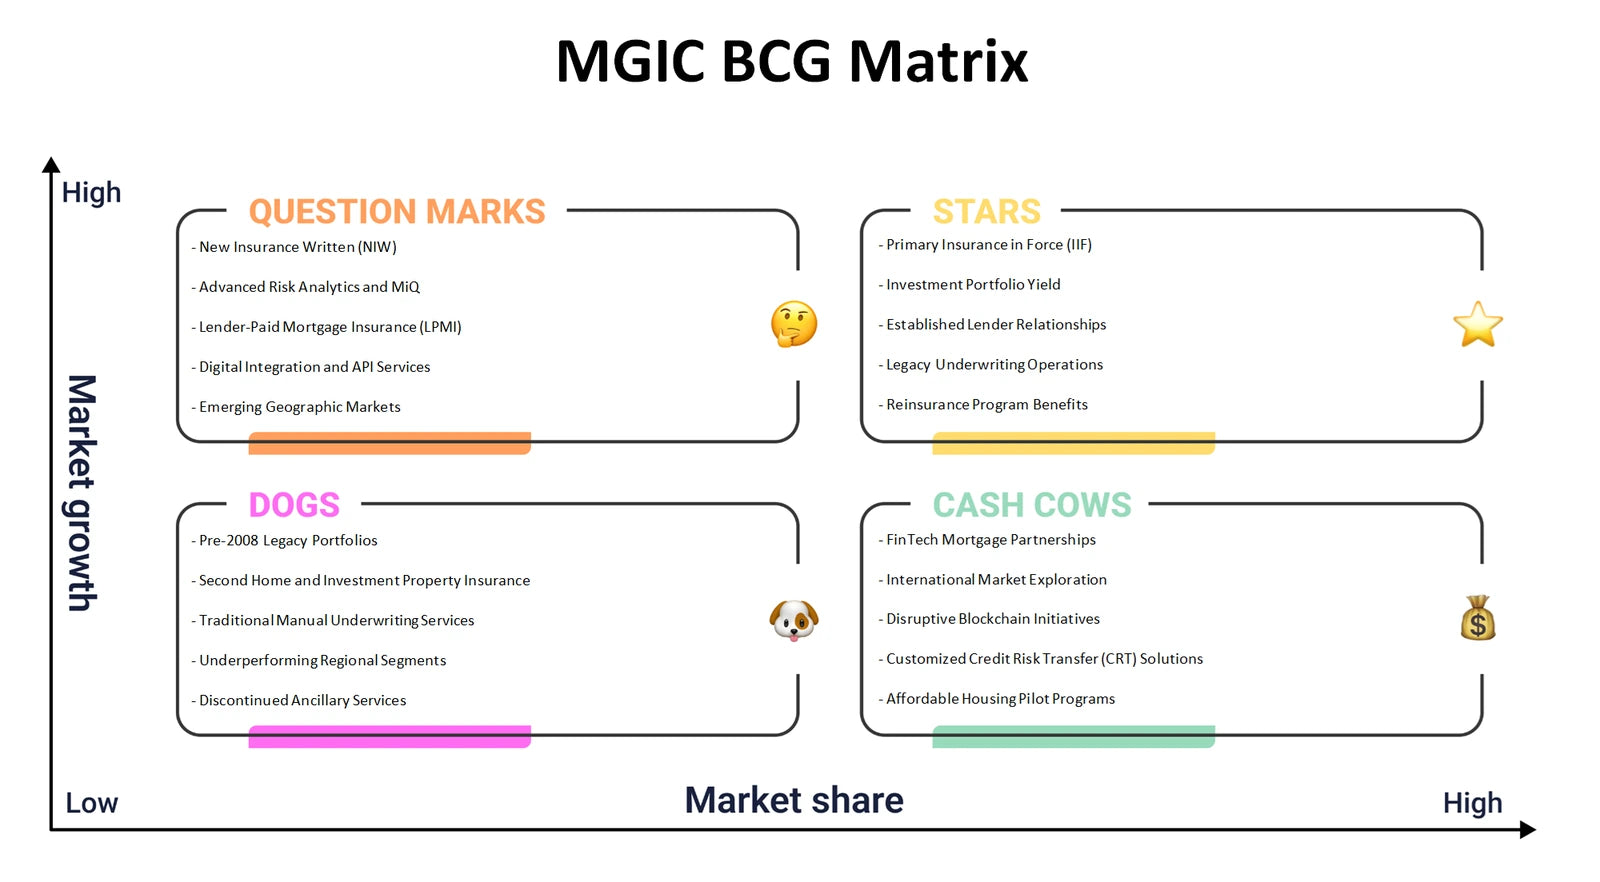
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do MGIC’s lender relationships, insurance economics and risk-management partners fit together to create value?
The MGIC Business Model Canvas connects all nine building blocks in one operating picture: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. Lenders are central customer segments and channels because they originate the mortgages that may be insured. The analysis can examine how underwriting, insurance coverage, servicing relationships and claims capability support the value proposition, while premiums, credit losses, operating costs and risk-transfer arrangements shape the economics. It also puts GSE eligibility requirements and reinsurance relationships in context as important partnership conditions rather than background details.
- Value chain logic. Follow the connection from lender origination through mortgage insurance, eligibility expectations, ongoing risk management and the revenue-and-cost consequences of each step.
- Partner dependence. Consider how Fannie Mae, Freddie Mac and unaffiliated reinsurers affect access, capital efficiency and operating flexibility without assuming those relationships eliminate risk.
- Model mapping. Populate the Excel Canvas block by block, then use the Word analysis to explore tensions between customer value, required capabilities and the economics of assuming mortgage-credit risk.
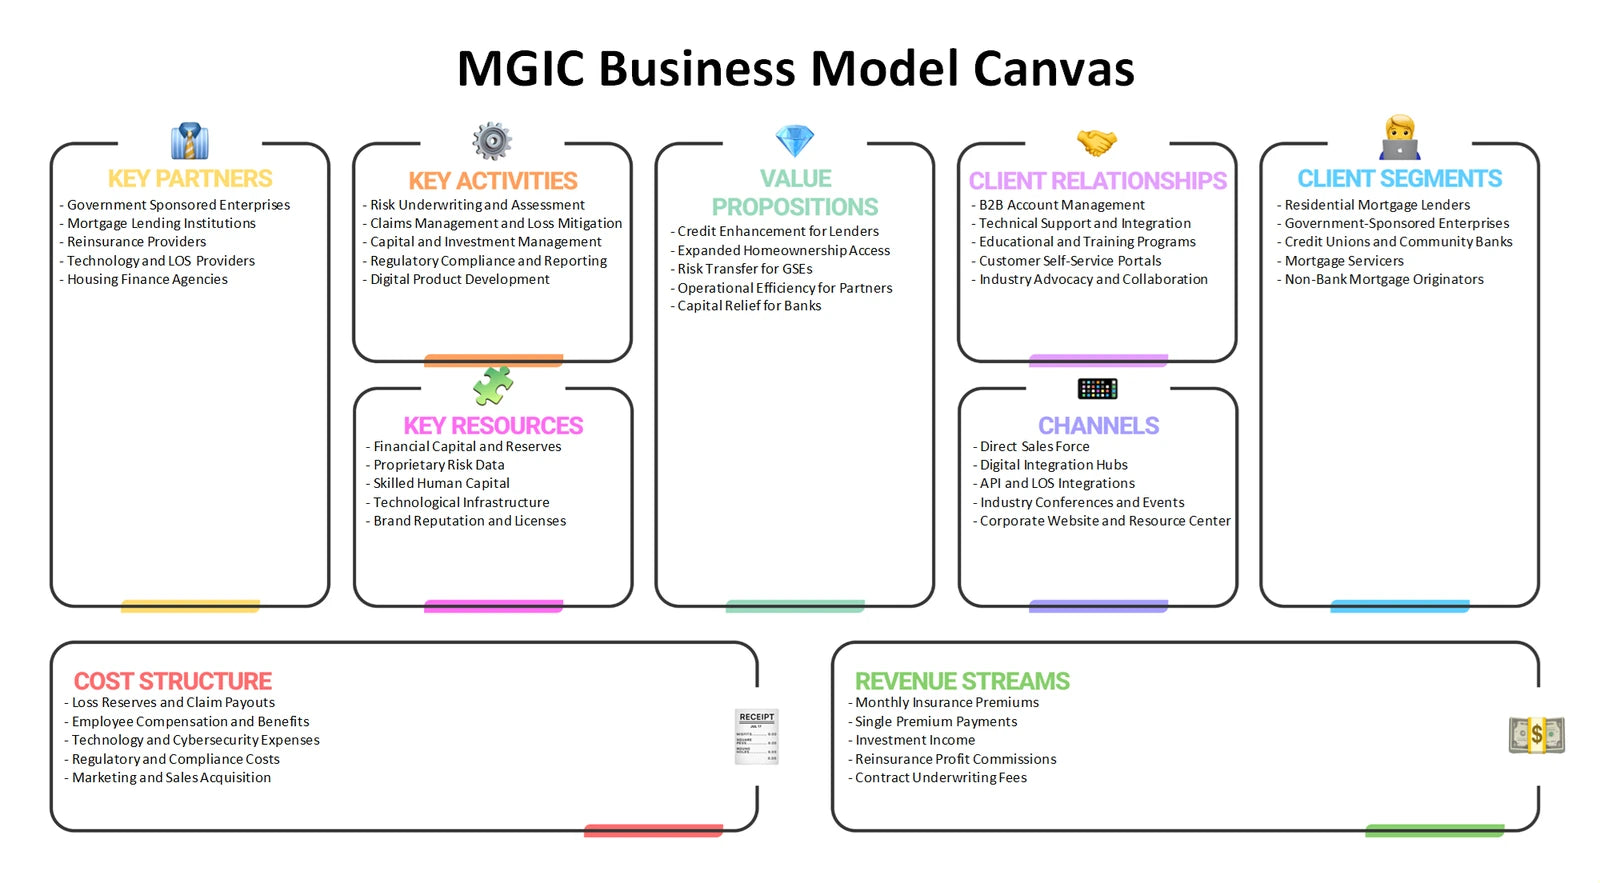
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What structural pressures influence MGIC’s ability to compete for lender business while maintaining disciplined mortgage-credit risk?
MGIC Porter’s Five Forces analysis examines rivalry, buyer power, supplier power, the threat of new entrants and the threat of substitutes in private mortgage insurance. Lenders can exert buyer power through their volume, channel choices and insurance-provider selection. Rivalry concerns the contest for eligible mortgage-insurance business, while new entrants face the challenge of building capital, credibility, underwriting capability and required eligibility. Supplier power can include the availability and terms of reinsurance or other risk-transfer capacity. Substitutes are not simply rival insurers: larger borrower down payments or loan structures that avoid a private-insurance need can alter demand.
- Buyer leverage. Examine how concentration, lender switching considerations and service expectations may affect negotiating power and relationship retention.
- Entry and substitution. Compare barriers created by capital, regulation and GSE-related eligibility with alternative ways borrowers or lenders may reduce the need for private coverage.
- Pressure testing. Use the Excel framework to rate evidence and open questions for each force, with the Word analysis supplying the sector context behind the ratings.
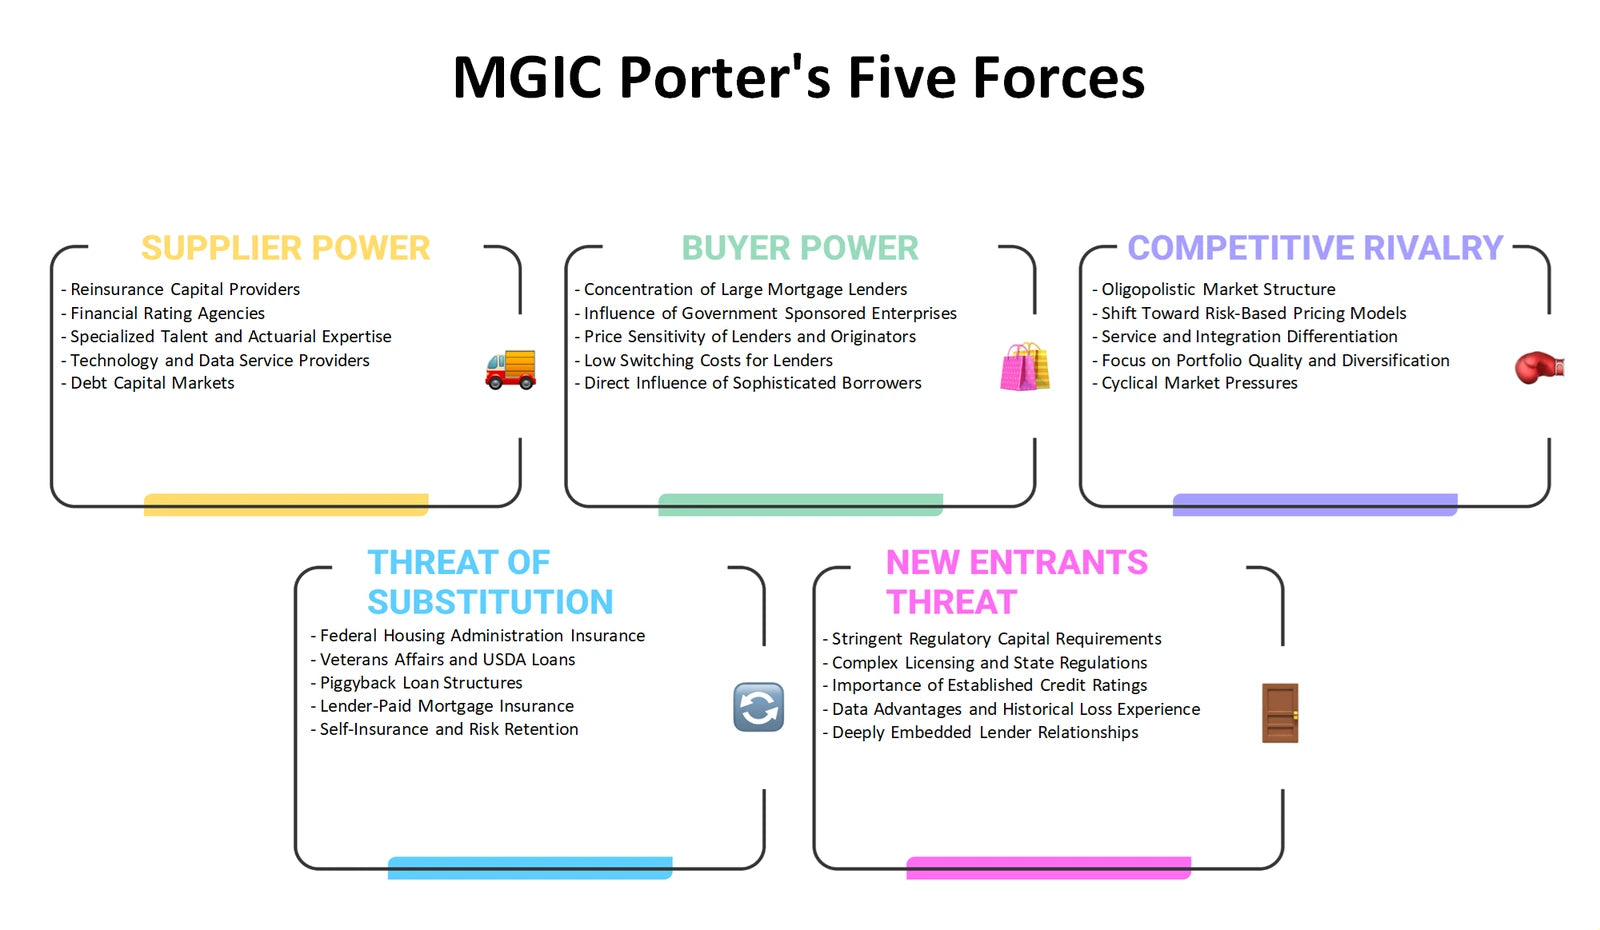
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can MGIC’s Product, Price, Place and Promotion be examined for a regulated business sold through mortgage-lender relationships?
The MGIC Marketing Mix treats the 4Ps as B2B insurance decisions, not as a consumer-retail checklist. Product can cover the mortgage-insurance protection, underwriting support and lender-facing service that accompany an eligible loan. Price concerns premium logic and the factors that may influence quoted coverage economics, without inventing actual rates. Place is chiefly the lender-originated route to market, including the relationships through which insurance is selected. Promotion concerns education, relationship communication and clear explanation of eligibility and value to lending professionals, rather than presumed advertising campaigns.
- Product fit. Assess whether the offering and service model address lender workflow, credit-risk needs and the requirements surrounding insured mortgages.
- Route-to-market. Compare how banks, credit unions and non-bank lenders may require different relationship coverage, communication and service priorities.
- Mix decisions. Organise the four Ps in Excel as linked choices, then use the Word analysis to discuss why a pricing or channel decision can affect customer adoption and risk quality.
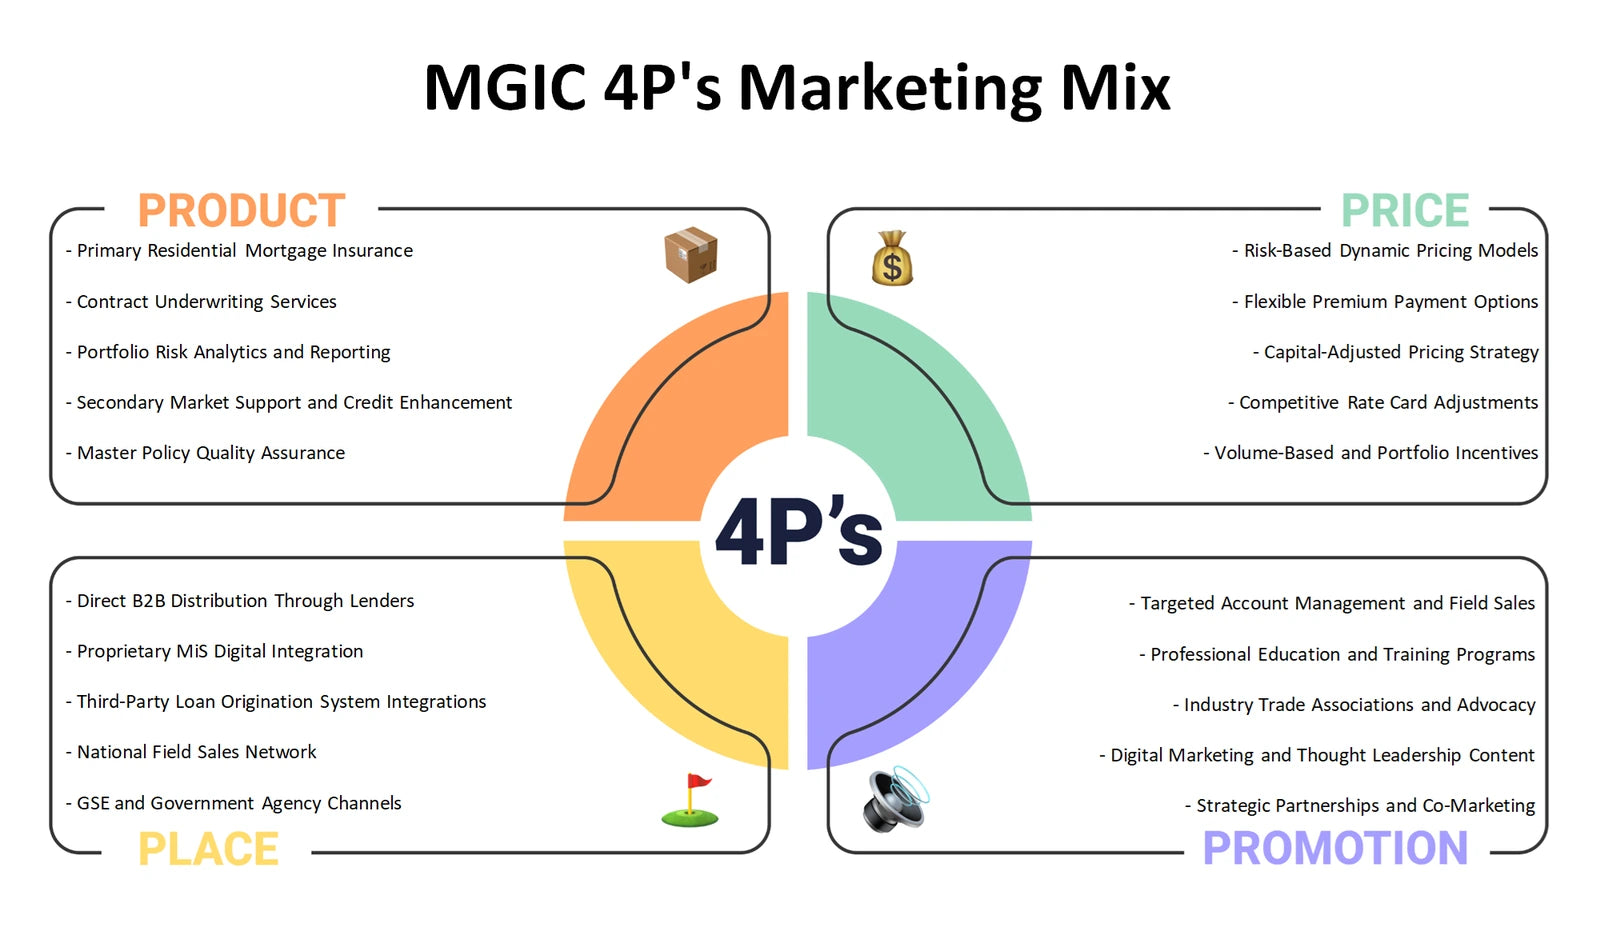
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could reshape the US mortgage environment in which MGIC serves lenders and manages insured credit risk?
The MGIC PESTLE analysis, also commonly called PESTEL, separates external influences from company capabilities. Political questions can include housing-policy direction and the role of government-sponsored enterprises. Economic conditions may affect mortgage demand, home prices, borrower stress and lending volumes. Social factors can include household formation, affordability and down-payment behaviour. Technological change can alter lender workflow, data use and fraud controls. Legal considerations include insurance oversight and GSE eligibility expectations, while environmental issues can raise questions about property exposure, resilience and geographic risk. These are areas to examine, not claims that a specific policy or market change has already occurred.
- External signals. Track which developments could influence lender origination activity, insurance demand, underwriting assumptions or claims exposure.
- Interconnected risks. Consider how a housing or economic shift may interact with legal, technology and environmental considerations instead of reviewing each factor in isolation.
- Scenario register. Use the Excel framework to log drivers, time horizons and possible implications, then consult the Word analysis to develop company-relevant questions for review.
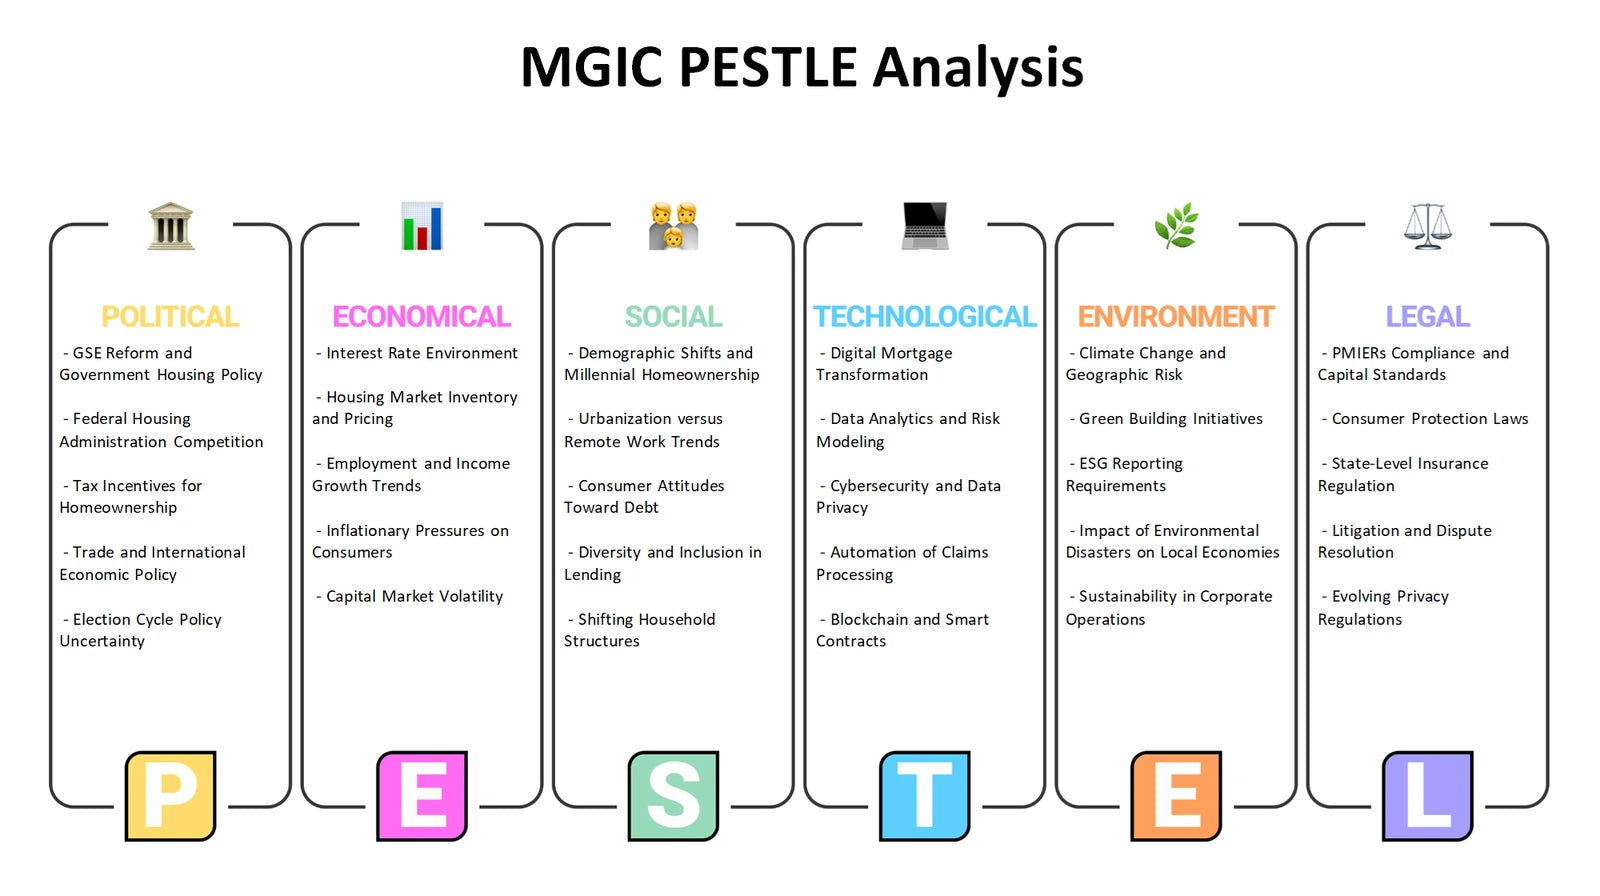
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How should MGIC distinguish its internal capabilities and constraints from external mortgage-market opportunities and threats?
The MGIC SWOT analysis keeps classification clear. Strengths and weaknesses are internal: for example, the analysis can test the significance of lender relationships, underwriting knowledge, operational processes, capital management or dependence on particular capabilities. Opportunities and threats come from outside the company, such as changes in mortgage demand, competitive conditions, GSE requirements, borrower affordability or the availability of reinsurance. The purpose is not to label plausible themes as settled findings. Instead, it creates a concise decision framework for considering whether documented capabilities are suited to external conditions and where a risk or opportunity warrants deeper evidence.
- Internal diagnosis. Separate operational capabilities and constraints from external market conditions so management questions are not mixed with industry observations.
- Strategic fit. Test whether lender reach, risk-transfer relationships and eligibility-related discipline could matter under different mortgage-market scenarios.
- Action comparison. Use the Excel SWOT grid to prioritise evidence-backed themes, then use the Word analysis to compare possible responses and identify questions requiring further validation.
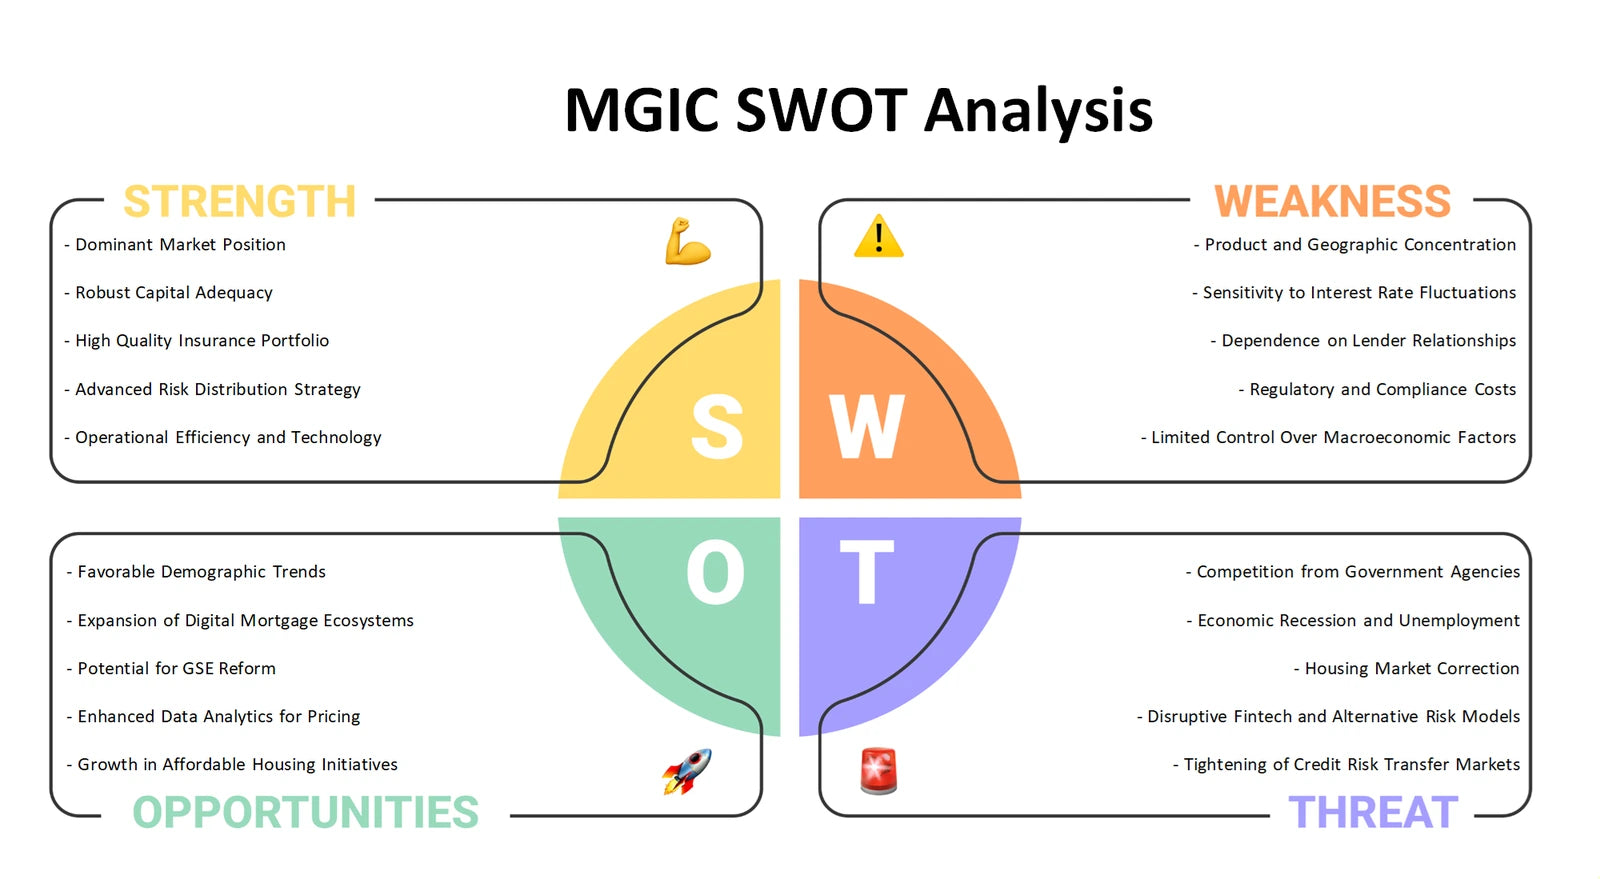
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of MGIC’s strategic choices
Together, the six perspectives connect portfolio priorities, value creation, industry pressure, lender-facing marketing choices, external conditions and internal-versus-external strategic fit. The Excel frameworks help organise comparisons and assumptions, while the Word materials provide detailed company analysis for developing more focused questions about MGIC’s mortgage-insurance business, partnerships and risk-sensitive operating model.
Company background: MGIC — matching product-context source.