

Mercuries & Associates: Underwriting and Distribution – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Mercuries & Associates Strategy Analysis Bundle
For this bundle, Mercuries & Associates is examined through the available Taiwan-focused insurance context: underwriting protection for risks such as typhoon, earthquake and SME property exposures, supported by relationships with global reinsurers. That context points to an insurance business in which policyholders need dependable cover while underwriting teams must balance local risk knowledge, capacity and service.
The supplied business context refers to reinsurer relationships including Munich Re, Swiss Re and SCOR, alongside specialty-product development for Taiwan. These are useful starting points rather than verified performance findings. The six analyses help customers examine portfolio choices, risk-transfer economics, distribution questions and the external conditions that can shape an insurer's priorities. Excel frameworks provide a structured working view, while the Word files provide detailed company analysis.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance product lines merit capacity, specialist attention or a more cautious allocation of resources?
A Mercuries & Associates BCG Matrix helps organise an insurance portfolio around two analytical criteria: market growth and relative market share. Rather than assuming that catastrophe, SME property or other specialist covers belong in a particular quadrant, it helps compare the evidence needed to test that position. Stars, Cash Cows, Question Marks and Dogs are portfolio categories, not ratings of policy quality. This matters where a growing protection need may consume underwriting capacity, reinsurance support and claims expertise before it produces dependable returns. The lens can connect product demand with the practical cost of carrying and servicing risk.
- Portfolio comparison. Examine whether different cover types face distinct growth conditions and relative competitive positions.
- Capacity trade-off. Consider where underwriting expertise, catastrophe modelling and reinsurance capacity could be most consequential.
- Working view. Use the Excel framework to map candidate lines and use the Word analysis to document assumptions, evidence gaps and priority questions.
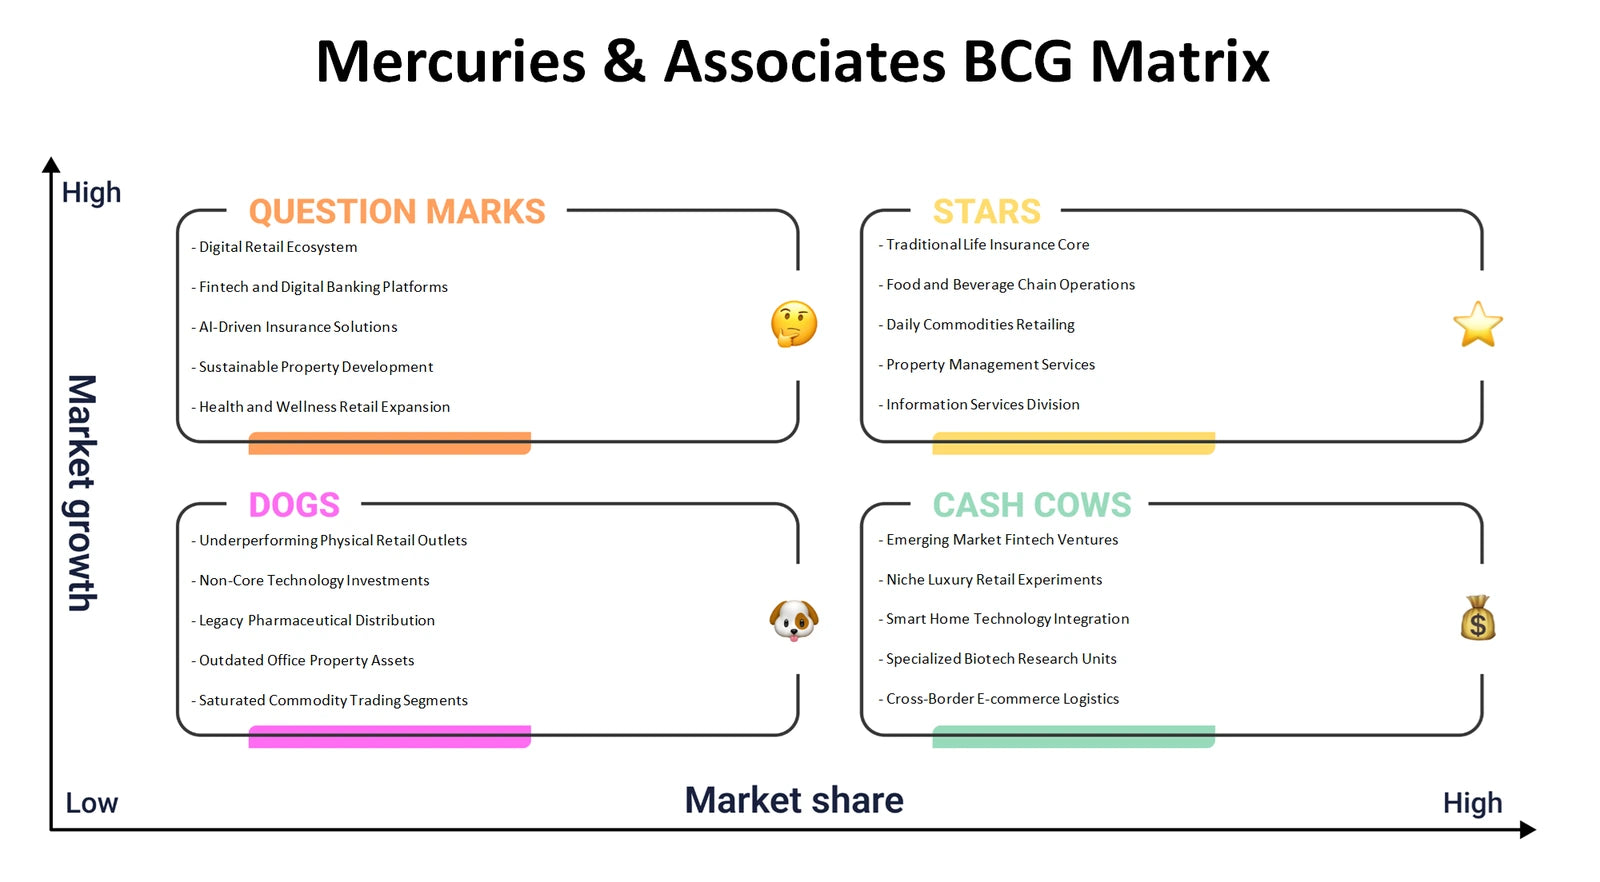
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How can risk expertise, reinsurance support and customer access combine into a viable insurance business model?
The Mercuries & Associates Business Model Canvas brings together all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. In the supplied context, prospective customer segments may include people or businesses seeking protection against property and catastrophe exposure; the analysis helps test rather than presume how those needs translate into a value proposition. It can also examine how policies reach customers, how relationships are maintained through underwriting and claims, and how premium income relates to the costs of risk selection, administration and risk transfer. Reinsurers are especially relevant as potential key partnerships, but their role must be assessed alongside the insurer's own capabilities and obligations.
- Value chain. Trace the connection from protection needs and policy design to distribution, service and premium-based revenue streams.
- Risk-transfer logic. Explore how key partnerships and key resources may support exposure management without assuming specific contract terms.
- Model workshop. Populate the Excel blocks systematically, then use the Word analysis to explain the links and tensions between the blocks.
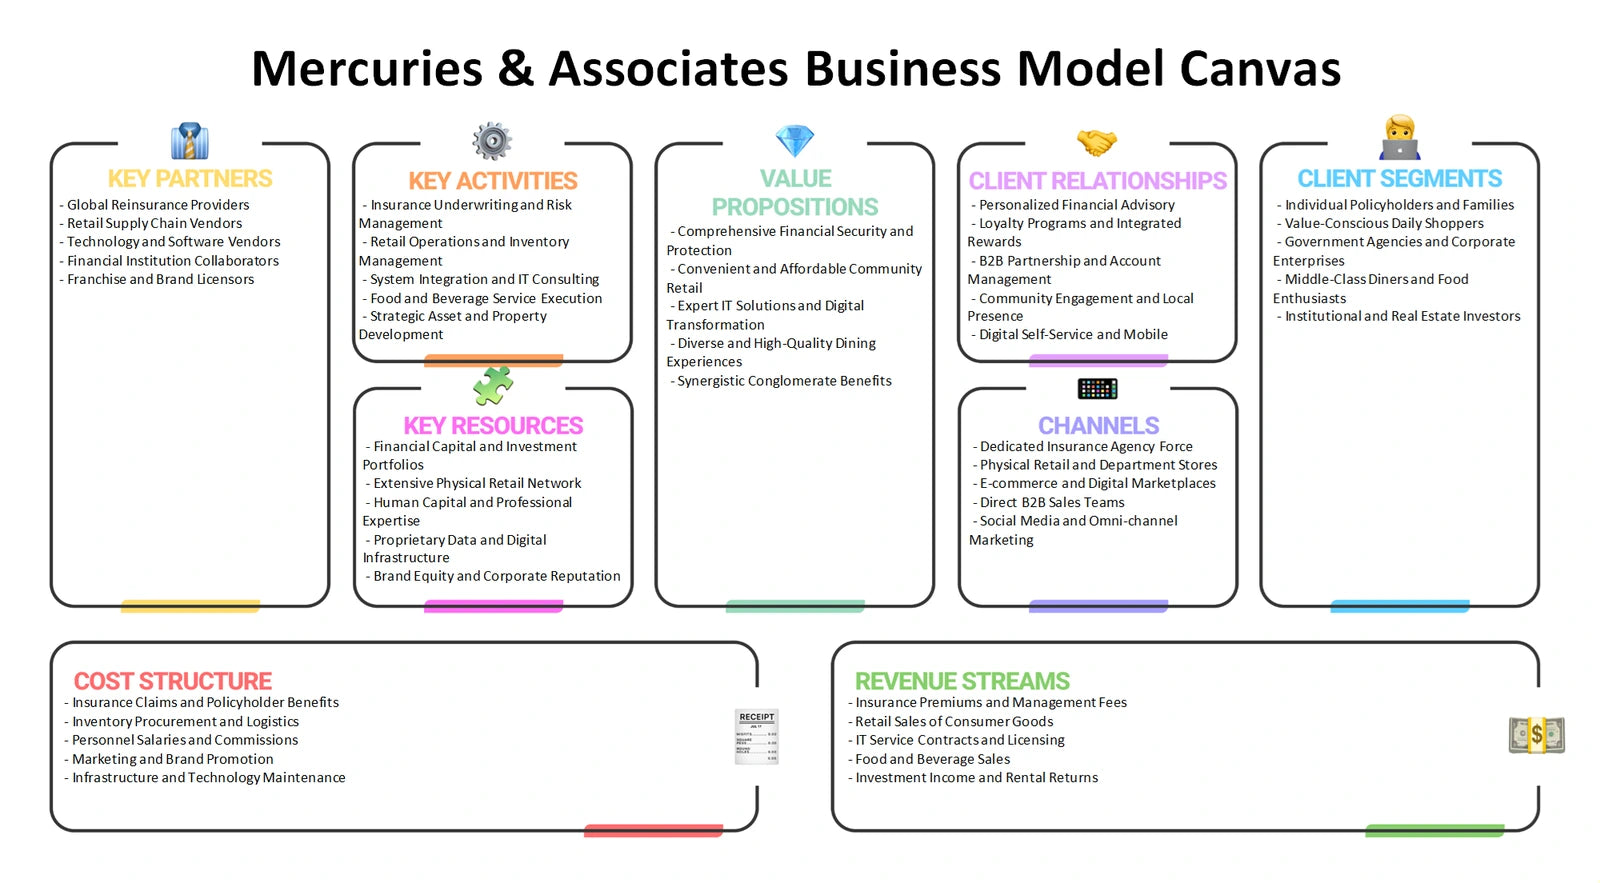
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could affect the attractiveness of Taiwan-focused property and catastrophe insurance activity?
Mercuries & Associates Porter's Five Forces analysis examines industry structure rather than declaring a force strong or weak without evidence. Rivalry concerns the contest for suitable policyholders, underwriting talent and intermediary attention. Supplier power can include the influence of capital providers, specialist service providers and reinsurers when risk capacity is scarce. Buyer power asks how informed policyholders, SMEs, brokers or corporate purchasers can compare terms and negotiate. Threat of new entrants considers the barriers created by regulation, capital, licences, risk expertise and trusted distribution. Threat of substitutes looks beyond direct insurers to alternative ways customers may retain, mitigate, pool or finance risk instead of buying conventional cover.
- Competitive pressure. Separate rivalry over price from competition based on coverage terms, claims experience and specialist knowledge.
- Counterparty leverage. Assess how dependence on external capacity or distribution could affect negotiating flexibility.
- Evidence trail. Use Excel to compare each force and the Word analysis to record the company-specific reasoning behind each assessment.
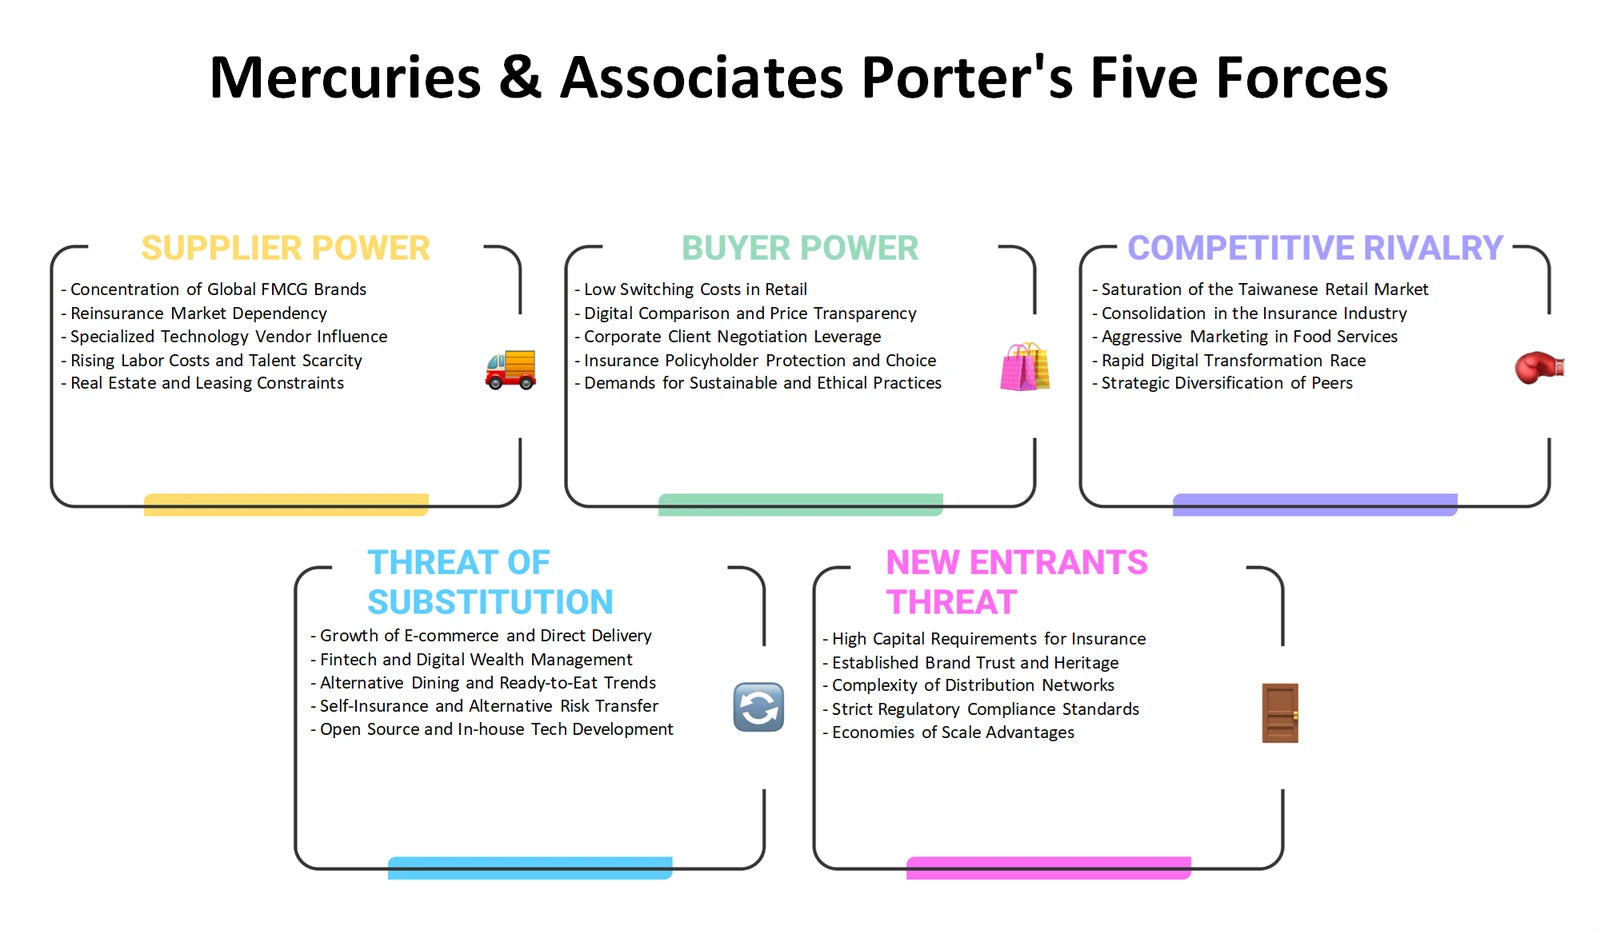
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should specialist insurance protection be shaped and communicated for customers facing identifiable property risks?
A Mercuries & Associates Marketing Mix considers Product, Price, Place and Promotion within a regulated, trust-dependent service category. Product analysis can examine the usefulness and boundaries of covers designed for property, typhoon or earthquake exposure, including the clarity customers need around exclusions and claims processes. Price is not simply a promotional figure: it can be studied as a balance among expected risk, coverage limits, service costs and reinsurance arrangements. Place addresses routes to market, such as direct, intermediary or partner-led distribution where supported by evidence. Promotion considers how risk education, product explanation and credible communication may help customers understand protection without making unsupported promises.
- Offer design. Compare customer needs with policy features, protection limits and understandable service information.
- Route to market. Examine which distribution and communication choices may suit SMEs or other relevant policyholder groups.
- Decision support. Use the Excel 4Ps layout to organise options, then consult the Word analysis for the strategic context behind each choice.
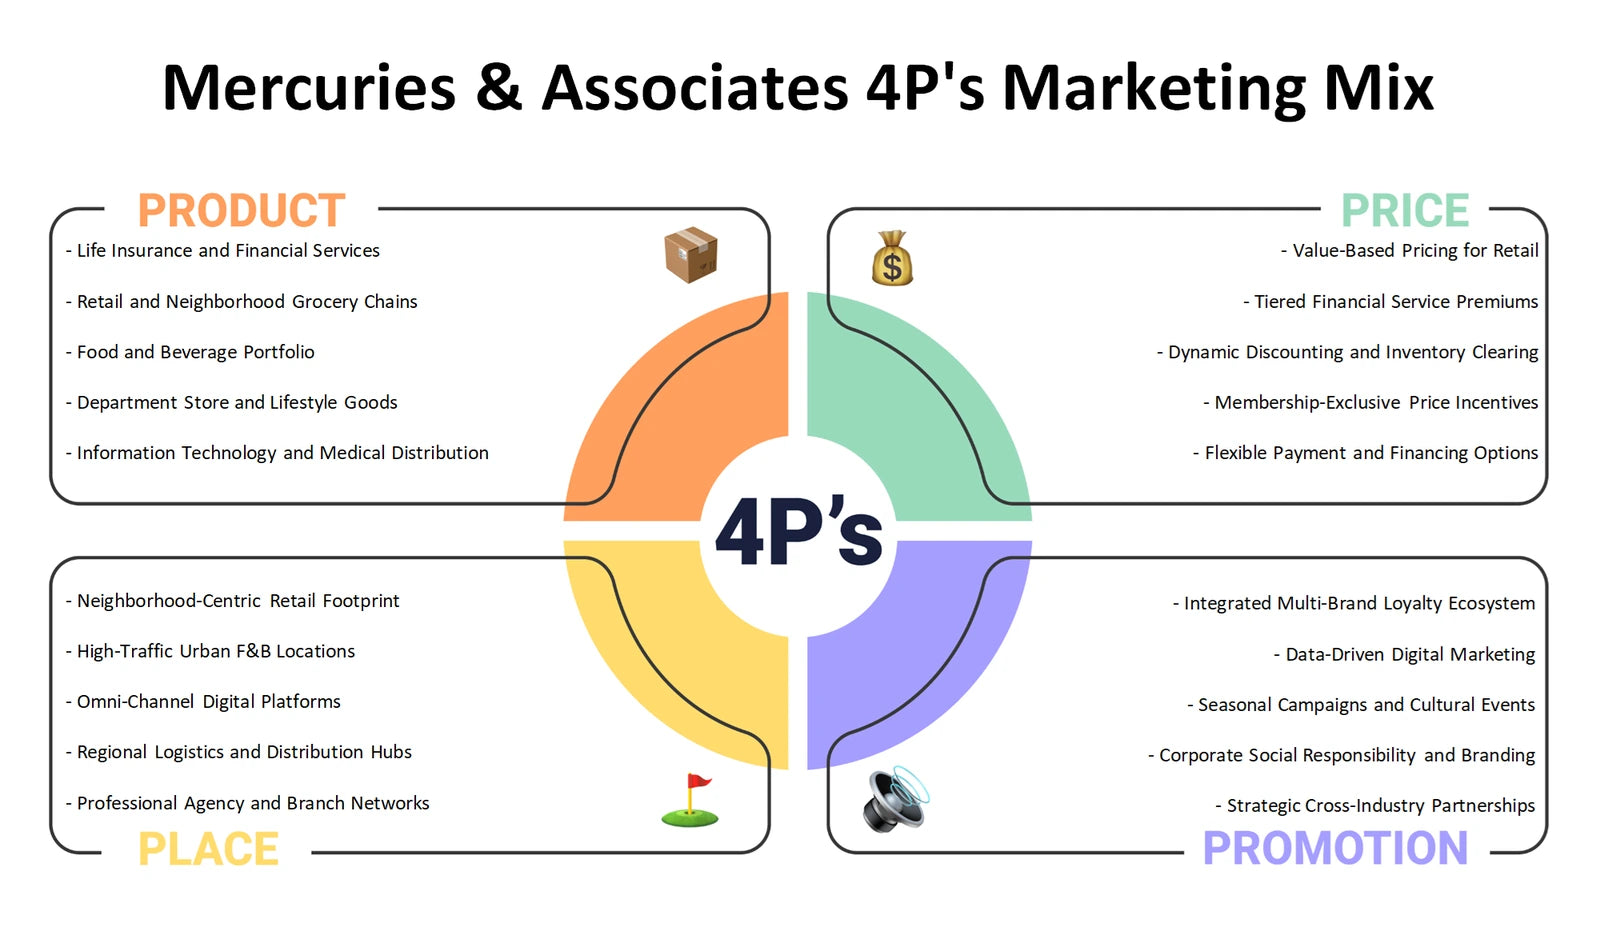
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external developments could alter insurance demand, risk costs and operating requirements in the relevant market?
Mercuries & Associates PESTLE analysis, also commonly called PESTEL, separates external influences into Political, Economic, Social, Technological, Legal and Environmental dimensions. Political and legal questions can address the policy, supervisory and consumer-protection environment affecting insurance, without assuming a particular new rule exists. Economic conditions may influence affordability, insured values, investment conditions and business demand. Social factors can include awareness of disaster resilience and expectations of claims support. Technology may reshape underwriting data, distribution and service operations. Environmental conditions are particularly relevant when catastrophe-related hazards influence property exposure; the framework helps distinguish a long-term risk consideration from a verified recent event or trend.
- External scan. Identify developments that may affect both the demand for protection and the cost of assuming risk.
- Change signals. Separate documented conditions from questions requiring regulatory, climate or market evidence.
- Monitoring plan. Use the Excel categories to track external signals and use the Word analysis to interpret why selected signals matter.
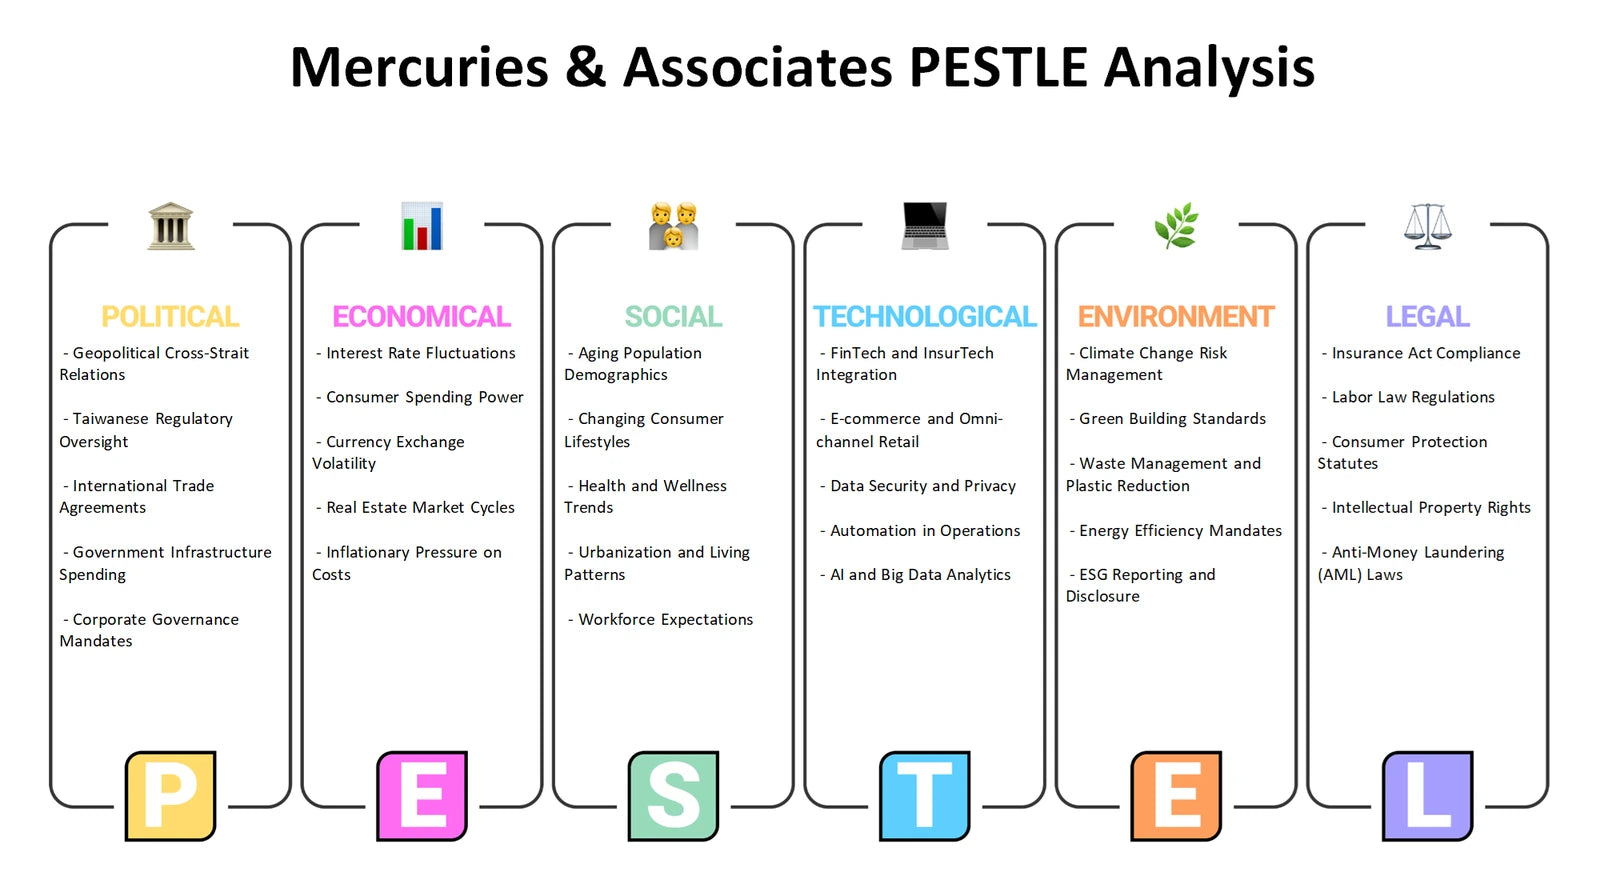
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal insurance capabilities be considered alongside external opportunities and threats without confusing the two?
A Mercuries & Associates SWOT analysis distinguishes internal Strengths and Weaknesses from external Opportunities and Threats. The supplied context suggests useful themes to investigate, not established conclusions: local understanding of catastrophe-sensitive cover, specialist underwriting knowledge and relationships with reinsurers could be tested as potential capabilities. Conversely, dependence on external capacity, concentration in selected exposures or gaps in distribution may be appropriate areas for examination if supported by evidence. Opportunities belong outside the company, such as evolving protection needs among SMEs, while threats include adverse loss experience, intense competitive conditions, changing requirements or shifting customer expectations. Keeping this classification clear prevents a list of plausible ideas from being presented as confirmed company findings.
- Internal diagnosis. Distinguish capabilities and constraints that management can influence from conditions it cannot control directly.
- Strategic fit. Test whether possible market opportunities align with underwriting, partnership and service capacity.
- Action framing. Use the Excel matrix to connect themes, then use the Word analysis to develop evidence-based discussion points and follow-up questions.
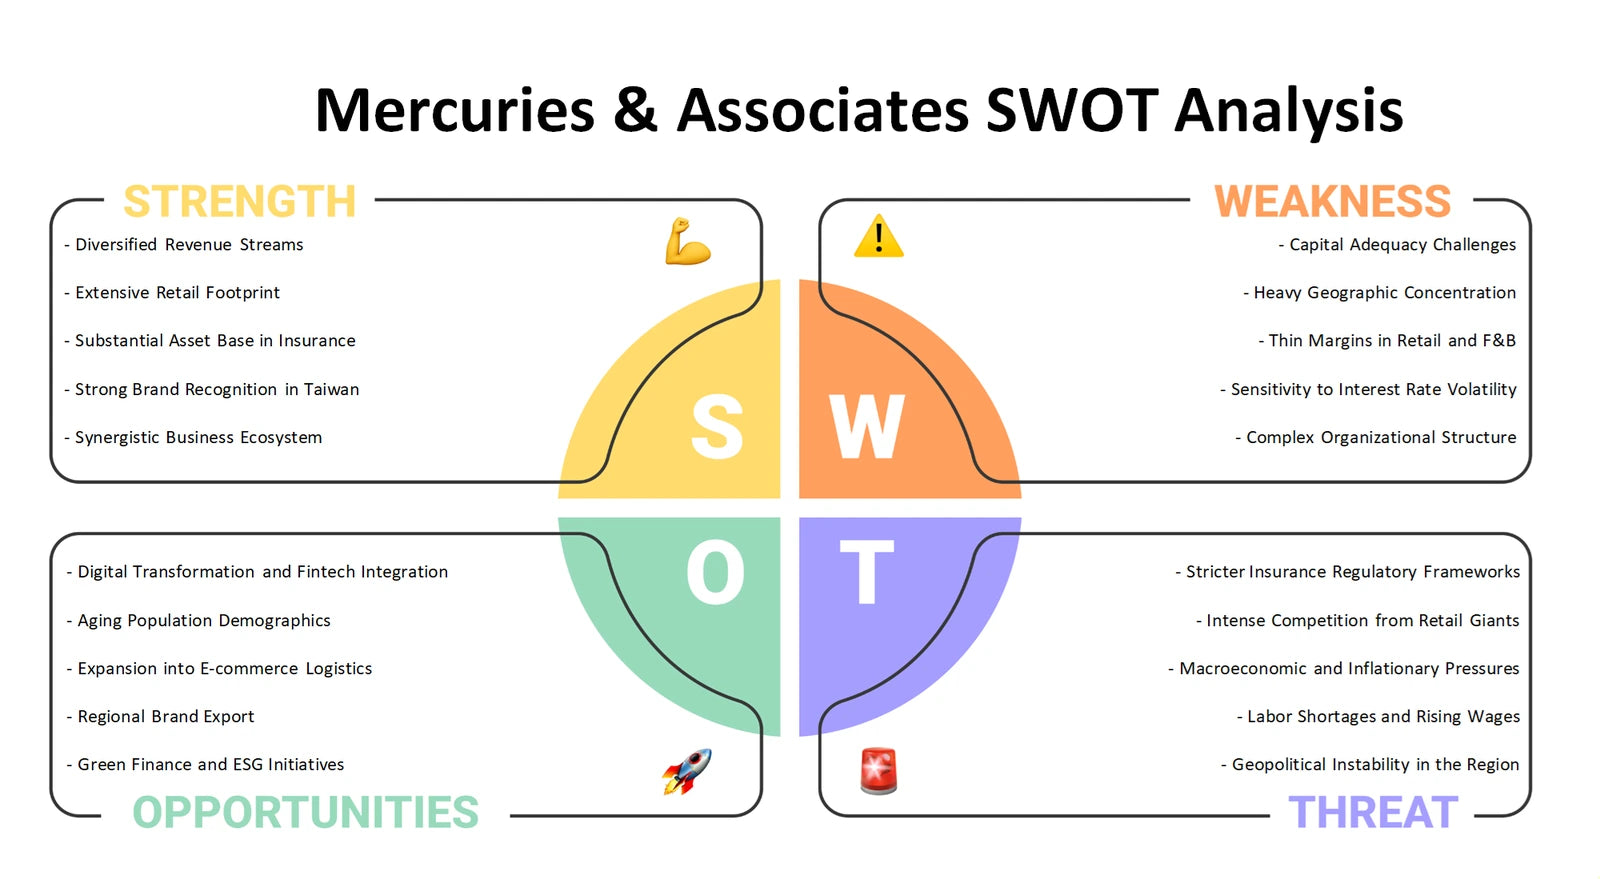
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Link portfolio choices to the business system around them
Together, the six perspectives let customers move from portfolio questions to the business model, industry pressures, customer-facing choices, external conditions and internal-versus-external strategic fit. For Mercuries & Associates, that creates a more coherent way to explore specialist insurance and reinsurance-related questions than using one framework alone. The Excel materials help structure comparisons and working assumptions, while the detailed Word analysis helps explain the company context and the reasoning behind each lens.
Company background: Mercuries & Associates — supplied analysis-context page.