

Merchants Bank: Banking Business and Lending Economics – Six Business Analyses

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Merchants Bank Strategy Analysis Bundle
This bundle is scoped to the U.S. financial-services business identified in the supplied product context as Merchants Bank of Indiana, while retaining the workbook display name Merchants Bank. The available context links its banking activities to commercial real estate financing, particularly multifamily housing and healthcare projects, alongside small-business lending and Merchants Capital mortgage activity. It should not be confused with other same-name institutions or historic banks.
The documented context points to relationships with real estate developers, the SBA, and government-sponsored enterprises including Fannie Mae and Freddie Mac. Those relationships raise practical questions about lending-market priorities, funding capacity, customer access, regulation, and external economic conditions. The six connected analyses help organize those questions without presenting unverified financial results, market shares, or investment conclusions as facts.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which lending, mortgage-finance, or relationship-led activities merit the greatest management attention?
A Merchants Bank BCG Matrix helps separate portfolio questions from assumptions. It compares market growth with relative market share, using the familiar Stars, Cash Cows, Question Marks, and Dogs categories as analytical positions rather than assigning them to products without evidence. For a bank connected to commercial real estate lending, SBA programs, and mortgage finance, the useful comparison is between the growth outlook and competitive position of different customer or financing activities.
- Portfolio boundaries. Compare activities such as commercial real estate finance, small-business lending, and mortgage-related services without treating them as one undifferentiated business.
- Capital discipline. Examine where growth demand, balance-sheet capacity, underwriting resources, and relationship-management effort may pull in different directions.
- Structured comparison. Use the Excel framework to map candidate activities, then use the Word analysis to document the evidence and assumptions behind each placement.
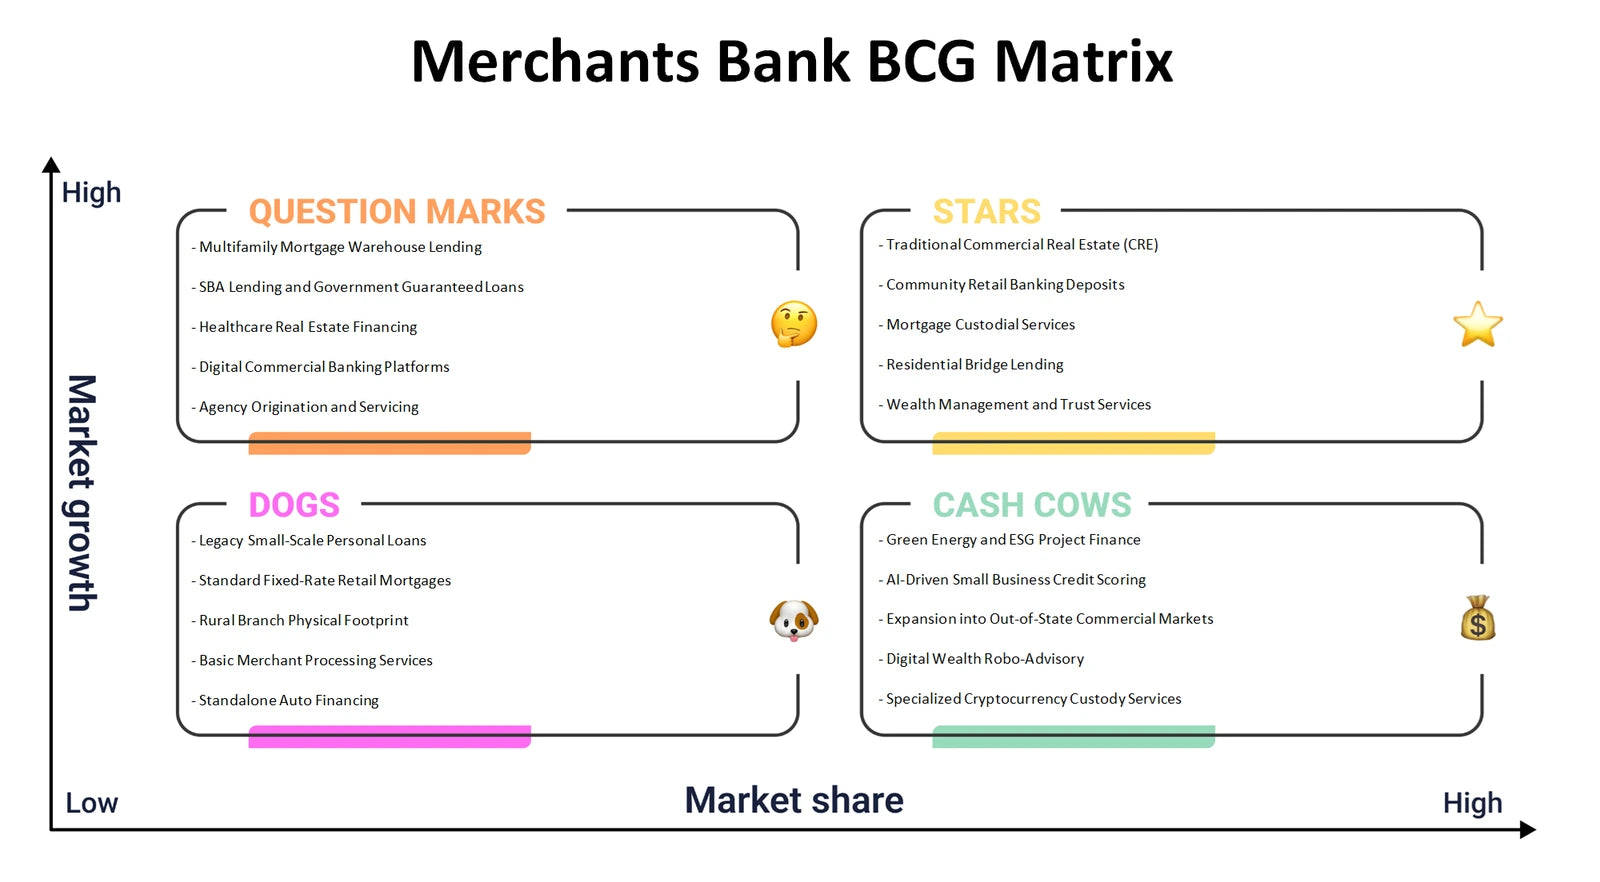
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How do customer relationships, lending capabilities, and funding partnerships connect to value creation and economics?
The Merchants Bank Business Model Canvas examines all nine building blocks as one connected system: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships, cost structure, and cost structure implications. The supplied context makes developer relationships, GSE connections, and SBA-related lending especially relevant topics to test. The lens helps show how specialized financing needs may shape service delivery, risk management, distribution, and the economics of originating and supporting loans.
- Customer logic. Distinguish the needs of property developers, multifamily and healthcare borrowers, mortgage counterparties, and small-business owners.
- Partnership mechanics. Consider how Fannie Mae, Freddie Mac, SBA programs, and professional referral networks may affect activities, channels, resources, and revenue logic.
- Model linkage. Populate the Excel canvas block by block and use the Word analysis to explain the connections, trade-offs, and open questions behind it.
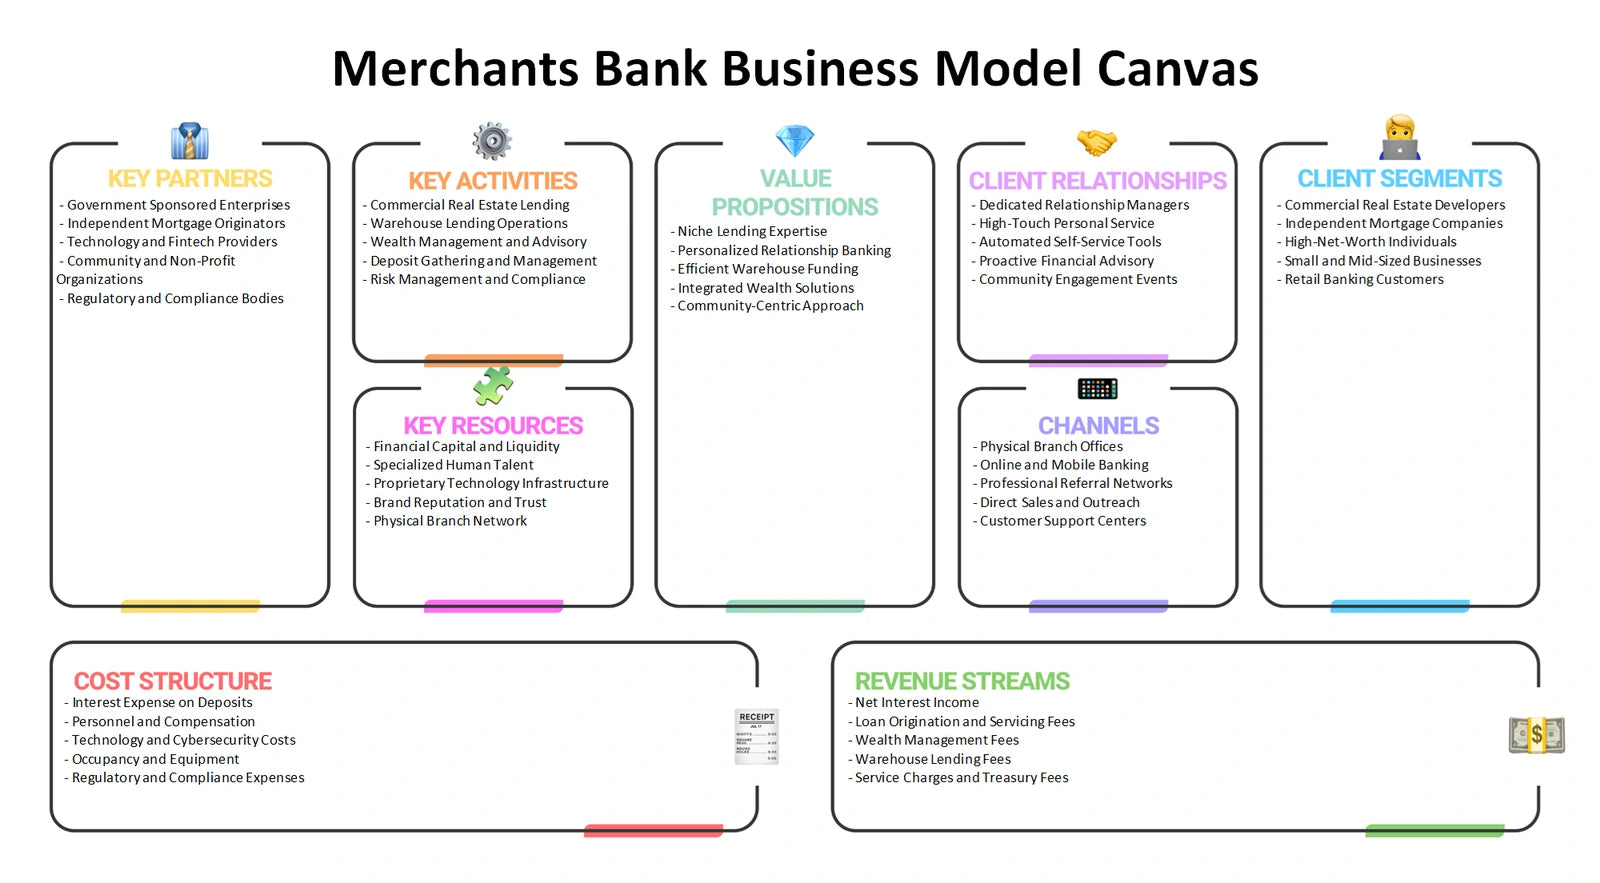
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could shape the attractiveness of specialized lending and mortgage-finance activity?
Merchants Bank Porter's Five Forces frames pressure around commercial lending, small-business finance, and mortgage-related services. Rivalry concerns the contest for qualified borrowers and trusted referral relationships. Buyer power considers borrowers that can compare lenders, terms, expertise, and speed. Supplier power can include reliance on funding sources, capital, technology, specialist talent, or program partners. New entrants may target profitable niches, while substitutes include non-bank lenders, private credit, equity financing, and alternative ways borrowers can meet financing needs.
- Competitive pressure. Assess whether specialization in real estate or government-supported lending creates differentiation, concentration risk, or both.
- Alternative funding. Compare bank finance with private lenders, capital-market options, investor equity, and other borrower funding routes.
- Evidence trail. Score discussion points in the Excel force structure, then use the Word analysis to record why each pressure matters operationally.
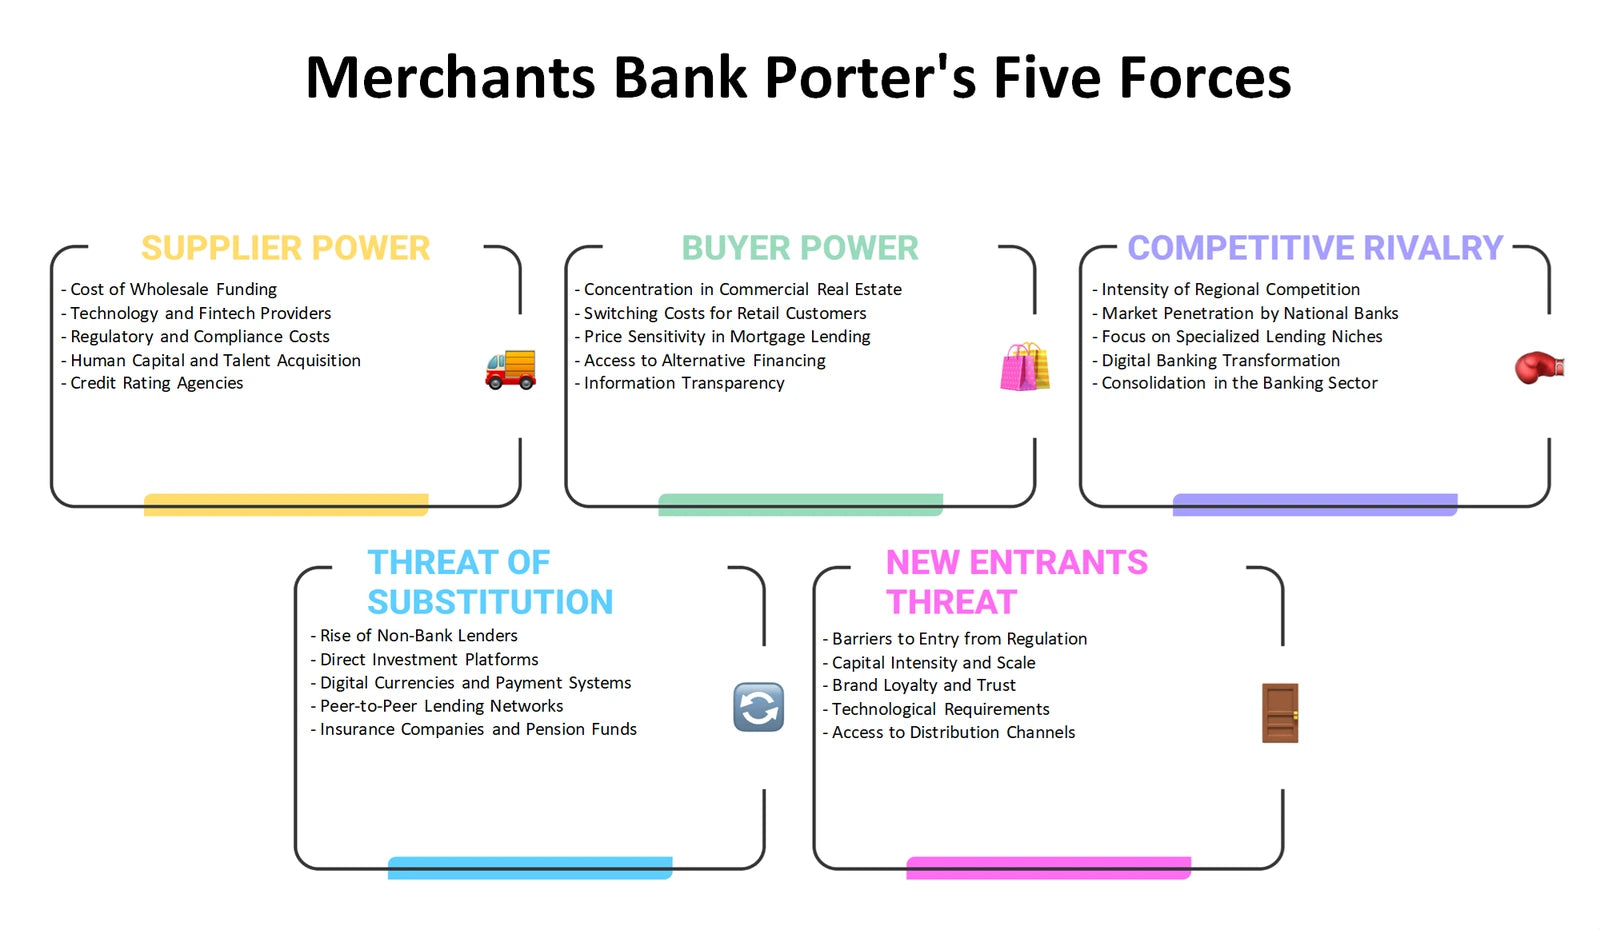
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How can a regulated, relationship-led lender align its offer, pricing logic, access routes, and communications?
The Merchants Bank Marketing Mix applies Product, Price, Place, and Promotion to financial services rather than consumer packaged goods. Product can cover financing expertise and lending programs relevant to commercial property borrowers, mortgage customers, or small-business owners. Price is broader than a headline rate: it can include terms, fees, risk-based underwriting, and the value of specialist service. Place considers direct relationship channels, professional networks, and program-linked access. Promotion should be assessed through credible education and compliant communication, not assumed campaigns.
- Offer design. Examine how loan purpose, sector expertise, service responsiveness, and program eligibility may make offerings more relevant to distinct borrower groups.
- Route to borrower. Compare relationship managers, developers, advisers, referral sources, and digital enquiry paths as possible access mechanisms.
- Planning application. Use the Excel 4Ps layout to align choices, then use the Word analysis to explain customer implications and compliance-sensitive messaging questions.
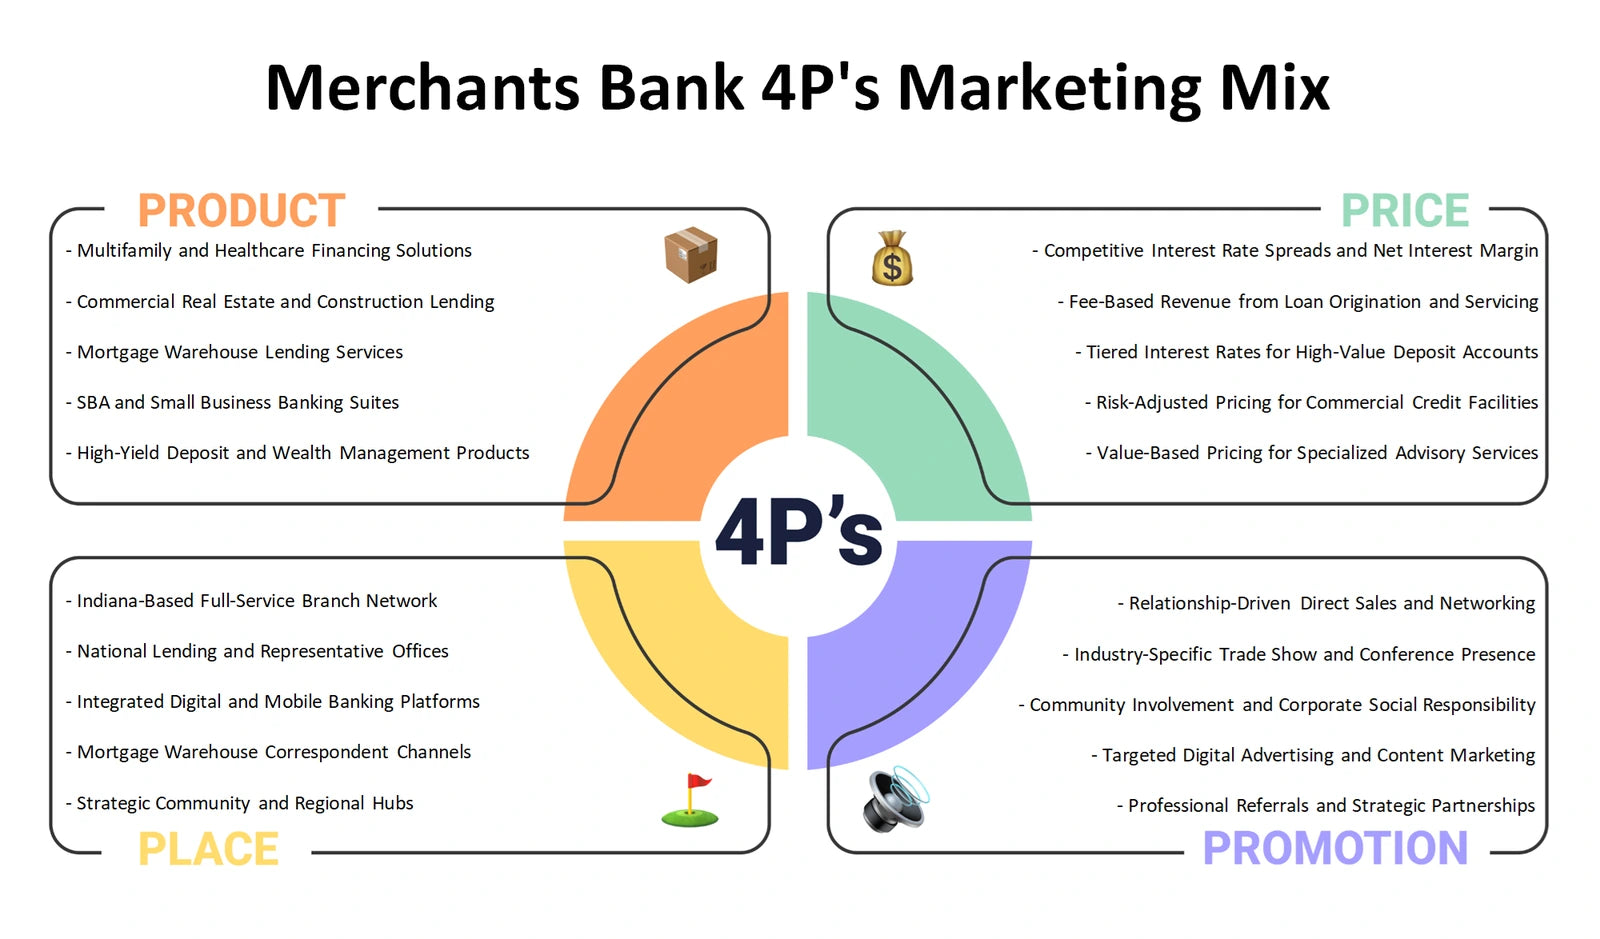
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external changes could alter borrower demand, lending economics, and operating requirements?
A Merchants Bank PESTLE analysis, also commonly called PESTEL, organizes external influences without confusing them with internal capabilities. Political factors may include public lending priorities and housing policy. Economic questions include credit conditions, real estate cycles, borrower affordability, and interest-rate sensitivity. Social trends can affect housing, healthcare facilities, and small-business demand. Technological change matters for servicing, data, cyber resilience, and customer access. Legal and environmental factors can shape banking compliance, property lending, construction standards, and climate-related exposure.
- Policy sensitivity. Explore how changes to government-supported lending programs or housing priorities could affect eligible customer demand.
- Property exposure. Consider how economic and environmental conditions may influence multifamily, healthcare, and commercial real estate financing decisions.
- External scan. Use the Excel framework to separate six external categories, supported by the Word analysis for context, implications, and monitoring questions.
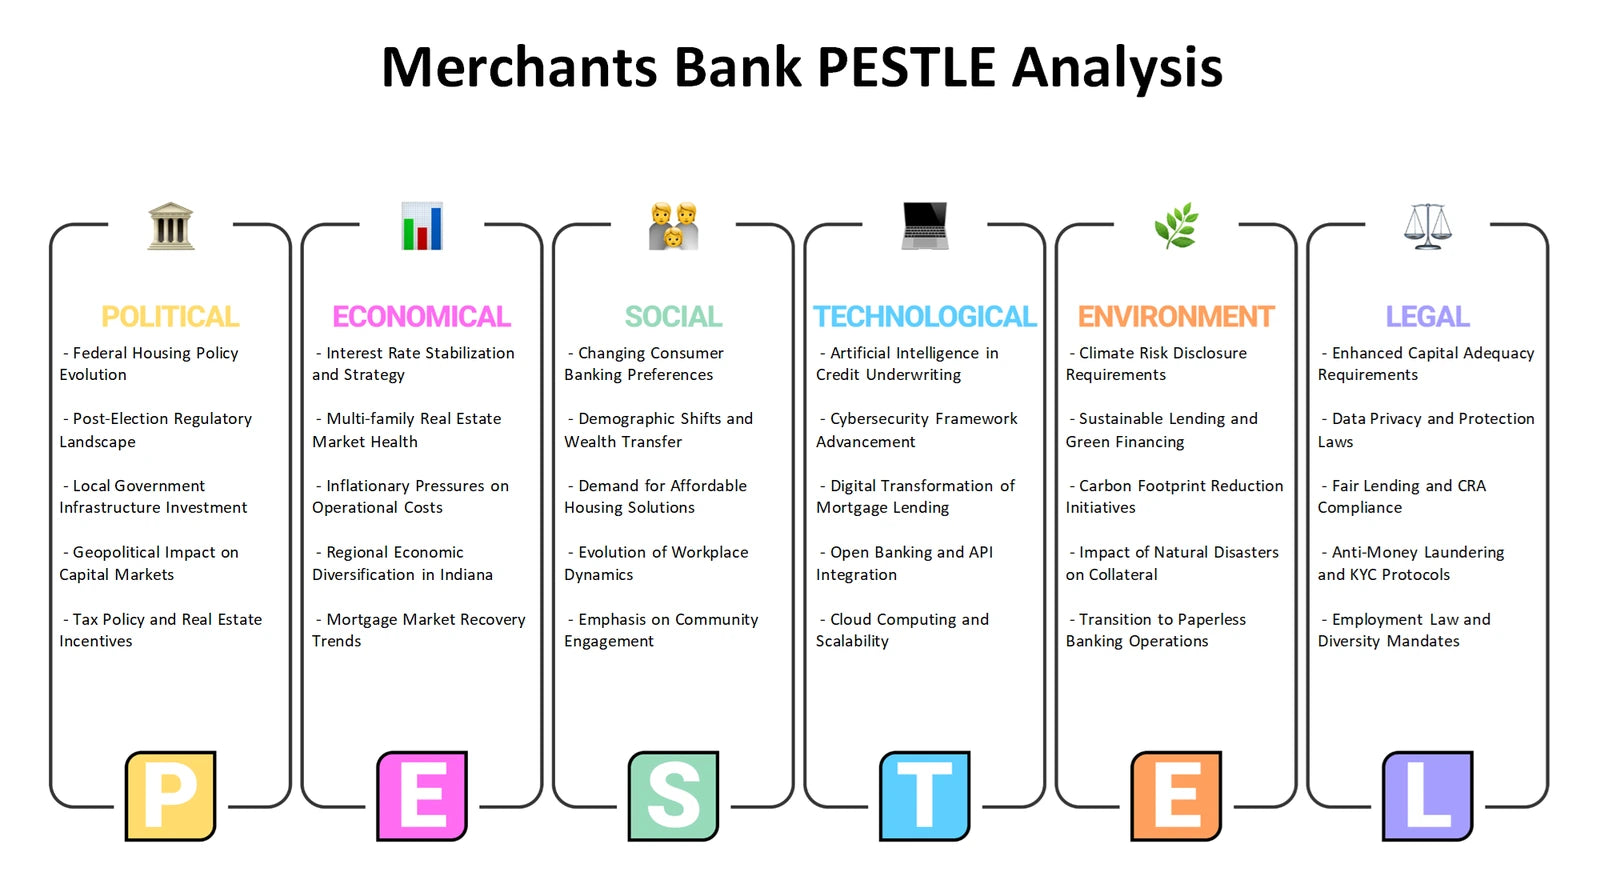
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can internal lending capabilities be considered alongside external openings and threats?
The Merchants Bank SWOT analysis separates what is inside the business from what is happening around it. Strengths and weaknesses concern internal capabilities or constraints, such as specialized sector knowledge, partnership-management capacity, underwriting processes, concentration exposure, systems, or talent. Opportunities and threats are external conditions, including borrower needs, funding-market changes, regulatory developments, competing finance sources, and property-market uncertainty. The framework does not claim that any listed theme has been proven; it provides a disciplined way to test how evidence from the other five analyses may fit together.
- Correct classification. Keep relationships, expertise, processes, and resource limits on the internal side; keep market and regulatory conditions on the external side.
- Strategic fit. Explore whether potential opportunities in specialized lending are matched by the capabilities, controls, and capacity needed to pursue them responsibly.
- Decision synthesis. Use the Excel matrix to prioritize themes and the Word analysis to capture supporting rationale, dependencies, and questions for review.
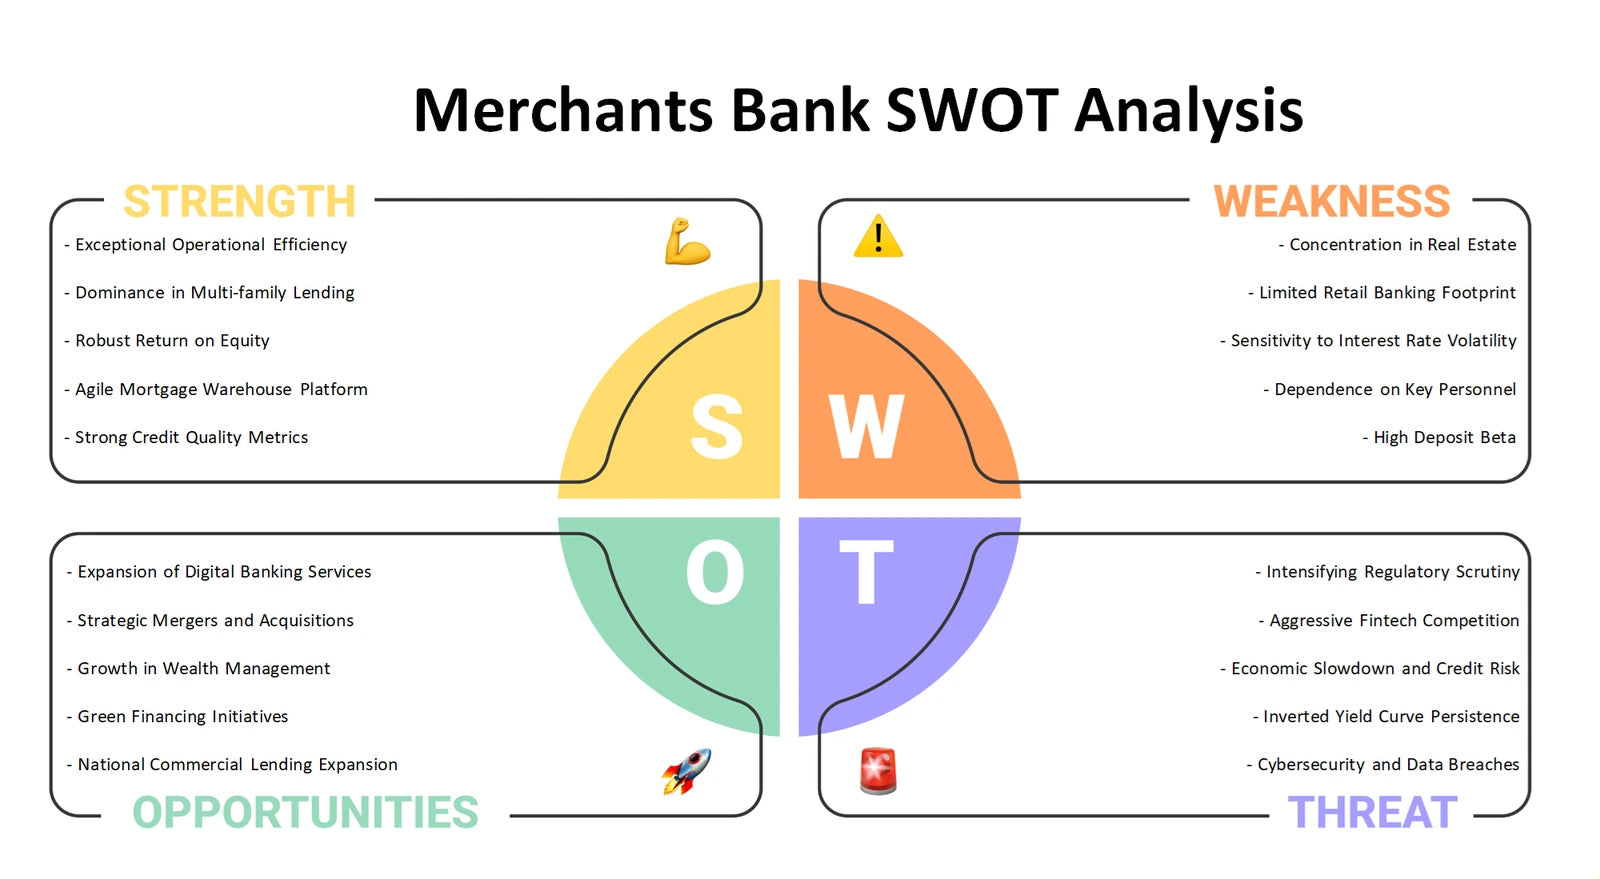
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Connect lending priorities to the wider business system
Together, the six perspectives help turn the available Merchants Bank context into a structured strategic discussion. BCG clarifies portfolio questions; Canvas connects customers, partnerships, operations, and economics; Five Forces and PESTLE examine outside pressure; 4Ps considers market-facing choices; and SWOT brings internal and external themes together. The Excel frameworks support organized comparison, while the detailed Word analyses provide company-focused context for further review.
Company background: Merchants Bank — business-model context product page.