

Manulife: Six Analyses of Investment Services and Digital Investment

Company-Specific Research
The core analysis is already completed
Everything in One Place
Key findings clearly organized and explained
Easy to Review & Adapt
Edit the content and add your own insights
Save Hours of Research
Ideal for essays, case studies and presentations
Six complementary perspectives. One company.
Manulife Strategy Analysis Bundle
This bundle is framed around the Manulife insurance and wealth-management business described in the matching business-model context. That context identifies insurance and wealth-management products, customers reached through advisers, brokers and an agent network, plus risk-transfer relationships with reinsurers. The available materials do not verify a specific legal issuer, reporting scope or geography, so this description avoids unsupported financial figures and jurisdictional claims.
For this financial-services model, portfolio choices, intermediary distribution and digital service design raise connected but different strategic questions. The referenced context also points to reinsurance for in-force long-term-care exposure and technology collaborations for customer interfaces. These are useful topics to assess, not pre-set conclusions. The Excel frameworks and detailed Word analyses provide a structured way to compare them through six lenses.
About the images: Each image is a brief summary preview. Your purchase includes the Excel frameworks and Word files with the detailed company analysis. The previews are not the complete downloadable products.
BCG Matrix
Which insurance, wealth-management or service priorities deserve resources when both market growth and relative market share matter?
The Manulife BCG Matrix creates a disciplined way to compare a portfolio rather than treating every offering or capability as equally important. It uses market growth and relative market share to test potential Stars, Cash Cows, Question Marks and Dogs. For a business distributed through advisers, brokers and agents, the exercise can also examine whether a product line’s economics depend on scale, specialist service, digital support or capital intensity. It does not assign any Manulife activity to a quadrant; it helps the customer assess what evidence would justify investment, maintenance, selective experimentation or withdrawal.
- Portfolio contrast. Compare mature recurring business with areas where changing customer needs or delivery models may create growth potential.
- Resource logic. Consider how distribution support, risk capacity and service investment could differ across high-growth and established activities.
- Decision view. Use the Excel framework to organise comparison criteria, then use the Word analysis to interpret the strategic trade-offs behind each quadrant.
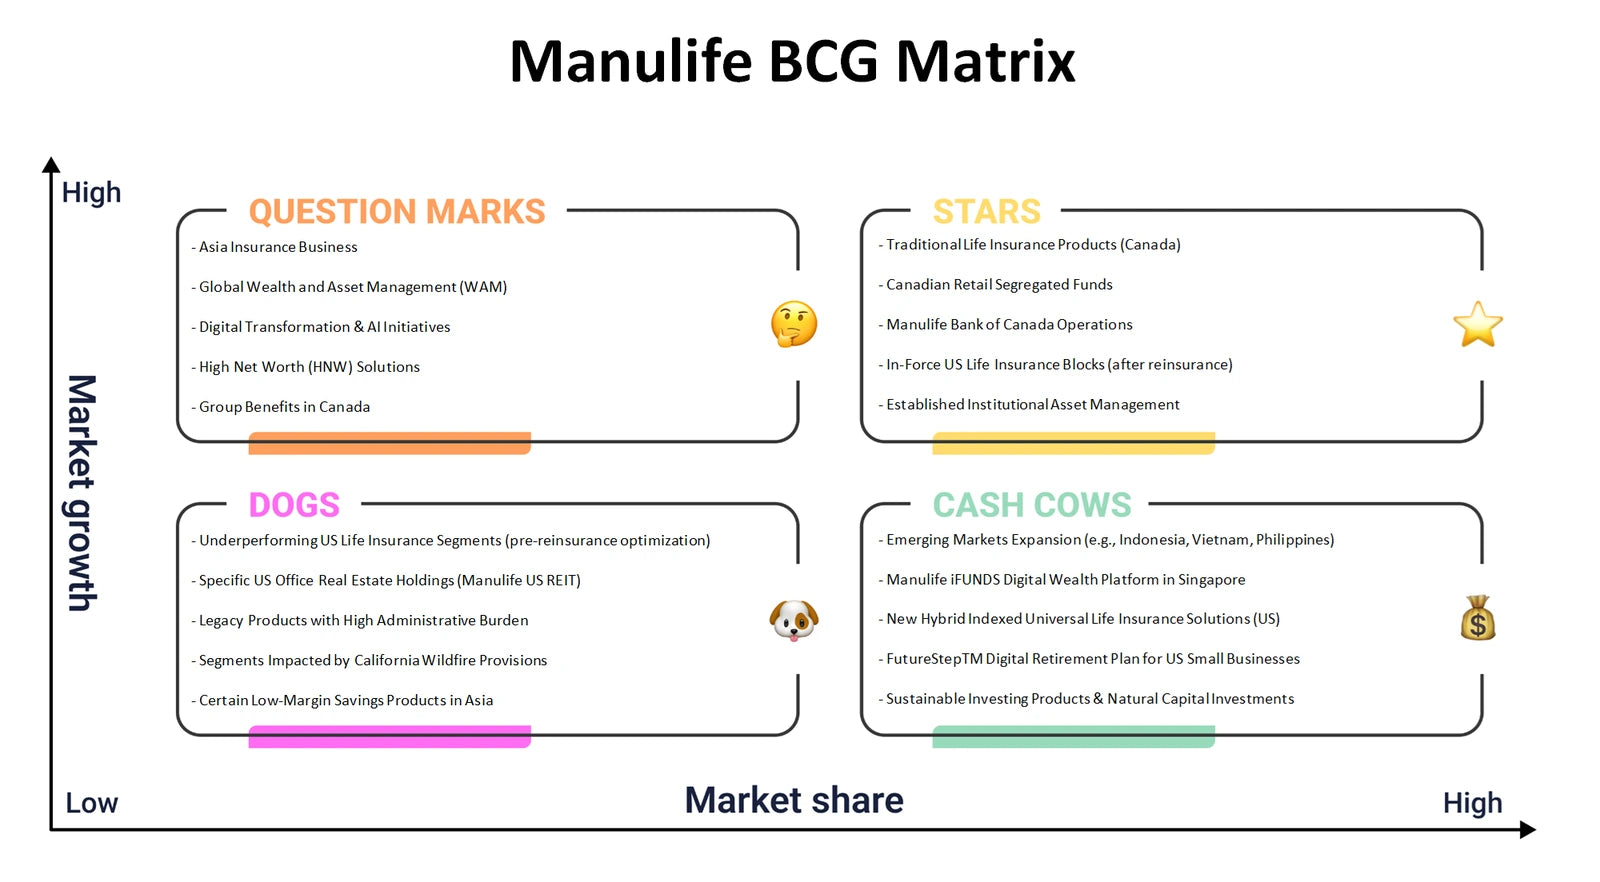
BCG Matrix summary preview. The full company analysis is provided in Excel and Word.
Business Model Canvas
How can Manulife connect customer access, financial protection or wealth value, partnerships and operating economics in one business-model view?
The Manulife Business Model Canvas brings together all nine building blocks: customer segments, value propositions, channels, customer relationships, revenue streams, key resources, key activities, key partnerships and cost structure. The available context makes intermediary distribution, reinsurance and technology collaboration especially relevant connections to inspect. Advisers, brokers and agents may influence how customers discover and receive support; reinsurers may affect risk-sharing considerations; digital tools may alter service delivery. The framework helps show how these relationships fit together without assuming that a particular channel, partnership or revenue source is superior.
- Value chain. Trace how insurance and wealth-management propositions move from design and risk management through distribution and ongoing customer service.
- Economic links. Examine how channels, partnerships, resources and activities may influence revenue logic and cost structure.
- Model review. Read the Excel canvas alongside the Word analysis to connect each block to the business questions it raises.
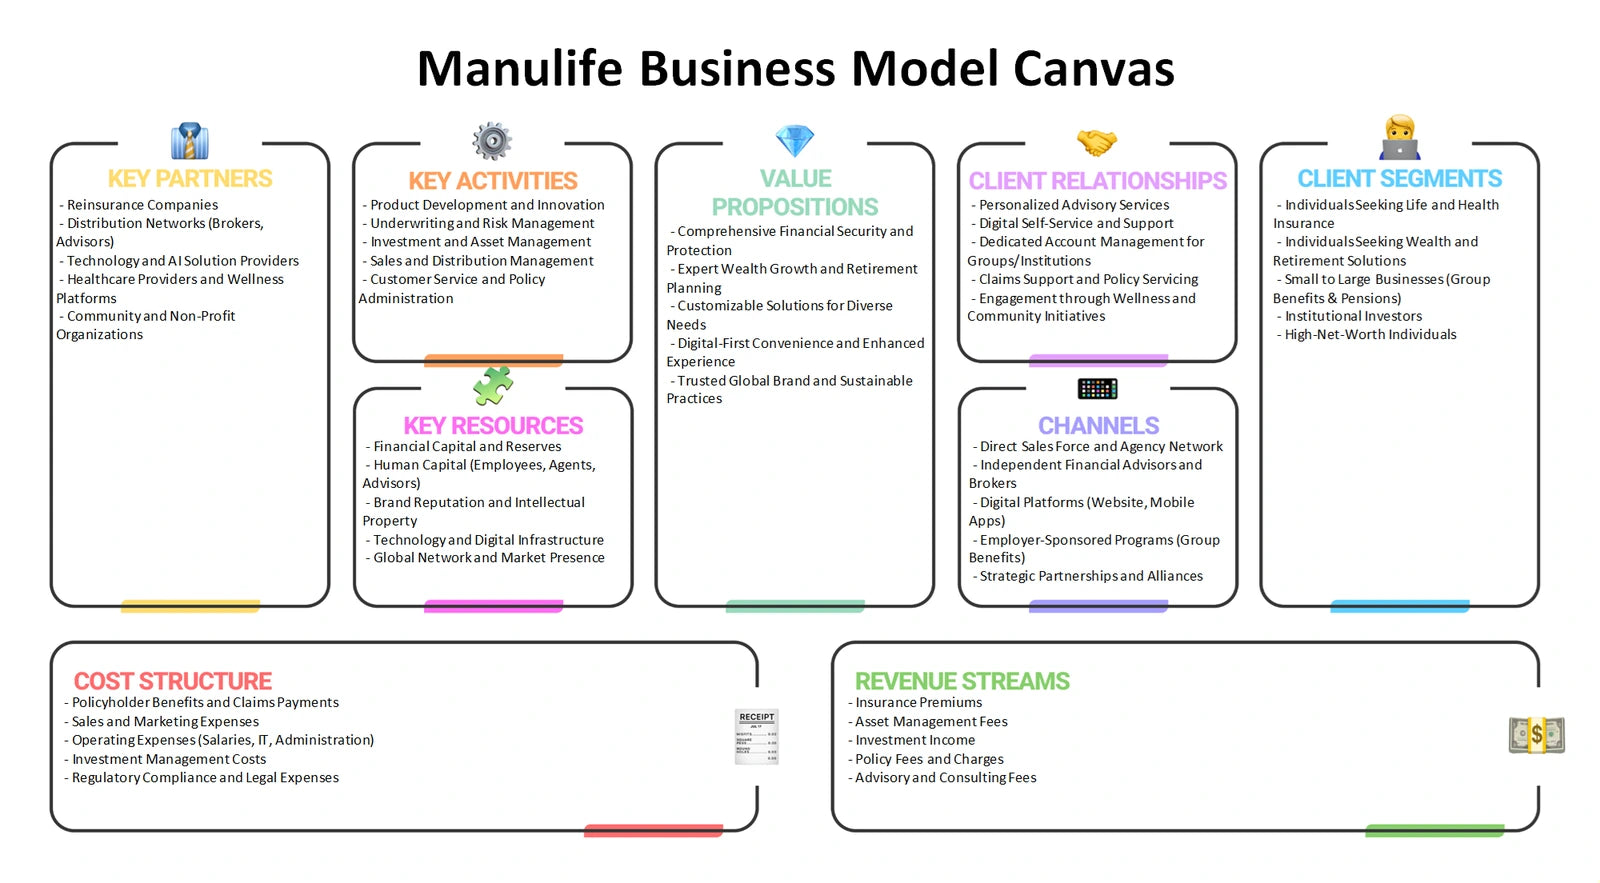
Business Model Canvas summary preview. The full company analysis is provided in Excel and Word.
Porter's Five Forces
What industry pressures could shape Manulife’s ability to serve customers through advice-led and digital financial-services channels?
Manulife Porter's Five Forces examines rivalry, supplier power, buyer power, the threat of new entrants and the threat of substitutes around insurance and wealth-management needs. Rivalry is more than price competition: service quality, trust, distribution reach and risk capability can all matter. Supplier power can include dependence on specialist technology, distribution partners or risk-transfer capacity. Buyer power asks how easily customers can compare, switch or use advice alternatives. Substitutes include other ways of meeting protection, savings or investment needs, not merely direct insurers or wealth providers. The lens helps separate industry structure from a company’s own internal capabilities.
- Channel dependence. Test where adviser, broker, agent or technology relationships may create negotiating leverage or concentration exposure.
- Customer alternatives. Compare the appeal of protection and wealth propositions with alternative ways customers may seek financial security or investment access.
- Pressure map. Use the Excel structure to keep each force distinct while the Word analysis explains why the pressures may interact.
Porter's Five Forces summary preview. The full company analysis is provided in Excel and Word.
Marketing Mix (4Ps)
How should product design, pricing logic, distribution routes and communication be considered for Manulife’s financial-services customers?
The Manulife Marketing Mix applies Product, Price, Place and Promotion to a regulated, trust-based service setting. Product can cover the fit between insurance or wealth-management needs and the support surrounding the offer. Price is not limited to a headline amount: the analysis can consider premiums, charges, perceived value and the clarity needed for customers to understand financial commitments. Place focuses on adviser, broker, agent and digital routes to market. Promotion considers educational communication and relationship-building, where confidence and comprehension can matter alongside awareness. The framework does not invent pricing, campaigns or channel shares; it helps assess their strategic coherence.
- Offer fit. Consider whether product features and service support address the needs of customers seeking protection, financial planning or wealth solutions.
- Route consistency. Compare the roles that human advice and digital interfaces may play across discovery, purchase and ongoing service.
- Go-to-market lens. Use the Excel framework to review the four Ps in sequence, with the Word analysis providing business-specific context for each choice.
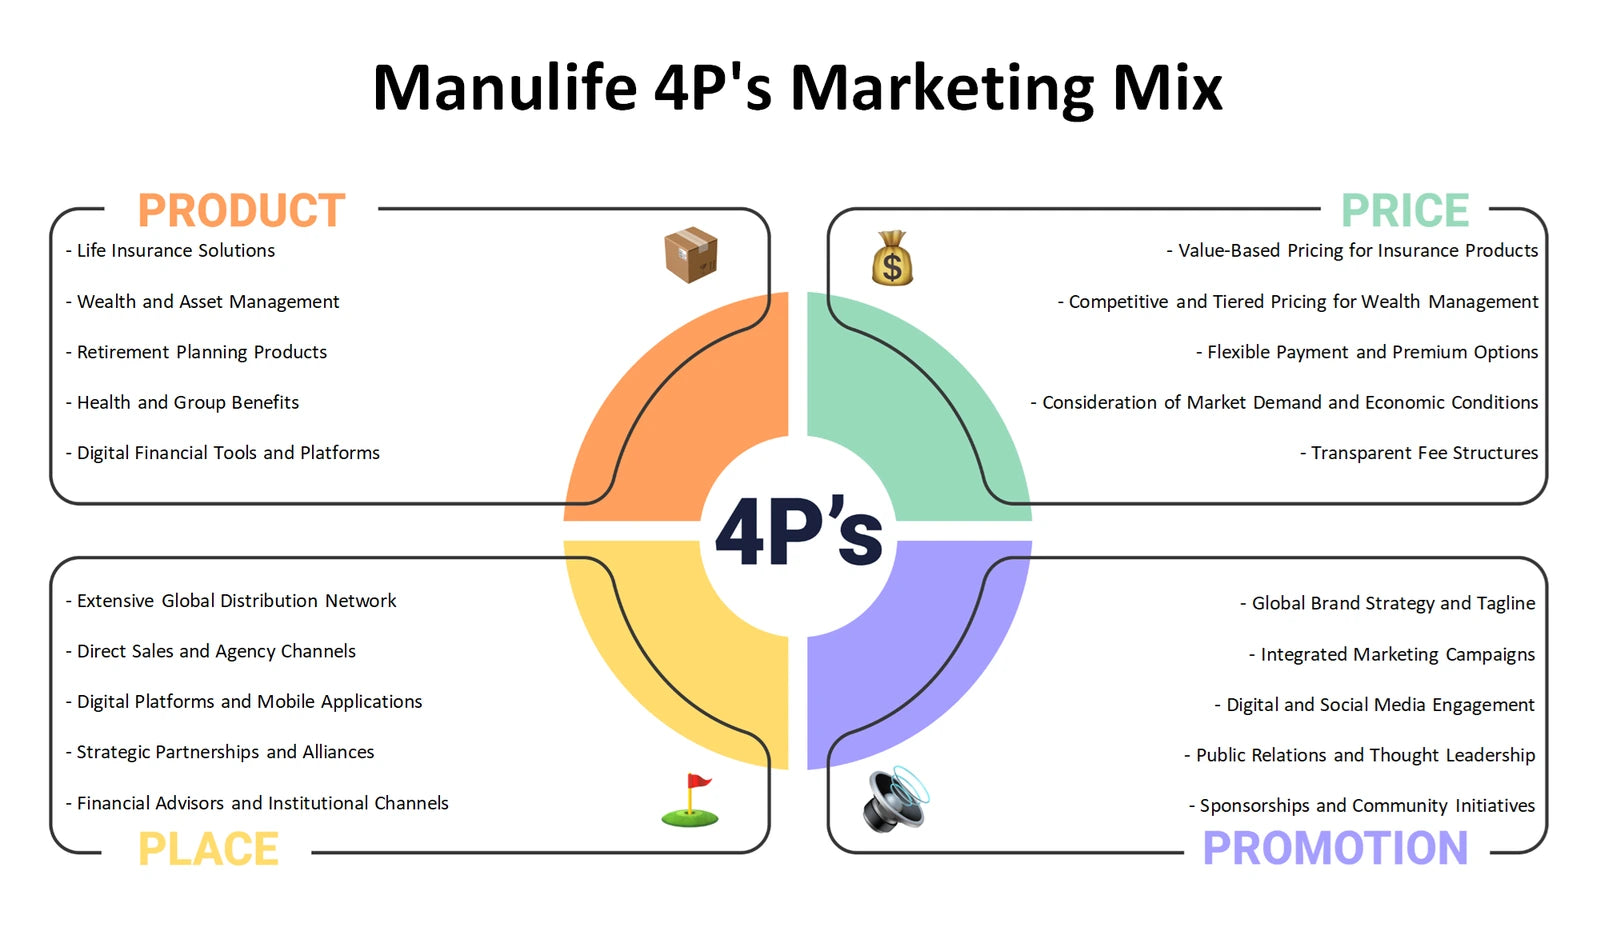
Marketing Mix summary preview. The full company analysis is provided in Excel and Word.
PESTLE Analysis
Which external forces should be monitored when evaluating Manulife’s protection, wealth and advice-led operating environment?
The Manulife PESTLE analysis, also commonly called PESTEL, separates Political, Economic, Social, Technological, Legal and Environmental influences. Political and legal questions can include the policy and supervisory setting for financial services, without assuming a particular law or location. Economic conditions may affect customer affordability, investment expectations and the value placed on protection. Social factors can shape financial confidence, ageing-related needs and preferences for advice. Technology is relevant to cloud migration, conversational interfaces and digital servicing referenced in the business context. Environmental considerations can be assessed through risk exposure, stakeholder expectations and operational resilience. This lens keeps external conditions distinct from internal performance.
- External scan. Separate possible policy, economic and social developments from management choices that belong inside the company.
- Digital context. Assess how technology opportunities may be balanced against privacy, resilience, implementation and customer-trust questions.
- Monitoring guide. Use the Excel categories to organise external signals and the Word analysis to understand their relevance to the business model.
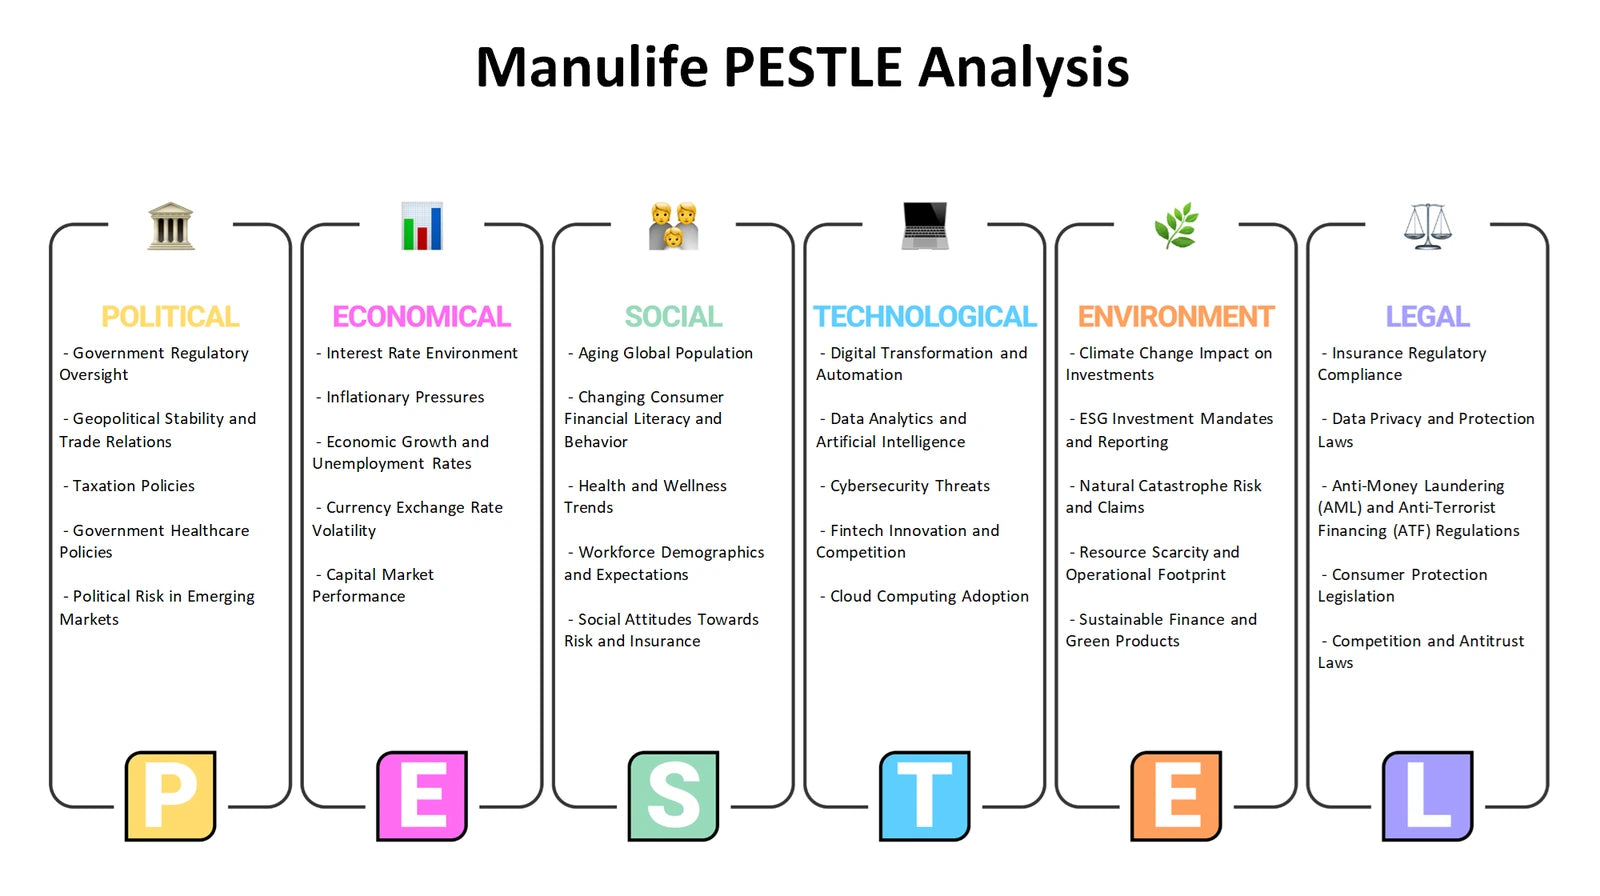
PESTLE Analysis summary preview. The full company analysis is provided in Excel and Word.
SWOT Analysis
How can Manulife distinguish internal capabilities and constraints from external opportunities and threats?
The Manulife SWOT analysis separates Strengths and Weaknesses, which are internal, from Opportunities and Threats, which arise outside the organisation. The documented context offers useful themes to examine: an established adviser, broker and agent distribution model; reinsurance relationships that can support risk management; and technology collaborations directed at digital customer engagement. These are not automatically strengths, because their value depends on execution, cost, governance and customer relevance. External opportunities may involve changing demand or service expectations, while threats may include competitive alternatives, regulatory developments or shifts in economic conditions. Keeping the categories separate prevents a broad list from becoming an unprioritised conclusion.
- Capability test. Consider how distribution reach, partnerships and service technology could be evaluated as internal advantages or areas requiring attention.
- Condition match. Link possible external opportunities and threats to the capabilities needed to respond rather than treating them as isolated observations.
- Priority synthesis. Use the Excel SWOT layout to classify themes, then consult the Word analysis to compare the implications of the resulting combinations.
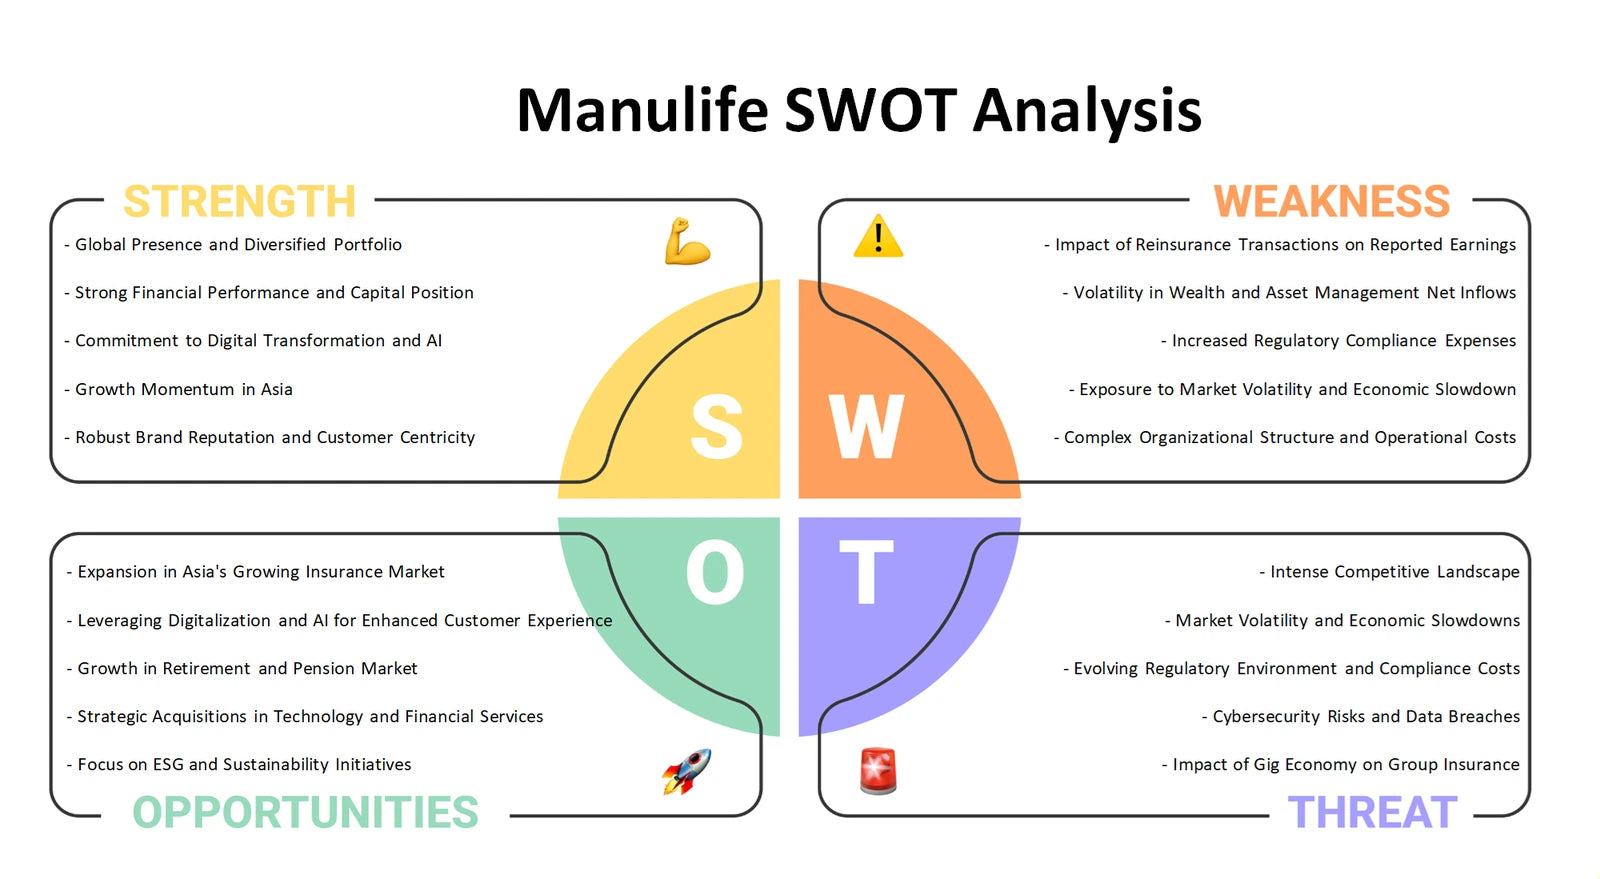
SWOT Analysis summary preview. The full company analysis is provided in Excel and Word.
Build a connected view of Manulife’s strategic questions
Together, the six perspectives move from portfolio priorities and business-model connections to industry pressure, customer routes to market, external change and strategic fit. The Excel frameworks provide structured ways to examine each lens, while the detailed Word analyses help customers develop a more connected understanding of the questions surrounding Manulife’s insurance and wealth-management context.
Company background: Manulife — business model context page.